
 Memory Foam Market | 2026-2036
Memory Foam Market Size, Share, and Industry Trends Forecast 2026-2036
Memory Foam Market Outlook
The split between premium viscoelastic formulations and commodity-grade polyether alternatives is realigning procurement patterns across the sleep products sector. Tempur Sealy International anchors the premium tier through proprietary density formulations and direct-to-consumer channel control. Serta Simmons Bedding competes at scale with diversified sourcing across multiple foam grades and retail partnerships. Carpenter Co. dominates the private-label and contract manufacturing segment, supplying foam components to brands lacking in-house production capabilities.
Memory foam denotes a polyurethane-based viscoelastic material engineered with open-cell architecture that softens in response to body heat and pressure, typically formulated with polyols and isocyanates reacted through slabstock or molded production methods to deliver contouring support and pressure redistribution. Mattresses command the largest value pool within product type segmentation, though toppers attract price-sensitive consumers seeking incremental comfort upgrades without full mattress replacement. The healthcare end-user segment generates outsized margins relative to residential volumes, as hospitals and long-term care facilities prioritize certified pressure-relief performance over per-unit cost minimization.
The EPA regulates VOC emissions from polyurethane foam through TSCA Title VI and aligned state-level air quality standards, while the Consumer Product Safety Commission enforces flammability protocols under 16 CFR Part 1633 that elevate compliance costs for domestic manufacturers. California's Bureau of Home Furnishings and Thermal Insulation maintains the nation's most stringent flammability testing requirements, effectively setting the benchmark for national product specifications. Stakeholders must monitor evolving state-level chemical restriction frameworks and assess whether reformulation investments or geographic sourcing shifts offer superior compliance economics.
Market Dynamics
Water-based blowing agents are displacing legacy HFC formulations as EPA TSCA Title VI enforcement tightens, forcing slabstock producers to retool continuous production lines and reformulate density gradients without sacrificing recovery rates.
Growth Catalysts
- Healthcare Pressure-Relief Mandates:United States long-term care facilities now specify certified viscoelastic surfaces for bedsore prevention, creating dedicated procurement channels for medical-grade foam density specifications.
- REACH Chemical Compliance:European ECHA restrictions on isocyanate exposure limits are accelerating adoption of closed-pour molding systems with automated ventilation and worker monitoring.
- Zhejiang-Jiangsu Cluster Proximity:Raw material polyol suppliers and slabstock fabricators operate within 150-kilometer radii, compressing logistics costs and enabling just-in-time density customization for export orders.
Market Restraints
- TDI/MDI Price Volatility:Toluene diisocyanate and methylene diphenyl diisocyanate feedstock costs swing with benzene-crude spreads, squeezing margin predictability for continuous-pour slabstock operations.
- China Supply Concentration:Over 60% of molded memory foam component output originates from three prefecture-level manufacturing zones, exposing buyers to single-point disruption risks from environmental compliance sweeps or power rationing.
- Latex Hybrid Substitution:Dunlop-process natural latex and synthetic styrene-butadiene blends capture premium positioning through biodegradability claims, pressuring polyurethane foam's sustainability narrative in European and North American mattress retail.
Strategic Opportunities
- India Residential Penetration:Organized mattress retail remains under 15% of Indian sleep products volume, creating first-mover positioning for viscoelastic formulations adapted to tropical humidity and price-sensitive entry tiers.
- Automotive Seating Integration:Electric vehicle platforms with extended cabin dwell times are specifying pressure-mapping-optimized foam contours, opening specification relationships with tier-one seat suppliers previously locked to conventional polyurethane.
- EU Green Deal Circular Economy:Ecodesign for Sustainable Products Regulation requirements for recycled content and end-of-life recyclability are creating compliant product differentiation for producers with chemical recycling partnerships or bio-based polyol sourcing.
Industry Challenges
- Certified Foam Technician Scarcity:Continuous-pour line operators and density-formulation chemists with VOC-compliant process experience command 40% wage premiums, constraining capacity expansion timelines for mid-scale fabricators.
- 16 CFR Part 1633 Testing Backlogs:California Bureau of Home Furnishings flammability certification queues extend 12-16 weeks for novel density formulations, delaying product launches and locking working capital in inventory.
- Legacy ERP Integration with IoT Sensors:Real-time temperature and pressure monitoring on molding lines requires retrofitting 1990s-era manufacturing execution systems, creating data architecture friction for quality traceability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Memory Foam Market |
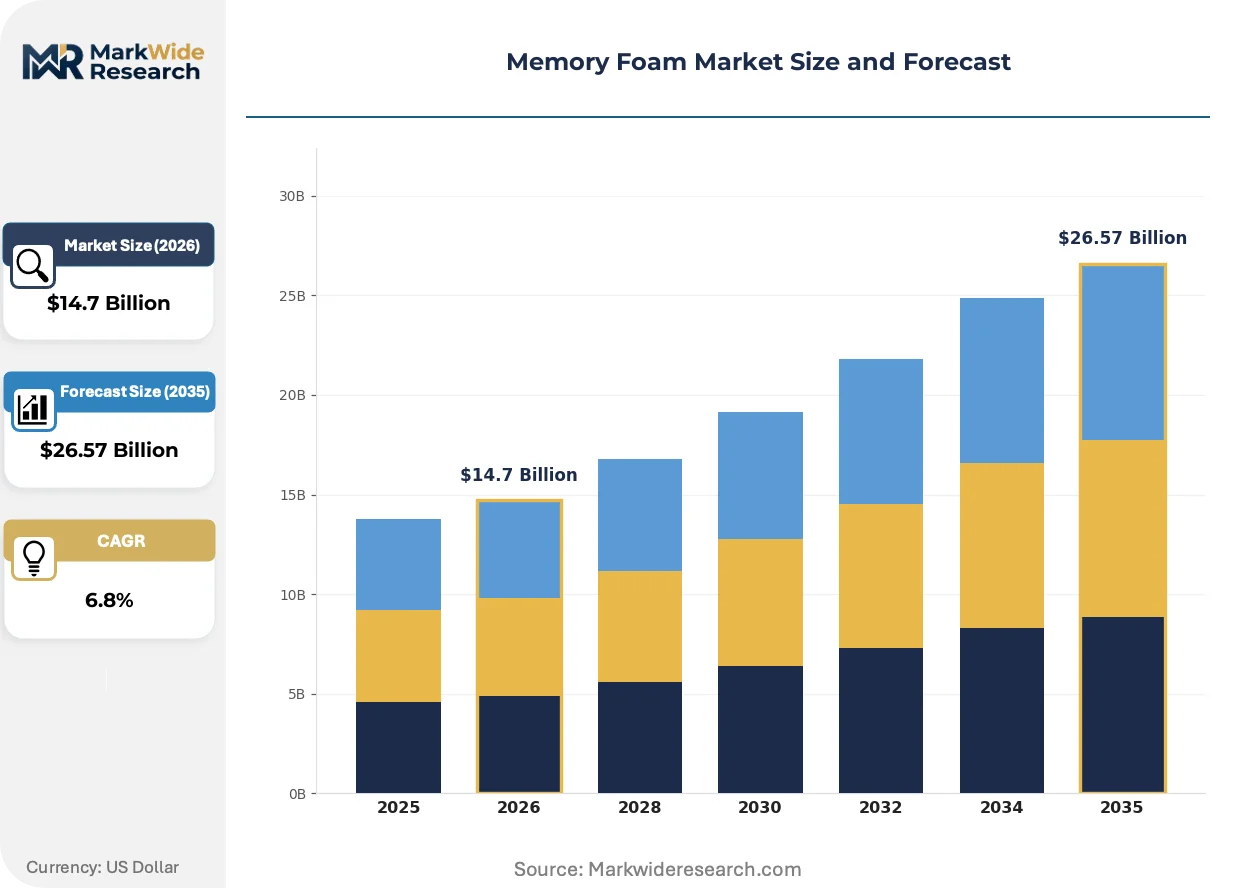
| Market Size in 2026 | $14.7 Billion |
| Market Size in 2035 | $26.57 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mattresses, Pillows, Cushions, Toppers End User: Residential, Hospitality, Healthcare, Automotive Application: Sleep Products, Seating Solutions, Medical Devices, Sports Equipment Distribution Channel: Online Retailers, Specialty Stores, Supermarkets, Wholesale |
| Companies Covered | FXI, Innocor, Inc., Foam Factory, Inc., Future Foam, Sinomax USA Inc., Tempur Sealy International, Inc., Serta Simmons Bedding, Carpenter Co., Elite Comfort Solutions, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Memory Foam Market Strategic Shifts
Graphene-infused viscoelastic formulations and AI-optimized cell structures are compressing traditional R&D cycles, while regulatory chemical phase-outs and direct-to-consumer channel maturation are rewriting how foam specifications reach end buyers.
Graphene oxide dispersions in polyol blends are rewriting thermal conductivity benchmarks for memory foam. Sleep product manufacturers in Germany and South Korea are piloting 3-5% graphene loadings to accelerate heat dissipation without sacrificing pressure relief. This thermal management leap is compressing the performance gap between open-cell viscoelastic and gel-infused alternatives, enabling price repositioning in premium mattress tiers.
ECHA's 2023-2027 restriction roadmap for diisocyanate respiratory sensitizers is forcing reformulation investments across EU polyurethane foam production. Industrial hygiene mandates now require automated pouring enclosures and continuous air monitoring in slabstock facilities. Small-batch custom molders in Italy and Poland are consolidating to amortize compliance capital, shifting contract manufacturing share toward integrated chemical-to-foam producers.
Certification-driven preference shifts are disintermediating traditional retail mattress channels. United States consumers increasingly validate purchases through CertiPUR-US and OEKO-TEX Standard 100 database lookups before brand consideration, compressing the importance of floor-model testing. This behavior concentrates marketing spend on transparency infrastructure rather than wholesale slotting fees, rewarding producers with documented supply chain audit trails.
Memory Foam Market Segmentation
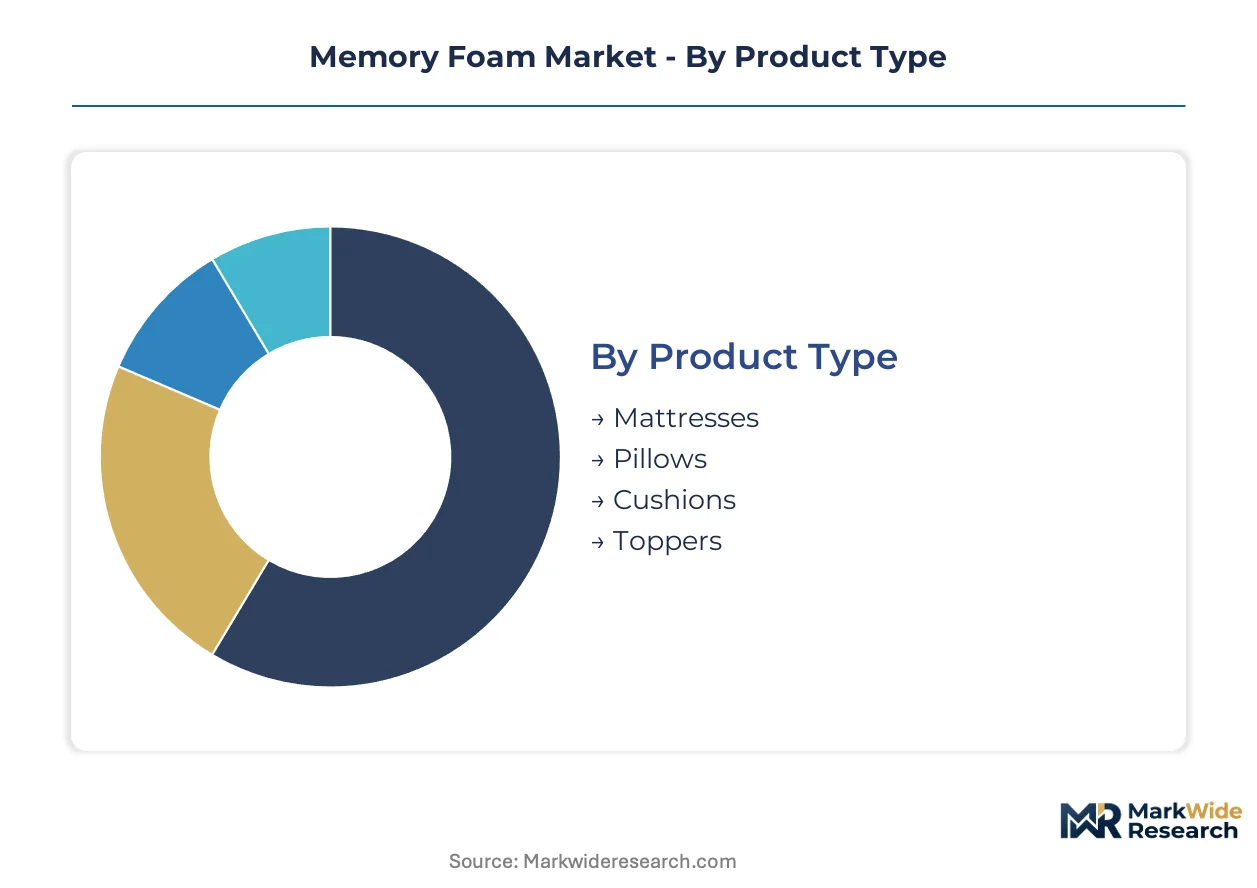
Memory foam segmentation reveals how formulation specifications and channel economics fragment value capture across sleep, medical, and mobility applications. Density gradients, certification requirements, and integration depth separate premium specification tiers from commodity substitution risks.
Product Type:
Standalone sleep systems dominate revenue concentration, while embedded components in multi-layer constructions represent a distinct procurement logic with different margin structures.
- Mattresses:Multi-layer viscoelastic cores with density specifications ranging from 3 to 7 pounds per cubic foot anchor premium positioning in residential and hospitality procurement. United States healthcare facilities now mandate certified pressure-relief mattresses for Medicare-reimbursed long-term care beds, creating dedicated specification channels with elevated compliance documentation requirements.
- Pillows:Contoured and shredded viscoelastic fills compete against down and latex alternatives through ergonomic positioning and temperature-neutral formulations. German and South Korean manufacturers are piloting graphene-infused pillow cores to accelerate heat dissipation, compressing the performance gap with gel-infused alternatives in premium retail tiers.
- Cushions:Seat and back cushions for office furniture and automotive applications emphasize durability cycling and compression set resistance over contouring depth.
- Toppers:Thin-profile viscoelastic overlays attract price-sensitive consumers seeking incremental comfort upgrades without full mattress replacement, concentrating in online retail channels with compressed margin structures.
Mattresses lead volumes today; toppers are gaining share fastest through e-commerce penetration and entry-tier positioning.
End User:
Procurement sophistication varies sharply across customer types, with certified medical specifications commanding premium pricing versus residential volume plays.
- Residential:Direct-to-consumer brands and traditional retail channels serve sleep product demand with density and cooling features as primary differentiation vectors. United States consumers increasingly validate purchases through CertiPUR-US database lookups before brand consideration, concentrating marketing spend on transparency infrastructure.
- Hospitality:Hotel chains specify durability-rated foam with accelerated compression testing to withstand commercial laundering cycles and guest turnover intensity.
- Healthcare:Hospitals and long-term care facilities prioritize certified pressure-relief performance over per-unit cost minimization, generating outsized margins relative to residential volumes for medical-grade density specifications.
- Automotive:Electric vehicle platforms with extended cabin dwell times are specifying pressure-mapping-optimized foam contours, opening specification relationships with tier-one seat suppliers.
Residential dominates absolute volume; automotive represents the steepest expansion trajectory through EV platform integration.
Application:
Functional performance requirements dictate formulation chemistry, with medical and sports applications demanding specialized density gradients and recovery rates.
- Sleep Products:Mattresses, pillows, and bedding accessories represent the core revenue pool, with open-cell viscoelastic formulations optimized for pressure redistribution and thermal neutrality.
- Seating Solutions:Office furniture and transportation seating emphasize durability cycling and ergonomic support over contouring depth, with molded foam specifications dominating.
- Medical Devices:Pressure-relief surfaces for bedsore prevention require certified density specifications and documented compliance with flammability protocols, creating dedicated procurement channels with elevated documentation requirements.
- Sports Equipment:Protective padding and recovery surfaces utilize high-resilience viscoelastic formulations with rapid recovery rates for impact absorption applications.
Sleep products anchor current revenue; medical devices demonstrate the most durable margin structure through certification barriers.
Distribution Channel:
Channel control determines pricing power, with direct-to-consumer platforms capturing margin compression from traditional wholesale relationships.
- Online Retailers:E-commerce platforms enable compressed mattress-in-box logistics and transparent specification comparison, with CertiPUR-US and OEKO-TEX database lookups increasingly validating purchase decisions before brand consideration.
- Specialty Stores:Traditional mattress retailers maintain floor-model testing importance for premium-tier purchases, though their share compresses as certification-driven preference shifts disintermediate physical channels.
- Supermarkets:Mass-market retailers concentrate topper and pillow volume with private-label positioning and price-focused merchandising.
- Wholesale:Contract manufacturing and private-label supply to hospitality and healthcare chains operates on specification-driven procurement with extended certification queues.
Online retailers lead volume growth; specialty stores retain premium-tier positioning despite share compression.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States and China operate on divergent demand logics. American healthcare procurement mandates certified pressure-relief surfaces, while Chinese manufacturing clusters optimize for export-scale slabstock production. Germany and India represent contrasting growth vectors through regulatory-driven premiumization and underpenetrated residential expansion.
United States
Medicare-reimbursed long-term care facilities now mandate certified viscoelastic mattresses for bedsore prevention. The EPA enforces VOC emission standards through TSCA Title VI, accelerating water-based blowing agent adoption. Manufacturing concentrates in North Carolina and Indiana, where continuous-pour slabstock lines supply both domestic healthcare procurement and hospitality contract channels.
China
Raw material polyol suppliers and foam fabricators cluster within 150-kilometer radii across Zhejiang and Jiangsu provinces. The Ministry of Ecology and Environment conducts periodic environmental compliance sweeps that disrupt production schedules. Ningbo and Suzhou host integrated chemical-to-foam operations serving European and North American export orders with just-in-time density customization.
Germany
Graphene-infused viscoelastic formulations are piloting accelerated heat dissipation for premium sleep products. ECHA restrictions on diisocyanate respiratory sensitizers mandate automated pouring enclosures and continuous air monitoring. Bavarian and North Rhine-Westphalian facilities are consolidating small-batch custom molders to amortize compliance capital investments.
India
Organized mattress retail remains under 15% of sleep products volume, creating first-mover positioning for viscoelastic formulations adapted to tropical humidity. The Bureau of Indian Standards maintains evolving quality benchmarks for polyurethane foam. Maharashtra and Gujarat manufacturing zones are scaling entry-tier production for price-sensitive residential penetration.
South Korea
German and domestic manufacturers are piloting graphene oxide loadings in polyol blends for thermal management differentiation. The Ministry of Environment enforces indoor air quality standards that elevate low-emission adhesive specifications. Seoul Capital Area fabrication facilities supply premium mattress-in-box brands targeting direct-to-consumer channels across Asia-Pacific markets.
Memory Foam Market Competitive Environment
Top-tier vendors anchor premium-tier specification control, while mid-scale fabricators compete on private-label volume and contract manufacturing efficiency. The vendor base separates into three strategic archetypes: integrated chemical-to-foam producers with proprietary density formulations, specialized slabstock operators serving healthcare certification channels, and diversified bedding conglomerates with multi-brand retail distribution. Dominant competitive moves include geographic sourcing shifts to amortize regulatory compliance costs and backward integration into captive polyol supply.
Among United States-based bedding conglomerates, Tempur Sealy International and Serta Simmons Bedding occupy positions across premium and mass-market tiers through differentiated channel strategies. Carpenter Co. exemplifies the private-label and contract manufacturing archetype, supplying foam components to brands lacking in-house production capabilities. FXI and Innocor represent integrated chemical-to-foam specialists with scale advantages in continuous-pour operations.
| Leading Market Players |
|---|
| FXI |
| Innocor, Inc. |
| Foam Factory, Inc. |
| Future Foam |
| Sinomax USA Inc. |
| Tempur Sealy International, Inc. |
| Serta Simmons Bedding |
| Carpenter Co. |
| Elite Comfort Solutions |
| Others |
Value Chain & Pricing Dynamics
TDI/MDI feedstock costs swing with benzene-crude spreads, transmitting volatility from petrochemical complexes through slabstock fabricators to hospital procurement officers and mattress-in-box brands. This input-cost channel concentrates margin pressure on continuous-pour operators lacking backward integration into captive isocyanate supply.
Pricing Analysis
Capacity additions in Zhejiang and Jiangsu provinces are reshaping price floors for commodity-grade polyether formulations, compressing export margins for standardized density specifications. Three-tier pricing structure across premium viscoelastic, certified medical-grade, and economy polyether alternatives separates Tempur Sealy's proprietary formulations from private-label volume plays. Pricing pressure stems from latex hybrid substitution in European retail, where biodegradability claims command shelf-space premiums. Residential consumers exhibit highest price sensitivity through topper and entry-tier mattress channels, while healthcare facilities absorb elevated per-unit costs for certified pressure-relief performance.
Supply Chain Analysis
Polyol supply rests on integrated chemical producers in China, Germany, and the United States, with specialty-grade formulations requiring technical collaboration between resin suppliers and foam fabricators. Critical inputs include toluene diisocyanate, methylene diphenyl diisocyanate, and water-based blowing agents displacing legacy HFC formulations. Single-source vulnerability concentrates in Zhejiang-Jiangsu manufacturing clusters, where environmental compliance sweeps or power rationing disrupt just-in-time export scheduling. Distribution runs through direct-to-consumer mattress-in-box platforms, traditional retail floor models, and contract manufacturing channels serving hospitality and healthcare chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds regulatory tailwinds into durable margin structures, with EPA TSCA Title VI enforcement and Medicare pressure-relief mandates creating certified-product premiums that resist commodity substitution.
For Market Incumbents: Extend formulation differentiation through graphene-infused thermal management patents and automated closed-pour molding systems that amortize ECHA diisocyanate compliance costs. Defend against latex hybrid substitution by accelerating bio-based polyol partnerships and chemical recycling infrastructure that satisfies EU Green Deal circular economy requirements. Prioritize captive TDI/MDI supply or long-term offtake agreements to insulate margin predictability from benzene-crude volatility.
For New Entrants and Emerging Players: AI-optimized cell structure algorithms offer specification relationships with electric vehicle seat suppliers previously locked to conventional polyurethane suppliers. Target India's underpenetrated organized mattress retail through humidity-adapted viscoelastic formulations priced for entry-tier residential penetration. Deploy CertiPUR-US transparency infrastructure as primary go-to-market credential, bypassing wholesale slotting fees that concentrate incumbent channel control.
For Investors and Strategic Acquirers: Consolidation pressure builds where small-batch EU custom molders face ECHA respiratory sensitizer mandates requiring capital investments beyond standalone amortization capacity. Five-to-ten year viability favors integrated chemical-to-foam producers with proprietary density libraries and healthcare certification track records. Watch California Bureau of Home Furnishings testing queue lengths as inflection indicator for new product launch velocity and working capital lockup risk.
| Strategic Initiative | Industry Significance |
|---|---|
| Water-Based Blowing Agent Transition | EPA TSCA Title VI compliance protects domestic manufacturing access against state-level air quality enforcement. |
| Graphene-Infused Formulation Patenting | German and South Korean pilot programs validate thermal conductivity differentiation in premium mattress tiers. |
| Healthcare Certification Investment | Medicare-reimbursed long-term care mandates create dedicated procurement channels with elevated documentation barriers. |
| India Manufacturing Scale-Up | Maharashtra and Gujarat zones enable price-adapted formulations for tropical humidity and sub-15% organized retail penetration. |
| Chemical Recycling Partnership | EU Ecodesign for Sustainable Products Regulation requirements reward producers with documented end-of-life recyclability pathways. |
Study Parameters
Multiple input streams — continuous-pour slabstock operators, hospital procurement managers, mattress brand technical directors, and polyol supplier R&D leads — were reconciled against customs trade data, EPA enforcement disclosures, and SEC 10-K filings from publicly traded bedding conglomerates. Bottom-up density-grade production estimates and top-down end-use consumption patterns were triangulated to anchor volume and value outputs.
Historical capacity utilization trends were cross-referenced against panel input from plant managers and distribution channel partners to model segment-level expansion trajectories across the analysis window. Forecasts incorporate product type segmentation by density specification, end-user procurement sophistication, and regional regulatory cluster intensity. CAGRs derive from petrochemical feedstock cost elasticity, certification queue dynamics, and electric vehicle platform seating integration timelines.
The model holds under stable EPA enforcement intensity and benzene-crude spread continuity; deviation in ECHA restriction acceleration or China environmental sweep frequency would shift capacity expansion assumptions. A small set of named triggers — California flammability testing backlogs, graphene raw material cost curves, and India organized retail penetration rates — warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Household Items
North America Glassware Market
Household Items
Disposable Napkins Market
Household Items
Indoor Humidifier Market
Household Items
Industrial Vacuum Cleaner Market
Household Items
Dishwasher Detergent Market
Household Items
Water Purifier Market
Household Items
Latex Mattress Market
Household Items
Electric Shoe Dryer Market
Household Items
Toilet Deodorant Market
Household Items
Hydralight Lanterns Market
Household Items
Portable Steam Cleaners Market
Household Items
Europe Ice/Cooler Box Market
Household Items
Moving Supplies Market
Household Items
India Non-Stick Cookware Market
Household Items
Home Scales Market
Household Items
Portable Car Vacuum Market