
 Professional Gear Bags Market | 2026-2036
Professional Gear Bags Market Size, Share, and Industry Trends Forecast 2026-2036
Professional Gear Bags Market Analysis
Freelance photographers and independent creative professionals are redrawing demand patterns in the Professional Gear Bags Market, displacing traditional bulk institutional procurement. Pelican Products, Inc. dominates hard-shell protective cases through its proprietary resin formulations and lifetime warranty positioning. Thule Group leverages its automotive rack heritage to extend brand trust into rolling camera bags and equipment transport systems. Mystery Ranch specializes in load-bearing chassis technology drawn from military contract experience, anchoring its premium backpack line.
Professional gear bags are purpose-built transport enclosures constructed from engineered textiles or molded polymers, featuring padded compartments, weather-resistant closures, and modular divider systems designed to protect sensitive equipment during transit and field use. The category spans backpacks, duffle bags, rolling bags, and tote bags, with rolling configurations capturing premium margin pools as traveling professionals prioritize mobility over carry comfort. Nylon and polyester materials lead volume production due to their strength-to-weight ratios and dye-sub patterning compatibility, while leather remains a niche prestige tier serving attorney and executive briefcase crossover segments.
REACH in Europe restricts perfluorinated compounds in water-repellent fabric treatments, forcing reformulation of coated nylon supply chains, while ISO 9001 quality management standards shape contract eligibility for institutional buyers in healthcare and government verticals. California's Proposition 65 labeling requirements affect products sold into the United States' largest state economy, creating compliance friction for imported goods. Stakeholders must monitor evolving chemical disclosure regimes and modular repairability mandates as sustainability criteria increasingly filter procurement specifications.
Market Dynamics
Freelance creative professionals are displacing institutional procurement as the dominant demand vector, forcing manufacturers to reconfigure volume-mix strategies away from bulk corporate contracts toward direct-to-consumer fulfillment infrastructure.
Growth Catalysts
- Remote Creative Work Normalization:Freelance photographers and independent videographers now constitute the fastest-expanding buyer segment, requiring modular, single-operator transport solutions rather than fleet-scale equipment.
- REACH Chemical Compliance:Europe's tightened perfluorinated compound restrictions are accelerating reformulation of water-repellent coated nylons, creating first-mover advantage for suppliers with certified alternative chemistries.
- China Production Cluster Scaling:Domestic manufacturing hubs in Guangdong and Zhejiang provinces are capturing export volume while simultaneously feeding indigenous brand consumption, compressing lead times for Asia-Pacific fulfillment.
Market Restraints
- Petrochemical Input Volatility:Nylon and polyester resin prices fluctuate with crude oil derivatives, squeezing margin predictability for textile-dependent bag manufacturers without backward integration into polymer supply.
- Coated Fabric Supply Concentration:Water-repellent textile finishing capacity concentrates among Korean and Taiwanese chemical processors, creating single-source vulnerability for European and North American bag assemblers.
- Hard-Shell Substitution Ceiling:Injection-molded polymer cases from Pelican and SKB limit fabric bag penetration in broadcast and military verticals where impact certification is non-negotiable.
Strategic Opportunities
- India Creative Economy Expansion:Mumbai, Bengaluru, and Delhi production clusters are scaling to serve domestic wedding photography and regional cinema equipment transport, with BIS quality standards creating entry barriers for uncertified imports.
- Modular Repairability Mandates:France's anti-waste circular economy law and emerging EU right-to-repair frameworks reward brands with field-replaceable components and documented disassembly protocols.
- Smart Inventory Integration:RFID-enabled compartment tracking is converging with mobile asset management platforms, enabling rental houses and production companies to monitor equipment location without separate scanning infrastructure.
Industry Challenges
- Load-Bearing Engineering Talent Scarcity:Military-to-civilian transfer of suspension system designers is tightening as defense contract volumes expand, constraining premium backpack development pipelines.
- Multi-Jurisdiction Labeling Complexity:California Proposition 65 chemical disclosure requirements conflict with EU minimal-labeling norms, forcing SKUs with geography-specific hangtags and compliance documentation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Professional Gear Bags Market |
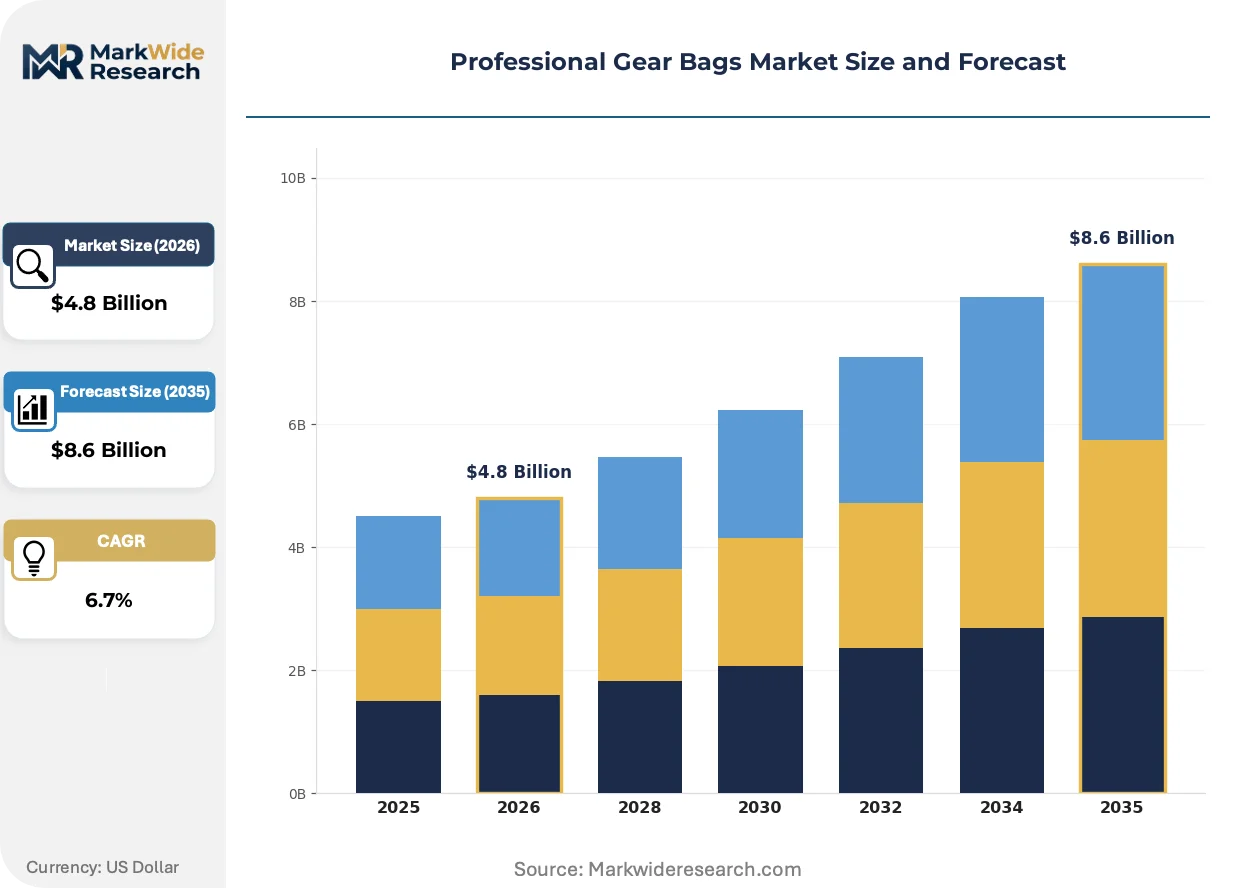
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Backpacks, Duffle Bags, Rolling Bags, Tote Bags Material: Nylon, Polyester, Leather, Canvas End User: Musicians, Photographers, Athletes, Professionals Capacity: Small, Medium, Large, Extra Large |
| Companies Covered | Samsonite International, VF Corporation, Pelican Products, Inc., Thule Group, Mystery Ranch, Lowepro, Peak Design, Osprey Packs, Direct Action Gear, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Professional Gear Bags Market Emerging Trajectories
Material science breakthroughs and regulatory chemistry shifts are compressing traditional competitive moats while opening premium positioning opportunities for compliant, traceable supply chains.
Recycled ocean-bound polyester is decomposing virgin polymer cost structures in mid-tier bag production. Sustainability-conscious production companies and corporate AV departments are specifying certified recycled content in RFPs at accelerating rates. This material transition is decomposing the historical price premium between sustainable and conventional supply chains, forcing commodity producers to absorb certification costs or surrender volume.
REACH Annex XVII restrictions on perfluorinated compounds are eliminating legacy C6 and C8 water-repellent treatments from European market access. Bag manufacturers are reformulating with silicone-based or paraffin alternatives, accepting modest performance trade-offs in extreme wet conditions. Rolling camera bag configurations for location cinematography face the steepest compliance timeline pressure, as these premium SKUs disproportionately serve EU production hubs.
Direct-to-creator e-commerce is fragmenting traditional distributor relationships that historically controlled rental house and retail channel access. Independent photographers are researching specifications through video review platforms and purchasing through manufacturer-owned storefronts, bypassing the dealer networks that once gated brand discovery. This channel compression is most visible in North American and Western European markets where creator economy infrastructure supports one-person business formation.
Professional Gear Bags Market Segmentation
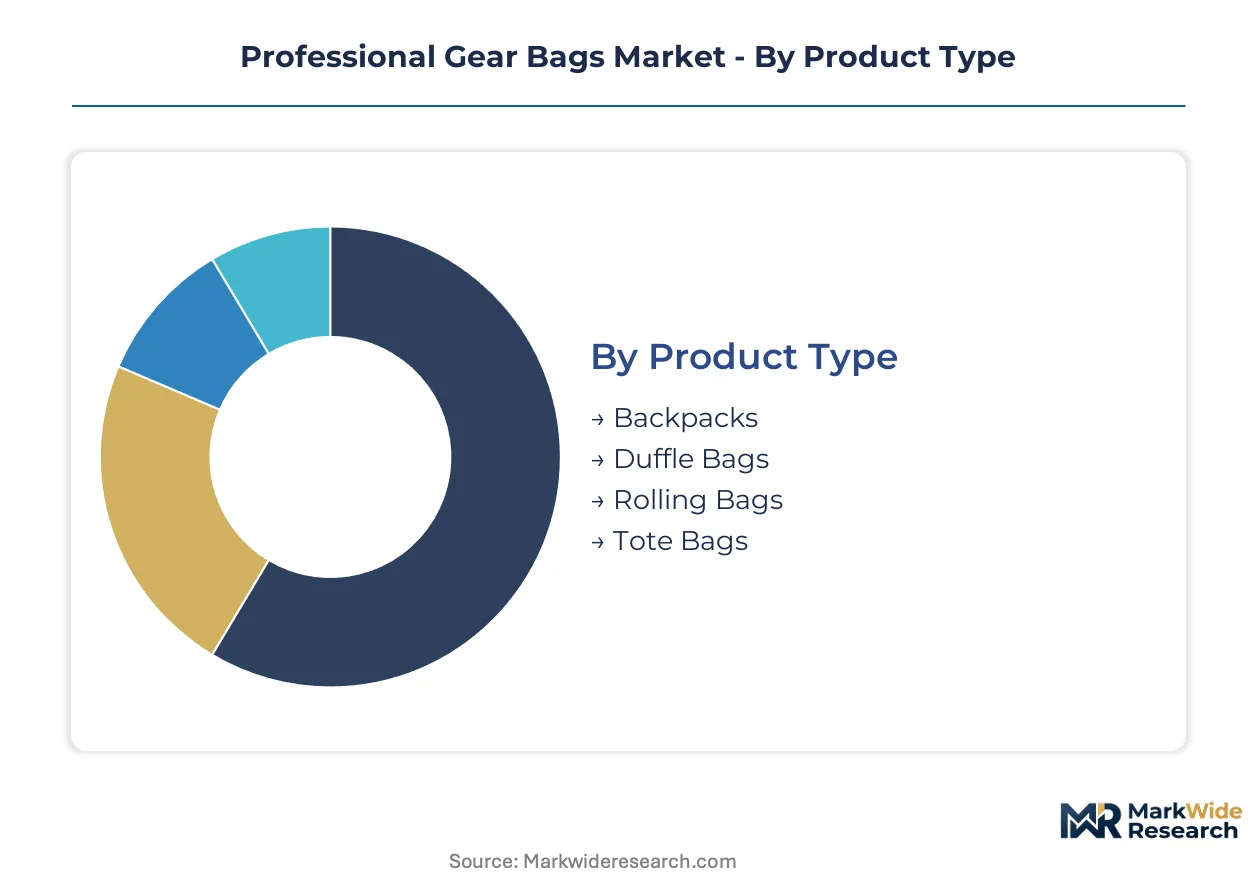
Professional gear bag purchasing patterns diverge sharply across transport modality, material preference, and operator scale. Segment-specific engineering requirements and compliance exposure create distinct margin profiles that reward targeted portfolio construction over undifferentiated breadth.
Product Type:
Backpacks and rolling bags anchor domestic consumption in North America and Western Europe, while duffle configurations dominate export volumes to Asia-Pacific production hubs.
- Backpacks:Dual-strap load-bearing chassis with padded harness systems and modular divider inserts. Freelance photographers in Germany and France drive specification intensity as ECHA chemical compliance tightens fabric treatment standards.
- Rolling Bags:Telescoping handle assemblies mounted on injection-molded frames with inline skate wheels. Location cinematographers across California production corridors prioritize these for equipment mobility despite FAA carry-on dimensional restrictions.
- Duffle Bags:Cylindrical soft-shell construction with wraparound zippers and removable shoulder straps. Studio rental houses in Mumbai and Bengaluru specify these for lighting kit transport.
- Tote Bags:Open-top or zippered rectangular profiles with reinforced base panels. Attorney and executive briefcase crossover segments in London and New York sustain leather-tier demand.
Rolling bags hold the largest share; momentum sits with backpacks as remote creative work normalizes single-operator mobility requirements.
Material:
Cost tier stratification separates commodity polymer supply from certified sustainable alternatives commanding procurement premiums.
- Nylon:High-tenacity polyamide 6,6 woven fabric with silicone-based water-repellent finishes replacing legacy C6 treatments. REACH Annex XVII compliance costs are compressing margins for European assemblers without Korean chemical processor partnerships.
- Polyester:Recycled ocean-bound PET filament constructions achieving GRS certification. Corporate AV departments in California and Texas are mandating certified recycled content in RFPs at accelerating rates.
- Leather:Full-grain vegetable-tanned hides with brass hardware. Italian tanneries supply prestige-tier briefcase crossover demand from legal and financial professionals in Manhattan and the City of London.
- Canvas:Heavy cotton duck with waxed or paraffin waterproofing treatments. Heritage positioning attracts independent photographers seeking differentiated aesthetic positioning on social media review platforms.
Nylon maintains volume leadership; recycled polyester is expanding most quickly as sustainability specifications harden in institutional procurement.
End User:
Customer type determines feature prioritization, with independent operators demanding modularity and institutional buyers requiring fleet-scale durability certification.
- Photographers:Freelance and independent image-makers requiring rapid-access compartment layouts and weather sealing. This segment concentrates in Los Angeles, Berlin, and Tokyo creative districts.
- Musicians:Touring performers and session players transporting instruments and amplification equipment. Flight-case compatibility and TSA-accessible locking systems dominate specification conversations.
- Athletes:Competitive and recreational users moving equipment to training facilities and event venues. Ventilated compartments for odor management separate premium from standard tiers.
- Professionals:Corporate, legal, and medical practitioners integrating device protection with formal aesthetic requirements. HIPAA-conscious healthcare IT administrators in Boston and Chicago specify RFID-blocking laptop compartments.
Photographers represent the dominant volume pool; athletes are gaining share fastest as fitness economy infrastructure expands in suburban markets.
Capacity:
Volume distribution tracks equipment payload requirements across single-operator and crew-scale transport scenarios.
- Large:Exceeding 60-liter internal volume with expandable collar designs and reinforced floor panels. Broadcast ENG crews in Atlanta and Dallas specify these for multi-camera location shoots.
- Medium:30-50 liter configurations balancing daily carry comfort with equipment diversity. Wedding photographers across Indian metropolitan clusters standardize on this tier for single-day event coverage.
- Small:Under 30 liter profiles optimized for mirrorless body and two-lens kits. Street photographers in Paris and Tokyo prioritize minimal footprint and rapid access.
- Extra Large:Exceeding 80 liters with dedicated lighting stand sleeves and wheeled chassis integration. Cine rental houses in Burbank and London provision these for grip and electric department transport.
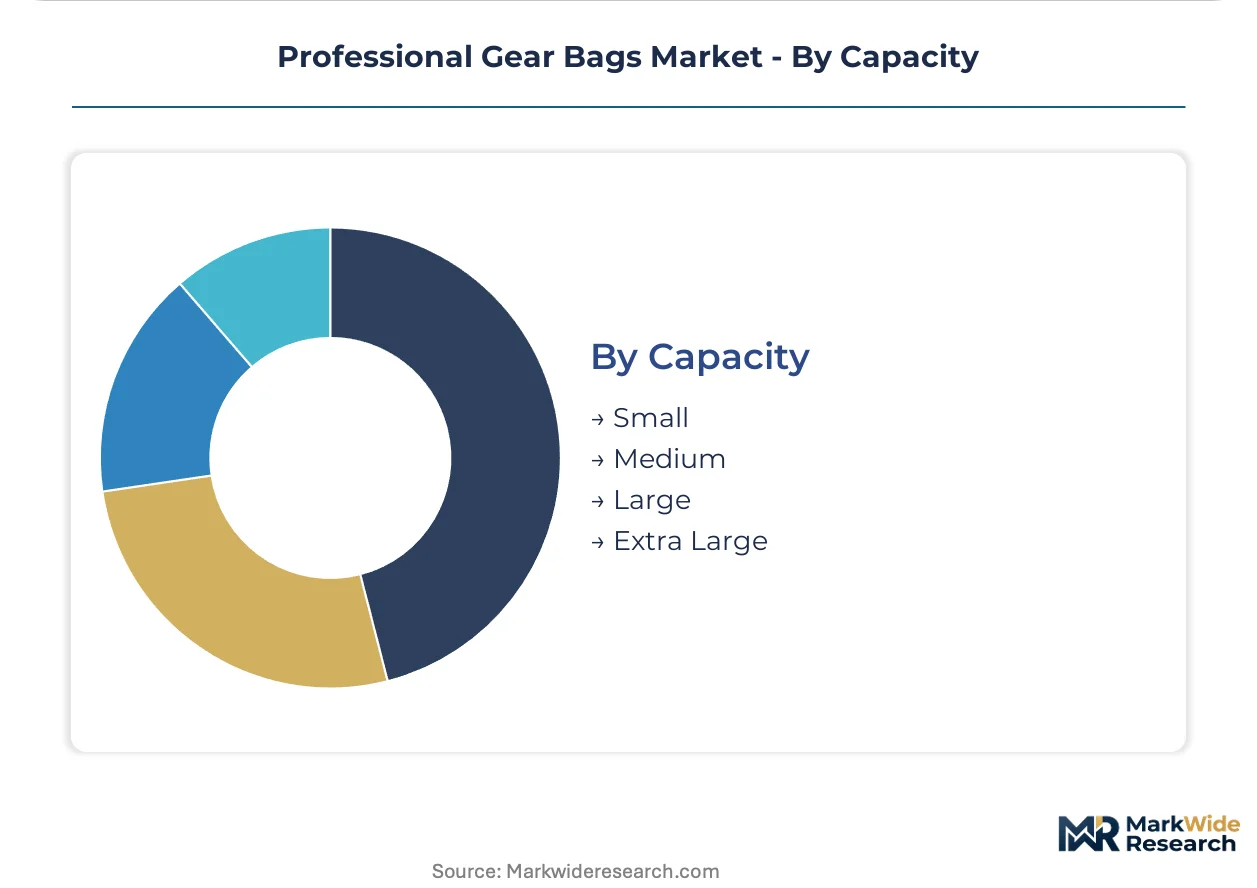
Medium capacity holds the largest share; small configurations are climbing the fastest as camera miniaturization reduces payload requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing capacity clusters in Guangdong and Zhejiang provinces feed both export demand and indigenous brand formation, while compliance divergence across jurisdictions fragments product specifications. Demand generation concentrates in metropolitan creative corridors where freelance operators outnumber institutional procurement.
United States
Los Angeles and New York creative districts generate concentrated demand from independent photographers and videographers. FAA carry-on dimensional restrictions shape rolling bag specifications for location cinematographers. California's Proposition 65 labeling requirements impose chemical disclosure obligations that complicate SKU management for imported goods.
China
Guangdong and Zhejiang production clusters scale manufacturing for global export while domestic consumption absorbs premium indigenous brands. MIIT standards for product quality and SAMR market supervision shape certification requirements for local distribution. Shenzhen and Dongguan municipalities concentrate hard-shell case molding capacity alongside soft-goods assembly.
Germany
Berlin and Munich creative districts drive specification intensity for modular backpack systems among freelance operators. ECHA REACH Annex XVII restrictions on perfluorinated compounds force reformulation of water-repellent fabric treatments. Bavarian industrial zones host specialized textile finishing operations serving premium bag assemblers.
India
Mumbai, Bengaluru, and Delhi production clusters scale to serve domestic wedding photography and regional cinema equipment transport. BIS quality standards create entry barriers for uncertified imports. Maharashtra and Karnataka states concentrate both manufacturing capacity and end-user demand generation.
United Kingdom
London creative professionals sustain demand for premium positioning and heritage aesthetic differentiation. CSRD sustainability disclosure requirements affect corporate procurement specifications for AV departments. City of London and West End districts sustain leather-tier briefcase crossover demand from legal and financial practitioners.
Professional Gear Bags Market Vendor Landscape
Concentration sits with diversified luggage conglomerates and specialized protective equipment fabricators rather than pure-play camera bag specialists. Hard-shell case manufacturers command broadcast and military verticals through impact certification barriers. Three strategic archetypes dominate: automotive-heritage lifestyle extenders, military-contract suspension specialists, and resin-formulation protective case engineers. Competitive moves center on direct-to-creator channel construction and REACH-compliant chemistry partnerships with Korean and Taiwanese textile processors.
Within the diversified luggage tier, Samsonite International and VF Corporation occupy positions anchored by global distribution infrastructure and multi-brand portfolio breadth. Pelican Products, Inc. exemplifies the protective case engineering archetype through proprietary resin formulations and lifetime warranty positioning. Thule Group represents automotive-heritage extension into rolling transport systems, leveraging rack-mounted equipment trust into mobile creative workflows. These three anchors illustrate how competitive advantage derives from supply chain control, material science certification, and channel access rather than undifferentiated product breadth.
| Leading Market Players |
|---|
| Samsonite International |
| VF Corporation |
| Pelican Products, Inc. |
| Thule Group |
| Mystery Ranch |
| Lowepro |
| Peak Design |
| Osprey Packs |
| Direct Action Gear |
| Others |
Supply Flow & Price Mechanics
Sixty-to-ninety-day fabric-finishing lead times from Korean and Taiwanese chemical processors compress pricing power for European and North American assemblers lacking backward integration into coated textile supply. This inventory-to-delivery gap concentrates margin capture with upstream chemical processors while forcing bag manufacturers to absorb reformulation costs from REACH Annex XVII compliance or surrender volume to certified competitors.
Pricing Analysis
REACH Annex XVII dictates the pricing tier structure across the Professional Gear Bags Market by imposing compliance cost differentials that separate certified silicone-based water-repellent finishes from legacy C6 treatments. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and volume scale, with rolling bag configurations for EU location cinematography commanding the steepest premiums due to accelerated compliance timelines. Cost compression in mid-tier recycled polyester constructions is intensifying because GRS certification costs are decomposing historical sustainable premiums. Corporate AV departments in California and Texas demonstrate lowest price sensitivity through mandated recycled-content RFPs, while freelance photographers in Berlin and Paris exhibit highest sensitivity as direct-to-creator e-commerce fragments traditional dealer margins.
Supply Chain Analysis
Port congestion on Shanghai-to-Long Beach trade lanes elevates inbound logistics costs for North American distributors dependent on Guangdong and Zhejiang assembly clusters. Manufacturing concentrates in China, South Korea, and Taiwan, with raw material dependencies spanning high-tenacity polyamide 6,6 filament, silicone-based water-repellent chemistries, and injection-molded polymer resins. Single-source vulnerability sits with Korean and Taiwanese coated-fabric finishing capacity, creating chokepoint exposure for REACH-compliant European assemblers. Distribution runs through direct-to-creator e-commerce storefronts and traditional rental house networks, with channel compression most advanced in North American and Western European markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Freelance creative professionals are fragmenting demand into modular, single-operator niches that reward specialized engineering over undifferentiated breadth. This demand-side shift creates entry points for focused players while pressuring conglomerate portfolios optimized for bulk institutional procurement.
For Market Incumbents: Fortify REACH-compliant chemistry partnerships with Korean and Taiwanese textile processors to defend margin position against certified competitors. Deepen direct-to-creator channel infrastructure in Los Angeles and Berlin creative districts where freelance photographers bypass traditional dealer networks. Invest in field-replaceable component design to capture France's anti-waste circular economy law compliance premiums before EU right-to-repair frameworks harden procurement specifications.
For New Entrants and Emerging Players: Lead with RFID-enabled compartment tracking integration for Mumbai and Bengaluru rental houses seeking mobile asset management without separate scanning infrastructure. Target India's wedding photography and regional cinema equipment transport segment where BIS quality standards create entry barriers for uncertified imports. Pursue white-label manufacturing partnerships with Guangdong clusters to compress lead times for Asia-Pacific fulfillment.
For Investors and Strategic Acquirers: Long-term, this sits as a compliance-arbitrage play because regulatory chemistry shifts are decomposing legacy competitive moats while opening premium positioning for traceable supply chains. Acquisition targets should prioritize brands with documented silicone-based water-repellent reformulations and established Korean processor relationships. Monitor ECHA Annex XVII expansion timelines as inflection indicators for accelerated C6/C8 phase-out enforcement.
| Strategic Initiative | Industry Significance |
|---|---|
| REACH-Compliant Chemistry Partnership | Secures European market access as ECHA Annex XVII restrictions eliminate legacy water-repellent treatments. |
| Direct-to-Creator E-Commerce Launch | Bypasses dealer networks in Los Angeles and Berlin where freelance photographers research through video review platforms. |
| Modular Repairability Redesign | Captures France's anti-waste law compliance premiums ahead of EU right-to-repair procurement mandates. |
| RFID-Enabled Inventory Integration | Converges with mobile asset management platforms for Mumbai and Bengaluru rental house monitoring. |
| India Production Cluster Scaling | Serves domestic wedding photography demand while meeting BIS quality standards that block uncertified imports. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted across the primary research phase, encompassing freelance photographers in Los Angeles, Berlin, and Tokyo, rental house procurement managers in Mumbai and Bengaluru, textile finishing engineers at Korean and Taiwanese chemical processors, and brand supply chain directors at diversified luggage conglomerates. Secondary validation drew from ECHA REACH regulatory filings, MIIT and SAMR certification databases, customs trade records for nylon and polyester resin flows, and corporate sustainability disclosures under CSRD frameworks. Bottom-up segment sizing triangulated against top-down macroeconomic indicators across the analysis window.
Across the projection horizon, the analytical framework modeled volume and value outputs through disaggregation by product type, material certification tier, end-user archetype, and capacity configuration, with regional regulatory clusters treated as distinct demand envelopes. CAGRs were derived from segment-level growth rate synthesis rather than single-point extrapolation. Industry-specific forecast inputs incorporated REACH Annex XVII compliance timeline assumptions and freelance creative professional formation rates in metropolitan creative corridors.
Forecasts assume regulatory continuity in EU REACH, California Proposition 65, and India BIS regimes; material policy shifts would require re-modeling of coated fabric supply chain economics and SKU management complexity. Specific risks that could revise projections include accelerated perfluorinated compound bans, petrochemical input volatility affecting nylon and polyester resin pricing, and hard-shell case substitution in broadcast verticals where impact certification is non-negotiable. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Outdoor Gear
Shared Umbrella Market
Outdoor Gear
UK Camping Equipment Market
Outdoor Gear
US Backpacks Market
Outdoor Gear
Canoe Paddles Market
Outdoor Gear
Australia Camping Equipment Market
Outdoor Gear
Deer Hunting Blinds Market
Outdoor Gear
North America Pocket Knives Market
Outdoor Gear
Outdoor Hot Tub Market
Outdoor Gear
Global Automatic Mower Market
Outdoor Gear
Fairway Mowers Market
Outdoor Gear
Sleeping Bag Market
Outdoor Gear
Crash Pads Market
Outdoor Gear
China Camping Tent Market
Outdoor Gear
Bicycle Bags and Bag Packs Market
Outdoor Gear
Cordless Garden Equipment Market
Outdoor Gear
Diving Regulator Market