
 UK Camping Equipment Market | 2026-2036
UK Camping Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
UK Camping Equipment Market Insights
Scotland is narrowing its manufacturing gap in technical outdoor textiles as Glasgow-based production clusters attract specialist labor. Dometic Group AB leverages its caravan and motorhome heritage to anchor premium coolbox and portable refrigeration lines within UK retail channels. VF Corporation, through its portfolio approach, sustains brand diversification across multiple price tiers while competing aggressively in direct-to-consumer digital channels.
UK camping equipment encompasses portable shelter systems, sleep systems, cooking apparatus, lighting, and furniture engineered for temporary outdoor habitation, typically constructed from ripstop nylon, aluminum alloys, and closed-cell foam to achieve weight-to-durability ratios measured in denier and hydrostatic head ratings. The primary commercial purpose centers on enabling safe, comfortable overnight stays in non-permanent locations without grid infrastructure. Tents and sleeping bags command the largest revenue pools due to replacement cycles and weather-driven upgrade patterns, while festival camping emerges as the fastest-growing application segment driven by multi-day event attendance and rental-to-purchase conversion. Cooking gear and lighting equipment concentrate margin pools in the premium tier where lithium-ion power integration and solar compatibility differentiate offerings.
The UK's Trading Standards office enforces Product Safety and Metrology Regulations on camping gas appliances and electrical equipment, while the British Standards Institution maintains BS EN 5912 for tent safety and BS 7837 for flammability of temporary structures, collectively shaping design mandates and import compliance costs. The Environment Agency's water framework directives restrict campsite development near sensitive catchments, redirecting demand toward established locations with permitted infrastructure. Stakeholders must monitor pending revisions to extended producer responsibility frameworks for textile waste, as these will alter material selection criteria and end-of-life collection obligations across the supply chain.
Market Dynamics
Post-pandemic outdoor recreation habits have solidified into durable demand patterns, with family outings and festival attendance driving replacement cycles for portable shelter and sleep systems while the UK's Environment Agency tightens water quality compliance near protected waterways.
Growth Catalysts
- BS EN 5912 tent safety standards:Mandatory compliance elevates product quality thresholds, filtering low-grade imports and rewarding certified domestic distributors with shelf space in major retail channels.
- Festival camping segment:Multi-day music and cultural events convert rental users to purchasers, compressing replacement cycles for entry-level equipment and driving accessory attach rates.
- Lake District infrastructure investment:Permitted campsite development concentrates demand in England's premier outdoor region, anchoring distribution network density and service center placement.
Market Restraints
- Ripstop nylon supply concentration:Technical textile production clusters in East Asia create input cost volatility and extended lead times for UK manufacturers lacking backward integration.
- Extended producer responsibility frameworks:Pending textile waste regulations impose end-of-life collection obligations, increasing material selection costs and compliance overhead.
- Flammability standard BS 7837:Temporary structure fire safety mandates restrict design freedom for ultra-lightweight shelter systems, compressing innovation headroom.
Strategic Opportunities
- Scottish Highlands campsite expansion:Permitted infrastructure growth in protected catchment areas redirects demand toward established locations with compliant wastewater systems.
- Lithium-ion power integration:Portable refrigeration and lighting equipment converges with solar compatibility, opening premium tier margin pools in off-grid habitation systems.
- Direct-to-consumer digital channels:Brand diversification across price tiers accelerates through owned e-commerce, disintermediating traditional outdoor retail gatekeepers.
Industry Challenges
- Specialist textile labor scarcity:Glasgow-based production clusters compete for technical outdoor fabric expertise against established European manufacturing centers.
- Product Safety and Metrology Regulations:Trading Standards enforcement on camping gas appliances creates certification timeline friction for seasonal product launches.
- Weather-driven upgrade pattern unpredictability:Demand forecasting complexity increases as extreme climate events compress tent and sleeping bag replacement decisions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UK Camping Equipment Market |
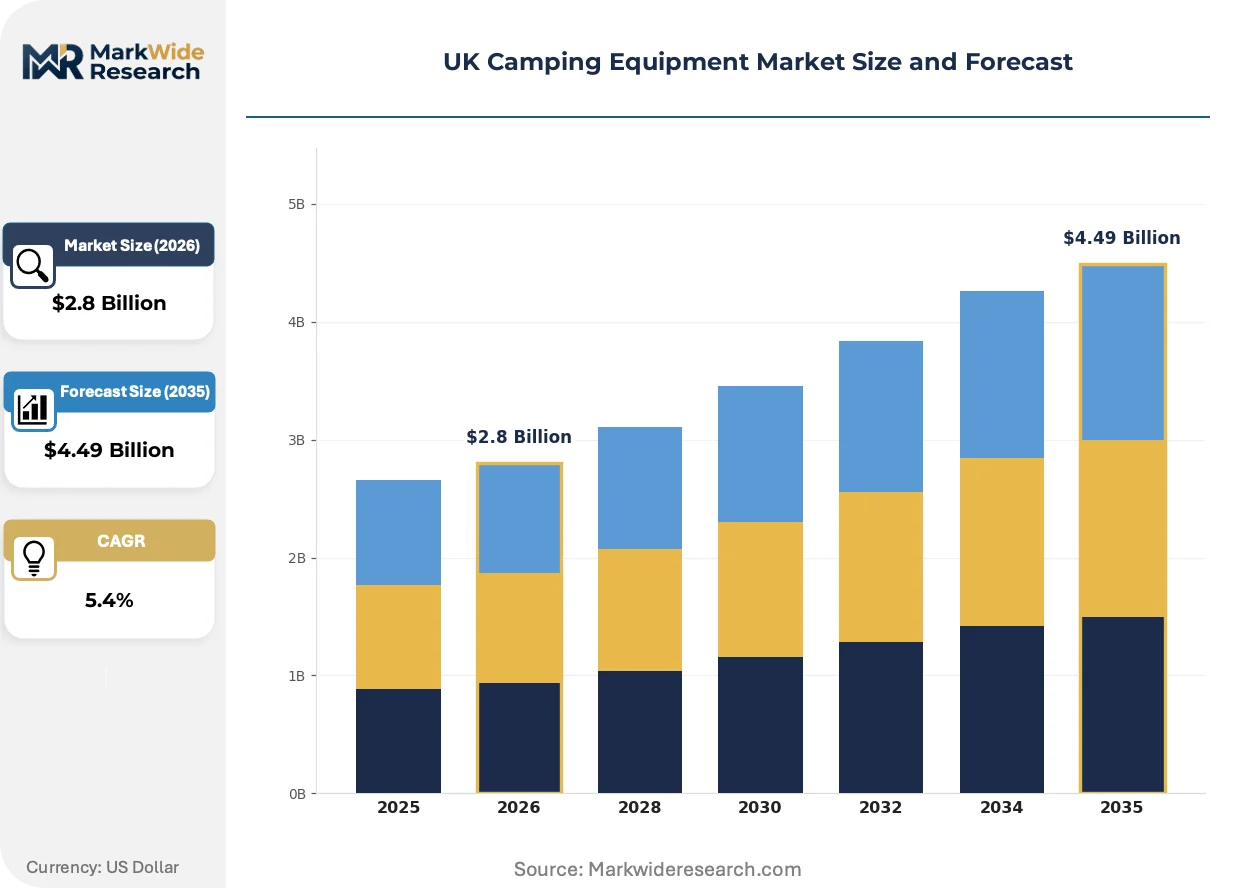
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.49 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tents, Sleeping Bags, Backpacks, Cooking Gear, Lighting Equipment, Camp Furniture Material: Polyester, Nylon, Aluminum, Stainless Steel, Foam, Rubber Application: Recreational Camping, Survival Camping, Hiking Expeditions, Family Outings, Backpacking, Festival Camping Customer Type: Outdoor Enthusiasts, Families, Adventure Travelers, Schools & Clubs, Wildlife Researchers, Retailers |
| Companies Covered | Dometic Group AB, VF Corporation, Johnson Outdoors, Newell Brands, Oase Outdoors ApS, Big Agnes, AMG Group, Decathlon S.A., NEMO Equipment, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UK Camping Equipment Market Trends and Innovations
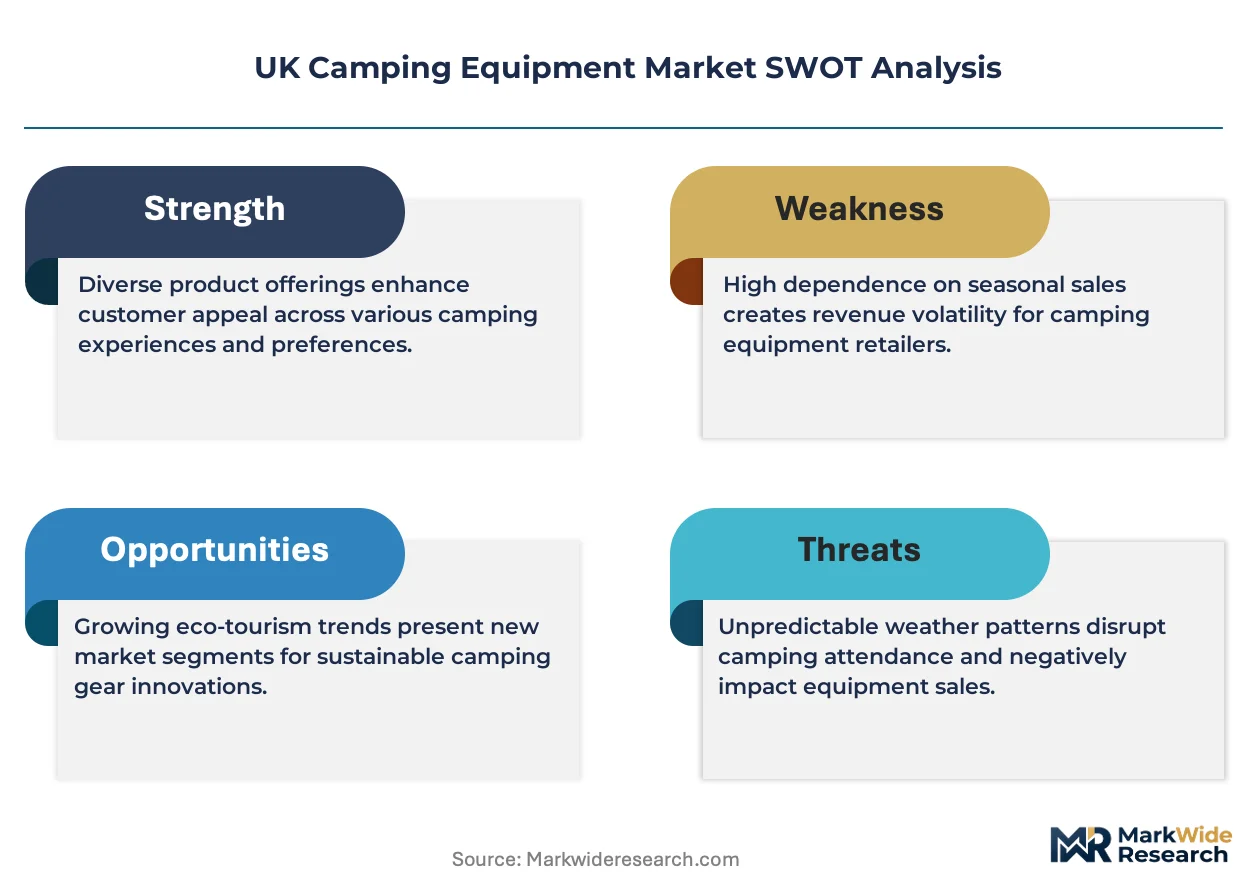
Three intersecting developments are restructuring competitive advantage in UK camping equipment: materials science advances, regulatory compliance automation, and buyer channel migration toward digital-first discovery and purchase.
Closed-cell foam and air-beam construction is collapsing the weight-to-durability tradeoff that historically segmented premium from mass-market sleep and shelter systems. Festival campers and lightweight backpackers adopt these technologies simultaneously, eroding the traditional price-tier boundary that organized brand positioning. Manufacturers now compete on integrated system design rather than isolated component specifications.
REACH chemical restrictions and the EU Green Deal's textile sustainability mandates are reshaping material sourcing decisions for UK importers. Substances of very high concern screening now precedes supplier qualification, extending product development timelines but creating defensible compliance positions. Dometic Group and similar caravan heritage players leverage existing supply chain audit infrastructure to accelerate certification.
Rental-to-purchase conversion models are fragmenting the traditional retail channel structure. Festival operators and outdoor experience platforms now intermediate equipment acquisition decisions, capturing customer relationships that previously flowed through specialty retailers. This behavioral shift concentrates most visibly in England's festival circuit, where multi-day event attendance normalizes trial before commitment.
UK Camping Equipment Market Segmentation
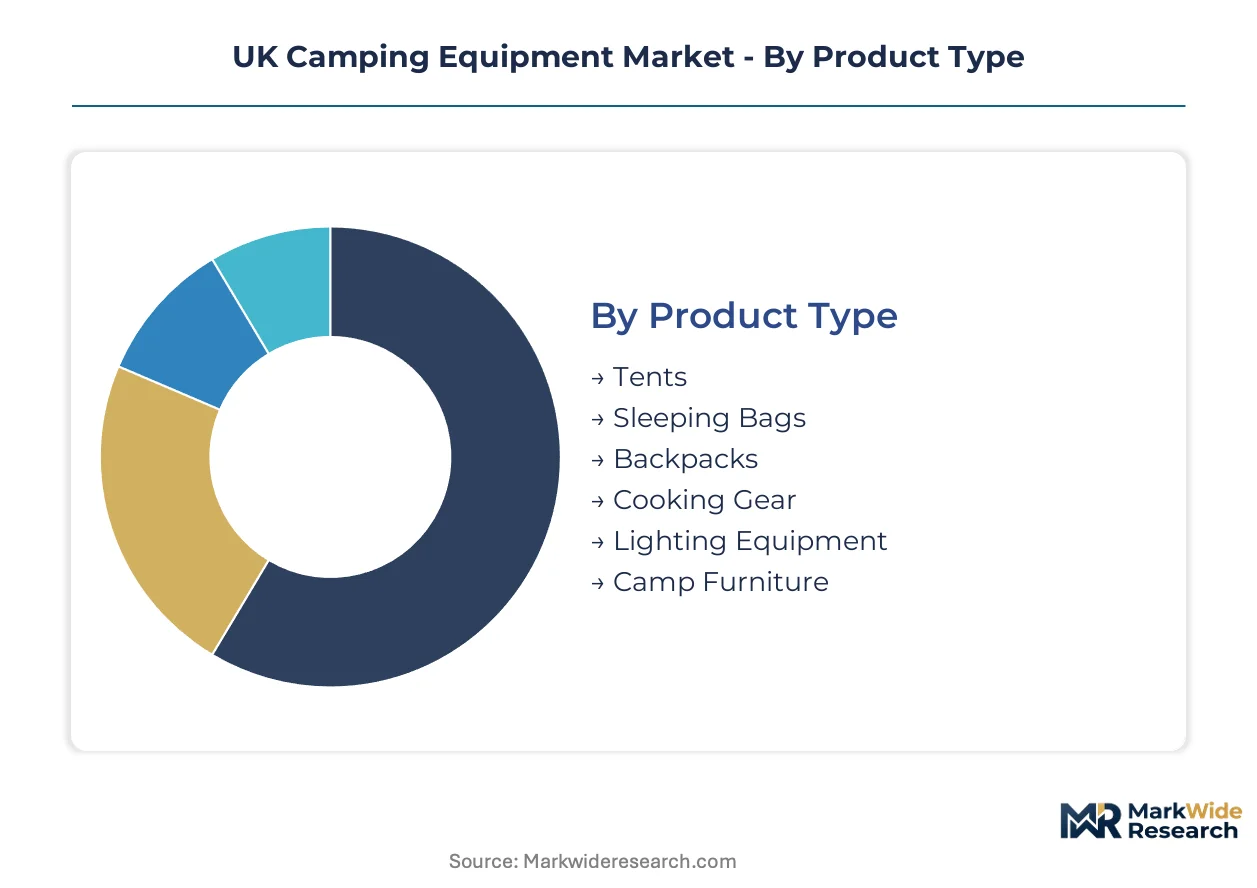
Segmentation in UK camping equipment reveals distinct service requirements and replacement cycles across product categories. Technical shelters demand seasonal maintenance support while consumable accessories rotate on faster purchase frequencies.
Product Type:
After-sales intensity varies sharply across equipment categories, with structural shelters requiring warranty servicing and seasonal repair networks while portable accessories operate on disposable replacement models.
- Tents:Portable shelter systems engineered from ripstop nylon and aluminum alloy poles, measured by hydrostatic head ratings and denier specifications. Demand concentrates in England's Lake District where campsite infrastructure investments anchor replacement cycles driven by weather damage and capacity upgrades. By volume, Tents leads. By growth pace, technical lightweight designs for backpackers are expanding most quickly.
- Sleeping Bags:Insulated sleep systems utilizing down or synthetic fill with temperature rating certifications under EN 13537. Scottish Highlands camping permits drive cold-weather specification demand where baffle construction and draft collar engineering differentiate premium tiers. By volume, Sleeping Bags leads. By growth pace, synthetic-fill festival-oriented models are climbing the fastest.
- Backpacks:Load-bearing systems with internal frame suspension and hip belt load transfer.
- Cooking Gear:Portable stoves and cookware meeting BS EN 521 and BS EN 497 safety mandates for gas appliance ignition stability.
- Lighting Equipment:LED and solar-integrated illumination with lithium-ion power storage.
- Camp Furniture:Collapsible seating and sleeping platforms utilizing aluminum tubing and tension fabric.
By volume, Tents commands the largest installed base. By growth pace, Lighting Equipment with power integration features is gaining share fastest.
Material:
Cost tier stratification follows raw material selection, with technical synthetics commanding premium positioning and commodity metals anchoring mass-market accessibility.
- Polyester:Woven synthetic fabric with PU coating treatments for UV degradation resistance, dominating entry-level tent flysheet production. Family outing segments in England's established campsites drive volume procurement where cost efficiency outweighs gram-count optimization.
- Nylon:High-tenacity ripstop weave with silicone elastomer face coatings, specified for lightweight backpacking and technical mountaineering shelters. Scottish Highlands expedition demand prioritizes tear strength and packability where denier ratings below 30D signal premium positioning.
- Aluminum:7000-series and 6000-series alloys for tent pole and furniture frame construction.
- Stainless Steel:Corrosion-resistant cooking apparatus and utensil substrates.
- Foam:Closed-cell and open-cell constructions for sleeping pad insulation and cushioning.
- Rubber:Sealing gaskets and flexible tubing for liquid fuel systems and hydration reservoirs.
By volume, Polyester leads material consumption. By growth pace, technical Nylon specifications for weight-sensitive applications show steepest expansion trajectory.
Application:
Customer maturity and purchase frequency diverge across use cases, with occasional recreational users exhibiting rental-to-purchase conversion patterns distinct from dedicated expedition specialists.
- Festival Camping:Multi-day event attendance driving entry-level equipment acquisition with high accessory attach rates for lighting and seating. England's music festival circuit concentrates demand where rental-to-purchase conversion compresses replacement cycles for shelter and sleep systems.
- Family Outings:Car-accessible campsite recreation emphasizing capacity, weather protection, and rapid pitch convenience. Lake District infrastructure investments anchor this segment where post-pandemic outdoor habits have solidified into durable demand patterns.
- Recreational Camping:General leisure use in established campgrounds with vehicle access.
- Survival Camping:Emergency preparedness and bushcraft skill application.
- Hiking Expeditions:Multi-day trail-based travel with weight-constrained loadouts.
- Backpacking:Self-supported wilderness travel with technical performance requirements.
By volume, Family Outings leads application demand. By growth pace, Festival Camping is expanding most quickly.
Customer Type:
Procurement authority and volume scale separate institutional buyers from individual consumers, with schools and clubs exhibiting seasonal concentration patterns distinct from dispersed household purchasing.
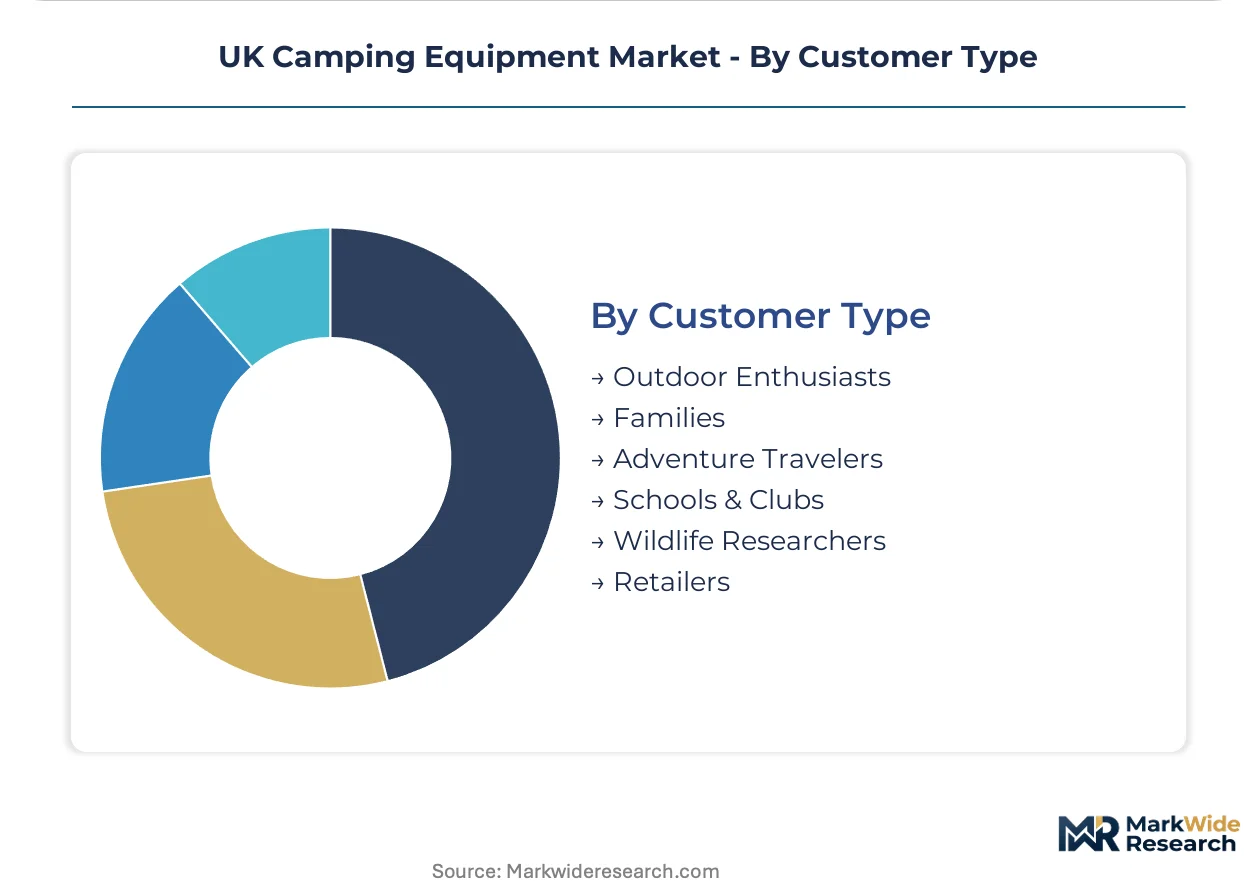
- Families:Multi-person equipment specifications prioritizing capacity, durability, and ease of use for car-camping scenarios. England's established campsite networks concentrate this demand where replacement cycles follow weather-driven damage and growing household size.
- Outdoor Enthusiasts:Dedicated recreationalists with technical knowledge driving specification-heavy purchases across multiple product categories. Scottish Highlands and Lake District geography anchors this segment where upgrade patterns follow materials science advances and weight reduction innovations.
- Adventure Travelers:International destination campers requiring compact, airline-checkable equipment specifications.
- Schools & Clubs:Institutional procurement with batch purchasing and storage logistics requirements.
- Wildlife Researchers:Extended field deployment specialists requiring expedition-grade durability certifications.
- Retailers:Channel intermediaries stocking inventory for resale with seasonal pre-order patterns.
By volume, Families lead customer type demand. By growth pace, Outdoor Enthusiasts with technical upgrade frequency are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing of technical outdoor textiles clusters in Glasgow and surrounding Scottish Central Belt, narrowing the historical production gap with continental European suppliers. Distribution networks anchor around England's Lake District and Scottish Highlands where campsite infrastructure investments concentrate demand.
England
Family outing segments drive volume demand across the Lake District and Peak District where campsite permits have expanded post-pandemic. Trading Standards enforces Product Safety and Metrology Regulations on camping gas appliances entering retail channels. Birmingham and Manchester distribution hubs service midlands and northern retail networks with seasonal pre-positioning.
Scotland
Highlands camping permits and expedition-grade equipment specifications dominate technical demand where cold-weather performance differentiates purchase decisions. The Environment Agency's water framework directives restrict development near sensitive catchments, redirecting demand toward established sites. Glasgow-based production clusters attract specialist textile labor for ripstop nylon and technical fabric finishing.
Wales
Snowdonia National Park camping infrastructure anchors regional demand for lightweight backpacking equipment suited to trail-based access. Natural Resources Wales administers water quality protections that shape campsite compliance requirements. Pembrokeshire coastal clusters concentrate glamping and eco-camping development with premium equipment specifications.
Northern Ireland
Causeway Coast and Mourne Mountains camping zones drive seasonal demand concentrated in summer months with rapid pitch convenience prioritized. The Northern Ireland Environment Agency implements water quality regulations parallel to UK-wide frameworks. Belfast serves as the primary distribution gateway with limited specialist retail presence relative to GB markets.
UK Camping Equipment Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in fabric, pole, and insulation supply. The UK camping equipment market structures around heritage caravan manufacturers extending into portable refrigeration, diversified outdoor conglomerates with portfolio brand strategies, and specialist tent and sleep system engineers. Three archetypes dominate: caravan heritage players leveraging existing retail relationships, multi-brand outdoor corporations optimizing direct-to-consumer channels, and technical equipment specialists competing on weight-to-durability specifications. Competitive moves concentrate on lithium-ion power integration partnerships and Scottish textile cluster capacity expansion.
Among heritage-anchored platform players, Dometic Group AB exemplifies the caravan-to-camping extension archetype, while VF Corporation occupies the multi-brand portfolio position. Johnson Outdoors represents the dedicated outdoor equipment specialist tier. These three companies collectively illustrate the competitive vectors shaping UK market positioning: thermal management expertise, brand diversification across price tiers, and technical product engineering respectively.
| Leading Market Players |
|---|
| Dometic Group AB |
| VF Corporation |
| Johnson Outdoors |
| Newell Brands |
| Oase Outdoors ApS |
| Big Agnes |
| AMG Group |
| Decathlon S.A. |
| NEMO Equipment |
| Others |
Pricing and Supply Chain Analysis
East Asian container freight corridors from Shanghai to Felixstowe transmit cost volatility directly into UK retail pricing, amplifying margin pressure for distributors lacking forward-contract coverage while compressing price differentiation between mass-market polyester shelters and premium nylon specifications.
Pricing Analysis
BS EN 5912 tent safety standards dictate the pricing tier structure across the UK camping equipment landscape. Three-tier pricing structure across premium, standard, and economy levels segments buyers by certification burden and after-sales service bundling. Price differentiation hinges on hydrostatic head ratings and denier specifications, with festival campers exhibiting highest price sensitivity while Scottish Highlands expedition specialists tolerate premium positioning for cold-weather performance. Cost compression in the economy tier is intensifying because Trading Standards enforcement timelines compress seasonal launch windows.
Supply Chain Analysis
Tariff exposure between China and the UK dominates supply chain risk planning for technical textile procurement. Manufacturing concentration in China, Taiwan, and Vietnam feeds ripstop nylon and silicone-coated fabric requirements, with raw material dependencies centering on petrochemical derivatives and aluminum alloy extrusions. Single-source vulnerability in 7000-series tent pole alloys threatens production continuity. Distribution runs through Birmingham and Manchester hubs with seasonal pre-positioning ahead of Lake District peak demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward festival operators and outdoor experience platforms as these intermediaries consolidate equipment procurement decisions across England's event circuit, fragmenting traditional specialty retail channel control.
For Market Incumbents: Insulate margin position by deepening backward integration into Glasgow-based textile finishing capacity and accelerating lithium-ion power system certification ahead of Trading Standards enforcement waves. Channel control through exclusive festival operator partnerships defends against rental-to-purchase conversion platforms eroding direct customer relationships. For New Entrants and Emerging Players: Northern Ireland's limited specialist retail presence offers white-space entry for direct-to-consumer digital brands targeting Causeway Coast seasonal demand with rapid-pitch convenience positioning. Wales Snowdonia trail-accessible lightweight segments present secondary penetration opportunity through eco-camping certification alignment with Natural Resources Wales sustainability mandates. For Investors and Strategic Acquirers: Technical outdoor fabric specialists with REACH compliance infrastructure and Scottish Central Belt production assets represent the priority acquisition archetype. Long-term viability across the analysis window rests on defensible regulatory positioning as extended producer responsibility frameworks reshape material selection economics. The signal to watch is Environment Agency wastewater directive enforcement intensity redirecting campsite permitting toward established infrastructure locations.| Strategic Initiative | Industry Significance |
|---|---|
| Lithium-Ion Power Integration Partnership | Portable refrigeration convergence with solar compatibility opens premium margin pools in off-grid habitation systems. |
| Scottish Textile Cluster Capacity Expansion | Glasgow-based production narrows manufacturing gap with continental European technical outdoor fabric suppliers. |
| Festival Operator Channel Partnership | Multi-day event intermediaries capture customer relationships previously flowing through specialty outdoor retailers. |
| REACH Compliance Automation Investment | Substances of very high concern screening accelerates supplier qualification timelines for UK importers. |
| Direct-to-Consumer Digital Platform Launch | Owned e-commerce disintermediates traditional outdoor retail gatekeepers across price tier diversification. |
Research Methodology
The analysis maps portable shelter systems, sleep systems, cooking apparatus, and lighting equipment segments, each validated through equipment procurement managers at festival operators, category buyers at outdoor retailers, textile sourcing directors, and campsite infrastructure planners. Primary interviews with these stakeholders combined with secondary validation from British Standards Institution certification databases, Environment Agency permitting records, UK customs import classifications, and Trading Standards enforcement bulletins. Bottom-up product category volume estimates and top-down market sizing triangulate through cross-referencing distributor shipment data and retail channel inventory turns.
Fixed assumptions across the modeling period include continuation of BS EN 5912 and BS 7837 regulatory frameworks, stable Environment Agency water quality directive enforcement patterns, and observed post-pandemic outdoor recreation habit persistence. Segmentation dimensions modeled encompass product type, material specification tier, application use case, and customer procurement authority. CAGRs derive from trend extrapolation of replacement cycle frequencies, infrastructure investment permit approvals, and materials science adoption curves. Forecast inputs incorporate lithium-ion battery cost trajectories and Scottish textile cluster labor availability indices.
The forecast holds incumbent behavior within observed patterns; aggressive moves by platform-integrated experience operators or vertically integrated Asian manufacturers would shift outcomes beyond modeled ranges. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Outdoor Gear
Camping Equipment Market
Outdoor Gear
Wheeled Insulated Cooler Market
Outdoor Gear
Outdoor Camping Toilet Market
Outdoor Gear
Japan Camping Equipment Market
Outdoor Gear
Global Automatic Mower Market
Outdoor Gear
Camp Fire Tripod Market
Outdoor Gear
Professional Gear Bags Market
Outdoor Gear
Shared Umbrella Market
Outdoor Gear
South Korea Camping Equipment Market
Outdoor Gear
Japan Camping Tent Market
Outdoor Gear
Hunting Boots Market
Outdoor Gear
Diving Equipment Market
Outdoor Gear
Inflatable Tents Market
Outdoor Gear
Snow Chain Market
Outdoor Gear
Camping Equipment and Furniture Market
Outdoor Gear
Australia Camping Equipment Market