
 Agritourism Market | 2026-2036
Agritourism Market Size, Share, and Industry Trends Forecast 2026-2036
Agritourism Market Intelligence
Subscription-based seasonal farm membership programs is recalibrating how agritourism operators monetize recurring visitor relationships. Blackberry Farm LLC leverages its estate-scale hospitality infrastructure to sustain year-round occupancy rates above regional norms. Harvest Travel International anchors its competitive position through curated multi-farm itinerary design across diverse agricultural zones. Agrilys Voyages differentiates by controlling direct vineyard relationships in France rather than relying on third-party farm contracts.
Agritourism denotes commercial enterprise models where working agricultural properties generate visitor revenue through accommodation, education, or recreation services integrated with active farming operations. Properties typically span 50 to 500 hectares, combining hospitality infrastructure with certified organic or conventional production systems to deliver authentic rural experiences. Farm stays and vineyard accommodations command the highest margin pools within the type segmentation due to extended length-of-stay and ancillary food-and-beverage spending. Educational visits represent the fastest-growing visitor category as school curricula and university agriculture programs formalize field-based learning requirements. Online travel agencies capture disproportionate booking volume among international visitors, though direct booking channels retain superior net revenue per transaction for farm operators.
FDA food safety protocols and USDA organic certification standards govern on-farm food service and product retail activities in the United States, while the EU Green Deal's Farm to Fork strategy imposes sustainability disclosure obligations on agritourism enterprises across Europe. These regulatory frameworks elevate compliance costs for small-scale operators but simultaneously create market access barriers that favor certified properties with documented environmental management systems. Stakeholders must monitor evolving carbon accounting requirements and visitor capacity regulations as rural municipalities balance economic development with infrastructure and conservation constraints.
Market Dynamics
The EU Green Deal's Farm to Fork strategy is recalibrating certification requirements across European agritourism properties, while family visitor segments drive demand for immersive educational programming that extends length-of-stay metrics.
Growth Catalysts
- EU Green Deal incentives:Sustainability disclosure obligations under the Farm to Fork strategy create competitive moats for certified organic properties, accelerating investment in environmental management systems across member states.
- School curriculum formalization:University agriculture programs and K-12 districts are mandating field-based learning hours, pulling educational visit volumes upward as institutions contract directly with working farms.
- Vineyard accommodation premiums:Extended-stay wine region properties in Italy's Tuscany cluster capture disproportionate ancillary food-and-beverage spend, anchoring margin expansion for estate-scale operators.
Market Restraints
- Compliance cost elevation:FDA food safety protocols and USDA organic certification standards impose documentation and infrastructure burdens that disproportionately constrain properties below 50 hectares.
- Seasonal occupancy volatility:Harvest-dependent demand curves force revenue concentration into narrow windows, compressing cash flow predictability for operators lacking year-round hospitality infrastructure.
- Direct booking channel weakness:Online travel agencies capture majority international visitor volume, extracting commission layers that erode net revenue per transaction for farm operators.
Strategic Opportunities
- Subscription membership models:Seasonal farm membership programs enable recurring revenue streams and advance booking commitments, reducing vacancy risk during shoulder seasons.
- Carbon accounting integration:Evolving municipal carbon disclosure requirements create first-mover advantages for properties with documented soil sequestration and renewable energy systems.
- Multi-farm itinerary curation:Aggregators designing cross-regional agricultural circuits can capture premium pricing by bundling diverse production experiences into extended rural tourism products.
Industry Challenges
- Hospitality-agriculture skill convergence:Properties require staff fluent in both farm operations and guest service delivery, creating recruitment friction in rural labor markets with limited hospitality training infrastructure.
- Visitor capacity regulation:Rural municipalities are tightening infrastructure and conservation constraints, forcing operators to navigate permitting complexity for accommodation expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Agritourism Market |
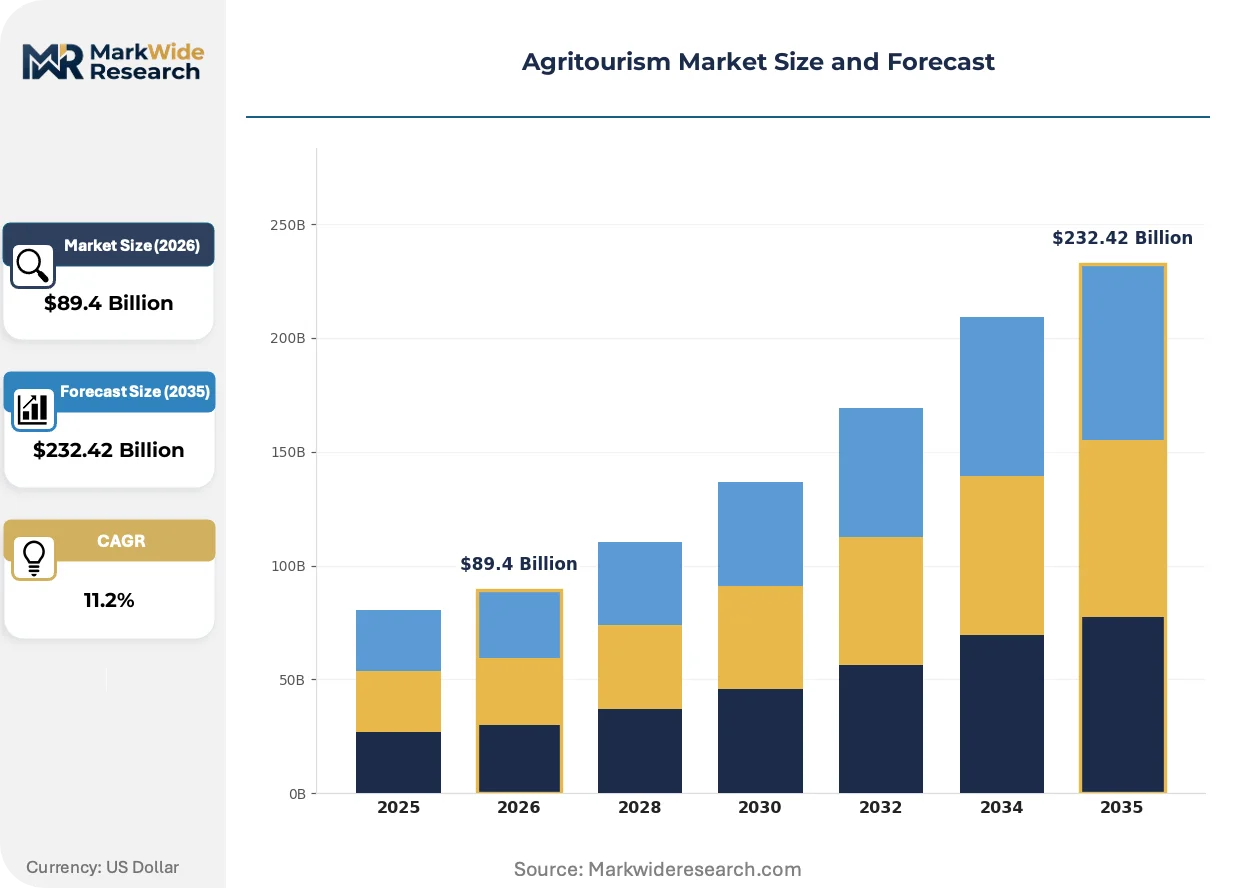
| Market Size in 2026 | $89.4 Billion |
| Market Size in 2035 | $232.42 Billion |
| CAGR (2026 – 2036) | 11.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Farm Stays, Agro Tours, Educational Visits, Recreational Activities, Pick-Your-Own Farms Visitor Profile: Families, Students, Eco-Tourists, Adventure Seekers, Retirees Farm Category: Crop Farms, Livestock Farms, Mixed Farms, Orchards, Vineyards Distribution Channel: Online Travel Agencies, Direct Booking, Tour Operators, Travel Agents, Local Tourism Offices |
| Companies Covered | Bay Farm Tours, Greenmount Travel, Blackberry Farm LLC, Field Farm Tours Limited, Harvest Travel International, Agricultural Tour Operators International, Farm To Farm Tours, Select Holidays, Agrilys Voyages, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Agritourism Market Strategic Shifts & Innovations
Digital booking infrastructure and sustainability certification systems are restructuring how agritourism properties acquire and retain visitor relationships across fragmented rural markets.
Sensor-based farm monitoring technology is expanding into visitor experience design. Estate properties deploy soil moisture and weather station data as educational touchpoints during guided tours. Family segments engage with real-time agricultural metrics through mobile interfaces. This transparency layer is expanding into premium pricing justification for properties with documented production practices.
EU Green Deal sustainability disclosure mandates are elevating compliance documentation requirements. Agritourism enterprises must now maintain verified environmental management systems to access member state incentive programs. Certified organic properties in France and Italy are responding by integrating third-party audit trails into guest-facing marketing materials.
Educational institutions are consolidating field-trip procurement through centralized district contracts. School agriculture programs now specify curriculum-aligned learning outcomes in vendor selection criteria. Direct booking relationships between farms and educational coordinators are displacing traditional travel agency intermediation in the United States and Germany.
Agritourism Market Segmentation
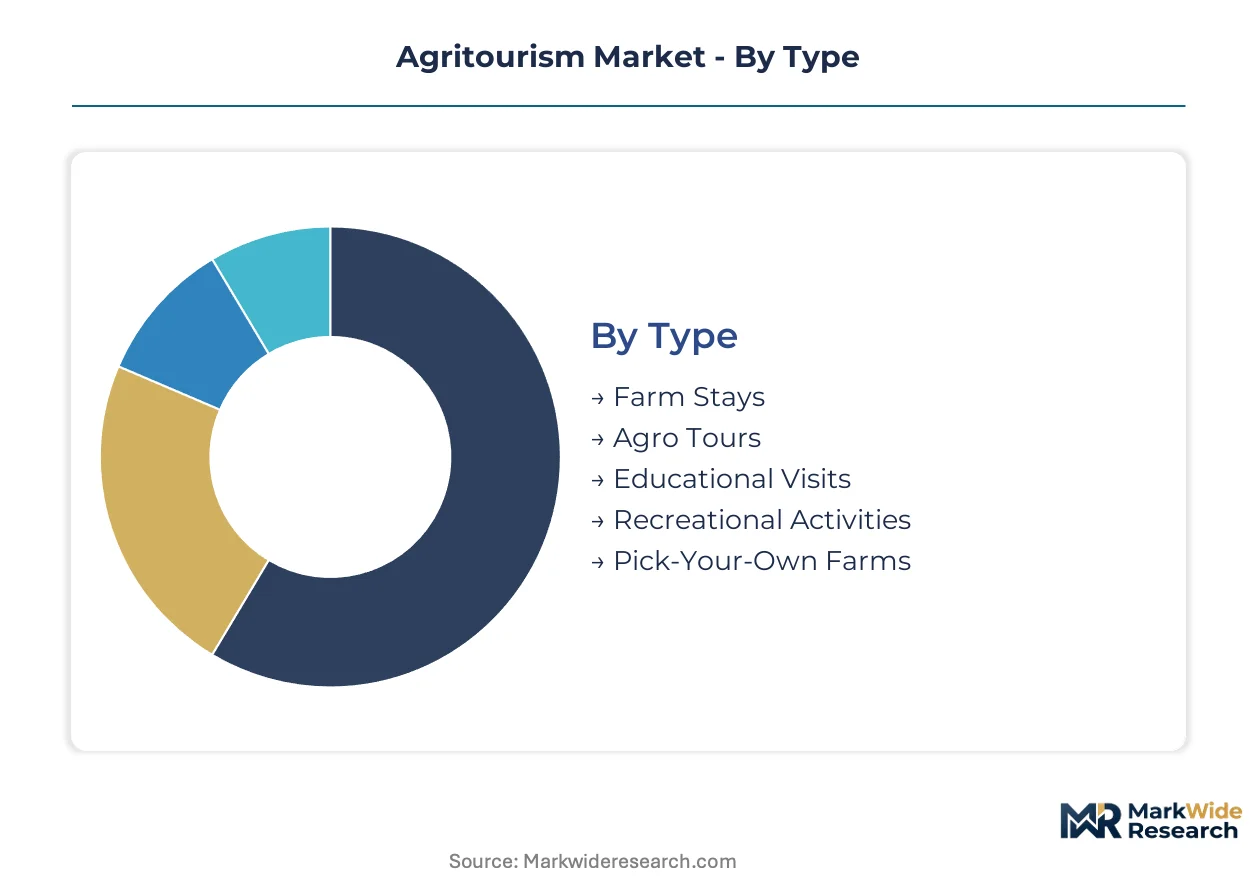
Agritourism operators segment their offerings across experience depth, visitor demographics, and farm infrastructure to match revenue models with operational capacity. Understanding these divisions reveals where premium pricing power concentrates and which channels capture margin.
Type:
Standardized day-trip formats compete against bespoke multi-night experiences across this spectrum, with property scale determining which formats prove economically viable.
- Farm Stays:Overnight accommodation integrated with working agricultural operations, typically featuring on-farm dining and guest participation in seasonal tasks. Tuscany vineyard estates and Provence lavender farms anchor premium pricing through extended length-of-stay and ancillary food-and-beverage spend.
- Educational Visits:Curriculum-aligned field experiences for K-12 districts and university agriculture programs. Germany's federal states and US Midwest school districts are formalizing mandatory farm-based learning hours, pulling institutional procurement toward direct farm contracts.
- Agro Tours:Guided excursions across multiple agricultural properties within a region. Operators bundle transportation and interpretation services for time-constrained visitors seeking breadth over depth.
- Recreational Activities:Experience-focused offerings including horseback riding, fishing, and hiking on agricultural land. Demand concentrates in properties adjacent to protected natural areas.
- Pick-Your-Own Farms:Direct consumer harvest participation for fruit and vegetable crops. Seasonal revenue windows limit this format to properties with diversified income streams.
Leading the category by volume: Farm Stays. Growing fastest: Educational Visits.
Visitor Profile:
Family units drive advance booking patterns and shoulder-season occupancy, while institutional contracts deliver revenue predictability distinct from leisure travel cycles.
- Families:Multi-generational groups seeking immersive rural experiences with child-friendly infrastructure. EU Green Deal sustainability incentives are steering this segment toward certified organic properties with documented environmental education programming.
- Students:School and university groups with curriculum-mandated field requirements. Direct procurement relationships between educational coordinators and farms are displacing traditional travel agency intermediation in the United States and Germany.
- Eco-Tourists:Visitors prioritizing carbon-neutral travel and regenerative agriculture exposure. Properties with third-party soil sequestration verification capture premium positioning.
- Adventure Seekers:Activity-focused travelers combining agricultural immersion with outdoor recreation. Demand clusters in mountainous and coastal farm regions with trail access.
- Retirees:Extended-stay visitors with flexible timing and higher per-diem spending. Off-peak travel patterns help operators smooth seasonal revenue curves.
Volume concentration: Families. Steepest expansion trajectory: Students.
Farm Category:
Production system characteristics determine hospitality infrastructure requirements and guest experience design possibilities across farm types.
- Vineyards:Wine region properties combining accommodation with cellar tours and tasting experiences. Italy's Chianti Classico zone and France's Bordeaux region sustain year-round occupancy through enotourism programming that extends beyond harvest season.
- Mixed Farms:Operations integrating crop and livestock production, offering diversified educational content. Crop-livestock rotation systems provide narrative depth for sustainability-focused marketing.
- Crop Farms:Arable and specialty crop operations with seasonal peak visibility. Harvest timing constraints compress revenue windows without supplemental hospitality infrastructure.
- Livestock Farms:Cattle, sheep, and dairy operations with animal interaction as core visitor draw. FDA food safety protocols govern on-farm dairy processing and product retail activities in the United States.
- Orchards:Tree fruit and nut operations with blossom and harvest season visitor peaks. Agritourism revenue often subsidizes multi-year cultivation cycles.
Margin leadership: Vineyards. Fastest volume gains: Mixed Farms.
Distribution Channel:
Channel selection determines customer acquisition cost and net revenue per transaction, with international versus domestic visitor mix driving platform strategy.
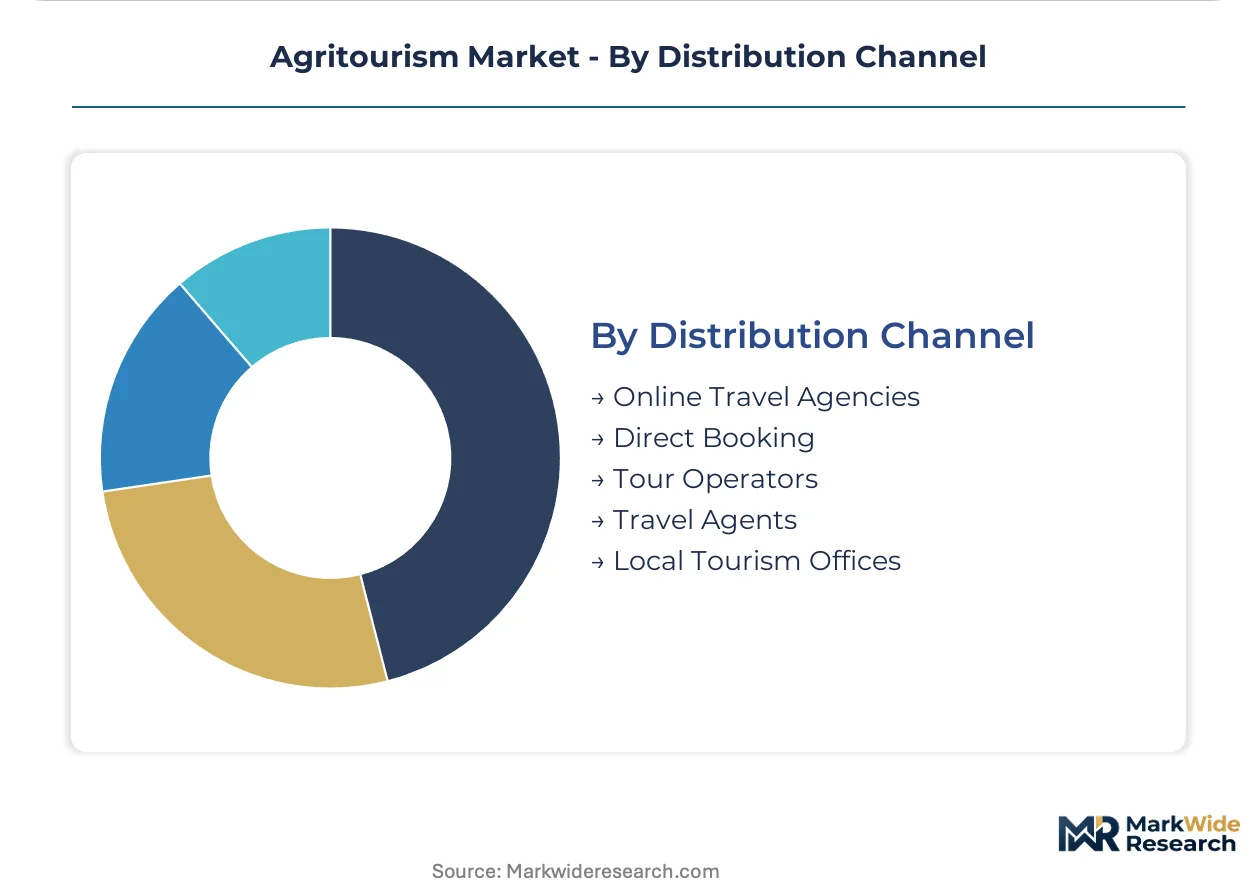
- Direct Booking:Property-controlled reservations via proprietary websites and email relationships. Estate-scale operators in France and Italy retain superior net revenue per transaction by avoiding online travel agency commission layers.
- Online Travel Agencies:Platform-mediated bookings capturing majority international visitor volume. Global OTA penetration is highest among first-time agritourists from Asia-Pacific source markets.
- Tour Operators:B2B intermediaries designing multi-farm itineraries across regional agricultural zones. Harvest Travel International anchors competitive position through curated cross-regional circuit design.
- Travel Agents:Traditional retail intermediaries serving older demographic segments with high service expectations. Declining share as digital booking infrastructure penetrates rural markets.
- Local Tourism Offices:Municipal and regional destination marketing organizations promoting farm networks. EU member state tourism boards are integrating sustainability certification filters into farm directory services.
Highest transaction value: Direct Booking. Fastest channel growth: Online Travel Agencies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Italy and France concentrate vineyard-based hospitality infrastructure, while the United States and Germany scale educational programming. Demand fragmentation across these production centers creates distinct regulatory and investment environments for operators.
Italy
Tuscany's Chianti Classico zone sustains year-round enotourism through cellar tours and extended-stay vineyard accommodations. EU Green Deal Farm to Fork strategy mandates sustainability disclosure for certified organic properties accessing member state incentives. Florence and Siena anchor premium pricing clusters where estate-scale operators combine hospitality with wine production.
France
Bordeaux and Provence regions command elevated ancillary food-and-beverage spend through integrated tasting experiences. EMA-aligned environmental management system requirements elevate compliance documentation for properties seeking EU tourism board directory placement. Burgundy's Côte d'Or sub-region exemplifies direct vineyard relationship models that bypass third-party farm contracts.
United States
Midwest school districts and California wine regions drive divergent demand patterns across institutional and leisure segments. FDA food safety protocols and USDA organic certification standards govern on-farm food service and retail activities, imposing infrastructure burdens on properties below 50 hectares. Napa Valley operators sustain margin leadership through estate-scale hospitality infrastructure.
Germany
Federal states formalize mandatory farm-based learning hours for K-12 agriculture curricula, pulling institutional procurement toward direct farm contracts. REACH-aligned chemical handling documentation requirements affect properties with educational programming involving crop protection exposure. Bavaria's mixed farm networks concentrate educational visit volume through centralized district contracting.
Australia
Victoria and New South Wales wine regions develop carbon-neutral tourism positioning through third-party soil sequestration verification. TGA-aligned biosecurity protocols govern livestock interaction components of farm stay programming. Yarra Valley operators integrate sensor-based farm monitoring into guest-facing educational interfaces.
Agritourism Market Key Industry Players
Top-tier vendors anchor estate-scale hospitality infrastructure, while mid-tier operators compete through curated itinerary design and regional farm network aggregation. The competitive landscape fragments across property-owning estates, tour aggregators, and specialized travel intermediaries. Three archetypes dominate: vertically integrated farm-estates controlling direct vineyard relationships, multi-farm itinerary designers bundling cross-regional experiences, and subscription-based membership platforms securing recurring visitor commitments. M&A activity concentrates on regional farm network consolidation, while capacity expansion focuses on year-round hospitality infrastructure to smooth seasonal occupancy curves.
Within the estate-scale tier, Blackberry Farm LLC and Blackberry Farm LLC exemplify property-owning models that sustain above-regional occupancy through integrated accommodation and dining infrastructure. Harvest Travel International occupies a position among itinerary-curating aggregators designing multi-farm circuits across diverse agricultural zones. Agrilys Voyages represents the direct-relationship archetype, controlling vineyard access in France rather than relying on third-party farm contracts.
| Leading Market Players |
|---|
| Bay Farm Tours |
| Greenmount Travel |
| Blackberry Farm LLC |
| Field Farm Tours Limited |
| Harvest Travel International |
| Agricultural Tour Operators International |
| Farm To Farm Tours |
| Select Holidays |
| Agrilys Voyages |
| Others |
Cost & Logistics Intelligence
Sensor-based farm monitoring technology deployment simultaneously elevates capital expenditure thresholds for competitive positioning and concentrates supply relationships among precision agriculture equipment providers certified under EU Green Deal sustainability frameworks. This dual effect reshapes cost economics for operators seeking premium pricing justification through documented production transparency.
Pricing Analysis
Margin tightening in vineyard accommodation tiers reflects estate-scale infrastructure requirements that compress returns for properties below 50 hectares. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and length-of-stay bundling. Cost compression accelerates in day-trip educational segments as school districts consolidate procurement through centralized contracts. Family visitor segments demonstrate lowest price sensitivity due to ancillary food-and-beverage spending, while student groups drive hardest bargain terms.
Supply Chain Analysis
Visitor capacity constraints and seasonal demand returns force operators into refurbishment cycles of hospitality infrastructure during shoulder seasons. Supply concentration rests on Italy, France, and the United States for vineyard estate development and hospitality equipment. Raw material dependencies span certified organic inputs, renewable energy systems, and sensor-based monitoring hardware. Single-source vulnerability concentrates in precision agriculture technology providers. Distribution runs through direct booking channels for estate-scale operators, online travel agencies for international visitor acquisition.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU Green Deal's Farm to Fork sustainability disclosure obligations function as a cost-of-compliance moat, advantaging certified organic properties with documented environmental management systems against undercapitalized entrants.
For Market Incumbents: Lock in recurring revenue through subscription-based seasonal farm membership programs that advance booking commitments and reduce vacancy risk. Deepen backward integration into on-farm food processing to capture margin pools currently extracted by third-party suppliers. Defend against online travel agency commission erosion by investing in proprietary digital booking infrastructure. For New Entrants and Emerging Players: The price-point gap between Tuscany vineyard estates and unclassified farm stays creates white-space opportunity for mid-tier properties with sustainability certification but limited acreage. Target Germany's educational visit segment through direct procurement relationships with federal state agriculture curricula. Pursue carbon accounting integration as a differentiated go-to-market angle ahead of municipal disclosure mandates. For Investors and Strategic Acquirers: Exit pathways concentrate in regional farm network consolidation plays, with estate-scale hospitality infrastructure commanding premium multiples. Long-term viability hinges on year-round occupancy capabilities that smooth harvest-dependent revenue curves. Watch EU member state incentive program expansion as the inflection signal for certified property valuation premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Subscription Membership Platform Launch | Recurring revenue streams reduce seasonal cash flow volatility for operators. |
| Carbon Accounting System Integration | Third-party soil sequestration verification unlocks EU Green Deal incentive access. |
| Direct Booking Channel Investment | Proprietary reservation infrastructure avoids OTA commission layers on international visitors. |
| Educational Curriculum Partnership | Direct farm contracts with school districts displace traditional travel agency intermediation. |
| Multi-Farm Itinerary Curation | Cross-regional agricultural circuit bundling captures premium pricing through experience diversity. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with agritourism operators, hospitality infrastructure suppliers, educational procurement coordinators, and sustainability certification auditors. EU Green Deal implementation documents, FDA food safety protocols, and USDA organic certification standards provided regulatory boundary conditions. Bottom-up property-level revenue modeling triangulated against top-down national tourism expenditure aggregates.
Granularity-level modeling disaggregated revenue across experience type, visitor profile, farm category, and distribution channel dimensions throughout the forecast period. CAGRs derived from trend extrapolation of certified property expansion rates and institutional procurement formalization trajectories. Enrollment patterns in university agriculture programs and K-12 field-based learning mandates supplied demand-side forecast inputs.
Inputs from national statistical offices and tourism board directories were available through the study window; gaps in informal farm stay revenue reporting introduce uncertainty bands around small-scale operator market sizing. Forecasts reflect documented assumptions regarding EU member state incentive program continuity and school curriculum mandate adoption timelines. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Travel and Tourism
Pet Travel Services Market
Travel and Tourism
Greece Tourism Market
Travel and Tourism
Middle East and Africa Travel Retail Market
Travel and Tourism
US and Canada Travel Market
Travel and Tourism
Japan Tourism Market
Travel and Tourism
B2B Travel Market
Travel and Tourism
New Zealand Sports Tourism Market
Travel and Tourism
Global Enotourism Market
Travel and Tourism
Hong Kong Outbound Tourism Market
Travel and Tourism
New Zealand Sustainable Tourism Market
Travel and Tourism
Global Duty-Free and Travel Retail Market
Travel and Tourism
Asia-Pacific Travel Retail Market
Travel and Tourism
GCC Outbound Tourism Market
Travel and Tourism
Latin America Inflight Services Market
Travel and Tourism
Singapore Tourism Market
Travel and Tourism
UK Outbound Travel Market