
 Horizontal Flow Wrapping Machines Market | 2026-2036
Horizontal Flow Wrapping Machines Market Size, Share, and Industry Trends Forecast 2026-2036
Horizontal Flow Wrapping Machines Market Foresight
The EU Green Deal's packaging waste reduction targets is pivoting food manufacturers toward flow wrapping formats that minimize material usage while maintaining seal integrity. Syntegon leverages its integrated systems portfolio to capture premium retrofit demand across European bakery and confectionery lines. Coesia anchors its position through deep specialization in pharmaceutical-grade continuous motion systems with validated cleanroom compatibility. Omori Machinery dominates Asian export markets with high-speed intermittent motion platforms engineered for flexible film structures.
Horizontal flow wrapping machines form continuous pouches around products using a single roll of flexible film, with forming collars shaping flat film into a tube while longitudinal and transverse sealing jaws create hermetic packages at speeds reaching 800 cycles per minute; these systems serve as the backbone of high-volume packaging for baked goods, confectionery, and medical devices where product protection and shelf-life extension are critical. Automatic systems lead installed capacity due to labor cost pressures in developed manufacturing economies, though smart technology integration represents the fastest-expanding segment as IoT-enabled predictive maintenance and recipe-driven changeover reduce unplanned downtime. Food packaging applications command the largest share of current demand, while pharmaceutical packaging generates superior margin pools driven by validation requirements and GMP-compliant documentation burdens.
FDA food-contact substance notifications and EU REACH chemical restrictions jointly determine acceptable film substrates and adhesive chemistries, compelling equipment builders to certify compatibility with evolving substrate portfolios. ISO 9001 quality management and CE marking requirements shape market access pathways, with notified body involvement escalating for machines incorporating robotic integration or autonomous safety systems. Stakeholders must monitor substrate innovation cycles and regulatory harmonization gaps between major jurisdictions to align R&D roadmaps with compliance timelines.
Market Dynamics
Food packaging automation is compressing changeover windows and forcing equipment builders to integrate servo-driven motion control with IoT-enabled predictive maintenance architectures.
Growth Catalysts
- EU Green Deal packaging waste targets:The regulation mandates material reduction thresholds that favor flow wrapping's film efficiency over rigid formats. Bakery and confectionery producers in Germany and Italy are retrofitting lines to meet compliance deadlines.
- Servo-driven intermittent motion platforms:These systems cut changeover times from hours to minutes. Asian export manufacturers deploy them to capture flexible packaging contracts from multinational food brands.
- REACH chemical compliance:The framework validates adhesive and substrate chemistries for food contact. Equipment builders certifying compatibility gain preferred supplier status with European dairy and snack producers.
Market Restraints
- Stainless steel and servo motor cost volatility:Input price swings compress margin pools for mid-tier equipment builders. German precision engineering clusters pass through costs faster than Asian competitors.
- Film substrate concentration:Biaxially oriented polypropylene supply concentrates among Korean and Japanese chemical conglomerates. Equipment buyers face extended lead times for validated film grades.
- Cleanroom validation documentation burdens:Pharmaceutical-grade systems require GMP-compliant traceability that extends sales cycles. Smaller builders lack regulatory affairs capacity to compete for medical device contracts.
Strategic Opportunities
- Indian food processing automation:The PLI scheme subsidizes packaging line upgrades. Domestic biscuit and namkeen producers represent untapped demand for entry-level automatic systems.
- Robotic integration with collaborative arms:Convergence of delta robots and flow wrappers enables direct feeding from irregular product streams. Confectionery manufacturers pilot these configurations for hand-placed specialty items.
- California SB 54 extended producer responsibility:The mandate drives demand for mono-material film structures compatible with existing sealing jaw geometries. Equipment builders offering retrofit kits capture upgrade revenue.
Industry Challenges
- Mechatronics technician scarcity:Servo programming and HMI configuration skills lag equipment complexity. German and Japanese builders operate captive training academies; others face commissioning delays.
- Legacy PLC integration friction:Brownfield sites running proprietary Allen-Bradley or Siemens architectures resist full control system replacements. Retrofit projects stall on communication protocol mismatches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Horizontal Flow Wrapping Machines Market |
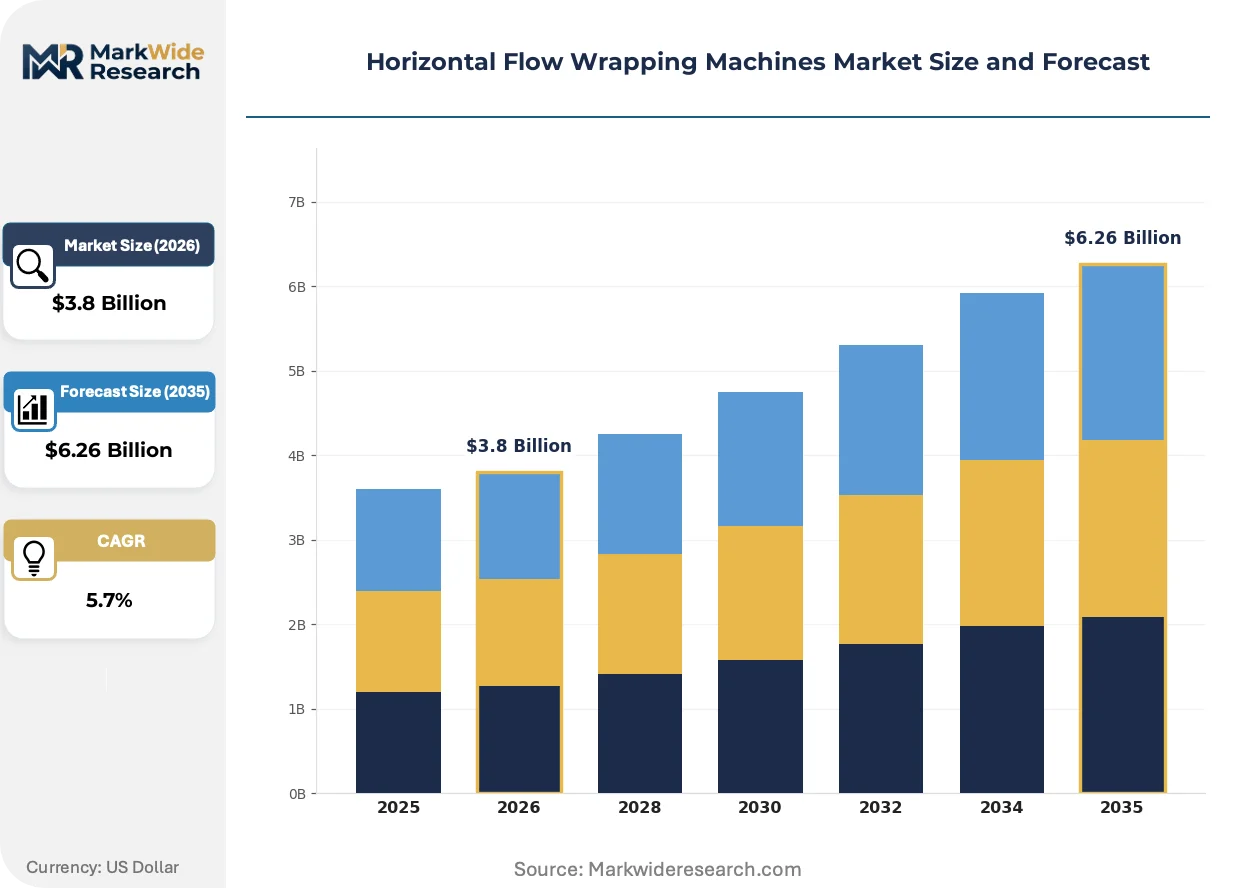
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automatic, Semi-Automatic, Manual, Specialty Application: Food Packaging, Pharmaceutical Packaging, Consumer Goods, Electronics Packaging End User: Food Manufacturers, Healthcare Providers, Retailers, E-Commerce Technology: Intermittent Motion, Continuous Motion, Integrated Systems, Smart Technology |
| Companies Covered | Syntegon, Coesia, Omori Machinery, Fuji Machinery, ULMA Packaging, BW Flexible Systems, ProMach, Theegarten-Pactec, Ilapak International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Horizontal Flow Wrapping Machines Market Shifts & Advancements
Digital twin architectures and sustainable film formulations are rewiring equipment specification priorities. Builders now compete on simulation-validated throughput guarantees and substrate flexibility rather than mechanical speed ratings alone.
Ultrasonic sealing jaws are rewriting package integrity standards for heat-sensitive confectionery and probiotic-enriched snacks. European premium chocolate manufacturers adopt them to eliminate thermal degradation of functional ingredients. The technology compresses energy consumption while enabling hermetic seals through metallized and paper-based films previously incompatible with thermal methods.
REACH Annex XVII restrictions on per- and polyfluoroalkyl substances are forcing substrate portfolio overhauls. Equipment builders must revalidate sealing temperature windows and jaw pressure profiles for fluorine-free barrier coatings. Pharmaceutical packaging lines in Germany and Switzerland face the tightest compliance timelines, with notified body involvement escalating for machines handling new film chemistries.
Outcome-based service contracts now displace traditional break-fix maintenance arrangements. Large food manufacturers in the Netherlands and Denmark bundle spare parts, remote monitoring, and guaranteed uptime into per-unit packaging fees. This compresses capital expenditure recognition for equipment builders while locking in decade-long customer relationships.
Horizontal Flow Wrapping Machines Market Segmentation
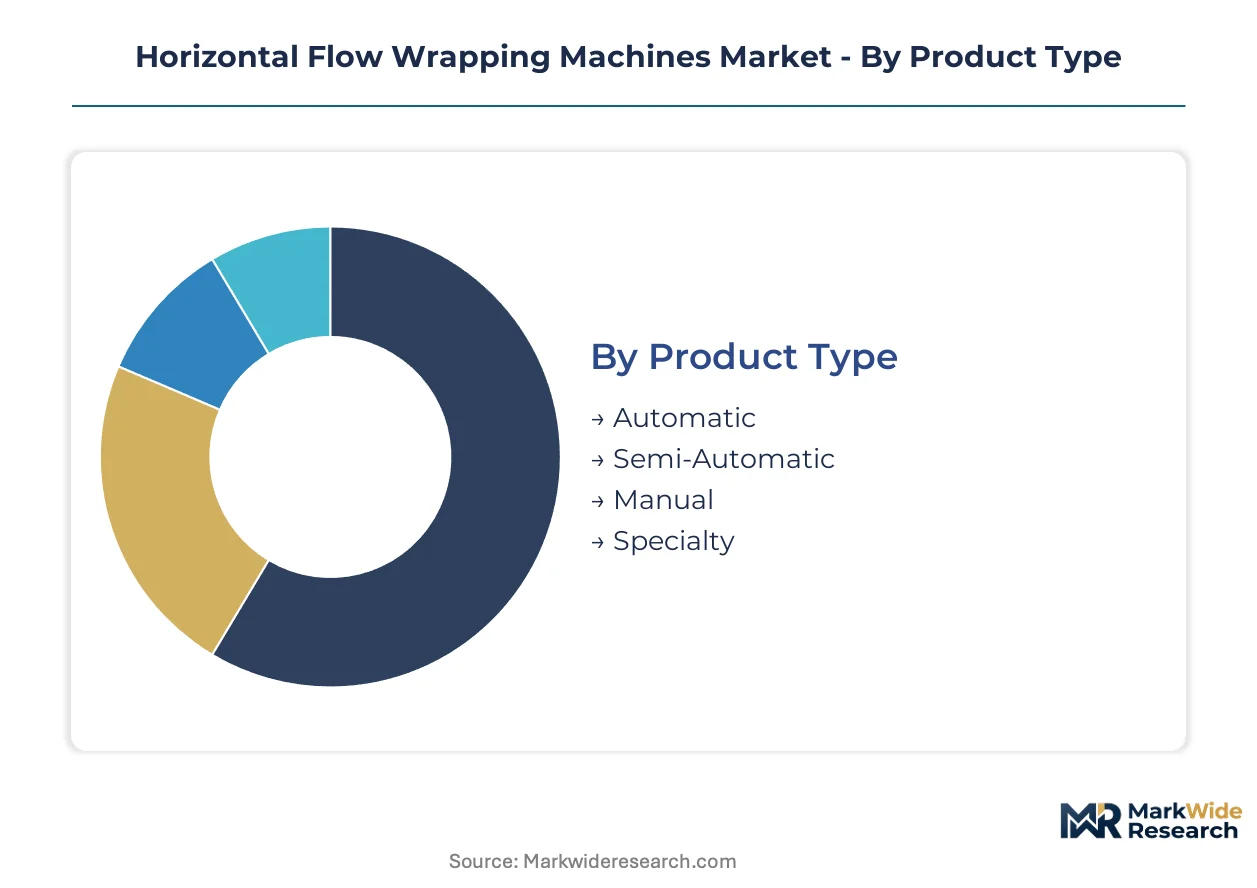
Horizontal flow wrapping machines serve distinct operational profiles across automation levels and end-use requirements. Segmentation reveals where capital deployment concentrates and which technology trajectories command engineering investment priorities.
Product Type:
Automatic systems anchor high-volume integrated lines, while semi-automatic and manual configurations retain relevance in batch-flexible environments. Specialty machines occupy niche retrofit and validation-intensive applications.
- Automatic:Servo-driven architectures with recipe-driven changeover dominate bakery and confectionery lines in Germany and Italy. EU Green Deal compliance deadlines accelerate retrofit demand for film-efficient formats with hermetic seal validation.
- Semi-Automatic:Hybrid configurations blend operator feeding with automated sealing cycles. Indian biscuit and namkeen producers under the PLI scheme represent emerging placement concentration for entry-level automatic migration paths.
- Manual:Hand-fed platforms persist in artisan chocolate and specialty confectionery where product irregularity defies mechanical feeding. Swiss and Belgian premium manufacturers maintain limited deployments for heritage positioning.
- Specialty:Cleanroom-validated systems with GMP-compliant documentation serve pharmaceutical contract packaging. Extended sales cycles and regulatory affairs capacity requirements filter competitive participation.
Volume placements concentrate in Automatic systems; the faster expansion belongs to Specialty configurations as pharmaceutical validation burdens deepen.
Application:
End-use requirements diverge sharply between shelf-life extension priorities in food and sterility assurance mandates in pharmaceutical packaging. Each application imposes distinct sealing technology and documentation specifications.
- Food Packaging:Baked goods and confectionery drive baseline demand with throughput maximizing as the primary specification. REACH-compliant adhesive validation and fluorine-free barrier coating compatibility reshape equipment specification checklists.
- Pharmaceutical Packaging:Continuous motion systems with validated cleanroom compatibility generate superior margin pools. FDA food-contact substance notifications and EU REACH chemical restrictions jointly determine acceptable film substrate portfolios.
- Consumer Goods:Personal care and household products utilize standard intermittent motion platforms with moderate speed requirements. California SB 54 extended producer responsibility mandates drive mono-material film retrofits.
- Electronics Packaging:Anti-static film handling and precision collation for small components define specification priorities. Asian export manufacturers deploy high-speed intermittent motion platforms for flexible film structures.
Revenue concentration sits with Food Packaging; steepest expansion trajectory belongs to Pharmaceutical Packaging as validation documentation burdens intensify.
End User:
Procurement authority and integration depth vary across manufacturer-owned lines versus contract packaging services. Capital deployment patterns reflect automation maturity and regulatory exposure differentiation.
- Food Manufacturers:Integrated bakery and dairy operations specify fully automatic lines with IoT-enabled predictive maintenance. German precision engineering clusters capture premium retrofit demand.
- Healthcare Providers:Hospital and clinic-affiliated packaging services prioritize validated systems with batch traceability. Swissmedic and EMA documentation requirements extend procurement cycles.
- Retailers:Private-label contract packaging demand concentrates in co-manufacturing networks with flexible changeover capabilities. Dutch and Danish outcome-based service contracts reshape supplier relationships.
- E-Commerce:Fulfillment-adjacent packaging lines emphasize damage resistance and dimensional optimization for parcel density. Robotic integration with collaborative arms enables direct feeding from irregular product streams.
Installed base dominance rests with Food Manufacturers; the most rapid share gain belongs to E-Commerce as fulfillment packaging specifications diverge from retail formats.
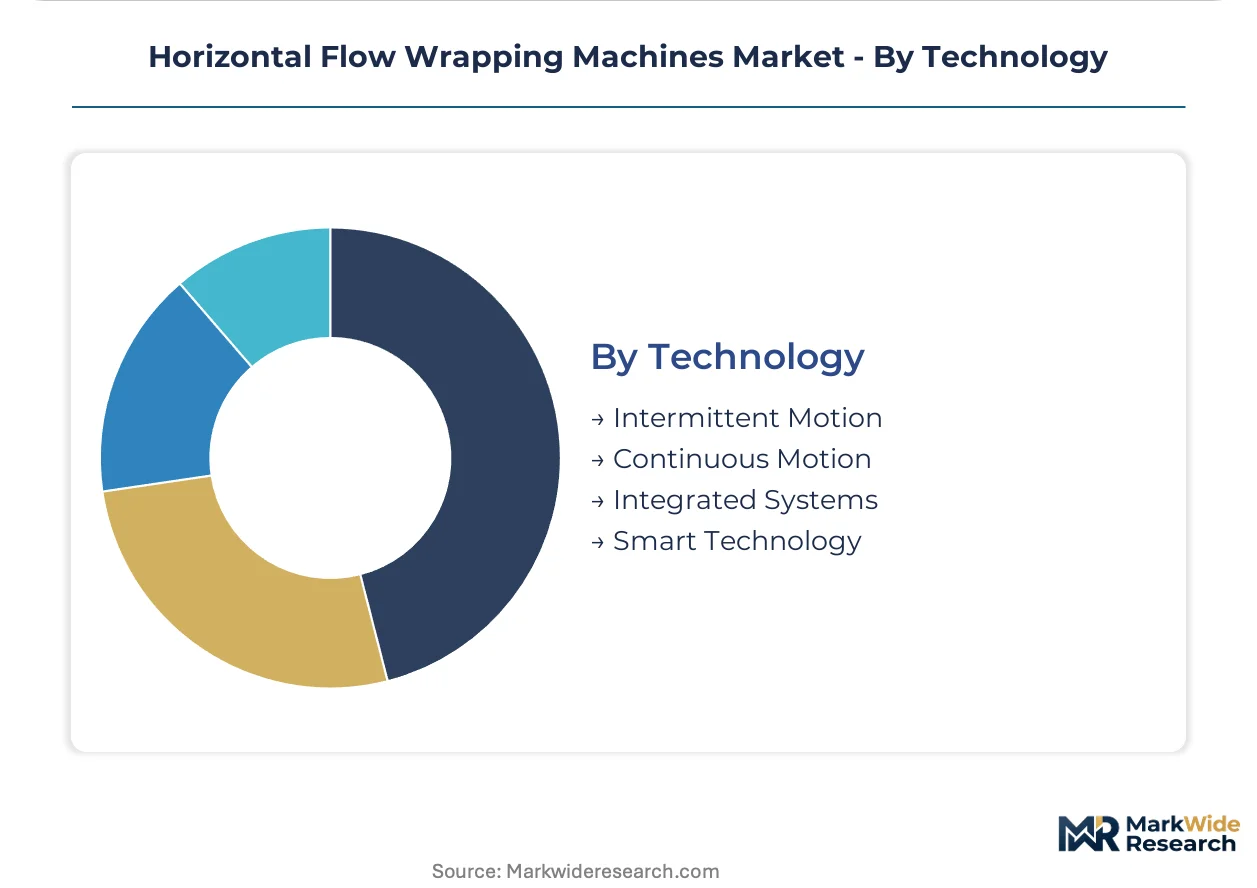
Technology:
Motion control architecture and intelligence integration define competitive differentiation beyond mechanical speed ratings. Builders now compete on simulation-validated throughput guarantees and substrate flexibility.
- Intermittent Motion:Sealing jaws pause for product placement, enabling precise handling of irregular or fragile items. Omori Machinery dominates Asian export markets with platforms engineered for flexible film structures.
- Continuous Motion:Products move through sealing zones without interruption, maximizing throughput for uniform geometries. Coesia anchors positioning through pharmaceutical-grade systems with validated cleanroom compatibility.
- Integrated Systems:Downstream cartoning, case packing, and palletizing modules synchronize through unified control architectures. Syntegon leverages portfolio breadth to capture premium retrofit demand.
- Smart Technology:IoT-enabled predictive maintenance and digital twin architectures reduce unplanned downtime. Mechatronics technician scarcity constrains commissioning velocity outside German and Japanese captive training academies.
Capacity concentration favors Continuous Motion; the climbing trajectory belongs to Smart Technology as outcome-based service contracts displace break-fix arrangements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Stuttgart anchors European precision engineering for flow wrapping machinery, with German clusters exporting validated systems worldwide. Demand concentrates where food automation meets stringent chemical compliance regimes.
Germany
Bakery and confectionery producers in Baden-Württemberg retrofit lines for EU Green Deal packaging waste deadlines. REACH Annex XVII restrictions on per- and polyfluoroalkyl substances force substrate revalidation across sealing jaw portfolios. Stuttgart-based machinery builders capture premium retrofit contracts through integrated servo architectures.
United States
California SB 54 extended producer responsibility mandates drive mono-material film retrofits for dairy and snack producers. FDA food-contact substance notifications determine acceptable adhesive chemistries for equipment specification. Chicago-area contract packaging networks pilot outcome-based service contracts bundling uptime guarantees with per-unit fees.
India
Domestic biscuit and namkeen producers under the PLI scheme automate packaging lines for export-ready output. FSSAI food safety standards align equipment validation with international substrate compatibility requirements. Gujarat and Maharashtra processing clusters represent emerging placement concentration for entry-level automatic system migration.
Japan
Premium chocolate manufacturers adopt ultrasonic sealing to eliminate thermal degradation of functional ingredients. METI industrial efficiency programs subsidize smart technology integration for predictive maintenance architectures. Nagoya-area machinery specialists engineer high-speed intermittent motion platforms for flexible film structures serving Asian export markets.
Switzerland
Pharmaceutical contract packaging services prioritize validated systems with GMP-compliant batch traceability. Swissmedic documentation requirements extend procurement cycles for cleanroom-compatible continuous motion equipment. Basel-area precision engineering clusters serve European medical device manufacturers with regulatory affairs capacity for validation-intensive contracts.
Horizontal Flow Wrapping Machines Market Competitive Landscape
The competitive structure tilts toward integrated system specialists with regulatory affairs depth. German and Japanese precision engineering clusters dominate premium-tier positioning through captive training academies and validated cleanroom architectures. Three archetypes define participation: full-line integrators with downstream cartoning synchronization, pharmaceutical-grade specialists with GMP documentation capacity, and high-speed intermittent motion fabricators serving flexible film export markets. Consolidation pressure favors M&A for regulatory capacity acquisition; geographic expansion targets Indian PLI scheme beneficiaries.
Among German-based precision engineering groups, Syntegon and Theegarten-Pactec exemplify full-line integration archetypes spanning forming, wrapping, and downstream modules. Japanese specialists including Omori Machinery occupy positions calibrated to Asian export markets with intermittent motion expertise for complex film structures. Coesia represents the pharmaceutical-grade tier with validated continuous motion architectures. These anchors illustrate how regulatory compliance capacity and motion control specialization determine competitive segmentation rather than mechanical speed ratings alone.
| Leading Market Players |
|---|
| Syntegon |
| Coesia |
| Omori Machinery |
| Fuji Machinery |
| ULMA Packaging |
| BW Flexible Systems |
| ProMach |
| Theegarten-Pactec |
| Ilapak International |
| Others |
Supply & Pricing Matrix
Mechatronics technician concentration in Stuttgart and Nagoya engineering clusters drives labor-cost differentials that separate premium-tier pricing from economy-tier spreads across German and Japanese machinery builders.
Pricing Analysis
Outcome-based uptime guarantees anchor value-based pricing for pharmaceutical-grade continuous motion systems. Three-tier pricing structure across premium, standard, and economy levels separates GMP-validated cleanroom architectures from entry-level intermittent motion platforms. Price differentiation hinges on certification grade and geographic delivery cost. Pricing pressure stems from stainless steel and servo motor cost volatility compressing margin pools for mid-tier equipment builders. Contract packaging networks in the Netherlands and Denmark exhibit lowest price sensitivity due to outcome-based service contract bundling.
Supply Chain Analysis
Stainless steel and servo motor supply rests on German precision engineering clusters and Japanese electromechanical specialists. Biaxially oriented polypropylene film substrates draw from Korean and Japanese chemical conglomerates. Supply chain risk centers on single-source vulnerability for validated film grades extending equipment lead times. Distribution runs through machinery builders' captive service networks and regional distribution partners serving bakery, confectionery, and pharmaceutical contract packaging operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a vertical-integration race where captive training academies and in-house servo motor production determine competitive durability against input cost volatility.
For Market Incumbents: Hedge margin exposure by deepening backward integration into servo drive manufacturing and expanding regulatory affairs capacity for REACH Annex XVII compliance. Defend against Asian intermittent motion specialists by accelerating ultrasonic sealing jaw retrofit programs for European premium chocolate manufacturers. Prioritize certification investment for fluorine-free barrier coating compatibility.
For New Entrants and Emerging Players: Begin with entry-level automatic system deployment targeting Indian biscuit and namkeen producers under the PLI scheme subsidy window. Capture white-space demand in Gujarat and Maharashtra processing clusters where FSSAI alignment creates validation pathway clarity. Pursue go-to-market partnerships with regional film substrate distributors to bundle equipment and material validation.
For Investors and Strategic Acquirers: The window for entry favors pharmaceutical-grade specialists with GMP-compliant documentation capacity and Swissmedic relationship depth. Long-term viability over the projection horizon hinges on regulatory affairs scalability rather than mechanical speed ratings alone. Watch for REACH chemical restriction expansion into new adhesive chemistries as inflection indicator for substrate revalidation demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Servo Manufacturing | Captive production of motion control components insulates German builders from input price volatility. |
| Regulatory Affairs Capacity Expansion | GMP-compliant documentation depth unlocks pharmaceutical contract packaging margin pools. |
| Ultrasonic Sealing Retrofit Programs | Premium chocolate manufacturers adopt jaw upgrades to eliminate thermal degradation of functional ingredients. |
| Captive Training Academy Establishment | Stuttgart and Nagoya clusters accelerate commissioning velocity amid mechatronics technician scarcity. |
| Outcome-Based Service Contract Rollout | Dutch and Danish food manufacturers bundle uptime guarantees with per-unit packaging fees. |
Research Methodology
Independent corroboration across machinery builder engineering directors, pharmaceutical packaging operations managers, and film substrate technical specialists underwrites the qualitative findings. Primary interviews with bakery and confectionery plant engineers, aftermarket service heads at OEMs, and regulatory affairs leads at notified bodies combined with secondary validation from CE marking documentation, REACH Annex XVII restriction filings, and FSSAI equipment validation guidelines. Bottom-up installed base enumeration and top-down trade flow analysis triangulate volume estimates.
Rate-of-change decomposition across the analysis window isolates automation level, motion control architecture, end-use application, and regional regulatory cluster as primary segmentation dimensions. CAGRs derive from equipment shipment trajectories, retrofit cycle frequencies, and substrate innovation adoption curves. Forecast inputs incorporate EU Green Deal packaging waste target compliance deadlines and PLI scheme subsidy phase structures without year-specific calibration.
Underlying measurement precision varies by segment; pharmaceutical-grade systems with validated cleanroom compatibility carry tighter precision than emerging e-commerce fulfillment configurations. Forecasts reflect documented assumptions regarding regulatory harmonization timelines and film substrate concentration patterns. Supply chain disruption from Korean and Japanese chemical conglomerate consolidation and REACH chemical restriction expansion warrant ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Machinery
Europe Blow Molding Machine Market
Packaging Machinery
Glazing Machine Market
Packaging Machinery
Tea Packing Machine Market
Packaging Machinery
Cup Fill and Seal Machine Market
Packaging Machinery
Confectionery Packaging Machine Market
Packaging Machinery
Medicine Decoction and Packing Machines Market
Packaging Machinery
Vial Capping Machines Market
Packaging Machinery
Tray and Sleeve Packing Machines Market
Packaging Machinery
Carton Erecting Machinery Market
Packaging Machinery
Meal Tray Sealing Machines Market
Packaging Machinery
Pre-Made Pouch Packaging Machines Market
Packaging Machinery
Volumetric Boom Filling Machine Market
Packaging Machinery
Toilet Roll Converting Lines Market
Packaging Machinery
Strapping Machine Market
Packaging Machinery
Stretch Blow Molding Machines Market
Packaging Machinery
Oral Dosage Powder Packaging Machines Market