
 Europe Blow Molding Machine Market | 2026-2036
Europe Blow Molding Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Blow Molding Machine Market Insights
CE marking under the EU Machinery Directive is collapsing the competitive field for smaller Asian exporters. Bekum Maschinenfabriken GmbH leverages its German manufacturing base to dominate custom industrial container applications. Sidel Group sustains technology leadership in high-speed PET bottle lines through intensive R&D spending. Krones AG anchors European beverage packaging with integrated blow-fill-cap systems that control downstream line economics.
A blow molding machine forms hollow plastic parts by inflating a heated plastic parison inside a mold cavity, typically processing polyethylene terephthalate, high-density polyethylene, or polypropylene at clamp forces ranging from a few tons to over 800 tons for large industrial parts. Its primary purpose is mass-producing bottles, containers, and technical hollow bodies for packaging and automotive applications. Stretch blow molding leads the product type landscape due to its dominance in carbonated soft drink and water bottle production across European bottling plants. Advanced automated systems are displacing conventional equipment in Germany and France as labor costs rise and output consistency demands tighten. Hybrid systems occupy the fastest-expanding technology tier by combining electric precision with hydraulic clamping force for energy-sensitive producers.
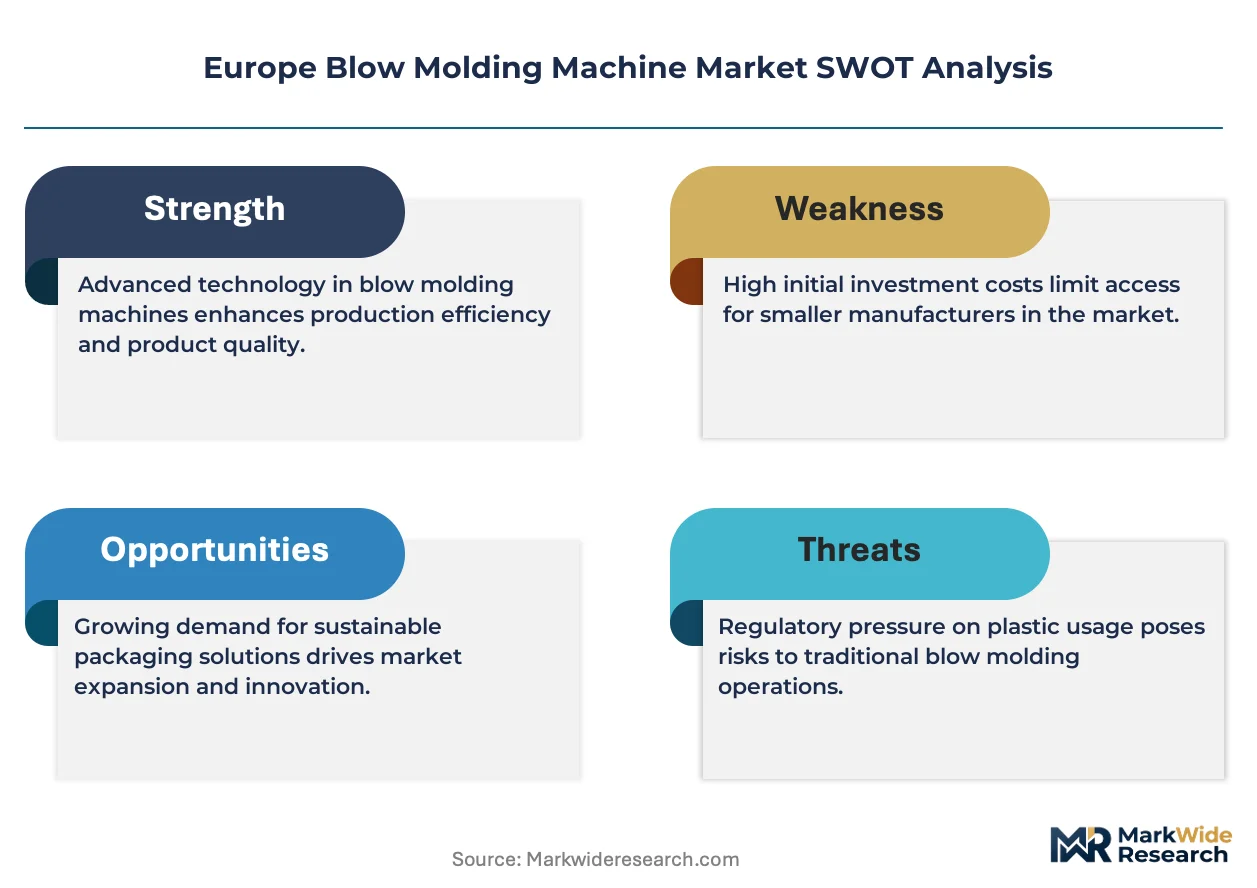
The EU Green Deal and F-Gas Regulation are reshaping equipment specifications by mandating reduced energy consumption and lower-GWP refrigerants in cooling circuits, which forces retooling investments across installed machine bases. ECHA's REACH compliance layers additional material certification burdens on mold builders and resin suppliers. REACH documentation requirements now extend through supply chains to machine OEMs sourcing coated alloys and lubricated components. Stakeholders must monitor how the EU AI Act will classify predictive maintenance algorithms embedded in next-generation blow molding controls.
Market Dynamics
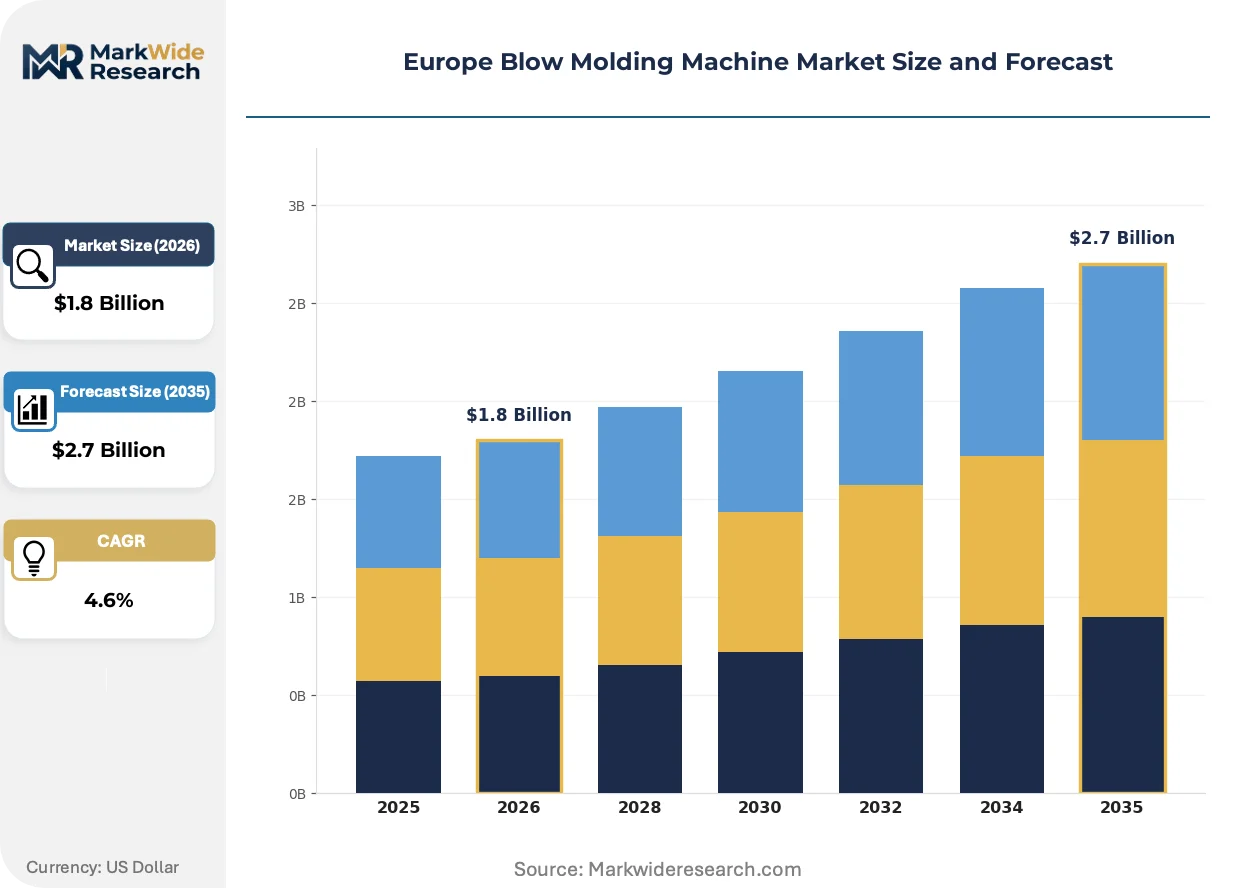
Energy-efficiency mandates under the EU Green Deal are forcing wholesale retooling of installed machine bases, while pharmaceutical packaging demand in Germany and France pulls capital toward automated stretch blow molding systems.
Growth Catalysts
- Pharmaceutical packaging expansion:Sterile blow-fill-seal applications for biologics and vaccines are accelerating capital deployment across German and French manufacturing clusters.
- F-Gas Regulation compliance cycles:Mandated refrigerant transitions in cooling circuits are triggering replacement demand for legacy hydraulic systems throughout EU member states.
- Hybrid electric-hydraulic architectures:Energy-sensitive producers in Italy and Spain are adopting these systems to reduce per-unit power consumption without sacrificing clamp force.
Market Restraints
- Specialized alloy supply concentration:Mold builders depend on limited European sources for coated beryllium-copper alloys, creating input cost volatility.
- REACH documentation friction:ECHA's extended compliance obligations through supply chains delay machine commissioning timelines.
- Mechanical recycling contamination limits:Current sorting and washing infrastructure caps post-consumer resin feedstock quality for food-contact applications.
Strategic Opportunities
- Spanish automation upgrade cycle:Mid-tier bottlers in Catalonia and Valencia remain underpenetrated by integrated blow-fill-cap systems.
- EU AI Act predictive maintenance:Embedded algorithm classification creates first-mover advantage for OEMs certifying condition-monitoring software.
- Bioplastics processing capability:PLA and bio-PET compatibility gaps present white space for screw and barrel engineering specialization.
Industry Challenges
- Electromechanical systems integration:Retrofitting servo-electric precision into legacy hydraulic frames demands scarce mechatronics expertise.
- CE marking timeline compression:EU Machinery Directive conformity assessment delays are extending from months to quarters for non-EU component sourcing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Blow Molding Machine Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Extrusion Blow Molding, Injection Blow Molding, Stretch Blow Molding, Reheat Stretch Blow Molding End User: Packaging, Automotive Components, Consumer Goods, Pharmaceutical Technology: Conventional Systems, Advanced Automated Systems, Hybrid Systems, Multilayer Systems Application: Bottles, Containers, Jars, Custom Shapes |
| Companies Covered | Krones AG, Sidel Group, Sacmi Imola S.C., Bekum Maschinenfabriken GmbH, Kautex Maschinenbau, Nissei ASB Machine Co. Ltd., Aoki Technical Laboratory Inc., Graham Engineering Corporation, Mag-Plastic Machinery SA, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Blow Molding Machine Market Trends and Innovations
Machine architecture is pivoting toward energy recovery and predictive control systems, while regulatory pressure on refrigerants and materials certification is rewriting equipment specifications.
All-electric clamping and injection units are miniaturizing footprint requirements for cleanroom pharmaceutical installations. Dutch and Belgian contract manufacturers are adopting these systems fastest. The technology is miniaturizing the boundary between packaging and medical device production, collapsing facility separation requirements.
F-Gas Regulation phase-down schedules are mandating lower-GWP alternatives in mold temperature control circuits. Equipment OEMs must redesign cooling architectures and requalify thermal performance. Beverage bottlers in Germany face the steepest compliance cliffs and are accelerating replacement timelines.
Outcome-based service contracts are displacing traditional breakdown-repair arrangements among large CPG groups. Performance guarantees covering uptime and energy consumption are replacing capital purchase decisions. French dairy and water bottlers are negotiating these structures most aggressively.
Europe Blow Molding Machine Market Segmentation
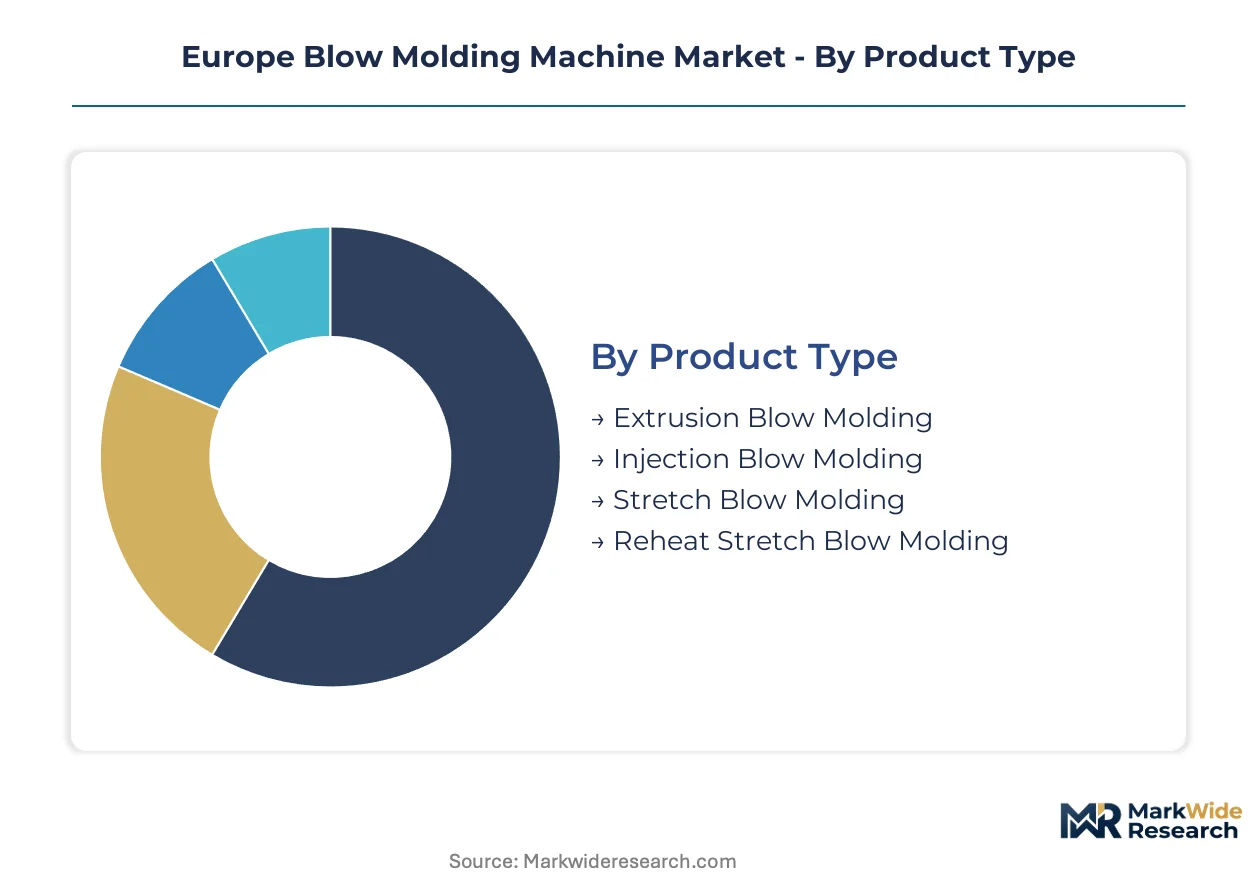
Segmentation in the Europe Blow Molding Machine Market reveals how regulatory pressure and application-specific demands fragment procurement criteria across end-use verticals. Equipment buyers in Germany and France prioritize CE marking compliance and energy efficiency certifications, while Spanish and Italian processors emphasize automation density per square meter.
Product Type:
CE marking under the EU Machinery Directive creates divergent compliance burdens across blow molding architectures, with stretch-based systems facing tighter scrutiny on clamp force calibration documentation.
- Stretch Blow Molding:Two-stage process orients PET molecular chains through axial stretching and radial blowing, producing biaxially oriented bottles with superior barrier properties. German beverage bottlers in Bavaria and North Rhine-Westphalia deploy these systems for carbonated soft drink lines where ECHA REACH compliance on resin additives is mandatory. The F-Gas Regulation drives cooling circuit redesigns in these high-throughput installations.
- Reheat Stretch Blow Molding:Preform reheating stage separates injection molding from blow molding, enabling centralized preform production and distributed bottle finishing. French pharmaceutical packaging clusters around Lyon and Strasbourg favor this architecture for sterile blow-fill-seal integration under EMA guidelines. Preform logistics optimization reduces per-unit energy intensity.
- Extrusion Blow Molding:Continuous parison extrusion suits large industrial containers and automotive fuel tanks with thick wall sections. HDPE processing dominates Italian automotive component suppliers.
- Injection Blow Molding:Single-stage process injects parisons directly into blow molds, minimizing contamination risk for small pharmaceutical vials. Belgian medical packaging specialists prefer this architecture for cleanroom installations.
Stretch Blow Molding handles the majority of throughput; Reheat Stretch Blow Molding is the fastest mover on share.
End User:
Cost tier differentiation separates premium automated installations from conventional equipment, with pharmaceutical and automotive buyers absorbing technology premiums that packaging processors resist.
- Packaging:Beverage, food, and personal care containers constitute the volume foundation. Spanish bottlers in Catalonia and Valencia are retrofitting conventional lines with hybrid electric-hydraulic systems to meet EU Green Deal energy benchmarks. Water and dairy segments negotiate outcome-based service contracts with uptime guarantees.
- Pharmaceutical:Sterile blow-fill-seal systems for biologics and vaccines command specialized cleanroom architectures. German manufacturing clusters around Frankfurt and Munich lead capital deployment for automated stretch systems under EMA sterile manufacturing guidelines. REACH documentation extends through supply chains to coated alloy mold components.
- Automotive Components:Fuel tanks, air ducts, and fluid reservoirs utilize multilayer coextrusion for permeation resistance. Italian OEM suppliers in Emilia-Romagna process engineering-grade polyamides.
- Consumer Goods:Cosmetic containers and household products prioritize surface finish and decoration compatibility. French processors dominate premium personal care packaging.
Packaging absorbs the largest equipment volume; Pharmaceutical is climbing the fastest as sterile manufacturing mandates tighten.
Technology:
Volume concentration in mid-tier Italian and Spanish processors creates demand for retrofit-compatible architectures that preserve hydraulic clamping investments while adding electric precision.
- Hybrid Systems:Electric servo motors drive injection and plastification while hydraulic circuits maintain clamp force, balancing precision with mechanical robustness. Italian energy-sensitive producers in Lombardy and Piedmont adopt these systems to reduce per-unit power consumption without sacrificing tonnage. The EU Green Deal accelerates replacement of pure hydraulic bases.
- Advanced Automated Systems:Integrated blow-fill-cap configurations collapse line economics through reduced labor touchpoints and compressed footprint. French dairy and water bottlers negotiate performance guarantees covering uptime and energy consumption. Dutch contract manufacturers miniaturize cleanroom boundaries with all-electric clamping units.
- Conventional Systems:Pure hydraulic architectures persist in legacy installations with long amortization schedules. Spanish mid-tier bottlers delay replacement due to capital constraints.
- Multilayer Systems:Coextrusion heads combine barrier and structural layers for automotive fuel tanks and sensitive food packaging. German automotive suppliers lead technical specification.
Conventional Systems retain the largest installed base; Hybrid Systems are gaining share fastest on energy compliance pressure.
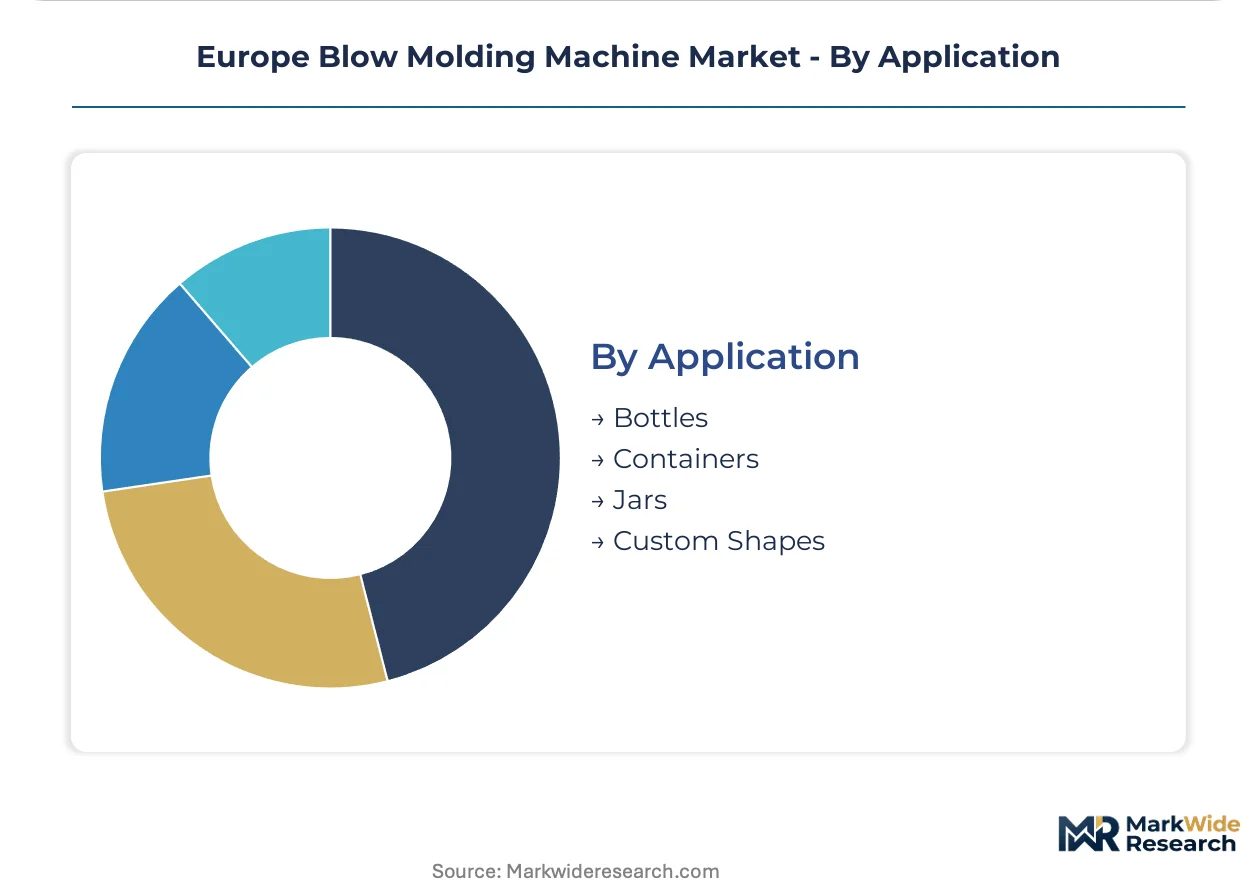
Application:
Customer type stratification separates high-volume commodity producers from specialized custom molders, with divergent procurement criteria on changeover speed versus cavity count.
- Bottles:Carbonated soft drink and water containers dominate PET stretch blow molding output. German beverage bottlers face the steepest F-Gas Regulation compliance cliffs and accelerate replacement timelines for cooling circuit redesigns.
- Containers:Industrial pails, drums, and intermediate bulk containers utilize extrusion blow molding of HDPE and polypropylene. Spanish chemical packaging processors cluster around Tarragona.
- Jars:Wide-mouth containers for food and cosmetics require controlled crystallization to prevent stress cracking. French personal care brands specify high-clarity PET grades.
- Custom Shapes:Technical hollow bodies for automotive and appliance applications demand engineered resins and complex mold geometries. Italian automotive tier suppliers specialize in this segment.
Bottles command the dominant equipment throughput; Custom Shapes show the steepest expansion trajectory on automotive lightweighting demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyer archetypes fragment across pharmaceutical sterilizers, beverage bottlers, and automotive tier suppliers, each demanding divergent machine architectures and compliance documentation.
Germany
Bavarian beverage bottlers and Frankfurt pharmaceutical clusters drive demand for automated stretch blow molding with integrated blow-fill-seal capability. The F-Gas Regulation forces cooling circuit redesigns in legacy installations throughout North Rhine-Westphalia. Munich-area OEMs accelerate replacement timelines to meet EU Green Deal energy benchmarks.
France
Lyon and Strasbourg pharmaceutical packaging hubs prioritize sterile manufacturing lines under EMA guidelines for biologics and vaccines. REACH documentation obligations extend through supply chains to coated alloy mold components sourced by equipment buyers. Dairy and water bottlers in the Rhône corridor negotiate outcome-based service contracts with uptime guarantees.
Italy
Emilia-Romagna automotive suppliers process engineering-grade polyamides for fuel tanks and fluid reservoirs using multilayer coextrusion systems. Lombardy and Piedmont energy-sensitive producers adopt hybrid electric-hydraulic architectures to reduce per-unit power consumption. The EU Green Deal accelerates replacement of pure hydraulic machine bases in northern manufacturing belts.
Spain
Catalonia and Valencia mid-tier bottlers remain underpenetrated by integrated blow-fill-cap systems, creating whitespace for automation upgrades. Chemical packaging processors cluster around Tarragona utilizing extrusion blow molding for industrial containers. Capital constraints delay replacement of conventional hydraulic installations in legacy plants.
Belgium
Medical packaging specialists in Flanders prefer injection blow molding architectures for cleanroom installations with minimized contamination risk. Dutch and Belgian contract manufacturers lead adoption of all-electric clamping units that miniaturize cleanroom boundaries. ECHA REACH compliance layers additional certification burdens on resin and coated component sourcing.
Europe Blow Molding Machine Market Competitive Landscape
Player mix skews toward German precision fabricators and Italian automation specialists, creating a tiered structure with consolidated leadership in beverage systems and fragmented competition in custom industrial containers. Strategic archetypes separate integrated line OEMs from standalone machine builders and mold-specialized boutiques. M&A activity concentrates among beverage packaging integrators, while technology licensing agreements proliferate in pharmaceutical sterilization segments.
Among Germany-based fabricators, Krones AG and Bekum Maschinenfabriken GmbH occupy positions anchoring distinct market vectors, with the former representing integrated line economics and the latter exemplifying custom industrial container specialization. Sidel Group sits within the premium-tier beverage technology segment. Sacmi Imola S.C. anchors Italian automation capabilities for ceramic and packaging machinery cross-application.
| Leading Market Players |
|---|
| Krones AG |
| Sidel Group |
| Sacmi Imola S.C. |
| Bekum Maschinenfabriken GmbH |
| Kautex Maschinenbau |
| Nissei ASB Machine Co. Ltd. |
| Aoki Technical Laboratory Inc. |
| Graham Engineering Corporation |
| Mag-Plastic Machinery SA |
| Others |
Pricing and Supply Chain Analysis
Hybrid electric-hydraulic architectures displacing pure hydraulic bases simultaneously concentrate component sourcing in German and Italian precision manufacturing belts while compressing price premiums for energy-efficient configurations. Buyers in Spain and France now face extended lead times for servo-electric subassemblies that command 15-25% hardware premiums over conventional alternatives.
Pricing Analysis
Cost-plus contracts with steel and copper indexation dominate equipment procurement between Italian mold builders and German OEMs. Three-tier pricing structure across premium, standard, and economy levels separates CE-marked automated lines from mid-tier hybrid retrofits and legacy hydraulic units. Pricing pressure stems from F-Gas Regulation compliance costs passed through cooling circuit redesigns. Spanish mid-tier bottlers exhibit highest price sensitivity; pharmaceutical sterilizers in France absorb technology premiums with minimal negotiation.
Supply Chain Analysis
Inbound logistics costs from Asian servo-motor suppliers through Rotterdam and Hamburg port congestion have compressed margins on electric subassemblies. Supply concentrates in Germany for precision screw-barrel fabrication, Italy for mold base casting, and Belgium for control system integration. Component sourcing draws from Japanese servo-drive manufacturers, Chinese rare-earth magnet processors, and Swedish specialty steel mills. Single-source vulnerability sits with coated beryllium-copper alloy suppliers in Germany. Distribution runs through manufacturer-direct channels for large OEMs and specialized distributors for mid-tier retrofits.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Outcome-based service contracts with uptime and energy-consumption guarantees now expand faster than hardware sales across French dairy and water bottling clusters. This recurring-revenue layer commands 40-60% gross margins versus 20-30% on equipment, reframing the market as a service-attach opportunity.
For Market Incumbents: Consolidate aftermarket service networks in Spain's underpenetrated Catalonia and Valencia bottling corridors before emerging automation specialists establish footholds. Deepen backward integration into screw-barrel fabrication to offset volatility in Japanese servo-drive pricing. CE marking documentation advantages under the EU Machinery Directive provide defensive moats against Asian exporters facing extended conformity timelines. For New Entrants and Emerging Players: Anchor in Spanish chemical packaging processors around Tarragona demanding extrusion blow molding retrofits with EU Green Deal compliance. Target hybrid system white space in Lombardy and Piedmont where energy-sensitive producers seek electric precision without full capital replacement. Pursue technology licensing partnerships with established mold builders rather than direct OEM competition. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed Italian automation specialists holding pharmaceutical sterilization expertise but lacking beverage packaging scale. Five-to-ten year viability hinges on bioplastics processing capability development as PLA and bio-PET adoption accelerates. Monitor EU AI Act predictive maintenance algorithm classification timelines as inflection signal for software-enabled valuation premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Screw-Barrel Fabrication | Captive supply of precision components insulates German OEMs from rare-earth price volatility. |
| Outcome-Based Service Contract Expansion | French dairy bottlers now negotiate uptime guarantees that collapse capital purchase cycles into recurring revenue. |
| Bioplastics Processing Capability Development | PLA and bio-PET compatibility gaps create white space for specialized extruder engineering in Italian clusters. |
| Predictive Maintenance Software Certification | EU AI Act compliance for embedded algorithms creates first-mover advantage in condition-monitoring services. |
| Hybrid System Retrofit Program Rollout | Spanish mid-tier bottlers in legacy plants represent addressable base for electric-hydraulic conversion kits. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured interviews with plant engineers at German beverage bottlers, procurement leads at French pharmaceutical packaging clusters, aftermarket service heads at Italian OEMs, and maintenance directors at Spanish chemical processors. Secondary validation incorporated ECHA REACH documentation databases, EU Machinery Directive conformity assessment records, F-Gas Regulation phase-down schedules, and customs data on servo-drive imports. Bottom-up equipment shipment tallies and top-down end-use demand estimates were triangulated to anchor market sizing.
Across the analysis window, projections incorporate product type segmentation by stretch, reheat stretch, extrusion, and injection architectures; technology tiers spanning conventional, hybrid, advanced automated, and multilayer systems; and end-use verticals including packaging, pharmaceutical, automotive, and consumer goods. CAGRs were derived from regression analysis against EU Green Deal energy-efficiency mandate timelines and pharmaceutical sterile manufacturing capacity expansion plans. Forecast inputs include F-Gas Regulation compliance cycle assumptions and bioplastics adoption curves.
Material uncertainties — abrupt refrigerant technology shifts, REACH documentation timeline extensions, or AI Act algorithm reclassification — sit outside the modeled envelope. Forecasts reflect documented assumptions on regulatory implementation pacing and substitution elasticities between hydraulic and electric architectures. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Machinery
Piston Fillers Market
Packaging Machinery
Cutter-Box Packaging Market
Packaging Machinery
Vertical Strapping Machines Market
Packaging Machinery
Pick Fill Seal Machines Market
Packaging Machinery
Case Packing Machines Market
Packaging Machinery
Straw Machine Market
Packaging Machinery
Barcode Labeller Machine Market
Packaging Machinery
Form-Fill-Seal Equipment Market
Packaging Machinery
Tube Sealing Machines Market
Packaging Machinery
Vertical Injection Molding Machine Market
Packaging Machinery
Wicketed Bagging Machines Market
Packaging Machinery
Wraparound Case Packers Market
Packaging Machinery
Glue Machine Market
Packaging Machinery
Sack Fillers Market
Packaging Machinery
Corrugated Box Making Machine Market
Packaging Machinery
Bottle Blowing Machine Market