
 Iron Supplement Market | 2026-2036
Iron Supplement Market Size, Share, and Industry Trends Forecast 2026-2036
Iron Supplement Market Analysis
Aftermarket service revenue from subscription-based supplement delivery is rewriting how manufacturers capture lifetime value. Abbott Laboratories leverages its diagnostic-to-nutrition pipeline to anchor iron supplementation within chronic disease management protocols. NOW Foods competes through vertical control over raw material sourcing, sustaining margin integrity amid volatile mineral prices.
An iron supplement is a dietary product containing bioavailable iron compounds, typically ferrous sulfate, ferrous gluconate, or ferrous fumarate, formulated to correct or prevent iron deficiency by restoring hemoglobin synthesis and oxygen transport capacity. Tablets dominate volume due to manufacturing economies and pharmacy reimbursement familiarity, while gummies capture the fastest expansion as pediatric and young-adult palatability preferences reshape formulation R&D. Liquid formulations occupy a stable clinical niche where swallowing difficulties or malabsorption conditions mandate alternative delivery, with pharmacies and online retailers splitting the channel margin pool as direct-to-consumer platforms erode traditional retail iron supplement traffic.
The FDA oversees dietary supplement Good Manufacturing Practices and adverse event reporting, while the EMA and national European regulators enforce novel food and health claim validations that gate market entry for fortified iron products. India's FSSAI mandates fortification standards for public distribution iron supplements, directly shaping procurement specifications and domestic manufacturer compliance investments. Stakeholders must monitor evolving bioequivalence requirements for generic ferrous salts and the regulatory trajectory of heme-iron alternatives as novel ingredient classifications proliferate across jurisdictions.
Market Dynamics
Subscription-based supplement delivery is digitizing how manufacturers capture lifetime value, anchoring iron supplementation within chronic disease management protocols and reshaping formulation R&D around pediatric palatability preferences.
Growth Catalysts
- Prenatal care expansion:National anemia reduction campaigns in India drive fortified product access through public health channels, elevating demand among women of childbearing age.
- Fortification mandates:India's FSSAI fortification standards for public distribution iron supplements reshape procurement specifications and domestic manufacturer compliance investments.
- Heme-iron alternatives:Novel ingredient classifications for bioavailable iron compounds are proliferating across jurisdictions, expanding formulation options beyond traditional ferrous salts.
Market Restraints
- Mineral price volatility:Raw material sourcing costs for ferrous sulfate and ferrous gluconate fluctuate with mining output and energy-intensive processing economics.
- Regulatory friction:The FDA's updated labeling requirements for dietary supplements force reformulation investments and inventory write-downs for non-compliant SKUs.
- Substitution pressure:Food fortification programs and intravenous iron therapies in clinical settings displace oral supplement consumption in severe deficiency cases.
Strategic Opportunities
- Gummy format penetration:Pediatric and young-adult palatability preferences in North America and Western Europe open white space beyond tablet-dominated pharmacy channels.
- Direct-to-consumer platforms:Online retailers erode traditional retail iron supplement traffic, enabling margin capture previously lost to distributor markups.
- Chronic disease integration:Diagnostic-to-nutrition pipelines embed iron supplementation within renal care and oncology protocols, expanding reimbursable indications.
Industry Challenges
- Bioequivalence validation:Generic ferrous salts face evolving bioequivalence requirements across the FDA and EMA, extending approval timelines and clinical trial costs.
- Legacy pharmacy reimbursement:Tablets dominate volume due to entrenched pharmacy reimbursement familiarity, creating channel resistance to novel delivery formats.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Iron Supplement Market |
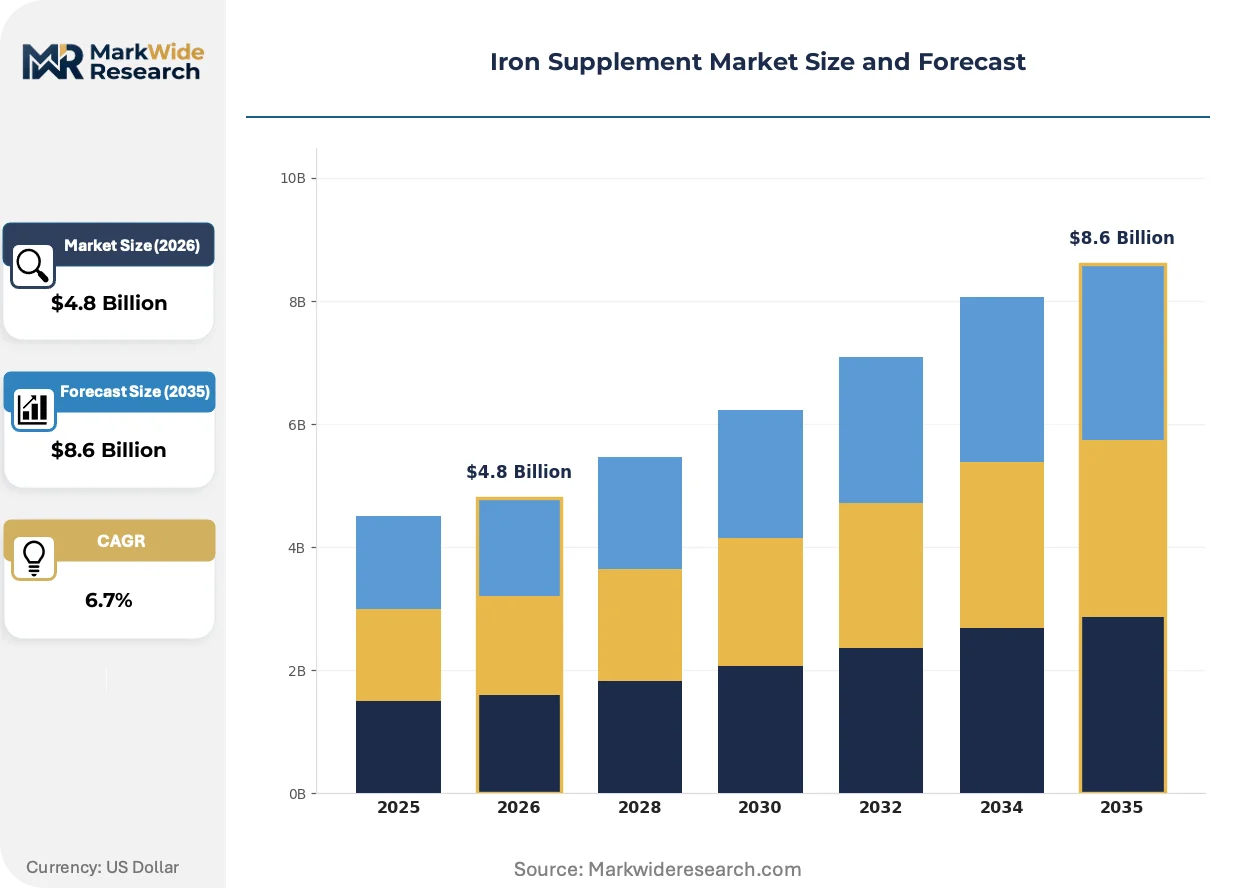
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tablets, Capsules, Liquid, Gummies End User: Women, Athletes, Vegetarians, Children Distribution Channel: Pharmacies, Supermarkets, Online Retailers, Health Stores Formulation: Ferrous Sulfate, Ferrous Gluconate, Ferrous Fumarate, Others |
| Companies Covered | Abbott Laboratories, Otsuka Pharmaceutical Co., Ltd., Pfizer Inc., Blackmores Limited, NOW Foods, Bayer AG, Nestlé, The Nature's Bounty Co., GlaxoSmithKline plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Iron Supplement Market Emerging Trajectories
Formulation science and distribution architecture are converging to personalize iron supplementation, with digital health integration and novel delivery systems compressing the gap between diagnosis and therapeutic adherence.
Microencapsulation technology is masking metallic taste and improving gastric tolerability of ferrous salts. Pediatric supplement buyers and adult consumers with swallowing difficulties are adopting these enhanced formulations at accelerated rates. This technology is digitizing adherence tracking through connected packaging that syncs consumption data with mobile health platforms.
The FDA's updated labeling requirements for dietary supplements are mandating clearer deficiency-risk disclosures and upper-limit warnings. Manufacturers must reformulate products to meet stricter purity standards for elemental iron content declarations. Tablet and capsule categories face the steepest compliance investments, while liquid formulations gain relative flexibility in label adaptation.
Direct-to-consumer subscription models are displacing pharmacy-centric replenishment habits among urban millennials and prenatal cohorts. Digital-native brands capture recurring revenue through personalized dosing algorithms and at-home hemoglobin testing integration. This shift concentrates in the United States and United Kingdom, where healthcare consumerism and high smartphone penetration enable seamless telehealth-supplement bundling.
Iron Supplement Market Segmentation
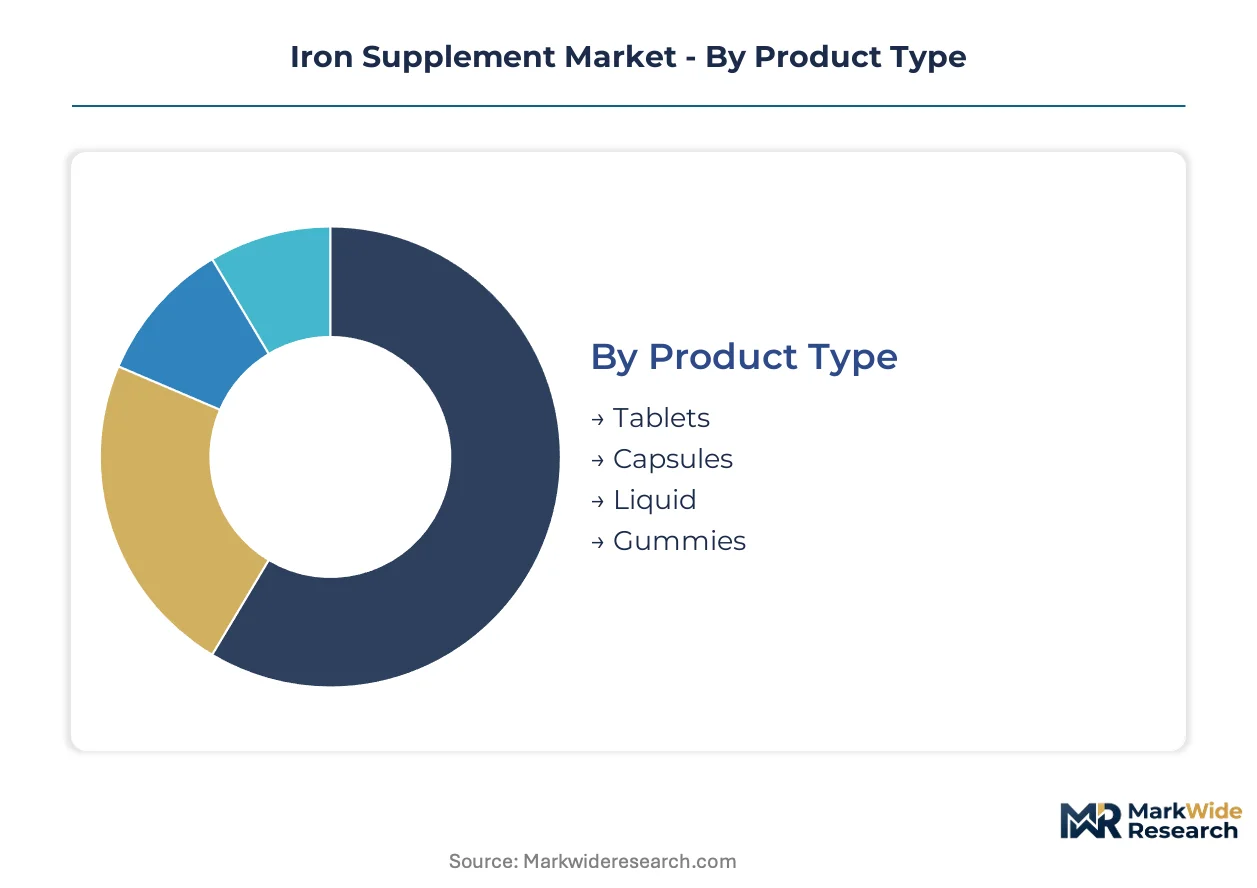
Subscription-based iron supplement delivery creates divergent service intensity across product formats. Pediatric gummies demand intensive onboarding support, while tablet replenishment operates with minimal intervention.
Product Type:
After-sales-service intensity varies dramatically by delivery mechanism, with liquid formulations requiring cold-chain guidance and gummies needing palatability troubleshooting that tablets never trigger.
- Tablets:Compressed ferrous sulfate or ferrous fumarate in scored or film-coated configurations. Manufacturing economies concentrate production in India and China for export to pharmacy chains across the United States and Germany. Reimbursement familiarity entrenches this format despite slower dissolution rates.
- Gummies:Gelatin or pectin matrices masking metallic taste through fruit flavoring systems. Demand concentrates among millennial parents in suburban United States markets where pediatric adherence failures drive format switching. Microencapsulation investments protect iron bioavailability during thermal processing.
- Capsules:Hard-shell gelatin or hypromellose enclosures for enteric release. Athletes in Australia and Canada favor this format for gym-bag portability.
- Liquid:Aqueous suspensions with dosing syringes for precise titration. Clinical prescribing in United Kingdom geriatric and bariatric practices sustains this niche.
Tablets hold the largest share; momentum sits with gummies.
End User:
Cost tier stratification separates premium-positioned prenatal segments from economy-tier pediatric formulations, with reimbursement eligibility determining effective price points across user categories.
- Women:Prenatal and perimenopausal cohorts drive volume through hemoglobin monitoring protocols. India's national anemia reduction campaigns distribute fortified tablets through public health channels to rural women of childbearing age. FSSAI compliance mandates shape domestic manufacturer specifications.
- Children:Palatability engineering dominates R&D spending as parents reject metallic aftertaste. Gummy adoption accelerates fastest in United States households with disposable income for premium formats.
- Athletes:Endurance sports participants in Italy and Spain pursue marginal hematocrit gains through controlled iron loading. Sports nutrition retail channels capture this premium segment.
- Vegetarians:Plant-based diet adherents in Netherlands and United Kingdom face non-heme iron absorption challenges. Heme-iron alternatives from animal sources are excluded by definition, driving demand for enhanced bioavailability formulations.
Women command the dominant volume position; children represent the steepest expansion trajectory.
Distribution Channel:
Volume concentration favors pharmacy networks with established reimbursement pathways, though margin capture is shifting toward direct-to-consumer platforms that eliminate distributor markups.
- Pharmacies:Brick-and-mortar dispensaries with pharmacist consultation services. Germany's Apotheken system and United States CVS/Walgreens chains dominate prescription-adjacent sales. Inventory write-downs from FDA labeling reforms hit this channel hardest.
- Online Retailers:Amazon, iHerb, and brand-direct subscription platforms. Urban millennials in London and New York metro areas drive recurring revenue through personalized dosing algorithms.
- Supermarkets:Mass-market placement in Walmart, Tesco, and Carrefour formats. Economy-tier tablets compete on shelf price in high-frequency shopping environments.
- Health Stores:GNC, Holland & Barrett, and independent natural product retailers. Premium capsule and liquid formats with organic positioning command shelf space here.
Pharmacies retain the largest share; online retailers are climbing the fastest.
Formulation:
Maturity gradients separate century-old ferrous sulfate from emerging heme-iron alternatives, with bioequivalence validation costs gating generic substitution for newer compounds.
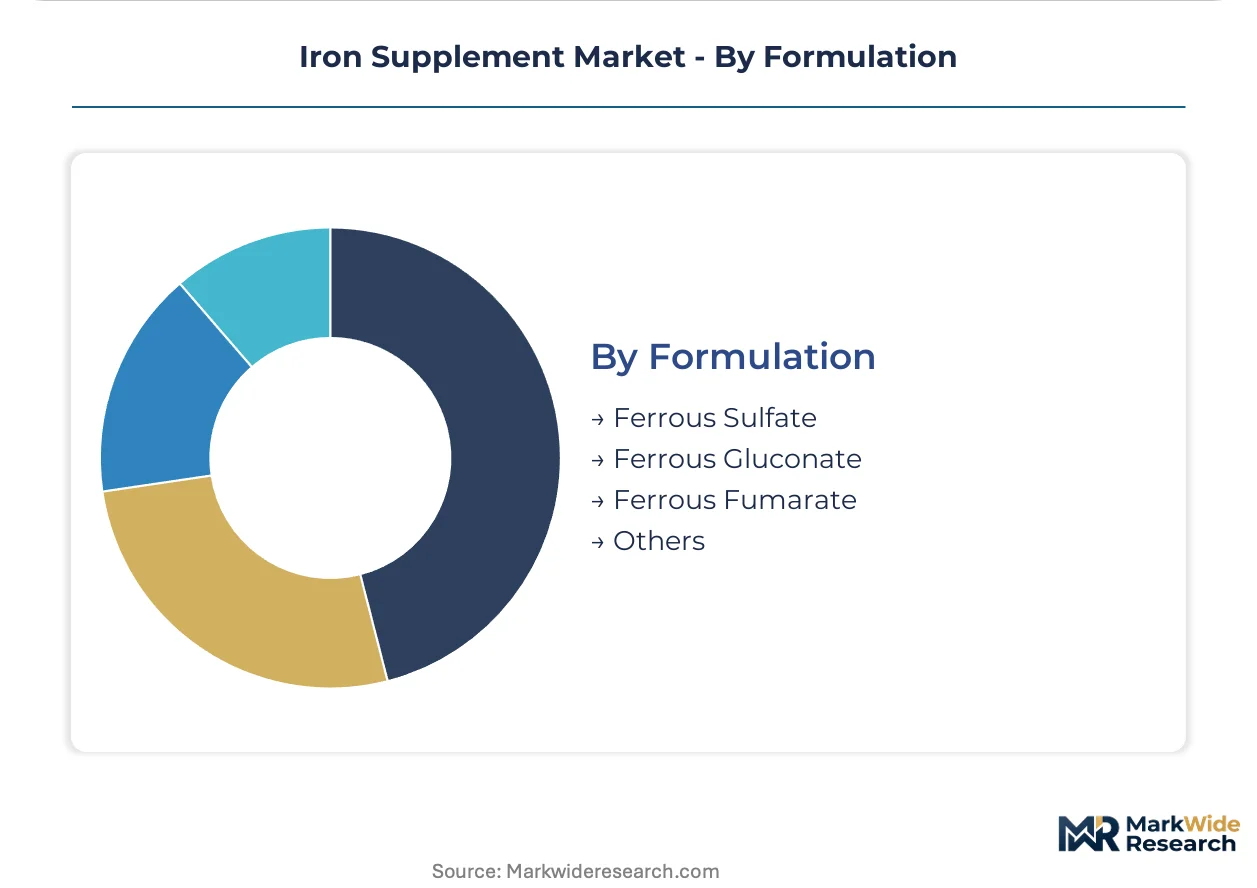
- Ferrous Sulfate:The reference standard with 65mg elemental iron per 325mg tablet. Cost-minimization procurement in India's public distribution system anchors global volume. Gastrointestinal side effects limit adherence in sensitive populations.
- Ferrous Fumarate:Higher elemental iron concentration per tablet reduces pill burden. United States prenatal vitamin formulations favor this salt for compliance optimization.
- Ferrous Gluconate:Milder gastric tolerability profile with lower elemental iron yield. Pediatric liquid suspensions in France and Italy utilize this form.
- Others:Heme-iron polypeptides, iron bisglycinate chelates, and carbonyl iron. Novel food classifications in European Union jurisdictions create regulatory friction for market entry.
Ferrous sulfate maintains volume leadership; heme-iron alternatives within Others are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply between clinical prescription channels in Western Europe and mass-market fortification programs in South Asia. India's public distribution networks prioritize cost-minimization through generic ferrous sulfate tablets, while United States households increasingly favor palatability-engineered gummies for pediatric adherence. Germany's pharmacy-centric Apotheken system sustains reimbursement-dependent tablet volumes that direct-to-consumer platforms have yet to displace.
United States
Millennial parents in suburban markets drive gummy format adoption as metallic aftertaste rejection reshapes pediatric supplementation. The FDA's updated labeling requirements for dietary supplements force reformulation investments and inventory write-downs for non-compliant SKUs. New York and Los Angeles metro areas concentrate subscription-based direct-to-consumer activity where personalized dosing algorithms capture recurring revenue.
India
National anemia reduction campaigns distribute fortified tablets through public health channels to rural women of childbearing age, anchoring global volume for ferrous sulfate. The FSSAI mandates fortification standards for public distribution iron supplements, directly shaping procurement specifications and domestic manufacturer compliance investments. Maharashtra and Gujarat host the largest concentration of contract manufacturing facilities serving both domestic public tenders and export markets.
Germany
The Apotheken system sustains prescription-adjacent tablet sales through entrenched pharmacy reimbursement familiarity that resists novel delivery formats. The EMA enforces novel food and health claim validations that gate market entry for fortified iron products with novel ingredient classifications. Berlin and Munich clusters concentrate specialty pharmacy distribution and diagnostic-to-nutrition pipeline integration for chronic disease protocols.
United Kingdom
Geriatric and bariatric clinical practices sustain liquid formulation demand where swallowing difficulties mandate precise titration via dosing syringes. The Medicines and Healthcare products Regulatory Agency aligns with EMA frameworks for bioequivalence validation of generic ferrous salts. London metro area households lead direct-to-consumer subscription adoption through telehealth-supplement bundling enabled by high smartphone penetration.
China
Domestic manufacturers leverage cost advantages in ferrous salt production to supply export markets while serving growing middle-class demand for enhanced bioavailability formulations. The NMPA oversees dietary supplement Good Manufacturing Practices with standards converging toward international harmonization. Yangtze River Delta industrial clusters concentrate tablet and capsule manufacturing capacity with integrated raw material processing capabilities.
Iron Supplement Market Vendor Landscape
Capability concentration sits with pharmaceutical-grade manufacturers possessing diagnostic-to-nutrition integration; scale advantage sits with commodity ferrous salt producers serving public procurement channels. The vendor base stratifies across three tiers: multinational healthcare conglomerates with chronic disease management protocols, mid-sized specialty nutrition houses with vertical raw material control, and regional contract manufacturers competing on cost-minimization for tender-based volumes. Dominant competitive moves include backward integration into mineral sourcing to defend margin integrity amid price volatility, and subscription platform development to capture lifetime value through recurring revenue models.
Among healthcare conglomerates with nutrition divisions, Abbott Laboratories and Pfizer Inc. exemplify the diagnostic-to-nutrition pipeline archetype that embeds iron supplementation within reimbursable chronic disease protocols. NOW Foods occupies a position within the specialty nutrition tier through upstream control over raw material sourcing that sustains formulation flexibility. Blackmores Limited represents the geographic-specialist archetype, anchoring Asia-Pacific market development through regional regulatory navigation capabilities.
| Leading Market Players |
|---|
| Abbott Laboratories |
| Otsuka Pharmaceutical Co., Ltd. |
| Pfizer Inc. |
| Blackmores Limited |
| NOW Foods |
| Bayer AG |
| Nestlé |
| The Nature's Bounty Co. |
| GlaxoSmithKline plc |
| Others |
Supply Flow & Price Mechanics
Mineral price volatility in ferrous sulfate and ferrous gluconate inputs compresses margin spreads across all three pricing tiers while forcing supply chain restructuring toward dual-source raw material strategies and extended payment term negotiations with Indian and Chinese contract manufacturers.
Pricing Analysis
Long-term offtake contracts anchor procurement for public distribution programs in India, while spot purchasing dominates premium gummy and liquid formulations in North American direct-to-consumer channels. Three-tier pricing structure across premium, standard, and economy levels separates heme-iron alternatives from ferrous fumarate tablets and generic ferrous sulfate tenders. Cost compression in economy-tier tablets is intensifying because India's FSSAI fortification mandates force purity standard investments without corresponding price adjustment mechanisms. Public health procurement officers exhibit highest price sensitivity; sports nutrition retailers purchasing enhanced bioavailability capsules show lowest elasticity.
Supply Chain Analysis
Extended payment terms from 60 to 90 days are becoming standard in supply-chain finance facilities offered by Indian and Chinese raw material processors to downstream formulation houses. Active pharmaceutical ingredient production for ferrous salts concentrates in India, China, and Germany, with gelatin and pectin matrix suppliers for gummy formats drawing from Brazil and Argentina. Single-source vulnerability in microencapsulation technology licensing creates bottleneck risk for pediatric palatability-engineered products. Distribution runs through pharmacy chains with established reimbursement pathways, though cold-chain requirements for liquid formulations sustain regional hub-and-spoke logistics networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Formulation science capabilities in heme-iron alternatives and microencapsulation technology remain scarce assets, creating acquisition premiums for specialists possessing proprietary delivery systems or regulatory approval in multiple jurisdictions.
For Market Incumbents: Build regulatory data moats through parallel FDA and EMA bioequivalence dossiers for novel iron compounds, insulating against generic substitution pressure from emerging ferrous bisglycinate entrants. Secure captive supply of pharmaceutical-grade ferrous sulfate through backward integration into Indian mineral processing or long-term tolling agreements with Maharashtra-based manufacturers. Channel control investments in direct-to-consumer subscription platforms defend against margin erosion from pharmacy distributor consolidation. For New Entrants and Emerging Players: Rural India's public health tender system offers the most penetrable volume anchor for economy-tier ferrous sulfate tablets compliant with FSSAI fortification standards. Pediatric gummy white space in suburban United States markets rewards microencapsulation partnerships with established flavor houses and rapid SKU expansion through Amazon-native brand architectures. Go-to-market execution should prioritize telehealth bundling with at-home hemoglobin testing integration. For Investors and Strategic Acquirers: The FDA's updated labeling requirements for dietary supplements reshapes the acquisition landscape toward targets with compliance-ready inventory and reformulation agility rather than legacy tablet portfolios. Long-term viability centers on diagnostic-to-nutrition pipeline integration capabilities spanning five-to-ten year chronic disease management adoption curves. Watch for EMA novel food classification decisions on heme-iron polypeptides as the signal indicating whether premium-tier formulation science investments will capture reimbursable indications or remain niche wellness positioning.| Strategic Initiative | Industry Significance |
|---|---|
| Microencapsulation Technology Licensing | Pediatric palatability engineering unlocks gummy format premium pricing in United States suburban markets. |
| Direct-to-Consumer Subscription Launch | Recurring revenue capture bypasses pharmacy distributor markups and enables personalized dosing algorithms. |
| FSSAI Compliance Investment | Fortification standard certification secures access to India's public distribution tender volumes. |
| Diagnostic Partnership Integration | Abbott Laboratories' pipeline model embeds iron supplementation within reimbursable chronic disease protocols. |
| Dual-Jurisdiction Regulatory Dossier | Parallel FDA and EMA submissions accelerate market access for novel heme-iron alternatives. |
Methodological Framework
Desk research of FDA adverse event reporting databases, FSSAI fortification standard notifications, and EMA novel food classification precedents preceded structured interviews with prenatal care protocol directors, pharmacy chain formulary managers, contract manufacturing executives in Gujarat and Maharashtra, and sports nutrition retail buyers. Secondary validation drew from customs trade data for ferrous salt imports, SEC 10-K nutrition segment disclosures, and Indian public tender award records. Bottom-up volume builds across product formats and end-user segments triangulated against top-down expenditure flows from national anemia reduction program budgets.
Fixed assumptions across the modeling period held mineral price volatility within observed historical bands and regulatory enforcement intensity at current levels across FDA, EMA, and FSSAI jurisdictions. Segmentation dimensions modeled included product type, end-user category, distribution channel, and geographic regulatory cluster. CAGRs derived from logistic diffusion curves fitted to format adoption patterns and public health program expansion timelines. Industry-specific inputs encompassed hemoglobin screening protocol penetration rates and pharmacy reimbursement pathway stability indices.
The forecast holds incumbent behavior within observed patterns; aggressive moves by diagnostic-to-nutrition integrated healthcare conglomerates or state-backed Chinese mineral processors would shift outcomes through accelerated vertical consolidation or supply-side capacity surges. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
Global Docosahexaenoic Acid (DHA) Market
Nutritional Supplements
North America Collagen Supplements Market
Nutritional Supplements
North America Vegan Supplements Market
Nutritional Supplements
Vitamin Shot Market
Nutritional Supplements
Nutritional Lipids Market
Nutritional Supplements
South America Collagen Supplements Market
Nutritional Supplements
Europe Botanical Supplements Market
Nutritional Supplements
Asia Pacific Nutritional Supplements Market
Nutritional Supplements
Eggshell Membrane Powder Market
Nutritional Supplements
Asia-Pacific Beta-Glucan Market
Nutritional Supplements
North America Bovine Lactoferrin Market
Nutritional Supplements
Inflammation Supplements Market
Nutritional Supplements
Middle East Protein Market
Nutritional Supplements
Grass-Fed Collagen Market
Nutritional Supplements
Organic Whey Protein Market
Nutritional Supplements
Asia Pacific Nutraceuticals Market