
 Asia-Pacific Car Loan Market | 2026-2036
Asia-Pacific Car Loan Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Car Loan Market Insights
Private-hire vehicle operators is realigning the largest demand pool in Southeast Asia, displacing traditional individual ownership as the primary borrower class. Toyota Financial Services leverages its captive finance arm to dominate fleet origination across Thailand and Indonesia. HDFC Bank anchors retail penetration in India's tier-two cities through dealer-integrated digital underwriting.
An Asia-Pacific car loan constitutes a secured credit instrument collateralized by vehicle title, typically structured with loan-to-value ratios between seventy and ninety percent and repayment horizons spanning twelve to eighty-four months. Its commercial purpose channels liquidity to automotive acquisition while generating interest income and asset-backed securities for originators. New car loans command the deepest margin pools where captive finance subsidiaries extract cross-selling value from manufacturer relationships, while used car loans represent the fastest-expanding segment as digital remarketing platforms compress information asymmetry between buyers and lenders. Lease financing occupies a narrower niche concentrated among corporate fleet managers seeking off-balance-sheet treatment.
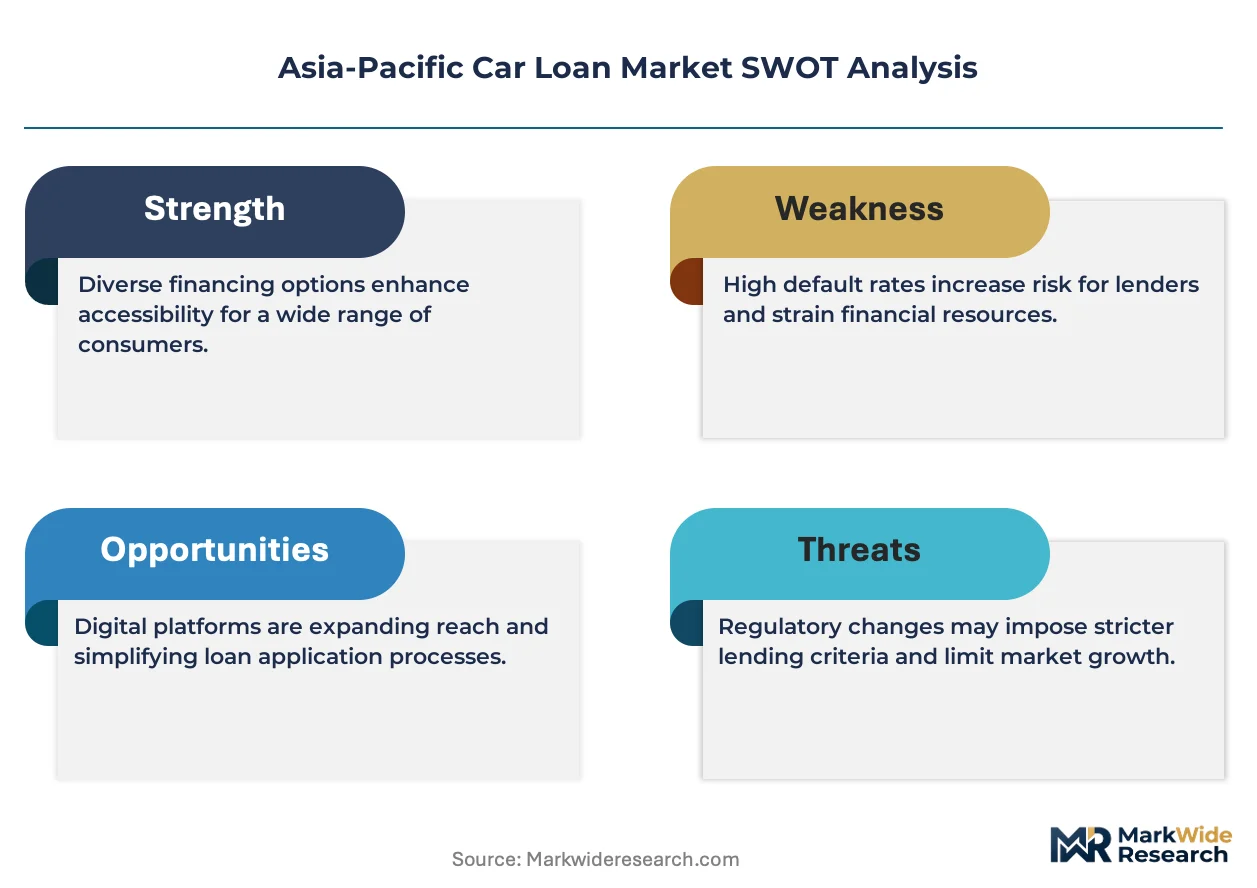
India's RBI digital lending guidelines, Australia's ASIC responsible lending obligations, and China's CBIRC consumer protection standards collectively reshape origination compliance costs and documentation requirements across the region. Australia's National Consumer Credit Protection Act imposes stringent suitability assessments that lengthen approval timelines but reduce portfolio delinquency. Stakeholders must monitor how central bank rate divergence between Australia, India, and China alters cross-border funding strategies and hedging structures.
Market Dynamics
Fleet operators across Southeast Asia are displacing individual borrowers as the dominant demand source, restructuring origination priorities toward commercial underwriting frameworks and dealer network reconfiguration.
Growth Catalysts
- India's RBI Digital Lending Guidelines:Standardized e-KYC and consent-based data sharing accelerate paperless origination, reducing approval friction for tier-two city borrowers.
- Ride-hailing fleet expansion:Grab, Gojek, and regional platform operators scale vehicle procurement programs, generating concentrated loan demand with standardized collateral pools.
- Embedded finance APIs:Dealer management systems now integrate real-time credit decisioning, collapsing the gap between vehicle selection and loan disbursement.
Market Restraints
- Central bank rate divergence:Differential monetary policy between Australia, India, and Indonesia complicates cross-border funding and hedging structures for regional lenders.
- Used vehicle information asymmetry:Fragmented condition assessment standards across Thailand, Vietnam, and the Philippines elevate residual value uncertainty and collateral risk pricing.
- ASIC responsible lending obligations:Australia's suitability assessment requirements lengthen approval timelines and elevate compliance documentation costs relative to regional benchmarks.
Strategic Opportunities
- Vietnam's secondary cities:Da Nang, Hai Phong, and Can Tho exhibit vehicle penetration gaps against ASEAN income-adjusted benchmarks, presenting greenfield origination potential.
- Electric vehicle transition incentives:Thailand's EV tax rebates and Indonesia's battery vehicle import duty reductions create preferential financing margins for green collateral.
- Telematics-enabled usage-based products:Integration of GPS and driver behavior data allows dynamic pricing models that align repayments with actual fleet utilization patterns.
Industry Challenges
- Legacy core system integration:Established lenders face friction connecting decades-old loan servicing platforms to modern API-driven dealer and fintech interfaces.
- Cross-border data localization:Divergent requirements across ASEAN member states complicate centralized credit scoring models and customer data portability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Car Loan Market |
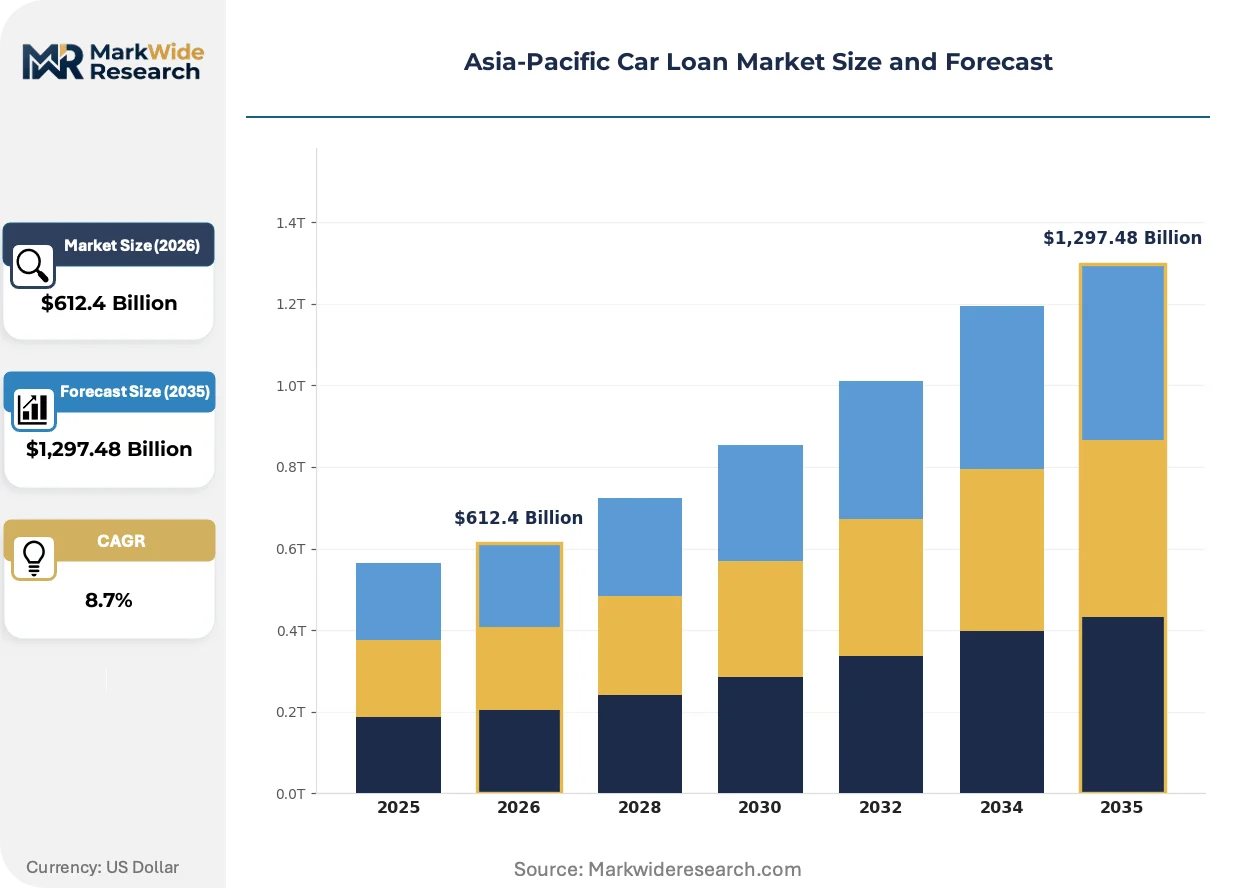
| Market Size in 2026 | $612.4 Billion |
| Market Size in 2035 | $1,297.48 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: New Car Loans, Used Car Loans, Lease Financing, Refinancing Customer Type: Individual Borrowers, Corporate Clients, Dealership Financing, Direct Lending Repayment Terms: Short Term, Medium Term, Long Term, Flexible Plans Interest Rate Type: Fixed Rate, Variable Rate, Hybrid Rate, Subsidized Loans |
| Companies Covered | Toyota Financial Services, HDFC Bank, Bank of China, ANZ Bank, Maybank, DBS Bank, OCBC Bank, PT Bank Mandiri, PT Bank Central Asia, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Car Loan Market Trends and Innovations
Digital origination infrastructure is compressing the traditional dealership-lender-borrower triangle, while regulatory fragmentation and fleet operator procurement centralization reshape competitive positioning across the region.
Artificial intelligence-driven credit scoring is consolidating alternative data sources—utility payments, mobile wallet histories, and geolocation patterns—into unified risk models. Non-bank lenders in Indonesia and the Philippines deploy these systems to serve thin-file borrowers excluded from conventional bureau scoring. The structural consequence is consolidating underwriting authority away from relationship-based branch networks toward centralized algorithmic platforms that operate at national scale with minimal physical presence.
China's CBIRC consumer protection standards and India's RBI digital lending guidelines impose parallel consent architecture and grievance redressal mandates on originators. These frameworks elevate operational compliance costs but create regulatory moats against undercapitalized competitors. Digital-native lenders in both markets respond by building dedicated compliance engineering teams that embed regulatory logic directly into product workflows rather than treating adherence as a post-hoc audit function.
Fleet procurement centralization among ride-hailing and logistics operators is displacing fragmented individual borrower acquisition as the primary origination channel. Toyota Financial Services and HDFC Bank restructure dealer incentive programs to prioritize volume commitments from fleet managers over retail walk-in traffic. This concentration is most visible in Indonesia's urban corridor from Jakarta to Surabaya, where platform-operated vehicles now represent the majority of new auto loan origination value.
Asia-Pacific Car Loan Market Segmentation
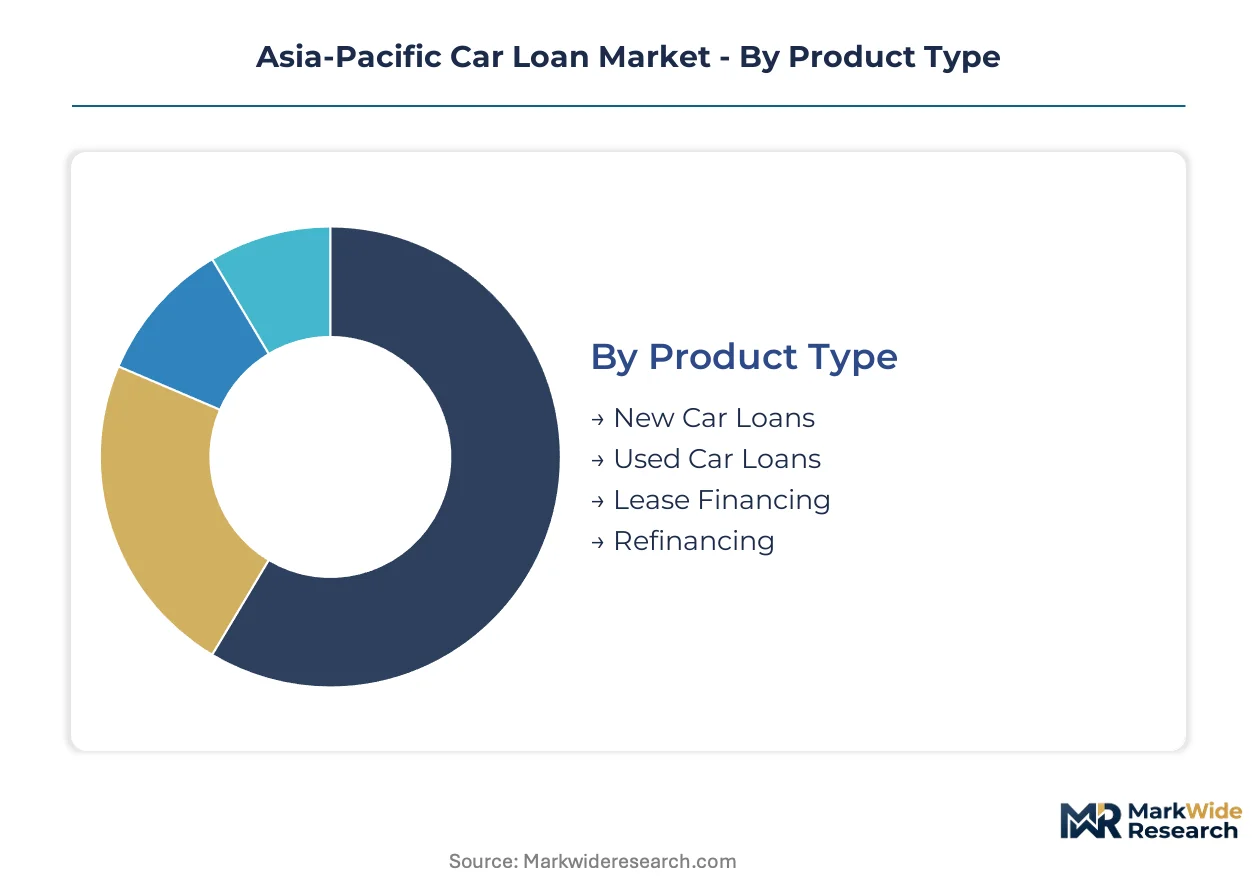
Segmentation in the Asia-Pacific car loan market reveals how collateral type, borrower structure, and rate mechanics determine origination workflows and risk pricing. Each dimension carries distinct regulatory and operational implications across the region's fragmented banking and fintech landscape.
Product Type:
New car loans operate through captive finance arms with deep manufacturer integration, while used car and lease products demand alternative collateral assessment frameworks and residual value modeling.
- New Car Loans:Secured instruments collateralized by first-title vehicles, typically structured at 70-90% loan-to-value with manufacturer-backed residual guarantees. Demand concentrates among fleet operators in Indonesia's Jakarta-Surabaya corridor where platform procurement centralizes volume.
- Used Car Loans:Fastest-expanding segment as digital remarketing platforms compress information asymmetry between dispersed sellers and lenders. Non-bank lenders in the Philippines deploy AI-driven condition assessment to price collateral risk for thin-file borrowers.
- Lease Financing:Off-balance-sheet structures favored by corporate fleet managers seeking tax-advantaged vehicle access without ownership transfer.
- Refinancing:Rate-arbitrage products capturing borrowers from rising-rate environments into fixed-rate structures.
Volume placements concentrate in New Car Loans; the faster expansion belongs to Used Car Loans.
Customer Type:
Borrower classification shapes origination channel economics, from high-touch dealer-integrated retail to low-touch API-driven fleet procurement.
- Individual Borrowers:Traditional retail segment requiring KYC documentation and bureau scoring. RBI digital lending guidelines accelerate paperless origination for tier-two city penetration in India.
- Corporate Clients:Fleet operators and logistics platforms generating concentrated demand with standardized collateral pools and centralized procurement authority. Ride-hailing expansion across Southeast Asia restructures dealer priorities toward commercial underwriting.
- Dealership Financing:Inventory floorplan credit enabling dealer working capital rotation, integrated with retail loan origination systems.
- Direct Lending:Bank-fintech partnerships bypassing dealer networks through embedded finance APIs that collapse selection-to-disbursement timelines.
Corporate placements now match Individual volume in key Southeast Asian markets; Direct Lending climbs fastest as API infrastructure matures.
Repayment Terms:
Tenure structure aligns with collateral depreciation curves and borrower cash flow predictability across salaried, self-employed, and fleet utilization profiles.
- Short Term:12-24 month structures for premium vehicles and corporate fleet rotation cycles, minimizing residual value exposure.
- Medium Term:36-60 month standard for mass-market new car origination, balancing installment affordability with collateral coverage duration.
- Long Term:72-84 month products penetrating budget segments where monthly payment minimization overrides total interest cost.
- Flexible Plans:Seasonal or usage-linked repayment structures for agricultural and tourism-dependent borrowers in Indonesia and Thailand.
Medium Term dominates origination value; Flexible Plans gain traction fastest among platform-operated fleet vehicles.
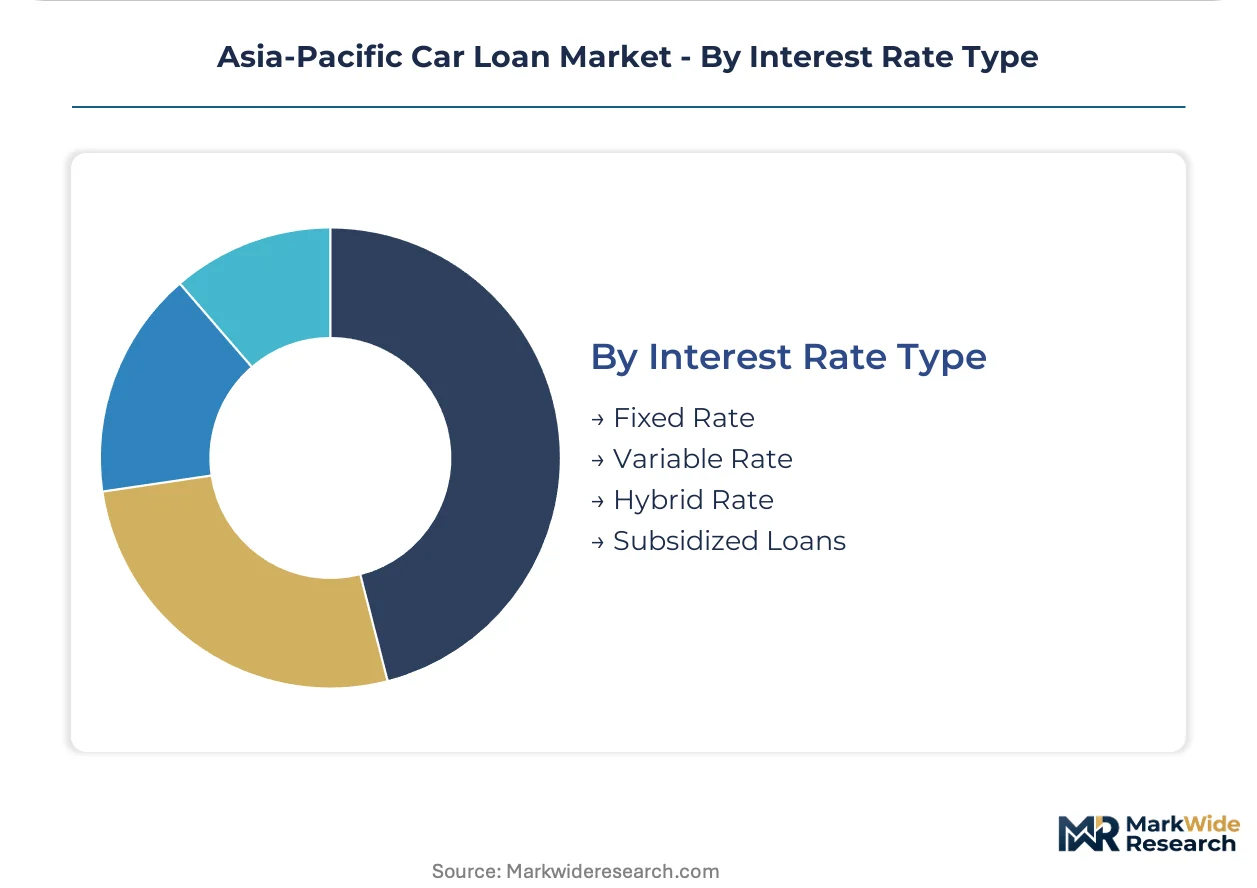
Interest Rate Type:
Rate mechanics determine funding cost pass-through and hedging complexity across divergent central bank policy cycles in Australia, India, and Indonesia.
- Fixed Rate:Predominant structure in Australia under ASIC responsible lending obligations, providing borrower certainty but exposing lenders to duration risk.
- Variable Rate:Tied to central bank policy rates, prevalent in India where RBI rate movements directly transmit to EMIs and portfolio yields.
- Hybrid Rate:Fixed-to-float conversions after initial lock periods, managing early-year affordability with later-year market alignment.
- Subsidized Loans:Government-backed programs for electric vehicle transition in Thailand and Indonesia, creating preferential margin pools for green collateral.
Fixed Rate placements lead in Australia; Variable Rate structures dominate India and Southeast Asia; Subsidized Loans expand most quickly around EV policy incentives.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Thailand's Eastern Economic Corridor tax incentives are concentrating captive finance operations and fleet leasing platforms, drawing regional origination capacity toward Bangkok-Rayong industrial corridor.
India
RBI digital lending guidelines and tier-two city vehicle penetration are accelerating paperless origination. The central bank's e-KYC mandates reduce approval friction for dealer-integrated platforms. Maharashtra and Gujarat anchor retail loan growth through Mumbai-Ahmedabad manufacturing clusters.
Indonesia
Ride-hailing fleet procurement and platform-operated vehicle financing dominate new demand formation. OJK consumer protection standards reshape documentation workflows for digital lenders. The Jakarta-Surabaya urban corridor generates the majority of new auto loan origination value.
Thailand
EV tax rebates and battery vehicle import duty reductions create preferential financing margins for green collateral. BOT macroprudential measures govern loan-to-value ceilings for passenger vehicles. The Eastern Economic Corridor concentrates Toyota Financial Services fleet operations and captive finance infrastructure.
Australia
ASIC responsible lending obligations impose stringent suitability assessments that lengthen approval timelines. Fixed-rate structures predominate under borrower certainty requirements. Sydney and Melbourne metropolitan areas concentrate retail origination through dealer-integrated digital platforms.
Vietnam
Secondary city vehicle penetration gaps against ASEAN income-adjusted benchmarks present greenfield origination potential. SBV credit growth quotas channel liquidity toward consumer finance subsidiaries. Da Nang and Hai Phong exhibit accelerating demand as logistics platforms expand fleet procurement.
Asia-Pacific Car Loan Market Competitive Landscape
Top-tier vendors anchor captive finance and universal banking segments, while non-bank digital lenders and fintech platforms occupy the agile-response tier. The market structure consolidates around manufacturer-captive arms with deep dealer integration, universal banks with national branch networks, and technology-native platforms leveraging alternative data scoring. Strategic archetypes include captive finance subsidiaries extracting cross-selling value from OEM relationships, universal banks scaling through dealer management system APIs, and algorithmic platforms serving thin-file borrowers outside conventional bureau coverage. Dominant competitive moves encompass embedded finance partnerships collapsing selection-to-disbursement timelines and telematics-enabled usage-based product development.
Among Japan-based captive finance operators, Toyota Financial Services exemplifies the manufacturer-integrated archetype with deep Thailand-Indonesia dealer network penetration. Within India's universal banking tier, HDFC Bank occupies a position representing tier-two city retail origination through digital underwriting integration. Chinese state-backed commercial banking groups including Bank of China anchor cross-border funding capacity for regional vehicle import financing.
| Leading Market Players |
|---|
| Toyota Financial Services |
| HDFC Bank |
| Bank of China |
| ANZ Bank |
| Maybank |
| DBS Bank |
| OCBC Bank |
| PT Bank Mandiri |
| PT Bank Central Asia |
| Others |
Pricing and Supply Chain Analysis
Thailand's EV tax rebate mandates and Indonesia's battery vehicle import duty reductions gate qualified supply access and premium-tier pricing for green collateral originators across the region. Fleet procurement centralization among platform operators compresses margins for standardized products while creating pricing power for telematics-enabled usage-based structures.
Pricing Analysis
Lead-time-driven pricing angles dominate fleet origination workflows, with short-cycle approvals commanding premium spreads and spot inventory clearance triggering discount structures. Three-tier pricing separates captive finance subsidiaries from universal bank programs from non-bank digital platforms, with manufacturer integration and bureau data depth as primary differentiation drivers. Pricing pressure stems from central bank rate divergence complicating hedging cost pass-through. Individual borrowers in tier-two Indian cities exhibit highest price sensitivity; fleet managers with centralized procurement authority demonstrate lowest sensitivity due to volume leverage.
Supply Chain Analysis
Direct-to-fleet channels handle concentrated demand from ride-hailing and logistics operators, while dealer-integrated distribution serves fragmented retail origination. Geographic supply concentration centers on Thailand for captive finance infrastructure, India for digital underwriting platforms, and Indonesia for platform-operated vehicle procurement. Funding liquidity draws from central bank policy rates, cross-border wholesale markets, and securitization pools. Single-source vulnerability runs through dealer management system providers dominating API infrastructure. Distribution runs through manufacturer-captive arms, universal bank partnerships, and embedded finance fintech integrations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market constitutes a vertical-integration race where control over telematics data streams and dealer API infrastructure determines origination cost structures. Players are pursuing downstream integration into fleet management platforms to lock in recurring revenue pools.
For Market Incumbents: Hedge against algorithmic lending displacement by acquiring alternative data scoring capabilities and embedding compliance engineering into product workflows. Captive finance arms should deepen API integration with dealer management systems to defend against fintech disintermediation. Regulatory moats from RBI digital lending guidelines and ASIC responsible lending obligations favor capitalized incumbents who can absorb elevated compliance costs.
For New Entrants and Emerging Players: Enter via Vietnam's secondary cities where vehicle penetration gaps against ASEAN income-adjusted benchmarks create white-field origination potential. Target thin-file borrowers outside conventional bureau coverage using AI-driven credit scoring that consolidates utility payments and mobile wallet histories. Pursue telematics-enabled usage-based products as the go-to-market angle for fleet operator segments.
For Investors and Strategic Acquirers: Fleet procurement centralization exceeding individual borrower volume in Indonesia's Jakarta-Surabaya corridor is the leading indicator that platform-operated vehicle financing will dominate origination value pools. Long-term viability favors algorithmic platforms with national scale and minimal physical presence over branch-dependent relationship networks. Acquisition targets should demonstrate embedded finance API maturity and compliance engineering capabilities. Watch for EV policy incentive expansion as the signal for green collateral margin pool growth.
| Strategic Initiative | Industry Significance |
|---|---|
| Telematics Data Platform Integration | Enables dynamic pricing models aligned with actual fleet utilization patterns across Southeast Asia. |
| Dealer API Infrastructure Expansion | Collapses selection-to-disbursement timelines for HDFC Bank and Toyota Financial Services origination workflows. |
| Compliance Engineering Team Buildout | Embeds RBI and ASIC regulatory logic directly into product workflows rather than post-hoc audit functions. |
| Alternative Data Scoring Acquisition | Consolidates utility payments and mobile wallet histories to serve thin-file borrowers in Indonesia and Philippines. |
| Fleet Management Platform Partnership | Locks in recurring revenue from Grab and Gojek vehicle procurement programs in urban corridors. |
Research Methodology
Central bank policy disclosures, automotive registration databases, and securitization prospectuses formed the secondary backbone of this analysis. Primary interviews with captive finance executives, digital lending product heads, dealer operations managers, and fleet procurement directors at ride-hailing platforms combined with secondary validation. Bottom-up origination volume triangulation against top-down funding flow analysis ensured cross-verification of market sizing across the analysis window.
Historical trendline analysis of loan origination volumes, portfolio delinquency rates, and central bank policy rate movements established baseline growth parameters. Segmentation modeling incorporated product type, customer structure, repayment tenure, and interest rate mechanics alongside regional regulatory cluster variations. CAGRs were derived from fitted trend projections adjusted for policy incentive phase-ins and fleet procurement cycle intensities. Forecast inputs included EV subsidy program durations and digital lending guideline implementation trajectories.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt central bank rate divergence or EV incentive withdrawal scenarios. Periodic stress-testing of base assumptions is recommended given regulatory fragmentation and cross-border data localization uncertainties.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Loans and Leasing
Germany Auto Loan Market
Loans and Leasing
Australia Automotive Financing Market
Loans and Leasing
China Mortgage/Loan Brokers Market
Loans and Leasing
France Student Loan Market
Loans and Leasing
Japan Car Loan Market
Loans and Leasing
Payday Loans Market
Loans and Leasing
Corporate Lending Market
Loans and Leasing
Used Car Financing Market
Loans and Leasing
Truck Financial Leasing Market
Loans and Leasing
Working Capital Loan Market
Loans and Leasing
Auto Finance Market
Loans and Leasing
Loan Servicing Software Market
Loans and Leasing
Indonesia Mortgage/Loan Brokers Market
Loans and Leasing
Factoring Market
Loans and Leasing
Car Finance Market
Loans and Leasing
Global Commercial Loan Software Market