
 Reduced-Risk Products (Rrps) Market | 2026-2036
Reduced-Risk Products (Rrps) Market Size, Share, and Industry Trends Forecast 2026-2036
Reduced-Risk Products (Rrps) Market Insights
Modular pod and cartridge bundling is repositioning how consumers purchase and replenish reduced-risk devices, shifting unit economics toward recurring consumables rather than hardware. Philip Morris International leverages its IQOS platform to anchor heated tobacco growth across multiple continents. British American Tobacco competes through its glo device ecosystem and broad vapor portfolio. Japan Tobacco International dominates its home market with Ploom and sustains aggressive R&D spending on next-generation aerosol technologies.
Reduced-risk products encompass nicotine delivery systems designed to minimize toxicant exposure relative to combustible cigarettes, typically operating below 350°C for heated tobacco or employing liquid vaporization at controlled wattages. These products serve smokers seeking to reduce harm while maintaining nicotine satisfaction. Heated tobacco products occupy the largest value pool given premium pricing and established brand loyalty, while nicotine pouches represent the fastest-expanding category as discrete, smoke-free formats gain traction among health-conscious consumers. Vapor products fragment across open-tank and closed-system designs, with margin concentration favoring proprietary pod architectures over generic refillables.
The FDA premarket authorization process determines which products legally enter the United States, while the EU Tobacco Products Directive and CE marking requirements govern market access across Europe. Japan's Ministry of Health, Labour and Welfare sets residual limits on harmful constituents that effectively filter product candidates. Stakeholders must monitor evolving flavor restrictions and taxation parity debates, as regulatory classification will determine whether reduced-risk products retain distinct commercial status or face full convergence with combustible cigarette regimes.
Market Dynamics
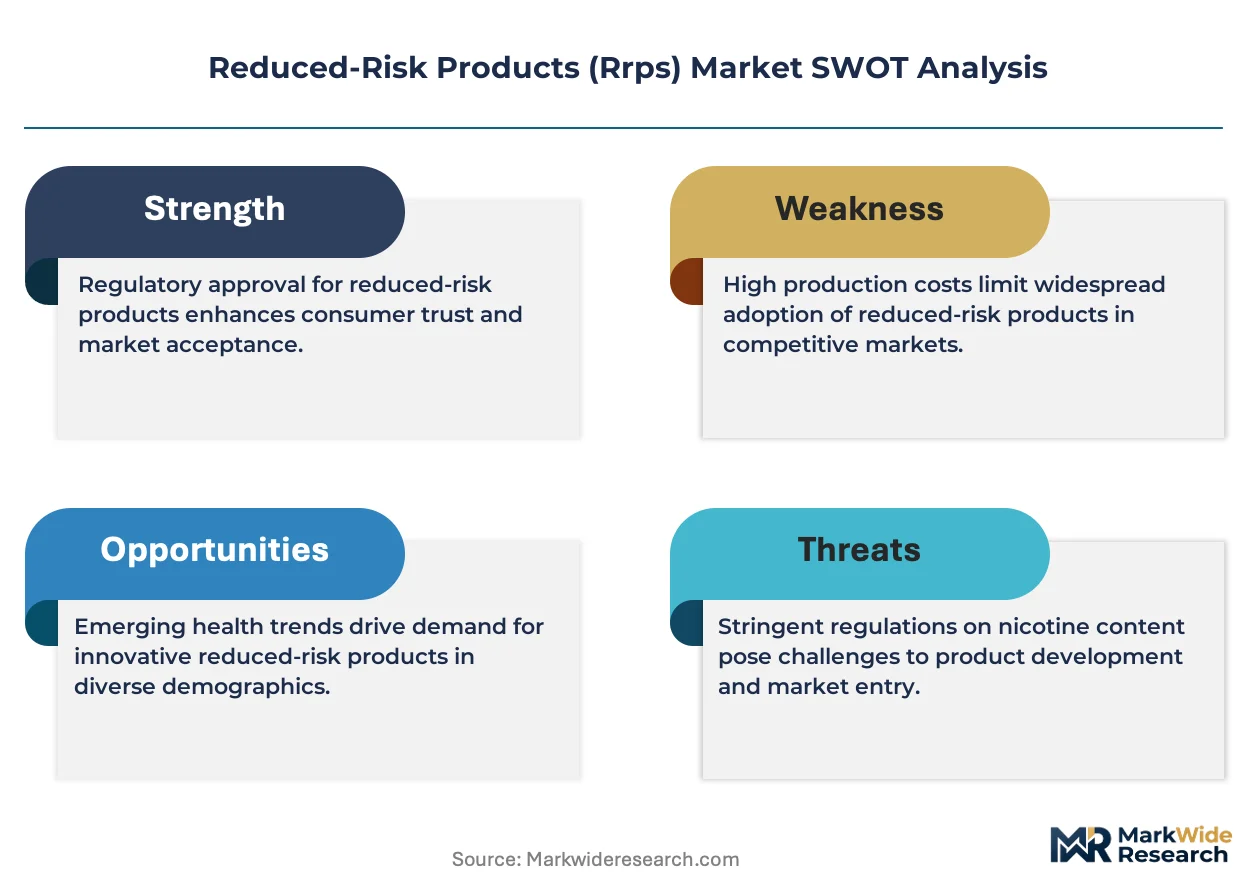
Modular pod architectures and cartridge bundling are restructuring unit economics across reduced-risk nicotine delivery, locking consumers into recurring consumable purchases rather than discrete hardware transactions. This shift concentrates margin capture in proprietary refill ecosystems while compressing generic open-system alternatives.
Growth Catalysts
- Flavor Innovation Pipelines:Tobacco-derived and synthetic nicotine formulations enable rapid product iteration that satisfies evolving consumer preferences while navigating regulatory constraints on characterizing flavors.
- Japan's Constituent Limits:The Ministry of Health, Labour and Welfare's residual harmful constituent thresholds create quality barriers that filter out inferior competitors and elevate compliant product premiums.
- Smoker Harm-Reduction Demand:Adult combustible cigarette users seeking reduced toxicant exposure without nicotine cessation represent a durable, motivated buyer base with established consumption rituals.
Market Restraints
- FDA Premarket Authorization Friction:The premarket tobacco product application pathway imposes multi-year timelines and substantial compliance costs that freeze market entry for non-incumbent innovators.
- Heated Tobacco Input Concentration:Specialized tobacco sheet manufacturing and precision heating element supply chains concentrate in limited East Asian production corridors, creating vulnerability to regional disruption.
- Taxation Parity Pressure:Proposals to equalize excise treatment between reduced-risk products and combustible cigarettes threaten to erode the price differential that drives consumer switching economics.
Strategic Opportunities
- Nicotine Pouch Geographic White Space:Scandinavian regulatory familiarity with oral nicotine products creates expansion pathways into Germany, the United Kingdom, and Switzerland where discrete consumption formats remain underpenetrated relative to tobacco heritage markets.
- EU Tobacco Products Directive Revision:Upcoming harmonization measures may standardize cross-border marketing and packaging rules, reducing fragmentation costs for multi-market operators.
- Pharmacy Channel Integration:Smoking cessation counseling infrastructure in British and German retail pharmacy networks offers a credibility-enhancing distribution vector distinct from traditional tobacco retail.
Industry Challenges
- Aerosol Science Talent Scarcity:Recruitment of inhalation toxicologists and aerosol physicists capable of generating publication-grade reduced-exposure evidence lags behind R&D program demands.
- Legacy Manufacturing Retrofit Costs:Converting cigarette production facilities for heated tobacco stick output requires capital-intensive cleanroom installation and precision cutting equipment incompatible with existing lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Reduced-Risk Products (Rrps) Market |
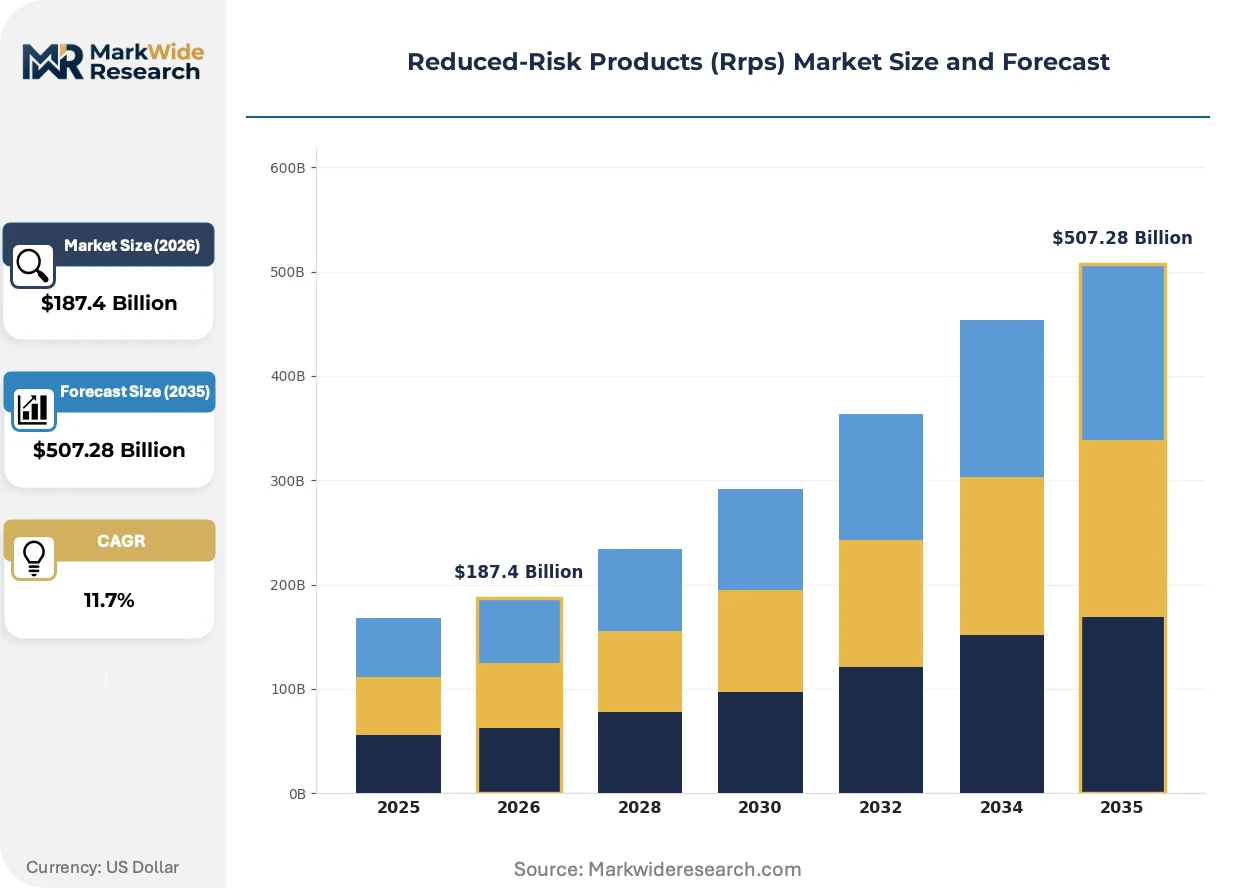
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $507.28 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electronic Cigarettes, Heated Tobacco Products, Nicotine Pouches, Vapor Products Application: Smokers, Vapor Enthusiasts, Health-Conscious Consumers, New Users Distribution Channel: Online Retailers, Specialty Shops, Convenience Stores, Supermarkets Regulatory Compliance: FDA Approved, CE Marked, TPD Compliant, Others |
| Companies Covered | Philip Morris International, British American Tobacco, Japan Tobacco International, Altria Group, Imperial Brands, KT&G, Swedish Match, Reynolds American, Juul Labs, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Reduced-Risk Products (Rrps) Market Trends and Innovations
Technology convergence between precision heating control and biometric user authentication is redefining device differentiation beyond nicotine delivery mechanics toward personalized consumption monitoring and access restriction.
Smart heating algorithms with real-time temperature modulation are expanding into premium device tiers, enabling consistent aerosol chemistry across variable draw patterns. Early adopters in Japanese and South Korean urban markets demonstrate willingness to pay hardware premiums for perceived reduction variance. This capability is expanding into subscription-linked hardware refresh programs that accelerate replacement cycles.
The EU Tobacco Products Directive's forthcoming track-and-trace serialization mandates will force supply chain visibility investments across all nicotine-containing product categories. Manufacturers must integrate unique identifier systems from production through point-of-sale by implementation deadlines. Heated tobacco stick packaging bears the highest compliance burden given multi-stick carton configurations and cross-border distribution complexity.
Direct-to-consumer replenishment apps with auto-ship functionality are displacing traditional convenience store purchase patterns among urban adult users. British and American metropolitan markets show strongest platform adoption where delivery logistics density supports same-day cartridge fulfillment. Subscription bundling with device warranty extensions locks switching costs while generating predictable revenue streams.
Reduced-Risk Products (Rrps) Market Segmentation
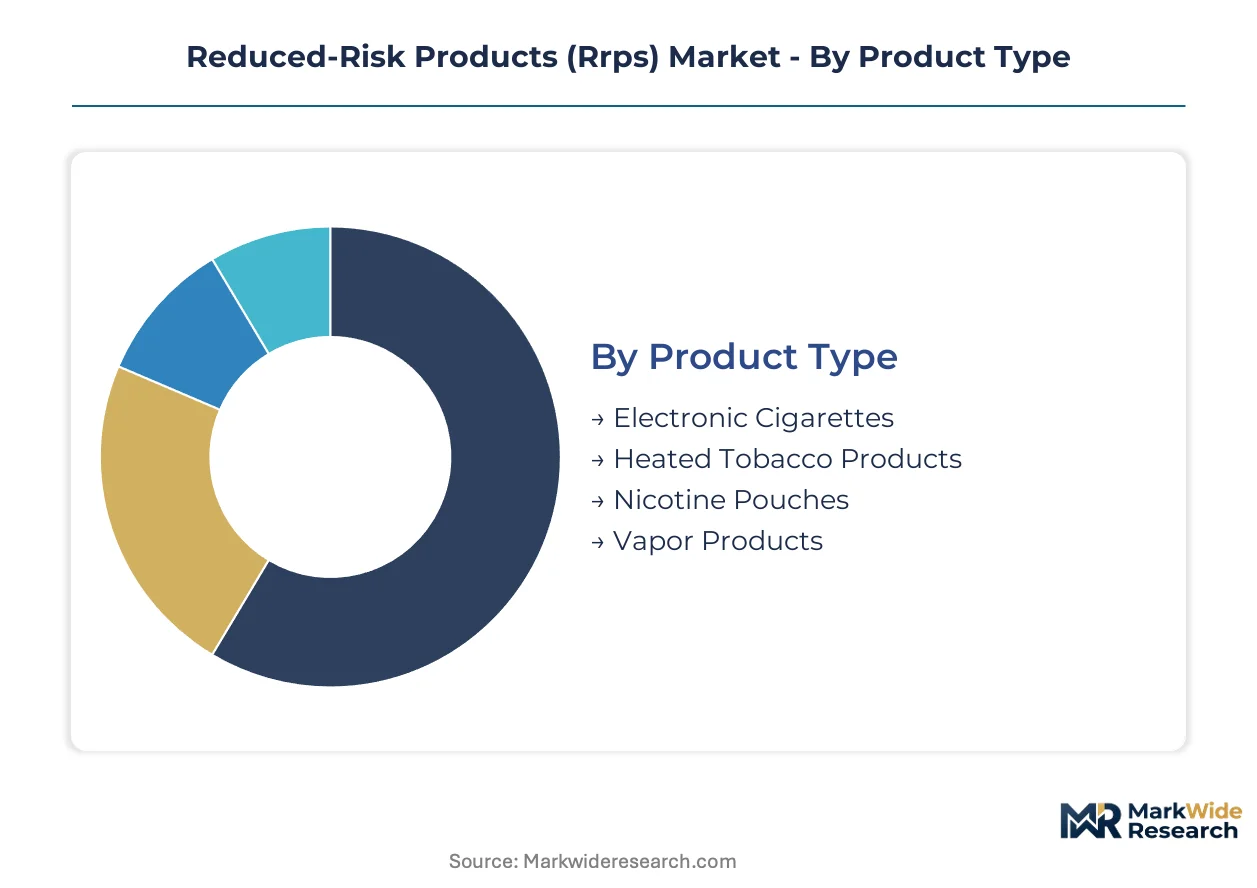
Segmentation in reduced-risk products determines margin architecture, regulatory pathway selection, and channel investment priorities. Distinct consumer cohorts exhibit sharply different price elasticity, flavor preferences, and device complexity tolerance.
Product Type:
Purchase decisions hinge on perceived harm reduction credibility versus convenience trade-offs, with thermal operating parameters and aerosol chemistry driving differentiation.
- Heated Tobacco Products:These systems heat processed tobacco sticks to temperatures below 350°C, generating nicotine-containing aerosol without combustion. Demand concentrates in Japan and Italy, where established smoker populations prioritize sensory fidelity to combustible cigarettes and accept premium hardware pricing.
- Nicotine Pouches:Oral delivery formats containing synthetic or tobacco-derived nicotine in cellulose matrices enable completely smoke-free consumption. Health-conscious consumers in Sweden and the United Kingdom are expanding most quickly into this category, drawn by discrete usage and zero residual odor.
- Electronic Cigarettes:Battery-powered devices vaporize propylene glycol and vegetable glycerin solutions with added nicotine.
- Vapor Products:Encompassing both open-tank and closed-system designs, these span disposable formats through modular pod architectures.
Heated Tobacco Products lead on scale; Nicotine Pouches lead on momentum.
Application:
User archetypes shape product positioning, with switching motivation and nicotine dependence history determining format suitability and lifetime value potential.
- Smokers:Adult combustible cigarette users seeking reduced toxicant exposure without cessation represent the core addressable population. These buyers demand nicotine satisfaction parity and familiar ritual elements, concentrating demand in the United States, Japan, and Germany where switching incentives align with regulatory pressure on traditional tobacco.
- Health-Conscious Consumers:Individuals prioritizing wellness optimization over nicotine maintenance exhibit strongest affinity for nicotine pouches and low-temperature vapor systems. This cohort expands most quickly in Scandinavian markets and British urban centers, where smoke-free workplace norms and fitness culture intersect.
- Vapor Enthusiasts:Hobbyist users pursuing flavor complexity, device customization, and cloud production volume.
- New Users:First-time nicotine adopters without prior tobacco exposure, predominantly young adults in permissive regulatory environments.
Smokers anchor revenue concentration; Health-Conscious Consumers are gaining share fastest.
Distribution Channel:
Channel selection determines customer acquisition cost, replenishment frequency, and regulatory exposure, with age verification infrastructure and excise tax collection obligations varying sharply by format.
- Convenience Stores:High-frequency impulse purchase locations dominate heated tobacco stick and pod cartridge replenishment in Japan and South Korea, where dense urban networks support immediate gratification demand. These outlets face mounting flavor restriction compliance burdens and track-and-trace serialization requirements under EU Tobacco Products Directive mandates.
- Online Retailers:Direct-to-consumer platforms with auto-ship functionality are displacing traditional purchase patterns in British and American metropolitan markets. Same-day delivery logistics density supports subscription bundling that locks switching costs while generating predictable revenue streams.
- Specialty Shops:Dedicated vape retailers with consultative service models and flavor sampling capabilities.
- Supermarkets:Mass retail channels with limited SKU breadth but maximum geographic penetration.
Convenience Stores dominate transaction volume; Online Retailers show steepest expansion trajectory.
Regulatory Compliance:
Authorization status functions as market access gating, with multi-year approval timelines and substantial compliance costs creating incumbent protection and freezing non-compliant competitors.
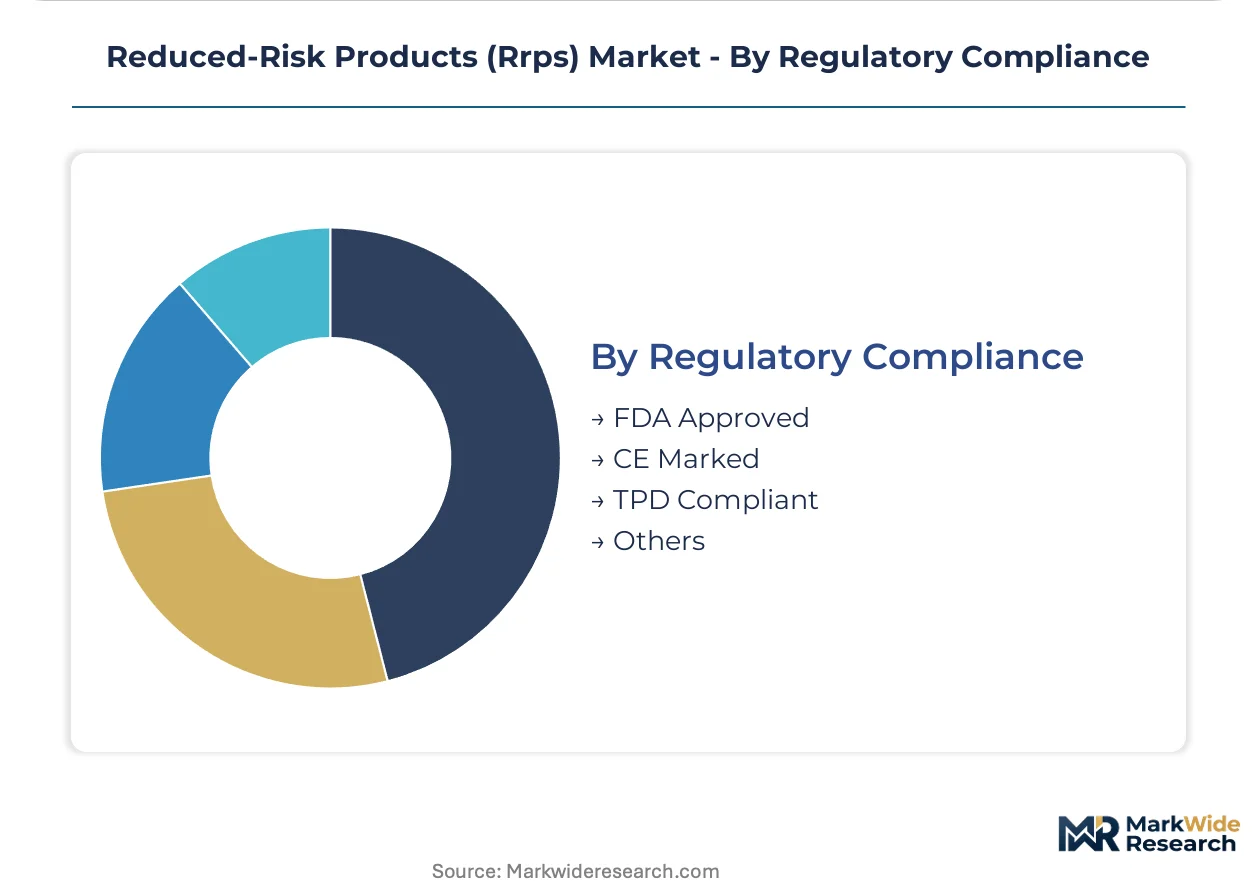
- FDA Approved:Premarket tobacco product application authorization enables legal United States market entry, with IQOS and select vapor products holding marketing granted orders. The pathway imposes multi-year timelines and substantial evidence generation costs that advantage firms with existing aerosol toxicology capabilities and clinical study infrastructure.
- TPD Compliant:EU Tobacco Products Directive adherence governs European Economic Area access, encompassing nicotine concentration limits, packaging health warnings, and cross-border notification requirements. Harmonization measures under revision may standardize marketing rules, reducing fragmentation costs for multi-market operators.
- CE Marked:Conformity with European health, safety, and environmental protection standards for electrical device components.
- Others:National-specific authorizations including Japan's Ministry of Health, Labour and Welfare constituent limits and Swissmedic registrations.
FDA Approved commands premium pricing power; TPD Compliant enables broadest geographic reach.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Heated tobacco products first achieved commercial scale in Japan during the mid-2010s, establishing regulatory templates and consumer acceptance patterns that subsequently diffused to European and North American markets. The industry's geographic footprint now concentrates in jurisdictions with mature tobacco control frameworks and established harm-reduction policy discourses.
United States
Adult smoker switching demand concentrates in coastal metropolitan corridors, with FDA premarket tobacco product application authorizations determining legal market access. The agency's marketing granted orders for select heated tobacco and vapor products create incumbent advantages through multi-year approval timelines. Device replenishment infrastructure clusters around Chicago, Los Angeles, and New York metro areas where same-day delivery logistics support subscription-based auto-ship models.
Japan
The Ministry of Health, Labour and Welfare's residual harmful constituent thresholds filter product candidates through quality barriers that elevate compliant premiums. Tokyo and Osaka metropolitan areas host the densest heated tobacco retail networks globally, with convenience store penetration exceeding combustible cigarette distribution points in several prefectures. Domestic manufacturers maintain aggressive R&D spending on next-generation aerosol technologies from Kansai-based research facilities.
Germany
EU Tobacco Products Directive harmonization measures reduce cross-border fragmentation costs for multi-market operators distributing from Frankfurt and Hamburg logistics hubs. The country's pharmacy channel integration offers smoking cessation counseling infrastructure as a credibility-enhancing distribution vector distinct from traditional tobacco retail. Bavaria and North Rhine-Westphalia exhibit strongest nicotine pouch adoption among health-conscious consumer cohorts.
United Kingdom
Smoke-free workplace norms and fitness culture intersect in London and Manchester urban centers, driving discrete consumption format demand. British American Tobacco competes through its glo device ecosystem and broad vapor portfolio from research facilities in Southampton. Online retail platforms with auto-ship functionality displace traditional convenience store purchase patterns most rapidly in this market.
Italy
Established smoker populations in Lombardy and Lazio prioritize sensory fidelity to combustible cigarettes and accept premium hardware pricing for heated tobacco systems. Milan anchors the southern European device replenishment infrastructure, with cross-border distribution complexity from multi-stick carton configurations creating compliance concentration. The country's retail pharmacy networks remain underexploited relative to British and German equivalents.
Reduced-Risk Products (Rrps) Market Competitive Landscape
Premium-margin players sit above commodity-margin players across regulatory authorization status and proprietary pod ecosystem control. The vendor base concentrates around three strategic archetypes: multinational tobacco incumbents with clinical study infrastructure, specialized vapor device manufacturers, and emerging nicotine pouch specialists. Dominant competitive moves include portfolio diversification across delivery formats and geographic expansion through harmonized regulatory approvals.
Within the multinational incumbent tier, Philip Morris International and British American Tobacco exemplify archetype positioning through integrated device-consumable platforms. Japan Tobacco International occupies a position representing home-market dominance combined with aggressive aerosol technology investment. KT&G and Swedish Match sit within specialized regional specialist and oral nicotine categories respectively, anchoring competitive diversity beyond integrated heated tobacco systems.
| Leading Market Players |
|---|
| Philip Morris International |
| British American Tobacco |
| Japan Tobacco International |
| Altria Group |
| Imperial Brands |
| KT&G |
| Swedish Match |
| Reynolds American |
| Juul Labs |
| Others |
Pricing and Supply Chain Analysis
Adult smokers seeking harm reduction anchor demand concentration in the United States, Japan, and Germany, locking the market into recurring-consumable pricing models where proprietary pod ecosystems capture margin through subscription bundling rather than hardware transactions.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels segments the market by device sophistication and consumable bundling intensity. FDA authorization status and CE marking tier create price differentiation between compliant and non-compliant product lines. Cost compression in economy vapor segments intensifies as open-tank alternatives commoditize, while heated tobacco maintains pricing power through tobacco sheet quality premiums. Health-conscious consumers in Scandinavian markets exhibit lowest price sensitivity, whereas price-elastic vapor enthusiasts drive erosion in generic refillable categories.
Supply Chain Analysis
Device refurbishment and trade-in programs for IQOS and glo hardware create reverse-logistics flows that extend customer lifetime value while recovering precision heating elements for remanufacturing. Specialized tobacco sheet manufacturing concentrates in Japan and South Korea, with precision heating element fabrication anchored in East Asian electronics corridors. Supply chain risk hinges on single-source vulnerability for ceramic heating blades and controlled-release polymer matrices. Distribution runs through convenience store networks in Tokyo and Osaka, with direct-to-consumer auto-ship platforms gaining share in London and New York metropolitan corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The reduced-risk products market functions as a stable compounder, with adult smoker switching demand providing durable recurring revenue streams that resist macroeconomic volatility.
For Market Incumbents: Acquire aerosol toxicology laboratories and clinical study infrastructure to defend FDA premarket authorization moats against emerging nicotine pouch specialists. Expand backward integration into tobacco sheet manufacturing to secure input quality against East Asian supply concentration risks. For New Entrants and Emerging Players: Direct-to-consumer subscription platforms offer the lowest customer acquisition cost route into British and American metropolitan markets where same-day delivery density supports auto-ship adoption. Target pharmacy channel partnerships in Germany and the United Kingdom where smoking cessation counseling infrastructure remains underexploited relative to traditional tobacco retail. For Investors and Strategic Acquirers: Multinational tobacco conglomerates are the most active acquirers in this space, seeking oral nicotine specialists with Scandinavian regulatory heritage and geographic expansion capability. Over a multi-year horizon, portfolio diversification across heated tobacco, vapor, and pouch formats signals resilient positioning. Monitor FDA marketing granted order issuance velocity as the inflection indicator for competitive access dynamics.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Authorization Investment | FDA premarket tobacco product applications and EU TPD compliance create incumbent-protected market access. |
| Proprietary Pod Ecosystem Development | Closed-system architectures lock consumers into recurring consumable purchases with higher lifetime value. |
| Aerosol Science Talent Acquisition | Inhalation toxicologists and aerosol physicists generate publication-grade reduced-exposure evidence for regulatory submissions. |
| Pharmacy Channel Partnership | German and British retail pharmacy networks offer credibility-enhancing distribution distinct from tobacco retail. |
| Geographic Expansion Through Harmonization | EU Tobacco Products Directive revision reduces fragmentation costs for multi-market operators. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with regulatory affairs directors at multinational tobacco firms, aerosol R&D scientists, pharmacy channel procurement managers, and convenience store category buyers with secondary validation against FDA marketing granted order databases, EU TPD notification registers, and Japanese Ministry of Health constituent limit filings. Bottom-up product-level volume builds and top-down market sizing triangulated across the analysis window.
Historical reference periods anchored the forecast window to pre-authorization and post-authorization market phases across the projection horizon. Segmentation dimensions modeled include product type, user archetype, distribution channel, and regulatory compliance tier. CAGRs derived from regression analysis of switching rates, pricing elasticity by segment, and replenishment frequency patterns. Industry-specific inputs incorporated FDA review timeline distributions and EU flavor restriction implementation schedules.
Regulatory reclassification, taxation parity legislation, and aerosol science talent scarcity are the dominant revision risks that could compress growth trajectories or accelerate competitive consolidation. Forecasts reflect assumptions about authorization pathway efficiency and consumer switching persistence. Practitioners should monitor FDA marketing granted order backlogs and EU TPD revision implementation timelines for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Deep Sea Mining Market
Others
Industrial PC Market
Others
Gym Wipes Market
Others
Bitcoin Mining Hardware Market
Others
Heavy Duty Traps Market
Others
Remanufacturing-as-a-Service (RaaS) Market
Others
Global Phablets and Superphones Market
Others
GCC Cigarette Market
Others
Latin America Fire Sprinklers Market
Others
Pet Care Packaging Market
Others
US Legal Services Market
Others
Italy Automotive Adaptive Lighting System Market
Others
Cloud Advertising Market
Others
Latin America IT Device Market
Others
North America Astrology Market
Others
Ambient Assisted Living and Smart Home Market