
 Butane Market | 2026-2036
Butane Market Size, Share, and Industry Trends Forecast 2026-2036
Butane Market Intelligence
The ISO 9001 quality management standard is bifurcating the supplier landscape between certified, large-scale producers and smaller, regional players. This creates a clear distinction in market access for critical applications. Global energy majors like Shell plc leverage their extensive refining capacity and logistics networks to serve high-volume contracts. Meanwhile, TotalEnergies differentiates through its integrated petrochemical value chain, turning butane into higher-value derivative products.
Butane is a highly flammable, colorless hydrocarbon gas with the chemical formula C4H10. It exists as two isomers, normal butane (n-butane) and isobutane, which possess distinct physical properties influencing their end-use suitability. The market for petrochemical feedstock represents the fastest-growing application, driven by its use in producing ethylene and propylene. In contrast, the gasoline blending segment, which utilizes normal butane to increase octane and vapor pressure, remains a mature and high-volume, but slower-growing, category.
Regulations from bodies like the US Environmental Protection Agency (EPA) govern emissions and handling protocols for butane as a volatile organic compound. The European Union's REACH framework imposes stringent registration and evaluation requirements on chemical substances, impacting market access. These rules directly shape product specifications for applications like aerosol propellants. Future profitability hinges on navigating the divergent regulatory pressures on butane's use as both a clean-burning fuel and a controlled chemical feedstock.
Market Dynamics
The central force shaping the market is the divergent value creation between butane as a bulk fuel component and as a specialized petrochemical feedstock. This split drives separate investment patterns, supply chain configurations, and pricing mechanisms for n-butane versus isobutane.
Growth Catalysts
- Petrochemical Feedstock Demand:Massive investment in dehydrogenation plants, particularly in China, to produce propylene and butadiene from butane is creating substantial, long-term demand for specific butane isomers as a primary raw material.
- Refrigerant Regulation:The European Union's F-Gas Regulation compels a shift away from high-GWP HFCs, directly boosting demand for high-purity isobutane (R-600a) as an alternative refrigerant in domestic and light commercial applications.
- Clean Cooking Initiatives:Government subsidies and infrastructure programs in nations like India and Indonesia to expand access to LPG for household cooking create a consistent, high-volume demand floor for butane.
Market Restraints
- Feedstock Price Volatility:Butane pricing is directly linked to fluctuating natural gas and crude oil markets, exposing downstream chemical producers and fuel blenders to significant input cost uncertainty and margin compression.
- Substitution from Propane:In the critical LPG market for heating and cooking, propane offers superior performance in colder climates and is a direct competitor, limiting butane's market share in certain geographies.
- Infrastructure Investment Hurdles:The requirement for specialized pressurized storage and transportation assets, such as pipelines and refrigerated tankers, represents a high capital barrier to entry and limits logistical flexibility.
Strategic Opportunities
- Bio-Butane Development:The production of butane from renewable sources like biomass or waste presents an opportunity to develop drop-in, low-carbon fuels and chemical feedstocks that meet corporate and national decarbonization goals.
- High-Purity Isobutane Expansion:Beyond refrigeration, opportunities exist for high-purity isobutane as a feedstock for producing isooctane, a high-value gasoline additive that enhances engine performance and efficiency.
- Aerosol Formulation Transition:As regulations tighten on volatile organic compounds and propellants, butane offers a cost-effective, low-GWP alternative to traditional aerosol propellants in consumer and industrial goods.
Industry Challenges
- Stringent Emissions Compliance:Adhering to strict protocols for handling butane as a volatile organic compound, mandated by regulators like the US EPA, requires ongoing investment in leak detection, vapor recovery, and monitoring systems.
- Isomer Separation Complexity:The energy-intensive fractionation process required to separate n-butane and isobutane to meet specific end-use purity specifications constitutes a major operational challenge and cost center for producers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Butane Market |
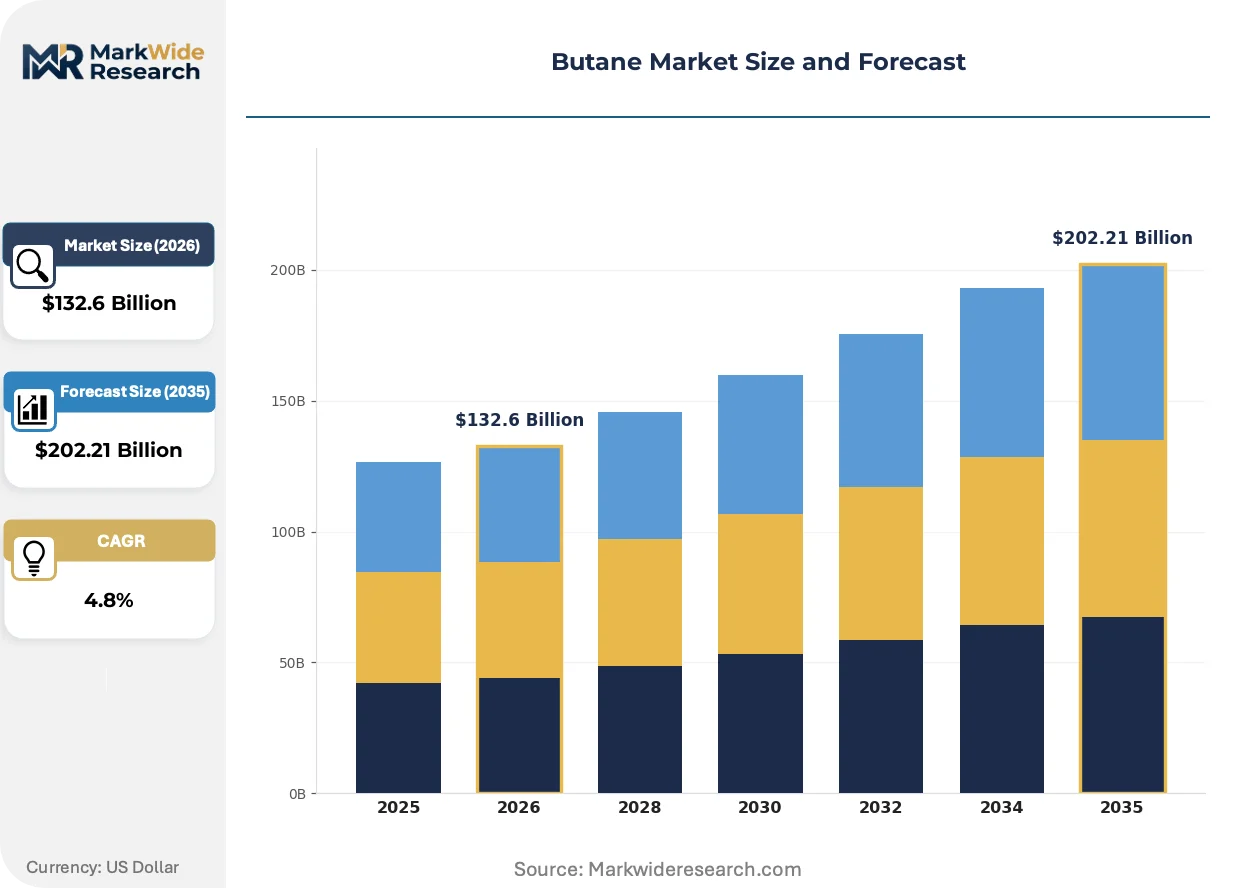
| Market Size in 2026 | $132.6 Billion |
| Market Size in 2035 | $202.21 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Isobutane, Normal Butane, Mixed Butane, Recycled Butane Application: Refrigerants, Aerosol Propellants, Portable Fuel, Petrochemical Feedstock, Gasoline Blending End User: Household Consumers, Industrial Manufacturers, Commercial Kitchens, Energy Producers, Laboratories Packaging Type: Liquefied Gas Cylinders, Bulk Storage Tanks, Disposable Canisters, Refillable Bottles, High-Pressure Containers |
| Companies Covered | Shell plc, TotalEnergies, Exxon Mobil Corporation, Chevron Corporation, China National Petroleum Corporation, Saudi Arabian Oil Company, British Petroleum, ConocoPhillips, China Petroleum & Chemical Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Butane Market Strategic Shifts & Innovations
The market is evolving along two distinct paths, creating separate value chains for butane as a high-volume fuel commodity versus a specialized, on-purpose chemical intermediate. This bifurcation influences technology investment, supply agreements, and regional pricing differentials.
On-purpose production technologies, specifically butane dehydrogenation (BDH), enable the direct conversion of butane into high-value chemical building blocks like butadiene. Petrochemical manufacturers, especially in China and the US Gulf Coast, are investing heavily in BDH units to gain control over their feedstock supply. This on-purpose production is fragmenting the historical market structure where butane was sourced primarily as a byproduct from oil refining.
The European Union's REACH framework imposes stringent registration and evaluation duties on all chemical substances, directly influencing market access and product formulation. This regulation forces producers and importers to generate extensive safety data, which acts as a non-tariff barrier. The aerosol propellant and specialty chemical segments are most affected, as compliance costs shape formulation choices and supplier selection.
A shift in procurement models sees large-scale petrochemical consumers moving away from spot market purchases toward long-term offtake agreements and dedicated pipeline supply. This model displaces the role of traditional distributors for high-volume contracts, securing feedstock predictability for new cracker and dehydrogenation projects. This pattern is most visible in integrated chemical production hubs in Texas and Shandong province, China.
Butane Market Segmentation
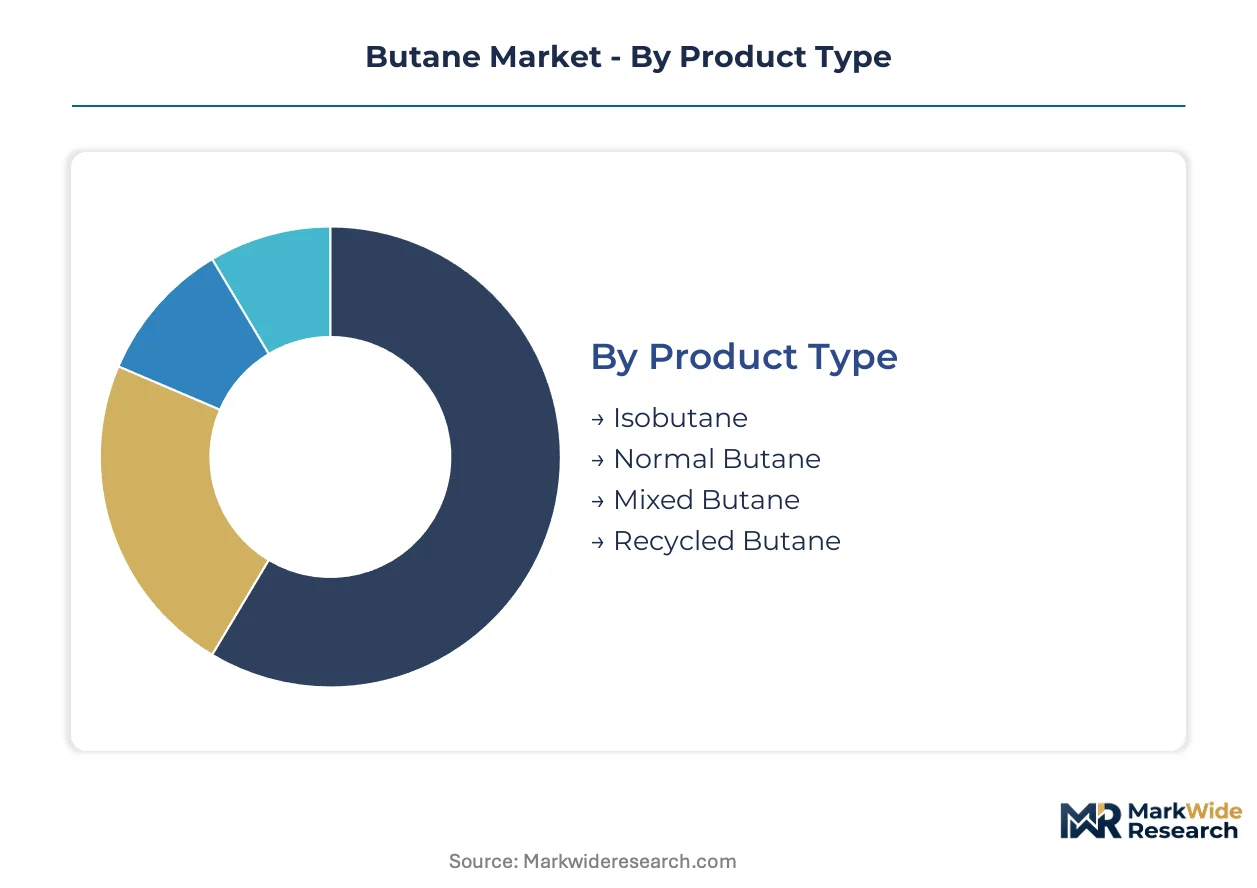
The Butane market's multifaceted nature necessitates a granular segmentation analysis to understand its diverse value streams. Product type, application, end-user, and packaging variations significantly influence demand patterns and competitive dynamics. This segmentation illuminates distinct market opportunities and operational complexities across the industry.
Product Type:
Margin pools within the product type category are increasingly concentrated in specialized, high-purity isomers and sustainably sourced options.
- Isobutane:This isomer, also known as 2-methylpropane, features a branched chemical structure, making it suitable for specific chemical reactions and as a refrigerant. Demand is concentrating in Europe for R-600a applications due to the F-Gas Regulation, driving its adoption in domestic and light commercial refrigeration.
- Normal Butane:A straight-chain hydrocarbon, n-butane is a primary component of LPG and a crucial feedstock for petrochemicals. High-volume consumption occurs in China's burgeoning dehydrogenation plants for butadiene production, underpinning its role in synthetic rubber manufacturing.
- Mixed Butane:This blend of n-butane and isobutane is commonly used in LPG for heating and cooking, particularly in regions like India and Indonesia.
- Recycled Butane:Butane recovered from industrial processes or waste streams offers a circular economy solution, appealing to producers aiming for lower carbon footprints.
The dominant share belongs to Normal Butane due to its bulk fuel and petrochemical uses, while Isobutane is closing the gap fastest driven by its specialized applications.
Application:
Applications for butane span a spectrum from high-volume commodity uses to niche, value-added chemical processes.
- Petrochemical Feedstock:Butane serves as a critical raw material for producing base chemicals like ethylene, propylene, and butadiene through processes such as dehydrogenation. Investments in China's chemical production infrastructure are driving substantial, long-term demand for this application.
- Gasoline Blending:Normal butane increases octane levels and vapor pressure in motor gasoline, improving engine performance and cold-weather starting. This mature application represents a significant volume segment in the US market, particularly during winter months.
- Refrigerants:Isobutane (R-600a) provides an environmentally friendly alternative to HFCs in domestic and light commercial refrigeration systems.
- Aerosol Propellants:Butane acts as a cost-effective, low-GWP propellant in various consumer and industrial aerosol products, replacing traditional alternatives.
- Portable Fuel:Disposable canisters containing butane power portable stoves and lighters, catering to outdoor recreational activities and household needs.
Volume concentration remains highest in gasoline blending, but petrochemical feedstock applications are expanding most quickly.
End User:
Demand drivers for butane vary significantly across end-user segments, reflecting diverse operational needs and regulatory landscapes.
- Industrial Manufacturers:This segment encompasses chemical producers utilizing butane as a feedstock, as well as manufacturers incorporating it into aerosol products or specialized fuels. Major chemical hubs in the US Gulf Coast and China represent significant industrial consumption centers.
- Household Consumers:Primarily consume butane as LPG for cooking and heating, especially in developing economies, and in smaller quantities for portable fuel canisters. Government initiatives in India subsidize LPG access, directly impacting household demand.
- Commercial Kitchens:Utilize butane in LPG blends for cooking and heating applications, particularly in regions with limited access to natural gas pipelines.
- Energy Producers:Employ butane as a fuel source for power generation or as a component in natural gas processing, contributing to broader energy supply chains.
- Laboratories:Require high-purity butane for research, calibration, and specialized analytical applications, demanding stringent quality specifications.
Household consumers represent a stable demand base, while industrial manufacturers are driving significant new growth areas.
Packaging Type:
Logistical considerations and safety requirements heavily influence the choice of packaging type for butane across its varied applications.
- Bulk Storage Tanks:Large-scale storage facilities, often integrated with petrochemical plants or import terminals, handle massive volumes of butane for industrial feedstock or regional distribution. These tanks require specialized infrastructure and adherence to stringent safety regulations.
- Liquefied Gas Cylinders:These pressurized steel cylinders are widely used for distributing LPG to household consumers and commercial kitchens, especially in regions lacking extensive pipeline networks. Their portability and standardized sizes facilitate broad market access.
- Disposable Canisters:Small, non-refillable butane canisters cater to portable stoves, lighters, and camping equipment, offering convenience for recreational users.
- Refillable Bottles:These smaller, reusable containers serve as a more sustainable option for portable fuel and some specialized applications, reducing waste.
- High-Pressure Containers:Designed for specific industrial or laboratory applications requiring ultra-high purity butane or specialized handling conditions.
Bulk storage tanks offer the highest efficiency for large-scale industrial use, while liquefied gas cylinders ensure widespread distribution to diverse end-users.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Player mix skews toward industrial manufacturers and household consumers, driving distinct regional demand patterns for butane. Industrial consumption concentrates in major chemical production hubs, while household demand is fueled by clean cooking initiatives in developing economies. This bifurcation influences supply chain configurations and investment flows across key geographies.
China
China's demand for butane as a petrochemical feedstock is substantial, driven by massive investments in dehydrogenation plants. The country's dual carbon goals also encourage cleaner fuel and feedstock options in industrial applications. Integrated chemical production hubs in Shandong province are central to butadiene and other derivative product manufacturing.
India
India's household consumers represent a consistent, high-volume demand floor for butane, primarily for LPG cooking. Government subsidies and infrastructure programs expand access to LPG across the nation. Major urban centers and rural distribution networks facilitate widespread butane consumption for domestic applications.
United States
United States demand concentrates in gasoline blending during winter months and as a critical petrochemical feedstock. The US EPA regulations govern emissions and handling protocols for butane as a volatile organic compound. Texas, particularly the US Gulf Coast, serves as a significant industrial consumption center for refining and chemical production.
Germany
Germany's market for butane is shaped by the European Union's F-Gas Regulation, boosting demand for high-purity isobutane as a refrigerant. The REACH framework imposes stringent registration requirements on chemical substances, impacting product specifications. Chemical parks in regions like North Rhine-Westphalia are adapting formulations for aerosol propellants and specialty chemicals.
Saudi Arabia
Saudi Arabia utilizes butane extensively as a petrochemical feedstock, supporting its national industrialization strategies for economic diversification. Its large-scale refining capacity generates significant butane volumes for domestic processing and export. Jubail Industrial City hosts massive petrochemical complexes that convert butane into higher-value chemical derivatives.
Butane Market Key Industry Players
Player mix skews toward large-scale integrated energy majors and specialized petrochemical producers, alongside smaller, regional distributors. The supplier landscape bifurcates between ISO 9001 certified producers and those operating regionally for less critical applications. Strategic archetypes include global energy companies with extensive refining capacity and petrochemical firms focused on value chain integration. Capacity expansion in dehydrogenation plants and securing long-term offtake agreements are dominant competitive moves.
At the scale-driven end, Shell plc and Exxon Mobil Corporation exemplify global energy majors leveraging extensive refining capacity and logistics networks. These companies occupy a position to serve high-volume contracts for both bulk fuel components and critical petrochemical feedstock. Their operational scale and logistical reach are fundamental to their market presence. TotalEnergies represents another integrated player, differentiating through its comprehensive petrochemical value chain by transforming butane into higher-value derivative products and securing captive supply. This strategic integration allows for optimized production and market responsiveness across diverse applications.
| Leading Market Players |
|---|
| Shell plc |
| TotalEnergies |
| Exxon Mobil Corporation |
| Chevron Corporation |
| China National Petroleum Corporation |
| Saudi Arabian Oil Company |
| British Petroleum |
| ConocoPhillips |
| China Petroleum & Chemical Corporation |
| Others |
Cost & Logistics Intelligence
Typical inventory levels for butane in industrial storage facilities hover around 30-45 days, reflecting the interplay between large-scale refining capacity and predictable long-term contracts shaping regional pricing power.
Pricing Analysis
Cost-plus contract structures, often indexed to crude oil or natural gas benchmarks, govern a significant portion of bulk butane transactions. Price differentiation stems from purity specifications for isobutane applications and the logistical costs associated with regional delivery. Pricing softness currently affects the gasoline blending segment due to shifting fuel demand patterns. Industrial manufacturers procuring high-purity petrochemical feedstock demonstrate the least price sensitivity, valuing consistent supply and stringent quality.
Supply Chain Analysis
Strategic stockpiling of butane is prevalent in major consumption hubs, particularly for LPG distribution, counterbalancing just-in-time practices for specialized petrochemical feedstocks. Supply concentration centers on Saudi Arabia, the United States, and China, leveraging their extensive refining and chemical production capacities. The market relies on natural gas liquids and crude oil as primary raw material inputs. Logistics chokepoints, especially for refrigerated marine transport, represent a structural risk, while distribution runs through a mix of integrated producer networks and regional distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The butane market requires a robust substitution defense as players navigate the growing threat from propane in critical LPG applications. Incumbents must strategically position their offerings to retain market share against this potent alternative.
For Market Incumbents: Fortify existing market positions by investing in advanced fractionation technologies to produce high-purity isobutane, meeting stringent F-Gas Regulation demands. Secure long-term offtake agreements with petrochemical manufacturers in China to guarantee volume predictability against feedstock price volatility. Pursue backward integration into natural gas processing to gain upstream control over supply, mitigating commodity price exposure. Prioritize ISO 9001 certification across all production facilities to maintain market access for critical applications.
For New Entrants and Emerging Players: Differentiate on sustainable sourcing by developing bio-butane production capabilities from biomass or waste streams. Target niche applications requiring low-carbon footprint solutions, such as specialized aerosol propellants or sustainable chemical feedstocks. Focus on the European Union market, where REACH regulations and F-Gas mandates create demand for compliant, environmentally preferred options. A go-to-market angle emphasizing environmental certifications and lifecycle assessments can attract discerning industrial buyers.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upwards across the petrochemical feedstock segment, driven by significant investment in dehydrogenation plants. Long-term viability over a five-to-ten-year window favors integrated players with captive feedstock supply and diversified end-use applications. Acquisition targets should include mid-sized producers with proprietary isomer separation technologies or strong regional distribution networks. The expansion rate of bio-butane production capacity serves as a key signal to watch for future market disruption.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Expanding dehydrogenation plant capacity in China ensures feedstock security for butadiene production. |
| Backward Integration | Gaining upstream control over natural gas liquids supply mitigates butane price volatility for refiners. |
| Green Manufacturing Transition | Developing bio-butane production from biomass aligns with corporate decarbonization goals and EU regulations. |
| Long-term Supply Agreement | Securing long-term offtake agreements with industrial manufacturers stabilizes revenue streams for producers. |
| Joint Venture | Partnering on specialized isomer separation technology improves efficiency and purity for R-600a applications. |
Research Approach
A standing panel of chemical engineers, procurement leads, logistics managers, and regulatory affairs specialists provided ongoing calibration for market assumptions. This involved combining primary interviews with industry stakeholders and validating insights against secondary data sources. Customs and trade data, petrochemical association reports, and environmental agency filings informed the analysis. Bottom-up and top-down triangulation ensured robust data integrity across all segments.
Forecast outputs underwent rigorous consistency checks against external industry benchmarks and historical market performance across the analysis window. Segmentation dimensions modeled included product type, application, end-user, and regional consumption patterns. Compound annual growth rates were derived through a robust regression analysis of historical data and projected demand drivers. Key forecast inputs included planned petrochemical capacity additions and regional LPG consumption trends.
Forecasts assume regulatory continuity in European F-Gas and US EPA regimes; material policy shifts would require re-modeling. Geopolitical events impacting crude oil and natural gas supply chains represent specific risk factors that could revise projections. Revision becomes warranted when feedstock price volatility exceeds historical thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solvents
Benzylamine Market
Solvents
Lithium-Ion Battery's Electrolyte Solvent Market
Solvents
Fluorinated Solvents Market
Solvents
Butyl Glycol Market
Solvents
Mixed Xylene Market
Solvents
Aliphatic Hydrocarbon Solvents and Thinners Market
Solvents
Global Chloroform Market
Solvents
Phenylacetonitrile Market
Solvents
Organic Solvents Market
Solvents
Dimethyl Sulfoxide Market
Solvents
Methyl Diethanolamine Market
Solvents
Oxygenated Solvents Market
Solvents
Benzene and Its Derivatives Market
Solvents
Global Ink Solvents Market
Solvents
Asia-Pacific Ethane Market
Solvents
Aliphatic Solvents Market