
 Global Next Generation Anode Materials Market | 2026-2036
Global Next Generation Anode Materials Market Size, Share, and Industry Trends Forecast 2026-2036
Global Next Generation Anode Materials Market Foresight
The capital-intensity divergence between thin-film deposition specialists and conventional graphite producers is unwinding competitive boundaries in anode supply chains. Sila Nanotechnologies leverages solid-state silicon composite architectures to sustain technology leadership in high-energy cell designs. Amprius Technologies anchors its position through silicon nanowire manufacturing scale, while POSCO Chemical dominates integrated precursor-to-anode production from South Korea's industrial base.
Next generation anode materials encompass engineered active substances—silicon composites, graphene architectures, lithium titanate spinels, and hard carbon matrices—that replace or supplement conventional graphite to achieve specific capacities exceeding 1000 mAh/g in lithium-ion cells. Manufacturing routes span chemical vapor deposition, mechanical milling, and solution-phase nano-structuring to control particle expansion and solid-electrolyte interphase stability. Silicon-based formulations command the dominant margin pool as automotive cell contracts specify 400 Wh/kg pack targets, while graphene-based variants occupy premium aerospace niches where cycle life thresholds exceed 2000 cycles. Hard Carbon segments compete on cost in grid storage applications where energy density trades off against calendar life requirements.
EU Battery Regulation mandates drive recyclability and carbon footprint disclosure requirements that reshape material qualification timelines for suppliers targeting European automotive OEMs. China's GB standards and NMPA cell certification protocols enforce domestic testing regimes that filter market access for foreign anode producers. Japan's METI coordinates national solid-state battery roadmaps that specify silicon anode compatibility thresholds. Stakeholders must monitor regulatory divergence between jurisdictions to align R&D pipelines with divergent certification requirements rather than assuming harmonized standards.
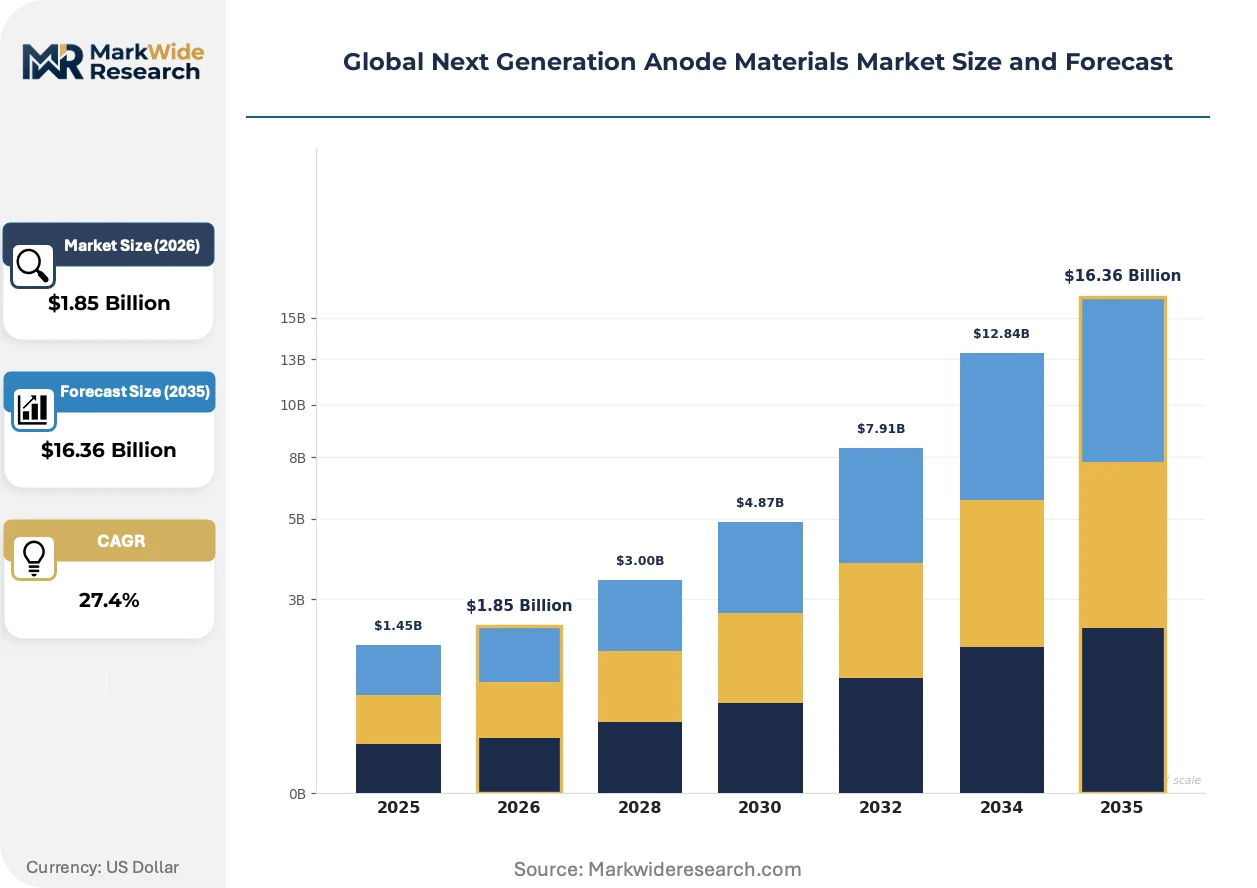
Market Dynamics
Silicon-dominant anode formulations are compressing qualification timelines as automotive cell contracts harden around 400 Wh/kg pack specifications, forcing material suppliers to accelerate pilot-to-production scale transitions.
Growth Catalysts
- EU Battery Regulation sustainability mandates:Recyclability and carbon footprint disclosure requirements are tightening material qualification standards for suppliers targeting European automotive OEMs.
- Solid-state battery roadmaps:Japan's METI coordinates national programs specifying silicon anode compatibility thresholds that validate next-generation architectures.
- Silicon nanowire manufacturing:Advanced nano-structuring processes are enabling specific capacities exceeding 1000 mAh/g in commercial cell designs.
Market Restraints
- Precursor supply concentration:Metallurgical-grade silicon purification capacity clusters in China's industrial provinces, creating single-source vulnerability for Western anode producers.
- Particle expansion mechanics:Silicon's 300% volume change during lithiation cycles degrades solid-electrolyte interphase stability, limiting commercial cycle life below aerospace thresholds.
- GB standards filtering:China's NMPA certification protocols enforce domestic testing regimes that restrict market access for foreign anode material suppliers.
Strategic Opportunities
- India's PLI scheme for cell manufacturing:Production-linked incentives for advanced chemistry cell plants are creating first-mover advantages for anode material qualification partnerships.
- Grid storage hard carbon demand:Calendar life requirements in utility-scale installations favor cost-optimized hard carbon matrices over energy density-focused alternatives.
- Silicon-graphene composite convergence:Hybrid architectures combining high capacity with structural conductivity are opening premium aerospace applications requiring 2000+ cycle thresholds.
Industry Challenges
- Thin-film deposition talent scarcity:Chemical vapor deposition specialists command premium compensation as capital-intensity divergence unwinds competitive boundaries between conventional and advanced anode producers.
- Dual certification timeline compression:Suppliers must simultaneously satisfy EU Battery Regulation carbon disclosure and China's GB standards testing, stretching R&D bandwidth across divergent protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Next Generation Anode Materials Market |
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $16.36 Billion |
| CAGR (2026 – 2036) | 27.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Silicon-based, Graphene-based, Tin-based, Lithium Titanate, Carbon Nanotubes, Hard Carbon Technology: Coating, Doping, Composite, Nano-structuring, Binder Development, Electrolyte Compatibility Application: Electric Vehicles, Consumer Electronics, Aerospace Systems, Grid Storage, Wearables, Industrial Equipment End User: Battery Manufacturers, Electronics OEMs, Energy Storage Providers, Aerospace Contractors, Research Institutions, Automotive Tier-1s |
| Companies Covered | Sila Nanotechnologies Inc., Nexeon Ltd., Amprius Technologies, LeydenJar Technologies BV, Shanghai Shanshan Technology Co., Ltd., POSCO Chemical, Talga Group, Resonac Holdings Corporation, OneD Battery Sciences, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Next Generation Anode Materials Market Shifts & Advancements
Solid-state silicon composite architectures are redefining manufacturing investment priorities as deposition specialists capture margin pools previously held by mechanical milling operations.
Silicon-dominant composite anodes are displacing conventional graphite in premium automotive cell designs. Korean battery manufacturers are accelerating procurement of solid-state silicon formulations to meet tightening energy density specifications. This displacement is compressing the addressable market for uncoated natural graphite suppliers.
REACH substance authorization requirements are extending material qualification timelines for European automotive supply chains. The EU Green Deal's carbon border adjustment mechanisms are forcing anode producers to document embedded emissions across precursor extraction. Suppliers targeting Germany's KBA-certified cell plants are restructuring supply chains to satisfy dual regulatory frameworks.
Automotive OEMs are consolidating anode material procurement through direct long-term offtake agreements with deposition specialists. Tier-one cell manufacturers are bypassing traditional distributor channels to secure captive silicon composite supply. This concentration is most visible in South Korea's cathode-anode industrial cluster, where POSCO Chemical's integrated precursor-to-anode production anchors regional supply security.
Global Next Generation Anode Materials Market Segmentation
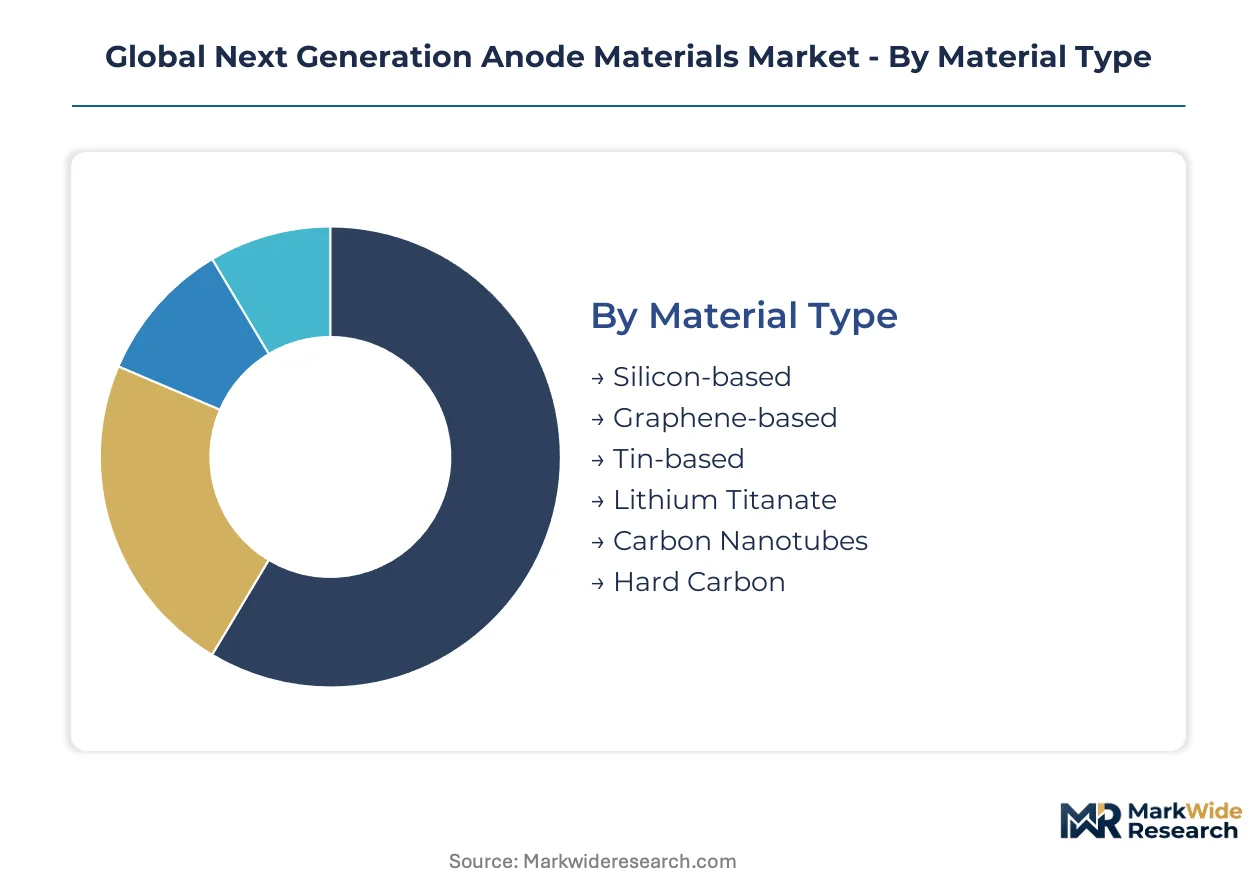
Segmentation reveals how qualification requirements diverge across material classes and end-use specifications. Procurement patterns in this market split between automotive cell contracts demanding silicon-dominant formulations and grid storage tenders favoring cost-optimized carbon architectures.
Material Type:
Domestic consumption clusters around silicon-based and hard carbon variants in South Korea and Japan, while graphene-based and tin-based segments serve export-led aerospace and specialty electronics demand from European and North American production bases.
- Silicon-based:Engineered composites and nanowire architectures deliver specific capacities exceeding 1000 mAh/g through controlled particle expansion management. Korean battery manufacturers concentrate procurement here to meet EU Battery Regulation energy density mandates for automotive cell supply.
- Graphene-based:Two-dimensional carbon lattices provide structural conductivity and cycle life stability exceeding 2000 cycles. Aerospace contractors in Germany and France anchor demand for satellite and aviation power systems where calendar life thresholds override cost sensitivity.
- Tin-based:Alloy formulations with cobalt or copper buffers address volume expansion challenges in niche medical device applications.
- Lithium Titanate:Spinel structures enable ultra-fast charging for electric bus fleets in China's municipal transit procurement.
- Carbon Nanotubes:Conductive additives enhance rate capability in premium consumer electronics cells from Japanese OEMs.
- Hard Carbon:Biomass-derived matrices compete on precursor cost for utility-scale grid storage installations in India and the United States.
Silicon-based formulations command the established base. The steepest expansion runs through hard carbon as India's PLI scheme accelerates domestic cell manufacturing qualification.
Technology:
Cost tiers separate deposition-intensive processes from mechanical milling operations, with nano-structuring and composite manufacturing commanding capital premiums that filter supplier participation.
- Coating:Surface modification techniques stabilize solid-electrolyte interphase formation through carbon or ceramic layers. Battery manufacturers in South Korea prioritize coated silicon particles to compress automotive qualification timelines under tightening OEM specifications.
- Nano-structuring:Silicon nanowire and porous architectures control lithiation-induced strain through geometric engineering. Amprius Technologies anchors manufacturing scale here, serving aerospace contractors requiring volumetric energy density above 450 Wh/l.
- Doping:Heteroatom insertion modifies electronic conductivity in graphite-silicon hybrid materials.
- Composite:Multi-phase architectures combine active materials with conductive matrices for mechanical resilience.
- Binder Development:Polymeric adhesion systems accommodate silicon expansion without electrode delamination.
- Electrolyte Compatibility:Formulation matching ensures stable cycling across temperature ranges for automotive Tier-1 validation.
Coating technology holds the volume base. Nano-structuring climbs the fastest as solid-state battery roadmaps from Japan's METI validate advanced architectures.
Application:
Customer type determines performance thresholds, with electric vehicles and aerospace systems specifying energy density floors that exclude conventional graphite, while grid storage and wearables trade density for cycle life or form factor flexibility.
- Electric Vehicles:Pack-level targets of 400 Wh/kg drive silicon-dominant anode procurement from Korean and Chinese cell manufacturers. EU Battery Regulation carbon disclosure requirements filter supplier qualification for European automotive OEM platforms.
- Grid Storage:Calendar life requirements exceeding 15 years favor hard carbon and lithium titanate formulations where degradation rates matter more than gravimetric density. Indian and American utility developers concentrate procurement here under cost-per-cycle optimization.
- Consumer Electronics:Smartphone and laptop manufacturers specify fast-charge capability with moderate cycle life.
- Aerospace Systems:Satellite and aviation applications demand radiation tolerance and extreme temperature operation.
- Wearables:Flexible cell architectures accommodate mechanical deformation in health monitoring devices.
- Industrial Equipment:Forklift and mining vehicle batteries prioritize safety and thermal stability.
Electric vehicles anchor the revenue base. Grid storage gains share fastest as renewable integration accelerates utility-scale battery procurement.
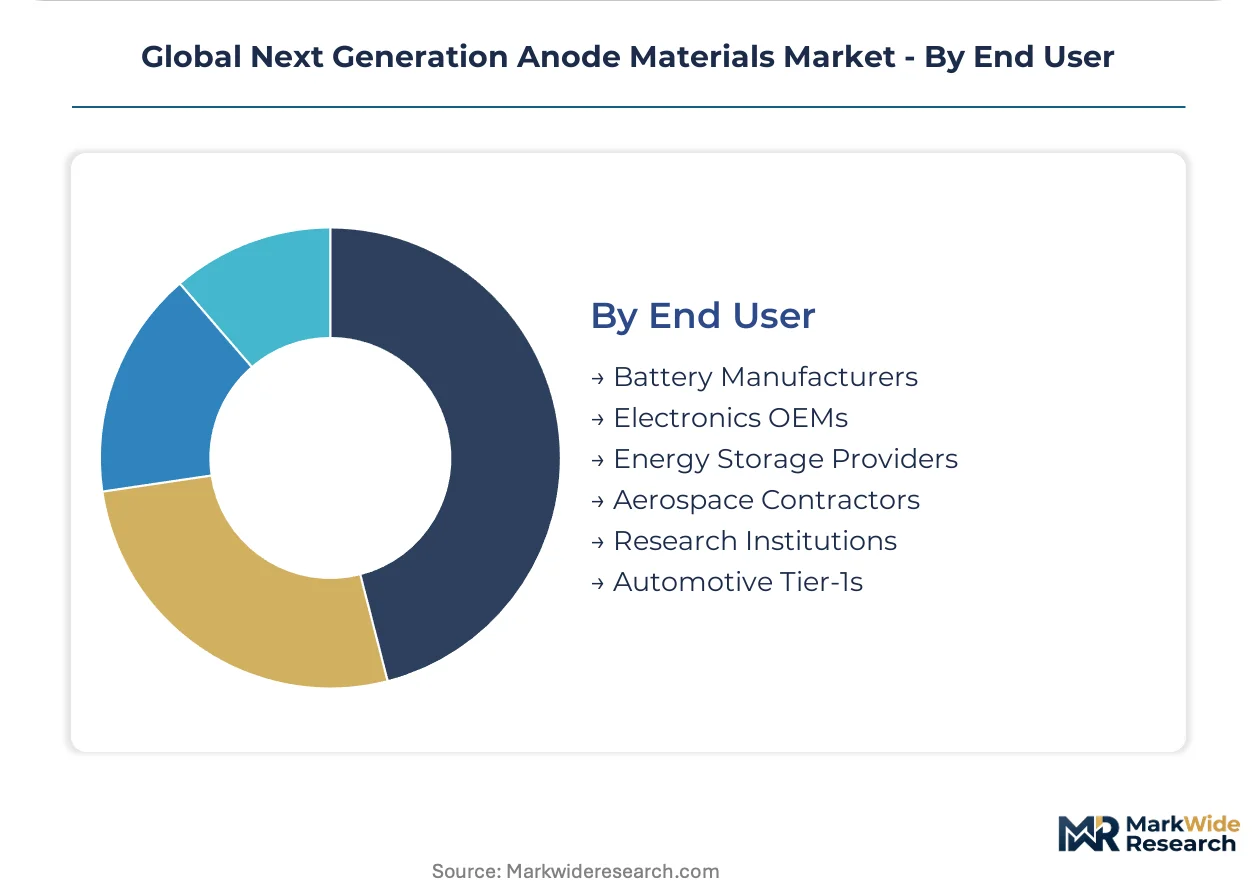
End User:
Supply concentration varies by buyer sophistication, with battery manufacturers and automotive Tier-1s conducting direct qualification of deposition specialists, while research institutions and smaller electronics OEMs rely on distributor channels.
- Battery Manufacturers:Cell producers including Korean majors and Chinese state-backed entities negotiate multi-year offtake agreements with silicon composite suppliers. Direct procurement bypasses traditional distributors, compressing margin pools for intermediate traders.
- Automotive Tier-1s:System integrators in Germany and Japan qualify anode materials for KBA-certified and METI-coordinated supply chains. Dual certification requirements under EU Battery Regulation and domestic testing protocols stretch supplier R&D bandwidth.
- Electronics OEMs:Consumer device manufacturers specify rate capability and form factor constraints.
- Energy Storage Providers:Utility and commercial project developers optimize levelized cost of storage through hard carbon selection.
- Aerospace Contractors:Satellite and defense prime contractors enforce radiation and vacuum environment validation.
- Research Institutions:National laboratories and university programs pilot solid-state cell architectures.
Battery manufacturers dominate procurement volume. Automotive Tier-1s expand their supplier development programs fastest as cell integration moves upstream.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Trade flows in next-generation anode materials tilt toward net-import dependence in Western automotive hubs, while East Asian production clusters generate surplus capacity for interregional supply. Korea and Japan export silicon-composite formulations to European cell plants. China's precursor dominance creates raw material leverage over downstream anode fabrication.
South Korea
Domestic battery manufacturers accelerate silicon-dominant anode procurement to satisfy EU Battery Regulation energy density mandates for automotive cell exports. METI-coordinated technical dialogues with Japan align solid-state battery roadmaps across the Korea Strait. POSCO Chemical's integrated precursor-to-anode complex in Pohang anchors regional supply security for Korean cell majors.
China
Metallurgical-grade silicon purification capacity concentrates in Jiangsu and Sichuan provinces, feeding domestic anode fabrication for state-backed cell manufacturers. GB standards and NMPA certification protocols enforce domestic testing regimes that filter market access for foreign material suppliers. The Yangtze River Delta cluster houses mechanical milling operations serving consumer electronics cell demand.
Germany
Automotive OEMs consolidate anode procurement through direct offtake negotiations with deposition specialists for KBA-certified cell plants. REACH substance authorization and EU Green Deal carbon border adjustments force suppliers to document embedded emissions across precursor extraction. Bavaria's industrial base hosts qualification laboratories for solid-state silicon composite architectures.
Japan
National solid-state battery roadmaps specify silicon anode compatibility thresholds that validate next-generation cell designs for automotive Tier-1 integration. Resonac Holdings and other domestic suppliers occupy positions in silicon-graphene composite development. The Chubu region around Nagoya maintains precision chemical processing infrastructure for nano-structuring operations.
United States
Thin-film deposition specialists command premium compensation as capital-intensity divergence unwinds competitive boundaries in anode manufacturing. IRA domestic content incentives reshape procurement calculations for battery cell plants in the Midwest and Southeast. Silicon Valley anchors venture-funded development of solid-state silicon composite architectures for aerospace applications.
Global Next Generation Anode Materials Market Competitive Landscape
Concentration sits with integrated chemical conglomerates and venture-backed deposition specialists rather than conventional graphite producers. Korean and Chinese industrial groups leverage backward integration into precursor supply. Two strategic archetypes dominate: silicon nanowire manufacturing scale players and solid-state composite architecture developers. Competitive moves center on multi-year automotive offtake agreements and pilot-to-production scale transitions.
Among venture-backed specialists, Sila Nanotechnologies Inc. and Amprius Technologies occupy positions exemplifying silicon composite and nanowire archetypes respectively. POSCO Chemical represents the integrated industrial group model with captive precursor supply. These three entities anchor distinct competitive vectors within the market structure.
| Leading Market Players |
|---|
| Sila Nanotechnologies Inc. |
| Nexeon Ltd. |
| Amprius Technologies |
| LeydenJar Technologies BV |
| Shanghai Shanshan Technology Co., Ltd. |
| POSCO Chemical |
| Talga Group |
| Resonac Holdings Corporation |
| OneD Battery Sciences |
| Others |
Supply & Pricing Matrix
Twelve-month qualification timelines for silicon-dominant formulations compress pricing negotiations as automotive cell contracts harden around energy density mandates, concentrating procurement leverage with Korean and Chinese battery manufacturers who control volume allocation decisions.
Pricing Analysis
Configured-to-order pricing for silicon nanowire architectures commands spreads exceeding standard silicon composite formulations by margins reflecting deposition complexity and automotive certification tier. Contract-based long-term offtake agreements dominate procurement, with price differentiation driven by GB standards certification level and volume scale commitments. Cost compression in uncoated natural graphite tiers intensifies as silicon-dominant alternatives displace conventional anodes in premium automotive segments. Grid storage developers exhibit highest price sensitivity, prioritizing cost-per-cycle optimization over energy density premiums.
Supply Chain Analysis
China and South Korea anchor metallurgical-grade silicon purification and anode fabrication respectively, with Japan maintaining precision nano-structuring capabilities for aerospace-qualified architectures. Western anode producers draw from Chinese precursor supply for silicon feedstock, creating single-source vulnerability amid NMPA certification filtering. Tariff exposure runs through EU Green Deal carbon border adjustments impacting embedded emissions documentation. Distribution runs through direct offtake agreements between deposition specialists and automotive Tier-1s, bypassing traditional distributor channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is exiting a cyclical trough as EU Battery Regulation mandates trigger replacement demand cycles across European automotive supply chains, compressing material qualification timelines and reallocating procurement budgets toward certified silicon composite suppliers.
For Market Incumbents: Compound technology leadership in solid-state silicon composite architectures through captive precursor supply investments in South Korea's industrial cluster. Accelerate pilot-to-production scale transitions to defend margin position against emerging mechanical milling specialists. Secure dual certification under EU Battery Regulation carbon disclosure and METI-coordinated roadmaps to maintain automotive Tier-1 access. For New Entrants and Emerging Players: KBA certification fast-track programs in Germany offer qualification pathways for deposition specialists targeting European automotive OEM procurement. India's PLI scheme for advanced chemistry cell manufacturing represents the most penetrable geography, with hard carbon supply partnerships offering lower capital barriers than silicon nanowire scale. Pursue direct qualification agreements with energy storage providers optimizing levelized cost of storage. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across nano-structuring operations as thin-film deposition talent scarcity commands premium compensation. Long-term viability over the next decade rests on backward integration into precursor supply and captive automotive offtake pipelines. Acquisition targets should display integrated precursor-to-anode production capabilities or validated silicon-graphene composite architectures. Monitor METI solid-state battery roadmap compatibility thresholds as the inflection signal for technology obsolescence risk.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precursor Supply | POSCO Chemical's Pohang complex demonstrates how captive metallurgical-grade silicon purification insulates margin pools from Chinese supply volatility. |
| Dual Certification Investment | Simultaneous EU Battery Regulation carbon disclosure and GB standards compliance compresses automotive qualification timelines for European market access. |
| Solid-State Composite Architecture Development | Sila Nanotechnologies validates how engineered silicon composites sustain technology leadership under tightening automotive energy density mandates. |
| Direct Long-term Offtake Agreements | Korean battery manufacturers bypass distributor channels to secure captive silicon nanowire supply from Amprius Technologies. |
| India PLI Scheme Partnership | Hard carbon suppliers qualify under production-linked incentives for grid storage installations serving utility-scale renewable integration. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across primary interviews with silicon composite procurement managers at Korean battery manufacturers, deposition process engineers at nano-structuring specialists, automotive Tier-1 cell integration leads, and utility-scale energy storage developers. Secondary validation drew from EU Battery Regulation implementation documents, METI solid-state battery roadmap publications, NMPA certification protocol disclosures, and customs trade data for metallurgical-grade silicon flows. Bottom-up capacity assessments and top-down demand projections were triangulated to anchor segmentation outputs.
Across the analysis window, the forecasting framework modeled material type segmentation by silicon-based, graphene-based, and hard carbon architectures; technology tiers spanning coating, nano-structuring, and composite manufacturing; and application splits between electric vehicles, grid storage, and aerospace systems. CAGRs were derived from regression analysis against automotive cell production schedules and renewable energy deployment pipelines. Key inputs included EU Battery Regulation compliance timelines and India's PLI scheme disbursement trajectories.
The analysis sits within stated boundaries; outcomes outside sustained automotive electrification capital deployment or relaxation of China's GB standards filtering would require recalibration. Forecasts reflect assumptions regarding silicon nanowire manufacturing scale economics and precursor supply concentration persistence. Recalibration cycles align with material shifts in EU Battery Regulation enforcement intensity and METI roadmap threshold revisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Advanced Materials
Long-Range Ordered Porous Carbon (LOPC) Market
Advanced Materials
Advanced Sports Materials Market
Advanced Materials
Cold Plasma Market
Advanced Materials
Liquid Thermal Interface Materials Market
Advanced Materials
Borophene Market
Advanced Materials
Vacuum Insulation Panels Market
Advanced Materials
Advanced Polymer Composites Market
Advanced Materials
Global High Performance Thermoplastics Market
Advanced Materials
North America Advanced Phase Change Materials Market
Advanced Materials
Global Aerogel Insulation Market
Advanced Materials
Corundum Market
Advanced Materials
Organic Aerogel Market
Advanced Materials
US Graphene Market
Advanced Materials
Electromagnetic Shielding Market
Advanced Materials
Carbon Graphite Market
Advanced Materials
High Nickel Cathode Materials Market