
 Global High Dispersible Silica Market | 2026-2036
Global High Dispersible Silica Market Size, Share, and Industry Trends Forecast 2026-2036
Global High Dispersible Silica Market Foresight
The tire reinforcement segment is realigning procurement priorities across major rubber manufacturers as fuel-efficiency mandates tighten. Evonik Industries AG leverages its silane chemistry integration to dominate premium tire silica formulations. Cabot Corporation sustains manufacturing scale across multiple continents, while Quechen Silicon Chemical Co., Ltd. anchors cost-competitive supply for Asian tire producers.
High dispersible silica refers to synthetic amorphous silicon dioxide engineered with surface areas typically exceeding 150 m²/g and controlled particle size distribution below 20 micrometers, manufactured through precipitation or fumed processes to achieve uniform dispersion in rubber matrices and polymer systems. Precipitated silica leads volume output across tire and industrial rubber applications, while silane treated silica commands margin concentration due to its coupling-agent integration that reduces rolling resistance in green tire formulations. The coatings additive segment within paints and coatings is growing fastest as architectural and automotive finish specifications demand improved scratch resistance and matting efficiency.
REACH in Europe, EPA guidelines in the United States, and China's GB standards under SAMR oversight collectively tighten purity thresholds and workplace exposure limits for synthetic amorphous silica. These frameworks push manufacturers toward surface-modified grades that reduce volatile content and improve handling safety. Stakeholders must monitor regulatory divergence between jurisdictions to align product portfolios with diverging certification requirements.
Market Dynamics
Tire labeling standards in Europe and China's GB standards under SAMR oversight are compressing formulation windows for rubber manufacturers, forcing rapid qualification of surface-modified silica grades that balance rolling resistance against wet grip performance.
Growth Catalysts
- Fuel-efficiency mandates:EU tire labeling regulations and NHTSA corporate average fuel economy standards in the United States are mandating lower rolling resistance compounds, pulling high dispersible silica into original equipment tire formulations.
- China's tire production expansion:Capacity additions in Shandong and Jiangsu provinces are concentrating procurement volumes for precipitated silica among domestic rubber compounders serving export markets.
- Silane chemistry integration:In-situ coupling agent treatments are reducing mixing stages and energy consumption in tire manufacturing, accelerating adoption across high-volume production lines.
Market Restraints
- Sodium silicate cost volatility:Fluctuations in energy-intensive feedstock production are compressing margins for precipitated silica manufacturers without captive alkali silicate supply.
- Supply concentration in East Asia:Over half of global precipitated silica capacity resides in China, exposing procurement chains to logistics disruptions and export control uncertainties.
- Fumed silica substitution in coatings:Premium architectural finishes are migrating toward fumed grades for superior optical clarity, limiting volume expansion in certain matting applications.
Strategic Opportunities
- India tire manufacturing:Tamil Nadu and Gujarat production clusters are expanding capacity for radial truck and bus tires, creating first-mover positioning for silica suppliers qualifying under BIS standards.
- Battery separator coatings:Ceramic-coated polyethylene separators for lithium-ion cells represent an emerging volume outlet for ultra-high purity precipitated silica with controlled pore architecture.
- EU Green Deal carbon border adjustments:Emissions-intensive imports face escalating levies, advantaging European-based manufacturers with renewable energy-integrated production.
Industry Challenges
- Silane handling expertise:Safe management of sulfur-containing coupling agents requires specialized occupational health protocols that many compounders lack in-house.
- REACH registration timelines:Novel surface modifications trigger extended substance evaluation periods, delaying commercial launch by multiple years.
- Legacy mixing equipment retrofit:Older Banbury and intermix installations require capital-intensive modifications to achieve dispersion quality specifications for next-generation green tire formulations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global High Dispersible Silica Market |
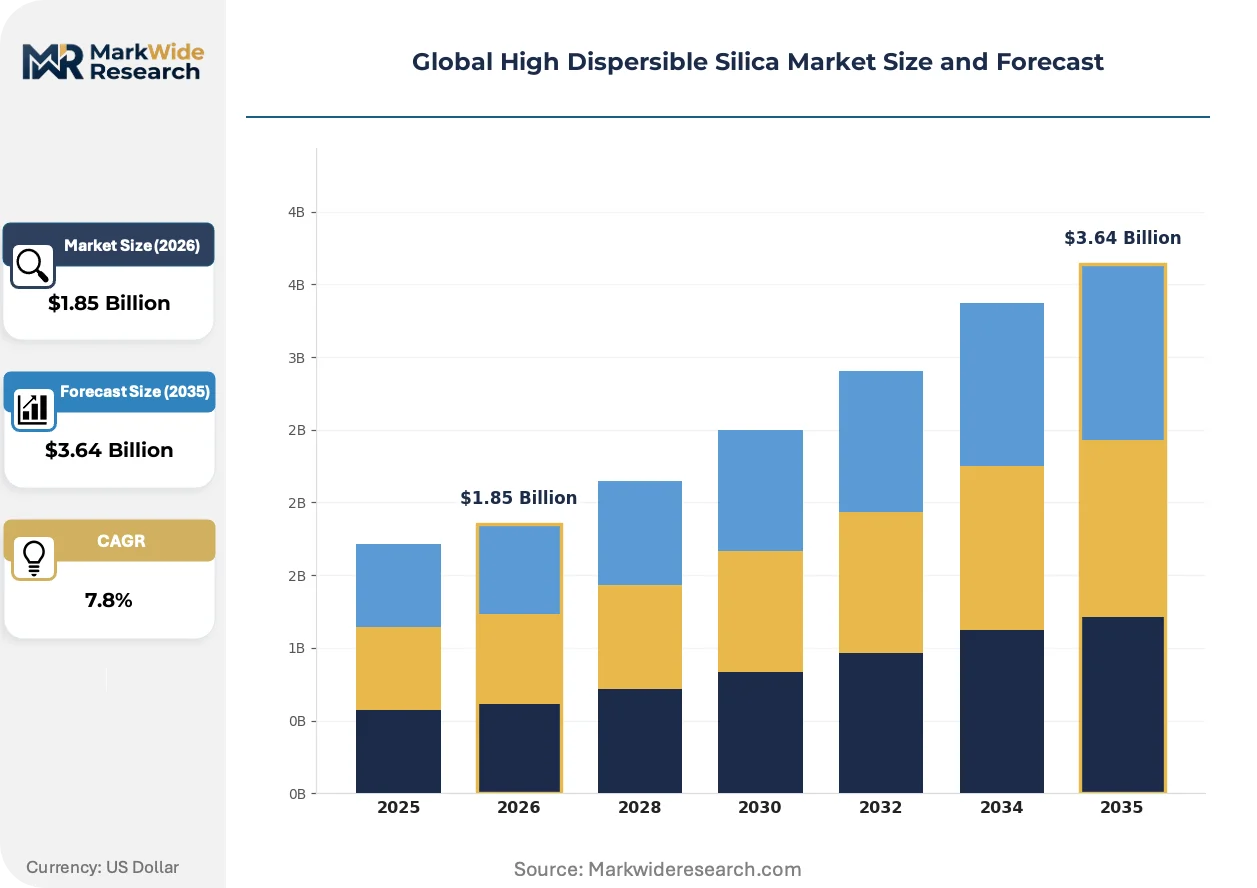
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.64 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Precipitated Silica, Fumed Silica, Colloidal Silica, Silane Treated Silica, Polymer Coated Silica Application: Tire Reinforcement, Coatings Additive, Adhesives & Sealants, Plastics Modification, Rubber Compounds End User Industry: Rubber Manufacturing, Paints and Coatings, Construction Materials, Polymer Processing, Adhesive Production Form: Powder, Granules, Slurry, Dispersion |
| Companies Covered | PPG Industries, Inc., Oriental Silicas Corporation, Evonik Industries AG, Quechen Silicon Chemical Co., Ltd., Cabot Corporation, Solvay S.A., Tosoh Silica Corporation, Madhu Silica Pvt. Ltd., W.R. Grace & Co., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global High Dispersible Silica Market Shifts & Advancements
Surface engineering and regulatory chemistry are converging to redefine performance benchmarks across tire, coatings, and industrial rubber applications. Formulation science is pivoting toward multifunctional additives that consolidate processing steps.
Silane-treated precipitated silica is overtaking conventional untreated grades in premium tire segments. The coupling-agent integration enables direct bonding between silica particles and rubber polymer chains, eliminating separate silane addition steps. Major tire manufacturers in Germany and Japan are qualifying these grades for original equipment supply contracts, compressing the competitive window for standard precipitation products.
REACH authorization requirements for certain organosilane intermediates are tightening supply chain documentation obligations. ECHA's evolving substance evaluation criteria are extending registration timelines for novel surface chemistries. Tire compounders in Europe are responding by locking in multi-year supply agreements with established registrants to secure formulation continuity.
Direct mill-base supply contracts are displacing traditional distributor channels in the coatings sector. Large architectural paint manufacturers in the United States are negotiating silica slurry deliveries integrated into tinting systems, bypassing powder handling entirely. This pattern concentrates procurement leverage among national account teams and compresses margins for regional distributors serving smaller formulators.
Global High Dispersible Silica Market Segmentation
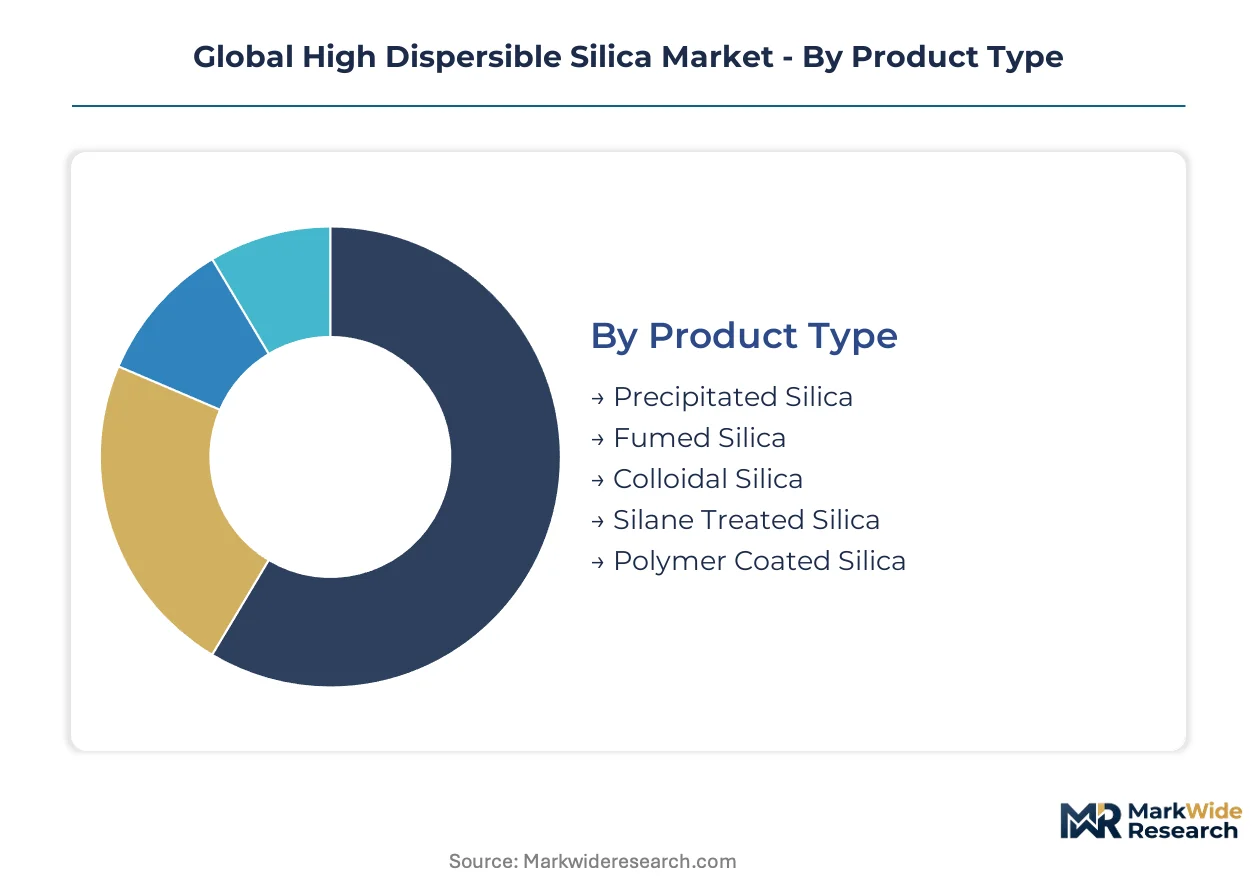
High dispersible silica markets fragment across manufacturing processes, application requirements, and handling specifications. Buyers prioritize dispersion efficiency, surface chemistry compatibility, and regulatory compliance differently depending on their end-use constraints. Understanding these segmentation layers reveals where procurement power concentrates and where formulation innovation unlocks premium positioning.
Product Type:
Purchasers in this category differentiate primarily by performance tier and integration complexity, with tire compounders seeking silane-coupled solutions while coatings formulators weigh optical clarity against cost.
- Precipitated Silica:Synthetic amorphous silicon dioxide produced via sodium silicate acidification, yielding surface areas of 150-300 m²/g with controlled porosity. Demand concentrates in Shandong and Jiangsu province tire clusters, where domestic rubber compounders serving export markets require high-volume, cost-optimized filler for truck and passenger tire treads.
- Silane Treated Silica:Surface-modified grades with pre-integrated sulfur-containing coupling agents that enable direct silica-polymer bonding without separate mixing stages. German and Japanese original equipment tire manufacturers are qualifying these grades for fuel-efficiency mandates, compressing adoption timelines for conventional untreated alternatives.
- Fumed Silica:Flame-hydrolyzed silicon tetrachloride producing nanoscale particles with superior optical transparency and rheological control. Architectural finishes in North America specify these grades for premium clarity requirements.
- Colloidal Silica:Stabilized aqueous dispersions of nanometer-scale particles, valued in precision polishing and catalyst support applications where particle monodispersity is critical.
- Polymer Coated Silica:Encapsulated variants designed for enhanced compatibility with non-polar polymer matrices, reducing agglomeration in high-shear processing environments.
Precipitated silica leads volumes today; silane treated silica is gaining share fastest.
Application:
Formulation windows vary sharply across this dimension, with automotive OEM specifications imposing stricter dispersion and performance thresholds than industrial rubber or construction applications.
- Tire Reinforcement:High-load silica incorporation into tread compounds to reduce rolling resistance while maintaining wet grip, driven by EU tire labeling regulations and NHTSA corporate average fuel economy standards. Rolling resistance reduction targets of 20-30% versus carbon black formulations have made this the dominant volume outlet.
- Coatings Additive:Matting agents and scratch-resistance modifiers for architectural and automotive finishes. Large US paint manufacturers negotiate direct slurry supply contracts integrated into tinting systems, bypassing powder handling and concentrating procurement leverage among national accounts.
- Adhesives & Sealants:Rheology modifiers and reinforcement fillers in structural bonding formulations, where thixotropic behavior and transparency requirements dictate grade selection.
- Plastics Modification:Anti-blocking and anti-slip agents in polyethylene and polypropylene films, competing with mineral alternatives on cost-efficiency metrics.
- Rubber Compounds:General industrial rubber applications including conveyor belts, hoses, and seals, where precipitated silica provides tear strength and abrasion resistance improvements over conventional fillers.
Tire reinforcement commands the largest revenue pool; coatings additive applications are climbing the fastest as architectural finish specifications tighten.
End User Industry:
Regulatory exposure and certification requirements separate buyers here, with automotive-facing rubber manufacturers navigating REACH and GB standards while construction material producers face less stringent purity thresholds.
- Rubber Manufacturing:The core demand base encompassing tire producers and industrial rubber compounders in China, India, and Germany. These buyers prioritize batch-to-batch consistency and silane handling safety protocols.
- Paints and Coatings:Formulators seeking matting efficiency, scratch resistance, and optical clarity in waterborne and solvent-based systems. Direct mill-base supply contracts are displacing traditional distributor channels in this segment.
- Construction Materials:Concrete admixtures and cement modifiers where silica fume and precipitated grades improve compressive strength and durability.
- Polymer Processing:Masterbatch producers and compounders incorporating silica for anti-blocking, reinforcement, and processing aid functions.
- Adhesive Production:Manufacturers of structural and pressure-sensitive adhesives requiring controlled rheology and adhesion promotion.
Rubber manufacturing absorbs the majority of volume; paints and coatings is expanding most quickly on per-kg value metrics.
Form:
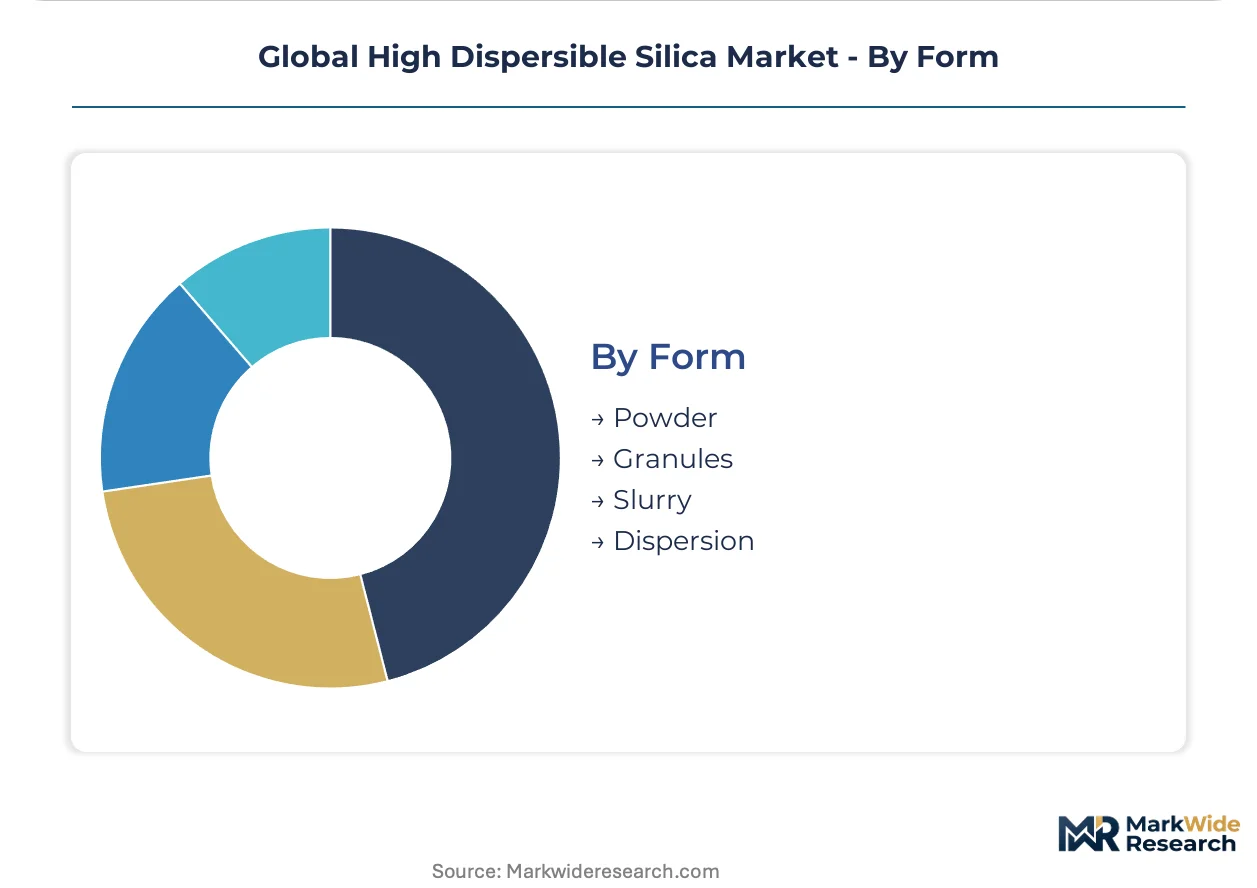
Handling infrastructure and dust exposure regulations drive selection in this category, with large integrated manufacturers preferring slurry or dispersion formats while smaller compounders rely on powder and granule shipments.
- Powder:Conventional dry form requiring dust control systems and respiratory protection during handling. Remains standard for smaller rubber compounders without liquid handling infrastructure.
- Slurry:Pre-dispersed aqueous formulations eliminating dust exposure and reducing mixing energy requirements. Large architectural paint manufacturers in the United States negotiate direct deliveries integrated into tinting systems.
- Granules:Agglomerated powder forms with reduced dusting tendency, bridging handling convenience and dispersion performance for mid-scale processors.
- Dispersion:Solvent-based or water-based concentrates with optimized particle stabilization for direct incorporation into high-shear mixing equipment.
Powder dominates shipment volumes today; slurry formats are gaining share fastest as occupational safety regulations tighten and integrated supply contracts proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturers are relocating precipitated silica capacity toward jurisdictions with lower energy costs and streamlined chemical registration pathways. This regulatory arbitrage is redrawing procurement maps as REACH compliance costs escalate in Europe while China's GB standards and India's BIS certification create alternative qualification tracks.
China
Shandong and Jiangsu province tire clusters are absorbing record volumes of domestic precipitated silica as radial tire exports surge. SAMR oversight of GB standards is tightening purity thresholds for workplace exposure limits. Qingdao-based compounders are integrating silane-treated grades directly into green tire formulations for European OEM supply contracts.
Germany
Original equipment tire manufacturers in Baden-Württemberg and Lower Saxony are mandating silane-coupled silica for rolling resistance compliance under EU tire labeling regulations. ECHA's REACH authorization timelines are extending registration periods for novel surface chemistries. Cologne-Essen industrial corridor facilities are retrofitting Banbury mixing equipment to handle next-generation dispersion specifications.
United States
NHTSA corporate average fuel economy standards are pulling high dispersible silica into domestic tire formulations at accelerating rates. EPA guidelines on synthetic amorphous silica workplace exposure are compressing handling protocol windows. Southeast tire production clusters in South Carolina and Georgia are negotiating direct slurry supply contracts to bypass powder handling infrastructure costs.
India
Tamil Nadu and Gujarat radial truck tire manufacturing hubs are expanding capacity for domestic replacement and export markets. BIS standards for silica filler purity are creating qualification barriers that favor established registrants with testing laboratory relationships. Mumbai-Pune chemical corridor distributors are consolidating procurement leverage through volume commitments to Chinese precipitated silica suppliers.
Japan
Premium tire compounders in Kansai and Chubu regions are qualifying silane-integrated silica grades for fuel-efficiency benchmarks exceeding domestic regulatory minima. METI industrial standards are aligning with JIS certification pathways for surface-modified fillers. Yokohama-based rubber research consortia are piloting direct mill-base delivery systems to reduce mixing stage energy consumption.
Global High Dispersible Silica Market Competitive Landscape
Capacity expansion dominates the current landscape as manufacturers race to secure positions in high-growth tire manufacturing clusters. The vendor base separates into three distinct tiers: integrated chemical conglomerates with captive silane supply, mid-scale precipitated silica specialists serving regional rubber compounders, and fumed silica purveyors targeting coatings applications. Strategic archetypes include backward-integrated alkali silicate producers, surface chemistry licensors, and slurry logistics operators. Geographic expansion and portfolio diversification represent the two most visible competitive vectors as firms chase qualification approvals across multiple regulatory jurisdictions.
Among German chemical conglomerates, Evonik Industries AG exemplifies the silane-integrated archetype through its coupling-agent chemistry dominance. Cabot Corporation anchors the multinational manufacturing scale tier with continental production footprints. Quechen Silicon Chemical Co., Ltd. occupies the cost-competitive supply position for Asian tire producers seeking volume-optimized precipitated grades.
| Leading Market Players |
|---|
| PPG Industries, Inc. |
| Oriental Silicas Corporation |
| Evonik Industries AG |
| Quechen Silicon Chemical Co., Ltd. |
| Cabot Corporation |
| Solvay S.A. |
| Tosoh Silica Corporation |
| Madhu Silica Pvt. Ltd. |
| W.R. Grace & Co. |
| Others |
Supply & Pricing Matrix
Sodium silicate feedstock indices in East Asian energy markets cascade directly into precipitated silica pricing tiers, compressing margins for manufacturers without captive alkali silicate production while amplifying cost advantages for backward-integrated producers serving European tire OEMs.
Pricing Analysis
Distributor margins in the coatings additive segment are compressing as direct mill-base supply contracts displace traditional powder distribution channels. Three-tier pricing structure across silane-treated premium grades, standard precipitated fillers, and economy industrial rubber variants reflects certification tier and volume scale differentiation. Pricing pressure stems from sodium silicate cost volatility in energy-intensive Chinese production clusters. Small rubber compounders in India exhibit highest price sensitivity, while German OEM tire manufacturers prioritize performance consistency over unit cost.
Supply Chain Analysis
Precipitated silica supply rests on sodium silicate acidification capacity concentrated in Shandong and Jiangsu provinces, with fumed silica production anchored in Germany and Japan. Key inputs span quartz sand, sulfuric acid, and organosilane coupling agents. Single-source vulnerability runs through Chinese export control uncertainties over energy-intensive chemical outputs. Distribution runs through direct long-term offtake agreements with tire manufacturers, bypassing spot market liquidity.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The global high dispersible silica market reads as a late-cycle quality story, with procurement specifications tightening around silane-coupled grades as EU tire labeling standards and NHTSA fuel economy mandates elevate performance thresholds above commodity filler alternatives.
For Market Incumbents: Anticipate fumed silica substitution pressure in premium architectural coatings by accelerating silane chemistry integration investments. Lock in multi-year REACH registration continuity with ECHA to secure formulation pipelines for novel surface modifications. Prioritize captive alkali silicate supply through backward integration into sodium silicate production, insulating margin structures from energy cost volatility in Chinese manufacturing clusters.
For New Entrants and Emerging Players: Capture battery separator coating qualification opportunities in South Korean and Japanese lithium-ion cell manufacturing, where ultra-high purity precipitated silica demand outpaces established supply relationships. Target Tamil Nadu and Gujarat radial tire clusters in India, where BIS certification barriers favor agile entrants with testing laboratory partnerships. Lead with slurry logistics capabilities to bypass incumbent powder distribution networks.
For Investors and Strategic Acquirers: Asymmetric upside sits with mid-scale precipitated silica specialists possessing silane treatment capabilities and existing REACH dossiers, positioned for European carbon border adjustment advantages. Long-term viability hinges on renewable energy-integrated production footprints qualifying for EU Green Deal procurement preferences. Watch ECHA substance evaluation timelines for organosilane intermediates as the inflection signal for formulation lock-in windows.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sodium Silicate | Captive feedstock supply insulates margin compression from energy cost volatility in East Asian production clusters. |
| Silane Chemistry Patent Licensing | Technology transfer agreements accelerate qualification timelines for tire OEMs under tightening fuel-efficiency mandates. |
| Slurry Logistics Infrastructure Buildout | Pre-dispersed aqueous delivery formats bypass powder handling costs and capture direct mill-base supply contracts. |
| REACH Dossier Expansion | Novel surface modification registrations secure multi-year formulation continuity with European rubber compounders. |
| Renewable Energy Production Integration | Carbon border adjustment compliance advantages position European facilities for premium tire OEM procurement. |
Research Methodology
Coverage spans China, Germany, the United States, India, and Japan, with primary inputs from each jurisdiction combined with secondary validation. Primary research incorporated interviews with tire manufacturing procurement directors, rubber compounding plant managers, coatings formulator technical leads, and precipitated silica distribution channel partners. Secondary sources included customs and trade flow databases, SEC 10-K filings from listed chemical producers, European Chemicals Agency REACH registration documentation, and national standards body publications from SAMR and BIS. Bottom-up volume modeling triangulated against top-down industry association aggregates.
Rate-of-change decomposition anchored the analytical framework across the projection horizon, segmenting by manufacturing process tier, application performance requirements, end-use regulatory exposure, and physical handling format. CAGRs derived from elasticity-adjusted demand projections against capacity expansion announcements and qualification timeline assumptions. Industry-specific forecast inputs incorporated EU tire labeling regulation compliance deadlines and NHTSA corporate average fuel economy standard phase-ins.
Regulatory authorization delays, energy cost volatility in alkali silicate production, and logistics disruption in East Asian export corridors are the dominant revision risks to modeled outputs. Forecasts reflect documented assumptions on substitution elasticity and qualification timeline distributions. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
High-Value Chemicals
Global Epichlorohydrin (ECH) Market
High-Value Chemicals
Phenanthroline Monohydrate Market
High-Value Chemicals
Global High Temperature Grease Market
High-Value Chemicals
P-Hydroxybenzoates (PHB) Market
High-Value Chemicals
Battery Grade High Purity Lithium Fluoride Market
High-Value Chemicals
High Purity Silica Market
High-Value Chemicals
Global 1-Hexanol Market
High-Value Chemicals
Potassium Hydroxide Market
High-Value Chemicals
High-Heat Melamine Foam Market
High-Value Chemicals
High Molecular Weight Polyisobutylene Market
High-Value Chemicals
Global High Heat Foam Market
High-Value Chemicals
Sodium Hexametaphosphate Market
High-Value Chemicals
Ammonium Metavanadate Market
High-Value Chemicals
Ultra-High Purity Hydrofluoric Acid Market
High-Value Chemicals
Asia-Pacific Hydrogen Bromide Market
High-Value Chemicals
Diethylhydroxylamine (DEHA) Market