
 Germany LED Lighting Market | 2026-2036
Germany LED Lighting Market Size, Share, and Industry Trends Forecast 2026-2036
Germany LED Lighting Market Insights
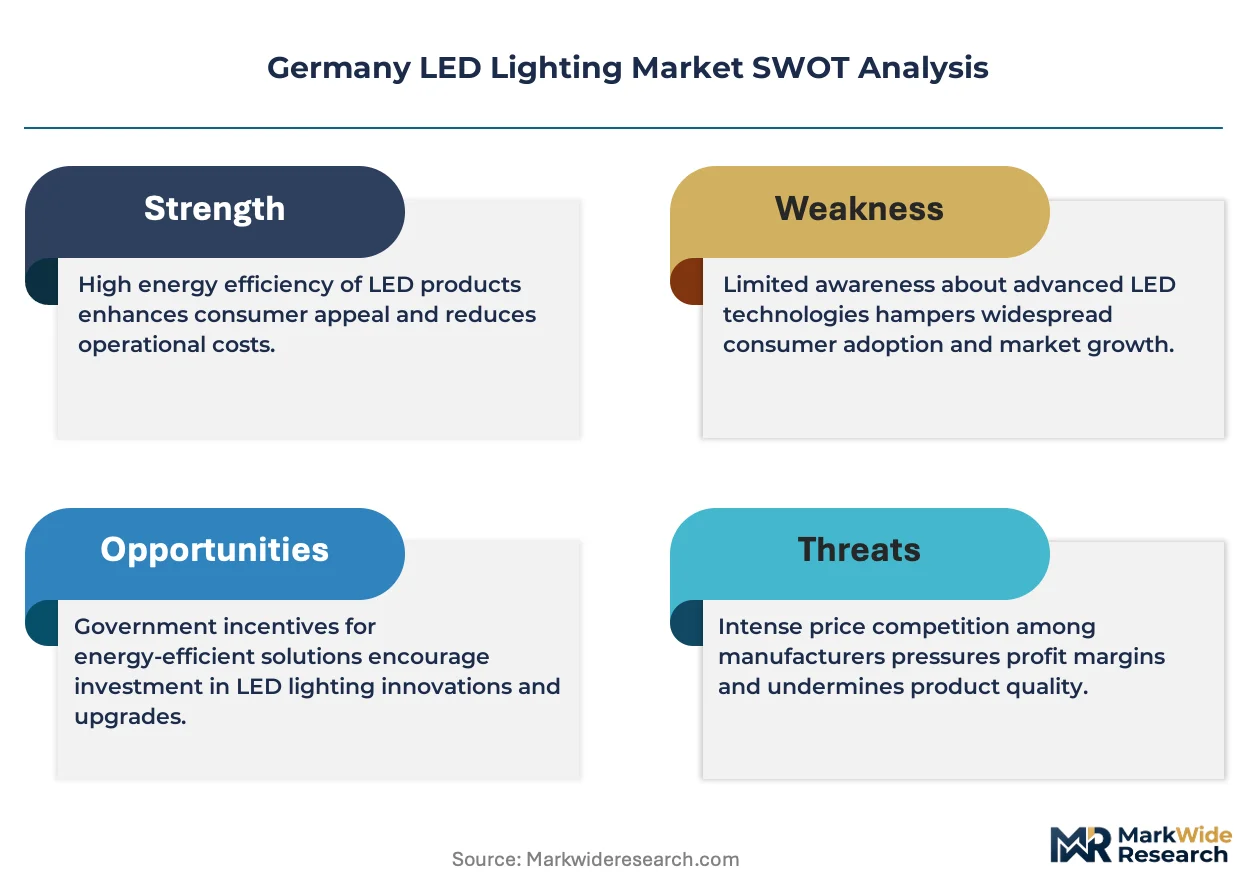
Modular fixture architectures paired with tunable white engines is recalibrating procurement patterns among German commercial landlords. TRILUX GmbH & Co. KG leverages its vertical manufacturing footprint in Arnsberg to control luminaire assembly and optical component sourcing. OSRAM GmbH sustains technology leadership in chip-on-board LED arrays for high-lumen industrial applications. LEDVANCE GmbH competes through aggressive channel positioning in retail and electrical wholesale networks across the DACH region.
Germany LED lighting comprises solid-state electroluminescent devices fabricated on sapphire or silicon carbide substrates, emitting visible light at 80-150 lumens per watt with rated lifespans exceeding 50,000 hours, primarily deployed to displace fluorescent and high-intensity discharge sources in energy-conscious built environments. The fixture segment anchors replacement demand as building codes mandate integrated controls and daylight harvesting sensors in new construction. Smart LED technology captures the fastest expansion as KNX and DALI-2 protocols become standard in German commercial specifications. RGB applications occupy niche positions in hospitality and architectural accent lighting where color rendering index requirements are less stringent.
The EU Ecodesign Directive and Germany's Building Energy Act (GEG) enforce minimum luminous efficacy thresholds and standby power limits, compelling manufacturers to redesign driver electronics and thermal management systems. KBA vehicle-type approval processes for automotive LED modules create parallel compliance obligations for suppliers with dual transportation and architectural exposure. Stakeholders must monitor the EU's F-Gas Regulation phase-down timeline, as refrigerant-linked building system retrofits often trigger simultaneous lighting upgrade decisions in integrated facility contracts.
Market Dynamics
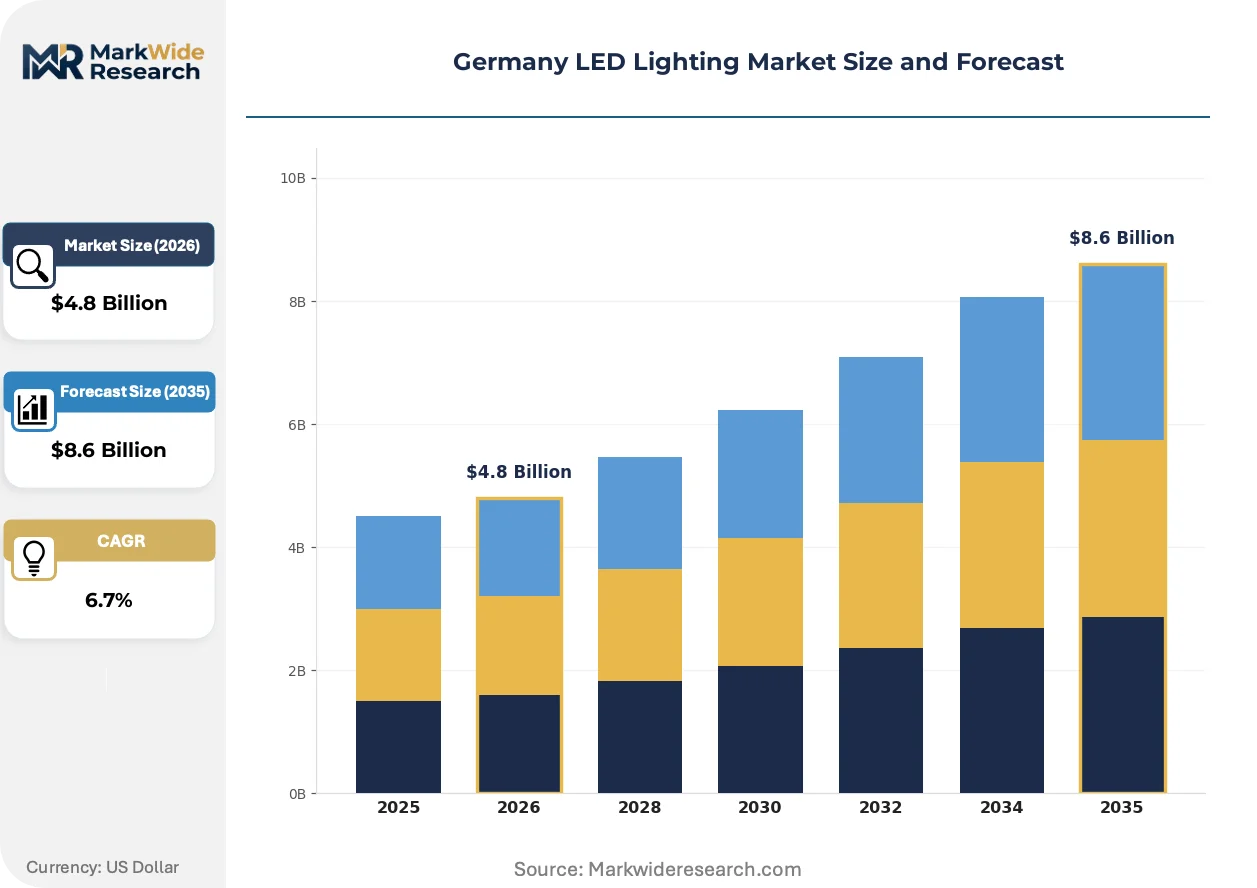
Germany's LED lighting sector is undergoing forced consolidation as the EU Ecodesign Directive and Building Energy Act compress replacement cycles while tightening efficacy thresholds, compelling manufacturers to redesign thermal management and driver architectures to maintain market access.
Growth Catalysts
- Building Energy Act (GEG):Minimum efficiency mandates for new construction and major renovations in commercial buildings accelerate fixture replacement demand across Berlin, Frankfurt, and Munich office stock.
- Tunable white systems:Workplace wellness certification programs in North Rhine-Westphalia and Bavaria drive specification of human-centric lighting with circadian rhythm modulation.
- KNX and DALI-2 protocol standardization:Building automation integration requirements in German commercial specifications expand addressable market for connected luminaire retrofits.
Market Restraints
- Sapphire substrate supply concentration:Dependence on Asian wafer suppliers creates input cost volatility and extended lead times for chip-on-board LED arrays.
- KBA automotive compliance overlap:Suppliers serving both transportation and architectural markets face parallel vehicle-type approval processes that divert engineering resources.
- Fluorescent stock persistence:Existing T8 and T5 installations in municipal and educational facilities exhibit slower replacement elasticity despite operating cost disadvantages.
Strategic Opportunities
- Rhine-Ruhr industrial corridor:Underpenetrated manufacturing facilities in Dortmund and Duisburg present retrofit potential for high-bay LED systems with occupancy sensing.
- F-Gas Regulation phase-down linkage:Integrated HVAC and lighting upgrade contracts create bundled procurement opportunities as refrigerant-linked building system retrofits accelerate.
- Human-centric lighting + IoT convergence:Integration of tunable white engines with building management systems enables premium positioning in healthcare and senior living verticals.
Industry Challenges
- Electronics engineering talent scarcity:Shortage of power electronics and thermal design specialists constrains driver redesign cycles needed for GEG compliance.
- Legacy control system interoperability:Integration complexity with existing 0-10V and DALI-1 installations in 1990s-era commercial stock delays smart retrofit adoption.
- CE marking documentation burden:Expanded technical file requirements under updated Ecodesign implementing measures extend product launch timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany LED Lighting Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bulbs, Fixtures, Strips, Panels Application: Residential, Commercial, Industrial, Outdoor Technology: Smart LED, Standard, RGB, Tunable White End User: Homeowners, Businesses, Municipalities, Contractors |
| Companies Covered | TRILUX GmbH & Co. KG, LED Linear, OSRAM GmbH, Nimbus Group GmbH, LUMITRONIX, LEDVANCE GmbH, PROLED, RZB Lighting GmbH, Paulmann Licht GmbH, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany LED Lighting Market Trends and Innovations
Sensor-integrated luminaires are compressing the traditional separation between lighting and building automation, as German commercial landlords demand unified platforms for energy reporting and space utilization analytics.
LiFi (light fidelity) transmission technology is automating secure data connectivity in electromagnetic-sensitive environments. Defense contractors and healthcare facilities in Stuttgart and Munich are piloting bidirectional optical wireless networks embedded in ceiling grids. This convergence of illumination and telecommunications infrastructure is collapsing the procurement boundary between IT and facilities departments.
The EU F-Gas Regulation phase-down timeline is accelerating coordinated building system decisions. Facility managers in integrated contracts are bundling refrigerant recovery, HVAC replacement, and LED upgrades to minimize disruption and capture combined energy savings. German industrial property portfolios exhibit the strongest bundling intensity.
Certification-driven specification is displacing price-first procurement in premium commercial segments. WELL Building Standard and LEED v4.1 compliance requirements in Frankfurt financial district leases are mandating tunable white systems with documented melanopic lux delivery. Landlords absorb higher fixture costs to secure tenant retention and rental premiums.
Germany LED Lighting Market Segmentation
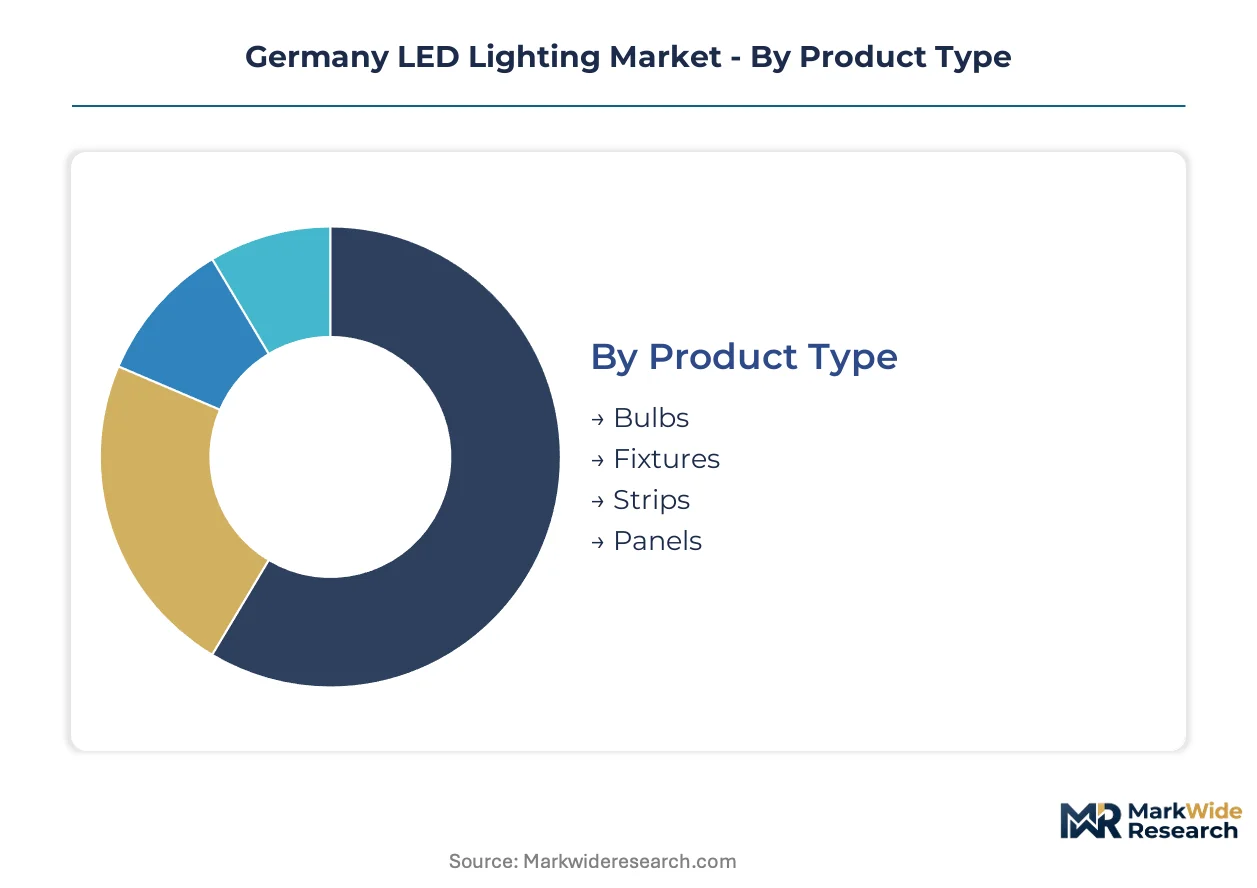
German LED procurement patterns diverge sharply across product architectures and buyer categories. Building code mandates and retrofit economics create distinct replacement-cycle rhythms that reshape volume distribution within each segment.
Product Type:
Fixture replacement cycles accelerate as the Building Energy Act tightens efficacy thresholds for permanent installations.
- Fixtures:Integrated luminaire assemblies with embedded drivers and thermal management systems anchor commercial retrofit demand. Office renovations in Frankfurt and Munich concentrate specification activity for recessed troffers and pendant systems with daylight harvesting sensors.
- Bulbs:Retrofit lamp form factors with Edison and bayonet bases serve residential and small commercial displacement of legacy sources. Bavarian municipal programs and North Rhine-Westphalia streetlight initiatives sustain volume for high-lumen A-lamps and PAR configurations.
- Panels:Flat-form ceiling-integrated systems with edge-lit or direct-backlit architectures serve open-plan commercial layouts.
- Strips:Flexible linear arrays with adhesive mounting profiles occupy architectural accent and cove illumination applications.
Volume placements concentrate in Fixtures; the faster expansion belongs to Panels.
Application:
Cost-tier stratification separates specification-driven commercial retrofits from price-sensitive residential replacement.
- Commercial:Tunable white and smart control integration dominates workplace wellness certification projects. Berlin and Munich landlords absorb premium fixture costs to secure WELL Building Standard compliance and tenant retention.
- Industrial:High-bay systems with chip-on-board arrays and occupancy sensing address underpenetrated manufacturing facilities in the Rhine-Ruhr corridor.
- Outdoor:Street and area luminaires with photocell controls serve municipal retrofit mandates across German states.
- Residential:Consumer-direct bulb and fixture sales through electrical wholesale and retail channels exhibit slower smart technology penetration.
Commercial applications command the highest per-unit value; industrial retrofits are climbing the fastest as energy audits accelerate.
Technology:
Customer-type differentiation separates building-automation-integrated specifications from basic replacement demand.
- Smart LED:KNX and DALI-2 protocol-enabled luminaires with wireless commissioning interfaces capture connected retrofit specifications. Frankfurt financial district leases increasingly mandate networked lighting for space utilization analytics.
- Tunable White:Circadian rhythm modulation engines with correlated color temperature adjustment serve healthcare and senior living verticals prioritizing melanopic lux delivery.
- Standard:Fixed CCT products without connectivity features occupy cost-constrained replacement cycles in educational and municipal facilities.
- RGB:Color-mixing arrays for hospitality accent and architectural effects where color rendering requirements are less stringent.
Standard technology retains volume dominance; smart LED systems are gaining share fastest through building automation convergence.
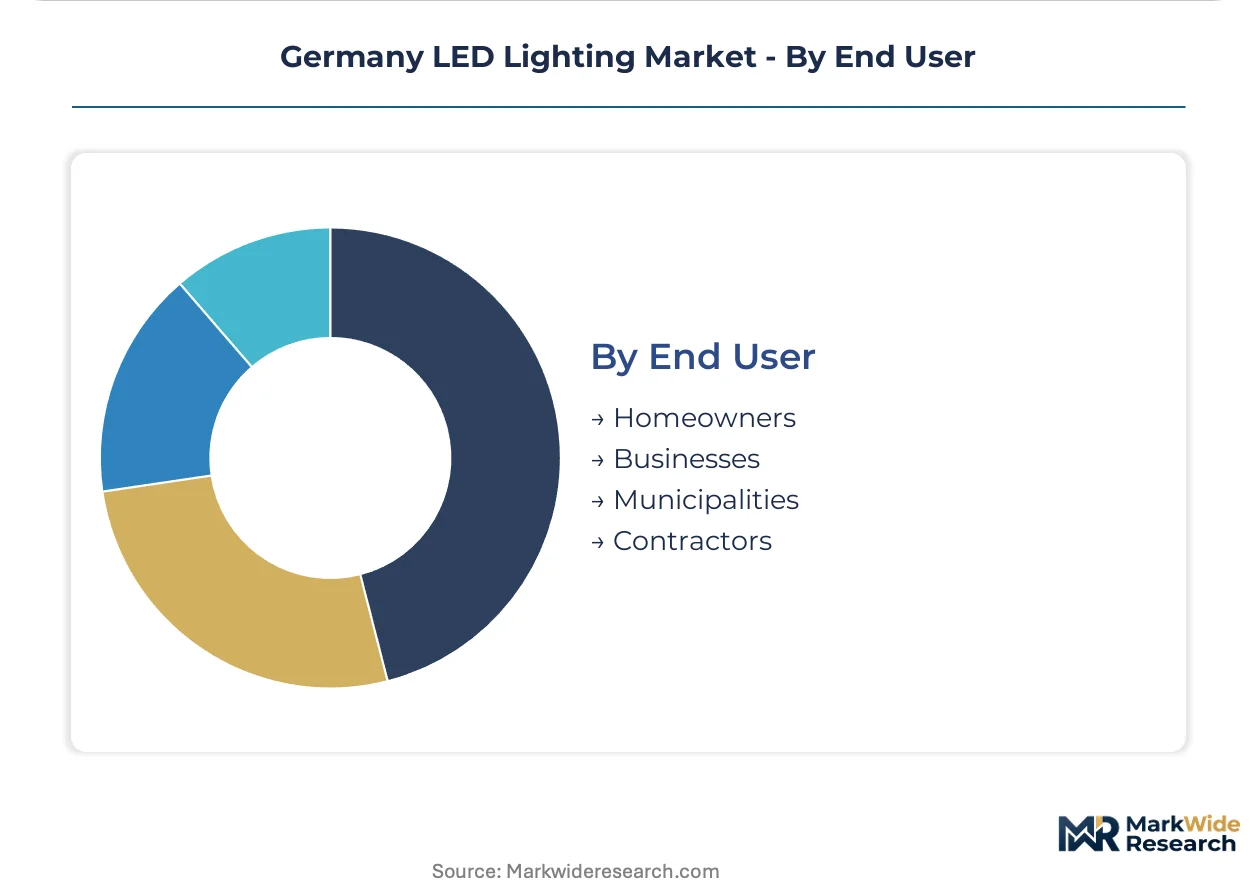
End User:
Supply concentration varies across direct-specification and channel-mediated procurement pathways.
- Businesses:Corporate facility managers and landlord entities drive integrated lighting-HVAC upgrade decisions with documented energy savings requirements.
- Municipalities:German state and city procurement offices administer streetlight retrofit programs with extended payback tolerance and public tender processes.
- Contractors:Electrical installation firms serve as specification influencers in mid-market commercial projects and residential new construction.
- Homeowners:End-consumer purchases through retail and e-commerce channels exhibit high price elasticity and low attachment rates for smart features.
Businesses generate the steepest expansion trajectory; municipalities anchor replacement volume through programmatic retrofits.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
North Rhine-Westphalia's InnovationRegion Rhein-Ruhr special economic zone concentrates LED manufacturing and engineering talent, drawing fixture producers to Dortmund and Essen. Bavaria's Munich-Augsburg corridor anchors tunable white R&D for workplace wellness applications.
Bavaria
Munich landlords drive tunable white specification for WELL Building Standard compliance. The state's Building Energy Act enforcement tightens efficacy thresholds for commercial renovations. The Ingolstadt-Augsburg manufacturing belt hosts fixture assembly operations serving southern German office markets.
North Rhine-Westphalia
Dortmund industrial facilities present underpenetrated retrofit potential for high-bay LED systems with occupancy sensing. Municipal streetlight programs across Cologne and Düsseldorf accelerate fixture replacement cycles. The Rhine-Ruhr corridor bundles HVAC and lighting upgrades under integrated facility contracts.
Baden-Württemberg
Stuttgart defense contractors pilot LiFi optical wireless networks in electromagnetic-sensitive environments. The state's automotive supply base creates KBA compliance overlap for dual-market LED producers. Karlsruhe and Mannheim host engineering centers developing chip-on-board arrays for industrial applications.
Hesse
Frankfurt financial district leases mandate networked lighting for space utilization analytics. The Building Energy Act drives major renovation cycles in aging commercial stock. The Rhine-Main metropolitan region concentrates specification activity for smart control integration.
Berlin-Brandenburg
Berlin office renovations prioritize daylight harvesting sensors and KNX protocol compatibility. Municipal procurement programs sustain volume for standard retrofit lamps in educational facilities. The capital region's startup ecosystem incubates IoT-enabled luminaire ventures targeting building automation convergence.
Germany LED Lighting Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across Germany's LED lighting sector. The vendor base organizes into three tiers: vertically integrated manufacturers controlling optical component sourcing, channel-centric distributors leveraging wholesale networks, and niche architectural specialists commanding premium positioning. Consolidation pressure intensifies as Ecodesign Directive compliance costs favor scale. Strategic moves center on backward integration into driver electronics and thermal management systems, plus geographic expansion into adjacent DACH markets.
Among Germany-based GmbH structures, TRILUX GmbH & Co. KG and OSRAM GmbH exemplify divergent archetypes—TRILUX representing captive manufacturing control through its Arnsberg assembly footprint, OSRAM occupying technology leadership in high-lumen industrial chip-on-board arrays. LEDVANCE GmbH sits within the channel-centric tier, its positioning anchored in retail and electrical wholesale penetration across the broader German-speaking region.
| Leading Market Players |
|---|
| TRILUX GmbH & Co. KG |
| LED Linear |
| OSRAM GmbH |
| Nimbus Group GmbH |
| LUMITRONIX |
| LEDVANCE GmbH |
| PROLED |
| RZB Lighting GmbH |
| Paulmann Licht GmbH |
| Others |
Pricing and Supply Chain Analysis
Family-owned mid-cap fixture specialists dominate Germany's LED supply base, anchoring pricing discipline through captive thermal management production and selective channel partnerships that resist commoditization pressure from Asian imports.
Pricing Analysis
Cost-down pressure on standard retrofit lamps accelerates because municipal procurement offices enforce reverse-auction tender formats across Bavaria and North Rhine-Westphalia. Pricing stratifies across premium tunable white systems, standard KNX-enabled fixtures, and economy bulb replacements. WELL Building Standard certification and GEG compliance tiering separate landlord-grade specifications from consumer-direct sales. Municipal buyers exhibit highest price sensitivity; Frankfurt financial district tenants absorb fixture premiums for wellness certification.
Supply Chain Analysis
Dual-sourcing mandates from German commercial landlords require qualified suppliers for both sapphire-substrate LED arrays and driver electronics. Manufacturing concentrates in China, Taiwan, and Malaysia for wafer fabrication, with final assembly anchored in Germany's Arnsberg and Ingolstadt corridors. German producers depend on Asian suppliers for silicon carbide substrates and gallium nitride epitaxy. Single-source vulnerability in substrate supply creates input cost volatility. Distribution runs through electrical wholesale networks and direct specification channels serving DACH-region contractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Germany's LED market operates under sapphire substrate supply constraints that prop fixture pricing and protect incumbent margins against low-cost import competition.
For Market Incumbents: To counter margin erosion from Asian chip-on-board imports, deepen backward integration into driver electronics and thermal management systems. Secure captive supply agreements with Taiwanese wafer suppliers to insulate against lead-time volatility. Prioritize GEG pre-certification investments to accelerate product launch timelines. For New Entrants and Emerging Players: The EU F-Gas Regulation phase-down across Germany opens a window for bundled HVAC-lighting retrofit specialists. Target underpenetrated industrial facilities in Dortmund and Duisburg with high-bay systems integrating occupancy sensing. Lead with energy-audit-driven procurement to bypass incumbent specification lock-in. For Investors and Strategic Acquirers: Accelerated municipal tender volumes in North Rhine-Westphalia is the leading indicator that programmatic retrofit demand is hardening. Five-to-ten year viability favors mid-cap fixture producers with vertical manufacturing footprints and established KNX/DALI-2 certification. Monitor German state budget allocations for streetlight replacement as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Driver Electronics | Captive production of GEG-compliant drivers insulates margins from Asian component volatility. |
| KNX/DALI-2 Protocol Certification | Building automation integration mandates in Frankfurt and Munich office leases expand addressable retrofit market. |
| Tunable White Engine Development | Melanopic lux delivery capabilities unlock WELL Building Standard premiums in healthcare and senior living verticals. |
| Rhine-Ruhr Industrial Corridor Expansion | High-bay LED penetration in Dortmund manufacturing facilities captures energy audit-driven replacement cycles. |
| Integrated HVAC-Lighting Contracting | F-Gas Regulation phase-down bundling creates sticky facility relationships with multi-year service revenue. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with electrical contractors, commercial facility managers, municipal procurement officers, and lighting specification engineers validated demand patterns. Bottom-up fixture shipment data from German electrical wholesale channels reconciled with top-down building stock renovation forecasts. ZVEI industry statistics, BAFA energy efficiency program disclosures, and KBA automotive compliance documentation supplemented quantitative modeling.
Data-stream reconciliation across shipment volumes, tender awards, and regulatory implementation timelines shaped the projection framework. Segmentation dimensions modeled include product architecture, application vertical, technology tier, and end-user procurement pathway. CAGRs derived from fitted growth curves applied to replacement-cycle economics and code-mandated retrofit deadlines. Sapphire substrate pricing indices and GEG enforcement schedules served as industry-specific forecast inputs across the analysis window.
The model assumes a particular technology adoption path; alternative pathways for LiFi optical wireless or solid-state laser illumination would alter the outlook. Forecasts reflect assumptions about Ecodesign Directive implementation pacing and municipal budget continuity. Deviation in substrate supply availability or GEG amendment timelines would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
LED
China Outdoor LED Lighting Market
LED
LED Modular Display Market
LED
GCC LED Lighting Market
LED
LED Display Market
LED
LED Tube Drivers Market
LED
North America Micro-LED Display Market
LED
LED Lighting Market
LED
Brazil LED Market
LED
Russia LED Market
LED
Thailand LED Market
LED
Global Chip on Board (COB) Light Emitting Diode Market
LED
Outdoor LED Display Market
LED
LED High Bay Drivers Market
LED
Arrow LED Displays Market
LED
Europe Outdoor LED Lighting Market
LED
Surface Mount PLCC Leds Market