
 Disposable Intestinal Wash Bags Market | 2026-2036
Disposable Intestinal Wash Bags Market Size, Share, and Industry Trends Forecast 2026-2036
Disposable Intestinal Wash Bags Market Analytics
Nursing specialization in enterostomal therapy is bifurcating the competitive landscape between premium sterile suppliers and cost-focused non-sterile producers. Medtronic leverages its surgical channel relationships to sustain institutional contracts across acute care networks. Coloplast anchors its position through dedicated stoma care education programs that lock in clinician preference. B. Braun Melsungen competes on manufacturing scale, operating high-throughput extrusion lines that feed both European and Asian distribution hubs.
Disposable intestinal wash bags are single-use collection devices, typically fabricated from medical-grade polyethylene or PVC with integrated closure mechanisms and odor-barrier films, designed for colostomy and ileostomy effluent management in post-operative or chronic bowel diversion patients. The product type dimension shows sterile variants commanding margin pools in surgical centers while non-sterile formats penetrate price-sensitive homecare channels. Material segmentation reveals biodegradable formulations gaining traction as hospital sustainability procurement criteria tighten, though polyethylene retains volume leadership due to established sterilization compatibility and supply chain reliability.
FDA 510(k) clearance requirements and EMA Medical Device Regulation standards govern sterility validation and biocompatibility testing for intestinal wash bags sold in the United States and European Union. The EU Green Deal and associated packaging waste directives are pressuring manufacturers to transition from PVC toward recyclable or biodegradable alternatives. Japan's PMDA enforces JIS-compliant quality management systems that create incremental compliance costs for foreign entrants. Stakeholders must monitor evolving extended producer responsibility frameworks and decide whether to absorb compliance investments or pass costs through tiered product architectures.
Market Dynamics
Homecare migration is compressing acute-care volumes while amplifying demand for simplified, patient-operable designs that reduce nursing dependency. This structural shift forces manufacturers to reconfigure product portfolios around unskilled user ergonomics rather than clinical workflow optimization.
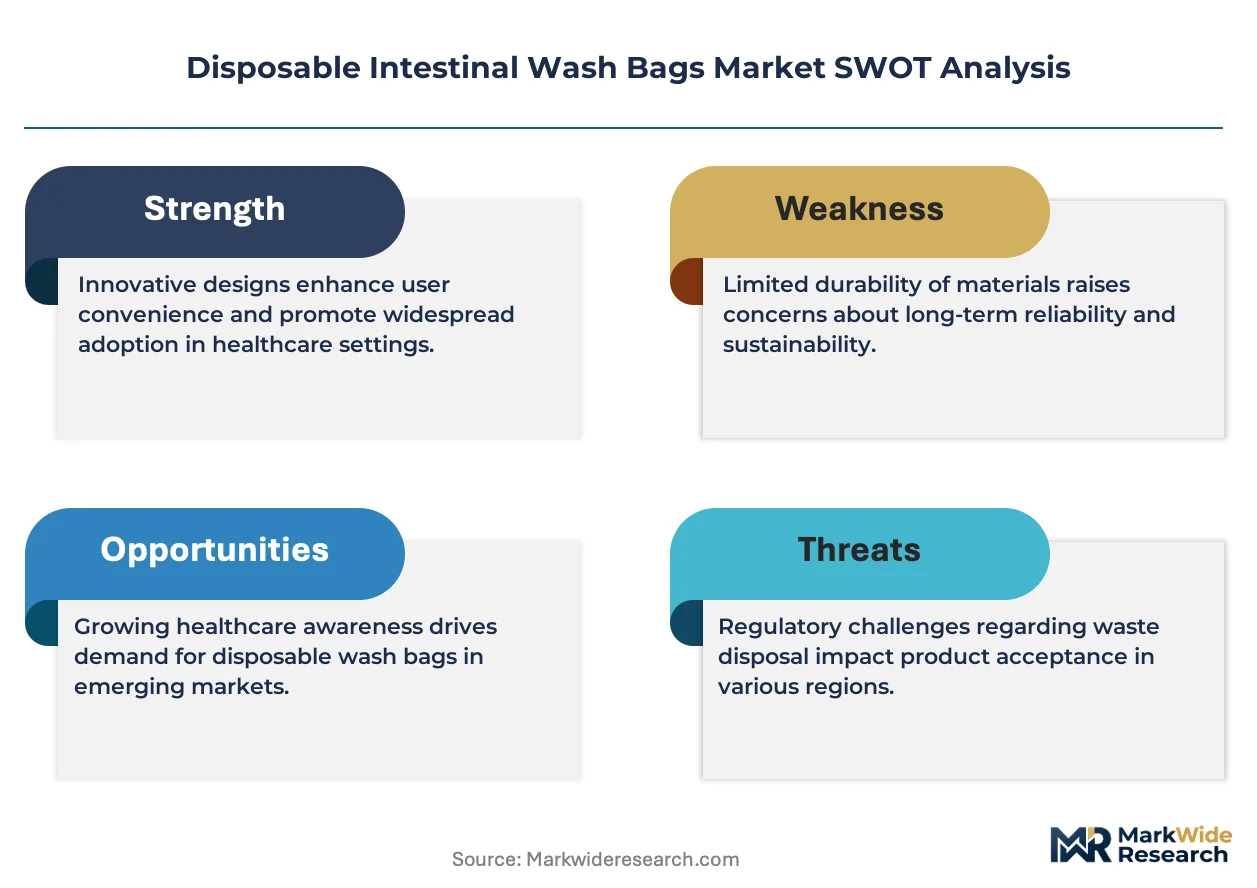
Growth Catalysts
- Japan's PMDA quality mandates:Stringent JIS-compliant manufacturing standards elevate entry barriers, protecting incumbent suppliers with certified production lines and creating pricing power for compliant domestic and foreign producers.
- Geriatric bowel diversion procedures:Aging demographics in Germany and the United States sustain procedural volume growth, with patients aged 65+ representing the dominant cohort for permanent colostomy formation.
- Biodegradable polymer R&D:Hospital sustainability procurement criteria under the EU Green Deal are accelerating material substitution programs, creating first-mover advantage for suppliers with validated compostable formulations.
Market Restraints
- Medical-grade polyethylene supply concentration:Feedstock availability tightens around Gulf Coast petrochemical complexes, exposing European and Asian converters to freight cost volatility and currency fluctuation risk.
- EMA MDR compliance timelines:Extended sterility validation protocols and notified body backlogs delay product launches by 12-18 months, compressing revenue recognition windows for pipeline innovations.
- Reusable collection systems:Silicone-based washable alternatives gain traction in environmental-conscious patient segments, threatening single-use volume in premium homecare channels.
Strategic Opportunities
- India's outpatient stoma care expansion:Underpenetrated Tier-2 and Tier-3 cities present volume growth potential as government health schemes expand reimbursement for post-surgical supplies.
- Subscription-based home delivery channels:Direct-to-patient replenishment models bypass traditional distributor markups, capturing margin and locking in recurring revenue through automated reorder algorithms.
- ISO 13485 certification arbitrage:Suppliers with dual US-EU quality system registrations can serve both FDA 510(k) and EMA MDR pathways from unified production footprints, reducing compliance duplication costs.
Industry Challenges
- Enterostomal therapy nurse scarcity:Specialized clinician training programs fail to match patient population growth, limiting effective product training and complication troubleshooting in community settings.
- Legacy ERP integration with track-and-trace systems:Serialization requirements for EU MDR compliance demand capital-intensive software upgrades that strain mid-tier manufacturer IT budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Disposable Intestinal Wash Bags Market |
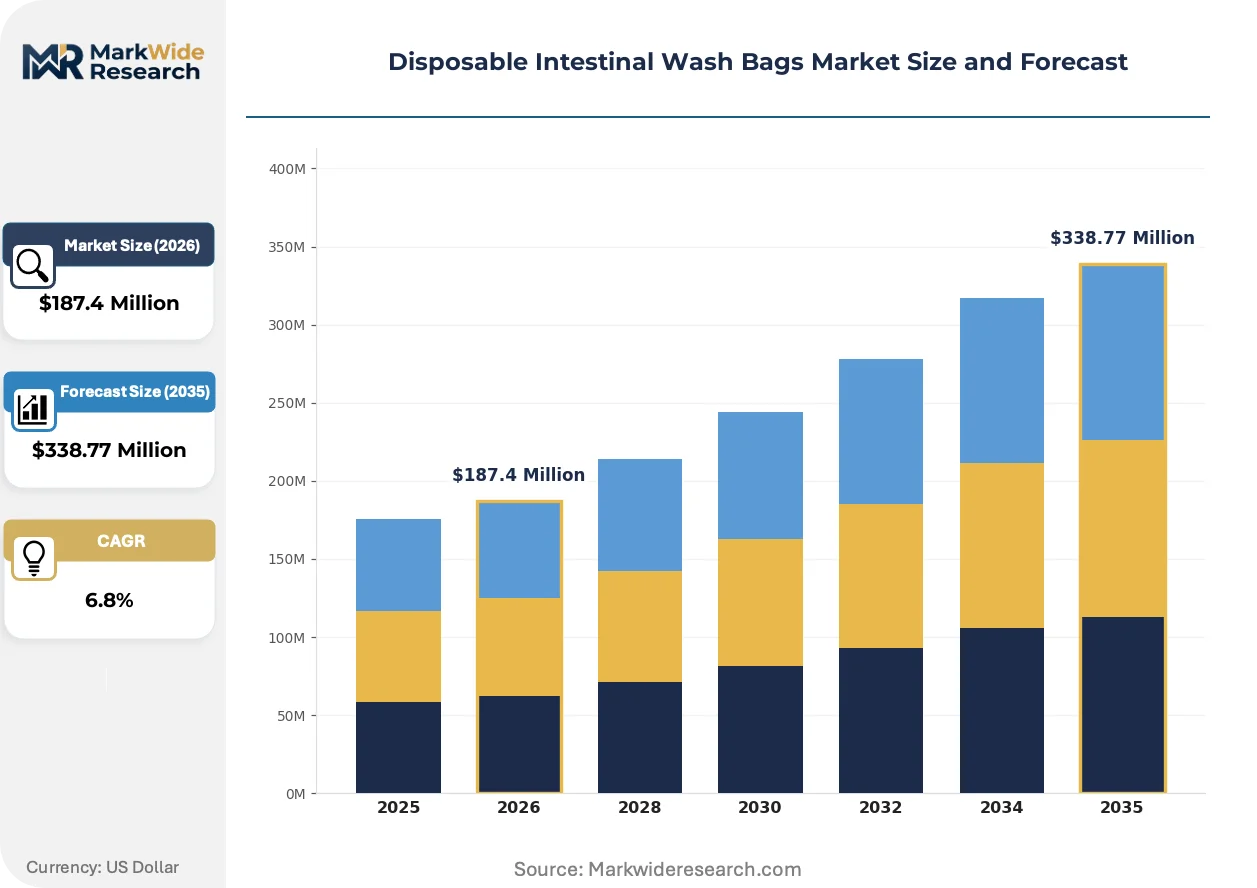
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Use, Sterile, Non-Sterile, Hydration End User: Hospitals, Clinics, Homecare, Surgical Centers Material: Plastic, Biodegradable, Polyethylene, PVC Packaging Type: Box, Pouch, Bag, Carton |
| Companies Covered | Medline, Medtronic, Coloplast, Johnson & Johnson, 3M Company, Medline Industries, B. Braun Melsungen, Flexicare Medical, Teleflex Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Disposable Intestinal Wash Bags Market Evolving Landscape
Material science advances and regulatory stringency are simultaneously elevating performance thresholds and sustainability expectations, forcing parallel investment in biocompatibility validation and circular economy design. The competitive frontier now sits at the intersection of clinical efficacy and environmental accountability.
Odor-barrier film technology is bifurcating competitive positioning. Multi-layer coextruded structures with activated carbon interlayers now dominate surgical center procurement, while simplified single-layer formats penetrate cost-sensitive homecare segments. Premium suppliers capture margin through proprietary laminate formulations, whereas commodity producers compete on extrusion throughput and geographic proximity to distribution hubs.
EMA Medical Device Regulation enforcement is compressing time-to-market for new entrants. Extended clinical evidence requirements for Class IIa intestinal devices now demand biocompatibility testing protocols that previously applied only to implantable products. German and French notified bodies are prioritizing submissions from manufacturers with established EU quality system histories, disadvantaging recent market entrants from non-European jurisdictions.
Patient self-management competency is reshaping after-sales support models. Traditional distributor-led education programs face displacement from manufacturer-hosted digital training platforms and telehealth-integrated troubleshooting services. The United States exhibits the most pronounced channel shift, where Medicare Advantage plans increasingly mandate remote monitoring compliance as a condition of durable medical equipment authorization.
Disposable Intestinal Wash Bags Market Segmentation
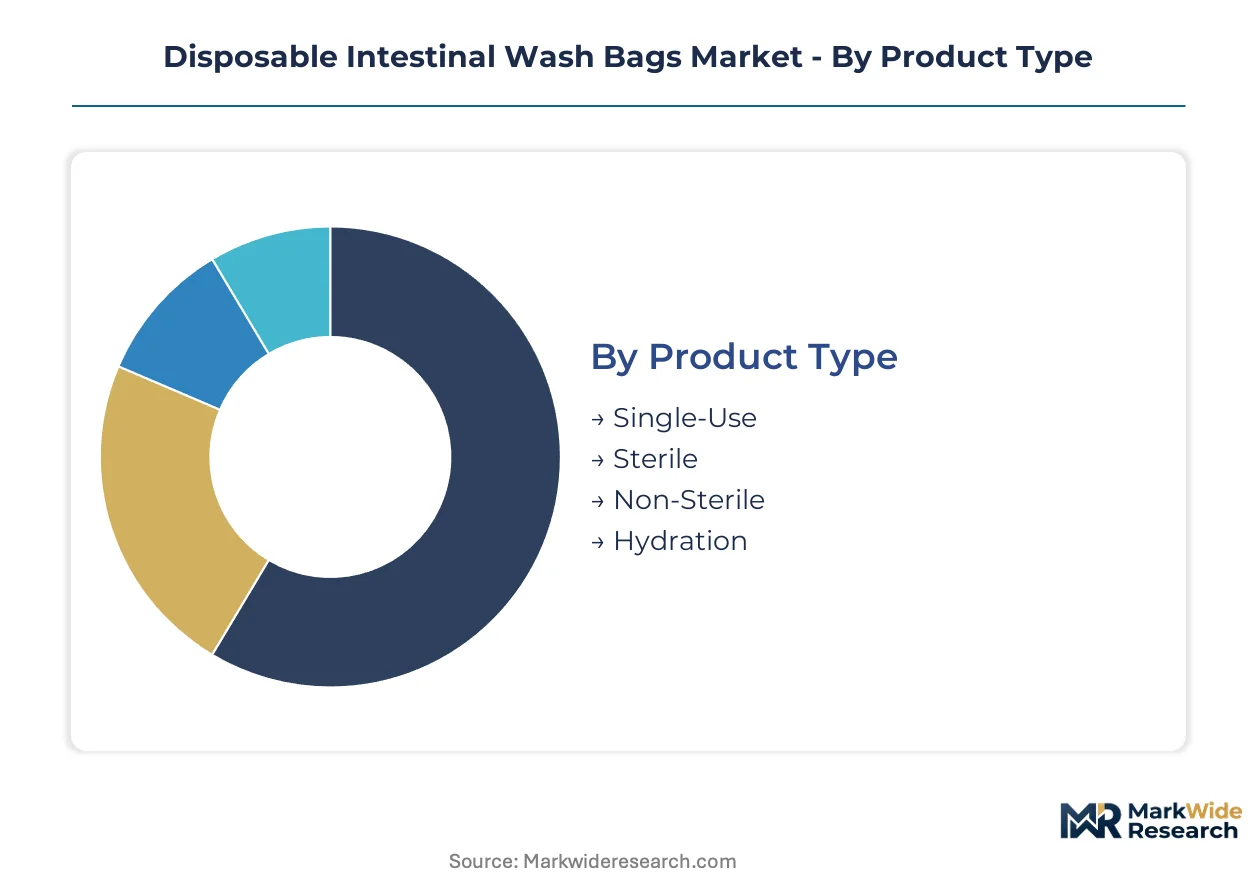
Channel configuration varies sharply across segment boundaries in this market. Sterile products flow through institutional procurement contracts, while non-sterile variants reach patients via retail and direct-to-home channels. Material and packaging choices increasingly reflect sustainability mandates from European hospital systems and Japanese quality regulators.
Product Type:
Channel mix splits sharply between institutional sterile supply chains and patient-direct non-sterile routes. Surgical centers and acute care networks anchor demand for validated sterile formats, while homecare migration amplifies simplified non-sterile consumption.
- Single-Use:Standard disposable construction using medical-grade polyethylene with integrated closure mechanisms. Demand concentrates in United States homecare settings where Medicare Advantage plans prioritize infection control through disposability over reusable alternatives.
- Sterile:Gamma-irradiated or ethylene oxide-sterilized units packaged in barrier pouches for operating room deployment. German surgical centers drive procurement volume under EMA MDR compliance frameworks that mandate validated sterility assurance levels for Class IIa devices.
- Non-Sterile:Clean-room manufactured but non-validated units for established ostomy patients. Patient-operable designs with simplified closure systems dominate Japanese homecare channels where PMDA quality mandates still apply to manufacturing if not terminal sterilization.
- Hydration:Specialized formulations with integrated irrigation ports for bowel management protocols. Compact volume segment serving rehabilitation clinics in United States and Germany where enterostomal therapy nurses supervise irrigation training.
By volume, Single-Use leads. By growth pace, Non-Sterile is ahead as homecare channels expand faster than institutional procurement.
End User:
Cost tier separation defines this dimension, with acute care absorbing premium sterile pricing and homecare gravitating toward economy formats. Reimbursement mechanics differ sharply across tiers.
- Hospitals:Integrated health systems in United States and Germany negotiate multi-year supply agreements covering sterile intestinal wash bags as part of broader surgical consumables bundles. EMA MDR compliance and FDA 510(k) clearance serve as mandatory qualification filters.
- Clinics:Outpatient surgical facilities with lower sterilization infrastructure dependence. Japanese day-surgery clinics represent concentrated demand under national health insurance reimbursement schedules for post-operative stoma supplies.
- Homecare:Patient-direct consumption through retail pharmacies, durable medical equipment suppliers, and subscription delivery services. Simplified user interfaces and odor-barrier films drive product selection as nursing dependency decreases.
- Surgical Centers:Ambulatory facilities performing colostomy and ileostomy formation with same-day discharge protocols. United States Medicare reimbursement rates for facility fees influence product tier selection toward mid-grade sterile formats.
Hospitals capture the largest revenue pool. Homecare exhibits the steepest expansion trajectory as bowel management protocols shift outpatient.
Material:
Supply concentration in petrochemical feedstocks shapes geographic sourcing patterns, while sustainability procurement criteria in European Union drive substitution experiments.
- Plastic:Broad category encompassing polypropylene and polyethylene blends with established sterilization compatibility. German converters dominate European supply through integrated extrusion and converting operations.
- Biodegradable:Compostable polymers including polylactic acid and starch-based formulations. EU Green Deal packaging waste directives accelerate hospital pilot programs in France and Germany despite higher unit costs and unproven shelf stability.
- Polyethylene:Medical-grade low-density and linear-low-density variants with validated biocompatibility per ISO 10993. United States Gulf Coast petrochemical complexes supply feedstock to North American and Asian converters, creating freight cost exposure for European manufacturers.
- PVC:Legacy material with established heat-sealing characteristics and clarity for content visibility. Regulatory pressure from REACH and EU packaging directives drives phase-out planning despite continued use in price-sensitive segments.
Polyethylene dominates current volume. Biodegradable formats are gaining share fastest as sustainability procurement criteria tighten.
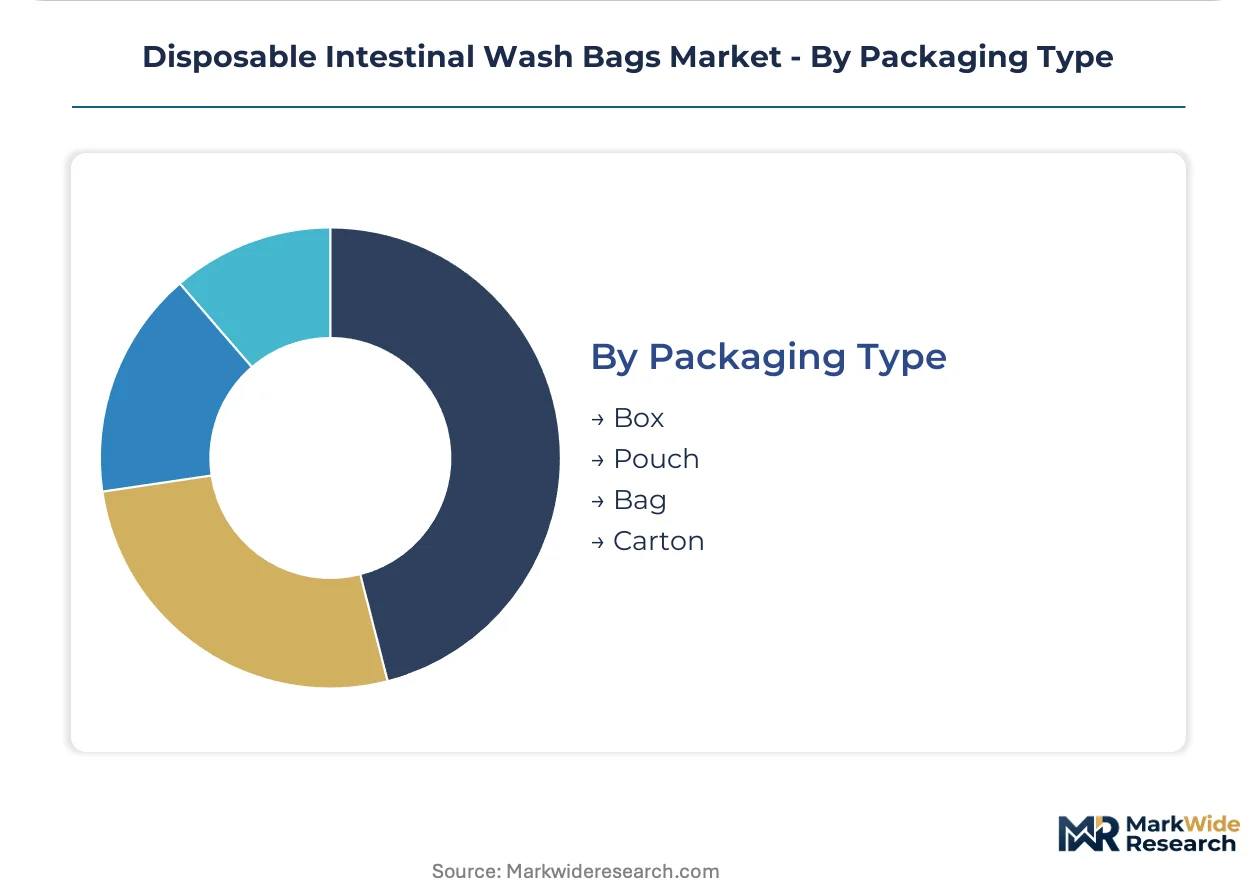
Packaging Type:
Volume scale and automation compatibility separate packaging choices, with high-throughput hospital procurement favoring rigid formats and homecare channels preferring flexible convenience.
- Box:Corrugated secondary packaging for palletized hospital distribution. Automated case-packing lines at German and United States manufacturing sites optimize for acute-care logistics networks.
- Pouch:Flexible primary packaging with heat-sealed barriers for individual unit protection. Japanese homecare channels favor compact pouch formats for discreet patient carriage and storage.
- Bag:Polyethylene shipping sacks for bulk institutional replenishment. Cost-minimized format for non-sterile products moving through distributor warehouses to retail pharmacies.
- Carton:Printed paperboard with regulatory labeling and patient instruction inserts. Required for direct-to-patient channels in United States where FDA device labeling mandates apply to home-use products.
Box and Carton formats lead by institutional volume. Pouch configurations are expanding most quickly through homecare channel growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in German surgical networks while United States homecare channels compress margins through volume-driven procurement. Japan's PMDA quality mandates sustain premium positioning for compliant suppliers. India's outpatient expansion offers volume growth at lower price points.
United States
Medicare Advantage plans drive disposability preference over reusable alternatives in homecare settings. FDA 510(k) clearance requirements filter market entry and sustain incumbent supplier relationships. The Gulf Coast petrochemical corridor feeds medical-grade polyethylene supply to domestic converters serving acute-care networks.
Germany
EMA MDR compliance frameworks mandate validated sterility assurance levels for Class IIa devices in surgical centers. EU Green Deal packaging waste directives accelerate hospital pilot programs for biodegradable alternatives. North Rhine-Westphalia hosts integrated extrusion and converting operations that dominate European supply.
Japan
PMDA enforces JIS-compliant quality management systems that create incremental compliance costs for foreign entrants. National health insurance reimbursement schedules concentrate demand in day-surgery clinics for post-operative stoma supplies. Kanto region manufacturing sites optimize for high-throughput production of patient-operable designs.
India
Government health schemes expand reimbursement for post-surgical supplies in Tier-2 and Tier-3 cities. CDSCO medical device regulations are tightening quality benchmarks for imported intestinal products. Maharashtra and Gujarat manufacturing clusters scale production for domestic consumption and regional export.
Disposable Intestinal Wash Bags Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across sterile and non-sterile product tiers. Surgical center procurement concentrates around validated sterile suppliers with established FDA and EMA quality system registrations. Homecare channels fragment across price-competitive converters and patient-direct subscription services. Dominant competitive moves include portfolio diversification into biodegradable materials and geographic expansion through distributor partnerships in underpenetrated Asian markets.
Among diversified medical device conglomerates, Medtronic and Coloplast exemplify distinct strategic positioning within the premium sterile tier. B. Braun Melsungen anchors the scale-driven manufacturing archetype with integrated European production capabilities. Medline Industries occupies a position spanning institutional and homecare channels through broad distribution reach.
| Leading Market Players |
|---|
| Medline |
| Medtronic |
| Coloplast |
| Johnson & Johnson |
| 3M Company |
| Medline Industries |
| B. Braun Melsungen |
| Flexicare Medical |
| Teleflex Incorporated |
| Others |
Value Network & Pricing Analysis
Ninety-day inventory cycles at German extrusion facilities concentrate pricing power among integrated polyethylene converters serving EMA-notified surgical centers. This lead-time band tightens whenever Gulf Coast petrochemical disruptions ripple through Atlantic freight routes, forcing acute-care buyers into premium spot purchasing.
Pricing Analysis
The customization-premium spread separates gamma-irradiated sterile units with proprietary odor-barrier laminates from standard polyethylene formats. Contract-based long-term offtake dominates institutional procurement, with price differentiation driven by ISO 13485 certification tier and volume scale commitments. Cost compression in non-sterile homecare tiers intensifies as subscription-based direct-to-patient channels bypass distributor markups. Homecare patients exhibit highest price sensitivity; German surgical networks show lowest.
Supply Chain Analysis
Inventory buffers at North Rhine-Westphalia converting sites rest on medical-grade polyethylene feedstock from United States Gulf Coast complexes and German petrochemical corridors. Raw material dependencies center on linear-low-density polyethylene resin, activated carbon interlayers for odor control, and barrier film substrates. Single-source vulnerability concentrates around ethylene oxide sterilization capacity for FDA 510(k) clearance pathways. Distribution runs through hospital GPO contracts in the United States and specialized stoma care distributors in Japan.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is recovering from reimbursement compression cyclicality, with Medicare Advantage expansion in the United States restoring procedural volumes to outpatient channels.
For Market Incumbents: Secure backward integration into medical-grade polyethylene compounding to insulate margin from Gulf Coast feedstock volatility. Anchor channel control through exclusive enterostomal therapy nurse training partnerships that lock in clinician preference against biodegradable substitute entrants. For New Entrants and Emerging Players: Digital patient education platform gaps expose under-served homecare segments where incumbents rely on legacy distributor training. Target India's Tier-2 and Tier-3 cities through government health scheme reimbursement alignment, deploying telehealth-integrated troubleshooting as the primary go-to-market angle. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified medical device conglomerates with under-optimized stoma care divisions lacking dedicated sales force focus. Long-term viability hinges on sustainability certification positioning; watch EU Green Deal packaging waste directive enforcement timelines as the inflection signal for biodegradable material substitution acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Biodegradable Material Certification | EU Green Deal compliance creates first-mover pricing power in French and German hospital systems. |
| Direct-to-Patient Subscription Launch | Medicare Advantage authorization requirements in the United States favor automated replenishment algorithms. |
| Dual FDA-EMA Quality System Registration | ISO 13485 certification arbitrage reduces compliance duplication costs across Atlantic markets. |
| Enterostomal Therapy Education Partnership | Clinician training scarcity in community settings locks in product preference through skill dependency. |
| India Distribution Channel Expansion | CDSCO regulatory alignment with government health schemes opens Tier-2 and Tier-3 city volume. |
Research Methodology
Cross-validation between hospital procurement database analysis and GPO contract documentation anchors the qualitative findings in this study. Primary interviews with enterostomal therapy nurses, biomedical engineers at acute-care networks, GPO contracts managers, and stoma care product managers combined with secondary validation against FDA 510(k) filings, EMA MDR notified body records, CMS Medicare reimbursement schedules, and Japanese PMDA quality system registrations. Bottom-up and top-down triangulation reconciles unit-volume estimates with value-chain margin analysis.
Sensitivity analysis across material substitution scenarios and reimbursement policy shifts frames the analytical approach over the projection horizon. Segmentation dimensions modeled include product sterility tier, end-user channel configuration, material composition, and geographic regulatory cluster. CAGRs derive from procedural volume trajectories, patient population demographics, and pricing elasticity coefficients specific to bowel diversion surgery recovery protocols.
Underlying assumptions cover sustained Medicare Advantage expansion, EMA MDR compliance timeline adherence, and Gulf Coast petrochemical supply stability, with deviation risk concentrated in biodegradable polymer shelf-life validation and enterostomal therapy workforce growth rates. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Gastroenterology
Stomach Cancer Market
Gastroenterology
Ulcerative Colitis (UC) Treatment Market
Gastroenterology
Colon Hydrotherapy Market
Gastroenterology
Inflammatory Bowel Disease Market
Gastroenterology
Gastrointestinal Drugs Market
Gastroenterology
Crohns Disease Therapeutics Market
Gastroenterology
Intestinal Pseudo-Obstruction Treatment Market
Gastroenterology
US Inflammatory Bowel Disease Treatment Market
Gastroenterology
Helicobacter Pylori Infections Treatment Market
Gastroenterology
Biliary Tract Cancers (Btcs) Treatment Market
Gastroenterology
Zollinger Ellison Syndrome Treatment Market
Gastroenterology
Diverticular Disease Therapeutics Market
Gastroenterology
Gallstone Market
Gastroenterology
US Gastroenterology Ambulatory Surgery Center Market
Gastroenterology
Intestinal Fistula Treatment Market
Gastroenterology
Malabsorption Syndrome Treatment Market