
 High Concentration Respiratory Masks Market | 2026-2036
High Concentration Respiratory Masks Market Size, Share, and Industry Trends Forecast 2026-2036
High Concentration Respiratory Masks Market Analytics
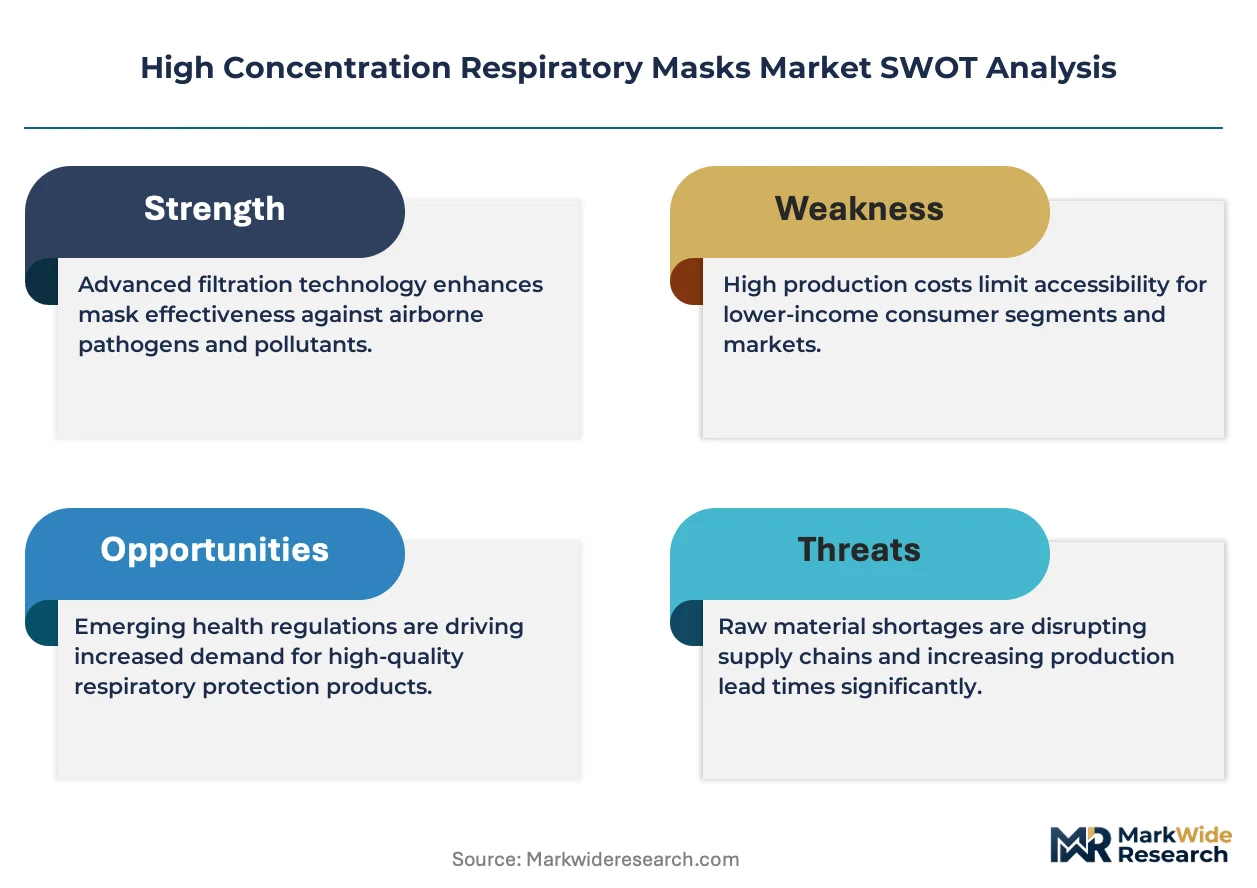
Hospital procurement of high concentration respiratory masks is hardening as post-acute care protocols expand. 3M Company leverages its NIOSH-certified manufacturing footprint to sustain dominant positions in industrial and healthcare channels. Honeywell International Inc. anchors its portfolio with dual-use designs that navigate both OSHA workplace mandates and clinical filtration requirements. MSA Safety competes through specialized emergency response configurations targeting first responder agencies.
High concentration respiratory masks are tight-fitting facepieces engineered to deliver oxygen concentrations exceeding standard ambient levels, typically incorporating silicone or thermoplastic elastomer face seals and adjustable head harness systems to maintain positive seal integrity under positive pressure or demand-flow conditions. Their primary purpose is to protect workers and patients from airborne particulates, toxic gases, or oxygen-deficient atmospheres in hazardous environments. Elastomeric respirators capture durable, reusable margin pools as healthcare systems prioritize total cost of ownership over disposable alternatives. N95 respirators dominate volume in day-to-day occupational safety applications where single-use protocols prevail. Powered air purifying respirators represent the fastest-growing product category as battery efficiency improvements enable extended wear in construction and industrial settings.
NIOSH certification under 42 CFR Part 84 governs filtration efficiency standards in the United States, while OSHA respiratory protection standards mandate fit testing and medical clearance programs that shape employer purchasing cycles. The FDA regulates surgical masks and emergency use authorizations for healthcare applications, creating parallel compliance tracks that manufacturers must satisfy. Stakeholders must monitor evolving harmonization between OSHA workplace rules and FDA clinical device requirements as dual-use product lines blur traditional category boundaries.
Market Dynamics
Hospital procurement hardening across the United States, Germany, and Japan is compressing supplier margins while expanding post-acute care protocols drive volume requirements upward, creating a structural squeeze between cost containment mandates and pandemic preparedness stockpiling imperatives.
Growth Catalysts
- OSHA Respiratory Protection Standards:Mandatory fit testing and medical clearance programs in the United States force employer purchasing cycles toward certified equipment, sustaining replacement demand across industrial and healthcare employers.
- Battery efficiency improvements:Extended wear capabilities in powered air purifying respirators are electrifying adoption in construction and industrial settings where shift-length protection is non-negotiable.
- Post-acute care expansion:Protocol proliferation across Japanese and German healthcare systems is generating institutional volume for high-concentration oxygen delivery configurations in step-down and rehabilitation facilities.
Market Restraints
- Silicone and thermoplastic elastomer input volatility:Face seal material costs fluctuate with petrochemical feedstock pricing, compressing margin pools for reusable elastomeric respirator manufacturers.
- NIOSH certification bottlenecks:42 CFR Part 84 testing queue backlogs in the United States delay product launches and freeze working capital in pre-approval inventory.
- Disposable N95 substitution:Single-use protocols in day-to-day occupational safety applications constrain reusable product penetration despite total cost of ownership advantages.
Strategic Opportunities
- Emergency response agencies:Specialized first responder configurations represent underpenetrated demand pools as MSA Safety's positioning demonstrates viable channel architecture.
- Dual-use product convergence:Designs satisfying both OSHA workplace mandates and FDA clinical filtration requirements blur category boundaries and expand addressable market scope.
- Industrial battery chemistry advances:Lithium-ion efficiency gains in powered air purifying respirators enable new construction subsegments previously blocked by weight and duration constraints.
Industry Challenges
- Harmonization friction between OSHA and FDA:Parallel compliance tracks for workplace and clinical applications force redundant testing protocols and extended certification timelines.
- Positive seal integrity engineering:Adjustable head harness system design for diverse facial geometries requires specialized biomechanical expertise scarce in contract manufacturing bases.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | High Concentration Respiratory Masks Market |
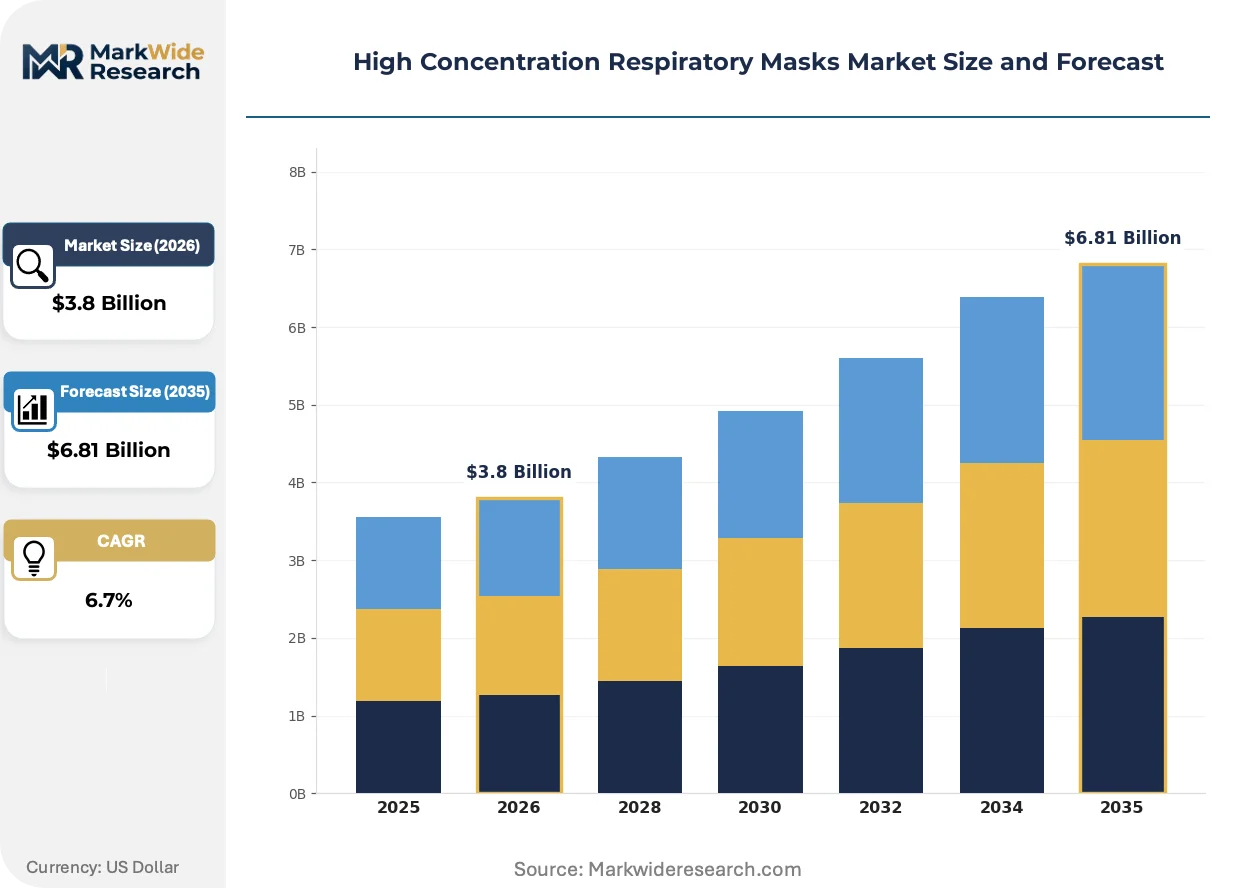
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powered Air Purifying Respirators, Elastomeric Respirators, Surgical Masks, N95 Respirators Application: Industrial Safety, Healthcare, Construction, Emergency Services Usage Scenario: Day-to-Day Use, Emergency Situations, Occupational Safety, Medical Procedures End User: Healthcare Professionals, Construction Workers, Industrial Workers, First Responders |
| Companies Covered | 3M Company, Honeywell International Inc., MSA Safety, Drägerwerk AG & Co. KGaA, Avon Protection, Ansell Ltd., Moldex-Metric, Alpha Pro Tech, Bullard, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High Concentration Respiratory Masks Market Evolving Landscape
Active reshaping in high concentration respiratory masks centers on power system miniaturization, regulatory pathway convergence, and procurement centralization—three forces compressing traditional product lifecycles while expanding performance thresholds.
Powered air purifying respirator technology is electrifying market structure through blower-assisted airflow systems that reduce breathing resistance during extended wear. Construction contractors in the United States are adopting these systems for full-shift deployments previously dominated by passive elastomeric designs. The technology is electrifying competitive positioning by enabling premium pricing for battery-integrated configurations that command three-to-five-year replacement cycles against disposable alternatives.
FDA emergency use authorization pathways for healthcare applications are tightening parallel to NIOSH certification requirements, creating dual-track compliance burdens. Manufacturers must now satisfy 42 CFR Part 84 filtration benchmarks while navigating FDA device classification for surgical mask equivalents. Clinical procurement divisions in United States hospital systems are responding by consolidating supplier lists toward vendors with pre-existing dual certifications, compressing vendor count.
Centralized hospital procurement is consolidating purchasing authority from individual department buyers to system-level supply chain functions. Group purchasing organizations are displacing direct manufacturer relationships in the United States healthcare channel, extracting volume commitments in exchange for preferred supplier status. This concentration is most visible in multi-hospital networks across the American Midwest and Southeast, where standardization mandates override individual clinician preferences.
High Concentration Respiratory Masks Market Segmentation
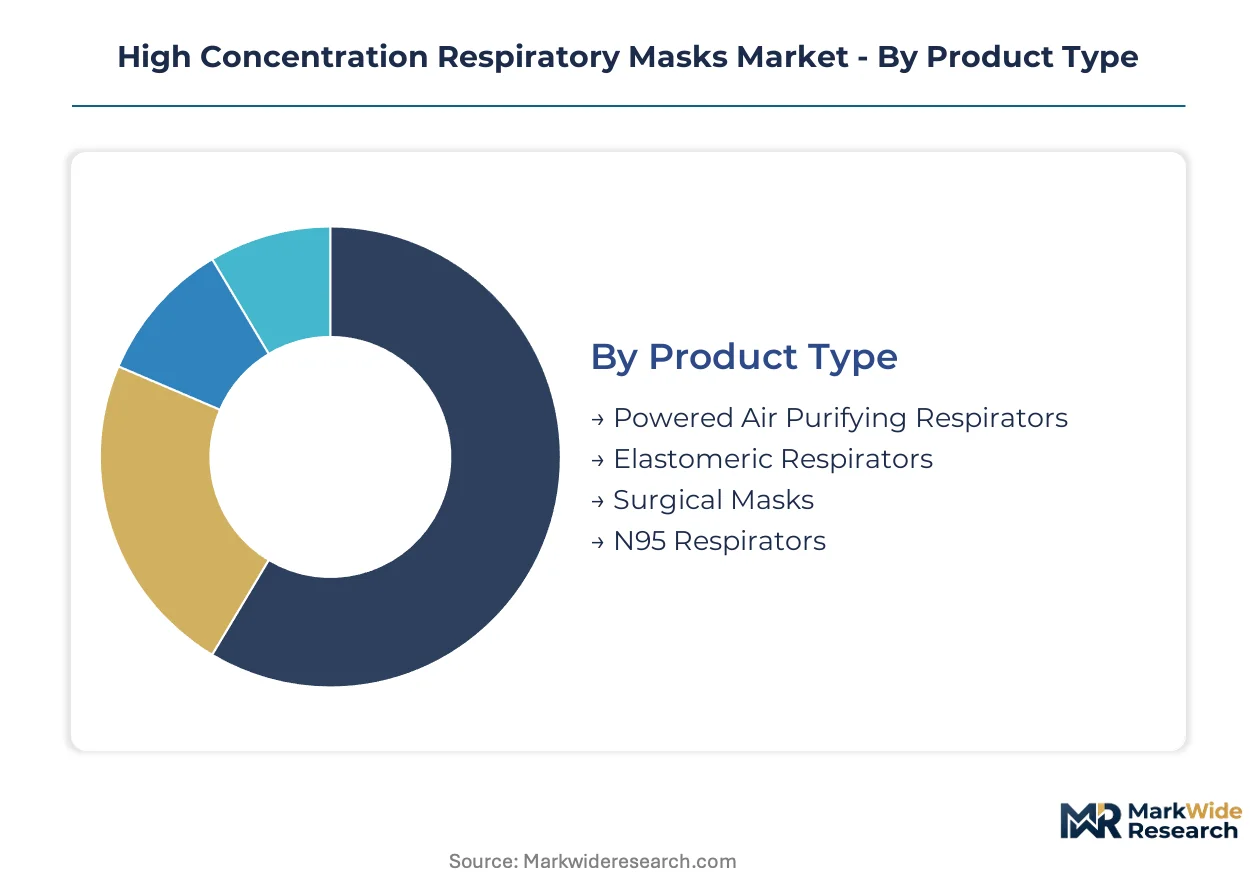
High concentration respiratory masks fragment across four critical dimensions that shape procurement patterns and margin structures. Product type determines certification burden and replacement cadence. Application context drives performance specifications and channel access. Usage scenario dictates inventory positioning and stockpile depth. End user profiles govern fit testing protocols and training requirements.
Product Type:
Procurement cycles diverge sharply based on reusability economics and regulatory certification intensity.
- Powered Air Purifying Respirators:Blower-assisted airflow systems with lithium-ion power packs reduce breathing resistance during extended industrial shifts. Construction contractors in the United States deploy these for full-shift protection where passive designs fail on duration. Battery chemistry improvements are expanding addressable segments previously blocked by weight constraints.
- Elastomeric Respirators:Silicone or thermoplastic elastomer face seals deliver durable, reusable protection with total cost of ownership advantages over disposables. Hospital systems prioritizing pandemic preparedness stockpiles in Germany and Japan specify these for post-acute care protocols despite higher upfront capital requirements.
- Surgical Masks:Loose-fitting barrier devices regulated by FDA for fluid resistance and bacterial filtration in clinical environments.
- N95 Respirators:Single-use filtering facepieces dominating day-to-day occupational safety volume where disposal protocols prevail.
N95 respirators lead on scale; powered air purifying respirators lead on momentum.
Application:
Risk environment severity and regulatory enforcement intensity determine specification thresholds and supplier qualification barriers.
- Industrial Safety:OSHA respiratory protection standards mandate fit testing and medical clearance programs that force employer purchasing toward certified equipment. Manufacturing facilities in the United States sustain replacement demand through compliance-driven refresh cycles.
- Healthcare:FDA device classification and emergency use authorization requirements create dual-track compliance alongside NIOSH certification. Hospital procurement centralization in the American Midwest and Southeast compresses vendor lists toward pre-qualified suppliers.
- Construction:Full-shift exposure to silica and particulate matter drives adoption of powered systems with extended battery life.
- Emergency Services:Specialized first responder configurations require rapid deployment capability and positive pressure operation in oxygen-deficient atmospheres.
Industrial safety commands volume concentration; healthcare exhibits steepest specification escalation.
Usage Scenario:
Frequency and predictability of deployment shape inventory economics and product configuration priorities.
- Day-to-Day Use:Routine occupational exposure protocols in manufacturing and healthcare settings where fit testing programs maintain compliance continuity. Employers amortize equipment costs across predictable replacement schedules.
- Emergency Situations:Unpredictable deployment patterns requiring immediate availability and minimal training burden. Stockpile depth mandates dominate procurement specifications for federal and state emergency response agencies.
- Occupational Safety:Scheduled exposure management with documented hazard assessments and engineering control hierarchies.
- Medical Procedures:Procedure-specific protection requirements in surgical and aerosol-generating contexts with fluid resistance imperatives.
Day-to-day use anchors baseline demand; emergency situations drive premium configuration development.
End User:
Facial geometry diversity and training infrastructure availability segment addressable markets by fit reliability and compliance cost.
- Healthcare Professionals:Diverse facial structures across clinical workforces demand adjustable head harness systems with biometric seal validation. Teaching hospitals in Japan maintain specialized fit testing programs for resident rotation schedules.
- Construction Workers:Extended wear tolerance and compatibility with other personal protective equipment determine adoption. OSHA workplace mandates in the United States enforce employer-funded medical clearance and fit testing programs.
- Industrial Workers:Shift-length protection requirements in chemical processing and manufacturing environments.
- First Responders:Rapid donning capability and communication system integration for fire service and hazardous materials teams.
Healthcare professionals represent the most specification-intensive segment; construction workers deliver volume scale through mandated employer provision.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping manufacturing footprints as cost-of-compliance gaps between jurisdictions widen. Production gravitates toward countries offering streamlined certification pathways while demand concentrates in markets with stringent enforcement regimes.
United States
Hospital procurement centralization across Midwest and Southeast hospital networks is consolidating supplier lists toward dual-certified vendors. OSHA respiratory protection standards mandate fit testing programs that sustain replacement demand across industrial employers. Boston and Houston medical centers anchor post-acute care protocol expansion driving elastomeric respirator stockpiling.
Germany
Post-acute care protocol proliferation in rehabilitation facilities is generating institutional volume for high-concentration oxygen delivery configurations. EU MDR harmonization with NIOSH-equivalent standards is compressing certification timelines for cross-Atlantic suppliers. Baden-Württemberg industrial clusters sustain demand for powered air purifying respirators in precision manufacturing settings.
Japan
Teaching hospitals in Tokyo and Osaka maintain specialized fit testing programs accommodating diverse facial geometries across clinical workforces. METI industrial safety directives enforce employer-funded medical clearance programs in manufacturing. Nagoya automotive manufacturing corridors deploy elastomeric respirators for chemical processing protection.
China
Construction sector expansion in Yangtze River Delta cities is electrifying demand for battery-powered respiratory systems with extended shift coverage. NMPA device classification convergence with international standards is accelerating domestic manufacturer export qualification. Shenzhen industrial zones concentrate powered air purifying respirator assembly operations.
United Kingdom
NHS procurement consolidation is standardizing respiratory protection specifications across integrated care systems. HSE workplace exposure limits enforcement sustains industrial replacement cycles in manufacturing and construction. Midlands manufacturing clusters specify reusable elastomeric configurations for total cost of ownership optimization.
High Concentration Respiratory Masks Market Competitive Landscape
Dual-certification pursuit dominates the current landscape as manufacturers navigate parallel OSHA and FDA compliance tracks. The vendor base stratifies across three tiers: diversified industrial conglomerates with pre-existing NIOSH footprints, specialized respiratory protection pure-plays, and emerging regional fabricators targeting price-sensitive procurement channels. Strategic archetypes include certification-heavy incumbents defending hospital system relationships and battery-technology specialists capturing construction sector electrification. M&A activity concentrates on acquiring NIOSH-approved manufacturing assets, while capacity expansion targets lithium-ion power pack integration for powered air purifying respirator lines.
Among diversified industrial conglomerates, 3M Company and Honeywell International Inc. occupy positions exemplifying the certification-heavy archetype with established regulatory footprints across healthcare and industrial channels. MSA Safety represents the specialized pure-play model, anchoring emergency response agency relationships through dedicated first responder configurations. Drägerwerk AG & Co. KGaA sits within the European-origin tier, leveraging regional regulatory familiarity to navigate EU MDR and German workplace safety mandates.
| Leading Market Players |
|---|
| 3M Company |
| Honeywell International Inc. |
| MSA Safety |
| Drägerwerk AG & Co. KGaA |
| Avon Protection |
| Ansell Ltd. |
| Moldex-Metric |
| Alpha Pro Tech |
| Bullard |
| Others |
Value Network & Pricing Analysis
Certification-grade bifurcation between NIOSH-certified configurations and uncertified commodity alternatives manifests in both pricing power and supply chain configuration. Dual-certified manufacturers command premium positioning through FDA-cleared production lines while single-standard suppliers compete on unit economics in price-sensitive industrial channels.
Pricing Analysis
Distributor margin layers in hospital procurement channels absorb 15-25 points before reaching end-user pricing, compressing manufacturer net realization. Three-tier pricing structure across premium elastomeric systems, standard powered air purifying units, and economy disposable N95 alternatives reflects certification burden and reusability economics. Cost compression in silicone face seal components intensifies pricing pressure as petrochemical feedstock volatility feeds through thermoplastic elastomer input costs. Group purchasing organizations exhibit highest price sensitivity through volume-commitment negotiations, while emergency response agencies prioritize performance specifications over unit economics.
Supply Chain Analysis
Refurbishment flows for elastomeric respirators create reverse-logistics value recovery in healthcare systems prioritizing total cost of ownership optimization. Manufacturing concentration centers on China, the United States, and Germany for NIOSH and CE-marked production, with Mexico emerging as nearshore assembly for North American hospital supply. Lithium-ion battery packs, silicone elastomer compounds, and filtration media membranes constitute critical input dependencies. Single-source vulnerability in N95 meltblown filtration fabric constrains surge capacity responsiveness. Distribution runs through group purchasing organizations and industrial safety distributors with direct-to-hospital contracts for high-volume health system networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory compounding accelerates as OSHA's respiratory protection standard updates and FDA emergency use authorization pathway refinements drive replacement demand across dual-use product categories.
For Market Incumbents: Cement hospital system relationships through pre-positioned dual-certification portfolios that satisfy both OSHA workplace mandates and FDA clinical device requirements. Deepen backward integration into silicone face seal molding capacity to insulate margin pools from petrochemical feedstock volatility. Defend against battery-technology specialists by accelerating lithium-ion power pack integration timelines for powered air purifying respirator lines. For New Entrants and Emerging Players: Launch via specialized emergency response configurations targeting underpenetrated first responder agency demand pools where MSA Safety's positioning demonstrates viable channel architecture. Penetrate construction sector electrification segments through lightweight powered air purifying designs enabled by industrial battery chemistry advances. Pursue white-label manufacturing partnerships with established NIOSH-certified facilities to bypass 42 CFR Part 84 testing queue backlogs. For Investors and Strategic Acquirers: Consolidation pressure builds where dual-certification capabilities command scarcity premiums in procurement centralization environments. Long-term viability favors manufacturers with pre-existing regulatory footprints across healthcare and industrial channels over pure-play commodity suppliers. Target acquisition archetypes include battery-technology specialists with powered air purifying respirator integration capabilities and regional fabricators with NIOSH-approved manufacturing assets. Monitor NIOSH certification queue duration as inflection indicator for working capital efficiency and product launch velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Certification Investment | Parallel OSHA and FDA compliance tracks expand addressable market scope across healthcare and industrial channels. |
| Battery Chemistry Advancement | Lithium-ion efficiency gains enable extended-shift powered air purifying respirator deployment in construction subsegments. |
| Backward Integration into Elastomers | Captive silicone face seal production insulates margin pools from petrochemical feedstock price volatility. |
| Emergency Response Channel Development | Specialized first responder configurations access underpenetrated demand pools with premium pricing tolerance. |
| Group Purchasing Organization Alignment | Volume commitments through GPO contracts secure preferred supplier status in centralized hospital procurement. |
Research Methodology
Multiple input streams — regulatory filing analysis, procurement database extraction, and manufacturing capacity surveys — were reconciled against primary fieldwork with hospital supply chain directors, industrial safety officers, and respiratory protection product managers. Secondary validation drew from OSHA enforcement data, FDA 510(k) and emergency use authorization filings, NIOSH certified equipment lists, and hospital group purchasing organization contract disclosures. Bottom-up demand modeling across product type, application, and end-user segments was cross-checked against top-down market sizing through the analysis window.
Historical shipment trajectories were cross-referenced against expert panel inputs from respiratory protection manufacturers and healthcare procurement executives. Segmentation dimensions modeled include product type reusability economics, application context risk severity, usage scenario deployment frequency, and end-user facial geometry diversity requirements. CAGRs were derived through logarithmic trend fitting with scenario-weighted probability distributions. Forecast inputs incorporated battery technology advancement curves, regulatory harmonization timelines between OSHA and FDA, and hospital procurement centralization velocity metrics.
Forecast precision tightens around the base case; tail outcomes carry wider variance under NIOSH certification backlog extensions or petrochemical price shock scenarios. Periodic stress-testing of base assumptions is recommended given regulatory pathway convergence uncertainties and pandemic preparedness stockpiling cyclicality.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Personal Health
Sleep Mask Market
Personal Health
North America Workplace Wellness Market
Personal Health
Medical Wellness Market
Personal Health
US Vaginal Moisturizers and Lubricants Market
Personal Health
Maternity and Personal Care Market
Personal Health
Asia Pacific Hair Loss Treatment Products Market
Personal Health
Patient Health Management Market
Personal Health
Tick Repellent Market
Personal Health
Tongue Scraper Market
Personal Health
North America Hair Loss Treatment Products Market
Personal Health
Asia-Pacific Mobile Health Market
Personal Health
Blackhead Removing Vacuum Market
Personal Health
Asia-Pacific Maternity & Personal Care Market
Personal Health
Hair Restoration Market
Personal Health
Feminine Hygiene Market
Personal Health
Infrared Sauna Blankets Market