
 Maternity and Personal Care Market | 2026-2036
Maternity and Personal Care Market Size, Share, and Industry Trends Forecast 2026-2036
Maternity and Personal Care Market Foresight
Pharmacy distribution is narrowing as a primary channel for maternity and personal care products, with digital platforms and specialty baby boutiques capturing incremental volume. Johnson & Johnson leverages its heritage in clinical-grade formulations to sustain credibility among healthcare professionals recommending postpartum recovery items. Procter & Gamble competes through manufacturing scale that anchors its baby care portfolio in mass retail. Lansinoh Laboratories specializes in breastfeeding accessories, occupying a defensible niche against broader personal care conglomerates.
Maternity and personal care encompasses purpose-designed garments, topical formulations, and infant hygiene products engineered with dermatological safety parameters such as pH-balanced compositions and hypoallergenic certifications, serving gestational health maintenance and neonatal wellbeing. Skin care commands the deepest margin pool due to premium positioning around stretch-mark prevention and scar reduction serums. Baby care products represent the fastest-growing product type as ingredient transparency becomes a non-negotiable purchase criterion. Postpartum recovery applications lead in average revenue per user because of extended purchase cycles spanning weeks to months after delivery.
FDA oversight of topical maternity treatments and baby skin care establishes baseline safety thresholds that shape product development timelines and labeling requirements. The EU Green Deal and REACH chemical restrictions are forcing reformulation of preservatives and fragrances across export-oriented portfolios. Stakeholders must monitor evolving state-level clean beauty legislation in the United States, where California's Proposition 65 expansion and emerging right-to-know laws threaten conventional ingredient profiles without rapid substitution strategies.
Market Dynamics
Clean-label ingredient mandates from the EU Green Deal and REACH are forcing wholesale reformulation across skin care and baby care portfolios, compressing product development timelines while elevating compliance costs for export-oriented manufacturers.
Growth Catalysts
- REACH chemical restrictions:The EU Green Deal's tightening standards on preservatives and fragrances is accelerating R&D investment in bio-based alternatives, creating first-mover advantages for compliant formulators.
- Hospital maternity wards:Postpartum service expansion across institutional buyers is pulling demand for clinical-grade recovery garments and dermatologically tested topical applications.
- pH-balanced compositions:Neonatal safety protocols are mandating hypoallergenic certifications, opening premium positioning for formulations meeting dermatological safety parameters.
Market Restraints
- Plant-derived surfactant costs:Input volatility for squalane and shea butter alternatives is squeezing margin pools in mid-tier skin care segments.
- EU regulatory concentration:Export-dependent manufacturers face asymmetric compliance burdens as ECHA restrictions outpace other jurisdictions.
- Silicone substitution limitations:Technical performance gaps in scar reduction serums without dimethicone are delaying clean-label transitions in postpartum recovery applications.
Strategic Opportunities
- California right-to-know laws:Proposition 65 expansion is creating regulatory tailwinds for transparency-first brands willing to preempt federal standards.
- Specialty baby boutiques:Channel innovation through curated retail experiences is capturing pharmacy-displaced volume in urban centers.
- Wearable lactation tech:Convergence of textile engineering and biosensor integration is opening subscription revenue models for nursing accessory manufacturers.
Industry Challenges
- Cosmetic chemist scarcity:Formulation expertise bridging dermatological safety and clean-label performance commands premium compensation, constraining mid-cap R&D expansion.
- ISO 16128 compliance timelines:Natural and organic certification complexity is extending go-to-market cycles by quarters for repositioned portfolios.
- Legacy ERP integration:Supply chain traceability requirements for ingredient transparency are forcing costly system overhauls at contract manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Maternity and Personal Care Market |
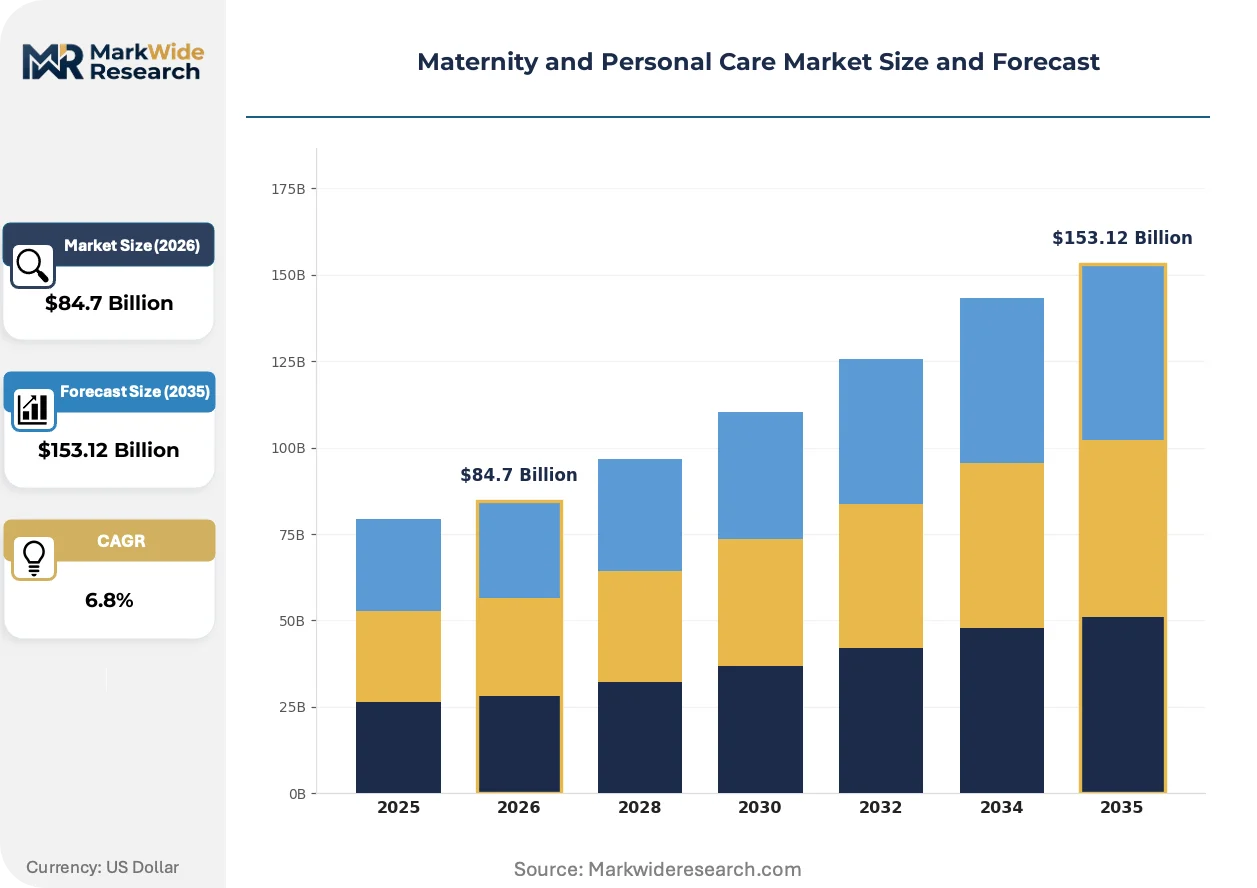
| Market Size in 2026 | $84.7 Billion |
| Market Size in 2035 | $153.12 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Maternity Wear, Nursing Accessories, Baby Care Products, Skin Care Application: Postpartum Recovery, Daily Use, Special Occasions, Breastfeeding End User: Expectant Mothers, New Mothers, Caregivers, Healthcare Professionals Distribution Channel: Online Retail, Specialty Stores, Pharmacies, Baby Boutiques |
| Companies Covered | Pfizer Inc., Church & Dwight Co., Inc., Johnson & Johnson, GlaxoSmithKline plc, Abbott Laboratories, Procter & Gamble Company, Reckitt Benckiser Group plc, Lansinoh Laboratories, Bayer Aktiengesellschaft, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Maternity and Personal Care Market Shifts & Advancements
Digital platforms are disintermediating traditional pharmacy distribution while regulatory pressure and ingredient transparency reshape product architecture across maternity and neonatal care segments.
AI-driven formulation platforms are virtualizing the R&D pipeline for stretch-mark prevention serums. Mid-sized skin care laboratories in South Korea and Germany are adopting these tools at accelerating pace, compressing development cycles from concept to stability testing. The technology is virtualizing competitive moats previously built on in-house dermatological expertise, enabling smaller players to match incumbent clinical validation protocols.
REACH Annex XVII restrictions on microplastics are forcing reformulation of rinse-off baby care products across European export portfolios. Manufacturers must substitute polyethylene beads with cellulose or mineral alternatives before enforcement deadlines, with baby shampoo and bath foam categories facing the steepest technical adaptation curves. German and French formulators are responding fastest, leveraging existing natural cosmetic infrastructure to maintain shelf presence.
Subscription-based replenishment models are capturing nursing accessory and postpartum recovery garment demand previously served through episodic retail purchases. Direct-to-consumer platforms with personalized sizing algorithms are displacing hospital gift shop and big-box baby registry channels, with highest penetration visible among millennial first-time mothers in United States metropolitan markets.
Maternity and Personal Care Market Segmentation
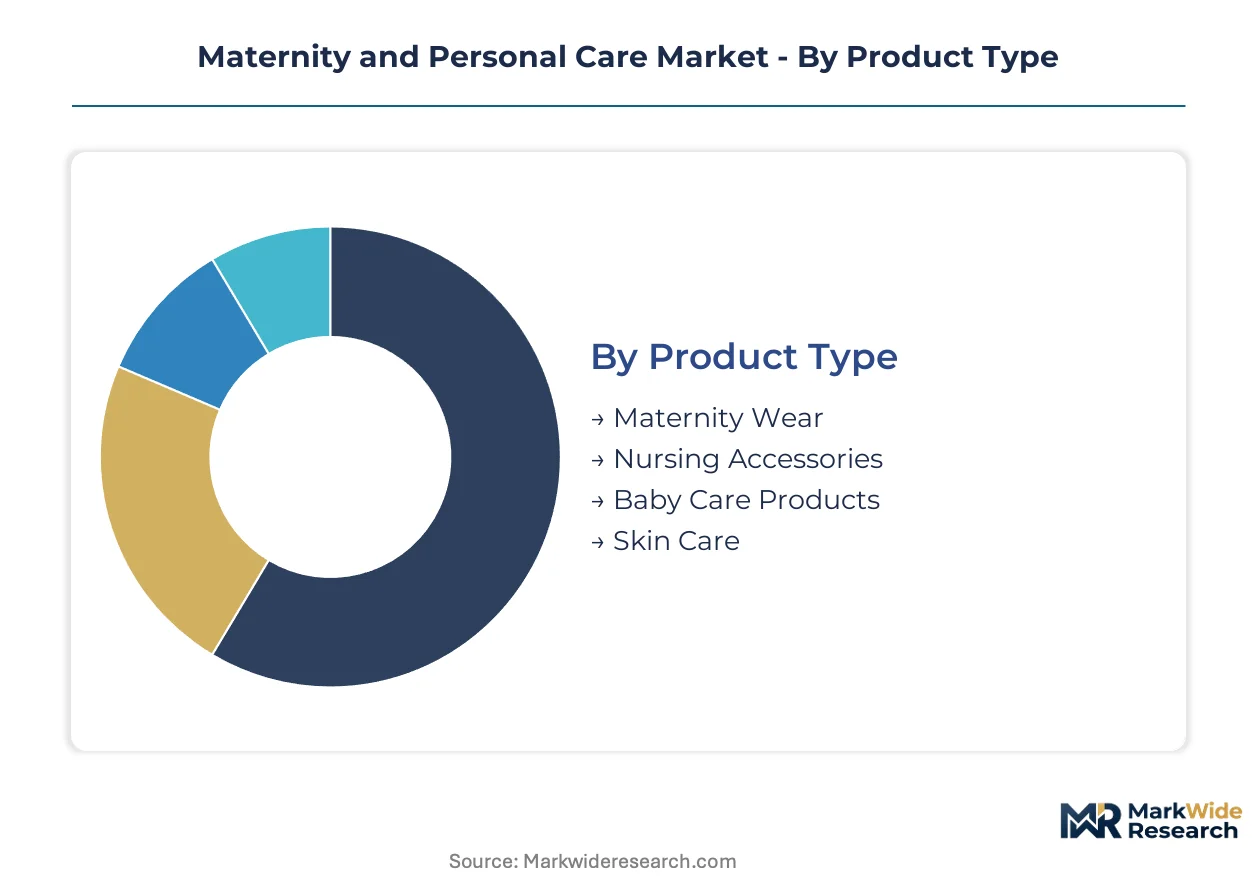
Segmentation in maternity and personal care reveals divergent margin profiles and regulatory exposure across product architectures. Understanding these fault lines enables targeted portfolio positioning against tightening ingredient mandates and shifting channel economics.
Product Type:
Mature categories with established dermatological protocols coexist alongside emerging segments where clean-label transitions are accelerating R&D cycles.
- Skin Care:Formulations engineered for stretch-mark prevention and scar reduction command premium positioning through pH-balanced compositions and hypoallergenic certifications. Demand concentrates in the United States where postpartum recovery protocols emphasize dermatological safety parameters, though REACH Annex XVII restrictions on microplastics are forcing rapid reformulation of rinse-off variants.
- Baby Care Products:Infant hygiene formulations with transparency-first ingredient disclosure represent the steepest expansion trajectory as millennial parents reject conventional preservative systems. EU Green Deal mandates on chemical restrictions are compressing development timelines for export-oriented manufacturers serving German and French retail channels.
- Maternity Wear:Purpose-designed garments with textile engineering integration support gestational comfort and nursing functionality.
- Nursing Accessories:Breastfeeding support equipment including pumps, pads, and storage systems anchors subscription revenue models through direct-to-consumer platforms.
Skin Care handles the majority of throughput; Baby Care Products is the fastest mover on share.
Application:
Application segments stratify by purchase cycle duration and reimbursement adjacency, with extended-use scenarios supporting higher lifetime value economics.
- Postpartum Recovery:Extended purchase cycles spanning weeks to months after delivery generate the deepest revenue per user across topical applications and recovery garments. Hospital maternity wards in the United States are expanding service offerings to capture this demand, pulling clinical-grade formulations through institutional procurement channels.
- Breastfeeding:Lactation support applications benefit from wearable technology convergence and biosensor integration, opening recurring revenue streams. Demand concentrates among first-time mothers in United States metropolitan markets where digital platforms displace traditional pharmacy distribution.
- Daily Use:Routine hygiene and comfort applications serve baseline consumption with lower switching costs.
- Special Occasions:Event-driven purchases for baby showers and hospital visits exhibit episodic demand patterns.
Postpartum Recovery captures the highest revenue intensity per user; Breastfeeding is gaining share fastest through technology-enabled subscription models.
End User:
End user categories reflect distinct decision-making hierarchies and information-seeking behaviors that shape channel strategy and messaging architecture.
- New Mothers:First-time parents with elevated risk sensitivity drive premium positioning for hypoallergenic certifications and clean-label transparency. Digital platforms and specialty baby boutiques in urban United States centers capture this cohort's demand previously served through pharmacy channels.
- Expectant Mothers:Pre-natal preparation purchases concentrate in stretch-mark prevention and maternity wear categories with extended consideration cycles.
- Caregivers:Secondary purchasers including family members and nannies exhibit price sensitivity and gift-registry-driven selection criteria.
- Healthcare Professionals:Institutional recommenders including lactation consultants and postpartum nurses influence brand credibility through clinical validation requirements.
New Mothers represent the primary volume anchor; Healthcare Professionals are expanding their influence fastest as hospital maternity wards deepen postpartum service integration.
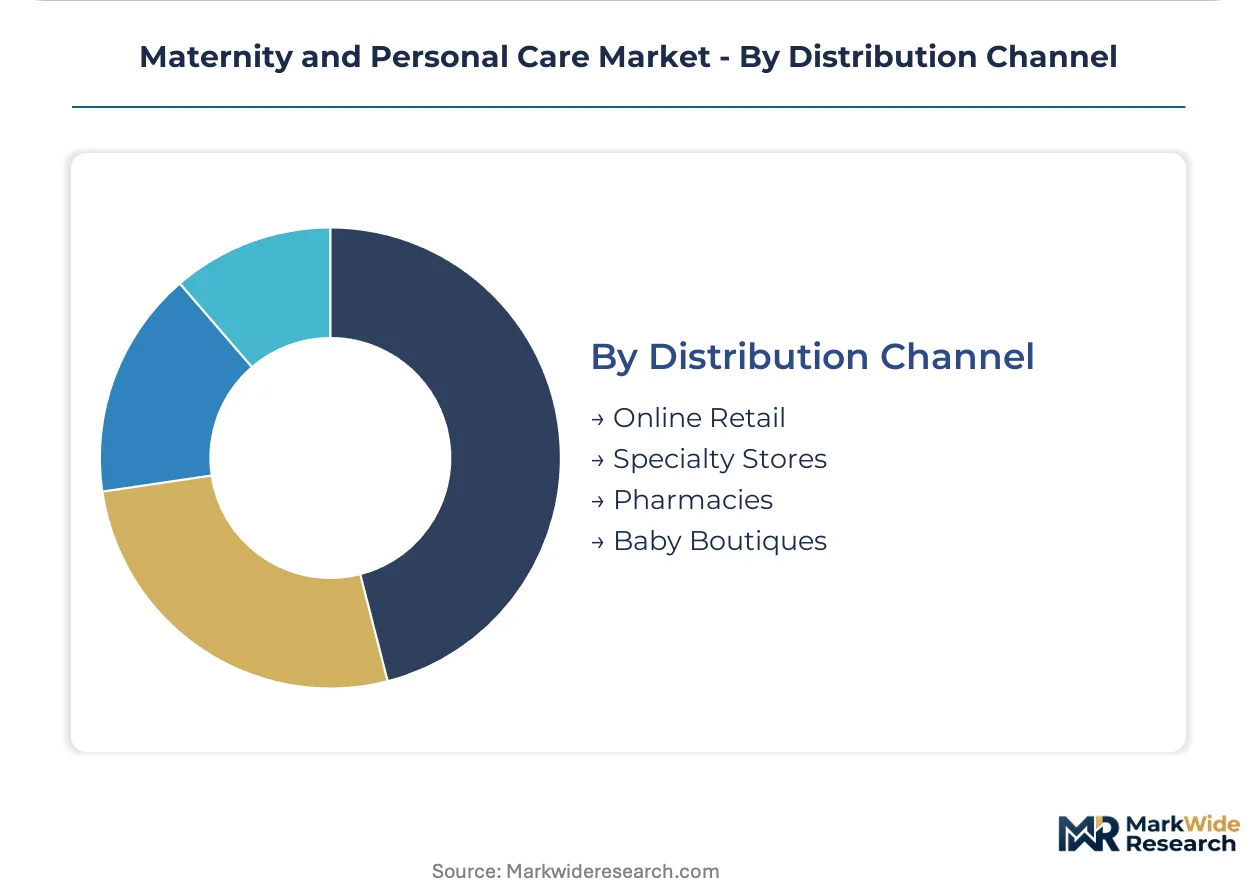
Distribution Channel:
Channel economics are restructuring as digital platforms disintermediate legacy pharmacy infrastructure and curated retail experiences capture urban demand.
- Online Retail:Direct-to-consumer platforms with personalized sizing algorithms and subscription replenishment models are displacing episodic retail purchases. Highest penetration appears among millennial first-time mothers in United States metropolitan markets where convenience and transparency outweigh traditional channel loyalty.
- Baby Boutiques:Curated specialty retail in urban centers captures pharmacy-displaced volume through experiential positioning and ingredient education. California's Proposition 65 expansion creates regulatory tailwinds for transparency-first brands willing to preempt federal standards through these channels.
- Specialty Stores:Dedicated maternity and infant care retailers serve informed consumers with extended product education.
- Pharmacies:Traditional drugstore distribution is narrowing as primary channel for maternity and personal care products, though clinical-grade postpartum recovery items maintain presence through healthcare professional recommendation.
Online Retail handles the majority of throughput; Baby Boutiques is climbing the fastest as curated urban retail captures pharmacy-displaced volume.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU Green Deal mandates and FDA safety protocols are reshaping formulation standards across export corridors, while hospital procurement expansion and digital platform penetration drive divergent channel economics in mature versus emerging markets.
United States
Premium nursing accessories and recovery-focused maternity wear command sustained consumer willingness to pay among millennial first-time mothers. FDA oversight of topical maternity treatments and baby skin care establishes baseline safety thresholds that compress product development timelines. Hospital maternity wards in metropolitan centers deepen postpartum service integration, pulling clinical-grade recovery garments through institutional procurement channels.
Germany
REACH Annex XVII restrictions on microplastics and preservatives accelerate reformulation of rinse-off baby care products across domestic and export portfolios. ECHA chemical restrictions outpace other jurisdictions, creating asymmetric compliance burdens for manufacturers serving German retail channels. Berlin and Frankfurt clusters host natural cosmetic infrastructure that enables rapid adaptation to clean-label mandates.
France
Transparency-first ingredient disclosure drives millennial parent rejection of conventional preservative systems in infant hygiene formulations. ANSM pharmaceutical oversight intersects with EU Green Deal chemical restrictions to elevate dermatological safety parameters. Paris and Lyon specialty baby boutiques capture pharmacy-displaced volume through curated retail experiences and ingredient education.
China
Rising middle-class consumption of premium postpartum recovery protocols expands demand for clinical-grade topical applications and textile-engineered nursing garments. NMPA cosmetic registration requirements and GB standards for infant products shape import compliance timelines. Shanghai and Beijing digital platforms disintermediate traditional pharmacy distribution through subscription replenishment models.
India
Urban first-time mothers in metropolitan markets exhibit elevated risk sensitivity driving hypoallergenic certification demand across skin care and baby care segments. CDSCO pharmaceutical oversight and emerging FSSAI cosmetic regulations establish evolving safety frameworks. Mumbai and Bangalore clusters concentrate specialty retail expansion targeting pharmacy-channel displacement.
Maternity and Personal Care Market Competitive Landscape
On the supply side, the industry is consolidating around three structural tiers: diversified healthcare conglomerates with clinical validation heritage, mass-market consumer goods manufacturers with manufacturing scale advantages, and specialized nursing accessory developers with defensible niche positioning. Strategic archetypes include clinical-credibility players leveraging healthcare professional recommendation networks, scale-driven operators anchoring mass retail shelf presence, and subscription-model specialists capturing direct-to-consumer loyalty. Dominant competitive moves encompass portfolio diversification into wearable lactation technology and geographic expansion through regulatory-compliant reformulation for EU export corridors.
Among diversified healthcare conglomerates, Johnson & Johnson and Pfizer Inc. exemplify the clinical-credibility archetype through heritage in dermatological safety protocols and healthcare professional channel access. Procter & Gamble Company represents the scale-driven tier with mass retail manufacturing infrastructure. Lansinoh Laboratories occupies the specialist position within breastfeeding accessories, anchoring defensible niche positioning against broader personal care portfolios.
| Leading Market Players |
|---|
| Pfizer Inc. |
| Church & Dwight Co., Inc. |
| Johnson & Johnson |
| GlaxoSmithKline plc |
| Abbott Laboratories |
| Procter & Gamble Company |
| Reckitt Benckiser Group plc |
| Lansinoh Laboratories |
| Bayer Aktiengesellschaft |
| Others |
Supply & Pricing Matrix
Shea butter and squalane sourcing concentration in West African cooperatives and South American botanical suppliers anchors margin compression dynamics in mid-tier skin care segments, with downstream price power flowing to brands commanding hypoallergenic certification premiums.
Pricing Analysis
Volume-discount tiering structures separate subscription-based nursing accessory replenishment from episodic retail purchases, with direct-to-consumer platforms capturing loyalty through personalized sizing algorithms. Price differentiation hinges on dermatological certification grade and clean-label ingredient transparency, with EU Green Deal compliance costs elevating premium positioning. Pricing pressure stems from plant-derived surfactant input volatility squeezing mid-tier skin care margins. New mothers in United States metropolitan markets exhibit lowest price sensitivity for postpartum recovery applications, while caregivers selecting gift-registry items show highest elasticity.
Supply Chain Analysis
Extended payment terms from European retail buyers are forcing working capital strain on contract manufacturers serving REACH-compliant reformulation cycles. Manufacturing concentrates in Germany, France, and China, with raw material dependencies spanning shea butter from West Africa, squalane from olive and sugarcane sources, and cellulose microbead substitutes for rinse-off baby care. Single-source vulnerability in bio-based preservative supply threatens clean-label transition timelines. Distribution runs through direct-to-consumer platforms and specialty baby boutiques displacing legacy pharmacy infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution defense imperatives as AI-driven formulation platforms virtualize R&D competitive moats previously built on proprietary dermatological expertise.
For Market Incumbents: Insulate formulation expertise through captive hiring of cosmetic chemists bridging dermatological safety and clean-label performance, while anchoring hospital maternity ward procurement relationships against digital-native entrants. REACH Annex XVII compliance investment serves as a defensive moat against mid-cap competitors lacking natural cosmetic infrastructure. For New Entrants and Emerging Players: Pursue wearable lactation technology convergence in United States metropolitan markets, where biosensor-enabled nursing accessories remain underpenetrated by established personal care conglomerates. Subscription revenue models with personalized sizing algorithms offer the most penetrable go-to-market angle against episodic retail incumbents. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across clean-label reformulation infrastructure as ISO 16128 certification complexity extends go-to-market cycles. Long-term viability favors acquisition targets with existing natural cosmetic manufacturing footprints in Germany or France. The signal to watch is ECHA restriction expansion pace relative to FDA alignment timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Clean-Label Reformulation Investment | REACH Annex XVII compliance secures EU market access ahead of enforcement deadlines. |
| Hospital System Partnership | Institutional procurement relationships anchor clinical-grade recovery garment volume. |
| Direct-to-Consumer Platform Launch | Subscription replenishment models capture millennial first-time mother loyalty. |
| Wearable Lactation Technology Development | Biosensor integration opens recurring revenue streams in nursing accessories. |
| Specialty Baby Boutique Distribution | Curated urban retail captures pharmacy-displaced volume through transparency positioning. |
Research Methodology
A spread of perspectives from brand managers at personal care conglomerates, category buyers at specialty baby boutiques, procurement leads at hospital systems, and regulatory affairs specialists converged on the working assumptions shaping this analysis. Primary interview insights combined with secondary validation from FDA 510(k) filings, ECHA restriction updates, customs trade data for shea butter and squalane imports, and Nielsen retail audit data. Bottom-up segment sizing and top-down macroeconomic anchoring triangulated volume and value estimates.
Demand-supply-balance framing anchored the analytical framework across the projection horizon, with segmentation dimensions spanning product type, application, end user, and distribution channel. CAGRs derived from modeled adoption curves for subscription replenishment models and clean-label formulation penetration. Industry-specific forecast inputs included REACH Annex XVII enforcement timelines and hospital maternity ward service expansion rates.
The forecast holds incumbent behavior within observed patterns; aggressive moves by AI-enabled formulation platforms or rapid FDA-EU regulatory convergence would shift outcomes. Macroeconomic deviation, accelerated ECHA restriction expansion, or breakthrough biosensor integration in wearable lactation technology would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Personal Health
Tongue Scraper Market
Personal Health
Asia Health Check-Ups Market
Personal Health
Global Health and Wellness Market
Personal Health
Feminine Hygiene Market
Personal Health
Biohacking Market
Personal Health
Reusable Face Mask Market
Personal Health
Sextech and Sexual Wellness Market
Personal Health
Medical Wellness Market
Personal Health
Health Check-Up Market
Personal Health
South America Hair Loss Treatment Products Market
Personal Health
Menstrual Cup Market
Personal Health
Global OTC Hair Loss Treatment Market
Personal Health
Asia-Pacific Mobile Health Market
Personal Health
PTBCHA Market
Personal Health
Obesity Treatment Market
Personal Health
Maternity Personal Care Products Market