
 Patient Health Management Market | 2026-2036
Patient Health Management Market Size, Share, and Industry Trends Forecast 2026-2036
Patient Health Management Market Analytics
Buyer concentration among large hospital networks and integrated delivery systems is realigning vendor priorities across the patient health management landscape. Epic Systems Corporation leverages deep electronic health record integration to anchor enterprise contracts with major health systems. Oracle Health sustains competitive positioning through cloud infrastructure scale and database architecture that supports population-level analytics. Koninklijke Philips N.V. differentiates via connected device ecosystems that feed real-time biometric streams into care coordination workflows.
Patient health management encompasses the systematic coordination, monitoring, and optimization of individual care trajectories through digital platforms that aggregate clinical, behavioral, and operational data across multiple touchpoints. These systems typically integrate FHIR-compliant APIs, HL7 messaging protocols, and predictive risk stratification algorithms to enable proactive intervention before acute episodes materialize. Cloud-based solutions occupy the dominant deployment architecture as health systems prioritize scalability and reduced capital expenditure, while artificial intelligence segments capture accelerating investment flows due to clinical decision-support applications. Remote monitoring devices represent a mature hardware category with established reimbursement pathways, whereas blockchain-enabled identity and consent management remains nascent with concentrated pilot activity among privacy-sensitive European deployments.
FDA oversight of clinical decision-support software and HIPAA privacy requirements shape product architecture and liability frameworks for US-facing vendors, while EMA medical device regulations and GDPR data governance standards constrain European platform design. Health systems must evaluate vendor roadmaps against evolving FDA guidance on AI-enabled diagnostic tools and the EU AI Act's risk classification schema for patient-facing algorithms. Stakeholders should monitor interoperability mandates from ONC and emerging cybersecurity disclosure requirements that will reshape procurement criteria and vendor qualification protocols.
Market Dynamics
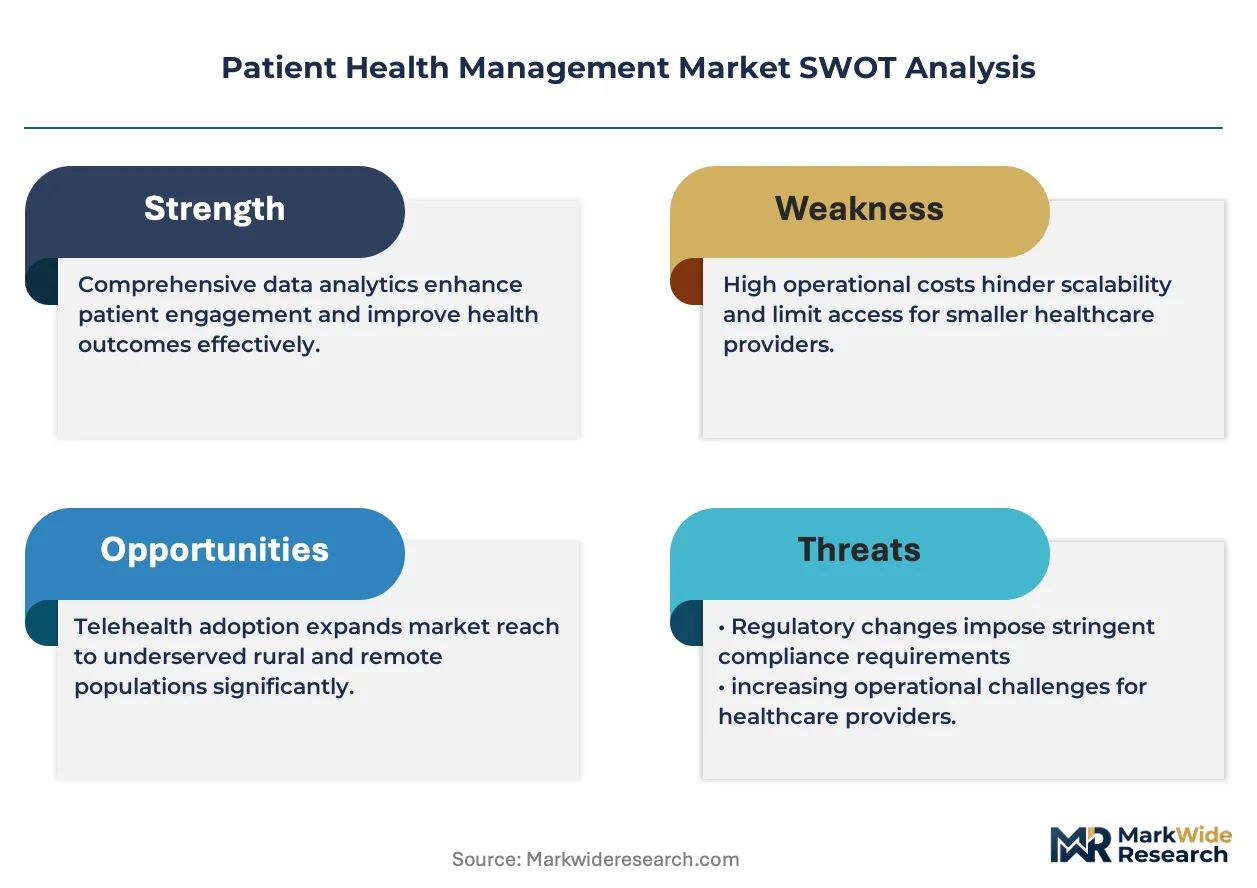
Hospital network consolidation is compressing vendor margins and forcing platform providers to restructure pricing around enterprise-wide deployment commitments rather than modular subscriptions.
Growth Catalysts
- FHIR API Mandates:ONC interoperability rules require standardized data exchange, compelling health systems to upgrade legacy infrastructure and adopt integrated patient health management platforms.
- Remote Patient Monitoring Reimbursement:CMS expanded CPT codes for continuous physiologic monitoring, accelerating provider investment in connected care programs across Medicare populations.
- Cloud Infrastructure Scale:Hyperscaler data center expansion into healthcare-compliant regions reduces latency for real-time analytics and enables multi-tenant platform architectures.
Market Restraints
- Specialized Clinical Informaticist Shortage:Health systems face 18-month average hiring timelines for professionals capable of configuring population health algorithms and care pathway protocols.
- Legacy EHR Lock-in:Proprietary data models from dominant incumbent vendors create switching costs that delay competitive platform procurement cycles.
- Cybersecurity Liability Exposure:State-level breach notification laws and ransomware litigation trends elevate cyber insurance premiums for cloud-hosted patient data platforms.
Strategic Opportunities
- Behavioral Health Integration:Unmet demand for coordinated mental and physical care pathways creates whitespace for platforms combining psychiatric diagnostic instruments with chronic disease protocols.
- EU AI Act Compliance Services:Risk classification requirements for patient-facing algorithms generate advisory and certification revenue streams for vendors with established quality management systems.
- Home-Based Acute Care:Hospital-at-home waivers and remote monitoring infrastructure enable platform extensions into post-acute settings previously served by facility-based providers.
Industry Challenges
- Interoperability Implementation Complexity:Health information exchanges and payer data feeds require custom mapping work that extends deployment timelines and strains professional services capacity.
- Algorithmic Bias Validation:FDA guidance on AI-enabled clinical decision-support demands retrospective performance audits across demographic subgroups, complicating product maintenance cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Patient Health Management Market |
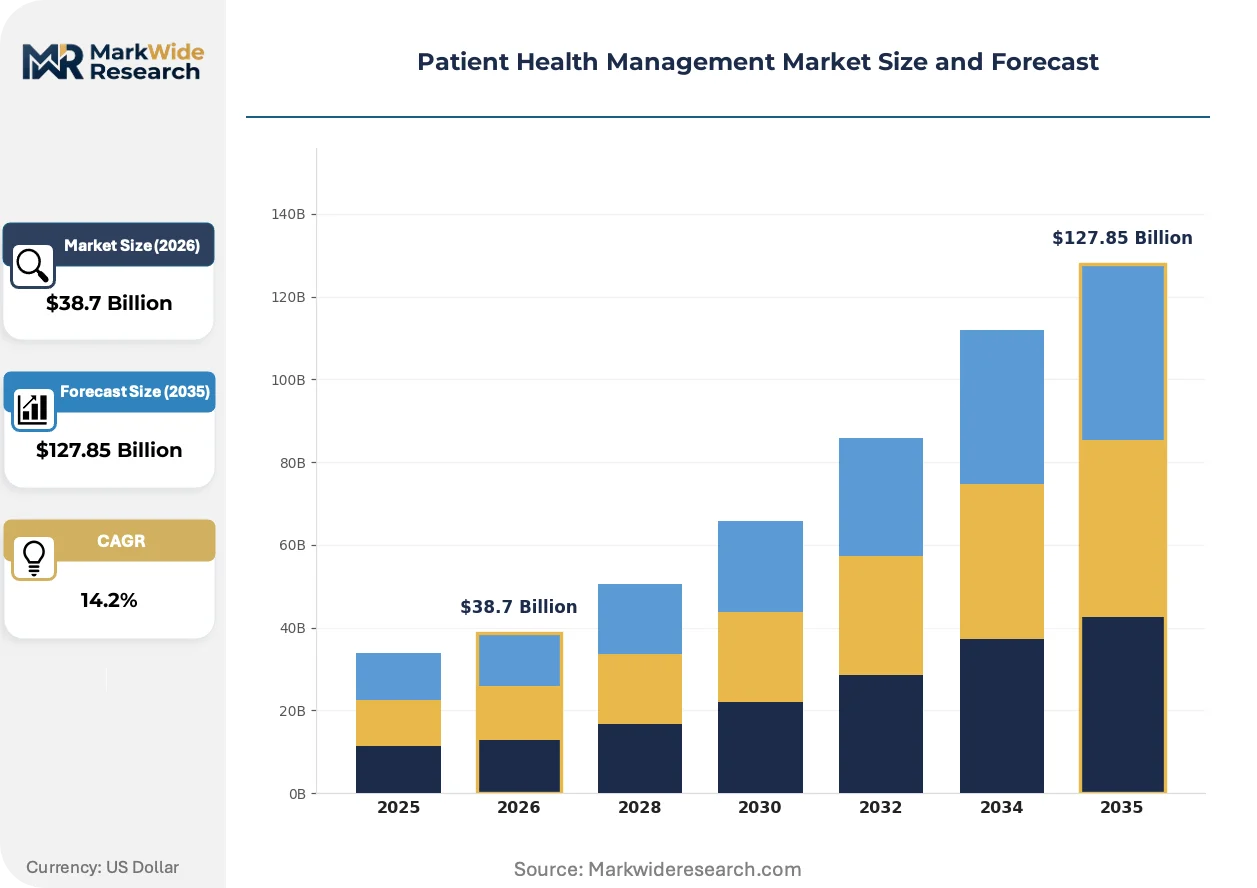
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $127.85 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Remote Monitoring Devices, Health Apps, Wearable Technology, Medication Management Systems Delivery Mode: Cloud-Based Solutions, On-Premise Solutions, Mobile Applications, Web Platforms End User: Healthcare Providers, Patients, Caregivers, Health Insurers Technology: Artificial Intelligence, Machine Learning, Blockchain, Internet of Things |
| Companies Covered | Epic Systems Corporation, Oracle Health, athenahealth, Veradigm LLC, McKesson Corporation, IBM, Koninklijke Philips N.V., GE Healthcare, ZeOmega, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Patient Health Management Market Evolving Landscape
Edge computing architectures and ambient clinical intelligence are redistributing data processing loads across care delivery networks. These shifts alter where clinical decisions are executed and who controls the underlying infrastructure.
Federated learning is decentralizing model training for predictive risk algorithms. Health systems in Germany and the Netherlands are piloting cross-institutional protocols that train population health models without centralizing patient records. This architecture compresses data governance overhead while preserving GDPR-compliant data localization.
The EU AI Act's risk classification framework is restructuring product development roadmaps for European market entry. High-risk patient-facing algorithms now require conformity assessments and post-market monitoring systems that add 12-18 months to commercialization timelines. Vendors are responding by segmenting product portfolios between diagnostic support tools and administrative automation features.
Consolidated procurement by integrated delivery systems is compressing vendor sales cycles and elevating outcome-based contracting terms. Large health systems in Texas and California now require guaranteed readmission reduction metrics as contract conditions. This shifts vendor compensation toward performance milestones rather than seat-based subscriptions.
Patient Health Management Market Segmentation
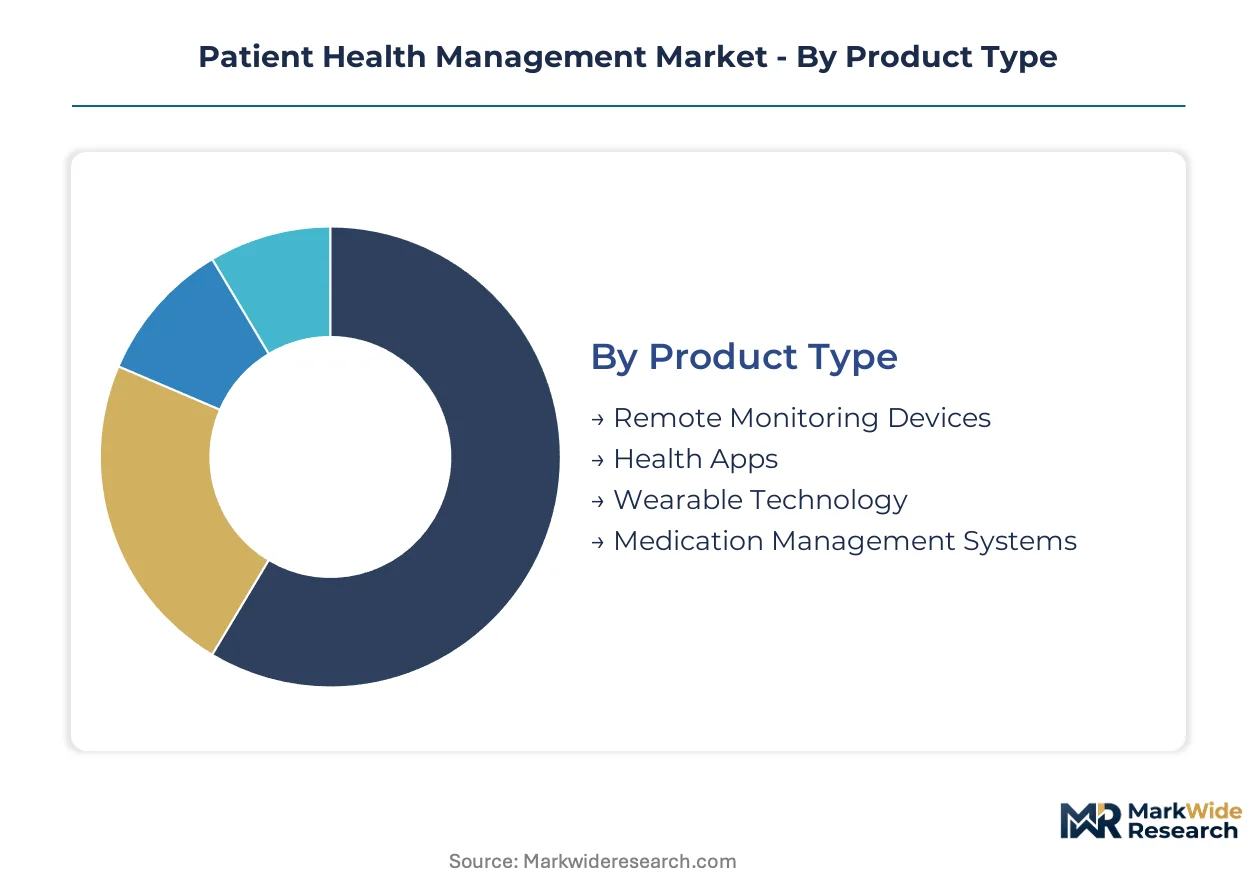
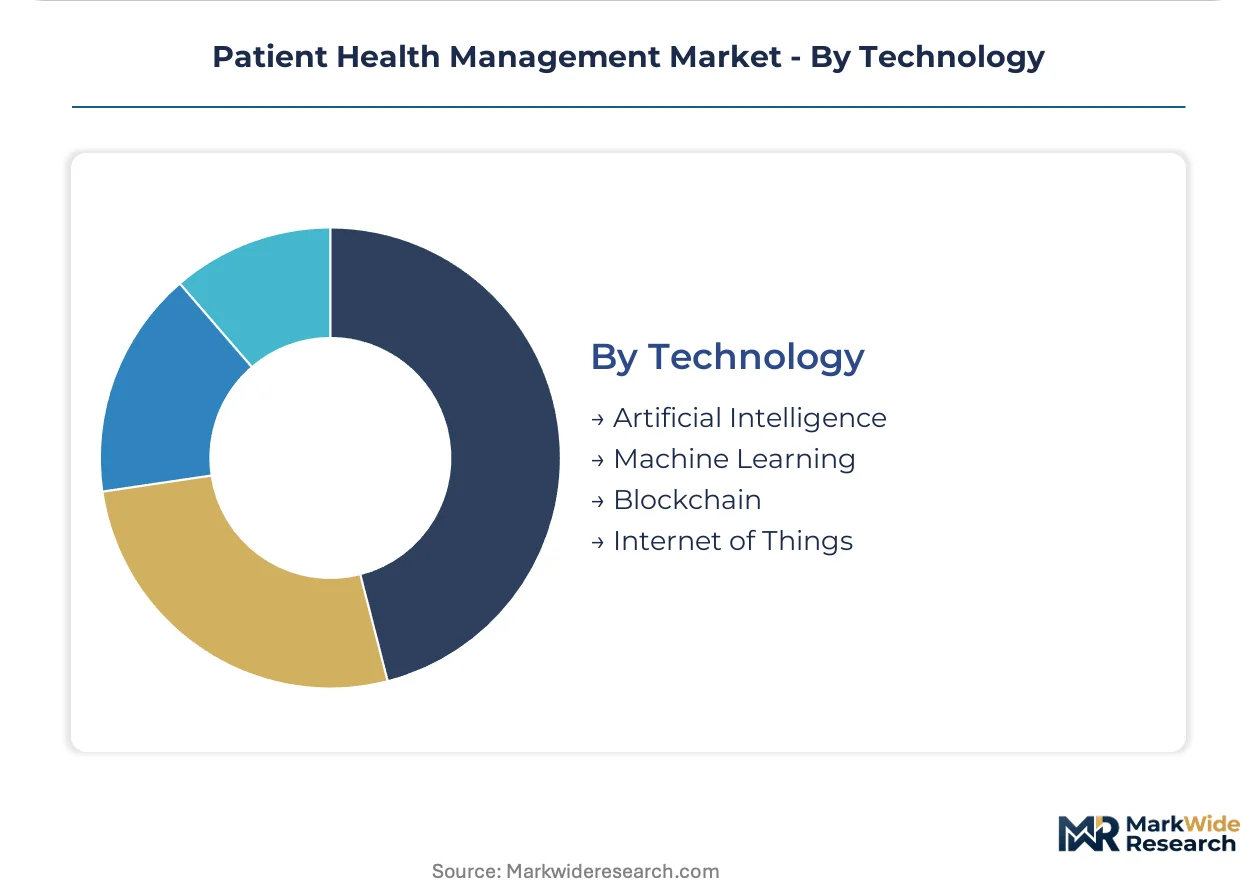
Patient health management platforms fragment across four structural dimensions that determine deployment architecture, revenue model, and regulatory exposure. Product type governs hardware-software mix and reimbursement eligibility. Delivery mode shapes capital intensity and data sovereignty. End user orientation dictates workflow integration depth. Technology foundation determines algorithmic capability and compliance burden.
Product Type:
Customization intensity varies sharply across this category, with implantable and durable medical equipment demanding bespoke regulatory pathways while consumer-facing applications pursue standardized scale.
- Remote Monitoring Devices:Continuous physiologic sensors capture cardiac rhythm, glucose fluctuations, and respiratory patterns for transmission to clinical dashboards. Hospital-at-home programs in Germany and the Netherlands are expanding procurement of pulse oximetry and blood pressure cuffs with cellular connectivity, driven by CMS-equivalent reimbursement codes for acute-level remote care.
- Health Apps:Smartphone-native platforms deliver symptom tracking, appointment scheduling, and patient education through modular feature sets. FDA 510(k) clearance pathways for software-as-medical-device are accelerating enterprise sales to US health systems seeking liability protection.
- Wearable Technology:Consumer-grade fitness bands and clinical-grade patches generate ambulatory biometric streams.
- Medication Management Systems:Smart dispensers and adherence algorithms coordinate polypharmacy regimens for chronic populations.
Most installed capacity flows through Remote Monitoring Devices. Expansion is steepest in Health Apps.
Delivery Mode:
Cost tier stratification separates capital-intensive on-premise deployments from operating-expense cloud subscriptions, with hybrid architectures emerging in privacy-sensitive European installations.
- Cloud-Based Solutions:Multi-tenant SaaS architectures enable elastic scaling of analytics workloads and reduce upfront infrastructure commitment. Hyperscaler data center expansion into HIPAA-compliant and GDPR-certified regions is removing latency barriers for real-time clinical decision support in Texas and Bavaria.
- On-Premise Solutions:Local server installations preserve data custody within hospital firewalls and satisfy national sovereignty requirements. Japanese academic medical centers maintain preference for air-gapped deployments due to METI cybersecurity guidelines and institutional risk aversion.
- Mobile Applications:Native iOS and Android clients extend platform reach to ambulatory settings and patient-owned devices.
- Web Platforms:Browser-accessible portals minimize installation friction for occasional users and administrative staff.
Cloud-Based Solutions carry the majority of new contract value. Mobile Applications are gaining share fastest among patient-facing deployments.
End User:
Customer type determines integration complexity, with institutional buyers demanding EMR interoperability while individual consumers prioritize usability and cost.
- Healthcare Providers:Hospitals and physician groups require FHIR-compliant data exchange, single sign-on, and population health dashboards. Integrated delivery systems in California are consolidating vendor relationships around platforms that guarantee readmission reduction metrics.
- Patients:Direct-to-consumer subscriptions for chronic disease management and wellness optimization are expanding through employer benefit programs and Medicare Advantage supplemental benefits.
- Caregivers:Family members and home health aides utilize simplified interfaces for care coordination and emergency alerting.
- Health Insurers:Payers deploy platforms for risk stratification, prior authorization automation, and network steerage.
Healthcare Providers account for the largest installed base. Patient-directed platforms are climbing the fastest as consumer health spending shifts toward digital modalities.
Technology:
Maturity gradients separate production-ready analytics from experimental architectures, with regulatory clarity determining commercial viability timelines.
- Artificial Intelligence:Clinical decision-support algorithms and predictive risk models require FDA premarket review for diagnostic applications. EU AI Act high-risk classification for patient-facing algorithms is extending conformity assessment timelines for European market entry.
- Machine Learning:Supervised learning pipelines for readmission prediction and sepsis detection are operational at scale within US health systems with established data governance frameworks.
- Blockchain:Distributed ledger applications for consent management and identity verification remain concentrated in pilot deployments among Dutch and Swiss privacy-focused networks.
- Internet of Things:Sensor interoperability standards and edge computing protocols enable device-to-platform data flows without centralized aggregation.
Machine Learning underpins the majority of deployed analytics capacity. Artificial Intelligence represents the steepest expansion trajectory as generative models enter clinical documentation and patient communication workflows.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Clinical informaticists and health data scientists concentrate in metropolitan medical centers across the United States, Germany, and Japan, anchoring platform development and deployment expertise in these markets.
United States
Hospital network consolidation in Texas and California drives enterprise-scale procurement of integrated patient health management platforms. CMS expanded remote patient monitoring reimbursement codes accelerate provider investment in connected care programs. The Dallas-Fort Worth metroplex hosts major health system headquarters where procurement teams negotiate outcome-based contracts with guaranteed readmission reduction metrics.
Germany
Academic medical centers in Bavaria and North Rhine-Westphalia pilot federated learning protocols for predictive risk algorithms without centralizing patient records. The EU AI Act's high-risk classification for patient-facing algorithms extends conformity assessment timelines for platform vendors. Berlin's digital health cluster concentrates GDPR-compliant data governance expertise serving cross-border deployments into Dutch and Swiss networks.
Japan
METI cybersecurity guidelines and institutional risk aversion sustain preference for air-gapped, on-premise deployments among Tokyo and Osaka academic medical centers. Aging demographics drive investment in home-based acute care platforms with remote monitoring integration. The Kansai region's medical device manufacturers supply connected diagnostic equipment feeding real-time biometric streams into care coordination workflows.
Netherlands
Hospital-at-home programs in Amsterdam and Rotterdam expand procurement of cellular-enabled pulse oximetry and blood pressure cuffs for acute-level remote care. Dutch privacy-focused networks concentrate pilot deployments of blockchain-enabled consent management and identity verification systems. Eindhoven's health technology cluster develops edge computing architectures for decentralized clinical decision support.
United Kingdom
NHS England's interoperability mandates compel health systems to upgrade legacy infrastructure and adopt FHIR-compliant patient health management platforms. London's digital health ecosystem attracts vendors seeking European market entry pathways aligned with EMA medical device regulations. The Greater Manchester health system consolidates vendor relationships around platforms integrating behavioral health protocols with chronic disease management.
Patient Health Management Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across the patient health management landscape, producing a tiered vendor structure where scale advantages clash with workflow depth. Electronic health record incumbents anchor enterprise contracts through data integration lock-in, while cloud infrastructure providers leverage hyperscaler capacity for population-level analytics. Strategic consolidation and outcome-based contracting represent the dominant competitive moves, with large health systems demanding performance milestones rather than seat-based subscriptions.
Among EHR-anchored platform providers, Epic Systems Corporation exemplifies the enterprise integration archetype, while Oracle Health occupies a position leveraging cloud infrastructure scale. Koninklijke Philips N.V. sits within the connected device ecosystem tier, anchoring real-time biometric data flows into care coordination workflows.
| Leading Market Players |
|---|
| Epic Systems Corporation |
| Oracle Health |
| athenahealth |
| Veradigm LLC |
| McKesson Corporation |
| IBM |
| Koninklijke Philips N.V. |
| GE Healthcare |
| ZeOmega |
| Others |
Value Network & Pricing Analysis
Integrated delivery systems in Texas and California concentrate procurement authority, forcing vendors toward enterprise-wide subscription bundles with outcome-based performance clauses rather than modular per-seat pricing.
Pricing Analysis
Bundled platform subscriptions dominate enterprise sales while unbundled point solutions serve mid-tier hospitals with limited integration budgets. Three-tier pricing structure across premium, standard, and economy levels reflects FHIR compliance depth and AI-enabled analytics capability. Pricing pressure stems from hospital network consolidation demanding guaranteed readmission reduction metrics as contract conditions. Safety-net hospitals and rural critical access facilities exhibit highest price sensitivity, while academic medical centers prioritize clinical functionality over cost.
Supply Chain Analysis
Cloud infrastructure supply rests on hyperscaler data center expansion into HIPAA-compliant and GDPR-certified regions across the United States, Germany, and Japan. Hardware dependencies include biometric sensors from Dutch and Japanese manufacturers, edge computing processors from Taiwanese foundries, and cellular connectivity modules from South Korean suppliers. Single-source vulnerability concentrates in specialized clinical informaticist talent pipelines. Distribution runs through direct enterprise sales teams serving integrated delivery systems alongside channel partners targeting independent physician practices.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in cloud-native platform architectures that reduce data center capital intensity while enabling premium-tier AI-enabled clinical decision-support modules.
For Market Incumbents: Deploy federated learning protocols to compress data governance overhead for European health systems facing GDPR localization requirements. Anchor enterprise contracts through deep EHR integration that elevates switching costs for hospital networks evaluating competitive platforms. Counter Oracle Health's cloud infrastructure scale by accelerating edge computing deployments that reduce latency for real-time clinical workflows. For New Entrants and Emerging Players: The premium-to-economy pricing gap in behavioral health integration creates whitespace for platforms combining psychiatric diagnostic instruments with chronic disease protocols. Target Medicare Advantage supplemental benefit channels where consumer-directed health spending shifts toward digital modalities. Pursue hospital-at-home waiver programs as the most penetrable acute-care extension segment. For Investors and Strategic Acquirers: Cloud infrastructure providers are the most active acquirer in this space, seeking clinical workflow depth to complement hyperscaler capacity. Five-to-ten year viability hinges on AI-enabled diagnostic tool portfolios cleared through FDA premarket review pathways. Watch EU AI Act conformity assessment timelines as the inflection indicator for European market entry cost structures.| Strategic Initiative | Industry Significance |
|---|---|
| FHIR API Integration | ONC interoperability mandates compel legacy infrastructure upgrades across US hospital networks. |
| AI-Enabled Clinical Decision Support | FDA premarket review requirements extend commercialization timelines for diagnostic applications. |
| Cloud Infrastructure Expansion | Hyperscaler data center buildout into healthcare-compliant regions reduces latency barriers. |
| Behavioral Health Platform Development | Unmet demand for coordinated mental and physical care pathways creates vendor whitespace. |
| EU AI Act Compliance Services | Risk classification requirements generate advisory revenue streams for established quality management systems. |
Research Methodology
Multiple input streams — hospital procurement database analysis, GPO contract reviews, CMS reimbursement filings, and hyperscaler healthcare capex disclosures — were reconciled through bottom-up and top-down triangulation. Primary interviews with hospital CIOs, clinical informaticists, biomedical engineers, and GPO contracts managers informed platform deployment patterns and vendor selection criteria. Secondary validation drew from FDA 510(k) clearance databases, EMA medical device registrations, hospital financial disclosures, and ONC interoperability compliance reports.
Historical adoption curves were cross-referenced against panel input from health system technology committees to model deployment trajectories across the projection horizon. Segmentation dimensions included product type, delivery mode, end user orientation, and technology foundation with regional regulatory cluster as an additional modeling axis. CAGRs were derived from elasticity-adjusted demand curves incorporating remote patient monitoring reimbursement expansion and cloud infrastructure scale effects.
Caveats apply where FDA guidance evolution on AI-enabled diagnostic tools, EU AI Act enforcement patterns, or cybersecurity disclosure requirement shifts could materially shift the outlook. A small set of named triggers — ONC interoperability mandate deadlines, CMS reimbursement code expansions, and ransomware litigation trends — warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Personal Health
Medical Wellness Market
Personal Health
Biohacking Market
Personal Health
Sleeping Aids Market
Personal Health
Menopause Wellness Market
Personal Health
Hair Restoration Market
Personal Health
High Concentration Respiratory Masks Market
Personal Health
OTC Health Products Market
Personal Health
North America Workplace Wellness Market
Personal Health
Parents-In-Waiting: Global Prenatal Market
Personal Health
Earwax Removal Products Market
Personal Health
Maternity Personal Care Products Market
Personal Health
Foot Insole Market
Personal Health
Reusable Face Mask Market
Personal Health
Obesity Treatment Market
Personal Health
Jet Lag Therapy Market
Personal Health
Sleep Mask Market