
 North America Hair Loss Treatment Products Market | 2026-2036
North America Hair Loss Treatment Products Market Size, Share, and Industry Trends Forecast 2026-2036
North America Hair Loss Treatment Products Market Analytics
Subscription-based replenishment services for topical solutions is hardening into a core revenue layer, shifting one-time purchasers into recurring revenue relationships. Johnson & Johnson leverages its established consumer health infrastructure to sustain pharmacy shelf presence across the United States and Canada. Kenvue anchors direct-to-consumer channels with personalized hair health assessment tools that drive retention. Procter and Gamble competes through mass-market distribution density in supermarket and drugstore networks.
North America hair loss treatment products encompass pharmacological, device-based, and surgical interventions designed to arrest follicular miniaturization and stimulate regrowth, typically incorporating active concentrations of minoxidil or finasteride in topical or oral delivery systems. These formulations function primarily to extend the anagen growth phase and inhibit dihydrotestosterone binding at androgen receptor sites in scalp tissue. Topical solutions and oral medications command the largest current revenue pools, reflecting established clinical validation and physician familiarity with minoxidil and finasteride protocols. Laser devices represent the fastest-expanding segment, driven by home-use portability and declining per-unit manufacturing costs. Distribution through pharmacies retains margin superiority due to professional consultation attachment and insurance reimbursement pathways.
FDA oversight of drug efficacy claims and EPA registration requirements for device emissions shape product development timelines and marketing language across the United States, while Health Canada and PMRA enforce parallel standards for northern market entry. The IRA's prescription drug pricing provisions introduce uncertainty for oral finasteride reimbursement structures, pressuring manufacturers toward topical alternatives. Stakeholders must monitor evolving state-level telehealth regulations that determine whether dermatologists can prescribe hair loss treatments across provincial and state lines without in-person examination.
Market Dynamics
FDA clearance pathways for low-level laser devices and the IRA's prescription pricing provisions are restructuring competitive positioning between pharmaceutical and device-based interventions across the United States and Canada.
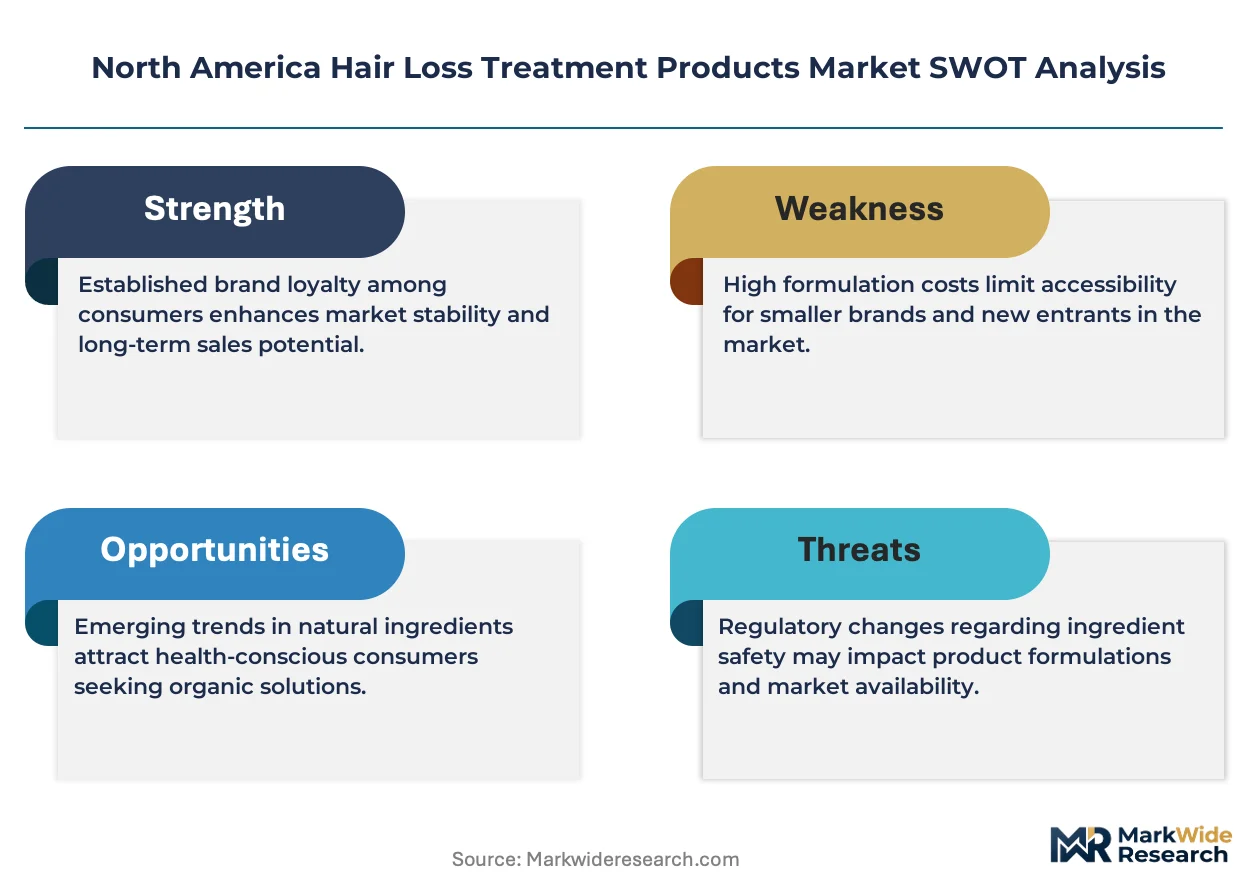
Growth Catalysts
- Telehealth expansion:State-level regulatory relaxations in Texas and California now permit dermatologists to prescribe finasteride without mandatory in-person scalp examinations.
- Device portability:Handheld laser units with rechargeable lithium-ion batteries are capturing bathroom-counter real estate previously dominated by topical bottles.
- Minoxidil patent expirations:Generic topical formulations at 5% concentration are flooding pharmacy shelves across the United States, collapsing per-treatment costs for chronic users.
Market Restraints
- Finasteride reimbursement uncertainty:The IRA's Medicare pricing negotiations are compressing margins on oral prescriptions, forcing manufacturers toward cash-pay topical alternatives.
- Device emission compliance:EPA registration requirements for laser wavelength outputs add twelve-to-eighteen-month delays to product launches versus topical drug pathways.
- Scalp surgery substitution:Follicular unit extraction clinics in Miami and Los Angeles are capturing high-value patients who abandon pharmaceutical regimens entirely.
Strategic Opportunities
- Canadian market underpenetration:Health Canada approval backlogs have left home-use laser devices with only three authorized brands versus eleven in the United States.
- Subscription bundling:Direct-to-consumer platforms are attaching nutraceutical supplements to recurring minoxidil shipments, lifting average revenue per user.
- Trichology clinic integration:Independent scalp health practices in Houston and Toronto are becoming exclusive distribution points for compounded topical formulations.
Industry Challenges
- Formulation stability expertise:Compounding pharmacies lack personnel trained in minoxidil-propylene glycol shelf-life extension for personalized prescriptions.
- Cross-border prescription fulfillment:State boards of pharmacy in New York and California are prosecuting telehealth platforms shipping finasteride across provincial lines without Canadian prescriber review.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Hair Loss Treatment Products Market |
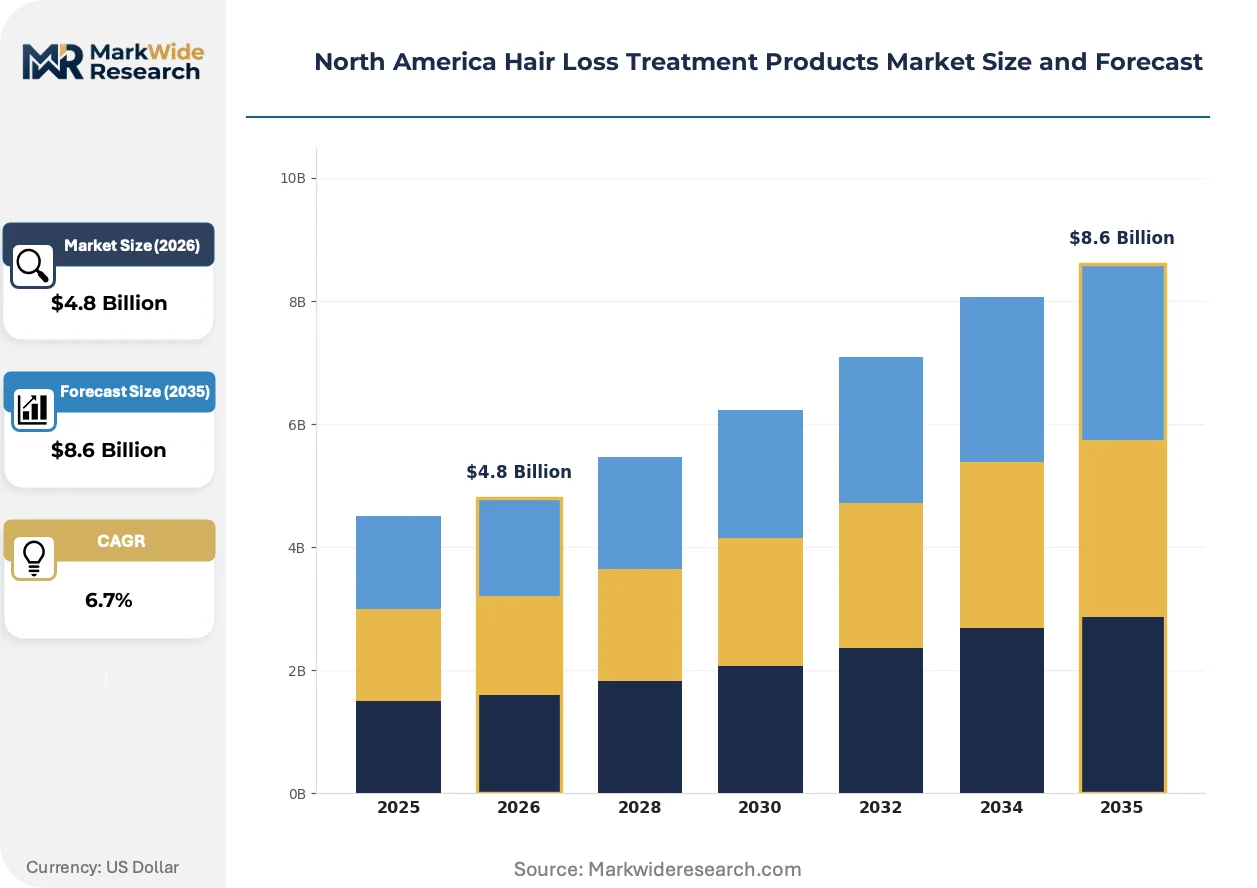
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Topical Solutions, Oral Medications, Laser Devices, Hair Transplant Target Gender: Men, Women, Unisex, Gender-Specific Distribution Channel: Pharmacies, Online Retail, Supermarkets, Salons Active Ingredient: Minoxidil, Finasteride, Saw Palmetto, Ketoconazole |
| Companies Covered | Johnson & Johnson, Kenvue, Procter and Gamble, Sun Pharma, Coty, L'Oréal, Church and Dwight, Merck & Co., Unilever, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Hair Loss Treatment Products Market Evolving Landscape
Product development pipelines are bifurcating between precision-dose topical systems and algorithm-guided laser protocols, with reimbursement pathways determining which modality captures physician mindshare.
Low-level laser therapy devices are expanding into the home-use segment as semiconductor manufacturing costs for 650-nanometer diodes collapse. Men aged 35-50 in suburban Dallas and Atlanta are replacing clinic visits with countertop units. This technology is expanding into pharmacy retail channels previously reserved for topical solutions, forcing shelf-space renegotiations.
The IRA's prescription drug pricing provisions are compressing oral finasteride reimbursement rates across Medicare Part D formularies. Pharmaceutical manufacturers are redirecting R&D spend toward topical foam formulations that bypass pharmacy benefit manager controls. Dermatology practices in California are responding by dispensing compounded alternatives through in-office cash-pay models.
Subscription-based replenishment services are displacing one-time pharmacy purchases for chronic topical users. Direct-to-consumer platforms attach diagnostic scalp imaging to recurring shipments, locking in retention. This behavioral shift concentrates in metropolitan markets where same-day delivery logistics already exist for other personal care categories.
North America Hair Loss Treatment Products Market Segmentation
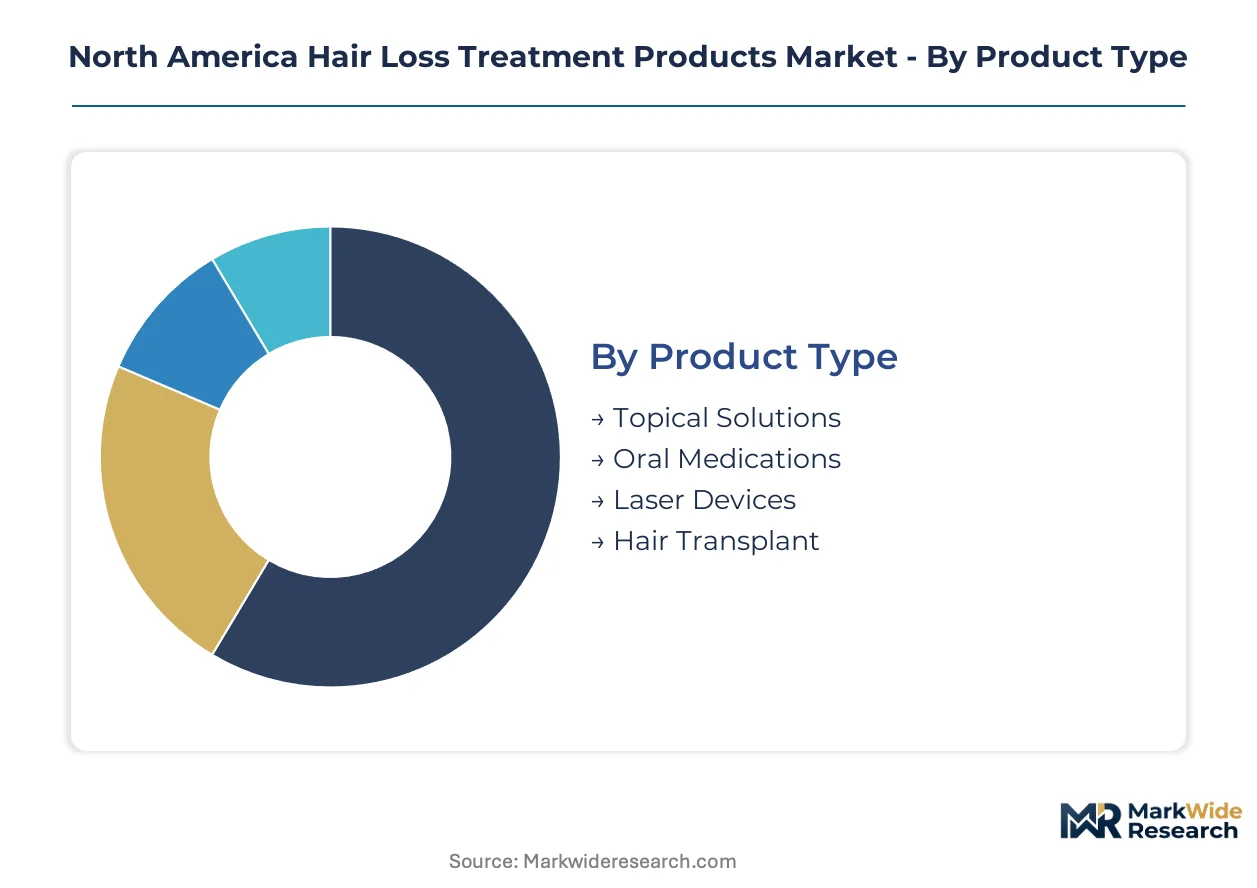
Product differentiation in North American hair loss treatment follows distinct upgrade cycles across pharmacological, device-based, and procedural categories. Consumer migration patterns between segments reveal shifting preferences for convenience versus clinical efficacy.
Product Type:
Replacement cycles vary dramatically across this category, with topical users replenishing monthly while laser device purchasers face multi-year upgrade decisions.
- Topical Solutions:Minoxidil-based formulations in 5% concentration dominate pharmacy shelves through foam and liquid delivery vehicles. Chronic users in California and Texas metro corridors drive recurring revenue through subscription replenishment services attached to diagnostic imaging.
- Oral Medications:Finasteride tablets face reimbursement compression under IRA Medicare pricing negotiations, pushing dermatology practices toward cash-pay dispensing models. Compounded alternatives are capturing share among patients seeking dose personalization.
- Laser Devices:Home-use units with 650-nanometer diode arrays are displacing clinic visits among suburban Dallas and Atlanta demographics.
- Hair Transplant:Follicular unit extraction procedures in Miami and Los Angeles surgical centers capture high-value patients abandoning pharmaceutical regimens entirely.
Topical Solutions sits at the top of the volume ranking, with Laser Devices climbing the fastest.
Target Gender:
Cost tier differentiation separates mass-market unisex formulations from premium gender-specific protocols with specialized excipient profiles.
- Men:Androgenetic alopecia protocols emphasizing 5-alpha-reductase inhibition through finasteride dominate prescription volumes. FDA-approved topical foam alternatives are redirecting R&D investment as oral reimbursement tightens.
- Women:Lower-concentration minoxidil formulations and anti-androgen combinations address hormonal hair thinning patterns. Post-menopausal demographics in New York and Toronto metropolitan areas drive specialist clinic referrals.
- Unisex:Mass-market shelf-stable formulations prioritize propylene glycol-free bases to minimize irritation across broader user bases.
- Gender-Specific:Niche compounded preparations with customized vehicle systems command premium pricing through trichology clinic channels.
Men captures the largest prescription volume, with Women gaining share fastest among newly diagnosed demographics.
Distribution Channel:
Margin structures diverge sharply between professional consultation channels and self-directed purchase environments.
- Pharmacies:CVS and Walgreens networks retain margin superiority through insurance reimbursement pathways for prescription finasteride. Pharmacist consultation attachment sustains compliance rates among chronic users.
- Online Retail:Direct-to-consumer platforms attach nutraceutical bundles to recurring minoxidil shipments, lifting average revenue per user through scalp imaging diagnostics.
- Supermarkets:Mass-market minoxidil placement in Walmart and Target aisle networks competes on unit economics against pharmacy counterparts.
- Salons:Independent trichology practices in Houston and Toronto function as exclusive distribution points for compounded topical formulations with personalized concentration adjustments.
Pharmacies maintains volume leadership, with Online Retail expanding most quickly through subscription lock-in mechanics.
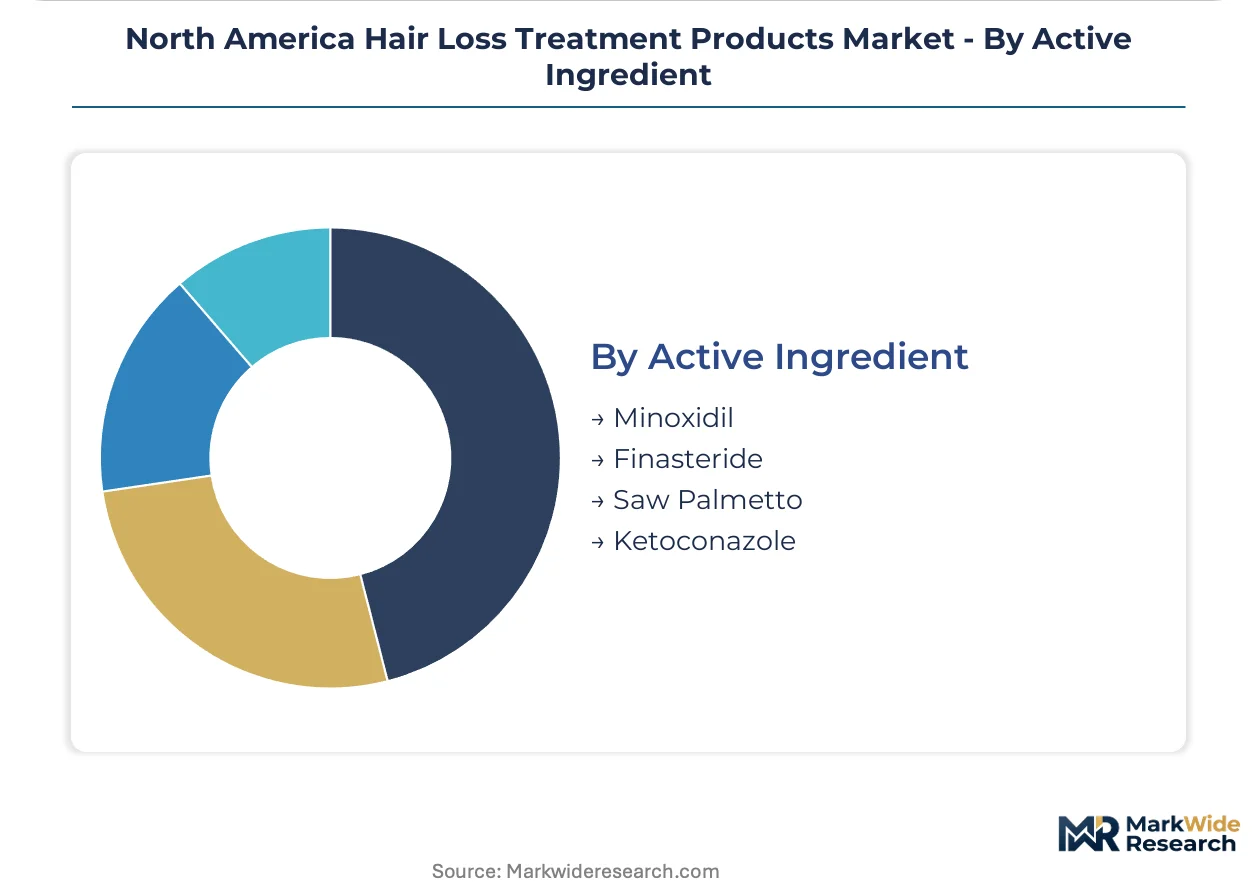
Active Ingredient:
Patent expiration timelines and clinical validation depth determine ingredient positioning across prescription and over-the-counter tiers.
- Minoxidil:Generic 5% topical formulations flooding United States pharmacy shelves have collapsed per-treatment costs for chronic users. Foam vehicle innovations extend market relevance beyond patent expiry.
- Finasteride:Oral tablet reimbursement uncertainty under IRA provisions is compressing manufacturer margins and redirecting formulation investment toward topical alternatives.
- Saw Palmetto:Botanical extracts occupy supplement aisle positioning with limited FDA efficacy claims, capturing price-sensitive segments seeking natural alternatives.
- Ketoconazole:Antifungal shampoo formulations address seborrheic dermatitis overlap with hair loss presentation, prescribed adjunctively in California dermatology practices.
Minoxidil sits at the top of the volume ranking, with Finasteride facing steepest reimbursement headwinds despite clinical efficacy.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Canada's regulatory approval backlog contrasts with the United States' accelerated FDA clearance pathways for home-use laser devices. Mexico's emerging middle-class demand for aesthetic interventions is reshaping import patterns from both neighbors.
United States
Dermatology clinic networks in California, New York, and Texas drive prescription volumes for finasteride and compounded topical alternatives. FDA oversight of drug efficacy claims and EPA registration requirements for laser emissions shape product development timelines and marketing language. Metropolitan markets in Dallas and Atlanta concentrate home-use laser device adoption among men aged 35-50.
Canada
Health Canada and PMRA enforce standards parallel to FDA requirements, though approval backlogs have left home-use laser devices with only three authorized brands versus eleven in the United States. Provincial telehealth regulations determine whether dermatologists can prescribe hair loss treatments across provincial lines without in-person examination. Toronto's independent trichology practices function as exclusive distribution points for compounded topical formulations.
Mexico
Growing aesthetic medicine infrastructure in Mexico City and Monterrey attracts cross-border patients seeking follicular unit extraction procedures at lower cost points than Miami or Los Angeles equivalents. The country's national pharmaceutical regulator oversees import licensing for minoxidil and finasteride formulations. Border state pharmacies in Tijuana and Ciudad Juárez serve cash-pay American consumers seeking prescription alternatives.
North America Hair Loss Treatment Products Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with pharmaceutical incumbents dominating pharmacy channels while device makers capture direct-to-consumer growth. The vendor base concentrates among consumer health conglomerates with established distribution infrastructure and dermatology-focused specialists with clinical validation assets. Three archetypes define competitive positioning: mass-market shelf-space dominators, prescription-protocol anchors, and subscription-platform operators. M&A activity targets telehealth-enabled prescription platforms and compounding pharmacy networks.
Among established consumer health conglomerates, Johnson & Johnson, Kenvue, and Procter and Gamble occupy positions reflecting distinct channel strategies. Johnson & Johnson exemplifies pharmacy shelf-presence archetypes through established United States and Canada infrastructure. Kenvue anchors direct-to-consumer positioning with personalized assessment tools. Procter and Gamble represents mass-market distribution density through supermarket and drugstore network penetration.
| Leading Market Players |
|---|
| Johnson & Johnson |
| Kenvue |
| Procter and Gamble |
| Sun Pharma |
| Coty |
| L'Oréal |
| Church and Dwight |
| Merck & Co. |
| Unilever |
| Others |
Value Network & Pricing Analysis
Compounding pharmacists trained in minoxidil-propylene glycol formulation stability command premium wage multiples in Texas and California versus Ontario, widening spreads between personalized prescription tiers and mass-market shelf equivalents.
Pricing Analysis
Capacity additions in Mexico's pharmaceutical manufacturing zones are reshaping price floors for generic minoxidil formulations across North American pharmacy networks. Subscription-based replenishment services deploy three-tier pricing structure across premium, standard, and economy levels, with scalp imaging diagnostics and compounded personalization driving tier separation. Price differentiation hinges on FDA approval status versus Health Canada backlog delays, with authorized laser devices commanding premiums over parallel imports. Cost compression in oral finasteride intensifies because IRA Medicare negotiations squeeze manufacturer margins, pushing cash-pay topical alternatives. Price-sensitive chronic users in supermarket channels exhibit highest elasticity, while trichology clinic patients show lowest sensitivity to concentration-customization premiums.
Supply Chain Analysis
Regional distribution centers in Memphis and Toronto operate hub-and-spoke patterns feeding pharmacy networks and direct-to-consumer fulfillment nodes. Active pharmaceutical ingredient production draws from India and China for minoxidil base compounds, with foam vehicle manufacturing concentrated in United States contract facilities. Semiconductor diode arrays for laser devices rest on Taiwanese and South Korean foundry output, creating single-source vulnerability for 650-nanometer wavelength components. Distribution runs through pharmacy benefit manager formularies for prescription tiers, bypassing traditional wholesale for subscription-platform operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Health Canada's approval backlog versus FDA clearance velocity creates a twelve-to-eighteen-month arbitrage window for device manufacturers establishing Canadian market presence ahead of competitor entry.
For Market Incumbents: Hedge against oral finasteride reimbursement compression by redirecting R&D spend toward topical foam formulations and in-office cash-pay dispensing infrastructure. Acquire compounding pharmacy networks in Houston and Toronto to secure personalized formulation capabilities before independent trichology practices consolidate exclusive distribution relationships. Capacity additions in Mexican manufacturing zones offer cost-advantaged sourcing for generic minoxidil supply security. For New Entrants and Emerging Players: Launch via direct-to-consumer subscription platforms attaching nutraceutical bundles to recurring shipments, exploiting same-day delivery logistics in Dallas and Atlanta metropolitan corridors. Target the Canadian home-use laser device segment, where Health Canada authorization backlogs have left only three brands versus eleven in the United States. White-space exists in compounded topical formulations for post-menopausal women seeking anti-androgen combinations through Toronto specialist clinics. For Investors and Strategic Acquirers: Consumer health conglomerates with established pharmacy shelf infrastructure represent the most active acquirer category in this space, seeking telehealth-enabled prescription platforms and compounding pharmacy networks. Long-term viability favors stakeholders positioned at the intersection of device portability and personalized formulation services. Monitor state-level telehealth regulatory relaxations as the inflection indicator for prescription volume migration toward cross-border fulfillment models.| Strategic Initiative | Industry Significance |
|---|---|
| Telehealth Platform Acquisition | Captures patient acquisition channels bypassing traditional dermatology clinic gatekeepers. |
| Compounding Pharmacy Network Buildout | Secures formulation expertise for personalized concentration adjustments in cash-pay models. |
| Laser Device Health Canada Authorization | Exploits regulatory backlog to establish first-mover position in underpenetrated Canadian market. |
| Subscription Replenishment Infrastructure | Locks chronic topical users into recurring revenue relationships with diagnostic imaging attachment. |
| Topical Foam R&D Investment | Redirects resources from oral finasteride toward IRA-resistant delivery formats. |
Research Methodology
Multiple input streams — structured interviews with dermatology practice administrators, regulatory affairs specialists at device manufacturers, pharmacy benefit manager formulary directors, and compounding pharmacy operators — were reconciled against FDA 510(k) filings, Health Canada device authorization databases, CMS Medicare Part D utilization data, and state-level telehealth regulatory trackers. Secondary validation drew from trade customs records, SEC consumer health segment disclosures, and clinic network expansion announcements. Bottom-up prescription volume modeling and top-down market sizing approaches were triangulated to constrain estimate variance.
Cross-referencing historical approval timelines against expert panel assessments shaped the analytical framework across the projection horizon. Segmentation dimensions modeled encompass product type, distribution channel, active ingredient class, and metropolitan versus non-metropolitan demand patterns. CAGRs were derived from fitted growth curves anchored to demographic diagnosis rates and technology adoption S-curves. Forecast inputs incorporated IRA prescription pricing provision implementation trajectories and semiconductor cost decline curves for laser diode components.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt Health Canada regulatory acceleration or state-level telehealth restriction reversals. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Personal Health
Global Health and Wellness Market
Personal Health
Jet Lag Therapy Market
Personal Health
Patient Health Management Market
Personal Health
Tongue Scraper Market
Personal Health
US Vaginal Moisturizers and Lubricants Market
Personal Health
Foot Insole Market
Personal Health
Disposable Underwear Market
Personal Health
Corporate Wellness Market
Personal Health
Interdental Brush Market
Personal Health
Global Weight Loss Services Market
Personal Health
Maternity Personal Care Products Market
Personal Health
Global OTC Hair Loss Treatment Market
Personal Health
Menstrual Cup Market
Personal Health
Workplace Wellness Market
Personal Health
Maternity and Personal Care Market
Personal Health
Biohacking Market