
 Asia-Pacific Maternity & Personal Care Market | 2026-2036
Asia-Pacific Maternity & Personal Care Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Maternity & Personal Care Market Insights
Multi-source ingredient sourcing is repositioning how Asia-Pacific maternity and personal care brands secure botanical actives and synthetic emollients. Procter & Gamble leverages its regional manufacturing footprint to anchor supply continuity across diverse raw material channels. Kao Corporation specializes in fermentation-derived ingredients that differentiate its maternal skin care portfolio. Pigeon Corporation dominates the premium baby care segment through rigorous quality control over Japanese-sourced base materials.
Asia-Pacific maternity and personal care encompasses formulations engineered with pH-balanced surfactant systems, hypoallergenic preservatives, and dermatologically tested active concentrations designed for prenatal, perinatal, and postnatal physiological conditions. Baby Care leads product type revenue contribution due to recurring purchase frequency and safety-driven premiumization, while Skin Care for pregnant women captures expanding margin pools through clinical-positioned stretch-mark and pigmentation solutions. Online Retail channels accelerate fastest among delivery modes as direct-to-consumer platforms enable subscription replenishment and telehealth-adjacent consultation services.
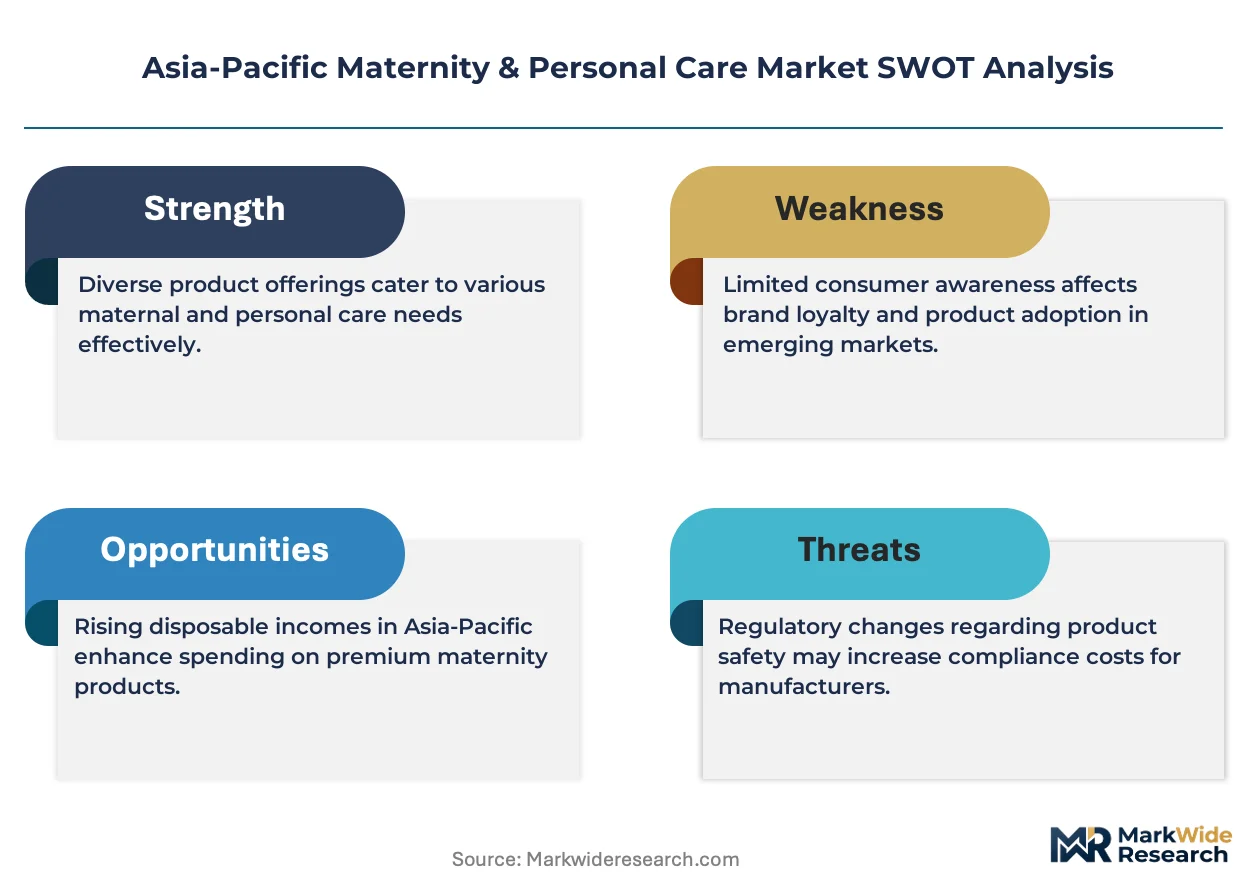
Japan's PMDA governs maternal topical product safety claims, Australia's TGA mandates ingredient disclosure thresholds for infant formulations, and India's BIS certification requirements restrict import access for uncertified baby care goods. These frameworks elevate compliance costs for new entrants while rewarding incumbents with established testing infrastructure and regulatory dossiers. Stakeholders must monitor evolving harmonization pressures between ASEAN cosmetic directive negotiations and national pharmacovigilance reporting obligations.
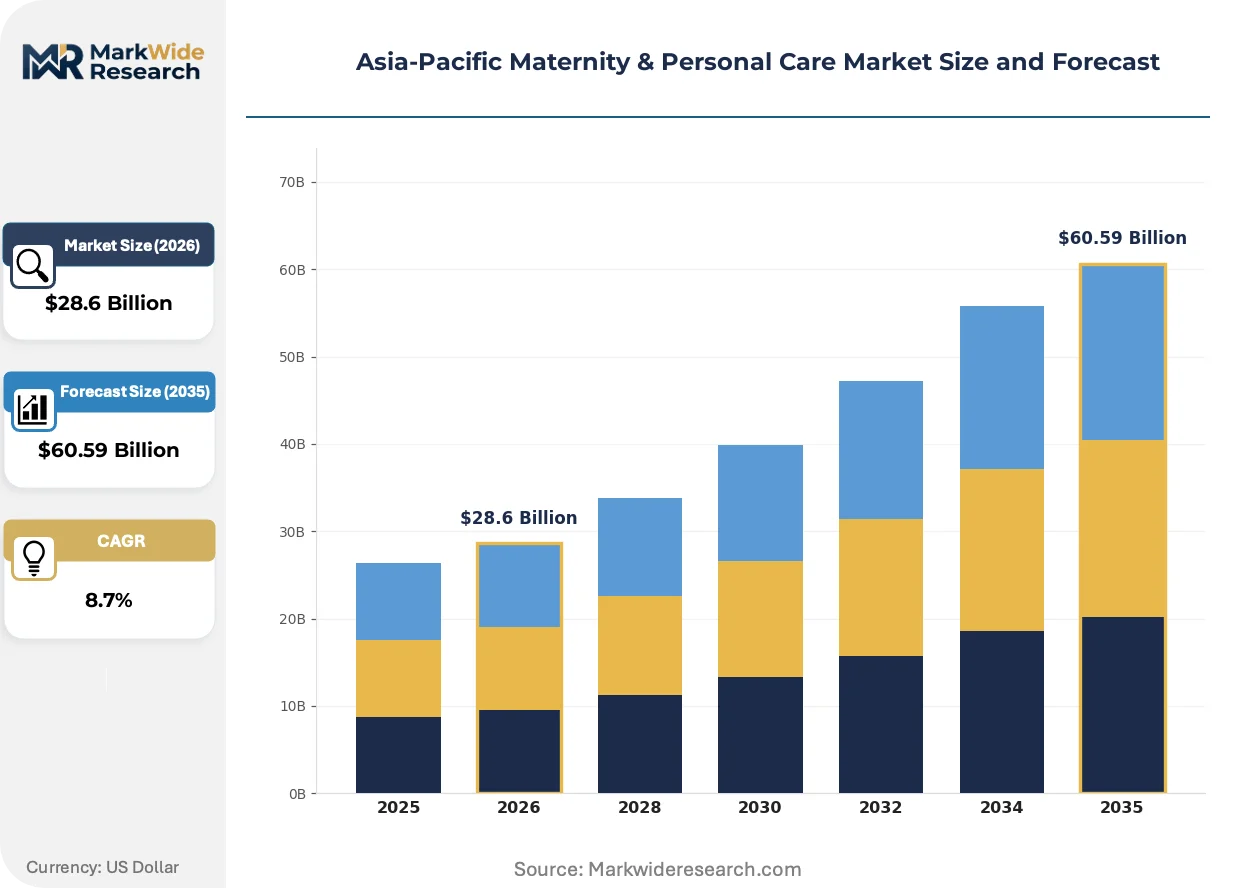
Market Dynamics
Clean-label ingredient transparency is compressing formulation cycles across Asia-Pacific maternity and personal care, forcing brands to revalidate supply chains and accelerate dermatological testing protocols to meet millennial parent expectations.
Growth Catalysts
- India's BIS infant cosmetic standards:Mandatory safety certification for imported baby care goods is elevating domestic manufacturing capacity and redirecting foreign investment toward local testing infrastructure.
- Fermentation-derived actives:Japanese biotech processes for maternal skin care ingredients are reducing dependency on petroleum-based emollients while improving biocompatibility profiles.
- Urban China demand concentration:Millennial and Gen Z parents in Shanghai, Beijing, and Shenzhen are driving premiumization through subscription-based replenishment models for hypoallergenic formulations.
Market Restraints
- Japanese botanical supply concentration:Premium baby care brands depend heavily on domestic Japanese-sourced base materials, creating vulnerability to climatic disruption and harvest volatility.
- PMDA safety claim documentation:Japan's pharmaceutical regulator requires extensive clinical substantiation for maternal topical product efficacy assertions, extending time-to-market by 18-24 months.
- Synthetic preservative substitution pressure:Clean-label preferences are forcing rapid reformulation away from established paraben systems toward unproven natural alternatives with shorter shelf stability.
Strategic Opportunities
- Indonesia's underpenetrated tier-2 cities:Surabaya, Bandung, and Medan present whitespace for direct-to-consumer platforms offering telehealth-adjacent maternity consultation bundled with product subscription.
- ASEAN cosmetic directive harmonization:Ongoing regulatory alignment negotiations are creating pathways for single-market certification across Thailand, Vietnam, and Philippines, reducing compliance fragmentation.
- Stretch-mark solution clinical positioning:Pigmentation and elasticity formulations for pregnant women remain underserved by evidence-based claims, opening margin expansion for dermatologically tested active concentrations.
Industry Challenges
- Formulation chemist talent scarcity:pH-balanced surfactant system design for prenatal physiological conditions requires specialized expertise concentrated in Japan and South Korea, constraining regional expansion.
- Multi-jurisdiction pharmacovigilance reporting:Divergent adverse event notification requirements between Australia's TGA, Japan's PMDA, and India's CDSCO are forcing redundant safety monitoring infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Maternity & Personal Care Market |
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $60.59 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Baby Care, Skin Care, Hair Care, Hygiene Products Delivery Mode: Online Retail, Supermarkets, Pharmacies, Direct Sales End User: Pregnant Women, New Mothers, Caregivers, Families Packaging Type: Bottles, Tubes, Pouches, Jars |
| Companies Covered | L'Oréal, Kimberly-Clark, Unilever, Kao Corporation, Shiseido, Procter & Gamble, Pigeon Corporation, Estée Lauder, Johnson & Johnson, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Maternity & Personal Care Market Trends and Innovations
Fermentation biotechnology and direct-to-consumer channel architecture are restructuring how Asia-Pacific maternity and personal care brands develop, manufacture, and distribute formulations across diverse regulatory environments.
Biotech-derived ingredients are overtaking conventional petrochemical emollients in premium maternal skin care formulations. Kao Corporation and domestic Chinese biotech suppliers are scaling fermentation platforms for ceramide and peptide production. Urban Chinese millennial parents are adopting these formulations at twice the rate of synthetic alternatives, compressing R&D cycles for legacy brands dependent on traditional supply chains.
Australia's TGA ingredient disclosure thresholds for infant formulations are mandating granular transparency in preservative and fragrance component labeling. This regulatory pressure is propagating through Southeast Asian markets as de facto standards for import acceptance. Premium baby care segments in Thailand and Singapore are responding by front-loading dermatological testing investments to preempt compliance friction.
Subscription replenishment models are displacing traditional retail pharmacy channels for recurring baby care purchases. Direct-to-consumer platforms in Jakarta, Bangkok, and Ho Chi Minh City are bundling product auto-delivery with pediatric nurse consultation access. This channel shift is most visible in Southeast Asian metropolitan corridors where smartphone penetration and digital payment infrastructure enable seamless recurring transaction architectures.
Asia-Pacific Maternity & Personal Care Market Segmentation
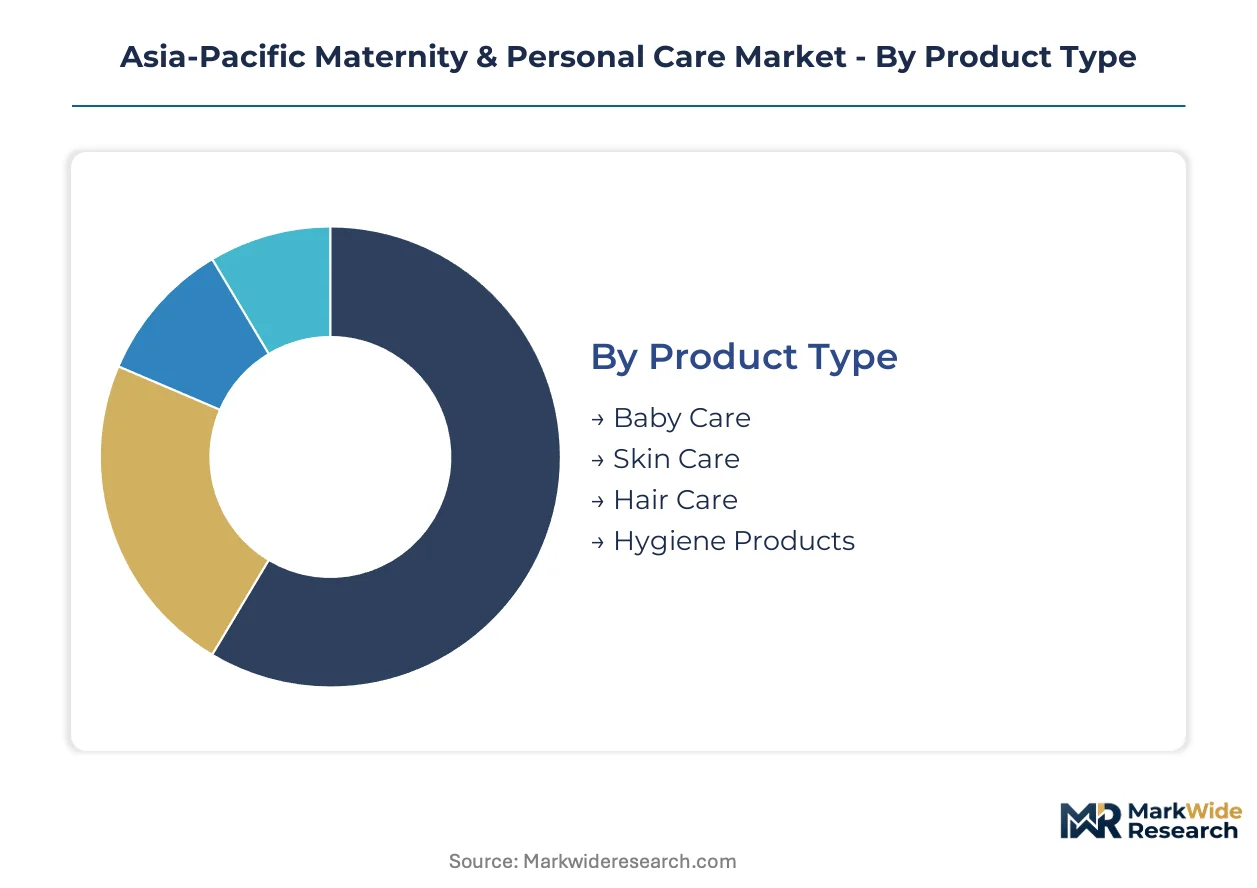
Asia-Pacific maternity and personal care segmentation reveals how formulation chemistry, channel infrastructure, and user physiology intersect to create distinct commercial battlegrounds. Each category carries divergent margin profiles, regulatory exposure, and supply chain requirements that reshape competitive priorities across the region.
Product Type:
pH-balanced surfactant systems and hypoallergenic preservative architectures differentiate commercial positioning across maternal physiological conditions.
- Baby Care:Formulations engineered with dermatologically tested active concentrations and microbiome-friendly emollient bases command recurring purchase frequency. Urban Chinese millennial parents in Shanghai and Beijing drive subscription-based replenishment for premium hypoallergenic variants, while India's BIS certification requirements redirect import-dependent brands toward local manufacturing partnerships.
- Skin Care:Stretch-mark and pigmentation solutions for pregnant women leverage clinical-positioned peptide and ceramide concentrations. Demand concentrates among Southeast Asian metropolitan corridors where telehealth-adjacent consultation services bundle evidence-based claims with product recommendations.
- Hair Care:Prenatal and postnatal scalp formulations address hormonal fluctuation patterns through gentle surfactant systems. Japanese fermentation-derived ingredients differentiate premium positioning.
- Hygiene Products:Disposable and reusable solutions for perinatal bleeding management emphasize absorbency engineering and skin-barrier protection. Price-sensitive penetration dominates tier-2 Indonesian cities.
Mature deployment sits with Baby Care. Newer deployment is concentrated in Skin Care for pregnant women.
Delivery Mode:
Channel economics vary sharply by customer acquisition cost and inventory velocity across metropolitan versus secondary city geographies.
- Online Retail:Direct-to-consumer platforms enable subscription replenishment architectures with pediatric nurse consultation bundling. Smartphone penetration and digital payment infrastructure in Jakarta, Bangkok, and Ho Chi Minh City accelerate this channel's expansion trajectory most steeply.
- Supermarkets:Mass-market baby care SKUs depend on shelf-space negotiations and promotional calendar alignment. Australia's TGA ingredient disclosure thresholds propagate as de facto standards for premium placement.
- Pharmacies:Clinical-positioned maternal skin care and pharmacist-recommended infant formulations retain trust-based purchase authority. Japan's PMDA safety claim documentation elevates incumbent advantage.
- Direct Sales:Network marketing and maternity consultant relationships penetrate underpenetrated tier-2 Indonesian cities including Surabaya and Bandung.
Established infrastructure sits with Pharmacies. Emerging infrastructure investment concentrates in Online Retail.
End User:
Physiological condition and decision-making authority create distinct formulation requirements and marketing communication strategies.
- Pregnant Women:Stretch-mark prevention and pigmentation management drive clinical evidence requirements. Australia's TGA mandates elevate transparency expectations.
- New Mothers:Postpartum recovery formulations address skin elasticity restoration and perineal care. Japanese biotech ceramides dominate premium positioning.
- Caregivers:Grandparents and domestic helpers purchasing on behalf of families prioritize price visibility and familiar brand recognition.
- Families:Household-level purchasing decisions for shared baby care products emphasize volume economics and multi-child usability.
Concentrated purchasing authority sits with Pregnant Women. Distributed purchasing authority is expanding among Caregivers.
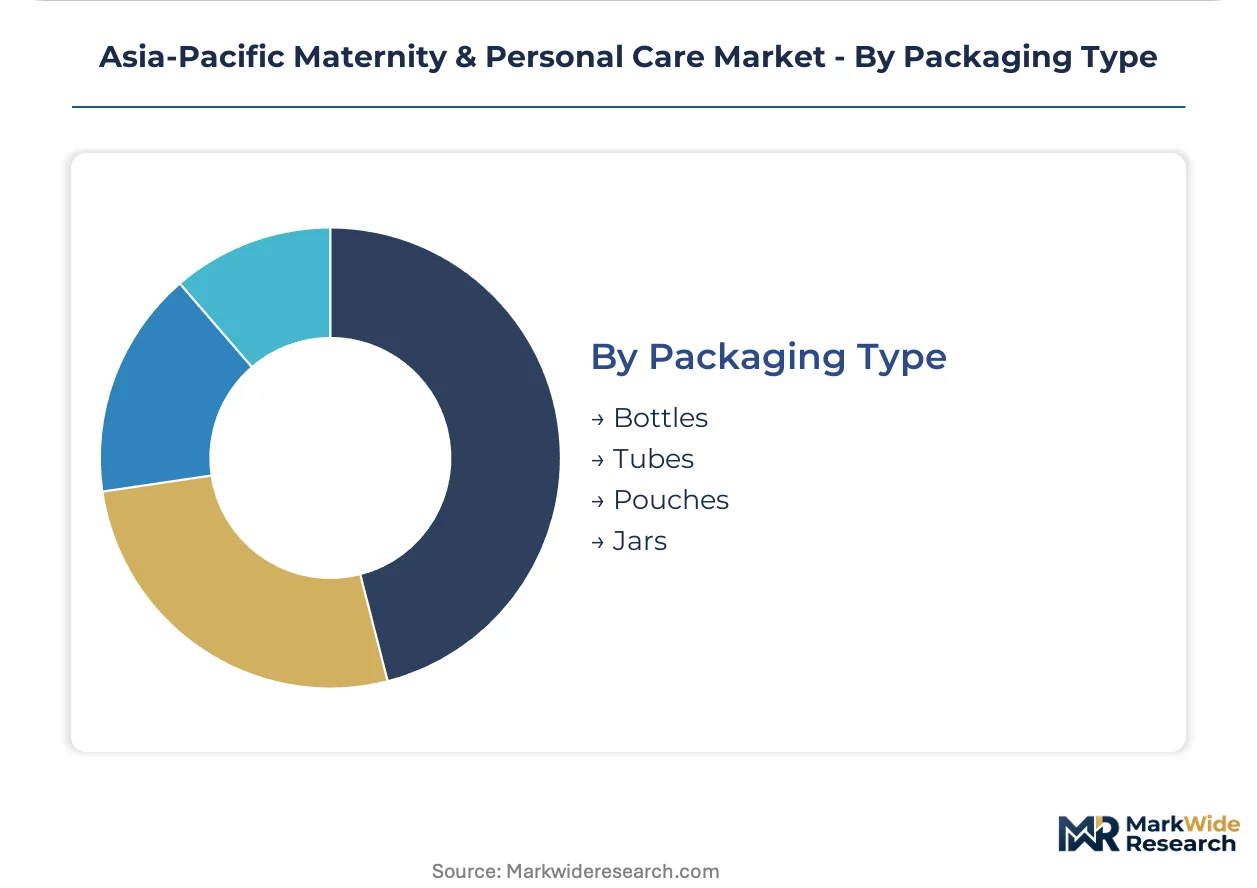
Packaging Type:
Material science and dispensing ergonomics intersect with sustainability pressures and travel-format convenience demands.
- Bottles:Pump and squeeze formats for liquid cleansers and lotions dominate baby care SKUs. Recycled plastic content mandates reshape supplier selection.
- Tubes:Collapsible aluminum and laminate structures for creams and ointments enable precise dosing control. Premium maternal skin care favors airless tube technology.
- Pouches:Flexible refill and travel formats reduce per-unit shipping costs and plastic intensity. Southeast Asian e-commerce fulfillment favors this format.
- Jars:Wide-mouth containers for balms and thick emollients retain tactile application preference among Japanese consumers.
Standardized volume sits with Bottles. Format innovation is concentrating in Pouches.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japanese botanical harvests and fermentation bioreactors anchor raw material security for premium maternal skin care formulations across the Asia-Pacific region. Supply chain resilience depends on climatic stability in Honshu cultivation zones and biotech scaling in Osaka-Kobe industrial corridors.
China
Millennial and Gen Z parents in Shanghai, Beijing, and Shenzhen drive subscription-based replenishment for hypoallergenic baby care formulations. NMPA cosmetic registration requirements mandate safety dossiers for imported maternal topical products, elevating compliance timelines for foreign entrants. Yangtze River Delta manufacturing clusters concentrate clean-label formulation capacity to serve domestic premiumization trends.
Japan
PMDA clinical substantiation requirements for maternal skin care efficacy claims extend product development cycles by 18-24 months. Kansai region fermentation biotech facilities supply ceramide and peptide actives to regional formulators. Tokyo-Osaka distribution networks prioritize pharmacist consultation channels for clinical-positioned stretch-mark solutions.
India
BIS mandatory safety certification for imported infant cosmetics redirects foreign investment toward local testing infrastructure in Maharashtra and Gujarat. Mumbai and Delhi-NCR urban corridors concentrate demand for dermatologically tested baby care SKUs. CDSCO pharmacovigilance reporting obligations parallel BIS compliance, creating dual regulatory navigation for market entrants.
Australia
TGA ingredient disclosure thresholds for infant formulations propagate as de facto standards for premium product acceptance across Southeast Asian import channels. Sydney and Melbourne metropolitan clusters anchor clinical evidence generation for pigmentation and elasticity solutions. Telehealth-adjacent consultation services bundle product recommendations with maternal skin care subscriptions.
Indonesia
Surabaya, Bandung, and Medan present whitespace for direct-to-consumer platforms offering bundled maternity consultation and product subscription. Smartphone penetration and digital payment infrastructure in Jakarta accelerate online retail channel displacement of traditional pharmacy distribution. ASEAN cosmetic directive harmonization negotiations create pathways for single-market certification leverage.
Asia-Pacific Maternity & Personal Care Market Competitive Landscape
Global majors compete with regional champions across formulation chemistry expertise and regulatory dossier depth. Market structure tilts toward consolidated premium tiers where Japanese fermentation biotech capabilities and multi-jurisdiction compliance infrastructure create defensive moats. Three archetypes dominate: multinational CPG conglomerates with regional manufacturing footprints, Japanese specialists in maternal skin care biotechnology, and emerging Chinese direct-to-consumer platforms. Competitive moves concentrate on backward integration into botanical supply chains and strategic partnerships with telehealth providers.
Within the fermentation biotechnology tier, Kao Corporation and Shiseido exemplify R&D-intensive positioning anchored in Kansai-region bioreactor capacity. Procter & Gamble represents the multinational archetype with distributed manufacturing assets spanning regulatory environments. Pigeon Corporation occupies a position in premium baby care quality assurance, with Japanese-sourced base material control serving as a differentiation anchor against synthetic emollient competitors.
| Leading Market Players |
|---|
| L'Oréal |
| Kimberly-Clark |
| Unilever |
| Kao Corporation |
| Shiseido |
| Procter & Gamble |
| Pigeon Corporation |
| Estée Lauder |
| Johnson & Johnson |
| Others |
Pricing and Supply Chain Analysis
Fermentation biotechnology adoption across Japanese maternal skin care manufacturing is simultaneously compressing unit production costs and concentrating supplier power among Kansai-region bioreactor operators. This production-method transition feeds pricing stratification between synthetic-emollient legacy formulations and biotech-derived premium SKUs.
Pricing Analysis
Consultation-bundled subscription pricing separates premium dermatologically tested formulations from unbundled transactional pharmacy purchases. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and BIS compliance status. Cost compression in economy tiers is intensifying because India's domestic manufacturing incentives redirect import-dependent brands toward local partnerships. Tier-2 Indonesian caregivers exhibit highest price sensitivity; urban Chinese millennial parents in subscription models show lowest.
Supply Chain Analysis
India's BIS certification mandates and China's NMPA registration requirements are reshaping sourcing toward domestic testing infrastructure and Yangtze River Delta manufacturing clusters. Raw material dependencies center on Japanese Honshu botanical harvests, Kansai fermentation-derived ceramides, and Southeast Asian palm-based emollients. Single-source vulnerability concentrates in Japanese-sourced base materials exposed to climatic disruption. Distribution runs through direct-to-consumer platforms displacing traditional pharmacy channels in Jakarta, Bangkok, and Ho Chi Minh City.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is becoming a vertical-integration race as players pursue captive supply of fermentation-derived actives to defend margin pools against synthetic-emollient commoditization.
For Market Incumbents: Anchor defensive positioning through backward integration into Kansai-region bioreactor capacity and exclusive botanical supply agreements with Honshu cultivation cooperatives. PMDA documentation requirements for maternal skin care efficacy claims create regulatory moats against emerging Chinese direct-to-consumer platforms lacking clinical substantiation infrastructure. For New Entrants and Emerging Players: The mid-tier price-point gap between Pigeon Corporation's premium Japanese-sourced formulations and mass-market synthetic alternatives presents whitespace for BIS-certified domestic Indian manufacturing. Surabaya and Bandung's underpenetrated tier-2 corridors offer the most penetrable geography. Telehealth-adjacent consultation bundling with product subscription provides the essential go-to-market angle. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by multinational CPG conglomerates seeking fermentation biotechnology capabilities and multi-jurisdiction regulatory dossiers. Long-term viability hinges on 5-10 year windows for ASEAN cosmetic directive harmonization completion. The signal to watch is CDSCO-BIS regulatory convergence accelerating domestic Indian manufacturing preference.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fermentation Capacity | Kansai-region bioreactor ownership secures ceramide supply continuity against harvest volatility. |
| BIS Certification Investment | Maharashtra and Gujarat testing infrastructure unlocks India's import-restricted infant cosmetic market. |
| Direct-to-Consumer Platform Launch | Jakarta and Ho Chi Minh City smartphone penetration enables subscription bundling with pediatric consultation. |
| Stretch-Mark Solution Clinical Positioning | Australia's TGA evidence requirements differentiate premium maternal skin care from commodity alternatives. |
| ASEAN Harmonization Prepositioning | Single-market certification across Thailand, Vietnam, and Philippines reduces compliance fragmentation costs. |
Research Methodology
Trade databases, regulatory filings, and industry association reports formed the secondary backbone, supplemented by primary interviews with formulation chemists, regulatory affairs specialists at BIS and PMDA, pediatric dermatologists, and direct-to-consumer platform operators. Bottom-up and top-down triangulation validated segment-level estimates against aggregate market sizing.
Bottom-up modeling anchored volume projections across product type, delivery mode, end user physiology, and packaging format dimensions. CAGRs were derived from segment-level growth rate reconciliation with macroeconomic indicators. Industry-specific forecast inputs incorporated NMPA registration timelines, BIS certification penetration curves, and smartphone-enabled subscription adoption rates.
Inputs from customs records and pharmaceutical regulatory databases were available through the study window; gaps in real-time adverse event reporting introduce uncertainty bands around pharmacovigilance compliance cost estimates. Forecasts reflect assumptions about ASEAN directive harmonization progress and climatic stability in Japanese botanical cultivation zones. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Personal Health
Global Weight Loss Services Market
Personal Health
North America Hair Loss Treatment Products Market
Personal Health
Foot Insole Market
Personal Health
Menstrual Cup Market
Personal Health
Europe Hair Loss Treatment Products Market
Personal Health
Sexual Wellness Market
Personal Health
Maternity Personal Care Products Market
Personal Health
Middle East and Africa Smoking Cessation and Nicotine De-Addiction Market
Personal Health
Sextech and Sexual Wellness Market
Personal Health
Parents-In-Waiting: Global Prenatal Market
Personal Health
Tongue Scraper Market
Personal Health
Asia-Pacific Mobile Health Market
Personal Health
High Concentration Respiratory Masks Market
Personal Health
Jet Lag Therapy Market
Personal Health
Patient Health Management Market
Personal Health
Biohacking Market