
 US Vaginal Moisturizers and Lubricants Market | 2026-2036
US Vaginal Moisturizers and Lubricants Market Size, Share, and Industry Trends Forecast 2026-2036
US Vaginal Moisturizers and Lubricants Market Intelligence
Market Context with Strategic Players
Buyer concentration in the US vaginal moisturizers and lubricants market is shifting from traditional pharmacy-dependent consumers toward direct-to-online purchasers seeking discretion and subscription convenience. Church & Dwight Co., Inc. leverages its established retail shelf presence and brand recognition across mass-market channels to sustain volume leadership. Combe Incorporated anchors the premium segment through specialized formulations targeting menopausal symptom relief. BioFilm Inc. differentiates via healthcare professional endorsements and clinical positioning in sexual health clinics.
Technical Definition and Structural Segments
Vaginal moisturizers and lubricants comprise pH-balanced, iso-osmolar formulations designed to supplement or replace physiological secretions, with water-based variants typically containing glycerin or propylene glycol humectants and silicone-based alternatives employing dimethicone polymers for extended residence time. These products serve both therapeutic applications addressing vaginal atrophy and dyspareunia and recreational sexual health enhancement across diverse consumer demographics. Water-based formulations occupy the largest volume share due to compatibility with latex barriers and broad retail accessibility, while organic and paraben-free formulations within the formulation segment command disproportionate margin pools as clean-label preferences intensify. Online retail channels represent the fastest-growing distribution pathway, though pharmacies retain structural importance for first-time purchasers seeking pharmacist guidance.
Regulatory Framework and Forward Outlook
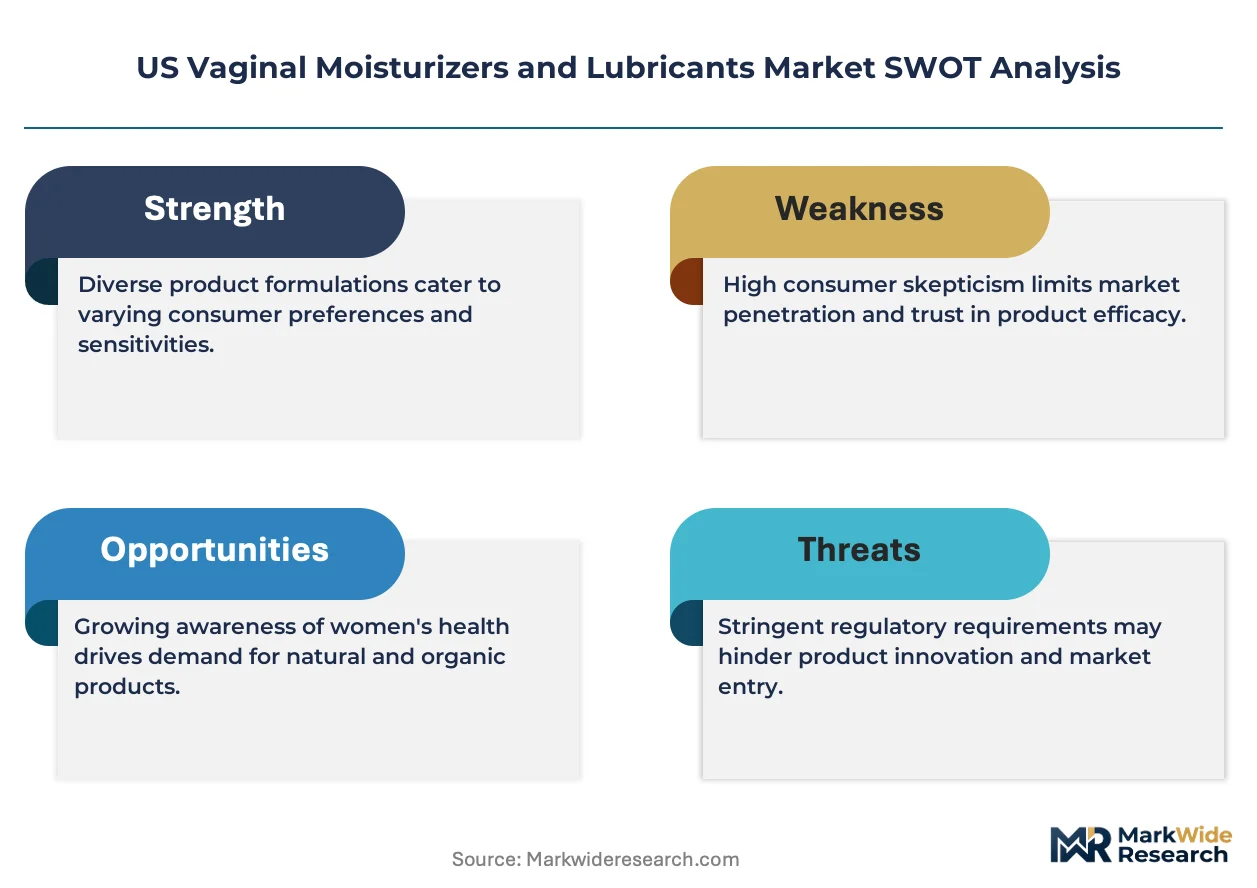
FDA Class II medical device classification governs personal lubricant safety and efficacy claims, while FTC advertising standards police marketing representations around therapeutic benefits. State-level pharmacy regulations and California's Proposition 65 chemical disclosure requirements further shape formulation transparency and labeling obligations. Stakeholders must monitor evolving FDA guidance on osmolality thresholds and preservative safety as these standards will determine which formulations maintain market access versus face reformulation costs or delisting.
Market Dynamics
FDA Class II medical device classification for personal lubricants is compressing formulation flexibility while elevating compliance costs, forcing manufacturers to prioritize clinical validation over marketing innovation.
Growth Catalysts
- Genitourinary Syndrome of Menopause Awareness:Healthcare providers increasingly screen postmenopausal patients for vaginal atrophy symptoms, expanding the addressable patient population seeking therapeutic lubricant solutions.
- California Proposition 65:Chemical disclosure mandates accelerate consumer demand for paraben-free and clean-label formulations, rewarding early reformulators with shelf space advantages in major retail chains.
- Telehealth Sexual Health Services:Virtual consultations normalize discussions around dyspareunia and vaginal dryness, reducing stigma-driven purchase hesitation among first-time buyers.
Market Restraints
- Glycerin Input Volatility:Water-based formulation dependence on refined glycerin exposes margins to biofuel policy-driven commodity price swings.
- Silicone Supply Concentration:Dimethicone polymer production clusters in Texas and Louisiana petrochemical corridors, creating hurricane-related disruption exposure.
- Osmolality Threshold Uncertainty:Pending FDA guidance on acceptable osmolality ranges threatens delisting of legacy formulations that fail prospective standards.
Strategic Opportunities
- Subscription Direct-to-Consumer Models:Automated replenishment services capture recurring revenue from menopausal women seeking discretion and convenience.
- Healthcare Professional Endorsement Channels:Gynecology and pelvic floor therapy clinics represent underdeveloped prescription-adjacent distribution pathways.
- ISO 13485 Certification:Quality management system adoption enables private-label manufacturing contracts with hospital systems and medical device distributors.
Industry Challenges
- Clinical Trial Design Complexity:Demonstrating non-inferiority to physiological secretions requires specialized endpoints that extend FDA 510(k) clearance timelines.
- Preservative System Reformulation:Eliminating parabens and formaldehyde-releasing agents demands stability testing investments that strain mid-tier manufacturer R&D budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Vaginal Moisturizers and Lubricants Market |
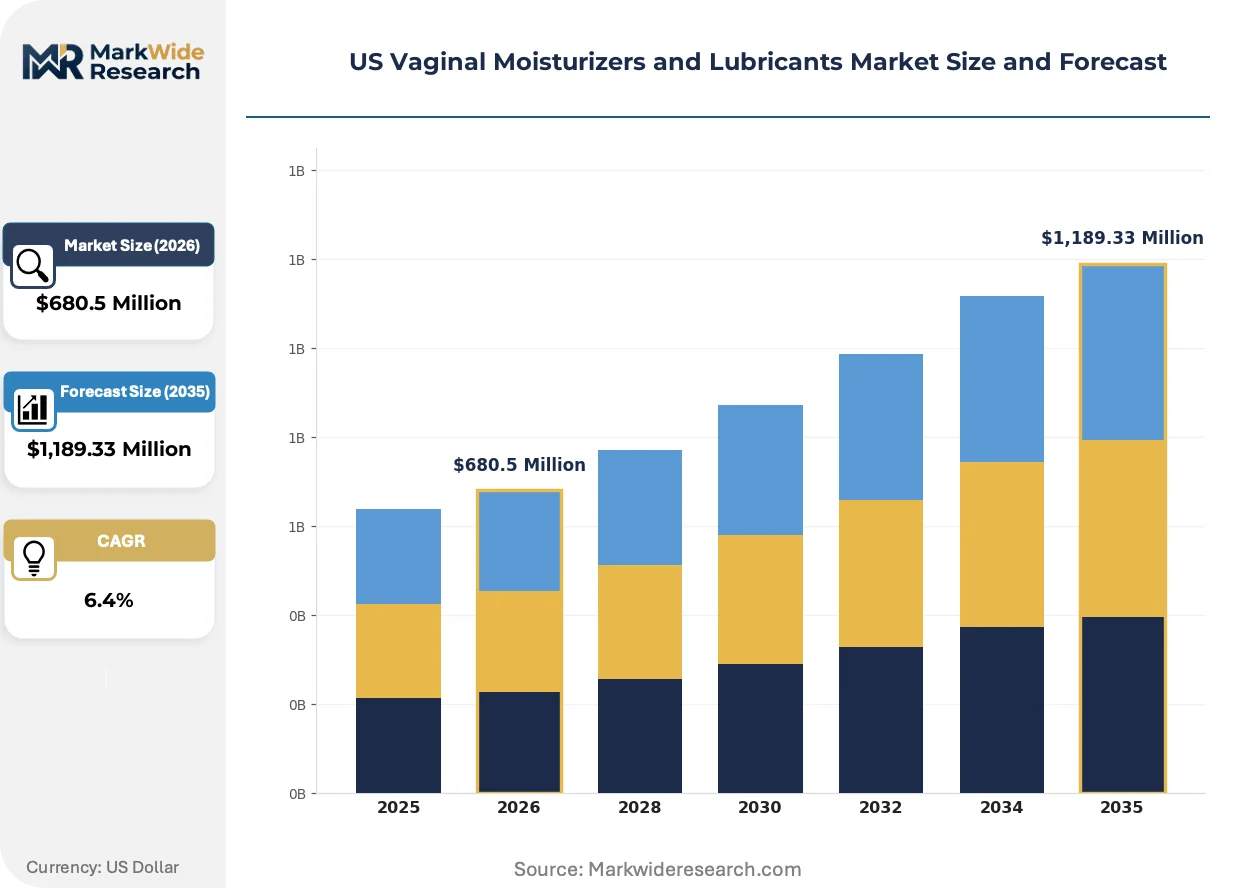
| Market Size in 2026 | $680.5 Million |
| Market Size in 2035 | $1,189.33 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Water-based, Silicone-based, Oil-based, Hybrid Formulation: Paraben-free, Organic, Scented, Sensitive Skin Distribution Channel: Online Retail, Pharmacies, Supermarkets, Health Stores End User: Women, Sexual Health Clinics, Healthcare Professionals, Seniors |
| Companies Covered | Combe Incorporated, The Yes Yes Company Ltd., Church & Dwight Co., Inc., Good Clean Love, Searchlight Pharma, Reckitt Benckiser Group plc, BioFilm Inc., KESSEL medintim GmbH, Bayer AG, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Vaginal Moisturizers and Lubricants Market Strategic Shifts & Innovations
Formulation science and distribution architecture are undergoing parallel transformation as digital health integration and clean-label chemistry redefine competitive differentiation.
Hyaluronic acid-based humectant systems are decentralizing glycerin dominance in premium water-based segments. Postmenopausal women with recurrent urinary tract infections favor these formulations for their mucosal compatibility. The shift is compressing legacy propylene glycol reliance among clinically positioned brands.
FDA draft guidance on personal lubricant biocompatibility testing is elevating premarket submission requirements. Manufacturers must now submit cytotoxicity and sensitization data previously accepted through predicate device claims. Small and mid-sized formulators in California and Massachusetts are responding by consolidating regulatory affairs functions or exiting the therapeutic claims space entirely.
Pharmacy benefit manager exclusion from sexual health products is redirecting volume toward cash-pay online channels. Subscription platforms now capture menopausal women who previously relied on pharmacist guidance for first purchases. This behavioral pivot concentrates most visibly in Northeast corridor metropolitan areas with high telehealth adoption rates.
US Vaginal Moisturizers and Lubricants Market Segmentation
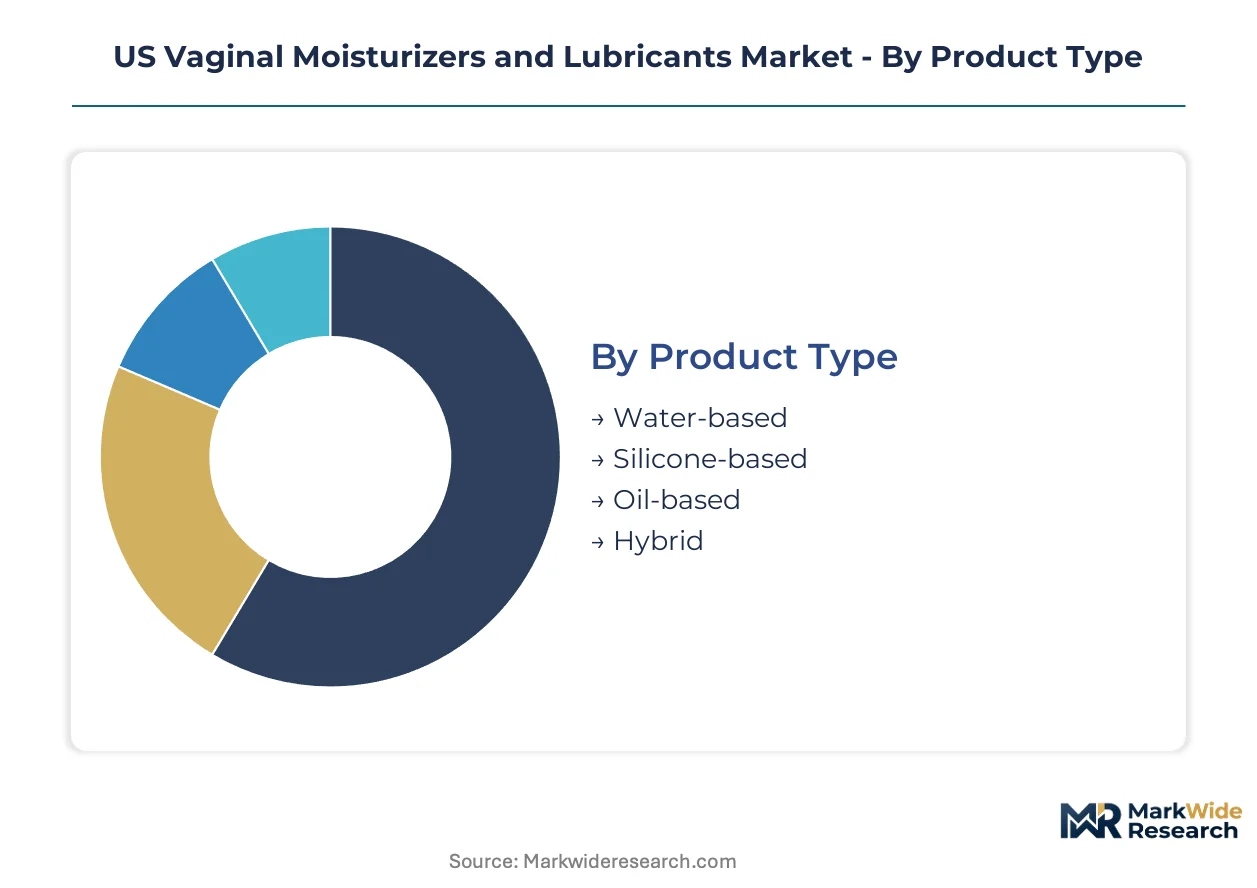
Product differentiation in the US vaginal moisturizers and lubricants market follows distinct technical and commercial fault lines. Each segmentation dimension reveals where manufacturing investment concentrates and where consumer preference is shifting.
Product Type:
Manufacturing capacity clusters around water-based and silicone-based chemistries, with formulation expertise determining regional production advantages.
- Water-based:Glycerin and propylene glycol humectant systems dominate current production volumes. California and Northeast corridor pharmacies move the highest unit volumes of these latex-compatible formulations as first-line therapeutic recommendations for postmenopausal patients.
- Silicone-based:Dimethicone polymer bases deliver extended residence time for dyspareunia management. Gulf Coast petrochemical corridor proximity shapes where these higher-margin formulations are compounded, though hurricane exposure creates periodic supply volatility.
- Oil-based:Natural oil emulsions serve niche preferences for chemical-minimal applications.
- Hybrid:Water-silicone combinations attempt to bridge compatibility and durability demands.
Water-based absorbs the bulk of installed capacity; silicone-based is expanding most quickly.
Formulation:
Clean-label chemistry investments are redrawing margin pools as California disclosure mandates ripple through national retail chains.
- Paraben-free:Preservative system reformulation has become table stakes for shelf placement in major pharmacy networks. FDA 510(k) clearance timelines extend for these reformulated products, but Proposition 65 compliance unlocks California market access worth disproportionate revenue concentration.
- Organic:Plant-derived humectants and natural gum thickeners command premium positioning. Direct-to-consumer subscription channels in metropolitan Northeast corridors show strongest uptake among menopausal women prioritizing ingredient transparency.
- Scented:Fragrance-added variants target recreational rather than therapeutic use cases.
- Sensitive Skin:Hypoallergenic positioning with minimal ingredient lists serves reactive mucosal conditions.
Paraben-free captures the largest reformulation investment; organic is climbing the fastest.
Distribution Channel:
Channel strategy determines customer acquisition economics and repeat purchase mechanics.
- Online Retail:Subscription models and discreet delivery address stigma barriers for first-time buyers. Telehealth-integrated platforms in Northeast metropolitan areas are capturing menopausal women who previously relied on pharmacist consultation.
- Pharmacies:Retail pharmacy networks retain structural importance for therapeutic positioning and healthcare professional endorsement. CVS and Walgreens shelf placement remains essential for brand legitimacy despite compressing foot traffic.
- Supermarkets:Mass-market accessibility drives volume for established household brands.
- Health Stores:Specialty retailers like Whole Foods gatekeep organic and clean-label product discovery.
Pharmacies retain the deepest existing infrastructure; online retail is gaining share fastest.
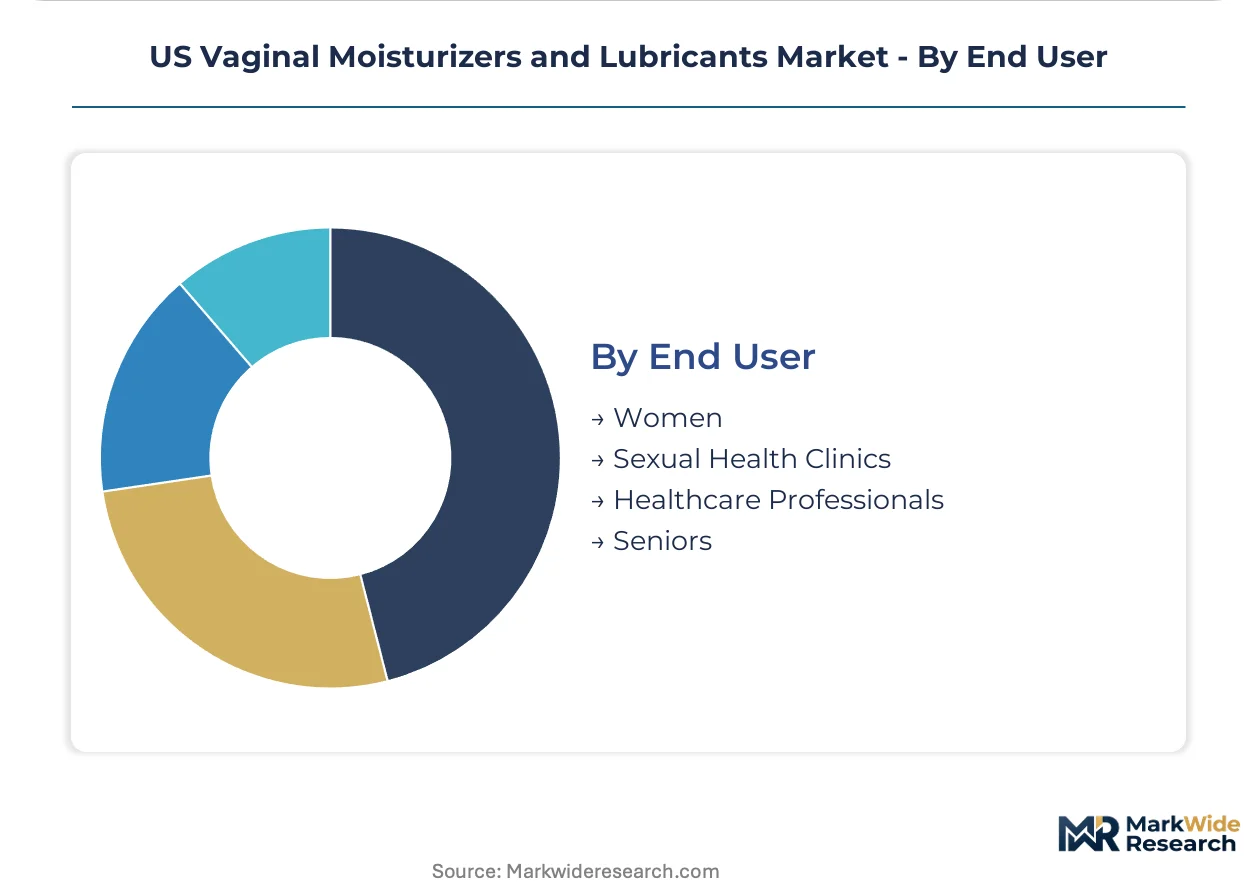
End User:
Demand concentration shifts as clinical screening protocols expand the addressable patient population.
- Women:Direct consumer purchase spans therapeutic and recreational applications. Postmenopausal women represent the fastest-expanding demographic as genitourinary syndrome of menopause awareness penetrates primary care screening protocols.
- Sexual Health Clinics:Clinical endorsement channels command premium pricing for therapeutic-positioned formulations. Pelvic floor therapy practices in California and Massachusetts are emerging as prescription-adjacent distribution nodes.
- Healthcare Professionals:Gynecologist recommendation drives trial and brand loyalty among symptomatic patients.
- Seniors:Medicare-age consumers with vaginal atrophy represent concentrated demand in Florida and Arizona retirement corridors.
Women absorb the bulk of unit volume; sexual health clinics are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Postmenopausal women in coastal metropolitan areas drive disproportionate demand for therapeutic formulations, while Gulf Coast petrochemical corridors concentrate silicone-based manufacturing capacity.
California
Los Angeles and San Francisco metropolitan areas generate the highest per-capita consumption of organic and paraben-free formulations. Proposition 65 chemical disclosure mandates force national reformulation standards as retailers standardize labeling for California compliance. San Diego hosts emerging clean-label manufacturing clusters serving direct-to-consumer subscription channels.
Northeast Corridor
Greater Boston and New York City anchor telehealth-integrated sexual health services that normalize clinical discussions around vaginal atrophy. FDA oversight of personal lubricants as Class II medical devices elevates formulation standards for Massachusetts and New York-based manufacturers. Philadelphia and Baltimore retail pharmacy networks retain structural importance for first-time therapeutic purchases.
Texas
Houston petrochemical complexes supply dimethicone polymers for silicone-based lubricant production. Hurricane exposure creates periodic supply volatility that ripples through national distribution networks. Dallas-Fort Worth serves as a regional distribution hub for Southwest and Mountain West markets.
Florida
Medicare-age consumers in Tampa and Miami retirement corridors concentrate demand for vaginal atrophy treatments. State pharmacy regulations govern therapeutic product placement in retail chains. Orlando health systems are piloting pelvic floor therapy clinic distribution models for prescription-adjacent positioning.
Illinois
Chicago anchors Midwest distribution infrastructure for water-based formulations serving pharmacy networks across the Great Lakes region. The state's aging demographic profile mirrors national trends in genitourinary syndrome of menopause prevalence. Peoria and Rockford manufacturing facilities produce glycerin-dependent humectant systems for mass-market brands.
US Vaginal Moisturizers and Lubricants Market Key Industry Players
California and Northeast-based formulators anchor the premium clean-label tier; Gulf Coast petrochemical-adjacent producers hold silicone-based manufacturing advantages. The market structures around three tiers: mass-market household brands, clinical-positioned therapeutic specialists, and direct-to-consumer subscription platforms. Consolidation pressures concentrate among mid-tier manufacturers facing FDA 510(k) clearance cost escalation. Dominant competitive moves include preservative system reformulation for Proposition 65 compliance and telehealth partnership development for patient acquisition channels.
Among mass-market incumbents, Church & Dwight Co., Inc. and Reckitt Benckiser Group plc exemplify retail shelf dominance through established pharmacy and supermarket networks. Combe Incorporated occupies a position within the clinical endorsement tier, while BioFilm Inc. represents healthcare professional channel specialization. The Yes Yes Company Ltd. and Good Clean Love anchor the organic formulation segment for subscription-direct consumers. KESSEL medintim GmbH exemplifies European-origin technical positioning in ISO-certified manufacturing.
| Leading Market Players |
|---|
| Combe Incorporated |
| The Yes Yes Company Ltd. |
| Church & Dwight Co., Inc. |
| Good Clean Love |
| Searchlight Pharma |
| Reckitt Benckiser Group plc |
| BioFilm Inc. |
| KESSEL medintim GmbH |
| Bayer AG |
| Others |
Cost & Logistics Intelligence
Captive supply of dimethicone polymers through Gulf Coast petrochemical corridor proximity anchors silicone-based manufacturers with cost advantages that translate into pricing power over water-based competitors dependent on commodity glycerin markets. FDA Class II medical device classification creates dual-tier compliance costs that stratify manufacturers into premium clinical-positioned brands versus mass-market formulations competing on shelf price.
Pricing Analysis
Volume concentrates in mass-market water-based formulations while margin pools concentrate in silicone-based and organic segments. Three-tier pricing structure across premium, standard, and economy levels separates clinical-endorsed hyaluronic acid formulations from pharmacy-tier glycerin products and supermarket private labels. Pricing pressure stems from glycerin input volatility driven by biofuel policy fluctuations. Postmenopausal women seeking therapeutic solutions show lowest price sensitivity, while recreational users in mass channels exhibit highest elasticity.
Supply Chain Analysis
Workforce availability in formulation chemistry and regulatory affairs clusters in California and Massachusetts, drawing talent from pharmaceutical and biotechnology sectors. Raw material sourcing draws from Texas and Louisiana petrochemical corridors for dimethicone, Midwest agricultural processing for refined glycerin, and California botanical suppliers for organic humectants. Single-source vulnerability concentrates in Gulf Coast hurricane exposure for silicone polymer feedstock. Distribution runs through CVS and Walgreens pharmacy networks for therapeutic positioning, with direct-to-consumer subscription platforms capturing fastest-growing volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation pressure concentrates among mid-tier manufacturers as FDA 510(k) clearance cost escalation forces exit or acquisition, with clinical validation capabilities becoming the primary survival filter.
For Market Incumbents: Hedge against glycerin commodity volatility through backward integration into humectant supply or exclusive supply agreements with agricultural processors. Secure ISO 13485 certification to capture private-label manufacturing contracts from hospital systems facing margin pressure. Church & Dwight and Combe must defend pharmacy shelf position against subscription-platform encroachment by embedding telehealth referral partnerships. For New Entrants and Emerging Players: Hyaluronic acid-based formulation technology offers entry wedge into premium therapeutic segments underserved by legacy glycerin-dependent incumbents. Target pelvic floor therapy clinics in California and Massachusetts as prescription-adjacent distribution white space. Direct-to-consumer subscription models with telehealth integration represent the most penetrable go-to-market angle for clinical credibility without retail slotting fee barriers. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by mass-market consumer health conglomerates seeking clinical credibility or pharmaceutical companies expanding into adjacent women's health categories. Five-to-ten year viability favors manufacturers with FDA-cleared therapeutic claims and established gynecologist endorsement networks. Watch FDA osmolality guidance finalization as inflection indicator for which formulation portfolios face delisting versus premium repositioning.| Strategic Initiative | Industry Significance |
|---|---|
| Preservative System Reformulation | Proposition 65 compliance unlocks California retail access worth disproportionate revenue concentration. |
| Telehealth Partnership Development | Virtual consultation integration normalizes clinical discussions and reduces stigma-driven purchase hesitation. |
| ISO 13485 Certification Investment | Quality management credentials enable hospital system private-label contracts and prescription-adjacent positioning. |
| Subscription Platform Launch | Automated replenishment captures recurring revenue from menopausal women prioritizing discretion and convenience. |
| Hyaluronic Acid Formulation Pivot | Mucosal-compatible humectant systems command premium positioning among recurrent UTI patient populations. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs, combined with primary interviews across gynecologists, pharmacy category managers, formulation chemists, and pelvic floor therapists. FDA 510(k) databases, California Proposition 65 enforcement records, and Nielsen retail audit data provided validation anchors. Bottom-up demand modeling across postmenopausal demographic cohorts triangulated against top-down manufacturer capacity assessments.
Granularity-level modeling operated at state-metropolitan area for demand geography, product chemistry type for supply segmentation, and distribution channel for price realization. CAGRs derived from patient population growth curves, screening protocol penetration rates, and channel shift elasticity parameters across the analysis window. Forecast inputs incorporated telehealth adoption trajectories and FDA guidance timeline probabilities without year-specific assumptions.
Several conditions sit outside the modeled scope, including hurricane disruption frequency in Gulf Coast petrochemical corridors and biofuel policy shifts affecting glycerin commodity markets. Forecasts reflect assumptions around stable FDA regulatory posture and continued Proposition 65 enforcement stringency. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Personal Health
Blackhead Removing Vacuum Market
Personal Health
North America Hair Loss Treatment Products Market
Personal Health
Asia Pacific Hair Loss Treatment Products Market
Personal Health
Patient Health Management Market
Personal Health
Sleeping Aids Market
Personal Health
Global Weight Loss Services Market
Personal Health
Jet Lag Therapy Market
Personal Health
Middle East and Africa Smoking Cessation and Nicotine De-Addiction Market
Personal Health
Global Health and Wellness Market
Personal Health
Earwax Removal Products Market
Personal Health
Interdental Brush Market
Personal Health
Asia-Pacific Maternity & Personal Care Market
Personal Health
Sextech and Sexual Wellness Market
Personal Health
Smoking Cessation and Nicotine De Addiction Market
Personal Health
Skin Tag Remover Market
Personal Health
PTBCHA Market