
 North America Workplace Wellness Market | 2026-2036
North America Workplace Wellness Market Size, Share, and Industry Trends Forecast 2026-2036
North America Workplace Wellness Market Insights
Employer consortiums across the United States and Canada are consolidating purchasing power for preventive health services. Teladoc Health leverages its virtual care infrastructure to serve distributed workforces across multiple provinces and states. Virgin Pulse anchors employer loyalty through integrated engagement platforms that combine wearables data with coaching portals. ComPsych Corporation dominates the employee assistance program channel with national provider networks and crisis intervention capabilities.
Workplace wellness encompasses employer-sponsored programs designed to improve worker health outcomes through preventive interventions, biometric monitoring, and behavioral coaching. These programs typically incorporate health risk assessments, fitness tracking devices, mental health counseling access, and nutritional guidance delivered through digital dashboards or onsite clinics. Employee Assistance Programs represent the most mature segment with established reimbursement pathways, while Digital Platforms capture the fastest expansion as employers seek scalable delivery for remote and hybrid work arrangements. Fitness Solutions occupy a specialized niche where EXOS competes through performance coaching protocols originally developed for athletic populations.
OSHA mandates for hazard communication and ergonomic standards indirectly elevate employer investment in physical wellness infrastructure. The Mental Health Parity and Addiction Equity Act, enforced by the Department of Labor and state insurance commissioners, requires equivalent coverage limits for behavioral health services. HIPAA privacy rules govern how wellness vendors handle employee biometric data and participation records. Stakeholders must monitor evolving state-level legislation on workplace mental health accommodations as compliance complexity intensifies across jurisdictional boundaries.
Market Dynamics
Employer self-insurance penetration among Fortune 500 corporations is compressing procurement cycles for preventive health services, forcing vendors to demonstrate measurable ROI through biometric outcome tracking and utilization analytics.
Growth Catalysts
- OSHA Ergonomic Standards:Federal mandates for workplace hazard mitigation are compelling manufacturers and logistics operators to invest in onsite physical therapy clinics and movement screening protocols.
- Biometric Monitoring Technology:Continuous glucose monitors and wearable heart rate variability trackers are enabling real-time stress intervention programs for knowledge workers in high-pressure financial services roles.
- Canada:Provincial health authority partnerships with private employers in Ontario and British Columbia are expanding subsidized mental health counseling access beyond traditional Employee Assistance Program limits.
Market Restraints
- HIPAA Privacy Compliance:Stringent data handling requirements for employee biometric information are elevating vendor legal costs and limiting third-party analytics partnerships.
- Specialized Clinical Talent:Licensed behavioral health providers concentrate in coastal metropolitan areas, creating access deserts for rural manufacturing facilities seeking onsite counseling capacity.
- Point Solution Fragmentation:Employers face integration complexity when stitching together separate vendors for fitness tracking, mental health coaching, and chronic disease management.
Strategic Opportunities
- Mexico Nearshoring Corridors:Manufacturing expansion in Querétaro and Nuevo León is creating demand for bilingual wellness programs serving transnational workforces.
- AI-Driven Personalization:Machine learning algorithms analyzing claims data and wearable inputs are enabling hyper-targeted intervention recommendations at individual employee levels.
- Direct Primary Care Integration:Employer-sponsored membership models are converging with wellness platforms to deliver preventive care outside traditional insurance billing structures.
Industry Challenges
- Behavioral Health Credentialing:Multi-state licensing requirements for virtual therapists create operational bottlenecks for vendors serving distributed remote workforces.
- Legacy HRIS Integration:Employer human capital management systems lack standardized APIs for wellness data ingestion, requiring costly custom middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Workplace Wellness Market |
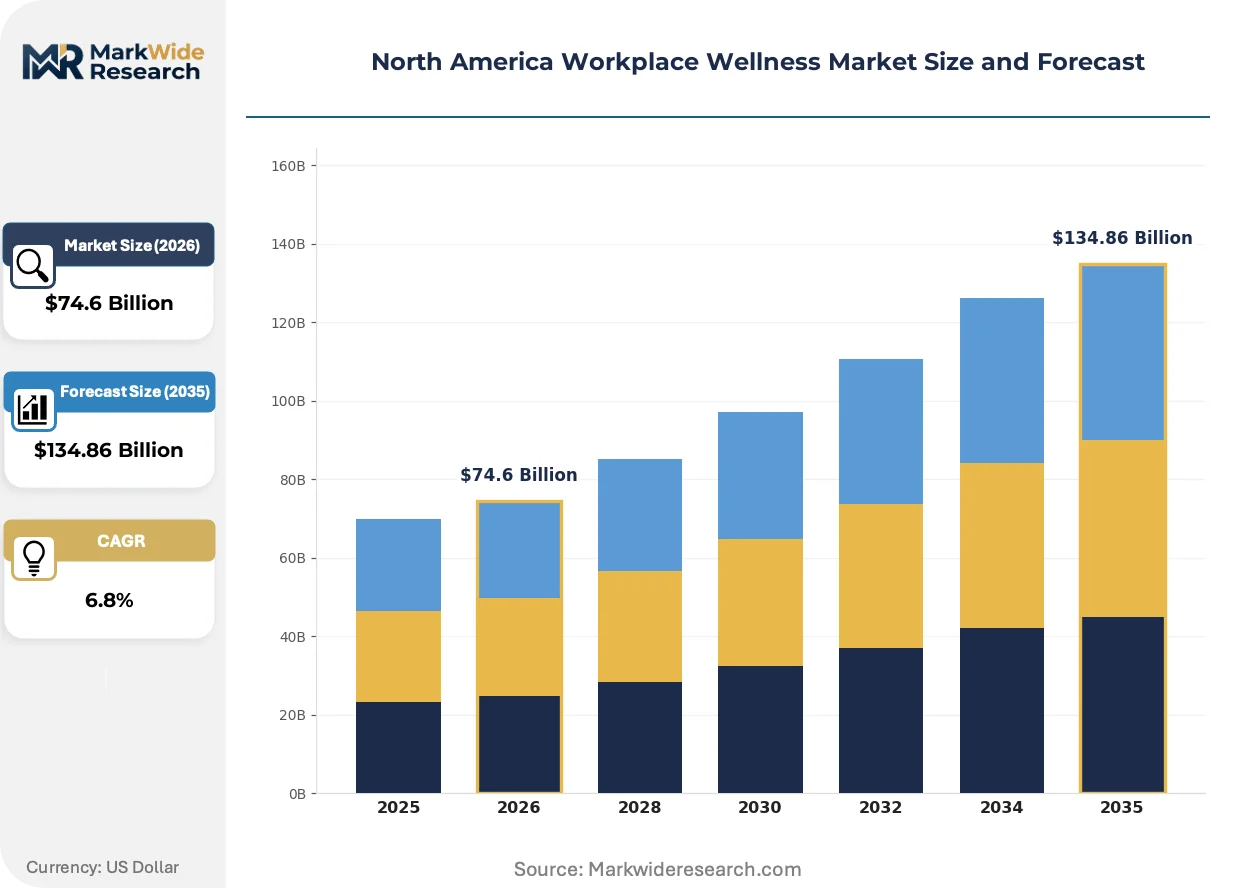
| Market Size in 2026 | $74.6 Billion |
| Market Size in 2035 | $134.86 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Health Assessments, Employee Assistance Programs, Fitness Solutions, Wellness Coaching Delivery Model: On-Site Services, Digital Platforms, Hybrid Programs, Mobile Solutions Employee Type: Blue-Collar Workers, White-Collar Employees, Remote Workers, Management Staff Wellness Focus: Physical Health, Mental Health, Nutritional Support, Stress Management |
| Companies Covered | ComPsych Corporation, Virgin Pulse, Marino Wellness, Modern Health, Teladoc Health, Wellable, EXOS, Privia Health, Fitbit, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Workplace Wellness Market Trends and Innovations
Digital health infrastructure is collapsing the distinction between acute care delivery and ongoing wellness management, with virtual platforms absorbing functions previously siloed in separate benefit categories.
Generative AI coaching interfaces are rewriting how behavioral interventions scale across enterprise populations. Large employers in financial services and technology sectors are piloting conversational agents for cognitive behavioral therapy skill-building. This compression of per-employee coaching costs is rewriting vendor economics and threatening traditional human-delivered program margins.
The Mental Health Parity and Addiction Equity Act enforcement actions by the Department of Labor are tightening audit protocols for employer plan designs. Self-insured corporations face retrospective claims reviews and penalty exposure for quantitative treatment limit disparities. Behavioral health carve-out vendors serving mid-market employers are responding by embedding parity compliance officers into account management structures.
Collective bargaining agreements in unionized sectors are embedding wellness participation incentives into total compensation frameworks. Manufacturing and transportation employers with organized workforces are negotiating biometric screening opt-outs and data privacy protections as standard contract provisions. This pattern is most visible in Midwest automotive assembly plants and Pacific Northwest port logistics operations where labor representation remains strong.
North America Workplace Wellness Market Segmentation
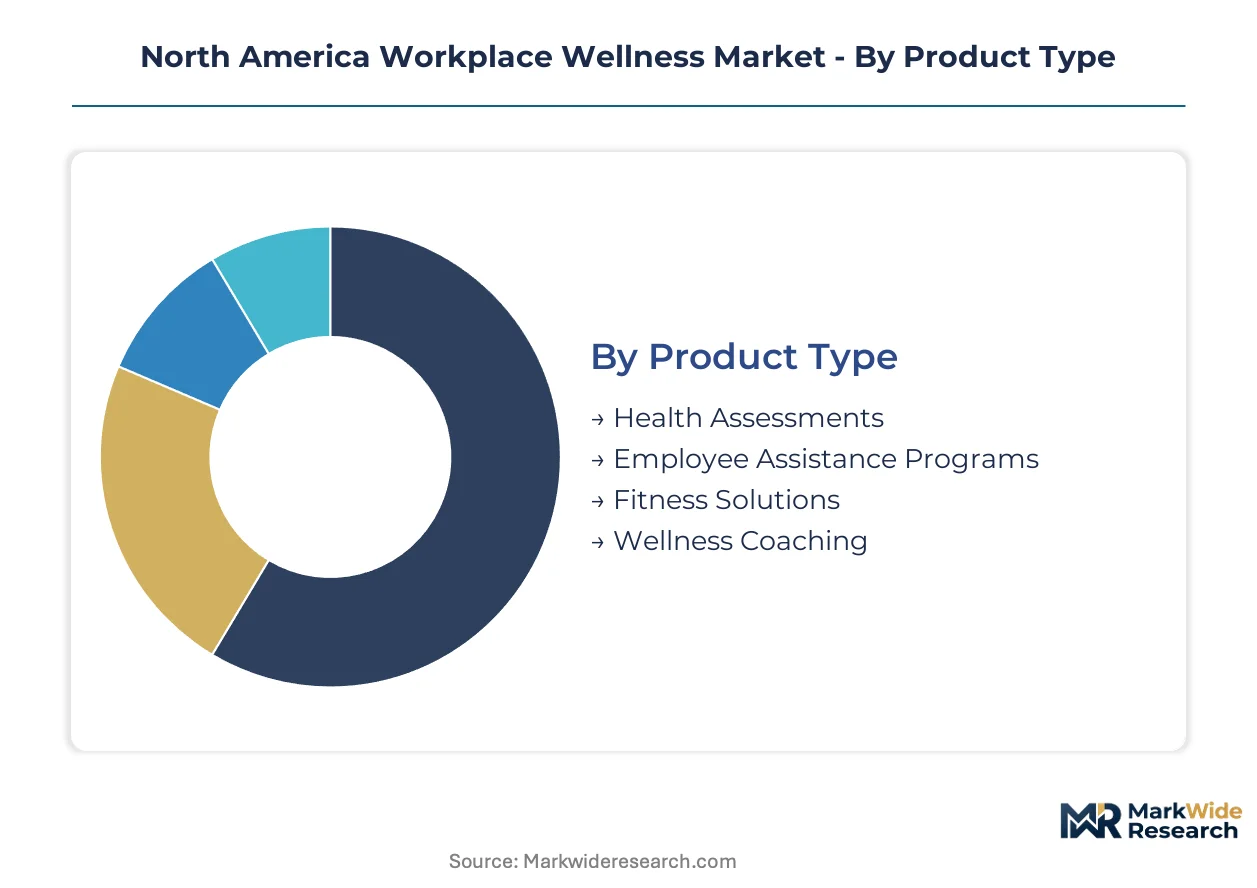
Workplace wellness vendors configure service portfolios around distinct delivery economics and workforce risk profiles. Segmentation clarity enables employers to match intervention intensity with occupational health exposures and benefits budget constraints.
Product Type:
Supply concentration in biometric monitoring hardware and licensed behavioral health networks shapes competitive positioning across product categories.
- Health Assessments:Comprise biometric screenings, health risk questionnaires, and metabolic panel testing protocols. Fortune 500 self-insured employers in the United States concentrate procurement here to satisfy ACA preventive care mandates and negotiate reinsurance rates.
- Employee Assistance Programs:Deliver 24/7 crisis counseling, substance abuse referral networks, and legal/financial consultation hotlines. Established reimbursement pathways through major health plans make this the most mature segment, though growth has flattened relative to digital alternatives.
- Fitness Solutions:Onsite gym facilities, performance coaching protocols, and wearable device subsidies. EXOS anchors this niche with athletic-derived training methodologies adapted for corporate populations.
- Wellness Coaching:One-on-one behavioral counseling for lifestyle modification targeting smoking cessation, weight management, and sleep hygiene. Telephonic and video delivery models are displacing in-person sessions across distributed workforces.
Today's leader: Employee Assistance Programs. Tomorrow's challenger: Wellness Coaching.
Delivery Model:
Cost tier differentiation separates capital-intensive onsite infrastructure from scalable digital subscriptions.
- On-Site Services:Physical clinics, fitness centers, and nursing stations embedded within employer facilities. Silicon Valley technology campuses and Seattle headquarters sustain this premium delivery tier through concentrated headcount density.
- Digital Platforms:Web-based dashboards aggregating wearable data, coaching portals, and health content libraries. Remote and hybrid work arrangements are accelerating employer migration toward this lowest per-employee cost structure.
- Hybrid Programs:Blended delivery combining periodic onsite biometric events with continuous digital engagement tools. Mid-market employers seeking measurable outcomes without full clinic investment favor this intermediate approach.
- Mobile Solutions:Smartphone-native applications for meditation, fitness tracking, and symptom checking. Native app performance and push notification engagement rates determine vendor selection in this category.
Today's leader: Hybrid Programs. Tomorrow's challenger: Digital Platforms.
Employee Type:
Application-specific risk exposures dictate intervention design and vendor specialization.
- Blue-Collar Workers:Manufacturing, logistics, and construction populations facing ergonomic injury and musculoskeletal disorder risks. OSHA compliance obligations drive employer investment in onsite physical therapy and movement screening.
- White-Collar Employees:Knowledge workers in financial services, technology, and professional services roles. Sedentary behavior and chronic stress patterns concentrate demand for mental health counseling and metabolic disease prevention.
- Remote Workers:Distributed employees lacking physical proximity to employer facilities. Virtual care infrastructure and home-delivered wellness kits address isolation and work-life boundary erosion.
- Management Staff:Executive populations with elevated cardiovascular risk profiles and limited schedule flexibility. Concierge medicine partnerships and personalized coaching retain this highest-value segment.
Today's leader: White-Collar Employees. Tomorrow's challenger: Remote Workers.
Wellness Focus:
Volume concentration in physical health programs is yielding share to mental health as parity enforcement tightens.
- Physical Health:Biometric monitoring, fitness programming, and chronic disease management for diabetes, hypertension, and obesity. Self-insured employers track HbA1c and blood pressure metrics to demonstrate plan year savings.
- Mental Health:Counseling access, stress intervention, and psychiatric care coordination. The Mental Health Parity and Addiction Equity Act is compelling benefit redesigns that elevate this focus area to equivalent coverage status.
- Nutritional Support:Dietary counseling, meal planning tools, and subsidized healthy food options. Weight management outcomes tie directly to pharmacy spend reduction in employer ROI calculations.
- Stress Management:Mindfulness training, resilience coaching, and workload boundary protocols. Burnout prevention has become a retention priority for technology sector employers competing for scarce talent.
Today's leader: Physical Health. Tomorrow's challenger: Mental Health.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage between U.S. compliance costs and Canadian provincial subsidies is reshaping vendor deployment patterns across the continent. Mexico's nearshoring corridors attract wellness program investment through lower operational overhead and bilingual workforce requirements.
United States
Fortune 500 self-insured employers in financial services and technology sectors drive demand for biometric monitoring and mental health parity compliance. The Department of Labor enforces Mental Health Parity and Addiction Equity Act standards through retrospective claims audits. Silicon Valley campuses and Seattle headquarters sustain premium onsite clinic infrastructure through concentrated headcount density.
Canada
Provincial health authority partnerships in Ontario and British Columbia expand subsidized counseling access beyond traditional Employee Assistance Program limits. Health Canada guidelines govern workplace mental health accommodation standards. Toronto and Vancouver anchor employer consortium purchasing power for preventive health services across distributed workforces.
Mexico
Manufacturing expansion in Querétaro and Nuevo León creates demand for bilingual wellness programs serving transnational workforces. Mexican labor law mandates employer-provided health services in industrial facilities. Monterrey and Mexico City metropolitan areas concentrate vendor investment for nearshoring corridor coverage.
California
State-level workplace mental health legislation exceeds federal minimums, elevating vendor compliance costs for employers operating in the jurisdiction. Cal/OSHA ergonomic standards mandate movement screening protocols in logistics and manufacturing operations. Los Angeles and San Francisco Bay Area technology employers pilot AI-driven personalization for distributed remote workforces.
Texas
Energy sector employers invest in stress intervention programs for high-pressure operational roles in oilfield services and power generation. Texas Department of Insurance oversight shapes self-insured plan design for large employers. Houston and Dallas-Fort Worth anchor onsite clinic networks serving energy and healthcare corporate headquarters.
North America Workplace Wellness Market Competitive Landscape
United States vendors anchor the enterprise tier through integrated platform scale; Canadian specialists hold regional positioning through provincial health system partnerships. Market structure concentrates around three to five dominant platforms serving Fortune 500 accounts, with mid-market fragmentation across point solution vendors. Two strategic archetypes emerge: virtual-first platforms leveraging telehealth infrastructure, and hybrid providers combining digital tools with onsite clinical capacity. Competitive moves center on strategic partnerships with health plan administrators and portfolio diversification into adjacent behavioral health services.
Within the integrated platform tier, Teladoc Health and Virgin Pulse occupy positions exemplifying virtual care infrastructure and engagement platform consolidation respectively. ComPsych Corporation anchors the Employee Assistance Program channel through national provider network scale. These three entities represent divergent strategic postures: telehealth expansion, wearable data integration, and crisis intervention specialization.
| Leading Market Players |
|---|
| ComPsych Corporation |
| Virgin Pulse |
| Marino Wellness |
| Modern Health |
| Teladoc Health |
| Wellable |
| EXOS |
| Privia Health |
| Fitbit |
| Others |
Pricing and Supply Chain Analysis
Private-equity-rolled-up wellness platforms have concentrated vendor ownership across the United States and Canada, compressing procurement cycles while elevating pricing discipline through bundled service offerings and multi-year enterprise contracts.
Pricing Analysis
Direct-to-employer channels bypass traditional health plan intermediaries, capturing margin that distributors once extracted. Three-tier pricing structure across premium, standard, and economy levels reflects integration depth, with Fortune 500 self-insured buyers commanding volume discounts while mid-market employers face price differentiation tied to biometric outcome guarantees. Cost compression in the standard tier is intensifying because AI-driven coaching interfaces reduce per-employee service delivery costs. Small and mid-sized employers exhibit highest price sensitivity; large technology corporations with self-insured health plans demonstrate lowest sensitivity due to reinsurance rate negotiation leverage.
Supply Chain Analysis
Direct-to-employer digital platforms handle distributed workforce demand, while hybrid providers route through regional clinical staffing networks for onsite service delivery. Licensed behavioral health talent concentrates in the United States, Canada, and select Mexican metropolitan areas, with wearable hardware manufacturing drawing from Chinese component suppliers and Taiwanese semiconductor foundries. Supply chain risk centers on single-source vulnerability for continuous glucose monitoring sensors and heart rate variability tracking devices. Distribution runs through employer benefits consultants and health plan administrators who gate vendor access to self-insured accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in workplace wellness rests on AI-driven coaching automation collapsing service delivery costs while employers upgrade from point solutions to integrated platform tiers.
For Market Incumbents: Anchor market position through exclusive biometric data partnerships with wearable manufacturers and backward integration into licensed behavioral health provider networks. Teladoc Health's virtual care infrastructure and Virgin Pulse's engagement platform consolidation demonstrate defensive moat construction. Threats from generative AI coaching interfaces demand rapid capability acquisition in conversational agent deployment. For New Entrants and Emerging Players: The gap between premium concierge executive programs and economy-tier Employee Assistance Program commoditization offers entry points for mid-market hybrid solutions. Target Canadian provincial health authority partnerships where subsidized mental health counseling access exceeds traditional EAP limits. Go-to-market leverage rests on bilingual program delivery for Mexico nearshoring corridors serving transnational manufacturing workforces. For Investors and Strategic Acquirers: Valuations sit cheapest among point-solution vendors facing integration pressure from platform consolidation. Long-term viability favors vendors with established health plan administrator partnerships and proven biometric outcome measurement. Watch Mental Health Parity and Addiction Equity Act enforcement actions as inflection indicator for behavioral health service demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| AI Coaching Platform Development | Generative conversational agents collapse per-employee behavioral intervention costs below human-delivered program economics. |
| Biometric Data Integration Partnership | Wearable manufacturer alliances lock exclusive data feeds into employer wellness dashboards and coaching algorithms. |
| Provincial Health Authority Collaboration | Ontario and British Columbia partnerships expand subsidized counseling access beyond traditional EAP reimbursement limits. |
| Behavioral Health Provider Network Acquisition | Licensed therapist concentration in coastal metropolitan areas creates scarcity value for credentialing infrastructure control. |
| Nearshoring Corridor Program Localization | Querétaro and Nuevo León manufacturing expansion demands bilingual wellness delivery for transnational workforce coverage. |
Research Methodology
Bottom-up employer segmentation modeling reconciled against top-down vendor revenue tracking forms the analytical core of this study. Primary interviews with benefits directors at Fortune 500 corporations, health plan administrator procurement leads, wellness platform product executives, and clinical network operations managers combined with secondary validation against SEC 10-K filings, OSHA enforcement databases, Department of Labor parity audit records, and health benefits consultant market assessments. Triangulation between self-insured employer spending patterns and vendor disclosed account metrics ensures cross-verification.
Historical trendline analysis of biometric screening penetration, Employee Assistance Program utilization rates, and digital platform subscription growth established baseline trajectories across the projection horizon. Segmentation modeling incorporated product type, delivery model, employee risk classification, and wellness focus area. CAGRs derived from regression analysis of employer wellness budget allocations and vendor pricing evolution, with sensitivity testing around AI adoption curves and mental health parity compliance cost impacts.
Caveats apply where Mental Health Parity and Addiction Equity Act enforcement intensity, AI coaching efficacy validation, or provincial subsidy policy shifts in Canada could materially shift the outlook. Forecasts reflect documented assumptions regarding remote work permanence and self-insurance penetration trends. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Personal Health
Foot Insole Market
Personal Health
North America Hair Loss Treatment Products Market
Personal Health
Piercing Aftercare Spray Market
Personal Health
US Vaginal Moisturizers and Lubricants Market
Personal Health
Blackhead Removing Vacuum Market
Personal Health
Sextech and Sexual Wellness Market
Personal Health
Maternity Personal Care Products Market
Personal Health
Biohacking Market
Personal Health
Interdental Brush Market
Personal Health
Infrared Sauna Blankets Market
Personal Health
PTBCHA Market
Personal Health
Global Health and Wellness Market
Personal Health
Menopause Wellness Market
Personal Health
Health Check-Up Market
Personal Health
Disposable Underwear Market
Personal Health
High Concentration Respiratory Masks Market