
 Medical Wellness Market | 2026-2036
Medical Wellness Market Size, Share, and Industry Trends Forecast 2026-2036
Medical Wellness Market Analytics
Modular bundling of telehealth consultations with wearable monitoring devices is expanding consumer choice in preventive care programs. Abbott Laboratories leverages its diagnostic technology leadership to anchor integrated wellness ecosystems across multiple geographies. Truworth Wellness competes through employer-focused program design that controls chronic disease risk pools. VLCC Health Care Limited dominates beauty-wellness crossovers in South Asia through its clinic network.
Medical wellness encompasses evidence-based health services, nutritional interventions, fitness protocols, and monitoring technologies designed to prevent disease onset and optimize physiological function rather than treat acute conditions. Diagnostic wearables incorporate photoplethysmography sensors, accelerometers, and continuous glucose monitors to capture real-time biometric streams for clinical interpretation. Preventive care applications command the largest addressable base as employers and insurers redirect spending from reactive treatment. Telehealth delivery modes are capturing the fastest growth trajectory by removing geographic friction from specialist access and enabling asynchronous care coordination.
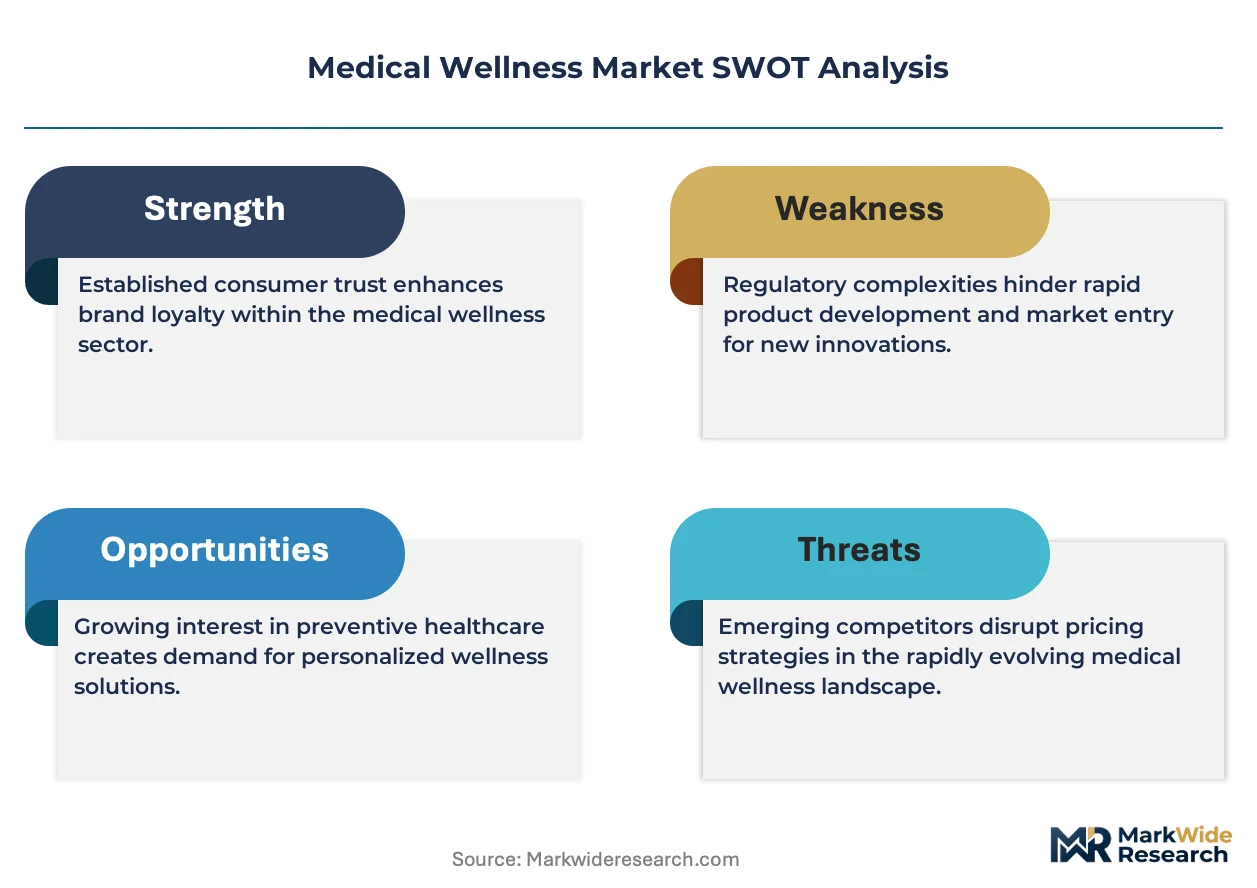
FDA oversight of Software as a Medical Device governs algorithmic diagnostic tools, while HIPAA mandates govern data exchange between wellness platforms and electronic health records. The EU AI Act introduces risk-classification requirements for automated health recommendations, tightening compliance obligations for cross-border service providers. Stakeholders must monitor evolving reimbursement codes for remote patient monitoring as payors recalibrate coverage boundaries between wellness and clinical care.
Market Dynamics
The medical wellness sector pivots on employer-sponsored preventive care mandates, with Fortune 500 companies redirecting healthcare budgets from reactive treatment toward biometric monitoring and chronic disease interception programs.
Growth Catalysts
- Remote Patient Monitoring Reimbursement:CMS reimbursement codes for continuous glucose monitoring and blood pressure telemetry incentivize provider adoption of connected wellness platforms in the United States.
- Employer Self-Insurance Migration:Large self-insured employers in Germany bundle wearable diagnostics with telehealth access to compress claims exposure in cardiovascular and metabolic risk pools.
- Photoplethysmography Miniaturization:Advances in optical sensor integration enable consumer-grade devices to capture clinical-grade heart rate variability data for stress and sleep optimization protocols.
Market Restraints
- Semiconductor Supply Concentration:Taiwan-based foundries fabricate over 70 percent of advanced biosensor chips, exposing wearable manufacturers to single-source vulnerability.
- Algorithmic Validation Burden:FDA 510(k) clearance timelines for Software as a Medical Device extend 18-24 months, delaying commercialization of AI-powered diagnostic features.
- Data Interoperability Friction:HIPAA constraints on electronic health record exchange fragment longitudinal wellness data across incompatible provider systems.
Strategic Opportunities
- Chronic Disease Management in India:Underpenetrated employer wellness markets in tier-2 cities offer first-mover positioning as diabetes prevalence accelerates among working-age populations.
- EU AI Act Compliance Services:Risk-classification mandates for automated health recommendations create advisory revenue streams for platforms navigating cross-border algorithmic transparency obligations.
- Pharmacy-Integrated Distribution:CVS Health and Walgreens clinic networks in the United States embed wellness coaching alongside prescription fulfillment, capturing medication-adjacent behavior change revenue.
Industry Challenges
- Behavioral Science Talent Scarcity:Platforms struggle to recruit intervention designers capable of translating biometric feedback into sustained user engagement protocols.
- Legacy EHR Integration Complexity:Enterprise wellness deployments require costly middleware development to synchronize with Epic and Cerner record systems without triggering data breach liability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Medical Wellness Market |
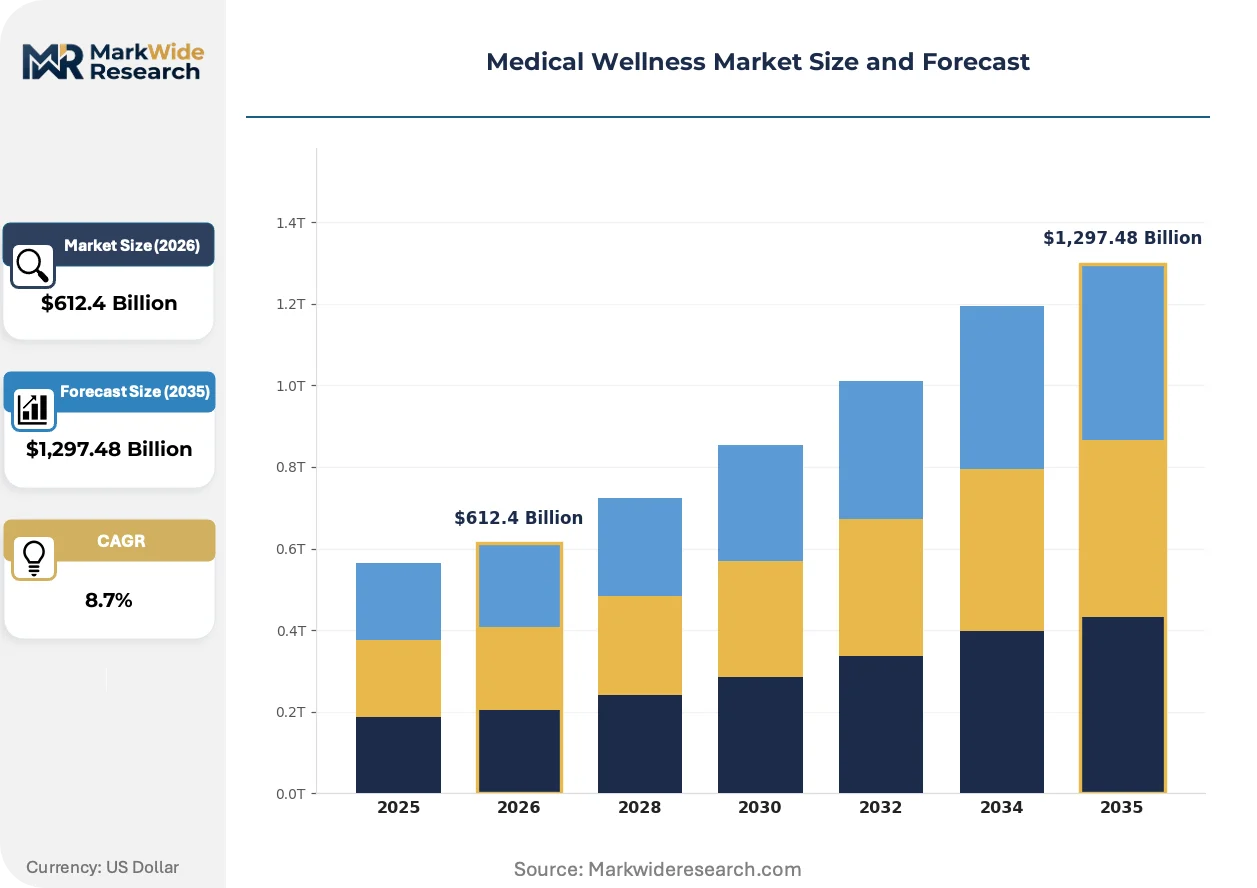
| Market Size in 2026 | $612.4 Billion |
| Market Size in 2035 | $1,297.48 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Supplements, Nutrition Products, Medical Devices, Fitness Equipment Application: Preventive Care, Chronic Disease Management, Rehabilitation, Lifestyle Improvement End User: Individuals, Healthcare Providers, Corporate Wellness Programs, Fitness Centers Delivery Mode: Telehealth, In-Person Consultations, Mobile Applications, Online Platforms |
| Companies Covered | Truworth Wellness, AsiaMedic Limited, Naluri, Mednefits, Magenta Wellness Pte Ltd., Minmed Group Pte Ltd, BDMS Wellness Clinic, VLCC Health Care Limited, Abbott Laboratories, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Medical Wellness Market Evolving Landscape
Continuous biometric streaming and algorithmic personalization are collapsing the boundary between consumer wellness and clinical surveillance, forcing regulatory frameworks to recalibrate oversight thresholds.
Multi-sensor wearable arrays incorporating accelerometry, galvanic skin response, and non-invasive glucose estimation are modularizing preventive care delivery. Self-insured employers in the United States deploy these devices as condition-of-coverage requirements for metabolic syndrome populations. The technology is modularizing risk stratification by enabling real-time intervention triggers that previously required quarterly lab panels.
The EU AI Act's risk-classification framework for health recommendation algorithms imposes conformity assessment obligations on wellness platforms operating across member states. High-risk systems must demonstrate bias mitigation and human oversight before market entry. German and French wellness providers are restructuring algorithm governance committees to preempt regulatory enforcement actions.
Subscription-based wellness coaching is displacing one-time biometric screenings as the dominant employer procurement model. Human-resources benefit managers in China negotiate multi-year contracts bundling device provision with nutritionist and sleep-coach access. This shift concentrates vendor selection power with benefits consultants at Mercer and Willis Towers Watson who control RFP processes.
Medical Wellness Market Segmentation
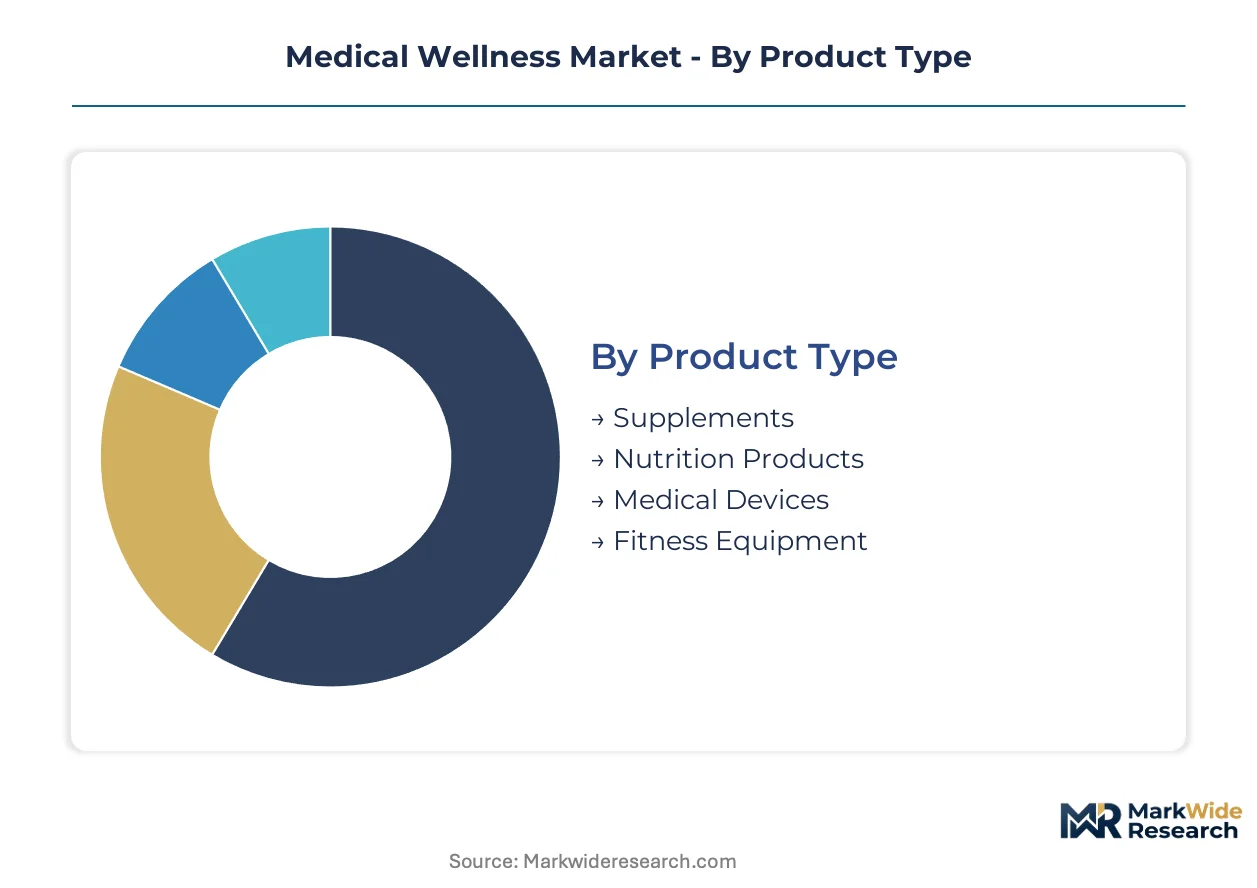
Segmentation in medical wellness reveals divergent upgrade cycles across hardware, software, and service layers. Preventive care applications compress replacement timelines for biometric devices while telehealth platforms demand continuous software iteration.
Product Type:
Replacement cycles vary sharply across physical and ingestible product categories, with sensor hardware refreshing every 18-36 months versus formulation stability in nutritional products.
- Supplements:Formulations combine bioavailable micronutrients, adaptogenic botanicals, and targeted probiotics with batch-certified purity standards. Demand concentrates in direct-to-consumer subscription models in the United States, where FDA cGMP enforcement and third-party NSF certification drive premium pricing tiers.
- Nutrition Products:Medical foods and condition-specific meal replacements deliver precise macronutrient ratios for metabolic syndrome populations. German statutory health insurers now reimburse diabetes-specific nutrition products, accelerating pharmacy channel penetration for Abbott and Nestlé Health Science portfolios.
- Medical Devices:Continuous glucose monitors, blood pressure telemetry cuffs, and pulse oximetry arrays capture real-time biometric streams.
- Fitness Equipment:Connected strength and cardiovascular systems integrate with wearable ecosystems for longitudinal performance tracking.
Medical Devices sits at the top of the volume ranking, with Nutrition Products climbing the fastest.
Application:
Application segments stratify by clinical intensity, from asymptomatic population screening through post-acute functional restoration.
- Preventive Care:Biometric screening protocols, vaccination reminders, and lifestyle coaching intercept disease onset before symptomatic presentation. Self-insured employers in China mandate annual health risk assessments as coverage conditions, with Ping An Insurance integrating wearable compliance into premium discount calculations.
- Chronic Disease Management:Continuous monitoring and medication adherence programs stabilize cardiovascular, metabolic, and respiratory conditions between clinical encounters. India's National Health Mission is expanding hypertension and diabetes management protocols into tier-2 city primary health centers.
- Rehabilitation:Post-surgical and injury recovery protocols restore functional capacity through supervised exercise and remote monitoring.
- Lifestyle Improvement:Sleep optimization, stress reduction, and performance enhancement programs target subclinical populations.
Preventive Care captures the dominant revenue share, while Chronic Disease Management expands most quickly as payors shift reimbursement toward longitudinal risk management.
End User:
Procurement authority determines pricing power and contract structure, with employers leveraging scale against fragmented individual purchasing.
- Individuals:Direct consumers purchase devices, supplements, and coaching through retail and e-commerce channels with limited price negotiation leverage.
- Healthcare Providers:Hospital systems and physician groups prescribe remote patient monitoring as reimbursed clinical services under CMS codes in the United States.
- Corporate Wellness Programs:Fortune 500 benefits managers negotiate multi-year contracts bundling biometric screening, device provision, and telehealth access. Willis Towers Watson and Mercer consultants control vendor selection through standardized RFP processes.
- Fitness Centers:Boutique studios and health club chains embed wellness coaching into membership tiers to differentiate against low-cost competitors.
Corporate Wellness Programs command the largest contract values, with Healthcare Providers gaining share fastest as reimbursement codes expand for preventive monitoring.
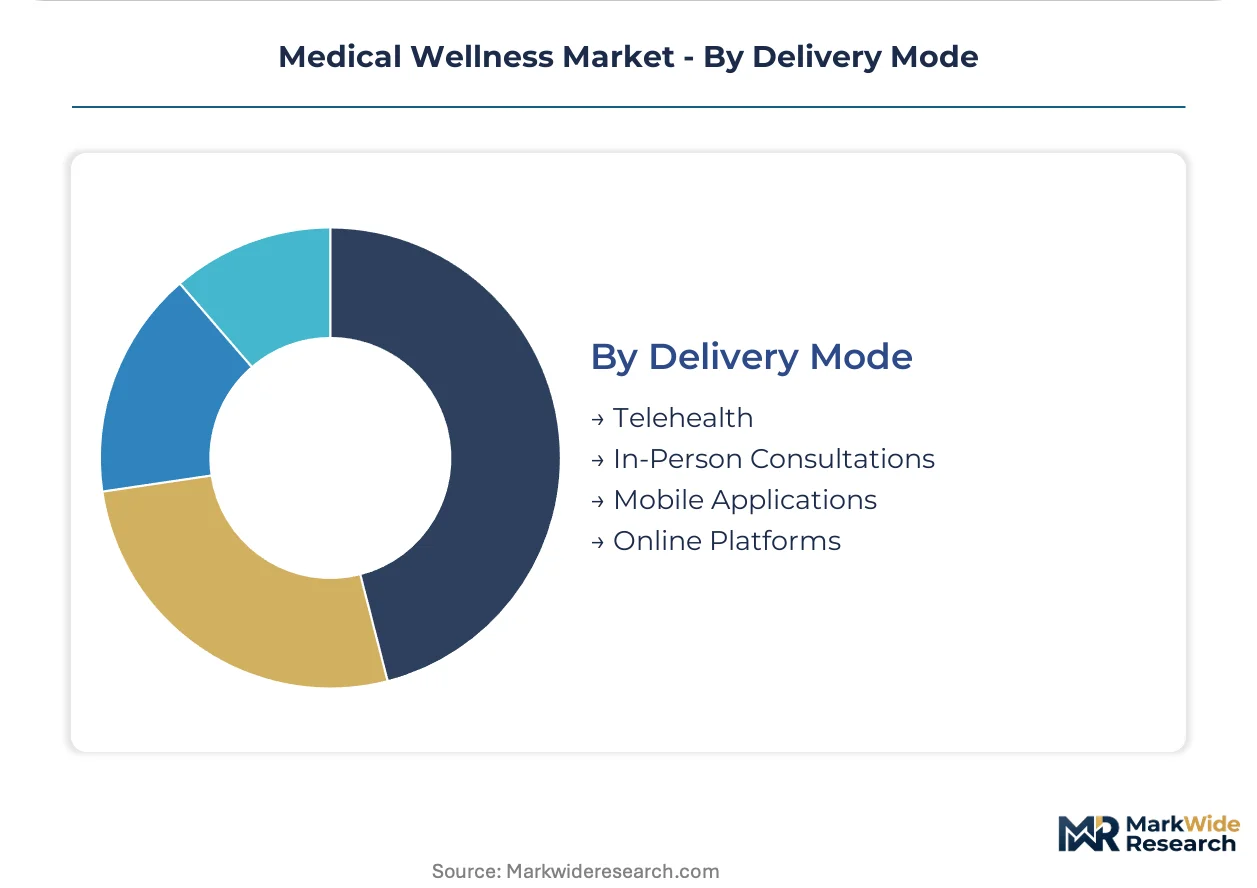
Delivery Mode:
Channel economics shift dramatically between synchronous human interaction and algorithmically mediated self-service platforms.
- Telehealth:Synchronous video consultation and asynchronous messaging connect patients with specialists regardless of geographic proximity. Germany's Digital Healthcare Act (DVG) established permanent reimbursement for video consultations, eliminating the pandemic-era temporary authorization framework.
- In-Person Consultations:Clinic-based assessments deliver physical examination capabilities that remote modalities cannot replicate. VLCC Health Care Limited operates 300+ centers across South Asia combining aesthetic services with metabolic screening.
- Mobile Applications:Smartphone-native platforms deliver coaching content, medication reminders, and biometric visualization with minimal marginal cost per user.
- Online Platforms:Web-based portals aggregate wellness content, e-commerce, and community features for desktop-centric engagement.
Telehealth leads current investment flows, with Mobile Applications showing the steepest user acquisition trajectory as smartphone penetration saturates emerging markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Medical wellness originated in employer-sponsored health programs across the United States before spreading to Germany's statutory insurance system and China's state-owned enterprise networks. Today demand concentrates where corporate self-insurance and aging demographics intersect.
United States
Fortune 500 employers mandate biometric screening as coverage conditions while CMS reimbursement codes for remote patient monitoring accelerate provider adoption. FDA oversight of Software as a Medical Device governs algorithmic diagnostic tools. The Boston-Cambridge corridor hosts concentrated digital health venture activity.
Germany
Statutory health insurers reimburse diabetes-specific nutrition products and video consultations under the Digital Healthcare Act. The EU AI Act imposes conformity assessment obligations on algorithmic health recommendations. Berlin and Munich anchor wellness platform development clusters.
China
Ping An Insurance integrates wearable compliance into premium discount calculations for working-age populations. NMPA regulates continuous glucose monitors and connected diagnostic devices. Shanghai and Shenzhen concentrate telehealth platform engineering talent.
India
The National Health Mission expands hypertension and diabetes management into tier-2 city primary health centers. CDSCO oversees medical device registration for imported wearables. Bangalore and Hyderabad host diagnostic technology R&D facilities.
United Arab Emirates
MOHAP mandates employer wellness screening for foreign worker visa renewals in Dubai and Abu Dhabi. The Dubai Health Authority licenses telehealth platforms for cross-border service delivery. Dubai Healthcare City clusters preventive care clinics serving Gulf expatriate populations.
Medical Wellness Market Competitive Landscape
The competitive structure tilts toward integrated health conglomerates with diagnostic device manufacturing capabilities. Market concentration remains moderate with distinct tiering between multinational laboratory suppliers, regional clinic networks, and digital-first coaching platforms. Three archetypes dominate: diagnostic technology anchors, employer program specialists, and beauty-wellness crossovers. Consolidation proceeds through vertical acquisition of coaching platforms by device manufacturers and strategic partnerships between insurers and telehealth providers.
Among diagnostic-anchored conglomerates, Abbott Laboratories exemplifies integrated wellness ecosystem development across multiple geographies. Truworth Wellness occupies a position within employer-focused program design, controlling chronic disease risk pools through benefits consulting relationships. VLCC Health Care Limited represents the beauty-wellness crossover archetype, leveraging clinic network density in South Asian metropolitan markets.
| Leading Market Players |
|---|
| Truworth Wellness |
| AsiaMedic Limited |
| Naluri |
| Mednefits |
| Magenta Wellness Pte Ltd. |
| Minmed Group Pte Ltd |
| BDMS Wellness Clinic |
| VLCC Health Care Limited |
| Abbott Laboratories |
| Others |
Value Network & Pricing Analysis
Silicon wafer spot prices cascade through biosensor fabrication into three-tier hardware pricing across consumer, clinical, and enterprise wellness segments. Taiwan-based foundry concentration amplifies cost volatility for photoplethysmography chipsets, compressing margins on mid-tier wearable devices while premium FDA-cleared monitors maintain pricing power through certification scarcity.
Pricing Analysis
Subscription bundling of devices with coaching services dominates employer procurement, separating premium telehealth-integrated programs from standard device-only tiers and economy self-service applications. Price differentiation hinges on FDA 510(k) clearance status and biometric data granularity, with clinical-grade heart rate variability commands substantial premiums over consumer PPG estimates. Cost compression in the standard tier intensifies as Chinese OEMs flood direct-to-consumer channels with unregulated alternatives. Corporate benefits managers exhibit lowest price sensitivity due to claims reduction calculus, while individual purchasers in emerging markets face acute budget constraints.
Supply Chain Analysis
Freight cost spikes from Asia-Pacific semiconductor hubs into European and North American assembly plants have compressed logistics budgets for wearable manufacturers reliant on just-in-time component flows. Taiwan, South Korea, and China concentrate advanced biosensor chip fabrication, with photodiode arrays and accelerometer MEMS drawing from concentrated foundry capacity. Single-source vulnerability around Taiwan Semiconductor exposes device makers to geopolitical disruption. Distribution runs through pharmacy retail networks in the United States and statutory insurer channels in Germany, with direct-to-consumer e-commerce gaining share fastest in China and India.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic arbitrage opportunities concentrate where EU AI Act compliance costs exceed India's regulatory lightness, enabling cost-advantaged algorithm development in Bangalore and Hyderabad for export into European markets.
For Market Incumbents: Lock in exclusive data-sharing agreements with Epic and Cerner to preempt middleware fragmentation that threatens enterprise wellness deployments. Deepen backward integration into optical sensor design to offset Taiwan foundry concentration risk. Prioritize FDA breakthrough device designation for AI diagnostic features to extend clearance timelines against emerging competitors. For New Entrants and Emerging Players: Launch via pharmacy-embedded coaching partnerships in the United States, capturing medication-adjacent behavior change revenue that incumbents overlook. Target tier-2 Indian cities where employer wellness penetration lags diabetes prevalence acceleration. Pursue white-label telehealth infrastructure from established platforms to compress time-to-reimbursement. For Investors and Strategic Acquirers: Asymmetric upside sits with diagnostic-anchored platforms possessing both wearable hardware and algorithmic software capabilities, as consolidation favors integrated ecosystems over point solutions. Five-to-ten year viability requires demonstrated CMS reimbursement code capture and cross-border regulatory navigation. Watch for FDA 510(k) clearance acceleration as signal of competitive inflection.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission | Clearance under Software as a Medical Device governs algorithmic diagnostic commercialization timelines. |
| EU AI Act Conformity Assessment | Risk-classification mandates impose transparency obligations on cross-border health recommendation platforms. |
| Hospital System Partnership | Epic and Cerner integration contracts unlock enterprise wellness deployment at Fortune 500 employers. |
| Software Companion Development | Asynchronous coaching modules differentiate subscription tiers against device-only competitors. |
| Reimbursement Strategy | CMS remote patient monitoring codes determine provider adoption of connected wellness platforms. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with benefits consultants at Mercer and Willis Towers Watson, biomedical engineers at wearable OEMs, GPO contracts managers, and telehealth platform executives with secondary validation against FDA 510(k) filings, CMS reimbursement code databases, EU AI Act regulatory texts, and hospital procurement records. Bottom-up segment sizing triangulated against top-down macroeconomic anchors.
Segment-weighting across product type, application, end user, and delivery mode dimensions shaped volume and value outputs across the projection horizon. CAGRs derived from regression analysis of historical adoption curves and forward-looking reimbursement expansion scenarios. Modeling incorporated semiconductor supply elasticity, employer self-insurance migration rates, and regulatory clearance timeline distributions as industry-specific inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under FDA enforcement acceleration or Taiwan supply disruption scenarios. Forecasts reflect documented assumptions regarding reimbursement code expansion and algorithmic validation burden evolution. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Personal Health
US Vaginal Moisturizers and Lubricants Market
Personal Health
Health Coaching Market
Personal Health
Piercing Aftercare Spray Market
Personal Health
Sextech and Sexual Wellness Market
Personal Health
Europe Hair Loss Treatment Products Market
Personal Health
Tongue Scraper Market
Personal Health
Asia Pacific Hair Loss Treatment Products Market
Personal Health
Asia-Pacific Maternity & Personal Care Market
Personal Health
Earwax Removal Products Market
Personal Health
Jet Lag Therapy Market
Personal Health
Middle East and Africa Smoking Cessation and Nicotine De-Addiction Market
Personal Health
Corporate Wellness Market
Personal Health
Global OTC Hair Loss Treatment Market
Personal Health
Tick Repellent Market
Personal Health
Sexual Wellness Market
Personal Health
Foot Insole Market