
 Asia-Pacific Mobile Health Market | 2026-2036
Asia-Pacific Mobile Health Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Mobile Health Market Outlook
The gap between premium clinical-grade wearables and consumer fitness trackers is hardening in the Asia-Pacific mobile health landscape. Philips Healthcare leverages its hospital relationships to sustain dominance in regulated remote monitoring systems across Australia and Japan. Samsung Electronics anchors the consumer tier through Galaxy Watch integrations with national health databases in South Korea, while Huawei Technologies competes aggressively in China's domestic telemedicine infrastructure despite overseas restrictions.
Asia-Pacific mobile health encompasses portable digital technologies that transmit physiological data through Bluetooth, Wi-Fi, or cloud computing architectures to enable clinical decision-making or wellness management. These systems typically incorporate biosensors measuring heart rate variability, blood oxygen saturation, or glucose levels with FDA-equivalent accuracy thresholds for medical use cases. Wearable devices and telemedicine solutions command the deepest margin pools as chronic disease management applications expand across aging populations in Japan and South Korea. mHealth apps face structural pressure from platform fees and data localization mandates, while health monitoring systems embedded in home care settings capture fastest growth as hospital-at-home programs proliferate across Singapore and Taiwan.
Japan's PMDA and South Korea's MFDS enforce divergent software-as-medical-device pathways, creating compliance complexity for cross-border platform deployment. India's CDSCO and China's NMPA are tightening data sovereignty requirements that reshape cloud architecture decisions for foreign entrants. Australia's TGA alignment with EU MDR streamlines certain approval routes but leaves cybersecurity standards fragmented. Stakeholders must monitor which regulator moves first on AI-diagnostic integration rules, as that jurisdiction will likely set the template for regional harmonization efforts.
Market Dynamics
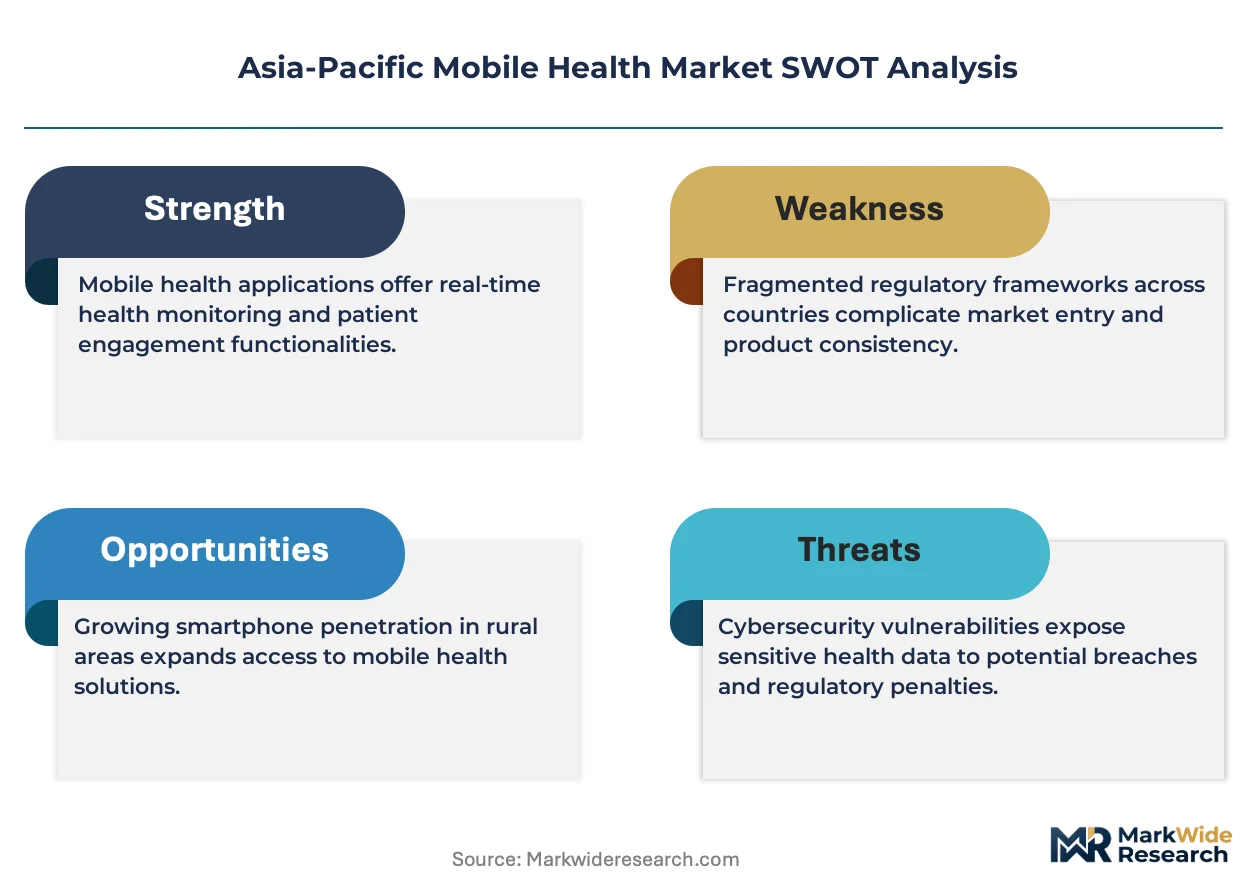
Hospital-at-home program expansion across Singapore and Taiwan is compressing care delivery timelines and forcing platform vendors to integrate with legacy HIS architectures. This structural shift privileges vendors with existing enterprise relationships over point-solution entrants.
Growth Catalysts
- India's PLI scheme for medical electronics:Domestic manufacturing incentives reduce import dependency for biosensor components and accelerate local platform deployment in tier-2 hospital networks.
- Japan's PMDA digital health guidelines:Regulatory clarity on software-as-medical-device pathways enables faster approval cycles for AI-integrated remote monitoring tools targeting chronic disease management.
- Cloud-connected diagnostic tools:China's tier-2 city hospital networks deploy these at scale, creating infrastructure pull for compatible patient monitoring peripherals and data integration middleware.
Market Restraints
- Data localization mandates:India's CDSCO and China's NMPA require sovereign cloud storage, fragmenting architecture decisions and raising compliance costs for cross-border platform operators.
- Sensor component concentration:High-precision biosensor supply concentrates in specialized East Asian foundries, exposing procurement timelines to single-source vulnerability.
- Divergent software-as-medical-device pathways:Japan's PMDA and South Korea's MFDS enforce incompatible technical documentation standards, delaying multi-market launches by 8-14 months.
Strategic Opportunities
- Vietnam's underpenetrated rural health networks:Provincial hospital digitization programs create first-mover advantage for remote monitoring vendors willing to build local technical support infrastructure.
- AI-diagnostic integration rules:Whichever regulator moves first on validation frameworks will set the template for regional harmonization, rewarding early compliance investment.
- Bluetooth-5 and edge computing convergence:Lower-latency physiological data transmission enables real-time clinical decision support in ambulance and home care settings previously limited to hospital environments.
Industry Challenges
- Interoperability engineering talent scarcity:Shortage of engineers capable of bridging HL7-FHIR standards with proprietary hospital information systems slows integration timelines.
- Cybersecurity certification complexity:Australia's TGA maintains fragmented standards relative to Singapore's HSA requirements, forcing redundant penetration testing cycles.
- Legacy HIS integration friction:Decades-old hospital databases in Southeast Asia lack API-native architectures, requiring expensive middleware development for data exchange.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Mobile Health Market |
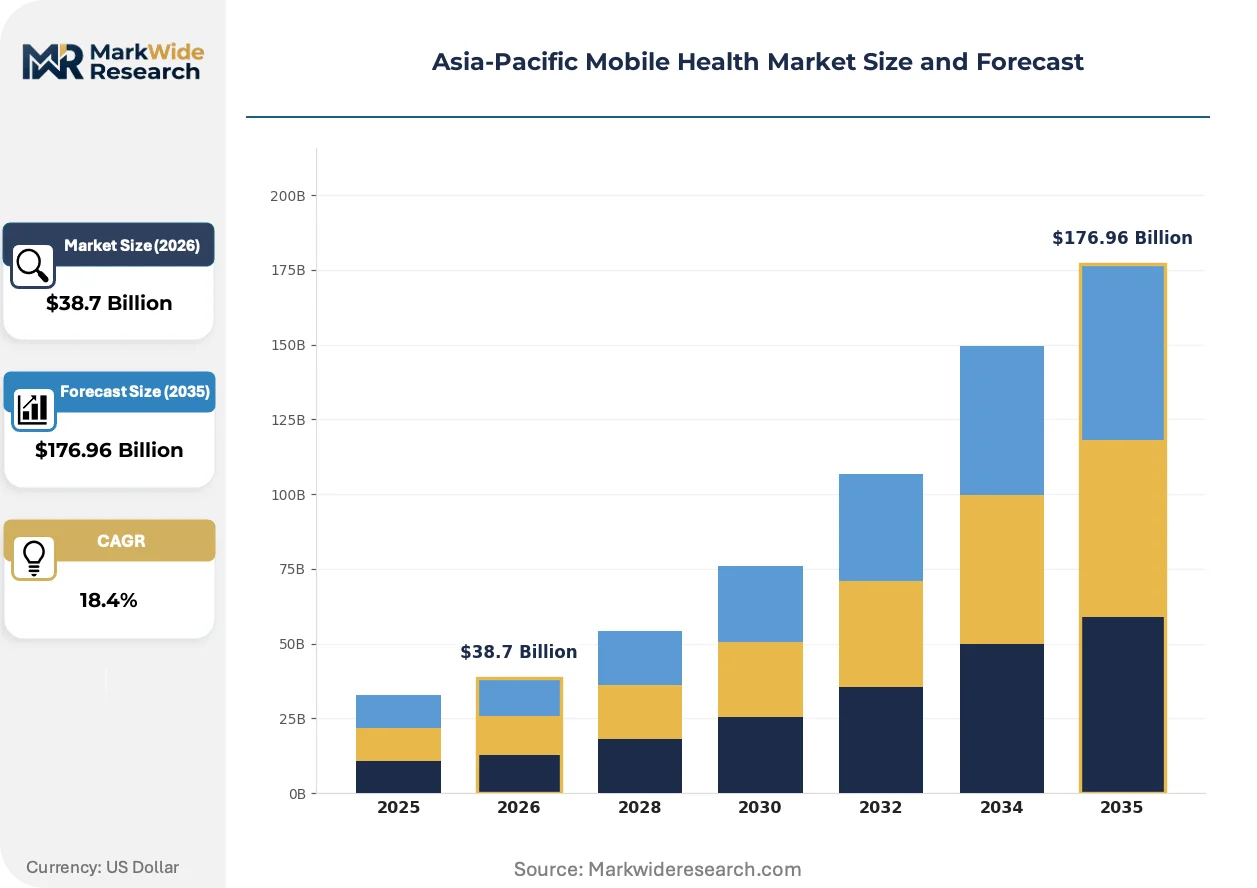
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $176.96 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wearable Devices, mHealth Apps, Health Monitoring Systems, Telemedicine Solutions Technology: Bluetooth, NFC, Wi-Fi, Cloud Computing End User: Patients, Healthcare Providers, Health Insurance Companies, Fitness Enthusiasts Application: Chronic Disease Management, Fitness Tracking, Remote Patient Monitoring, Medication Management |
| Companies Covered | Cisco Systems, Apple, Philips Healthcare, Huawei Technologies, Google, Medtronic, Samsung Electronics, Omron Corporation, Johnson & Johnson, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Mobile Health Market Strategic Shifts
Remote patient monitoring architectures are fragmenting between closed hospital-system ecosystems and open consumer-facing platforms, with regulatory alignment determining which model captures margin. This bifurcation is accelerating vendor specialization decisions.
Continuous glucose monitoring with factory-calibrated sensors is consolidating clinical validation standards for wearable biosensors. Endocrinology departments in South Korean tertiary hospitals adopt these systems for outpatient diabetes management at twice the pace of Southeast Asian peers. The technology is consolidating reimbursement pathways around single-vendor platform commitments rather than device-agnostic data standards.
PMDA's 2024 guidance on machine-learning-enabled diagnostic algorithms imposes locked-algorithm requirements that prevent real-time model updates without re-approval. Japanese medical device manufacturers restructure R&D pipelines to front-load algorithm training before submission. Cardiology AI tools face the steepest compliance burden given the agency's heightened scrutiny of arrhythmia classification outputs.
Hospital procurement committees in Australia's public health system now mandate ISO 27001 certification as a gate criterion for remote monitoring tenders, displacing previous security self-assessment regimes. Smaller platform vendors without dedicated compliance functions lose access to state-level contracts. Victoria and New South Wales health departments enforce this most strictly, while Queensland maintains transitional grace periods through 2025.
Asia-Pacific Mobile Health Market Segmentation
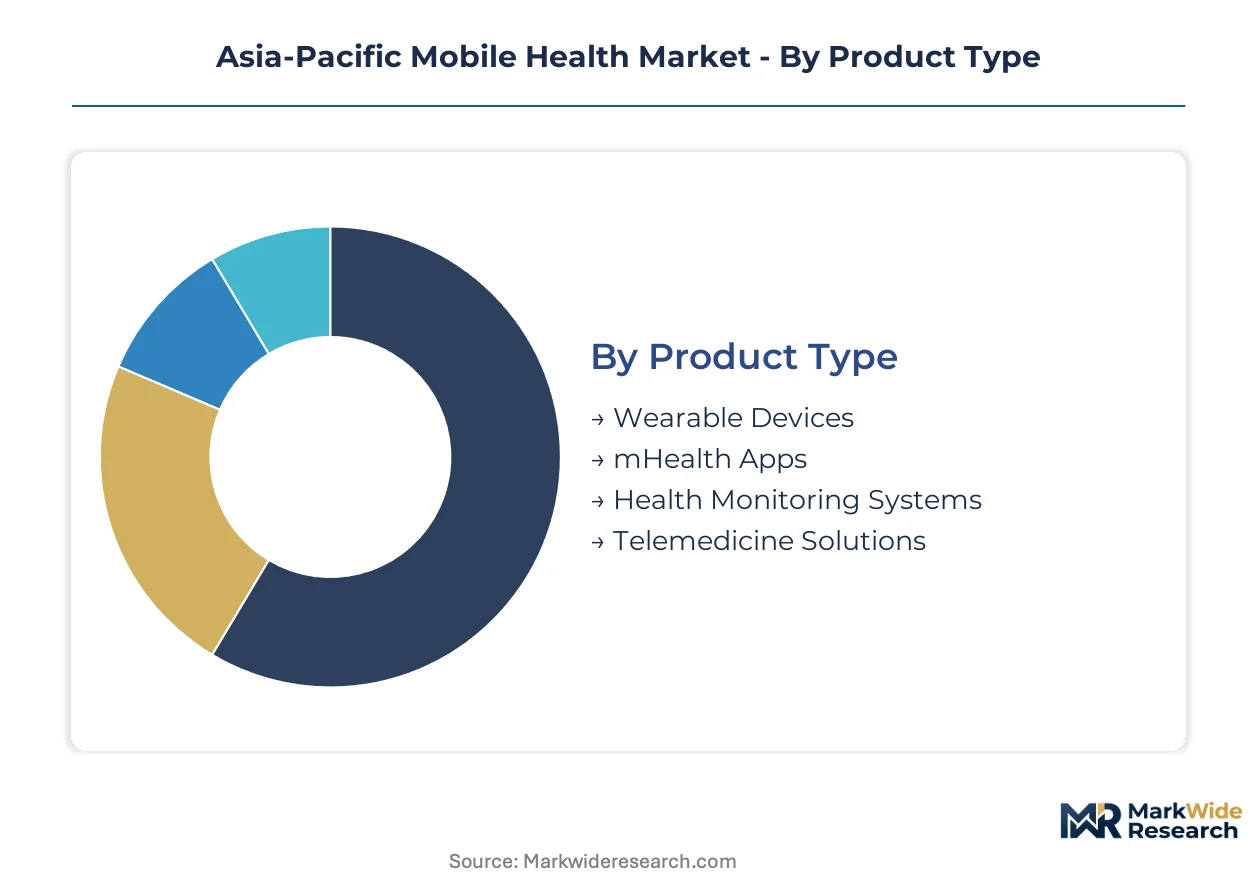
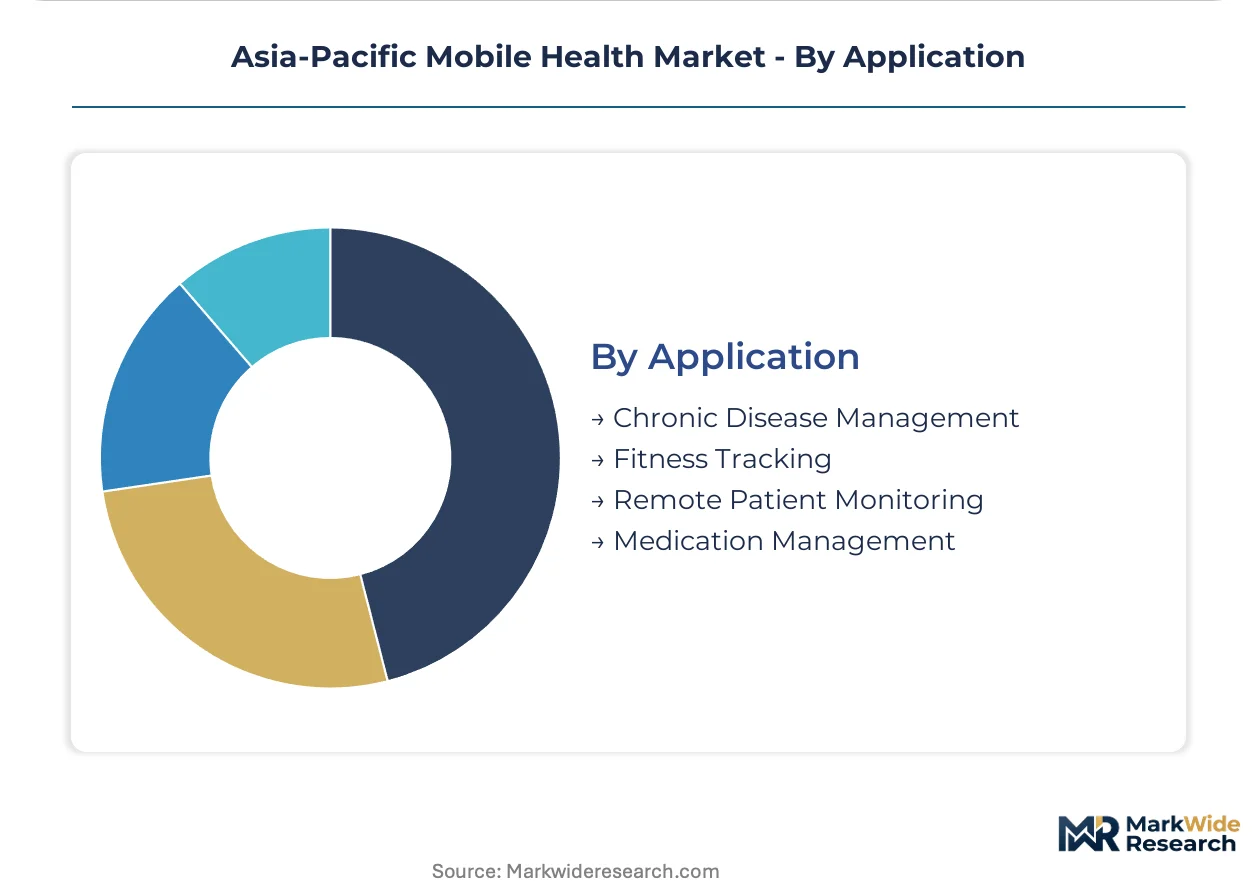
Segmentation reveals how procurement priorities diverge across the Asia-Pacific mobile health ecosystem. Hospital administrators, insurance payers, and individual consumers each activate distinct technology combinations based on reimbursement pathways and clinical validation requirements.
Product Type:
Purchasing committees weigh regulatory certification depth against per-unit cost when selecting hardware-software bundles for institutional deployment.
- Wearable Devices:Factory-calibrated biosensors measuring heart rate variability and blood oxygen saturation achieve clinical-grade accuracy thresholds. South Korean tertiary hospitals deploy these for outpatient diabetes management at twice the pace of Southeast Asian peers, driven by consolidated reimbursement pathways.
- Telemedicine Solutions:Cloud-connected platforms integrating with legacy hospital information systems enable real-time clinical decision support. Singapore and Taiwan health authorities compress care delivery timelines through hospital-at-home programs, privileging vendors with existing enterprise relationships.
- mHealth Apps:Platform fees and data localization mandates in India and China create structural margin pressure for consumer-facing developers.
- Health Monitoring Systems:Embedded home care devices capture steepest expansion trajectory as hospital-at-home programs proliferate across aging populations in Japan and Australia.
Wearable devices lead on scale; health monitoring systems lead on momentum.
Technology:
Latency tolerance and data sovereignty requirements determine protocol selection for cross-border platform architectures.
- Cloud Computing:Sovereign storage mandates from India's CDSCO and China's NMPA fragment architecture decisions for foreign operators. Domestic cloud providers in Beijing and Mumbai capture institutional contracts previously held by hyperscale multinationals.
- Bluetooth:Bluetooth-5 convergence with edge computing enables real-time physiological data transmission in ambulance and home care settings previously limited to hospital environments. Australian ambulance services pilot these configurations for pre-hospital cardiac monitoring.
- Wi-Fi:Hospital networks in China's tier-2 cities deploy cloud-connected diagnostic tools at scale, creating infrastructure pull for compatible peripherals.
- NFC:Short-range protocols dominate medication adherence applications where tamper-evident dosing verification is required.
Cloud computing leads on scale; Bluetooth leads on momentum.
End User:
Reimbursement model sophistication separates institutional buyers from out-of-pocket consumer segments.
- Healthcare Providers:Procurement committees in Australia's public health system mandate ISO 27001 certification as a gate criterion for remote monitoring tenders. Victoria and New South Wales health departments enforce this most strictly, displacing previous security self-assessment regimes.
- Patients:Chronic disease management applications drive adoption among aging populations in Japan and South Korea, where national health databases enable seamless device integration.
- Health Insurance Companies:Pay-for-performance contracts in Singapore incentivize preventive monitoring investments that reduce acute episode frequency.
- Fitness Enthusiasts:Consumer tier demand concentrates in South Korea through Galaxy Watch integrations with national health infrastructure.
Healthcare providers lead on scale; patients lead on momentum.
Application:
Clinical validation requirements and regulatory pathway complexity separate medical-use cases from wellness management.
- Chronic Disease Management:Continuous glucose monitoring with factory-calibrated sensors consolidates clinical validation standards for wearable biosensors. Endocrinology departments drive platform commitments through single-vendor reimbursement contracts rather than device-agnostic data standards.
- Remote Patient Monitoring:PMDA's locked-algorithm requirements for machine-learning-enabled diagnostic tools prevent real-time model updates without re-approval. Japanese manufacturers front-load algorithm training before submission to accommodate extended validation timelines.
- Fitness Tracking:Consumer-grade accuracy thresholds suffice for wellness applications, enabling faster product cycles without equivalent regulatory burden.
- Medication Management:Provincial hospital digitization programs in Vietnam create first-mover advantage for vendors building local technical support infrastructure.
Chronic disease management leads on scale; remote patient monitoring leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's tier-2 hospital networks deploy cloud-connected diagnostics at scale, while Japan's aging population drives chronic disease management adoption through PMDA-cleared platforms. India's PLI scheme for medical electronics accelerates domestic biosensor manufacturing, contrasting with Australia's ISO 27001 procurement mandates that filter vendor access.
China
NMPA data sovereignty requirements reshape cloud architecture decisions for foreign platform operators. Domestic cloud providers in Beijing capture institutional contracts previously held by hyperscale multinationals. Tier-2 city hospital networks in Sichuan-Chongqing deploy compatible patient monitoring peripherals at accelerating pace.
Japan
PMDA's 2024 locked-algorithm guidance for machine-learning diagnostics prevents real-time model updates without re-approval. Cardiology AI tools face heightened scrutiny of arrhythmia classification outputs. Tokyo-based manufacturers front-load algorithm training before submission to accommodate extended validation timelines.
India
CDSCO data localization mandates fragment architecture decisions and raise compliance costs for cross-border operators. PLI scheme incentives reduce import dependency for biosensor components in tier-2 hospital networks. Maharashtra and Karnataka health authorities expand provincial digitization programs with local technical support requirements.
Australia
TGA alignment with EU MDR streamlines certain approval routes but leaves cybersecurity standards fragmented relative to Singapore's HSA requirements. Victoria and New South Wales health departments mandate ISO 27001 certification as gate criterion for remote monitoring tenders. Queensland maintains transitional grace periods through 2025.
South Korea
MFDS software-as-medical-device pathways diverge from Japan's PMDA standards, delaying multi-market launches. National health database integration enables seamless Galaxy Watch deployments for chronic disease management. Seoul Capital Area tertiary hospitals adopt continuous glucose monitoring at twice the pace of Southeast Asian peers.
Asia-Pacific Mobile Health Market Competitive Environment
Top-tier vendors anchor hospital-system ecosystems, while mid-tier specialists compete for provincial digitization contracts. The vendor base stratifies across three archetypes: enterprise platform integrators with legacy HIS relationships, consumer electronics manufacturers with national health database access, and regional specialists building local technical infrastructure. M&A activity concentrates on middleware capabilities that bridge HL7-FHIR standards with proprietary hospital databases. Geographic expansion into Vietnam's underpenetrated rural networks represents the dominant competitive move.
Within the enterprise platform tier, Philips Healthcare and Cisco Systems occupy positions defined by hospital relationship depth and network infrastructure integration respectively. Samsung Electronics exemplifies the consumer-electronics-to-clinical pivot through national health database integrations. Huawei Technologies sits within the regional infrastructure specialist category despite overseas market restrictions, anchoring domestic telemedicine deployment in China's tier-2 cities.
| Leading Market Players |
|---|
| Cisco Systems |
| Apple |
| Philips Healthcare |
| Huawei Technologies |
| Medtronic |
| Samsung Electronics |
| Omron Corporation |
| Johnson & Johnson |
| Others |
Value Chain & Pricing Dynamics
Interoperability engineering talent scarcity in Bangalore and Hyderabad widens pricing-tier spreads between premium clinical-grade platforms and economy remote monitoring bundles. Labor-cost differentials between India's technical workforce and Japan's regulatory compliance specialists compress margins for mid-tier vendors unable to command either certification premiums or volume scale.
Pricing Analysis
Bundled hardware-software service contracts dominate hospital procurement in Australia's public health system, while unbundled per-device transactions persist in Vietnam's provincial digitization programs. Price differentiation rests on ISO 27001 certification grade and after-sales technical support depth. Cost compression in economy-tier consumer wearables is intensifying because platform fee structures from app store operators erode developer margins. Tier-2 city hospital networks in China exhibit lowest price sensitivity due to consolidated reimbursement pathways, whereas fitness enthusiasts in Southeast Asia drive hardest bargain hunting.
Supply Chain Analysis
Direct-to-hospital channels handle hyperscale demand from China's tier-2 city networks, while regional distributors serve Vietnam's provincial digitization programs. High-precision biosensor manufacturing concentrates in Taiwan, South Korea, and Japan. Component sourcing draws from specialized East Asian foundries for MEMS sensors, medical-grade lithium cells, and flexible printed circuit boards. Single-source vulnerability in MEMS accelerometer supply exposes procurement timelines to foundry capacity constraints. Distribution runs through hospital procurement committees in institutional segments and consumer electronics retail in wellness applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Asia-Pacific mobile health operates as a geographic-arbitrage play where India's PLI scheme manufacturing incentives contrast with Australia's ISO 27001 certification gatekeeping, creating divergent cost structures for platform deployment.
For Market Incumbents: Lock in hospital information system integration capabilities before HL7-FHIR middleware talent scarcity worsens. Prioritize backward integration into biosensor component supply to reduce exposure to Taiwan foundry concentration. Defend against point-solution entrants by deepening enterprise relationships in Singapore's hospital-at-home programs. For New Entrants and Emerging Players: Provincial health authorities in Vietnam represent the most penetrable buyer segment for remote monitoring vendors willing to build local technical support infrastructure. Target medication management applications where regulatory pathway complexity filters out multinational competitors. Pursue cloud-sovereign architecture partnerships with domestic providers in Mumbai and Beijing to satisfy CDSCO and NMPA data localization mandates. For Investors and Strategic Acquirers: Hospital network operators are the most active acquirer in this space, consolidating middleware capabilities that bridge legacy HIS architectures with modern platforms. Five-to-ten year viability favors vendors with locked-in regulatory compliance across multiple jurisdictions rather than single-market specialists. Monitor which regulator moves first on AI-diagnostic integration rules as the signal for regional harmonization timing and platform consolidation acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| PMDA Software-as-Medical-Device Pathway | Locked-algorithm requirements from Japan's PMDA force front-loaded R&D investment before submission. |
| Hospital System Partnership | Enterprise relationships with Singapore and Taiwan health authorities compress competitor entry timelines. |
| Backward Integration into Biosensors | In-house MEMS sensor production reduces Taiwan foundry dependency and procurement vulnerability. |
| Cloud Sovereign Architecture Deployment | Domestic cloud partnerships in Beijing and Mumbai satisfy NMPA and CDSCO data localization mandates. |
| Reimbursement Strategy | Single-vendor platform commitments with South Korean endocrinology departments consolidate glucose monitoring adoption. |
Study Parameters
Coverage spans East Asia, South Asia, and Southeast Asia, with primary inputs from each regional cluster. The analysis combines structured interviews with hospital procurement managers, biomedical engineers, and GPO contracts managers alongside secondary validation from hospital procurement databases, GPO contract filings, and CMS Medicare-equivalent data in each jurisdiction. Regulatory submissions to PMDA, MFDS, CDSCO, NMPA, and TGA provide approval pathway documentation. Bottom-up device shipment modeling and top-down healthcare expenditure triangulation cross-validate volume estimates.
Granularity-level modeling disaggregates the market by product type, technology protocol, end-user archetype, and application use case across the projection horizon. Segmentation dimensions include wearable form factor, connectivity standard, buyer reimbursement model, and clinical validation tier. CAGRs derive from installed base growth curves and replacement cycle analysis. Forecast inputs incorporate PMDA locked-algorithm guidance implementation timelines and PLI scheme manufacturing capacity expansion trajectories.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to regulatory harmonization pace and AI-diagnostic validation framework adoption. Forecasts reflect documented assumptions regarding hospital-at-home program expansion rates and biosensor foundry capacity additions. Periodic stress-testing of base assumptions is recommended given divergence risk between Japan's PMDA and South Korea's MFDS software-as-medical-device standards.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Personal Health
Global on Site Preventive Care Market
Personal Health
Biohacking Market
Personal Health
US Vaginal Moisturizers and Lubricants Market
Personal Health
Menstrual Cup Market
Personal Health
Workplace Wellness Market
Personal Health
Tongue Scraper Market
Personal Health
Global Health and Wellness Market
Personal Health
Patient Health Management Market
Personal Health
OTC Health Products Market
Personal Health
Asia Pacific Hair Loss Treatment Products Market
Personal Health
Sextech and Sexual Wellness Market
Personal Health
Maternity Personal Care Products Market
Personal Health
Blackhead Removing Vacuum Market
Personal Health
Disposable Underwear Market
Personal Health
High Concentration Respiratory Masks Market
Personal Health
Health Check-Up Market