
 Blackhead Removing Vacuum Market | 2026-2036
Blackhead Removing Vacuum Market Size, Share, and Industry Trends Forecast 2026-2036
Blackhead Removing Vacuum Market Analytics
The capital-intensity divergence between mass-market assemblers and precision-engineering specialists is reorganizing competitive tiers in blackhead removing vacuum production. Xiaomi Corporation leverages its electronics ecosystem to control component sourcing costs across cordless models. Panasonic Corporation sustains premium positioning through in-house motor technology and Japanese manufacturing standards. Philips dominates professional channels with FDA-cleared devices that anchor dermatology clinic procurement cycles.
A blackhead removing vacuum is a suction-based dermal cleansing device that operates through calibrated negative pressure measured in kilopascals, typically ranging from 20 to 65 kPa, to extract comedones, sebaceous filaments, and surface debris from pores without invasive incision. The technology segment splits across suction, ultrasonic, pulsating, and LED variants, with ultrasonic integration commanding margin pools as consumers seek multi-functional devices that combine extraction with skin-tightening therapy. The end-user base spans home users, beauty salons, dermatologists, and spa centers, where the dermatologist channel leads average selling prices despite smaller unit volumes due to clinical-grade certification requirements and insurance reimbursement protocols.
The FDA regulates blackhead removing vacuums sold in the United States as Class I or Class II medical devices depending on intended use claims, while China's SAMR enforces GB 4706 safety standards for household electrical appliances that directly shape product design and export eligibility. The EU MDR and CE marking requirements for devices making therapeutic claims are tightening documentation burdens for manufacturers targeting European dermatology practices. Stakeholders must monitor how regulatory divergence between clinical-grade and cosmetic-grade classifications reshapes portfolio allocation and geographic launch sequencing.
Market Dynamics
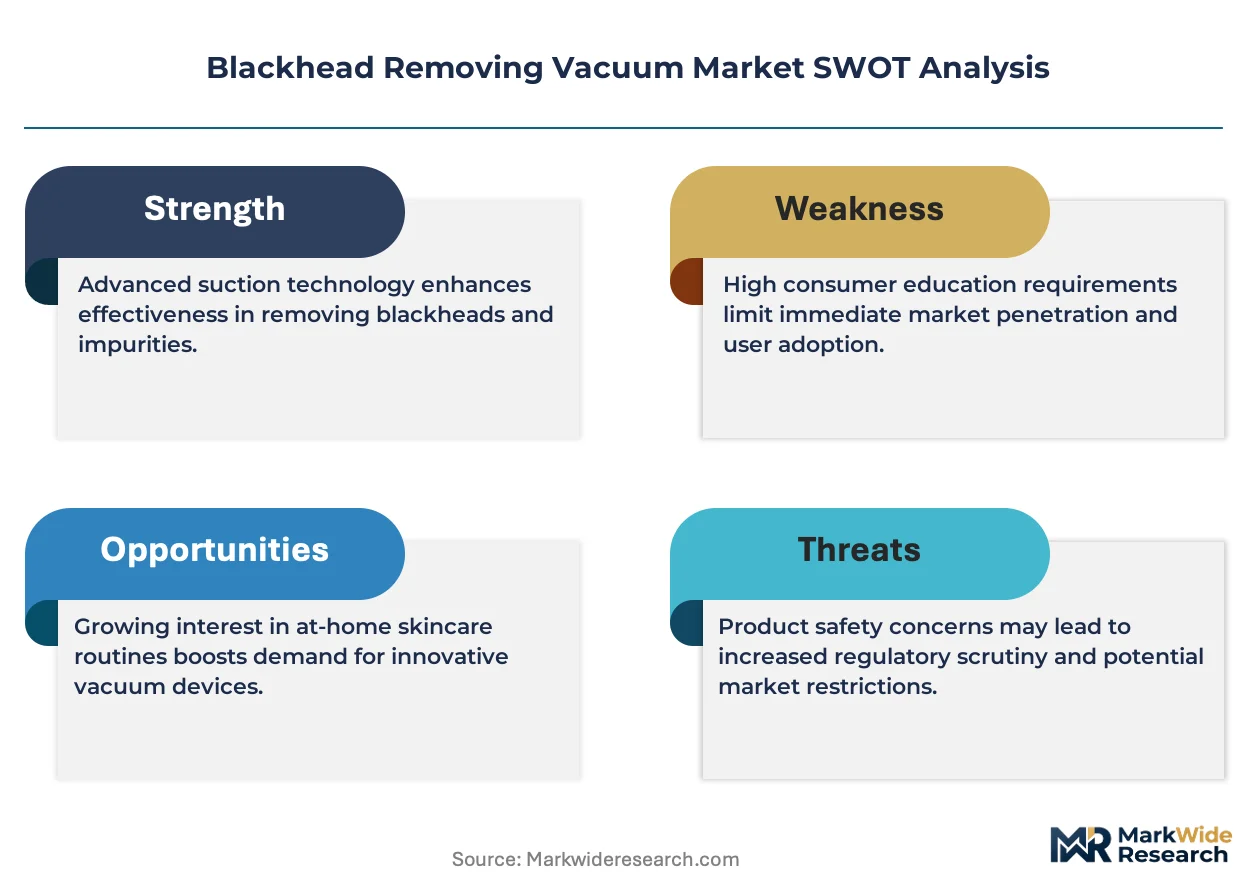
The blackhead removing vacuum market is restructuring around clinical-grade certification requirements that bifurcate production tiers between FDA-cleared professional devices and cosmetic-grade consumer units, with dermatology clinic procurement cycles now dictating R&D investment priorities.
Growth Catalysts
- GB 4706 Safety Standards:China's tightened electrical safety requirements for personal care appliances are accelerating factory consolidation and pushing export-oriented manufacturers toward automated quality systems that reduce defect rates.
- Dermatology Clinic Procurement:Professional channels are expanding device adoption for pre-treatment skin preparation and post-procedure maintenance, creating recurring revenue streams through disposable tip attachments.
- Ultrasonic Integration:Multi-functional devices combining suction with skin-tightening therapy command margin premiums as consumers reduce bathroom countertop clutter through consolidated appliances.
Market Restraints
- Micro-Motor Supply Concentration:Precision brushless motors for calibrated suction control concentrate among Japanese and German component specialists, exposing assemblers to allocation risk during semiconductor shortages.
- EU MDR Documentation Burden:Devices making therapeutic claims face tightened clinical evidence requirements under European Medical Device Regulation, extending time-to-market for professional-grade launches.
- Manual Extraction Substitution:Low-cost comedone extractors and pore strips retain price-sensitive segments, particularly in emerging markets where device penetration remains shallow.
Strategic Opportunities
- India's BIS Certification Pathway:Formalized standards for electronic beauty appliances create first-mover advantage for manufacturers establishing local testing partnerships before mandatory compliance deadlines.
- Subscription Consumables Models:Dermatology clinics and high-volume spa chains are piloting scheduled filter and tip replacement programs that lock in recurring revenue and reduce customer acquisition costs.
- LED-Suction Convergence:Blue-light antibacterial modules integrated with vacuum extraction address post-treatment inflammation concerns, opening positioning against standalone LED mask competitors.
Industry Challenges
- FDA 510(k) Timeline Compression:Clinical-grade device manufacturers face extended clearance durations as the agency applies heightened scrutiny to software-controlled pressure algorithms in Class II submissions.
- Biocompatibility Testing Backlogs:ISO 10993 skin contact material assessments are creating bottlenecks for new product launches, with third-party laboratory capacity failing to match submission volumes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Blackhead Removing Vacuum Market |
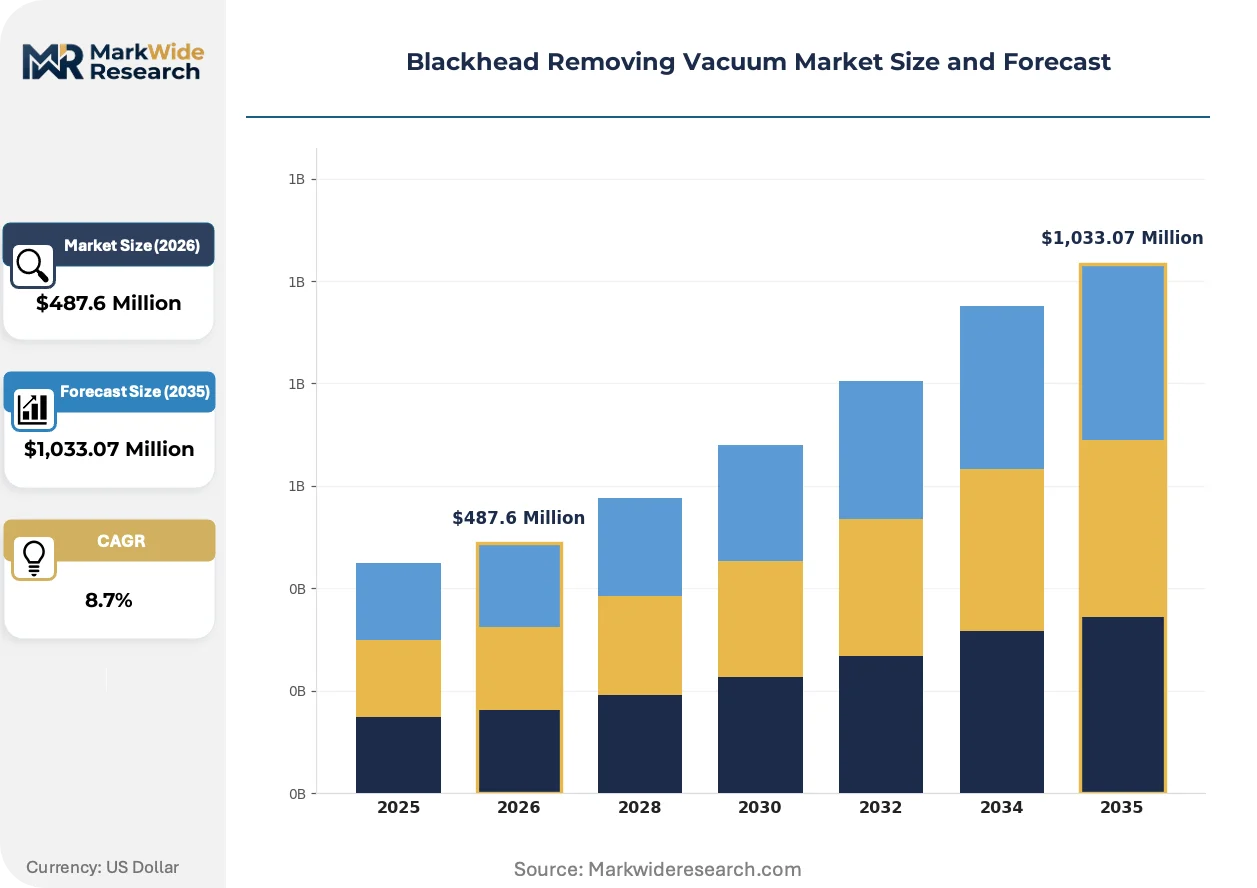
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,033.07 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Handheld, Portable, Wired, Cordless Technology: Suction, Ultrasonic, Pulsating, LED End User: Home Users, Beauty Salons, Dermatologists, Spa Centers Distribution Channel: Online Retail, Specialty Stores, Medical Supply Stores, Pharmacies |
| Companies Covered | PMD Beauty, Xpreen, Voyor, Xiaomi Corporation, Philips, Panasonic Corporation, Freeshow, LONOVE, Hangsun, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Blackhead Removing Vacuum Market Evolving Landscape
Active pressure modulation algorithms and real-time skin impedance sensing are redefining extraction safety profiles, while regulatory divergence between cosmetic and medical classifications forces parallel product development tracks.
Variable suction intensity controlled through skin impedance feedback is supplanting fixed-pressure presets in mid-tier and premium devices. Dermatology practices in South Korea and Germany are adopting these systems for patient-specific sebaceous density mapping. This technology is compressing liability exposure while enabling premium pricing against legacy fixed-pressure competitors.
China's SAMR enforcement of GB standards for lithium-ion battery containment in personal care appliances is mandating redesigned power management circuits and thermal runaway protection. Factory audit failure rates have risen sharply for exporters lacking in-house battery testing laboratories. Manufacturers targeting both domestic and export markets are consolidating SKU portfolios to single compliant architectures.
Direct-to-clinic sales teams are replacing distributor networks for professional-grade device penetration in tier-one Chinese cities and their surrounding manufacturing clusters. Device vendors are hiring former dermatology equipment specialists to manage hospital procurement committees. This channel compression is most visible in Shanghai and Shenzhen, where clinic chains centralize purchasing decisions at headquarters level.
Blackhead Removing Vacuum Market Segmentation
Segmentation in blackhead removing vacuums determines pricing architecture, regulatory pathway, and channel strategy. Device classification across product type and technology tiers separates cosmetic-grade units from clinical equipment requiring FDA or SAMR clearance. End-user and distribution splits reveal where margin pools concentrate versus where volume scales.
Product Type:
Substitution pressure from manual extraction tools hits wired and basic handheld units hardest, while cordless portability commands defensive positioning through convenience premiums.
- Cordless:Lithium-ion powered units with 20-65 kPa calibrated suction enable bathroom-counter mobility and travel use. Demand clusters in China's tier-one cities and surrounding manufacturing clusters where Xiaomi's electronics ecosystem controls component sourcing costs across cordless models.
- Handheld:Ergonomic pistol-grip designs with fixed suction heads dominate mass-market pharmacy shelves. Beauty salons in South Korea and Germany adopt these for pre-treatment skin preparation where patient-specific sebaceous density mapping requires variable intensity control.
- Portable:Compact travel-sized units with USB charging prioritize luggage-friendly dimensions over suction power.
- Wired:AC-powered devices with continuous operation capability serve professional settings where battery degradation risks liability exposure.
Cordless anchors the volume base while handheld gains share at the steepest rate.
Technology:
Cost tier stratification separates single-function suction devices from multi-therapy systems commanding margin premiums through consolidated appliance positioning.
- Ultrasonic:Piezoelectric transducers operating at 20-40 kHz combine comedone extraction with skin-tightening therapy through thermal and cavitation effects. Dermatology clinics in Shanghai and Shenzhen centralize purchasing decisions at headquarters level for these multi-functional units that reduce countertop clutter.
- Suction:Pure negative pressure systems ranging 20-65 kPa remain the baseline technology where Panasonic's in-house motor technology and Japanese manufacturing standards sustain premium positioning against mass-market assemblers.
- LED:Blue-light antibacterial modules integrated with vacuum extraction address post-treatment inflammation concerns, opening positioning against standalone LED mask competitors.
- Pulsating:Rhythmic pressure variation mimics manual extraction techniques for sensitive skin protocols in spa center environments.
Suction anchors the volume base while ultrasonic climbs the fastest through dermatology channel expansion.
End User:
Customer type determines certification burden and pricing power, with clinical-grade procurement cycles dictating R&D investment priorities separate from cosmetic-grade consumer markets.
- Dermatologists:FDA-cleared Class II devices with software-controlled pressure algorithms anchor professional channels despite extended 510(k) clearance durations. Philips dominates this segment where clinical-grade certification requirements and insurance reimbursement protocols support average selling price premiums.
- Home Users:Direct-to-consumer units operating under cosmetic-grade classifications face manual extraction substitution from low-cost comedone extractors and pore strips, particularly in emerging markets where device penetration remains shallow.
- Beauty Salons:Mid-tier equipment with disposable tip attachments creates recurring revenue streams through scheduled filter replacement programs.
- Spa Centers:Experience-focused environments prioritize aesthetic device design and quiet operation over clinical precision specifications.
Home users anchor the volume base while dermatologists expand most quickly through clinic procurement centralization.
Distribution Channel:
Margin structure varies sharply across channel tiers, with medical supply stores capturing value through clinical relationships while online retail scales through electronics ecosystem integration.
- Online Retail:E-commerce platforms enable electronics ecosystem players to leverage existing logistics networks and component sourcing advantages. Factory audit failure rates for lithium-ion battery containment have risen sharply for exporters lacking in-house testing laboratories.
- Medical Supply Stores:Professional-grade device penetration relies on former dermatology equipment specialists managing hospital procurement committees in tier-one Chinese cities.
- Specialty Stores:Beauty-focused retail environments provide tactile product demonstration for consumers comparing ultrasonic and suction variants.
- Pharmacies:Over-the-counter placement reaches price-sensitive segments where manual extraction tools retain competitive position.
Online retail anchors the volume base while medical supply stores gain share fastest through direct-to-clinic sales team deployment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in German dermatology practices where clinical-grade certification commands premium positioning, while Chinese manufacturing clusters compete on electronics ecosystem integration and component sourcing efficiency.
China
Demand clusters in tier-one cities and their surrounding manufacturing clusters where Xiaomi's electronics ecosystem controls component sourcing costs across cordless models. SAMR enforces GB 4706 safety standards for household electrical appliances that directly shape product design and export eligibility. Shanghai and Shenzhen clinic chains centralize purchasing decisions at headquarters level for professional-grade device procurement.
United States
FDA-cleared Class II devices anchor dermatology clinic procurement cycles despite extended 510(k) clearance durations as the agency applies heightened scrutiny to software-controlled pressure algorithms. The FDA regulates devices as Class I or Class II medical devices depending on intended use claims. Professional channels concentrate in metropolitan healthcare corridors with established dermatology practice networks.
Germany
EU MDR documentation burdens for devices making therapeutic claims are tightening clinical evidence requirements and extending time-to-market for professional-grade launches. Devices face CE marking requirements under European Medical Device Regulation for therapeutic positioning. Precision brushless motor supply concentrates among German component specialists serving calibrated suction control specifications.
South Korea
Dermatology practices adopt active pressure modulation systems for patient-specific sebaceous density mapping and pre-treatment skin preparation protocols. The country's national medical device regulator enforces clinical evidence standards for professional equipment clearance. Seoul-based clinic chains pilot subscription consumables models with scheduled filter and tip replacement programs.
India
BIS certification pathways for electronic beauty appliances create first-mover advantage for manufacturers establishing local testing partnerships before mandatory compliance deadlines. The Bureau of Indian Standards formalizes standards that reshape import eligibility and domestic production requirements. Mumbai and Bangalore manufacturing zones attract assembly investments targeting price-sensitive consumer segments.
Blackhead Removing Vacuum Market Competitive Landscape
Concentration sits with diversified electronics conglomerates that leverage existing supply chain infrastructure and component sourcing scale. The market structure fragments across three tiers: mass-market assemblers competing on cost, precision-engineering specialists defending premium positioning through motor technology, and ecosystem players integrating devices into broader personal care portfolios. Dominant competitive moves include backward integration into battery and motor component supply, and direct-to-clinic sales team deployment replacing distributor networks in professional channels.
Within the electronics ecosystem tier, Xiaomi Corporation anchors volume positioning through supply chain integration, while Panasonic Corporation exemplifies the precision-engineering archetype with Japanese manufacturing standards. Philips occupies the clinical-grade certification tier where FDA-cleared devices anchor dermatology procurement cycles. These three players represent distinct competitive vectors: ecosystem scale, component technology, and regulatory clearance.
| Leading Market Players |
|---|
| PMD Beauty |
| Xpreen |
| Voyor |
| Xiaomi Corporation |
| Philips |
| Panasonic Corporation |
| Freeshow |
| LONOVE |
| Hangsun |
| Others |
Value Network & Pricing Analysis
Sixty-day motor procurement lead times for precision brushless units tether pricing power to Japanese and German component specialists, while Chinese electronics ecosystems compress cordless model costs through captive battery sourcing. This inventory exposure bifurcates margin structures between mass-market assemblers absorbing allocation risk and premium specialists commanding configured-to-order premiums.
Pricing Analysis
The customization-premium spread separates FDA-cleared Class II devices with software-controlled pressure algorithms from cosmetic-grade consumer units. Three-tier pricing structure across clinical certification, professional salon, and mass-market economy levels reflects divergent biocompatibility testing burdens and channel control investments. Cost compression in the handheld tier intensifies because Xiaomi's ecosystem integration enables component sourcing scale that independent assemblers cannot match. Home users exhibit highest price sensitivity, while dermatology clinics demonstrate lowest sensitivity due to insurance reimbursement protocols and liability risk transfer.
Supply Chain Analysis
Inventory concentration for precision motors and lithium-ion cells rests on Japanese, German, and South Korean manufacturing bases. Brushless micro-motors, piezoelectric transducers, and medical-grade silicones draw from specialized component tiers with limited second-source alternatives. Single-source vulnerability concentrates in motor winding and battery management IC fabrication, exposing assemblers to semiconductor allocation cycles. Distribution runs through direct-to-clinic sales teams replacing distributor networks in tier-one Chinese cities, alongside electronics platform logistics for consumer-tier fulfillment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits at a platform-economics inflection where Xiaomi's electronics ecosystem integration redefines component sourcing scale and channel reach, displacing standalone device economics.
For Market Incumbents: Consolidate backward integration into battery testing laboratories and motor winding capabilities to defend against allocation risk from Japanese and German specialists. Capture channel control by deploying former dermatology equipment specialists to manage hospital procurement committees before distributor networks fully dissolve. For New Entrants and Emerging Players: Lead with India's BIS certification pathway as the most penetrable geography, establishing local testing partnerships before mandatory compliance deadlines formalize. Target beauty salon segments with subscription consumables models for disposable tip attachments, leveraging scheduled filter replacement programs to lock in recurring revenue against transactional competitors. For Investors and Strategic Acquirers: Long-term, this sits as a clinical-grade certification play because dermatology clinic procurement centralization in Shanghai and Shenzhen creates durable pricing power through FDA and SAMR clearance moats. Monitor FDA 510(k) timeline compression as the inflection signal indicating whether software-controlled pressure algorithms face sustained regulatory scrutiny or pathway normalization.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Motor Technology | Panasonic's in-house production insulates premium positioning from semiconductor allocation cycles. |
| Direct-to-Clinic Sales Team Deployment | Device vendors bypass distributor networks to capture Shanghai and Shenzhen procurement centralization. |
| FDA 510(k) Clearance Investment | Philips anchors dermatology channel dominance through Class II software-controlled pressure algorithms. |
| Subscription Consumables Model | Seoul clinic chains pilot scheduled filter programs that reduce customer acquisition costs. |
| Ultrasonic-Suction Convergence | Multi-therapy integration commands margin premiums against single-function competitors. |
Research Methodology
Cross-validation between primary dermatology equipment procurement interviews and secondary FDA 510(k) filing analysis anchors the qualitative findings. Conversations with biomedical engineers, hospital purchasing committee members, GPO contracts managers, and spa center operations directors combined with SAMR GB standard documentation, customs export records, and lithium-ion battery safety certification databases. Bottom-up unit economics triangulate against top-down category spend estimates from electronics platform disclosures.
Sensitivity analysis across suction intensity tiers, certification grades, and channel structures shapes the analytical framework over the projection horizon. Segmentation dimensions modeled include product portability class, technology integration level, end-user clinical credential requirements, and regional regulatory cluster. CAGRs derive from installed base replacement cycles and clinic penetration curves, with ultrasonic adoption rates and dermatology channel expansion serving as primary demand drivers.
The analysis sits within stated boundaries; outcomes outside sustained FDA clearance timeline normalization or lithium-ion supply stabilization would require recalibration. Forecasts reflect assumptions around GB 4706 enforcement consistency and EU MDR documentation burden trajectories. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Personal Health
Sextech and Sexual Wellness Market
Personal Health
Patient Health Management Market
Personal Health
Reusable Face Mask Market
Personal Health
Sexual Wellness Market
Personal Health
Disposable Underwear Market
Personal Health
Maternity Personal Care Products Market
Personal Health
Tongue Scraper Market
Personal Health
Sleeping Aids Market
Personal Health
Asia-Pacific Maternity & Personal Care Market
Personal Health
Piercing Aftercare Spray Market
Personal Health
Infrared Sauna Blankets Market
Personal Health
Europe Hair Loss Treatment Products Market
Personal Health
Tick Repellent Market
Personal Health
US Vaginal Moisturizers and Lubricants Market
Personal Health
Menopause Wellness Market
Personal Health
Feminine Hygiene Market