
 Feminine Hygiene Market | 2026-2036
Feminine Hygiene Market Size, Share, and Industry Trends Forecast 2026-2036
Feminine Hygiene Market Analysis
Subscription-based bundling of menstrual cups with organic cotton liners is expanding consumer choice architecture beyond single-format purchasing. Procter & Gamble leverages its retail shelf dominance to anchor premium pad positioning across mass-market channels. Essity AB competes through specialized incontinence-to-menstrual product crossovers that blur traditional category boundaries. Kimberly-Clark Corporation sustains manufacturing scale advantages in synthetic absorbent cores that underpin cost leadership.
Feminine hygiene encompasses absorbent and non-absorbent products engineered for menstrual fluid management, typically constructed from layered cellulose pulp, superabsorbent polymers, and breathable polyethylene backings with acquisition-distribution layers controlling fluid spread. These products serve commercial purpose by enabling continued participation in education, workforce activity, and social engagement during menstruation. Sanitary pads occupy the largest value pool due to established habit formation and lower usage barriers across age demographics. Biodegradable materials represent the fastest-expanding segment as regulatory pressure and consumer preference converge on compostable substrates. Online retail channels capture disproportionate growth in recurring subscription models that reduce price sensitivity and build brand loyalty.
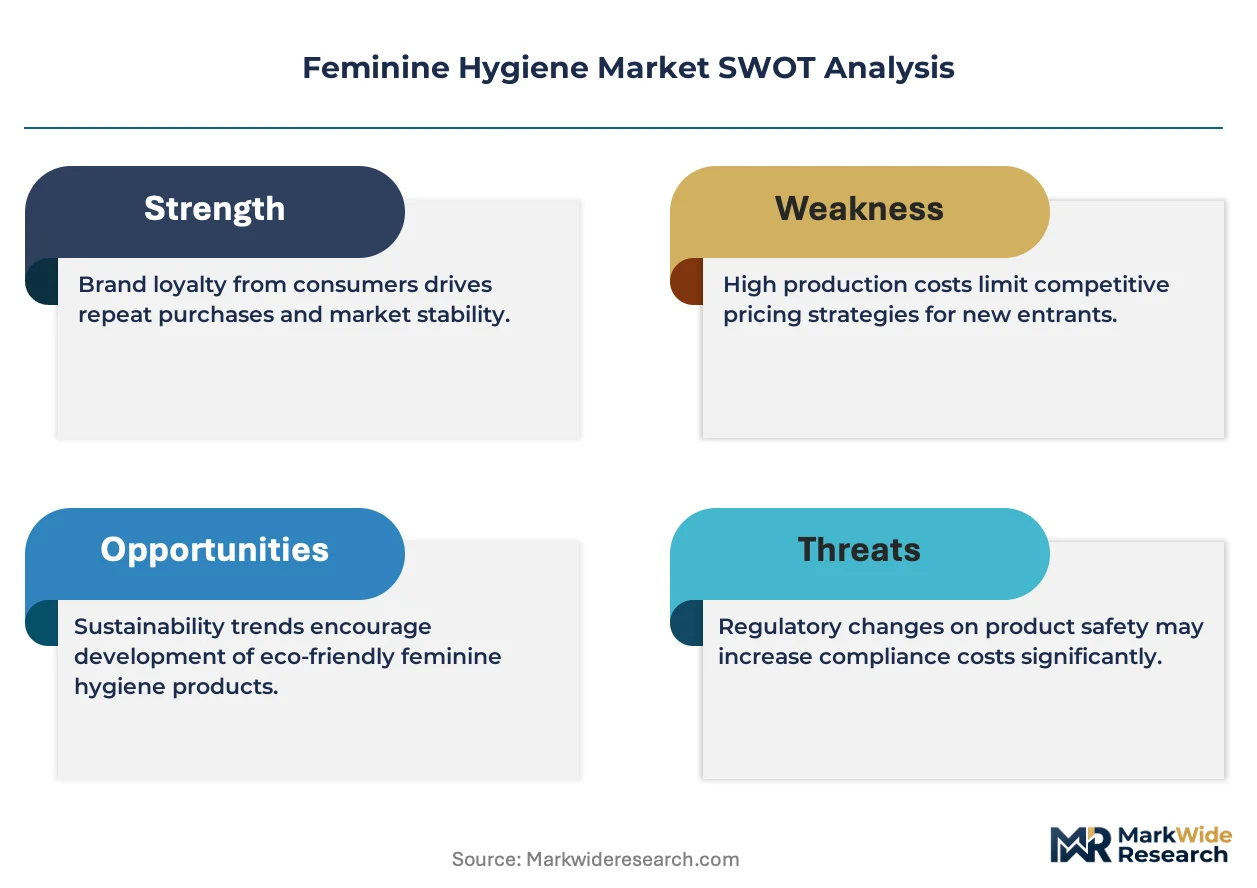
The EU Green Deal and REACH frameworks mandate chemical disclosure and restrict persistent organic pollutants in absorbent articles, forcing reformulation of fragrance and adhesive components. The FDA regulates tampon absorbency labeling and fiber composition in the United States, creating compliance cost differentials between domestic and imported products. India's BIS certification requirements for sanitary pad safety standards are tightening market access for unorganized producers. Stakeholders must monitor evolving biodegradability certification schemes as these standards become gatekeepers for premium shelf placement and public procurement eligibility.
Market Dynamics
Biodegradable substrate transitions are compressing established supply chains as the EU Green Deal's single-use plastics directive forces material reformulation across absorbent product portfolios.
Growth Catalysts
- School-based health programs:Menstrual literacy initiatives in India and Kenya normalize early product education, expanding the teenager cohort faster than other demographics.
- REACH chemical disclosure mandates:European regulatory pressure on fragrance and adhesive components accelerates reformulation investment that differentiates compliant suppliers.
- Organic cotton cultivation clusters:Indian domestic manufacturing scale reduces import dependency and reshapes rural category access through localized production.
Market Restraints
- Superabsorbent polymer cost volatility:Petroleum-derived input prices fluctuate with crude benchmarks, squeezing margin structures for synthetic core manufacturers.
- Compostable certification fragmentation:Competing biodegradability standards across EU member states create compliance cost differentials that favor larger formulators.
- Menstrual cup durability:Reusable alternatives threaten replacement-cycle frequency for disposable formats in urban educated segments.
Strategic Opportunities
- Rural India penetration:Unorganized sector displacement through BIS-certified affordable pads opens volume pools currently served by cloth alternatives.
- Subscription bundling architecture:Recurring delivery models combining cups with liners reduce price sensitivity and capture lifetime value.
- Incontinence-menstrual product convergence:Aging demographics in Japan and Germany create crossover demand for absorbent solutions serving multiple life stages.
Industry Challenges
- Acquisition-distribution layer engineering talent:Fluid management specialists command premium compensation as material transitions require redesigned core architectures.
- Biodegradability testing timeline compression:Accelerated certification demands strain laboratory capacity and delay product launches.
- Legacy polyethylene backing integration:Breathable film substitution with compostable barriers requires line retooling that disrupts continuous production.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Feminine Hygiene Market |
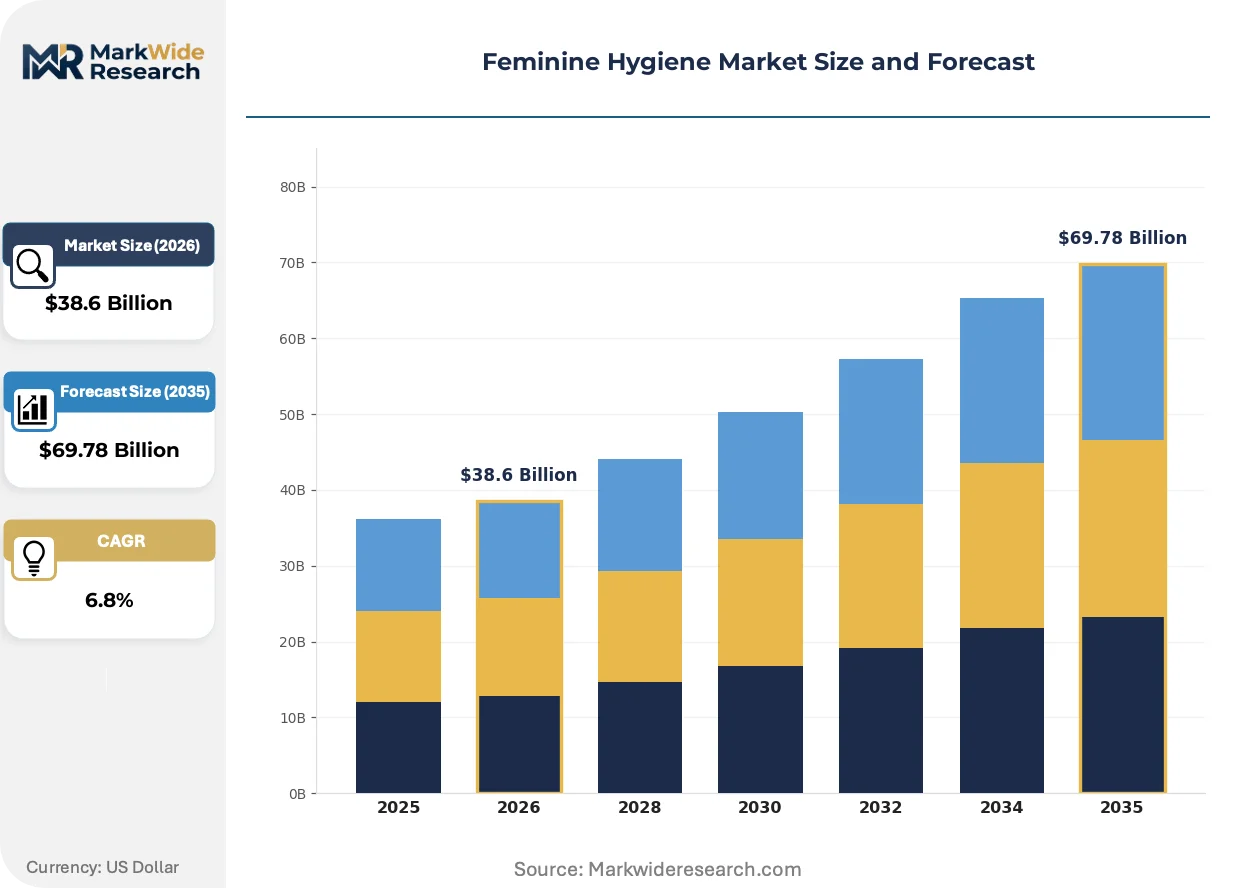
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $69.78 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sanitary Pads, Tampons, Menstrual Cups, Panty Liners Material: Cotton, Biodegradable, Synthetic, Organic End User: Teenagers, Adults, Seniors, Postpartum Users Distribution Channel: Online Retail, Supermarkets, Pharmacies, Convenience Stores |
| Companies Covered | Unicharm Corporation, Ontex Group NV, Procter & Gamble, Hengan International Group, Johnson & Johnson Services Inc., Kimberly-Clark Corporation, Edgewell Personal Care, Kao Corporation, Essity AB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Feminine Hygiene Market Emerging Trajectories
Material science convergence with regulatory chemistry mandates is collapsing traditional product development cycles while digital channels rewrite how consumers discover and replenish hygiene supplies.
Plant-based superabsorbent polymers derived from agricultural waste streams are unifying sustainability credentials with performance parity. Teenage consumers in Scandinavian markets adopt these formats fastest, treating compostability as a non-negotiable attribute. This unifying pressure is compressing R&D timelines and forcing petrochemical-dependent suppliers into accelerated partnership strategies with biotech feedstock developers.
REACH restrictions on persistent organic pollutants in absorbent articles are forcing fragrance and adhesive reformulations across European manufacturing footprints. The industrial consequence is supplier consolidation as smaller fragrance houses lack toxicology testing infrastructure. Premium pad segments in Germany and France absorb compliance costs through shelf price adjustments while economy tiers face margin compression.
Direct-to-consumer subscription models are displacing pharmacy and supermarket restocking rituals among urban professional women. Digital-native brands capture recurring revenue through personalized cycle-tracking apps that automate delivery timing. This behavioral pivot concentrates in United States coastal metros and London commuter belts where convenience premiums outweigh traditional channel loyalty.
Feminine Hygiene Market Segmentation
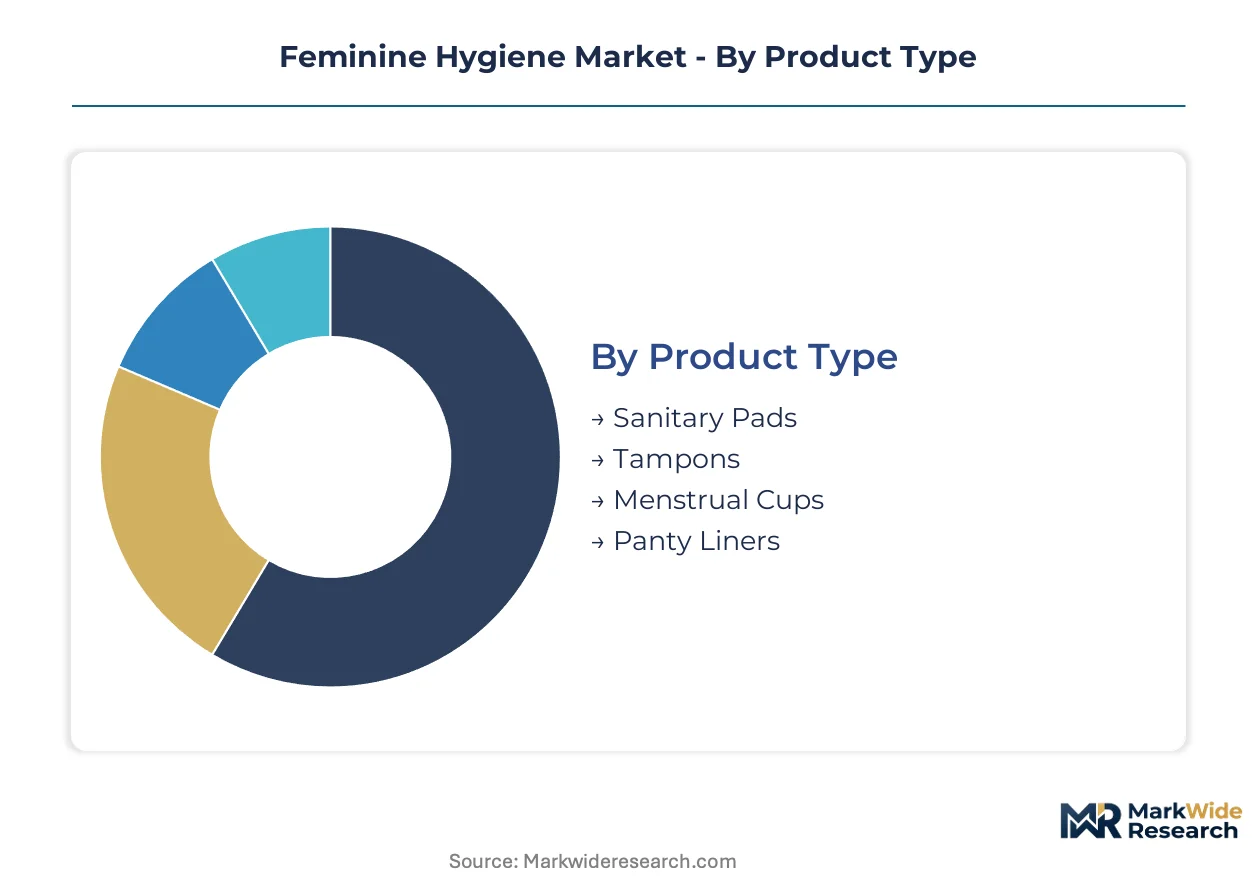
Product differentiation in feminine hygiene hinges on absorbency engineering, material origin, and usage occasion. Segmentation reveals how regulatory chemistry mandates and channel migration reshape competitive boundaries across formats.
Product Type:
Usage barriers and habit persistence separate buyers across formats, with convenience tolerance and cultural acceptance driving format selection.
- Sanitary Pads:Layered cellulose pulp cores with acquisition-distribution layers manage fluid spread across varying flow intensities. Demand concentrates in India and Kenya where school-based distribution programs normalize pad-centric menstrual management. Established habit formation and minimal insertion learning curve sustain volume dominance across age demographics.
- Tampons:Compressed cotton or rayon cylinders with plastic or cardboard applicators require insertion familiarity that limits adoption in conservative cultural contexts. Scandinavian markets and US coastal metros show highest penetration where early product education reduces usage anxiety. FDA absorbency labeling mandates create compliance cost differentials between domestic and imported variants.
- Menstrual Cups:Medical-grade silicone or thermoplastic elastomer reservoirs offer multi-year reusability that compresses replacement cycles. Urban professional segments in London and New York commuter belts adopt fastest through subscription bundling with disposable liners.
- Panty Liners:Thin cellulose cores with breathable polyethylene backings address light discharge or backup protection needs. Pharmacy and supermarket channels dominate replenishment patterns for this accessory format.
Volume sits with Sanitary Pads; growth tilts toward Menstrual Cups.
Material:
Certification grade and petroleum dependency distinguish sourcing tiers, with regulatory pressure accelerating feedstock transitions.
- Cotton:Conventional cotton cultivation supplies absorbent layers with established processing infrastructure across Indian manufacturing clusters. Domestic scale reduces import dependency for brands serving price-sensitive rural segments.
- Biodegradable:Compostable substrates from agricultural waste streams unify sustainability credentials with EU Green Deal compliance. German and French premium segments absorb certification costs through shelf price adjustments while economy tiers face margin compression from fragmented compostable standards across member states.
- Synthetic:Superabsorbent polymers derived from petroleum feedstocks deliver performance parity at cost-efficient scale. Crude price volatility squeezes margin structures for manufacturers dependent on synthetic core architectures.
- Organic:Certified organic cotton cultivation eliminates pesticide residues that REACH frameworks restrict in absorbent articles. Teenage consumers in Scandinavian markets treat compostability as non-negotiable, accelerating adoption fastest among material variants.
Volume concentrates in Synthetic; expansion accelerates most sharply in Biodegradable.
End User:
Life stage and physiological circumstance determine absorbency requirements and format flexibility tolerance.
- Teenagers:School-based health programs in India and Kenya normalize early product education, expanding this cohort faster than other demographics through menstrual literacy initiatives.
- Adults:Workforce participation demands reliable fluid management across variable cycle intensities, sustaining premium pad and tampon replenishment through subscription channels in US coastal metros.
- Seniors:Aging demographics in Japan and Germany create crossover demand with incontinence products, blurring traditional category boundaries for absorbent solutions.
- Postpartum Users:Elevated flow volumes and healing sensitivity require specialized pad architectures with enhanced breathability and reduced adhesive contact zones.
Volume resides with Adults; steepest expansion trajectory belongs to Teenagers.
Distribution Channel:
Convenience premium tolerance and replenishment urgency separate channel selection, with digital migration rewriting discovery and loyalty patterns.
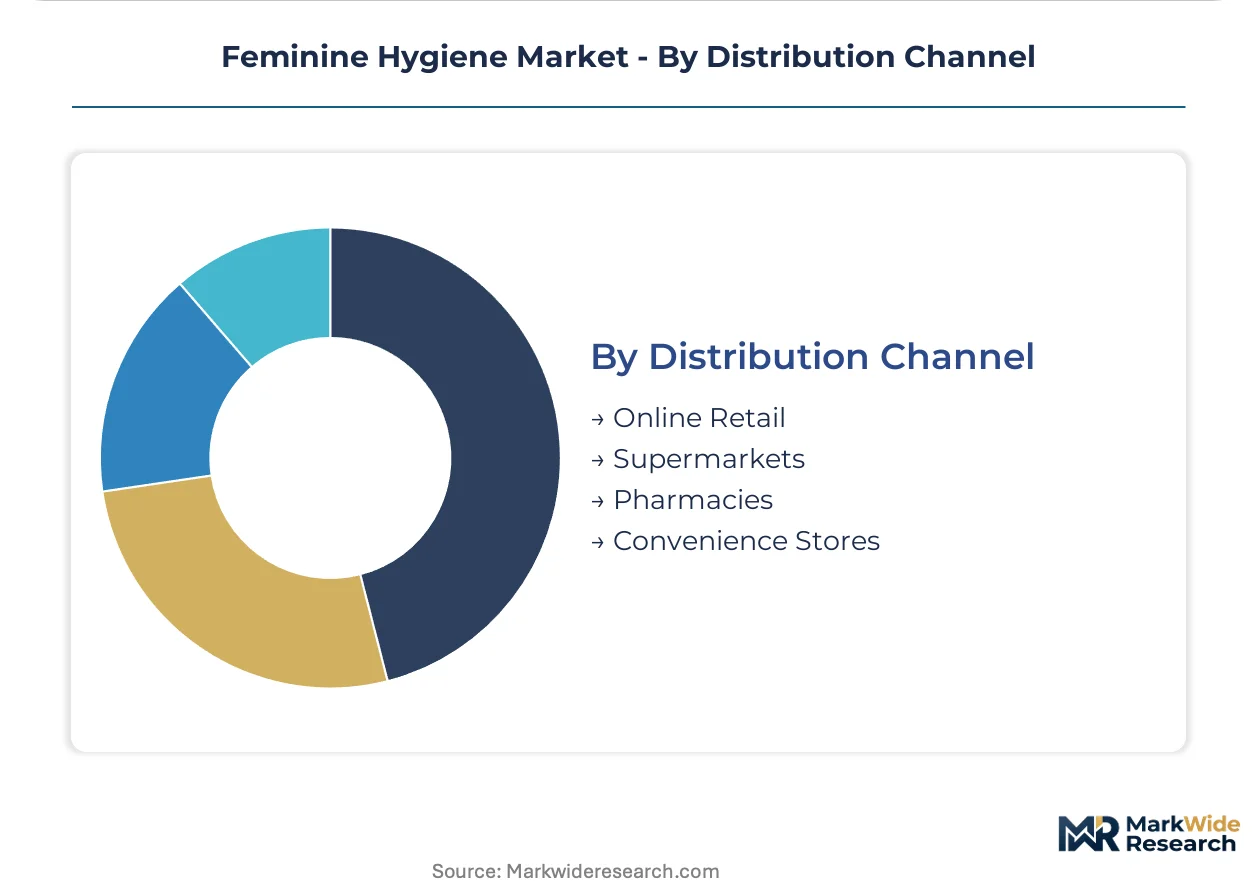
- Online Retail:Direct-to-consumer subscription models displace pharmacy and supermarket rituals through personalized cycle-tracking apps that automate delivery timing. Digital-native brands capture recurring revenue and reduce price sensitivity among urban professional women.
- Supermarkets:Mass-market shelf dominance anchors premium pad positioning through retail presence that Procter & Gamble leverages across channels. Impulse replenishment and promotional visibility sustain volume for established brands.
- Pharmacies:Professional recommendation environments support tampon and specialized format credibility, particularly in European markets where pharmacists influence switching behavior.
- Convenience Stores:Emergency replenishment occasions command price premiums for single-unit purchases, serving travelers and cycle unpredictability scenarios.
Volume flows through Supermarkets; share gains concentrate in Online Retail.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India concentrates manufacturing scale while developed markets drive premium material transitions. Domestic production clusters reduce import dependency for price-sensitive rural segments. Regulatory chemistry mandates in Europe and North America accelerate feedstock diversification beyond petroleum-derived inputs.
India
School-based health programs in Karnataka and Maharashtra normalize early menstrual product education, expanding the teenager cohort faster than other demographics. BIS certification requirements for sanitary pad safety standards tighten market access for unorganized producers. Tamil Nadu manufacturing clusters supply affordable BIS-certified pads that displace cloth alternatives in rural penetration programs.
Germany
REACH chemical disclosure mandates accelerate fragrance and adhesive reformulation investment that differentiates compliant suppliers. The EU Green Deal's single-use plastics directive forces material transitions toward biodegradable substrates across absorbent product portfolios. Frankfurt and Hamburg distribution hubs serve premium segments absorbing certification costs through shelf price adjustments.
United States
FDA absorbency labeling regulations for tampons create compliance cost differentials between domestic and imported variants. Subscription bundling of menstrual cups with organic cotton liners captures recurring revenue among urban professional women in coastal metros. Chicago and Dallas manufacturing footprints sustain synthetic superabsorbent polymer production at cost-efficient scale.
Japan
Aging demographics create crossover demand between incontinence and menstrual products, blurring traditional category boundaries for absorbent solutions. METI industrial standards influence material specifications for breathable backings and acquisition-distribution layers. Osaka and Nagoya R&D clusters engineer specialized architectures serving multiple life stages.
Brazil
ANVISA pharmaceutical-grade standards for intimate hygiene products elevate quality benchmarks for imported and domestic manufacturers. São Paulo and Rio de Janeiro retail channels anchor mass-market pad positioning through supermarket shelf dominance. Northeast region underpenetration programs target volume expansion among consumers currently served by informal supply chains.
Feminine Hygiene Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. Consolidated multinational presence in synthetic absorbent cores and retail shelf dominance contrasts with emerging biodegradable material specialists. Three archetypes dominate: petrochemical-dependent scale manufacturers, organic cotton cultivators with backward integration into agricultural supply, and digital-native subscription brands. Capacity expansion in Indian domestic manufacturing and strategic partnerships between biotech feedstock developers and legacy formulators represent the dominant competitive moves.
Among Asia-Pacific headquartered conglomerates, Unicharm Corporation and Hengan International Group occupy positions spanning mass-market to premium tier distribution. Procter & Gamble and Kimberly-Clark Corporation exemplify scale-driven manufacturers leveraging retail channel dominance and synthetic core cost structures. Essity AB represents the specialized crossover archetype, anchoring competitive positioning in absorbent solutions that serve multiple life stages across European and North American markets.
| Leading Market Players |
|---|
| Unicharm Corporation |
| Ontex Group NV |
| Procter & Gamble |
| Hengan International Group |
| Johnson & Johnson Services Inc. |
| Kimberly-Clark Corporation |
| Edgewell Personal Care |
| Kao Corporation |
| Essity AB |
| Others |
Supply Flow & Price Mechanics
The EU Green Deal's single-use plastics directive gates both qualified supply and premium-tier pricing access by mandating biodegradable substrate transitions that only certified formulators can meet, compressing margins for synthetic-dependent manufacturers while enabling shelf price premiums for compliant suppliers.
Pricing Analysis
Margin tightening in economy tiers reflects superabsorbent polymer cost volatility tied to crude benchmarks, while premium segments absorb certification expenses through shelf price adjustments. Three-tier pricing structure across premium, standard, and economy levels separates compostable-certified organic formats from conventional cotton and petroleum-derived synthetic cores. Price differentiation hinges on biodegradability certification grade and geographic delivery cost from Indian manufacturing clusters. Rural Indian buyers exhibit highest price sensitivity, while Scandinavian teenage consumers treat compostability as non-negotiable regardless of premium.
Supply Chain Analysis
Regional distribution centers in Frankfurt and Hamburg anchor European premium segment replenishment, while hub-and-spoke patterns from Tamil Nadu manufacturing clusters serve price-sensitive Indian rural penetration programs. Supply concentrates in India, China, and Germany across cotton cultivation, superabsorbent polymer synthesis, and precision converting equipment. Raw material dependencies center on petroleum-derived polymer feedstocks, organic cotton lint, and agricultural waste stream cellulose. Single-source vulnerability in medical-grade silicone for menstrual cups threatens subscription bundling models. Distribution runs through supermarket shelf dominance for mass-market pads and direct-to-consumer platforms for digital-native brands.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Plant-based superabsorbent polymers are displacing petroleum-derived cores, compressing traditional R&D timelines and forcing legacy formulators into accelerated biotech partnerships or margin erosion.
For Market Incumbents: Lock in backward integration into Indian organic cotton cultivation clusters to defend against feedstock cost volatility and BIS certification requirements that squeeze unorganized competitors. Prioritize acquisition-distribution layer engineering talent retention as material transitions require redesigned core architectures. Anchor retail shelf dominance through Procter & Gamble-style mass-market positioning while building subscription infrastructure to capture lifetime value from urban professional segments. For New Entrants and Emerging Players: REACH chemical disclosure mandates in Europe open a window for fragrance-free and adhesive-reformulated product lines that incumbent suppliers struggle to certify quickly. Target rural India displacement through BIS-certified affordable pads that unorganized producers cannot access. Pursue direct-to-consumer launch with cycle-tracking app integration to automate replenishment timing and reduce price sensitivity among digital-native consumers. For Investors and Strategic Acquirers: Accelerated biodegradability testing timeline compression is the leading indicator that laboratory capacity constraints will create acquisition premiums for certified testing facilities and compliant formulators. Five-to-ten year viability favors specialists with captive organic cotton supply and compostable certification infrastructure over petrochemical-dependent scale manufacturers. Watch for EU member state harmonization of compostable standards as the signal for premium tier margin expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Biodegradable Material Transition | EU Green Deal compliance enables premium shelf placement and public procurement eligibility. |
| Rural India Distribution Expansion | BIS-certified affordable pads displace cloth alternatives in underpenetrated states. |
| Subscription Platform Development | Cycle-tracking apps automate delivery timing and capture recurring revenue from urban professionals. |
| Biotech Feedstock Partnership | Agricultural waste stream cellulose reduces petroleum dependency and satisfies REACH mandates. |
| Incontinence-Menstrual Product Convergence | Aging demographics in Japan and Germany create crossover demand for multi-life-stage absorbent solutions. |
Methodological Framework
Document review covered customs records, BIS certification filings, and EU regulatory chemistry disclosures, complemented by interviews with brand managers at multinational consumer goods companies, category buyers at supermarket chains, supply planners at Indian manufacturing clusters, and regulatory affairs leads navigating REACH reformulation requirements. Secondary validation drew from Nielsen retail audit data, ECHA substance restriction updates, and FDA absorbency labeling guidance documents. Bottom-up volume builds across product format, material grade, and distribution channel triangulated against top-down market sizing from manufacturing capacity assessments.
Cross-referencing historical consumption patterns with panel input from procurement officers and channel sales heads anchored the analytical framework across the analysis window. Segmentation dimensions modeled include product type, material origin, end-user life stage, and distribution channel migration patterns. CAGRs were derived from elasticity-adjusted demand projections and capacity expansion timelines. Industry-specific forecast inputs incorporated school-based health program rollout schedules and biodegradability certification pipeline visibility.
Caveats apply where crude price volatility, fragmented compostable standards across EU member states, or menstrual cup durability improvements could materially shift the outlook for synthetic core manufacturers and disposable format replacement cycles. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Personal Health
Jet Lag Therapy Market
Personal Health
Reusable Face Mask Market
Personal Health
Piercing Aftercare Spray Market
Personal Health
Maternity and Personal Care Market
Personal Health
Blackhead Removing Vacuum Market
Personal Health
Sleep Mask Market
Personal Health
Skin Tag Remover Market
Personal Health
Tongue Scraper Market
Personal Health
Interdental Brush Market
Personal Health
Sexual Wellness Market
Personal Health
Asia Pacific Hair Loss Treatment Products Market
Personal Health
Health Coaching Market
Personal Health
Middle East and Africa Smoking Cessation and Nicotine De-Addiction Market
Personal Health
Corporate Wellness Market
Personal Health
North America Workplace Wellness Market
Personal Health
Medical Wellness Market