
 Chlorinated Methane Market | 2026-2036
Chlorinated Methane Market Size, Share, and Industry Trends Forecast 2026-2036
Chlorinated Methane Market Intelligence
The development of advanced catalytic hydrodechlorination processes is fragmenting traditional production routes for chlorinated methanes, creating new cost structures. This technological shift allows for more selective synthesis and reduced byproduct formation. Shin-Etsu Chemical Co., Ltd. leverages its scale in silicone production to optimize feedstock use. Dow Chemical Company specializes in differentiated grades for high-purity applications, while Solvay S.A. positions its portfolio to serve the European pharmaceutical sector's stringent requirements.
Chlorinated methanes are a group of organochlorine compounds derived from methane by substituting one to four hydrogen atoms with chlorine. These chemicals, including methylene chloride and chloroform, are typically produced via thermal or photochlorination of methane. They serve as essential solvents and chemical intermediates across multiple industries. Methylene chloride continues to be the dominant product type by volume, driven by its application in paints and coatings, while chloroform is a critical precursor for fluoropolymer synthesis and pharmaceutical intermediates.
Regulatory frameworks, including the US EPA's controls on solvent emissions and the EU's REACH regulation, directly influence product formulation. In China, MEE's 'dual carbon goals' are pushing producers toward cleaner manufacturing technologies. Future profitability for producers will hinge on navigating divergent regional environmental policies while investing in sustainable production pathways.
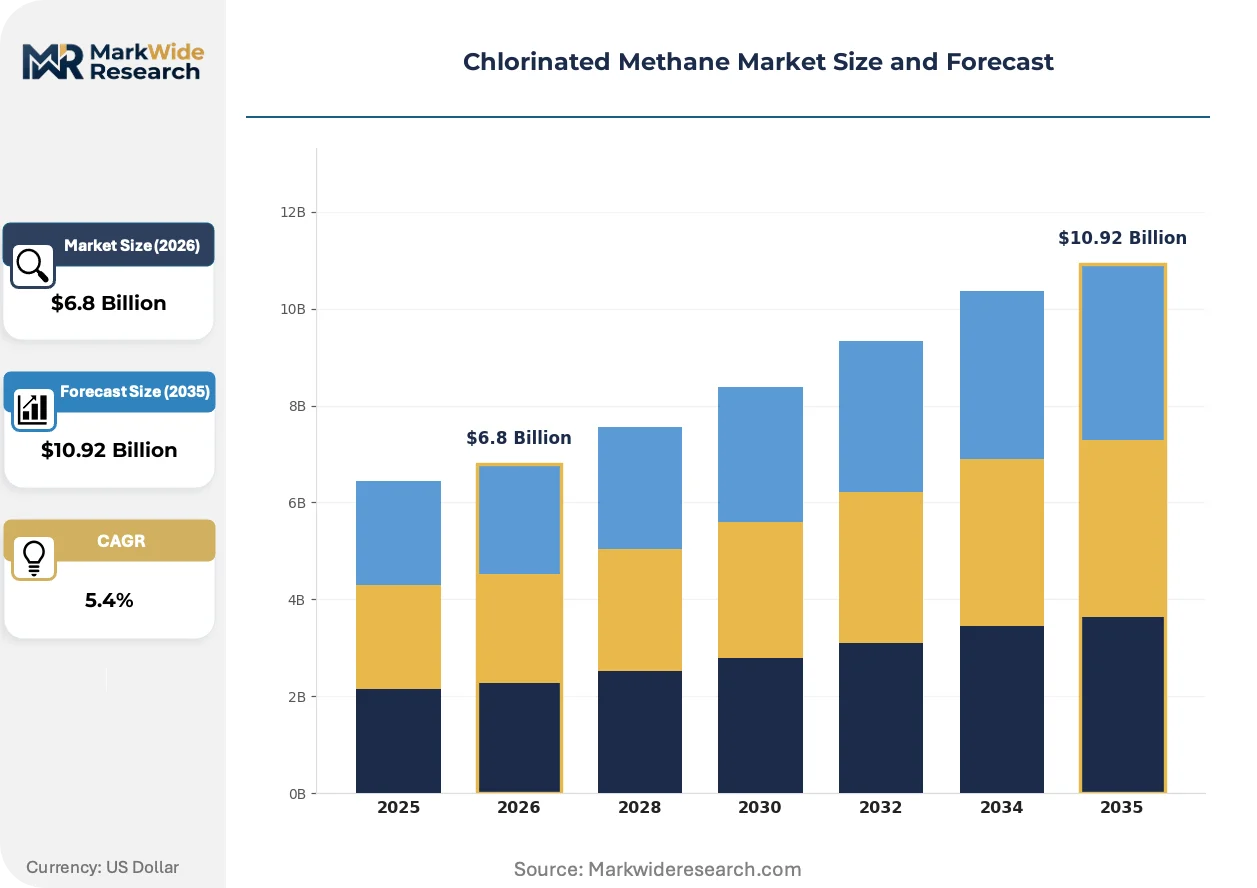
Market Dynamics
The chlorinated methane market's evolution is defined by the tension between established, cost-effective thermal chlorination production and the pressing need for cleaner manufacturing pathways. This dynamic is driven by divergent regional environmental policies and advancements in catalytic processes, forcing producers to re-evaluate long-term capital investment strategies against shifting compliance landscapes.
Growth Catalysts
- Pharmaceutical Intermediates:Consistent demand from the pharmaceutical industry for high-purity chloroform serves as a critical catalyst, as it is an essential precursor in the synthesis of active pharmaceutical ingredients and other complex molecules.
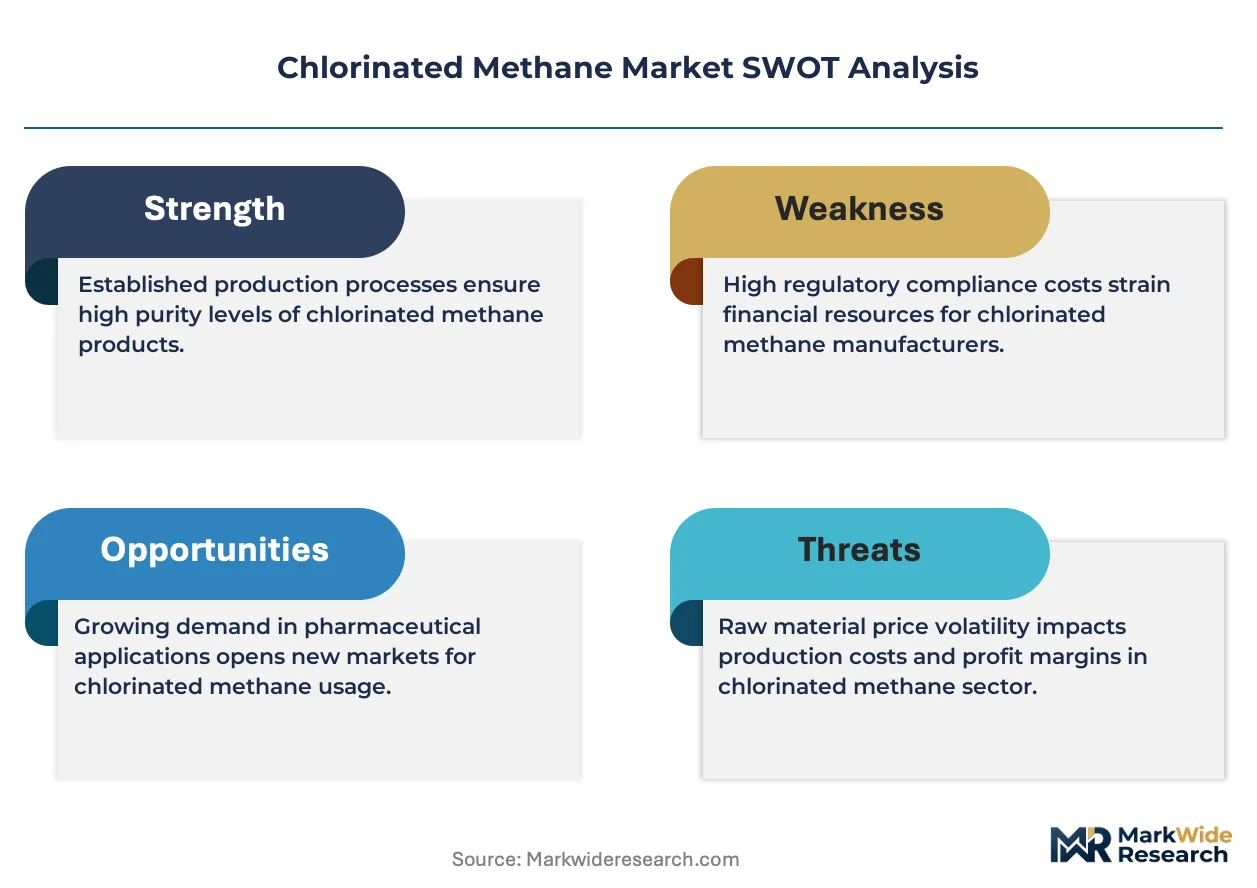
- EU REACH Regulation:The European Union's REACH framework mandates stringent purity and documentation standards, which creates a premium market for compliant grades of chlorinated methanes and supports value growth over volume.
- Fluoropolymer Synthesis:Chloroform's role as a primary feedstock for producing fluoropolymers, particularly PTFE, underpins a significant portion of demand, especially in industrial regions with strong polymer manufacturing sectors.
Market Restraints
- Substitution Threats:Increasing regulatory scrutiny and health concerns associated with methylene chloride, particularly under frameworks like the US EPA's solvent regulations, are accelerating its substitution with aqueous cleaners or bio-based solvents in some applications.
- Feedstock Price Volatility:Producer profitability is constrained by the fluctuating costs of key raw materials, namely natural gas (methane) and chlorine, which introduces significant margin uncertainty into the production cycle.
- Byproduct Management Costs:Traditional photochlorination and thermal chlorination processes generate a mix of chlorinated methanes, requiring energy-intensive and costly distillation steps to separate products and manage unwanted byproducts like carbon tetrachloride.
Strategic Opportunities
- Green Chemistry Pathways:Investing in the development of novel catalytic systems that allow for the selective synthesis of a single chlorinated methane product presents a major opportunity to reduce waste and improve process economics.
- High-Purity Electronics Grade:There is a growing opportunity in the electronics sector for specialized, ultra-high-purity grades of methylene chloride for use in precision cleaning and photoresist stripping during semiconductor fabrication.
- Circular Economy Models:Developing and scaling solvent recovery and recycling programs for end-users offers a pathway to create closed-loop systems, addressing environmental concerns and providing a competitive service-based revenue stream.
Industry Challenges
- Capital-Intensive Process Upgrades:The transition from legacy thermal chlorination plants to cleaner, more efficient catalytic hydrodechlorination technologies requires substantial capital investment, creating a high barrier to modernization for some producers.
- Navigating Divergent Regulations:Managing compliance across disparate regulatory regimes, such as the EU's ECHA requirements versus China's MEE standards, complicates global trade and increases operational overhead for multinational producers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chlorinated Methane Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $10.92 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Methylene Chloride, Chloroform, Carbon Tetrachloride, Tetrachloroethylene End Use Industry: Pharmaceuticals, Agrochemicals, Paints & Coatings, Cleaning Products Grade: Industrial Grade, Laboratory Grade, Reagent Grade, Electronic Grade Packaging Type: Drums, Bulk Containers, Bottles, Carboys |
| Companies Covered | Shin-Etsu Chemical Co., Ltd., Albemarle Corporation, The Chemours Company, BASF SE, Wacker Chemie AG, Occidental Petroleum Corporation, Solvay S.A., Dow Chemical Company, INEOS Group Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chlorinated Methane Market Strategic Shifts & Innovations
Process technology evolution is fundamentally altering the cost structure and environmental footprint of chlorinated methane production. This shift is occurring alongside tightening global regulations on solvent emissions, compelling a strategic pivot towards higher-purity grades and more sustainable manufacturing methods across the industry.
Advanced catalytic hydrodechlorination provides a more selective pathway for synthesizing specific chlorinated methanes. Chemical manufacturers focused on reducing byproduct formation and energy consumption are steadily exploring these next-generation processes. This development is hybridizing the production landscape, allowing firms to blend traditional thermal methods for bulk output with precise catalytic routes for high-value specialty grades.
The European Union's F-Gas Regulation directly impacts the fluoropolymer value chain, which uses chloroform as a key precursor. The regulation's phasedown of certain hydrofluorocarbons (HFCs) influences feedstock demand patterns for chloroform producers supplying the refrigerants and polymers sector. This regulatory pressure is most acute for producers whose portfolios are heavily weighted towards feedstocks for older-generation HFCs.
A notable behavioral shift is the rising demand for products with verified compliance and supply chain transparency. This trend is disrupting purchasing decisions based purely on price, giving an advantage to suppliers who can provide extensive documentation aligned with standards like REACH or specific end-use industry requirements. The pharmaceutical and medical device sectors are at the forefront of this movement, particularly in North America and Europe.
Chlorinated Methane Market Segmentation
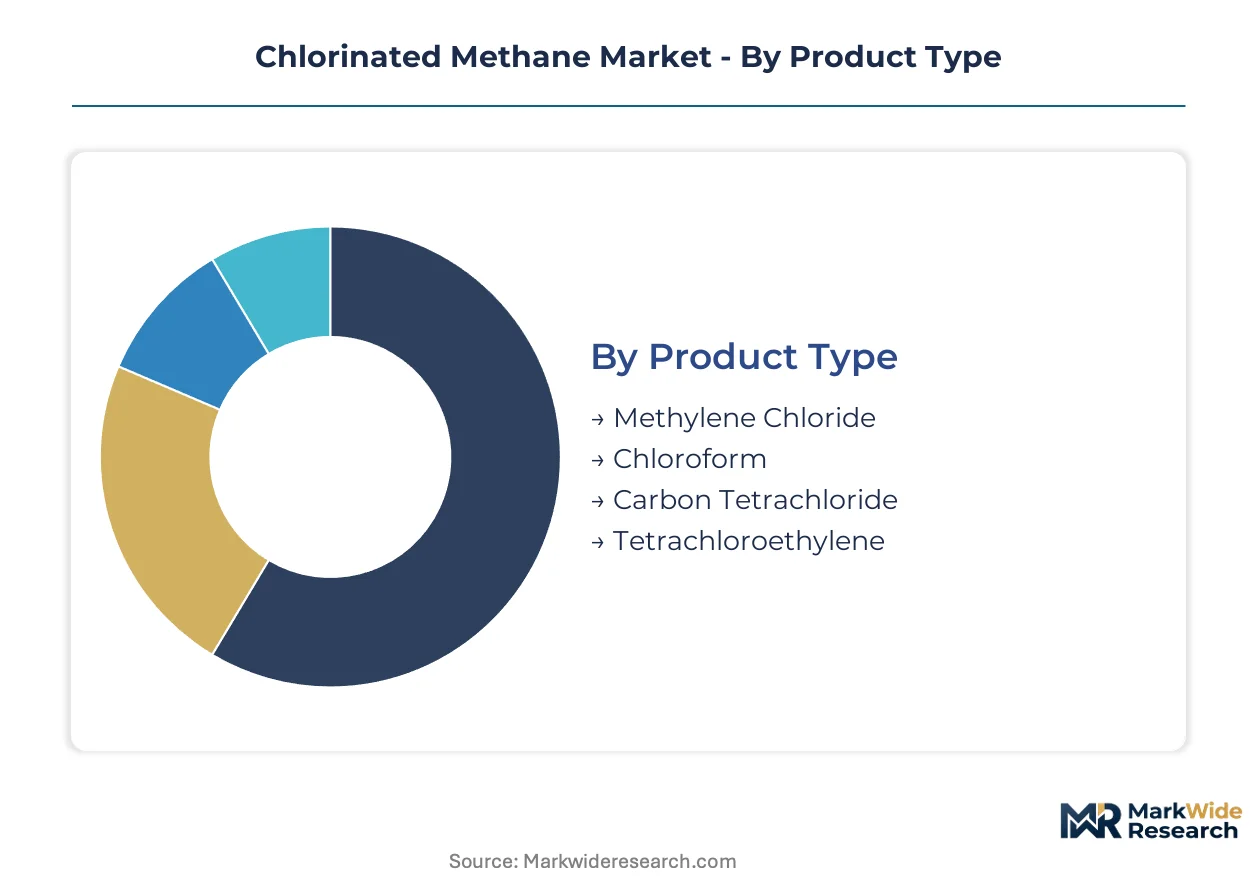
The chlorinated methane market's segmentation reveals the diverse applications and purity requirements driving demand across industries. Understanding these distinct segments is crucial for producers to align their manufacturing capabilities with specific market needs and regulatory landscapes. This granular view highlights areas of concentrated value and emerging opportunities.
Product Type:
The volume and application diversity of chlorinated methanes define the product type segmentation.
- Methylene Chloride:This colorless, volatile liquid serves as a versatile solvent for paints, coatings, and degreasing applications. Its widespread use in industrial settings drives significant bulk demand, particularly in Asia-Pacific manufacturing hubs.
- Chloroform:A dense, colorless liquid, chloroform is primarily valued as a precursor for fluoropolymer synthesis, such as PTFE, and as an intermediate in pharmaceutical production. Demand for high-purity grades is consistent from European pharmaceutical companies adhering to REACH standards.
- Carbon Tetrachloride:Once widely used as a refrigerant and fire extinguishant, its application is now severely restricted due to environmental concerns, primarily serving as a feedstock for specific chemical syntheses under strict controls.
- Tetrachloroethylene:Also known as perchloroethylene, this solvent is mainly utilized in dry cleaning and metal degreasing processes, facing substitution pressures from alternative cleaning technologies and environmental regulations.
Methylene Chloride holds installed capacity. Chloroform is rotating up the share rankings.
End Use Industry:
The functional requirements and regulatory compliance needs of various industries shape the end-use segmentation.
- Pharmaceuticals:This sector requires ultra-high purity chlorinated methanes, especially chloroform, for synthesizing active pharmaceutical ingredients (APIs) and as an extraction solvent. Strict quality standards from regulators like the US FDA and Europe's EMA dictate supplier selection.
- Paints & Coatings:Methylene chloride is extensively used as a solvent in paint removers and aerosol formulations due to its excellent solvency and rapid evaporation rate. Demand is influenced by construction activity and automotive production, particularly in China's industrial clusters.
- Agrochemicals:Chlorinated methanes function as solvents and intermediates in the production of various pesticides and herbicides. The demand here is cyclical, often tied to agricultural seasons and crop protection needs.
- Cleaning Products:Methylene chloride finds application in industrial degreasers and specialized cleaning formulations for electronics. Regulatory scrutiny from the US EPA on solvent emissions is driving innovation towards less hazardous alternatives.
Pharmaceuticals are expanding most quickly. Cleaning Products are gaining share fastest.
Grade:
The purity levels and specific performance criteria demanded by various applications delineate the grade segmentation.
- Industrial Grade:This grade represents the largest volume segment, used in bulk manufacturing processes where high purity is less critical than cost-effectiveness, such as general solvent applications and chemical intermediates. Production typically involves traditional thermal chlorination.
- Electronic Grade:Characterized by extremely low levels of impurities, moisture, and particulate matter, this specialized grade of methylene chloride is essential for precision cleaning in semiconductor manufacturing and photoresist stripping. Demand is concentrated in regions with advanced electronics production like South Korea and Taiwan.
- Laboratory Grade:Used in research and development settings for analytical purposes and small-scale syntheses, this grade offers consistent quality suitable for controlled experiments.
- Reagent Grade:This grade meets specific chemical purity standards for use in chemical reactions and analytical procedures, often with certified assay values.
Industrial Grade maintains significant market presence. Electronic Grade shows the steepest expansion trajectory.
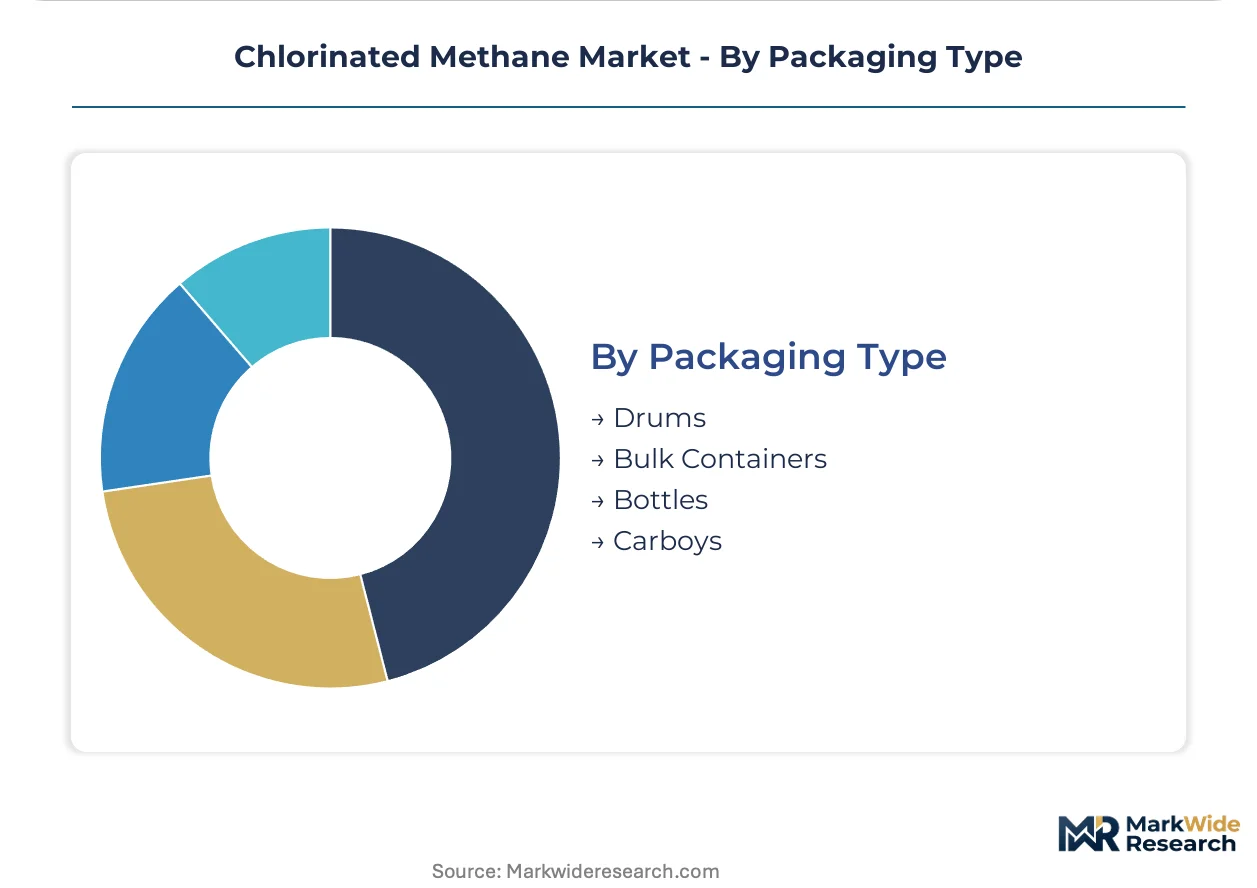
Packaging Type:
The scale of consumption and logistical considerations dictate the packaging type segmentation.
- Drums:Standard 200-liter drums are widely used for distributing chlorinated methanes to medium-sized industrial users and for export, balancing transport efficiency with manageable handling. This format facilitates distribution across diverse end-use sectors.
- Bulk Containers:Large-volume users, such as major chemical manufacturers and fluoropolymer producers, receive chlorinated methanes in ISO tanks or rail cars. This method optimizes logistics and reduces costs for high-tonnage deliveries to industrial parks in China.
- Bottles:Smaller quantities, typically laboratory or reagent grades, are packaged in bottles for precise dispensing and to maintain product integrity for specialized applications.
- Carboys:Intermediate volumes, larger than bottles but smaller than drums, are transported in carboys, often for specialized industrial applications or for distribution to smaller commercial users.
Bulk Containers dominate large-scale distribution. Carboys are climbing the fastest in specialized uses.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Concentrated demand from pharmaceutical and chemical manufacturing clusters significantly shapes the regional outlook for chlorinated methanes. Stringent regulatory frameworks and the push for cleaner production methods influence market dynamics across key industrial nations. Producers must strategically align their offerings with regional environmental policies and specific end-use sector requirements.
China
Demand for methylene chloride and chloroform remains substantial from China's robust chemical manufacturing clusters, supporting its extensive industrial output. The Ministry of Ecology and Environment's (MEE) 'dual carbon goals' are compelling producers towards cleaner technologies and more efficient processes. The Yangtze River Delta region, a hub for chemical production, is seeing investments in advanced catalytic systems to meet evolving environmental standards.
Germany
Germany's pharmaceutical industry drives consistent demand for high-purity chloroform, essential for synthesizing active pharmaceutical ingredients. The European Union's REACH regulation mandates strict purity and documentation standards, creating a premium market for compliant grades within the country. Chemical parks in regions like North Rhine-Westphalia are adapting production to serve the stringent requirements of the European pharmaceutical sector.
United States
The United States market sees significant demand for methylene chloride in industrial cleaning applications and for electronic-grade specifications. The US EPA's controls on solvent emissions are accelerating the substitution of methylene chloride in some traditional uses, pushing innovation. Major electronics manufacturing hubs in California and Texas require ultra-high-purity grades for semiconductor fabrication processes.
South Korea
South Korea's advanced electronics sector fuels strong demand for specialized, ultra-high-purity methylene chloride for precision cleaning and photoresist stripping. Stringent quality control is paramount for suppliers serving the country's semiconductor and display manufacturing industries. Industrial complexes in Gyeonggi Province are a focal point for the production and consumption of electronic-grade chlorinated methanes.
India
India's burgeoning pharmaceutical and agrochemical sectors represent significant demand drivers for chlorinated methane intermediates. The country's national pharmaceutical regulators emphasize quality, influencing the purity requirements for chemical inputs. Chemical manufacturing zones in Gujarat and Maharashtra are expanding capacity to support the growth of local drug and crop protection industries.
Chlorinated Methane Market Key Industry Players
Channel-controlling players compete with product-specialist players across the chlorinated methane market, creating a tiered competitive structure. Large-scale integrated chemical companies leverage their feedstock advantages and broad portfolios to maintain market share. Specialized manufacturers, conversely, focus on niche applications requiring ultra-high purity or specific formulations. The dominant competitive moves include strategic partnerships for technology development and capital investments in process upgrades.
Scale-driven producers like Dow Chemical Company occupy a significant position, offering differentiated grades for high-purity applications across diverse industries. Similarly, Solvay S.A., a Belgian multinational, represents a key player whose portfolio is strategically positioned to serve the stringent requirements of the European pharmaceutical sector. Shin-Etsu Chemical Co., Ltd., a Japanese chemical company, exemplifies firms leveraging vertical integration in silicone production to optimize feedstock use and cost structures for chlorinated methanes.
| Leading Market Players |
|---|
| Shin-Etsu Chemical Co., Ltd. |
| Albemarle Corporation |
| The Chemours Company |
| BASF SE |
| Wacker Chemie AG |
| Occidental Petroleum Corporation |
| Solvay S.A. |
| Dow Chemical Company |
| INEOS Group Ltd. |
| Others |
Cost & Logistics Intelligence
China's concentrated chemical manufacturing output for chlorinated methanes significantly influences global pricing, determining where value accrues for downstream users. Upstream cost volatility, particularly for methane and chlorine, directly impacts producer margins across all grades.
Pricing Analysis
Cost-plus contracts, often indexed to natural gas and chlorine prices, govern many long-term chlorinated methane agreements. Price differentiation arises from ultra-high purity specifications for electronic grade and stringent pharmaceutical certifications. Pricing pressure stems from overcapacity in industrial grades, particularly in Asian markets. Electronic and pharmaceutical sectors exhibit the lowest price sensitivity, prioritizing quality and compliance over cost.
Supply Chain Analysis
Export control regimes, particularly those impacting precursors for fluoropolymers or high-purity electronics chemicals, limit the free flow of chlorinated methanes globally. Supply concentrates heavily in China, the United States, and Germany, which draw from methane and chlorine as primary raw materials. Regulatory restrictions like the EU's REACH framework pose a significant structural risk by fragmenting market access. Distribution often runs through a mix of large bulk shipments and specialized chemical distributors for high-purity grades.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The chlorinated methane market exhibits a significant scarcity in advanced catalytic hydrodechlorination expertise, creating a bottleneck for sustainable production. Strategic investments targeting this technological gap will redefine competitive advantages.
For Market Incumbents:Harden existing long-term supply agreements with pharmaceutical and electronics clients to counter emerging regulatory threats. Invest in process R&D for catalytic hydrodechlorination to reduce byproduct formation and energy consumption, mitigating margin pressure from fluctuating feedstock costs. Leverage captive supply of methane and chlorine to optimize production costs and ensure supply stability.
For New Entrants and Emerging Players:Specialized high-purity electronics grade demand in Southeast Asia represents a significant underpenetrated segment for new entrants. Target niche applications requiring ultra-high purity methylene chloride for semiconductor fabrication in countries like Vietnam and Malaysia. A go-to-market angle focusing on certified compliance and technical support for advanced manufacturing processes will differentiate offerings.
For Investors and Strategic Acquirers:Secondary-cycle assets sit with mid-sized chemical producers lacking the capital for advanced catalytic upgrades. Long-term viability hinges on acquiring firms with established regulatory compliance pathways and strong intellectual property in green chemistry. The signal to watch is successful pilot-scale demonstrations of novel, selective chlorination technologies gaining commercial traction.
| Strategic Initiative | Industry Significance |
|---|---|
| Green Manufacturing Transition | Reduces environmental footprint and aligns with global 'dual carbon goals' in China. |
| Capacity Expansion | Meets growing demand from pharmaceutical and electronics sectors in Asia-Pacific. |
| Long-term Supply Agreement | Secures consistent feedstock for critical downstream industries like fluoropolymers. |
| Joint Venture | Accelerates development and commercialization of advanced catalytic processes. |
| Regulatory Compliance Investment | Ensures market access and premium pricing for high-purity grades in the EU. |
Research Approach
Operator-level perspectives from plant managers, R&D directors, procurement leads, and regulatory affairs specialists anchored the qualitative base for this analysis. This primary research was triangulated with secondary data from customs and trade records, Cefic and ACC reports, and company SEC filings. A rigorous bottom-up and top-down approach validated market sizing and segmentation.
Scenario bracketing provided a robust framework for projecting market evolution across the analysis window. The analytical framework modeled segmentation dimensions including product type, end-use industry, grade tier, and regional regulatory impact. Compound annual growth rates were derived from historical trends and anticipated technological shifts. Key forecast inputs included pharmaceutical production volumes and fluoropolymer demand forecasts.
The forecast holds incumbent behavior within observed patterns; aggressive moves by state-backed chemical enterprises or major green chemistry innovators would shift outcomes. Forecasts reflect assumptions regarding regulatory enforcement and technological adoption rates. Material shifts in global trade policies would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Organic Chemicals
Phenol Market
Organic Chemicals
Synthetic and Bio-Based Aniline Market
Organic Chemicals
1,3-Dichloroacetone Market
Organic Chemicals
Heterocyclic and Fluoro Organic Compounds Market
Organic Chemicals
Acrylic Acid Market
Organic Chemicals
Organic Peroxide Market
Organic Chemicals
2-Methylbutanoic Acid Market
Organic Chemicals
Organocatalyst Market
Organic Chemicals
Behenyl Alcohol Market
Organic Chemicals
Asia-Pacific Synthetic Camphor Market
Organic Chemicals
Crotonic Acid Market
Organic Chemicals
Ethylamine Market
Organic Chemicals
Global Metal-Organic Framework Market
Organic Chemicals
Global Biphenyl Market
Organic Chemicals
Chloro -Dimethylsilane (CAS 1066-35-9) Market
Organic Chemicals
Pyridine Derivatives Market