
 Acrylic Acid Market | 2026-2036
Acrylic Acid Market Size, Share, and Industry Trends Forecast 2026-2036
Acrylic Acid Market Analysis
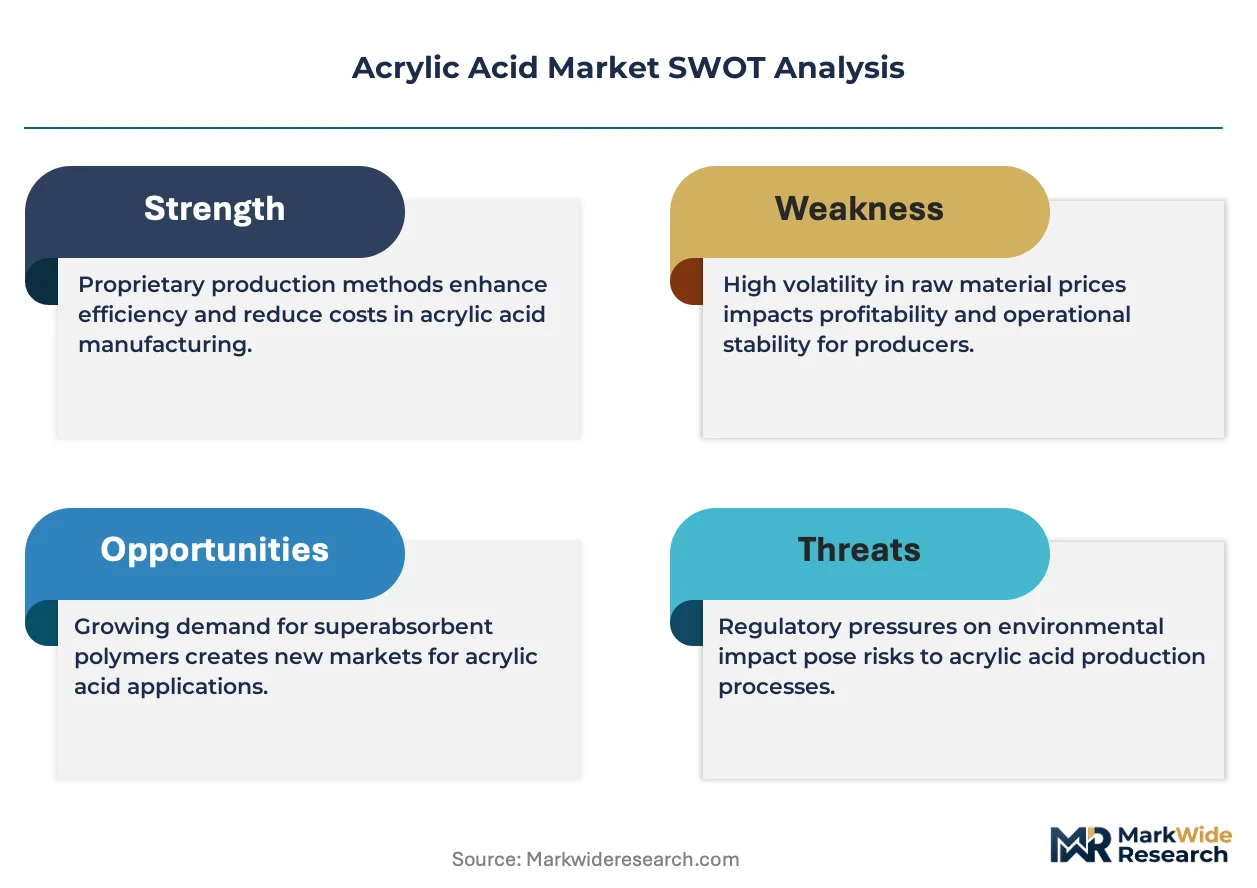
The EU Green Deal is hardening demand for bio-based acrylic acid pathways across European supply chains. BASF SE leverages its integrated Ludwigshafen complex to sustain cost-advantaged glacial acrylic acid output. Arkema competes through specialty ester derivatives, while Nippon Shokubai Co., Ltd. anchors Asian superabsorbent polymer feedstock supply with controlled oxidation technology.
Acrylic acid is an unsaturated carboxylic acid with the formula CH₂=CHCOOH, produced industrially via two-stage propylene oxidation with acrolein as an intermediate; its conjugated double bond enables radical polymerization into polyacrylic acid salts, esters, and amides serving water absorption, adhesion, and surface coating functions. Superabsorbent polymers command the dominant value pool in personal care and agriculture applications where liquid retention specifications are stringent. Coatings and adhesives segments are gaining structural importance in construction and automotive end uses as VOC regulations elevate performance requirements for waterborne acrylic systems.
EPA standards in the United States and REACH in Europe constrain residual monomer thresholds and emission profiles during acrylic acid production, while China's MEE enforces wastewater discharge limits that affect propylene oxidation unit economics. Stakeholders must monitor regulatory divergence between jurisdictions to align capacity investments with compliant process configurations and derivative qualification timelines.
Market Dynamics
Propylene feedstock volatility and oxidation catalyst degradation cycles are compressing operating margins across acrylic acid production networks, forcing asset owners to recalibrate maintenance schedules and intermediate storage configurations.
Growth Catalysts
- EU Green Deal bio-mandates:European formulators face binding renewable content thresholds in coatings and adhesives, pulling bio-based acrylic acid pathways into commercial scale.
- Superabsorbent polymer specifications:Personal care manufacturers in China and Southeast Asia are tightening liquid retention performance standards for hygiene products, elevating high-purity glacial acid demand.
- Propylene oxidation yield improvements:Advanced molybdenum-vanadium catalyst formulations are lifting selectivity in acrolein-to-acrylic conversion, reducing per-unit energy intensity.
Market Restraints
- Propylene price linkage:Acrylic acid economics remain tethered to naphtha-cracker propylene output decisions in Gulf Coast and Northeast Asian refining complexes.
- MEE wastewater discharge limits:China's Ministry of Ecology and Environment enforcement is raising treatment capital requirements for oxidation unit effluent streams.
- Ester substitution in coatings:Methacrylate and vinyl acetate systems are capturing share in low-VOC architectural formulations where hardness specifications permit.
Strategic Opportunities
- Indian coatings expansion:Infrastructure investment and automotive production growth are outpacing domestic acrylic ester supply, creating import substitution openings.
- Controlled-release agriculture:Superabsorbent polymer formulations for moisture retention in drought-prone cultivation zones represent an emerging volume pool.
- REACH-REACH UK divergence:Separate chemical registration requirements in Great Britain are fragmenting compliance pathways, favoring localized derivative production.
Industry Challenges
- Catalyst engineering expertise:The specialized knowledge required for oxidation reactor optimization and byproduct suppression is concentrating among a narrow technical cohort.
- Derivative qualification timelines:Coatings and adhesive formulators demand extended stability testing for new acid batches, stretching working capital cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Acrylic Acid Market |
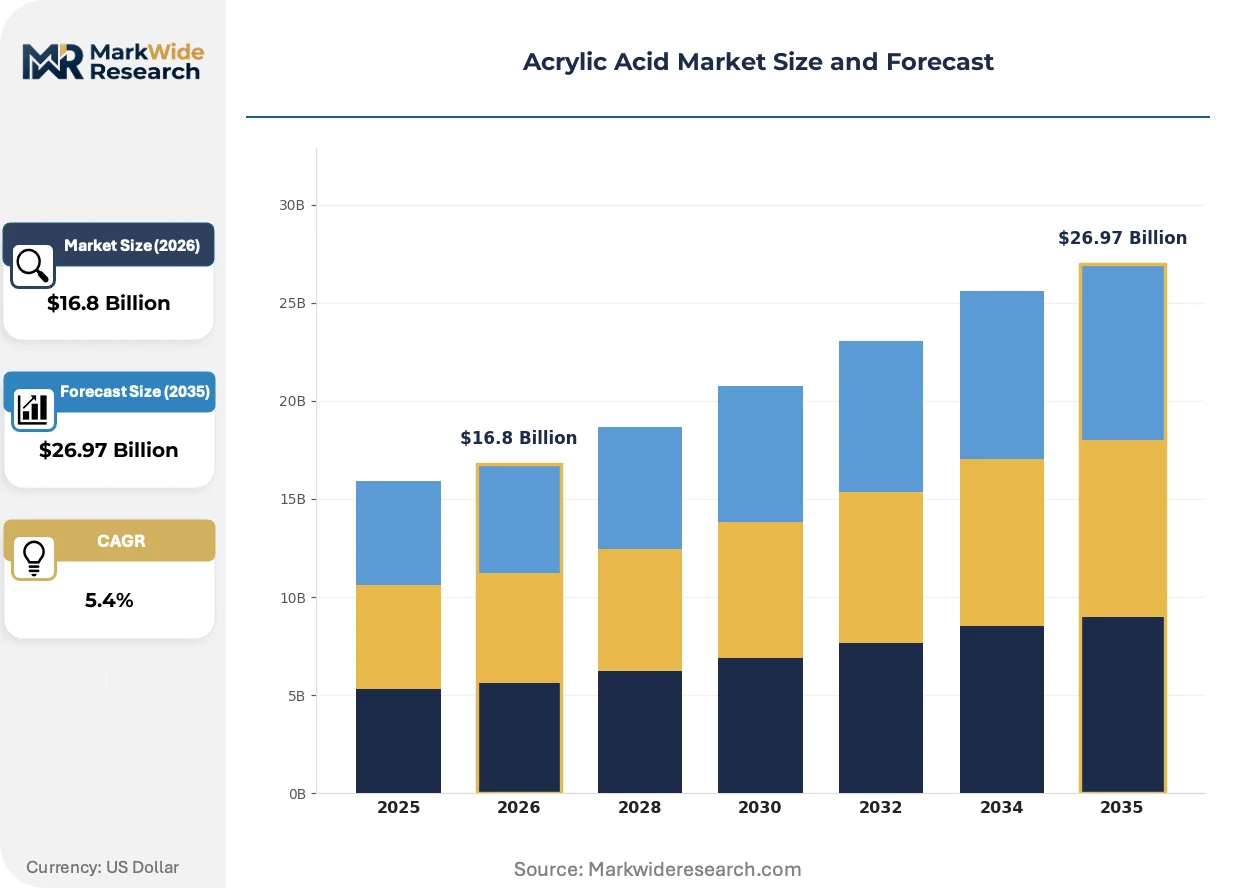
| Market Size in 2026 | $16.8 Billion |
| Market Size in 2035 | $26.97 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Superabsorbent Polymers, Coatings, Adhesives, Textiles Application: Personal Care, Agriculture, Construction, Automotive End User: Consumer Goods, Pharmaceuticals, Electronics, Industrial Form: Liquid, Solid, Emulsion, Polymer |
| Companies Covered | BASF SE, Arkema, Dow Inc., Nippon Shokubai Co., Ltd., Evonik Industries AG, Mitsubishi Chemical Corporation, LG Chem Ltd., Formosa Plastics Corporation, SIBUR Holding, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Acrylic Acid Market Emerging Trajectories
Acrylic acid production and derivative formulation are experiencing simultaneous pressure from decarbonization mandates and performance specification elevation, compressing the viable technology set toward higher-yield, lower-emission configurations.
Biocatalytic routes employing engineered bacteria are absorbing research investment from European and North American chemical majors seeking to bypass propylene oxidation entirely. Specialty ester producers in Germany and the Netherlands are piloting fermentation-derived acid for high-margin cosmetic and pharmaceutical applications. This pathway is absorbing regulatory preference as EU taxonomy criteria harden against fossil-derived building blocks.
REACH authorization requirements for residual monomer thresholds are tightening specification windows for superabsorbent polymer feedstock across European personal care supply chains. Formulators serving the German and French hygiene markets are demanding certificates of analysis with ppb-level impurity documentation. The compliance burden is absorbing smaller traders and pushing volume toward integrated producers with in-house analytical capabilities.
Specification-driven procurement is compressing supplier lists as coatings manufacturers consolidate acid purchasing around fewer qualified sources with documented carbon footprints. Large architectural coatings buyers in the United States are requiring Scope 3 emissions disclosures that favor domestic producers with verified natural gas feedstock provenance. The concentration effect is visible in contract structures along the Gulf Coast petrochemical corridor.
Acrylic Acid Market Segmentation
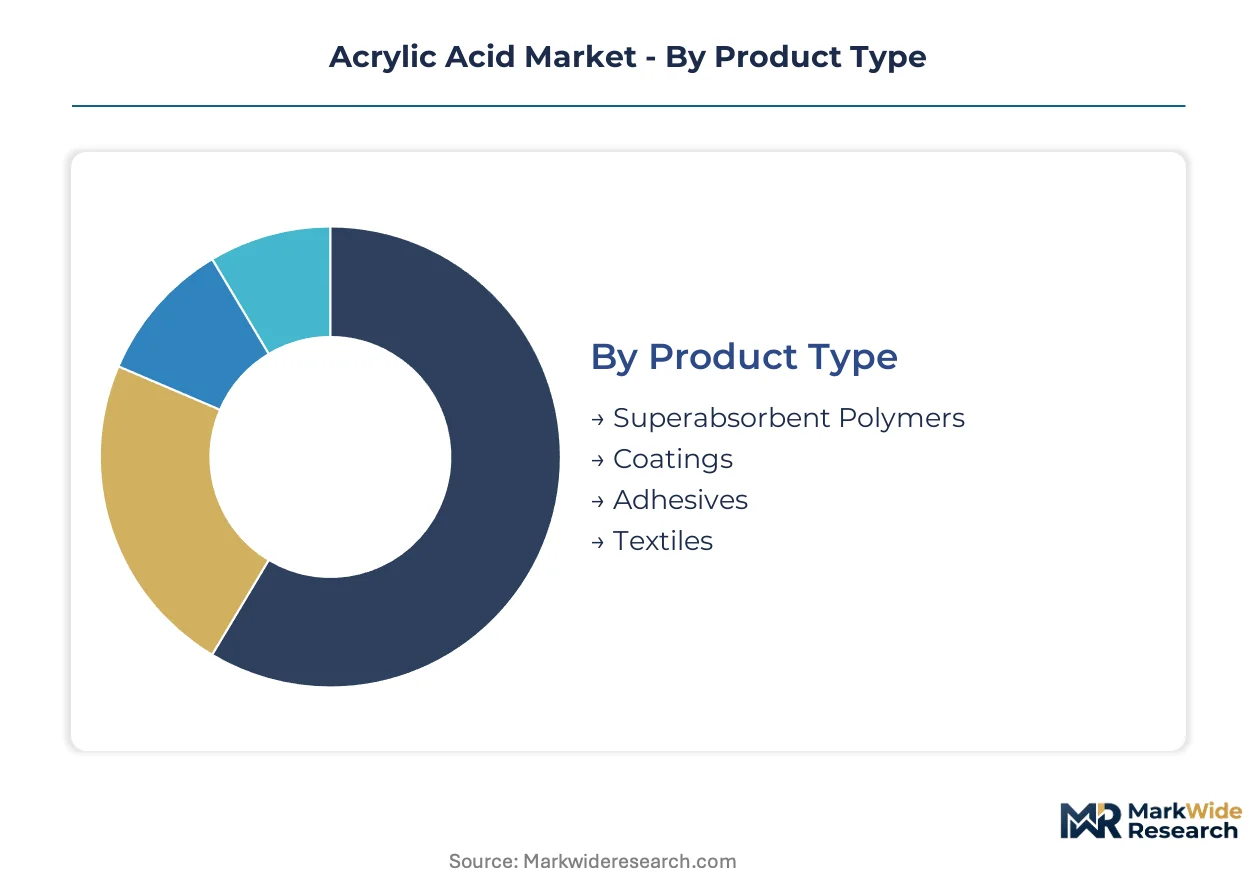
Acrylic acid derivatives serve both standalone commodity markets and embedded formulation systems, with segmentation revealing where value capture concentrates versus where material flows as an intermediate input. Product type and application splits expose divergent margin structures across hygiene absorbents versus industrial coatings.
Product Type:
Standalone polymer systems absorb most volume, while coating and adhesive formulations embed acid derivatives as performance-modifying components within larger chemical architectures.
- Superabsorbent Polymers:Cross-linked polyacrylic acid salts retain hundreds of times their mass in aqueous solution. Personal care manufacturers in China enforce tightening liquid retention specifications, pulling high-purity glacial acid into premium diaper and hygiene product supply chains.
- Coatings:Waterborne acrylic emulsions deliver film-forming properties with low volatile organic compound emission profiles. Construction activity in India and Southeast Asia is outpacing domestic ester supply, forcing formulators to qualify imported acid batches against extended stability protocols.
- Adhesives:Pressure-sensitive and structural bonding applications leverage acrylic ester tack and weathering resistance.
- Textiles:Sizing agents and finish coatings employ polyacrylic acid derivatives for yarn protection and hand modification.
Superabsorbent polymers lead volumes today; coatings are gaining share fastest.
Application:
Cost tier stratification separates high-specification personal care formulations from price-sensitive agricultural and construction end uses.
- Personal Care:Diaper and hygiene product manufacturers demand superabsorbent polymer feedstock with ppb-level residual monomer documentation. REACH authorization requirements in Europe are compressing supplier lists toward integrated producers with in-house analytical capabilities.
- Agriculture:Controlled-release formulations for moisture retention in drought-prone cultivation zones represent an emerging volume pool. Superabsorbent polymer incorporation into soil conditioning products is expanding beyond traditional personal care anchors.
- Construction:Architectural coatings and sealant applications drive waterborne acrylic ester consumption.
- Automotive:OEM and refinish coatings employ specialty ester derivatives for gloss retention and chip resistance.
Personal care dominates value capture; agriculture is climbing the fastest.
End User:
Customer type determines specification stringency, with pharmaceutical and electronics buyers imposing purity thresholds that commodity industrial users do not require.
- Consumer Goods:Hygiene and household product manufacturers anchor superabsorbent polymer offtake. German and French formulators are demanding certificates of analysis with documented carbon footprints, favoring producers with verified natural gas feedstock provenance.
- Pharmaceuticals:Specialty ester producers in Germany and the Netherlands are piloting fermentation-derived acid for high-margin cosmetic and pharmaceutical applications, absorbing regulatory preference as EU taxonomy criteria harden against fossil-derived building blocks.
- Electronics:Photoresist and display coating applications require ultra-high purity grades.
- Industrial:General adhesive and coating formulations consume standard commercial grades.
Consumer goods absorbs the most tonnage; pharmaceuticals commands the steepest premium expansion.
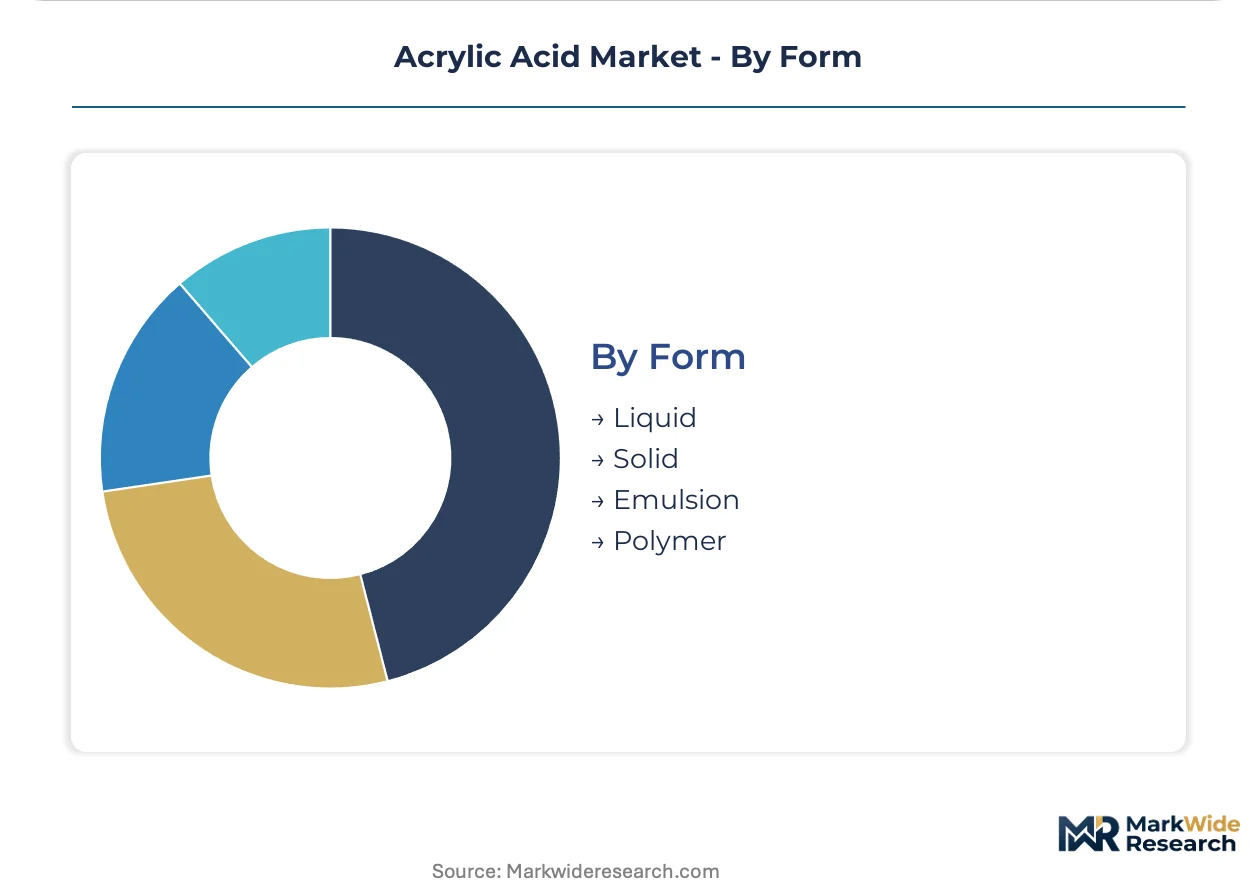
Form:
Supply concentration varies by physical state, with liquid and emulsion forms dominating merchant trade while solid and polymer forms flow through captive channels.
- Liquid:Glacial acrylic acid in aqueous solution serves direct esterification and polymerization feedstock. Gulf Coast petrochemical corridor producers with integrated propylene oxidation units capture most merchant liquid supply.
- Emulsion:Pre-dispersed waterborne systems bypass customer-side formulation complexity. Large architectural coatings buyers in the United States are requiring Scope 3 emissions disclosures that favor domestic emulsion producers.
- Solid:Crystalline or flake forms enable long-haul logistics to remote formulation sites.
- Polymer:Pre-reacted polyacrylic acid salts and esters ship as finished feedstock for downstream compounding.
Liquid leads merchant volumes today; emulsion is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Acrylic acid production scaled through post-war petrochemical corridor development in Germany and the United States, with Asian capacity following in the 1980s as propylene oxidation technology diffused to Japan and South Korea.
United States
Gulf Coast refineries supply propylene feedstock to integrated oxidation complexes serving domestic coatings and adhesive formulators. EPA emission standards constrain residual monomer thresholds during acrylic acid production. Houston and Corpus Christi host concentrated derivative manufacturing for waterborne architectural coatings.
Germany
Ludwigshafen's integrated chemical complex anchors European glacial acrylic acid output for superabsorbent polymer and specialty ester markets. REACH authorization requirements harden purity benchmarks for personal care feedstock supply. The Rhine-Neckar industrial cluster sustains cost-advantaged production through captive propylene and energy integration.
China
Coastal provinces dominate acrylic acid derivative output feeding both domestic coatings expansion and export adhesive markets. MEE wastewater discharge limits raise treatment capital requirements for oxidation unit operators. Yangtze River Delta chemical parks concentrate superabsorbent polymer feedstock production for hygiene manufacturers.
Japan
Controlled oxidation technology expertise concentrates among Osaka and Tokyo metropolitan area producers serving high-specification electronics and pharmaceutical grades. METI industrial standards govern residual impurity thresholds for display coating applications. The Keihin industrial corridor maintains specialized ester derivative capacity.
India
Infrastructure investment and automotive production growth outpace domestic acrylic ester supply, creating import substitution openings for coatings formulators. BIS certification requirements extend qualification timelines for imported acid batches. Gujarat and Maharashtra industrial zones attract merchant acid imports for construction chemical compounding.
Acrylic Acid Market Vendor Landscape
Capital-heavy producers compete with asset-light specialty ester formulators across divergent margin structures. The market consolidates around integrated petrochemical operators with captive propylene supply and oxidation reactor expertise. Three archetypes dominate: Gulf Coast refiners with backward integration into feedstock, European chemical majors with fermentation-derived acid pilots, and Asian conglomerates with controlled oxidation technology. Competitive moves center on catalyst yield improvements and geographic capacity expansion into undersupplied Indian and Southeast Asian markets.
Within the integrated petrochemical tier, BASF SE and Dow Inc. exemplify asset-heavy positioning with complex-integrated production. Arkema and Nippon Shokubai Co., Ltd. occupy specialist positions emphasizing derivative formulation expertise over commodity acid output. These four represent the dominant competitive anchors across European, North American, and Asian supply corridors.
| Leading Market Players |
|---|
| BASF SE |
| Arkema |
| Dow Inc. |
| Nippon Shokubai Co., Ltd. |
| Evonik Industries AG |
| Mitsubishi Chemical Corporation |
| LG Chem Ltd. |
| Formosa Plastics Corporation |
| SIBUR Holding |
| Others |
Supply Flow & Price Mechanics
REACH authorization thresholds for residual monomer documentation are forcing coatings formulators to consolidate procurement around fewer qualified suppliers, compressing merchant acid spot markets and elevating contract premiums for integrated producers with in-house analytical capabilities.
Pricing Analysis
Three-tier pricing structure across pharmaceutical-grade, industrial-grade, and commodity-grade levels anchors acrylic acid commercial terms. Price differentiation hinges on certification stringency and volume scale, with personal care manufacturers absorbing steep premiums for ppb-level impurity documentation while construction chemical buyers negotiate on delivered cost. Cost compression in standard industrial grades is intensifying because methacrylate and vinyl acetate substitution erodes share in low-VOC architectural formulations. Construction chemical formulators exhibit highest price sensitivity; pharmaceutical and electronics buyers demonstrate lowest elasticity due to qualification lock-in effects.
Supply Chain Analysis
REACH-REACH UK divergence and EPA residual monomer thresholds are fragmenting compliance pathways and forcing dual-track qualification investments. Supply concentrates in China, the United States, and Germany, with coastal Chinese provinces dominating derivative output for both domestic coatings expansion and export adhesive markets. Production draws from propylene feedstock anchored in Gulf Coast refining complexes and Northeast Asian naphtha crackers, with molybdenum-vanadium catalyst formulations representing a critical input bottleneck. Single-source vulnerability concentrates in controlled oxidation technology expertise held by a narrow technical cohort. Distribution runs through long-term offtake contracts to integrated downstream operations, with spot merchant liquidity thinning outside the Rhine-Neckar and Houston corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in acrylic acid hinges on catalyst yield improvements compressing per-unit energy intensity and premium-tier demand from pharmaceutical-grade fermentation-derived acid pilots absorbing regulatory preference under EU taxonomy criteria.
For Market Incumbents: Deepen backward integration into propylene supply through Gulf Coast refining corridor partnerships or Rhine-Neckar complex expansion, while investing in ppb-level analytical capabilities to defend against specialty ester formulators capturing REACH-qualification premiums. Arkema and Nippon Shokubai demonstrate how derivative formulation expertise can offset commodity acid margin pressure. For New Entrants and Emerging Players: Biocatalytic fermentation routes employing engineered bacteria offer a technology-first wedge into high-margin cosmetic and pharmaceutical applications where EU Green Deal bio-mandates harden renewable content thresholds. India's coatings expansion presents the most penetrable geography, with infrastructure investment outpacing domestic ester supply and BIS certification creating qualification barriers that favor patient capital with extended stability testing capabilities. For Investors and Strategic Acquirers: Asymmetric upside sits with controlled oxidation technology specialists and fermentation-derived acid pilots positioned for EU taxonomy preference escalation. Long-term viability favors assets with captive propylene supply and demonstrated catalyst engineering expertise rather than merchant acid traders facing specification-driven procurement consolidation. Watch for MEE wastewater discharge enforcement tightening in China's Yangtze River Delta chemical parks as an inflection indicator for regional capacity rationalization.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Propylene Supply | Gulf Coast refinery partnerships secure feedstock cost advantage against naphtha-cracker volatility. |
| Green Manufacturing Transition | Fermentation-derived acid pilots absorb EU taxonomy preference as fossil-derived building blocks face exclusion. |
| Capacity Expansion in India | Gujarat and Maharashtra industrial zones capture import substitution openings in construction chemical compounding. |
| Long-term Supply Agreement | Personal care manufacturers lock in high-purity glacial acid through multi-year offtake with ppb-level documentation. |
| Joint Venture for Catalyst Technology | Specialized oxidation reactor expertise concentrates among Osaka and Tokyo metropolitan area producers. |
Methodological Framework
Direct dialogue with plant managers at propylene oxidation complexes, procurement leads at downstream coatings and adhesive OEMs, distribution channel partners in the Rhine-Neckar and Gulf Coast corridors, and technical R&D directors specializing in molybdenum-vanadium catalyst formulations grounded this analysis. Secondary validation drew from customs and trade data, ACC and Cefic industry reports, SEC 10-K filings, and EPA emission compliance disclosures. Bottom-up capacity and utilization estimates triangulated against top-down demand segmentation across personal care, agriculture, construction, and automotive end uses.
Top-down macroeconomic drivers and bottom-up segment-level consumption patterns converged across the analysis window. The modeling framework disaggregated volume and value by product type, application, end user, and form dimensions, with additional stratification by regional production hub and certification grade tier. CAGRs were derived from trend extrapolation of historical consumption intensities adjusted for regulatory mandate phasing and substitution elasticity estimates. Forecast inputs incorporated propylene feedstock price linkage dynamics and REACH authorization timeline assumptions.
The model holds under stable propylene oxidation yield improvement trajectories and gradual EU Green Deal implementation; deviation in MEE enforcement intensity or sudden catalyst technology disruption would shift capacity utilization assumptions and derivative qualification timelines. Forecasts reflect documented base conditions with acknowledged sensitivity to regulatory divergence between jurisdictions. A model refresh is warranted upon material change in EPA residual monomer threshold revisions or BASF Ludwigshafen complex operational disruptions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Organic Chemicals
Dioctyl Maleate (DOM) Market
Organic Chemicals
Oryzenin Market
Organic Chemicals
Synthetic and Bio-Based Aniline Market
Organic Chemicals
North America Biphenyl Market
Organic Chemicals
Acrylonitrile Market
Organic Chemicals
Terephthalic Aldehyde Market
Organic Chemicals
Crotonic Acid Market
Organic Chemicals
Organocatalyst Market
Organic Chemicals
Europe Lactic Acid Market
Organic Chemicals
Cycloalkanes Market
Organic Chemicals
Asia-Pacific Synthetic Camphor Market
Organic Chemicals
Phenol Market
Organic Chemicals
Nonylphenol Market
Organic Chemicals
Gamma-Butyrolactone (GBL) Market
Organic Chemicals
Methyl Isobutyl Ketone (MIBK) Market
Organic Chemicals
Chlorocyclopentane Market