
 Chloroethylene Market | 2026-2036
Chloroethylene Market Size, Share, and Industry Trends Forecast 2026-2036
Chloroethylene Market Analytics
Aftermarket service revenue for chloroethylene processing equipment is reshaping margin distribution across the value chain. Westlake Corporation leverages its integrated vinyls platform to sustain feedstock cost advantages across North American production sites. The Dow Chemical Company anchors its position through chlor-alkali and ethylene dichloride assets that supply captive monomer requirements. Arkema differentiates via specialty copolymer grades targeting high-performance automotive and electrical applications.
Chloroethylene denotes a family of chlorinated ethylene compounds, principally vinyl chloride monomer with the molecular formula C₂H₃Cl, produced via thermal cracking of ethylene dichloride at temperatures exceeding 500°C and subsequently polymerized to form polyvinyl chloride resin. The primary industrial purpose centers on manufacturing rigid and flexible PVC products for construction infrastructure, automotive components, and electrical insulation systems. Polyvinyl chloride dominates product type volumes as the foundational resin grade consumed across building and consumer goods sectors, while copolymers capture expanding margin pools in specialty film and medical device applications where enhanced flexibility and chemical resistance command premium positioning. Construction leads application demand through piping, siding, and window profile fabrication, with electrical insulation representing the fastest-growing application segment driven by wire and cable jacketing requirements for renewable energy grid expansion.
EPA emissions standards govern vinyl chloride monomer air releases and workplace exposure limits at US production facilities, while REACH registration requirements in Europe mandate comprehensive toxicological dossiers for chloroethylene substance authorization. OSHA's vinyl chloride standard establishes strict permissible exposure limits that shape plant engineering controls and monitoring investments across American manufacturing operations. China's MEE implements national emission standards for chlorinated hydrocarbon production that influence capacity planning and technology upgrade timelines. Stakeholders must monitor regulatory divergence between jurisdictions as compliance cost asymmetries increasingly determine competitive positioning in chloroethylene trade flows.
Market Dynamics
Feedstock cost asymmetries between ethane-based North American producers and naphtha-based Asian facilities are compressing margin structures and forcing capacity reconfiguration decisions across integrated chloroethylene chains.
Growth Catalysts
- Renewable energy grid buildout:Wire and cable jacketing requirements for offshore wind and solar farm interconnections are accelerating vinyl chloride monomer consumption in electrical insulation grades across Germany, China, and the United States.
- REACH authorization timelines:European chemical safety dossier completion for chloroethylene substances is creating first-mover certification advantages for compliant producers serving medical device and automotive interior specifications.
- Ethylene dichloride cracking efficiency gains:Advanced oxychlorination catalyst systems are reducing energy intensity per ton of vinyl chloride monomer output at integrated petrochemical complexes on the US Gulf Coast.
Market Restraints
- Ethylene feedstock volatility:Crude oil and natural gas price divergence is amplifying cost unpredictability for naphtha-based chloroethylene producers in Northeast Asia versus ethane-advantaged competitors.
- Chinese capacity concentration:Over half of global vinyl chloride monomer fabrication capacity sits within Shandong and Jiangsu provinces, creating geographic supply risk exposure for downstream compounders.
- Biopolymer substitution pressure:Polylactic acid and bio-based polyethylene formulations are capturing niche flexible packaging applications previously served by plasticized PVC compounds.
Strategic Opportunities
- Medical-grade copolymer white space:Vinyl acetate copolymer formulations for blood bag and dialysis tubing applications face limited qualified supply sources outside of Arkema's French production base.
- India construction acceleration:National infrastructure pipeline investments in water distribution and sanitation are expanding PVC pipe procurement volumes ahead of domestic resin capacity additions.
- EPA emissions credit trading:Vinyl chloride monomer facilities achieving sub-threshold air release rates can monetize surplus allowances with struggling compliance-bound competitors under evolving Clean Air Act mechanisms.
Industry Challenges
- Process safety engineering scarcity:Specialized expertise in thermal cracking furnace design and pyrolysis gas handling commands premium compensation, constraining expansion project staffing.
- Legacy control system integration:Digital twin deployment for predictive maintenance requires bridging 1980s-era distributed control architectures with modern IoT sensor networks without production interruption.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chloroethylene Market |
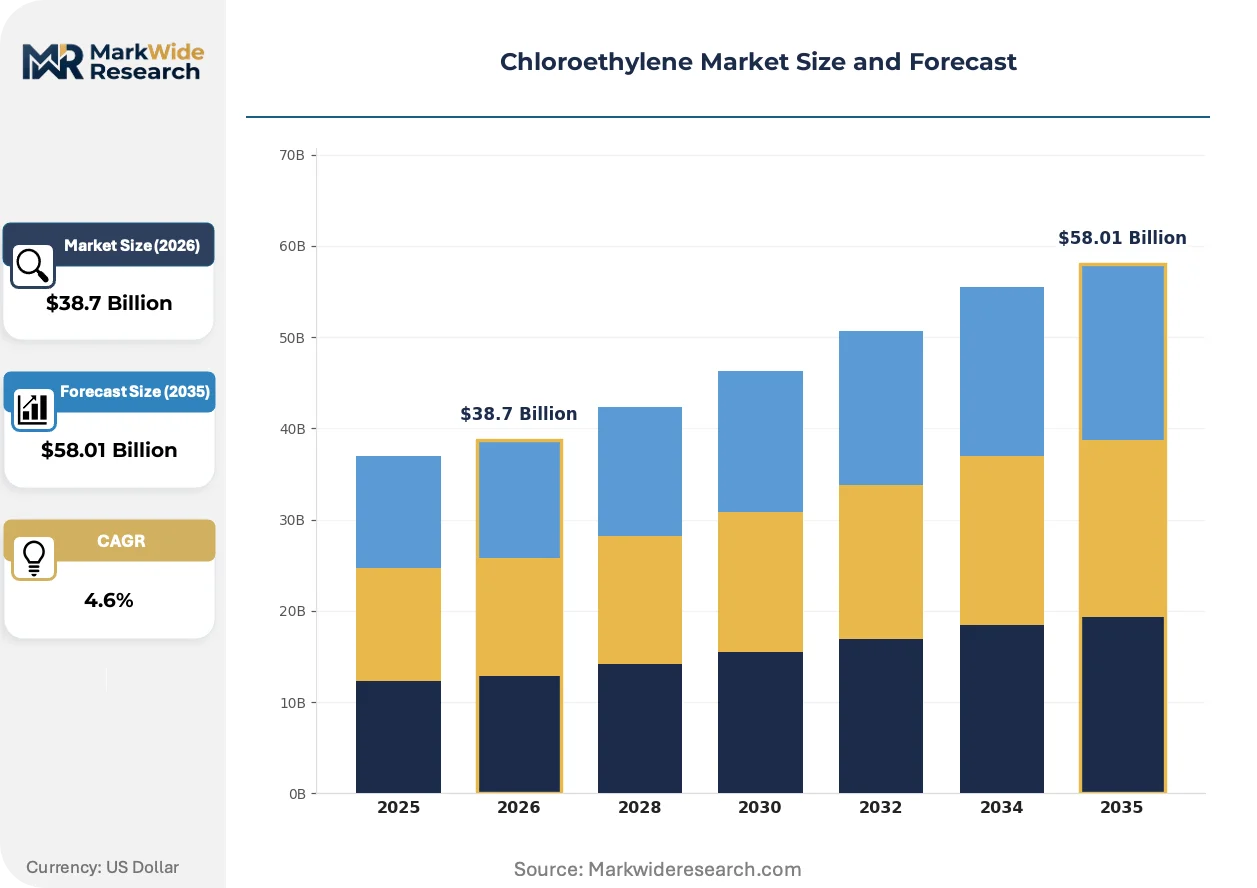
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $58.01 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyvinyl Chloride, Copolymers, Monomers, Others Application: Construction, Automotive, Electrical, Packaging End User: Manufacturers, Contractors, Retailers, Wholesalers Distribution Channel: Online Retail, Offline Retail, Direct Sales, Distributors |
| Companies Covered | Westlake Corporation, Tahrir Petrochemicals, Ineos Styrolution, Synthos, The Dow Chemical Company, Solvay, Arkema, PPG Industries, 3M Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chloroethylene Market Evolving Landscape
Process intensification and regulatory disclosure requirements are forcing simultaneous reinvention of production technology and supply chain transparency mechanisms across chloroethylene value chains.
Membrane-based oxygen separation is migrating from pilot demonstration to commercial scale at select oxychlorination units, replacing cryogenic air separation with polymer hollow-fiber modules that cut electricity consumption per ton of ethylene dichloride. European producers in the Antwerp-Rotterdam chemical cluster are piloting this shift to meet EU Green Deal carbon intensity benchmarks. The technology is compressing energy cost differentials between legacy and modernized facilities.
REACH SCIP database obligations now mandate granular disclosure of chloroethylene-containing articles throughout supply chains, forcing compounders to deploy blockchain-traceable batch coding systems. The regulation is reshaping procurement qualification protocols, with automotive OEMs demanding real-time substance-of-concern tracking from Tier 3 resin suppliers. German and French converters are consolidating supplier bases to reduce compliance verification burden.
Specification-driven buying is consolidating procurement authority at major construction distributors, displacing traditional spot-market purchasing by regional pipe fabricators. Large national building supply chains now negotiate direct vinyl compound formulations with specified additive packages, bypassing intermediate compounder relationships. This pattern is most visible in the United States, where Ferguson and HD Supply are capturing specification-setting power for commercial plumbing infrastructure.
Chloroethylene Market Segmentation
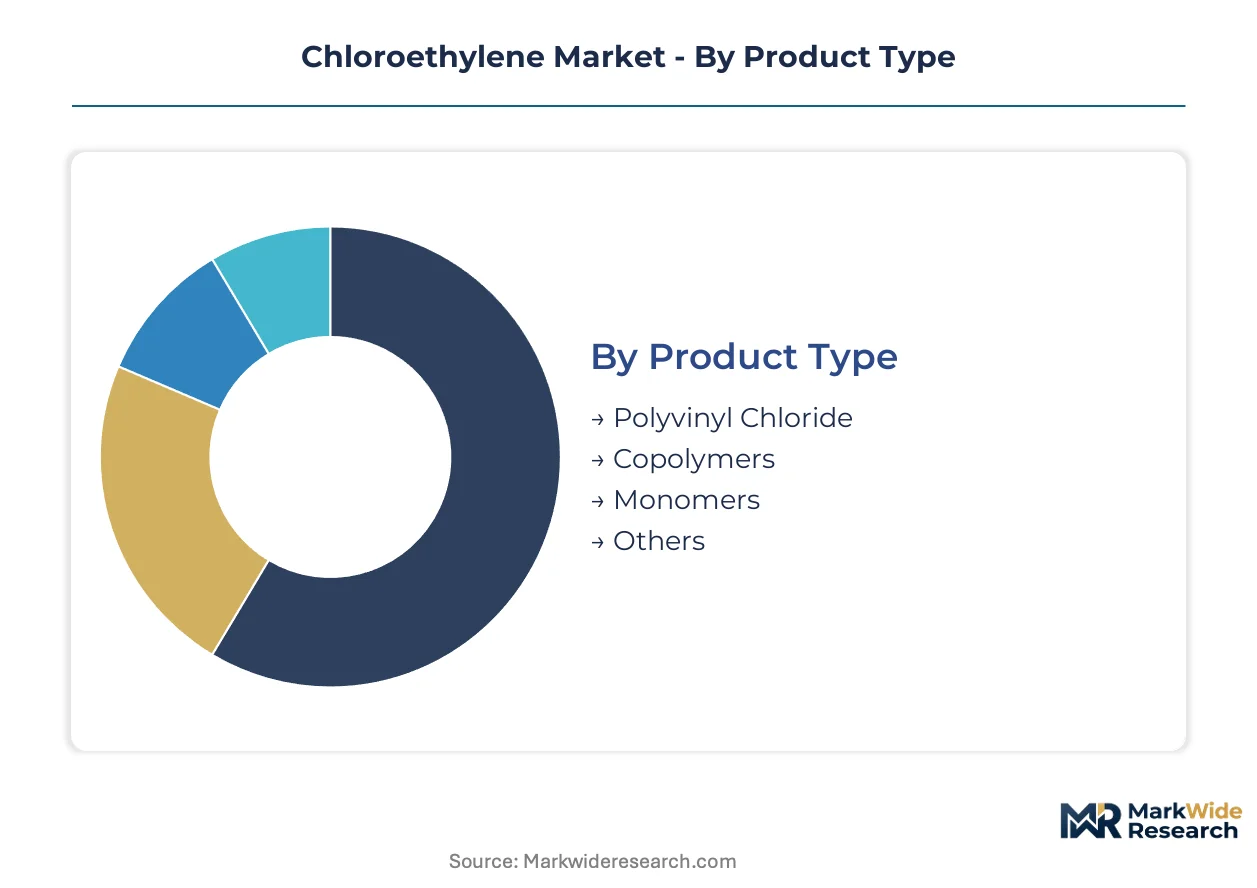
Chloroethylene market segmentation reveals distinct velocity profiles across product categories, with commodity resins cycling through inventory rapidly while specialty copolymers move through extended qualification timelines. Understanding these turnover differentials enables capacity planners to align production scheduling with downstream demand cadences and working capital requirements.
Product Type:
Cycle times vary dramatically across chloroethylene product categories, with bulk commodity grades turning inventory weekly while medical-grade copolymers sit in qualification queues for months.
- Polyvinyl Chloride:Rigid and flexible resin formulations dominate construction infrastructure consumption through pipe extrusion and profile fabrication. Demand concentrates in China's Shandong and Jiangsu manufacturing clusters where downstream vinyl fabrication capacity continues scaling, though REACH compliance costs are reshaping European procurement patterns toward certified supply sources.
- Copolymers:Vinyl acetate and specialty grafted formulations deliver enhanced flexibility and chemical resistance for medical device and automotive interior specifications. Arkema's French production base anchors qualified supply for blood bag and dialysis tubing applications, with REACH SCIP database obligations forcing compounders to deploy blockchain-traceable batch coding systems for regulatory transparency.
- Monomers:Vinyl chloride monomer serves as the foundational feedstock for integrated PVC production chains, with ethylene dichloride cracking efficiency gains reducing energy intensity at US Gulf Coast facilities.
- Others:Chlorinated polyethylene and specialty intermediates capture niche applications in adhesive and coating formulations.
Polyvinyl chloride anchors the volume base while copolymers gain share at the steepest rate.
Application:
Cost tier differentiation separates specification-driven procurement in electrical infrastructure from price-sensitive spot purchasing in commodity construction.
- Construction:Piping, siding, and window profile fabrication consume the majority of rigid PVC resin volumes across residential and commercial building markets. Procurement authority is consolidating at large national distributors like Ferguson and HD Supply in the United States, which now negotiate direct compound formulations with specified additive packages.
- Electrical:Wire and cable jacketing for renewable energy grid buildout represents the expanding margin pool, with offshore wind and solar farm interconnections accelerating vinyl chloride monomer consumption in insulation grades across Germany, China, and the United States.
- Automotive:Interior trim and under-hood applications demand heat-stabilized formulations meeting OEM volatile organic compound restrictions.
- Packaging:Flexible film and blister pack applications face substitution pressure from polylactic acid and bio-based polyethylene formulations in sustainability-sensitive segments.
Construction maintains the installed demand base while electrical applications climb the fastest.
End User:
Customer type determines order pattern predictability, with manufacturers running continuous consumption schedules against contractors' project-driven lumpiness.
- Manufacturers:Integrated vinyl compounders and downstream fabricators operate on long-term supply agreements with indexed ethylene pricing, requiring just-in-time resin delivery to minimize working capital.
- Contractors:Commercial plumbing and electrical installation firms purchase through distributor networks with specification-driven buying consolidating at national building supply chains.
- Retailers:Home improvement and hardware channels serve the repair and renovation segment with packaged PVC products.
- Wholesalers:Regional distributors maintain inventory positions for spot market access by smaller fabricators.
Manufacturers anchor the volume base while contractors expand most quickly as infrastructure investment accelerates.
Distribution Channel:
Channel selection reflects buyer scale and technical sophistication, with large compounders bypassing intermediaries while smaller players rely on distributor inventory buffers.
- Direct Sales:Major PVC resin producers like Westlake Corporation and The Dow Chemical Company maintain dedicated account teams for integrated vinyl compounders, offering formulation technical support and logistics optimization.
- Distributors:National and regional chemical distributors provide inventory financing and smaller lot sizes for mid-tier compounders lacking railcar receiving infrastructure.
- Online Retail:Digital platforms are capturing specification-grade compound sales for qualified buyers with established credit relationships.
- Offline Retail:Traditional branch networks serve contractor pickup demand for packaged PVC products and fittings.
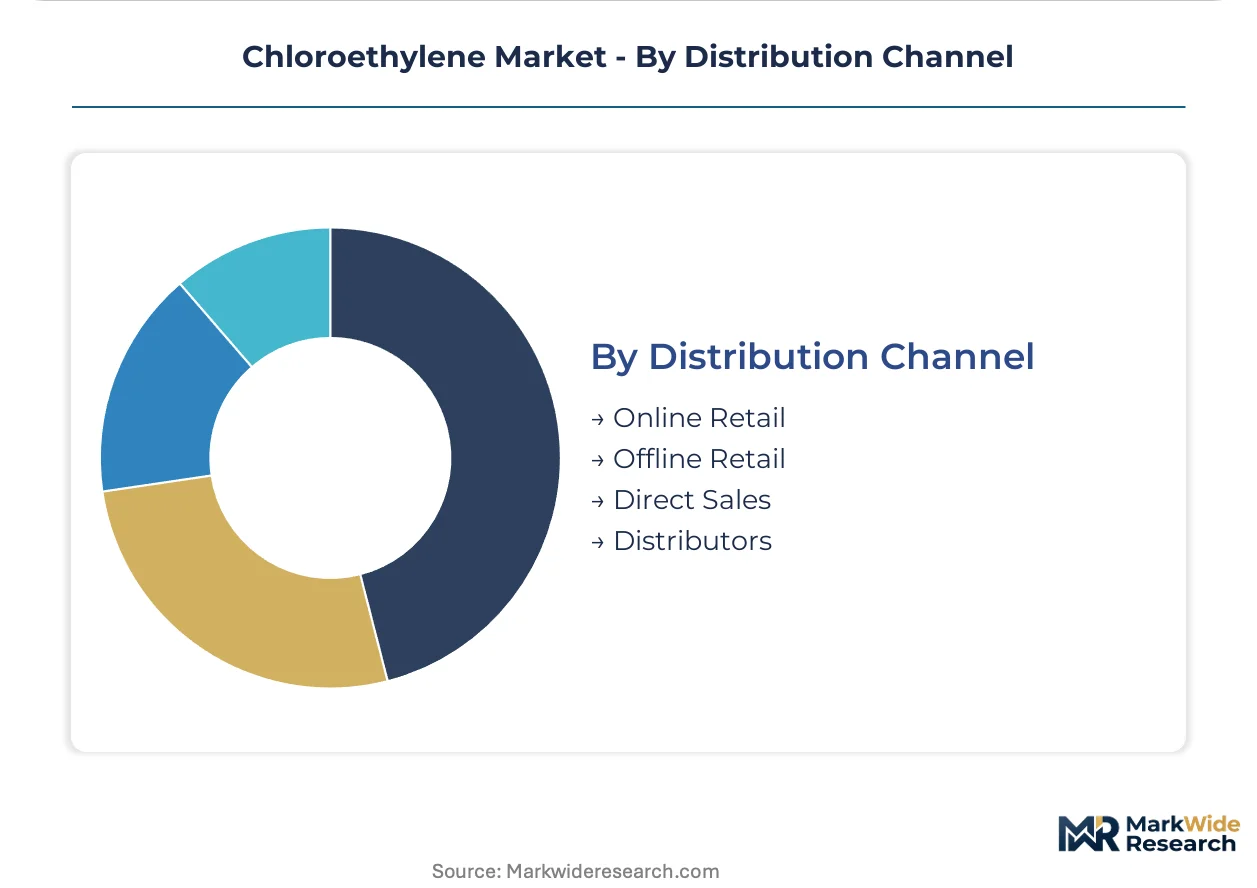
Direct sales anchors the volume base while online retail gains share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies. China deploys chloroethylene predominantly for construction-grade PVC fabrication, while Germany and the United States prioritize electrical insulation compounds for industrial infrastructure. This demand-mix differential shapes regulatory priorities and investment allocation across production clusters.
United States
Electrical wire and cable jacketing for renewable energy interconnections drives vinyl chloride monomer consumption across Texas and Louisiana production corridors. EPA emissions standards under the Clean Air Act enforce strict vinyl chloride air release thresholds at Gulf Coast facilities. Houston and Lake Charles host integrated chlor-alkali complexes where oxychlorination catalyst upgrades are reducing energy intensity per ton of output.
Germany
Offshore wind farm cable specifications and automotive interior applications command premium copolymer grades from Rhineland chemical clusters. REACH authorization timelines and SCIP database obligations mandate granular supply chain disclosure for chloroethylene-containing articles. The Antwerp-Rotterdam chemical corridor is piloting membrane-based oxygen separation to meet EU Green Deal carbon intensity benchmarks.
China
Residential and commercial building markets absorb rigid PVC resin volumes for piping and cladding fabrication across Shandong and Jiangsu provinces. MEE national emission standards for chlorinated hydrocarbon production influence capacity planning and technology upgrade timelines. Qingdao and Nantong manufacturing clusters concentrate over half of global vinyl chloride monomer fabrication capacity.
India
National infrastructure pipeline investments in water distribution and sanitation systems are expanding PVC pipe procurement ahead of domestic resin capacity additions. BIS certification requirements and DGFT import regulations shape compound formulation standards for construction applications. Gujarat and Maharashtra industrial zones are attracting downstream vinyl fabrication investments to serve western and southern building markets.
Saudi Arabia
Desalination plant infrastructure and petrochemical complex construction generate specialized chloroethylene demand for corrosion-resistant piping systems. The country's national chemical regulator enforces product safety standards aligned with Gulf Cooperation Council technical regulations. Jubail Industrial City hosts integrated ethylene dichloride production feeding regional PVC compound manufacturing.
Chloroethylene Market Competitive Landscape
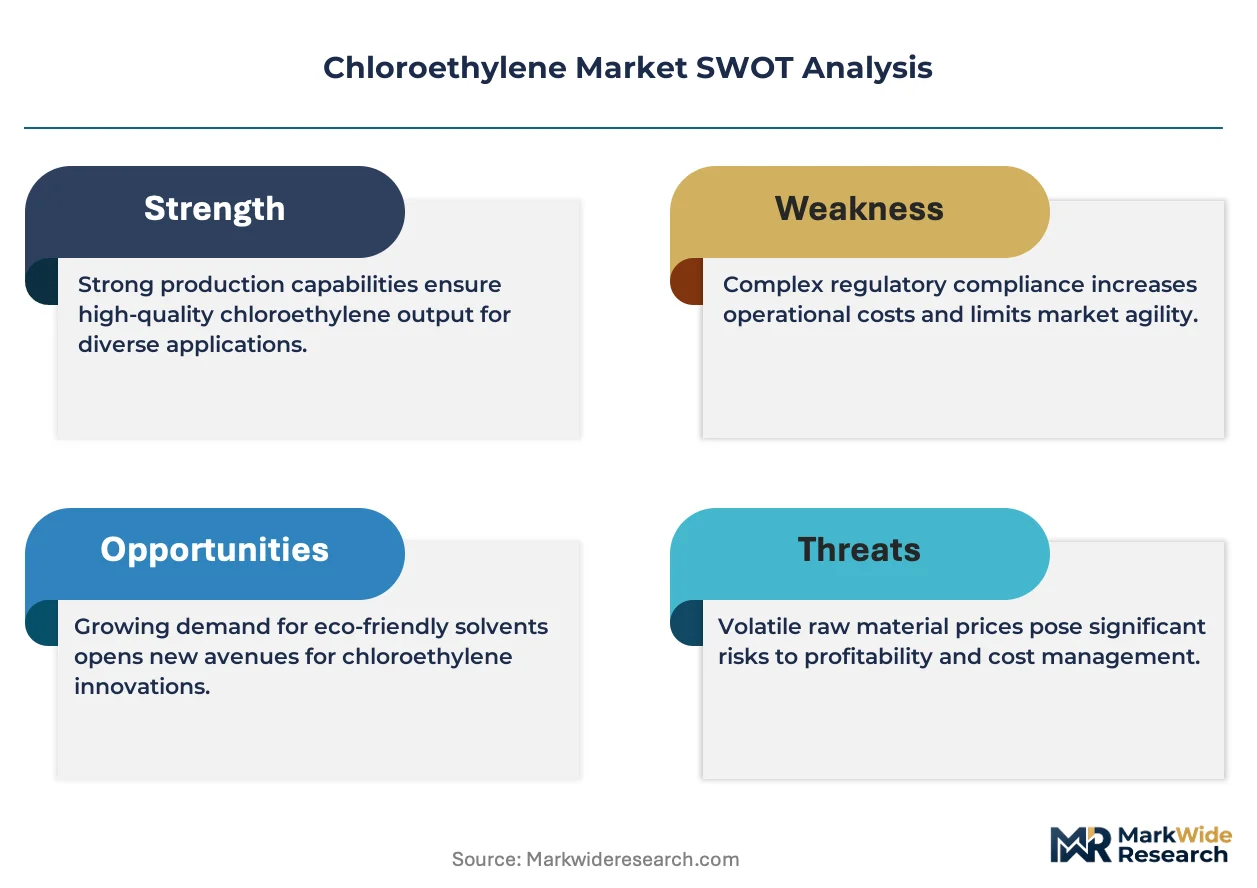
Capability concentration sits with one tier; scale advantage sits with another. The chloroethylene market structures around three distinct player categories: integrated petrochemical majors with captive ethylene supply, specialty copolymer specialists serving qualification-intensive medical and automotive segments, and regional compounders purchasing merchant monomer for construction-grade resin production. Strategic differentiation hinges on backward integration into ethylene dichloride cracking and forward control over formulation technical service.
Within the integrated major tier, Westlake Corporation and The Dow Chemical Company exemplify scale-driven positioning through Gulf Coast production assets and dedicated account structures for large compounders. Arkema occupies a specialist position in the copolymer segment, anchoring qualified supply for medical device applications where REACH compliance and batch traceability command premium positioning.
| Leading Market Players |
|---|
| Westlake Corporation |
| Tahrir Petrochemicals |
| Ineos Styrolution |
| Synthos |
| The Dow Chemical Company |
| Solvay |
| Arkema |
| PPG Industries |
| 3M Company |
| Others |
Value Network & Pricing Analysis
The Houston-Rotterdam freight corridor carries vinyl chloride monomer and ethylene dichloride feedstock across Atlantic routes, with bunker fuel cost swings amplifying margin pressure for European compounders sourcing US Gulf Coast material while simultaneously reinforcing price premiums for REACH-certified medical-grade copolymers against commodity construction resin.
Pricing Analysis
Long-term offtake contracts with ethylene price indexing dominate procurement between integrated producers and large compounders, while spot purchases serve smaller fabricators lacking railcar infrastructure. Price differentiation separates REACH-authorized specialty grades from standard construction resins, with certification tier and volume scale as primary levers. Cost compression in flexible PVC compounds is intensifying because biopolymer alternatives capture sustainability-sensitive packaging applications. Contractors through national distributors like Ferguson exhibit highest price sensitivity, while medical device manufacturers prioritize qualified supply security over unit cost.
Supply Chain Analysis
Export control regimes limiting dual-use chemical processing technology transfers constrain oxychlorination catalyst system flows to certain jurisdictions, reshaping technology access asymmetries. Supply concentrates in China, the United States, and Germany, with Shandong province and the US Gulf Coast anchoring integrated production. Raw material dependencies center on ethylene feedstock, chlorine from chlor-alkali operations, and specialized cracking furnace components. Single-source vulnerability runs through membrane-based oxygen separation technology pilots in the Antwerp-Rotterdam cluster. Distribution runs through direct railcar delivery for major compounders and regional chemical distributors for mid-tier buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Chloroethylene demand sits in early-cycle expansion as renewable energy grid buildout accelerates vinyl chloride monomer consumption for wire and cable jacketing across offshore wind and solar interconnection projects.
For Market Incumbents: Entrench feedstock cost advantages through oxychlorination catalyst upgrades at Gulf Coast facilities, while securing REACH authorization timelines ahead of competitors to capture medical-grade copolymer premiums. Biopolymer substitution pressure in flexible packaging demands defensive formulation innovation in plasticized compounds. For New Entrants and Emerging Players: Pursue medical-grade vinyl acetate copolymer white space where qualified supply scarcity outside Arkema's French base creates penetration opportunity. India's national infrastructure pipeline for water distribution represents the most penetrable geography, with BIS certification as the critical go-to-market threshold. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified chemical conglomerates seeking portfolio simplification, particularly European assets with stranded REACH compliance investments. Long-term viability hinges on backward integration into ethylene dichloride cracking and captive chlorine supply. Watch EPA emissions credit trading mechanism development as inflection signal for US facility valuation premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration | Captive ethylene dichloride cracking secures margin control against feedstock volatility at US Gulf Coast complexes. |
| REACH Authorization Investment | First-mover toxicological dossier completion locks in medical device and automotive interior specification access. |
| Membrane Oxygen Separation Deployment | Polymer hollow-fiber modules cut electricity consumption to meet EU Green Deal carbon intensity benchmarks. |
| Long-term Supply Agreement | Indexed ethylene pricing contracts with national distributors reduce working capital for integrated compounders. |
| Joint Venture | India downstream fabrication partnerships with Gujarat industrial zone developers capture infrastructure pipeline demand. |
Research Methodology
The analysis maps vinyl chloride monomer production, polyvinyl chloride resin fabrication, and specialty copolymer compounding, each validated through plant managers at integrated chlor-alkali complexes, procurement leads at downstream pipe extruders, distribution channel partners, and technical R&D directors. Primary interview insights triangulate against customs and trade data, ACC and Cefic industry reports, SEC 10-K filings, and MEE emission standard disclosures. Bottom-up capacity utilization estimates and top-down construction spending correlations converge to validate volume assumptions.
Fixed assumptions include sustained ethane-naphtha feedstock cost differentials, phased REACH authorization timelines, and renewable energy interconnection buildout trajectories across the analysis window. Segmentation modeling incorporates product grade tier, end-use industry, regional production hub, and regulatory compliance cluster. CAGRs derive from ethylene demand elasticity coefficients and PVC substitution rates in construction applications. Forecast inputs include oxychlorination energy intensity curves and membrane separation technology adoption slopes.
Macroeconomic conditions sit as an overlay; deviation in construction spending cycles, crude oil-natural gas price spreads, or carbon border adjustment implementation would shift the trajectory. Material shifts in EPA emissions credit trading liquidity, Chinese capacity rationalization policy, or biopolymer cost-parity achievement would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Organic Chemicals
Dioxolane Market
Organic Chemicals
Diethyl Ketone Market
Organic Chemicals
Organic Rheological Modifiers Market
Organic Chemicals
Organic Hydrosols Market
Organic Chemicals
Organic Polysulfide Market
Organic Chemicals
Chlorinated Methane Market
Organic Chemicals
Crotonic Acid Market
Organic Chemicals
N-Pentane Market
Organic Chemicals
North America Phenol Market
Organic Chemicals
Organic Chemicals Market
Organic Chemicals
Long-Chain Dicarboxylic Acid Market
Organic Chemicals
N-Hexyl Chloride Market
Organic Chemicals
Mercaptopropionic Acid Market
Organic Chemicals
Azelaic Acid Market
Organic Chemicals
Global Ketones Market
Organic Chemicals
Dioctyl Phthalate Market