
 Pentachlorophenol Market | 2026-2036
Pentachlorophenol Market Size, Share, and Industry Trends Forecast 2026-2036
Pentachlorophenol Market Analysis
Biocide substitution technology is tilting wood treatment formulations toward alternative chemistries, forcing incumbents to defend legacy positions. Lanxess AG anchors its portfolio through backward integration into chlorinated phenol intermediates, sustaining cost advantages in industrial-grade supply. Merck KGaA differentiates via research-grade purity standards, occupying the analytical and reference-material niche. UPL Limited leverages its agrochemical distribution network to compete in pesticide applications across emerging markets.
Pentachlorophenol (PCP, C6Cl5OH) is a chlorinated aromatic compound manufactured by alkaline hydrolysis of hexachlorobenzene or direct chlorination of phenol, historically employed as a broad-spectrum biocide, fungicide, and wood preservative. Its primary industrial purpose centers on protecting timber and cellulose materials from fungal decay and insect infestation, though its persistence and toxicity have triggered regulatory restrictions worldwide. The application dimension shows wood preservation retaining volume leadership while pesticide formulations face accelerated substitution pressure from neonicotinoid and pyrethroid alternatives. Among end-user segments, construction absorbs the largest share of industrial-grade material, whereas the textile industry's leather treatment niche commands premium pricing for specialized biocide formulations.
The EPA regulates pentachlorophenol under FIFRA re-registration review and TSCA chemical substance restrictions, limiting new product approvals and mandating exposure controls for applicators. ECHA classifies PCP as a substance of very high concern under REACH, enforcing authorization requirements that constrain European manufacturing and import volumes. China's MEE enforces GB standards on chlorophenol emissions and residue limits, shaping production economics for domestic suppliers. Stakeholders must monitor regulatory divergence between jurisdictions to anticipate where formulation flexibility will contract or where grandfathered uses will persist.
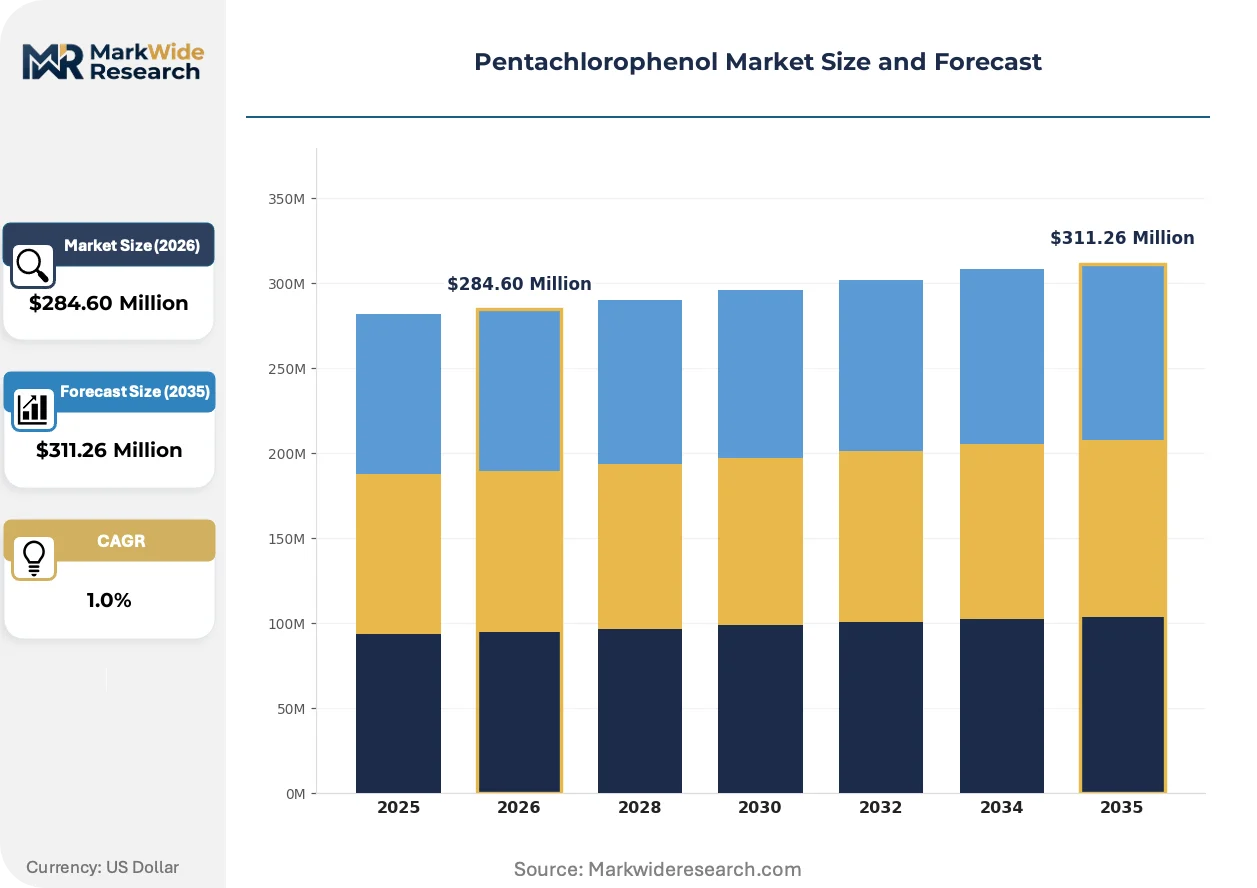
Market Dynamics
Biocide substitution technology is compressing formulation economics for legacy chlorinated phenol producers, forcing incumbents to absorb margin erosion while defending grandfathered industrial applications against neonicotinoid and pyrethroid alternatives.
Growth Catalysts
- Timber infrastructure replacement cycles:Aging railway ties and utility poles in North America and Europe require periodic retreatment, sustaining baseline demand for industrial-grade wood preservatives despite regulatory headwinds.
- REACH authorization grandfathering:Existing authorized uses in EU member states permit continued industrial applications while blocking new entrants, protecting incumbent supply positions.
- Agricultural storage biocide persistence:Grain silo and warehouse treatments in India and China retain PCP formulations where pyrethroid resistance has emerged in target pest populations.
Market Restraints
- Hexachlorobenzene feedstock constraints:Chlorinated benzene precursor availability tightens as environmental authorities in Germany and Japan restrict legacy chlor-alkali coproduction.
- ECHA authorization thresholds:REACH substance-of-very-high-conern classification imposes use-specific exposure limits that compress formulation flexibility for European applicators.
- Copper azole substitution economics:Alternative wood preservatives achieve cost parity in above-ground residential construction, displacing PCP in the largest North American end-use segment.
Strategic Opportunities
- Marine piling specialty formulations:Saltwater immersion applications for dock and harbor infrastructure tolerate higher biocide loadings, supporting premium pricing for creosote-PCP blends.
- India agrochemical distribution networks:Post-harvest crop protection in grain-producing states retains PCP-based fumigant formulations where regulatory phase-out timelines lag OECD schedules.
- Analytical reference material purity standards:Environmental testing laboratories require certified PCP standards for dioxin and furan contamination assays, creating a defensible niche insulated from volume substitution.
Industry Challenges
- Applicator certification attrition:EPA-mandated handler training programs face declining enrollment as younger workers exit hazardous chemical applicator careers, constraining field deployment capacity.
- Legacy equipment decontamination liabilities:Former wood treatment facilities in the US and Canada carry soil and groundwater remediation obligations that cloud asset transfer valuations and deter site redevelopment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pentachlorophenol Market |
| Market Size in 2026 | $284.60 Million |
| Market Size in 2035 | $311.26 Million |
| CAGR (2026 – 2036) | 1.0% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Industrial Grade, Agricultural Grade, Commercial Grade, Research Grade Application: Pesticides, Wood Preservation, Disinfectants, Leather Treatment End User: Agriculture, Construction, Healthcare, Textile Industry Distribution Channel: Online Sales, Direct Sales, Distributors, Retail |
| Companies Covered | Cabot Corporation, Lanxess AG, Merck KGaA, UPL Limited, Dow Inc., BASF SE, Arkema Group, Occidental Petroleum Corporation, Sigma-Aldrich Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pentachlorophenol Market Emerging Trajectories
Digital monitoring systems are penetrating industrial biocide application workflows, creating data streams that reshape how treatment efficacy is verified and how regulatory compliance is documented across dispersed timber processing facilities.
Microencapsulation technology for controlled-release biocide delivery is virtualizing traditional dip-tank and pressure-treatment processes, enabling timber processors to reduce chemical loading while maintaining fungal decay protection. Sawmills in the Pacific Northwest are piloting these systems to preempt EPA exposure violation penalties. The technology is virtualizing capital-intensive treatment infrastructure into modular, mobile application units that bypass fixed-plant regulatory jurisdiction.
EPA FIFRA re-registration review timelines are compressing product maintenance windows, forcing registrants to front-load toxicology study costs earlier in the commercial lifecycle. Industrial-grade formulation holders face accelerated data submission deadlines compared to residential-use products. Wood treatment chemical suppliers with US manufacturing footprints are consolidating regulatory affairs functions to manage simultaneous state-level notification requirements.
Consolidation among North American railroad operators is concentrating procurement authority into fewer buyers with standardized material specifications. Class I railways now mandate third-party certified treatment records for all cross-tie purchases, displacing informal supplier relationships. This concentration is most visible in the southern yellow pine belt, where two buyers now control tie specifications for the majority of new track installations.
Pentachlorophenol Market Segmentation
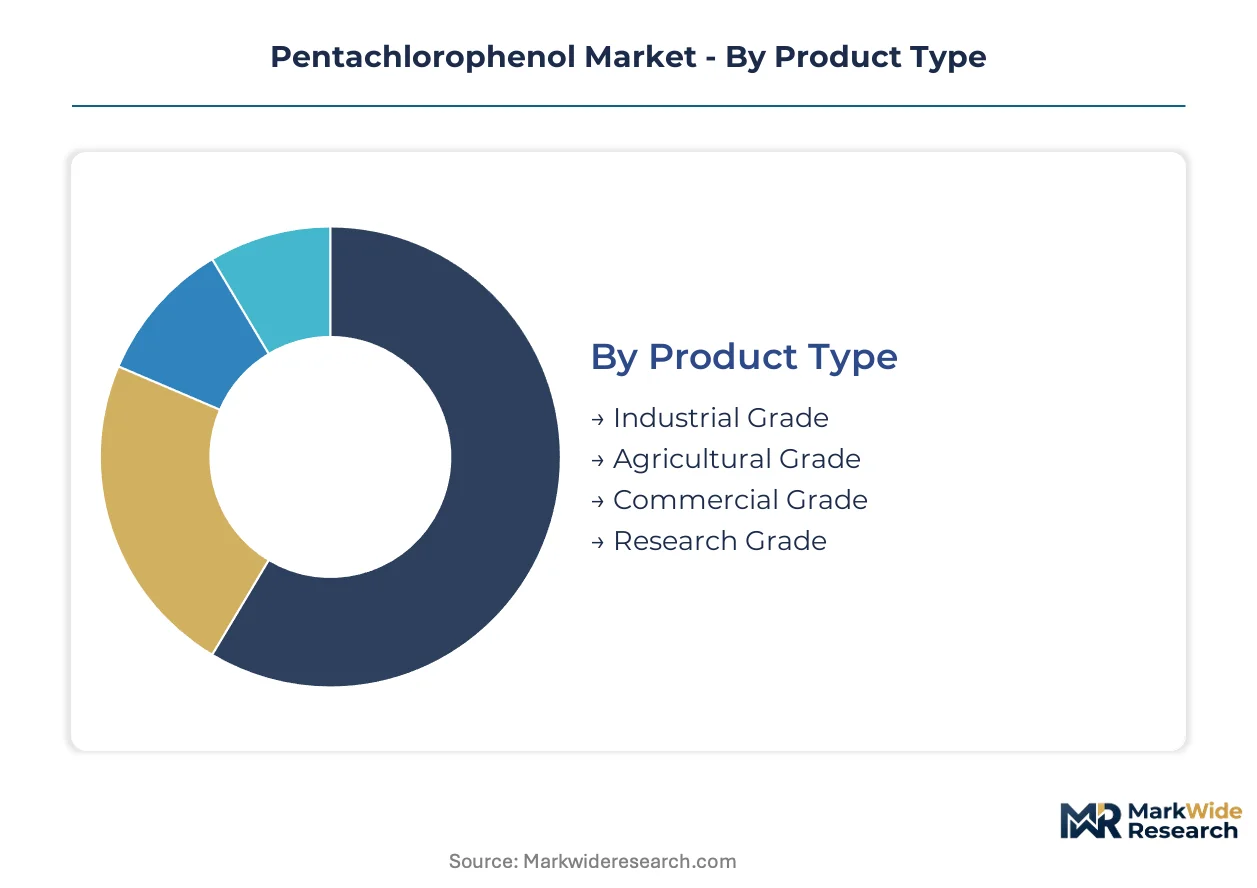
Pentachlorophenol demand fragments across purity specifications and regulatory jurisdictions, with industrial-grade formulations commanding volume leadership while research-grade segments extract premium pricing from analytical laboratories. The market's segmentation logic reflects divergent compliance burdens between legacy biocide applications and emerging reference-material niches.
Product Type:
Cost tier differentiation separates commodity chlorinated phenol supply from certified analytical standards, with purity thresholds determining regulatory authorization pathways and end-use eligibility.
- Industrial Grade:Technical-grade formulations containing 85-90% PCP with permissible dioxin and furan contamination levels, supplied in bulk to wood treatment facilities. Railway tie and utility pole retreatment cycles in the United States and Canada sustain procurement volumes despite EPA handler certification attrition.
- Agricultural Grade:Formulations meeting FAO/WHO residue specifications for grain storage and warehouse fumigation, with controlled impurity profiles for food-adjacent applications. Post-harvest crop protection in India's grain-producing states retains this tier where pyrethroid resistance has emerged in target pest populations.
- Commercial Grade:Mid-purity intermediates for leather treatment and textile biocide compounding.
- Research Grade:Certified reference materials with documented traceability for environmental contamination assays.
Industrial Grade holds installed capacity. Research Grade is rotating up the share rankings.
Application:
Application dimension reveals wood preservation defending grandfathered positions against accelerated substitution in pesticide formulations, with each use case carrying distinct regulatory maintenance costs.
- Wood Preservation:Pressure-treatment and dip-tank processes for timber, railway ties, and marine pilings. Class I railroad consolidation in the southern United States has concentrated procurement authority, with third-party certified treatment records now mandatory for cross-tie purchases.
- Pesticides:Broad-spectrum biocide formulations for agricultural storage and vector control. Neonicotinoid and pyrethroid alternatives are displacing PCP in OECD jurisdictions, though grain silo applications in China persist under MEE emission standards with extended phase-out timelines.
- Disinfectants:Hospital and industrial sanitation formulations with restricted authorization under REACH substance-of-very-high-concern classification.
- Leather Treatment:Fungicide applications in tanning processes, concentrated in South Asian export-oriented tanneries.
Wood Preservation retains formulation volume leadership. Pesticides is climbing the fastest as substitution pressure intensifies in regulated markets.
End User:
Customer type segmentation tracks divergent procurement sophistication, with construction buyers consolidating specifications while agricultural channels fragment across informal distributor networks.
- Construction:Timber processors, railroad operators, and marine infrastructure contractors absorbing industrial-grade material. Copper azole substitution has achieved cost parity in above-ground residential construction, compressing PCP's addressable market to saltwater immersion and heavy-duty industrial applications.
- Agriculture:Grain elevator operators and warehouse facilities in India and China. UPL Limited's distribution network competes for procurement contracts in states with lagging regulatory phase-out schedules.
- Healthcare:Hospital systems and medical device sterilization facilities with stringent handler training requirements.
- Textile Industry:Leather tanneries and textile finishing plants requiring specialized biocide formulations.
Construction dominates volume absorption. Agriculture is gaining share fastest as post-harvest protection demand persists in emerging markets.
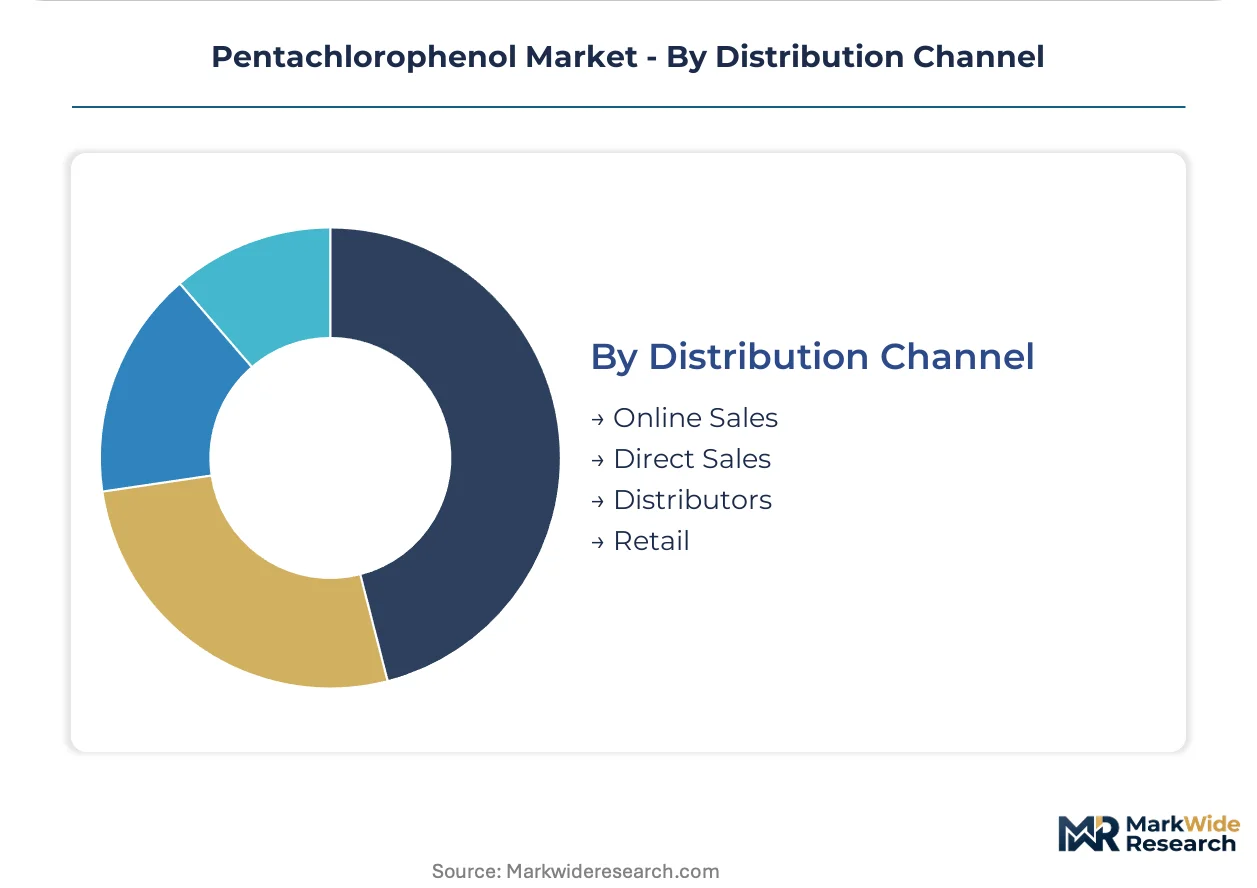
Distribution Channel:
Supply concentration patterns vary by channel, with direct sales consolidating around railroad procurement while distributor networks fragment across agricultural geographies.
- Direct Sales:Long-term supply agreements between chlorinated phenol manufacturers and Class I railroads, timber processors, and marine contractors. Lanxess AG leverages backward integration into chlorinated phenol intermediates to sustain cost advantages in direct industrial supply.
- Distributors:Regional agrochemical networks in India and China with field technical support capabilities. These channels retain PCP-based formulations where applicator certification infrastructure remains underdeveloped.
- Online Sales:Research-grade and small-volume industrial orders with documented chain-of-custody requirements.
- Retail:Limited consumer-accessible formulations in jurisdictions with minimal handler training mandates.
Direct Sales commands the premium tier. Distributors is expanding most quickly as agricultural coverage deepens in South and Southeast Asia.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese manufacturers export industrial-grade pentachlorophenol to India and Southeast Asian agricultural markets, sustaining volume flows despite tightening environmental controls in OECD jurisdictions.
United States
Railway tie retreatment cycles and utility pole replacement programs absorb the bulk of domestic industrial-grade consumption. EPA FIFRA re-registration reviews compress product maintenance windows, forcing registrants to front-load toxicology study costs. Southern yellow pine belt sawmills in Georgia and Alabama concentrate procurement for Class I railroad specifications.
China
Post-harvest grain protection and warehouse fumigation sustain agricultural-grade demand where pyrethroid resistance has emerged in target pest populations. MEE enforces GB standards on chlorophenol emissions and residue limits, shaping production economics for domestic suppliers. Yangtze River Delta chemical clusters near Shanghai maintain chlor-alkali coproduction capacity for hexachlorobenzene feedstock.
Germany
REACH substance-of-very-high-concern classification constrains formulation flexibility for European applicators while grandfathering existing authorized uses. ECHA authorization thresholds protect incumbent supply positions against new entrants. Industrial biocide compounding in North Rhine-Westphalia serves residual wood treatment demand for heavy-duty infrastructure.
India
Grain silo and warehouse treatments in Punjab and Haryana retain PCP-based formulations where regulatory phase-out timelines lag OECD schedules. FSSAI residue specifications shape agricultural-grade import requirements. UPL Limited's distribution network competes for procurement contracts across states with underdeveloped applicator certification infrastructure.
Canada
Marine piling specialty formulations for saltwater immersion applications support premium pricing for creosote-PCP blends in dock and harbor infrastructure. Health Canada PMRA maintains parallel re-registration timelines with EPA, compressing regulatory maintenance windows. British Columbia timber processors face legacy equipment decontamination liabilities at former treatment facilities.
Pentachlorophenol Market Vendor Landscape
Channel-controlling players compete with product-specialist players across fragmented supply tiers. The vendor base separates into backward-integrated chlorinated phenol manufacturers, research-grade purity specialists, and agrochemical distribution networks. Three strategic archetypes dominate: industrial-grade volume suppliers defending grandfathered applications, analytical-standard purity providers occupying defensible niches, and emerging-market distributors leveraging field technical capabilities. Consolidation among North American railroad operators concentrates procurement authority, while M&A activity targets regulatory affairs functions to manage simultaneous state-level notification requirements.
Within the backward-integrated tier, Lanxess AG anchors industrial-grade supply through captive chlorinated phenol intermediate production. Merck KGaA occupies the research-grade purity segment, serving environmental testing laboratories requiring certified reference materials. UPL Limited exemplifies the emerging-market distribution archetype, competing across South and Southeast Asian agricultural channels where regulatory phase-out timelines remain extended.
| Leading Market Players |
|---|
| Cabot Corporation |
| Lanxess AG |
| Merck KGaA |
| UPL Limited |
| Dow Inc. |
| BASF SE |
| Arkema Group |
| Occidental Petroleum Corporation |
| Sigma-Aldrich Corporation |
| Others |
Supply Flow & Price Mechanics
Underutilized chlor-alkali capacity in China's Yangtze River Delta compresses hexachlorobenzene feedstock costs, forcing European suppliers to absorb margin erosion or exit industrial-grade formulation entirely. This utilization asymmetry between Asian and OECD production clusters directly shapes pricing power across purity tiers and regulatory jurisdictions.
Pricing Analysis
Legacy formulation pricing diverges sharply from next-generation microencapsulated biocide delivery systems, with the technology-generation gap widening as EPA handler certification costs escalate. Three-tier pricing structure across research-grade certification, industrial-grade bulk supply, and agricultural-grade residue-controlled formulations dominates transaction structures. Price differentiation hinges on REACH authorization documentation and volume scale, with railroad procurement consortiums extracting steepest discounts through multi-year offtake agreements. Pricing pressure stems from copper azole substitution achieving cost parity in above-ground residential construction, compressing margins in the largest North American end-use segment. Agricultural distributors in India exhibit highest price sensitivity due to fragmented procurement authority, while analytical laboratories purchasing certified reference materials demonstrate lowest sensitivity due to regulatory compliance mandates.
Supply Chain Analysis
Contract manufacturing concentration among Yangtze River Delta chemical clusters and North Rhine-Westphalia industrial biocide compounders anchors global formulation capacity. Geographic supply concentrates in China, Germany, and India, with Chinese manufacturers exporting industrial-grade material to Southeast Asian agricultural markets. Raw material dependencies center on hexachlorobenzene feedstock, chlor-alkali coproduction capacity, and creosote blending stocks for marine specialty formulations. Supply chain risk rests on single-source vulnerability for REACH-authorized European supply, where ECHA substance-of-very-high-concern classification blocks new manufacturing entrants. Distribution runs through direct sales channels for railroad and marine infrastructure procurement, while agrochemical distributor networks fragment across Indian grain-producing states.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service-attach opportunities in applicator certification training and third-party treatment record verification are expanding faster than commodity formulation sales, creating recurring revenue layers insulated from biocide substitution pressure.
For Market Incumbents: Entrench backward integration into chlorinated phenol intermediates to defend cost position against pyrethroid and neonicotinoid substitution threats. Prioritize certification investment in REACH authorization maintenance to sustain grandfathered European supply positions. Consolidate regulatory affairs functions to manage simultaneous EPA state-level notification requirements and compress compliance overhead per formulation. For New Entrants and Emerging Players: Build out analytical reference material supply capabilities targeting environmental testing laboratories requiring certified PCP standards for dioxin and furan contamination assays. India's grain silo fumigation segment offers most penetrable white-space, with regulatory phase-out timelines lagging OECD schedules by several years. Pursue go-to-market partnerships with established agrochemical distributors possessing field technical support infrastructure across Punjab and Haryana. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across research-grade purification equipment as modular chromatography systems displace legacy batch processing infrastructure. Long-term viability favors analytical-standard purity providers occupying defensible niches insulated from volume substitution, with 5-10 year windows contracting for industrial-grade formulation holders. Target acquisition archetype: research-grade specialists with documented traceability protocols and existing EPA/FIFRA registration maintenance capabilities. Monitor ECHA authorization renewal timelines as inflection indicator for European manufacturing asset valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Chlorinated Phenol Intermediates | Lanxess AG sustains cost advantages in industrial-grade supply through captive hexachlorobenzene production. |
| Microencapsulation Technology Deployment | Pacific Northwest sawmills pilot controlled-release systems to preempt EPA exposure violation penalties. |
| REACH Authorization Maintenance Investment | ECHA substance-of-very-high-concern classification protects incumbent supply positions against new European entrants. |
| Agrochemical Distribution Network Expansion | UPL Limited leverages field technical capabilities across Indian states with underdeveloped applicator certification infrastructure. |
| Analytical Reference Material Certification | Merck KGaA serves environmental testing laboratories requiring documented traceability for contamination assays. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of regulatory filings, customs trade data, and industry association reports to validate pentachlorophenol demand trajectories across purity tiers. Primary interviews encompassed plant managers at chlor-alkali production facilities, procurement leads at Class I railroad operators, distribution channel partners in Indian agrochemical networks, and technical R&D directors at wood treatment chemical suppliers. Secondary sources included EPA FIFRA re-registration dockets, ECHA authorization databases, China MEE emission standard disclosures, SEC 10-K filings from backward-integrated chemical manufacturers, and ACC/Cefic chlorinated phenol market reports. Bottom-up volume modeling triangulated against top-down macroeconomic indicators to ensure segmentation consistency.
Forecast inputs incorporate grade-tier production capacity, end-use industry demand elasticity, regional regulatory phase-out timelines, and packaging format distribution economics across the projection horizon. Segmentation dimensions modeled include purity specification tier, application type, end-user industry vertical, and regional production hub classification. CAGRs were derived through logarithmic trend extrapolation of historical volume data adjusted for regulatory inflection points. Industry-specific forecast inputs encompassed railway tie retreatment cycle frequencies and pyrethroid resistance emergence patterns in target pest populations.
Stress conditions across hexachlorobenzene feedstock availability, ECHA authorization threshold stringency, and copper azole substitution penetration were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding grandfathered use persistence and regulatory divergence between OECD and emerging market jurisdictions. Quarterly review of EPA handler certification enrollment trends and ECHA substance-of-very-high-concern review schedules is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Organic Chemicals
Chloroethylene Market
Organic Chemicals
Bio-Acetic Acid Market
Organic Chemicals
Chlorinated Methane Market
Organic Chemicals
N-Pentane Market
Organic Chemicals
Soy Chemicals Market
Organic Chemicals
Chlorinated Isocyanurates Market
Organic Chemicals
N-Hexyl Chloride Market
Organic Chemicals
Pyridine Derivatives Market
Organic Chemicals
Alanine Market
Organic Chemicals
Phenolic Board Market
Organic Chemicals
2-Amino-5-Nitrobenzophenone Market
Organic Chemicals
Dioxolane Market
Organic Chemicals
Cycloalkanes Market
Organic Chemicals
Aspartic Acid Market
Organic Chemicals
Trimethylcyclohexanone Market
Organic Chemicals
2-Iodophenol Market