
 Chondroitin Market | 2026-2036
Chondroitin Market Size, Share, and Industry Trends Forecast 2026-2036
Chondroitin Market Intelligence
Increased production capacity in China is reshaping the supply landscape for raw chondroitin sulfate, affecting global cost structures and sourcing strategies. Spain-based Bioiberica S.A.U. leverages its pharmaceutical-grade manufacturing and extensive clinical research to command premium segments. In contrast, Synutra capitalizes on its large-scale fermentation capabilities to serve high-volume nutraceutical markets from its domestic base. SEIKAGAKU CORPORATION of Japan specializes in high-purity chondroitin for specialized medical and research applications.
Chondroitin is a sulfated glycosaminoglycan composed of a chain of alternating sugars, primarily extracted from animal cartilage like bovine, porcine, or avian sources. Its principal biological function is to provide cartilage with resistance to compression, making it a vital structural component for joint health. The Chondroitin Sulfate product type, particularly in powder form, dominates raw material supply destined for the nutraceuticals application. Finished products in tablet and capsule form for joint care and osteoarthritis management constitute the largest and most mature end-use segments.
Regulatory oversight from bodies such as the United States' FDA and the European Union's EMA establishes strict guidelines for purity and labeling when chondroitin is sold as a dietary supplement. In parallel, China's NMPA enforces distinct standards for material used as an active pharmaceutical ingredient, influencing export quality and market access. Key strategic decisions for suppliers will revolve around navigating the different compliance pathways and associated costs for pharmaceutical versus nutraceutical grade products.
Market Dynamics
The central dynamic in the chondroitin market is the growing divergence between high-volume nutraceutical supply chains, driven by cost-efficiency, and low-volume pharmaceutical-grade channels, dictated by stringent regulatory compliance mandates from bodies like the FDA and EMA.
Growth Catalysts
- Aging Demographics:Expanding elderly populations in developed nations like the United States and Germany sustain strong demand for dietary supplements aimed at managing osteoarthritis and maintaining joint mobility.
- Nutraceutical Formulation Trends:The expansion of the nutraceuticals industry drives demand for chondroitin as a core component in multi-ingredient joint health formulas, often combined with glucosamine and MSM.
- Wellness Trends in Asia:Rising disposable incomes and a focus on preventative health in countries like South Korea and Japan are creating new consumer bases for joint care and anti-aging supplements.
Market Restraints
- Raw Material Volatility:The market's dependence on animal cartilage creates supply chain vulnerability to epizootic diseases, such as avian influenza or African swine fever, which can disrupt availability and increase costs.
- Substitution from Alternatives:Competition from other joint health ingredients, including glucosamine, methylsulfonylmethane (MSM), and emerging plant-based compounds, presents a persistent substitution threat.
- High Cost of Pharmaceutical Grade:The significant investment required to meet pharmaceutical GMP standards set by regulators like the EMA or Japan's PMDA limits the number of suppliers able to serve the high-purity medicinal segment.
Strategic Opportunities
- Fermentation-Based Production:Developing non-animal, fermentation-derived chondroitin sulfate offers a path to mitigate supply volatility, address ethical consumer concerns, and provide a vegan-certified alternative.
- Expansion in Veterinary Medicine:Formulating specialized chondroitin products for companion animals, particularly in the large North American and European pet care markets, represents a major growth vector.
- Medical Device Applications:High-purity chondroitin has potential uses in ophthalmology for viscoelastic solutions used in eye surgery and in tissue engineering as a component of biocompatible scaffolds.
Industry Challenges
- Navigating Divergent Regulations:Manufacturers face operational complexity in managing separate production lines and documentation to comply with the different standards of the FDA for supplements versus the EMA or NMPA for pharmaceutical ingredients.
- Ensuring Batch-to-Batch Consistency:A key operational challenge is maintaining consistent purity, molecular weight, and sulfation patterns from raw animal cartilage, which impacts final product efficacy and requires extensive quality control.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chondroitin Market |
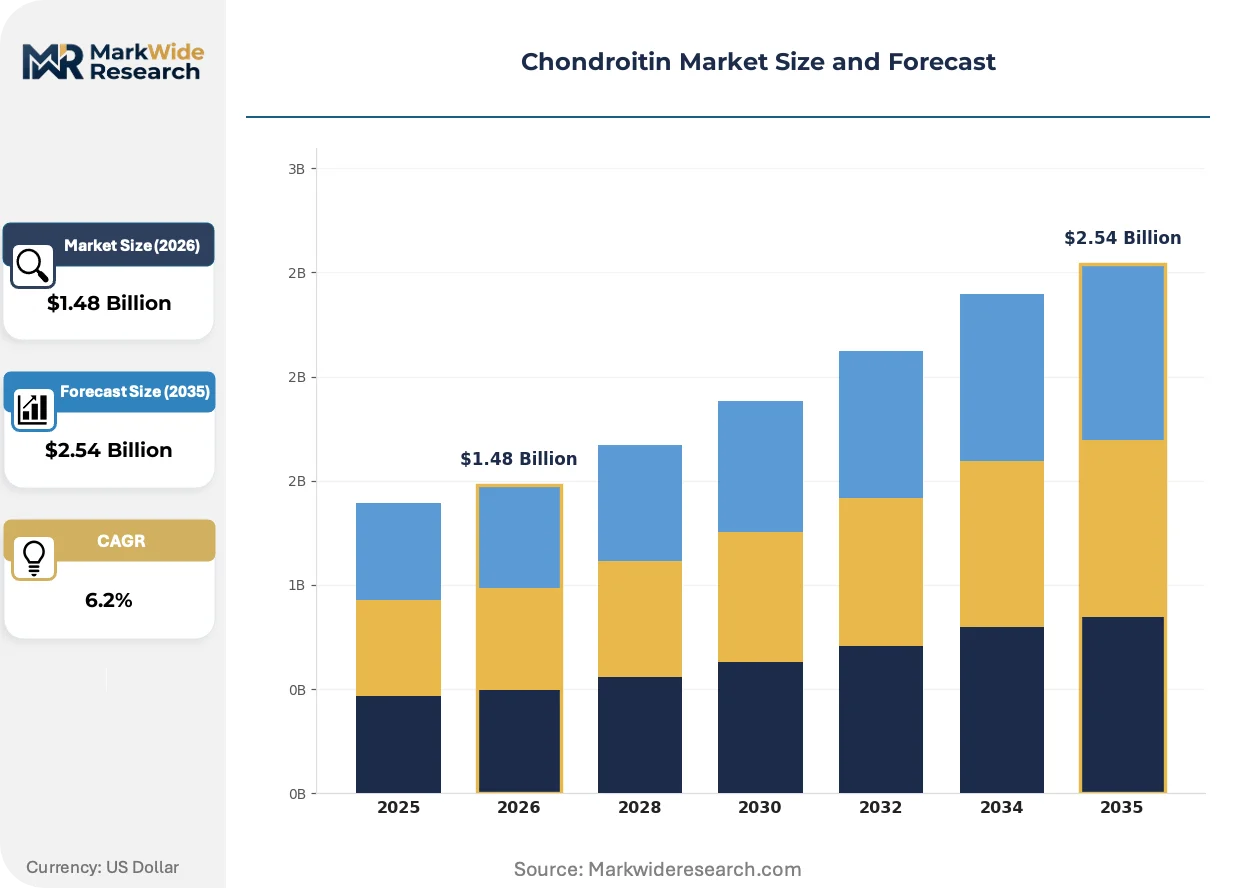
| Market Size in 2026 | $1.48 Billion |
| Market Size in 2035 | $2.54 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chondroitin Sulfate, Sodium Chondroitin, Chondroitin Capsules, Chondroitin Powder Application: Osteoarthritis, Joint Care, Sports Injuries, Nutraceuticals End User: Hospitals, Clinics, Pharmacies, Online Retail Form: Tablet, Liquid, Powder, Softgel |
| Companies Covered | Bioiberica S.A.U., TSI Group Ltd., Pacific Rainbow International, Synutra, SEIKAGAKU CORPORATION, Merck, Chongqing Aoli Biopharmaceutical Co. Ltd, Summit Nutritionals International, Gnosis S.p.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chondroitin Market Strategic Shifts & Innovations
A fundamental split defines the market's evolution, separating high-purity, clinically validated chondroitin from cost-sensitive, high-volume nutraceutical grades. This bifurcation directly influences technological investment, regulatory strategy, and end-user purchasing criteria.
Fermentation-based synthesis provides a method for producing chondroitin sulfate without animal inputs, using microbial processes. Manufacturers seeking supply chain stability and catering to vegan consumer preferences are primary early adopters. The market’s sourcing foundation is migrating from total reliance on animal cartilage to a more resilient, hybrid model that includes these biotechnological materials.
European Union regulations, specifically the EMA's framework for medicinal products, impose strict evidence requirements for chondroitin's use in treating osteoarthritis. This policy mandates extensive clinical trials and pharmaceutical-grade manufacturing, creating a significant barrier to entry. Consequently, the European pharmaceutical segment remains concentrated, compelling suppliers to invest heavily in research and development to compete.
Demand for supply chain transparency is compelling nutraceutical brand owners to require third-party certifications and full traceability for raw materials. This behavior is displacing anonymous commodity sourcing with strategic partnerships built on documented quality and origin. This shift is most visible in the United States and German dietary supplement markets, where consumer trust is paramount.
Chondroitin Market Segmentation
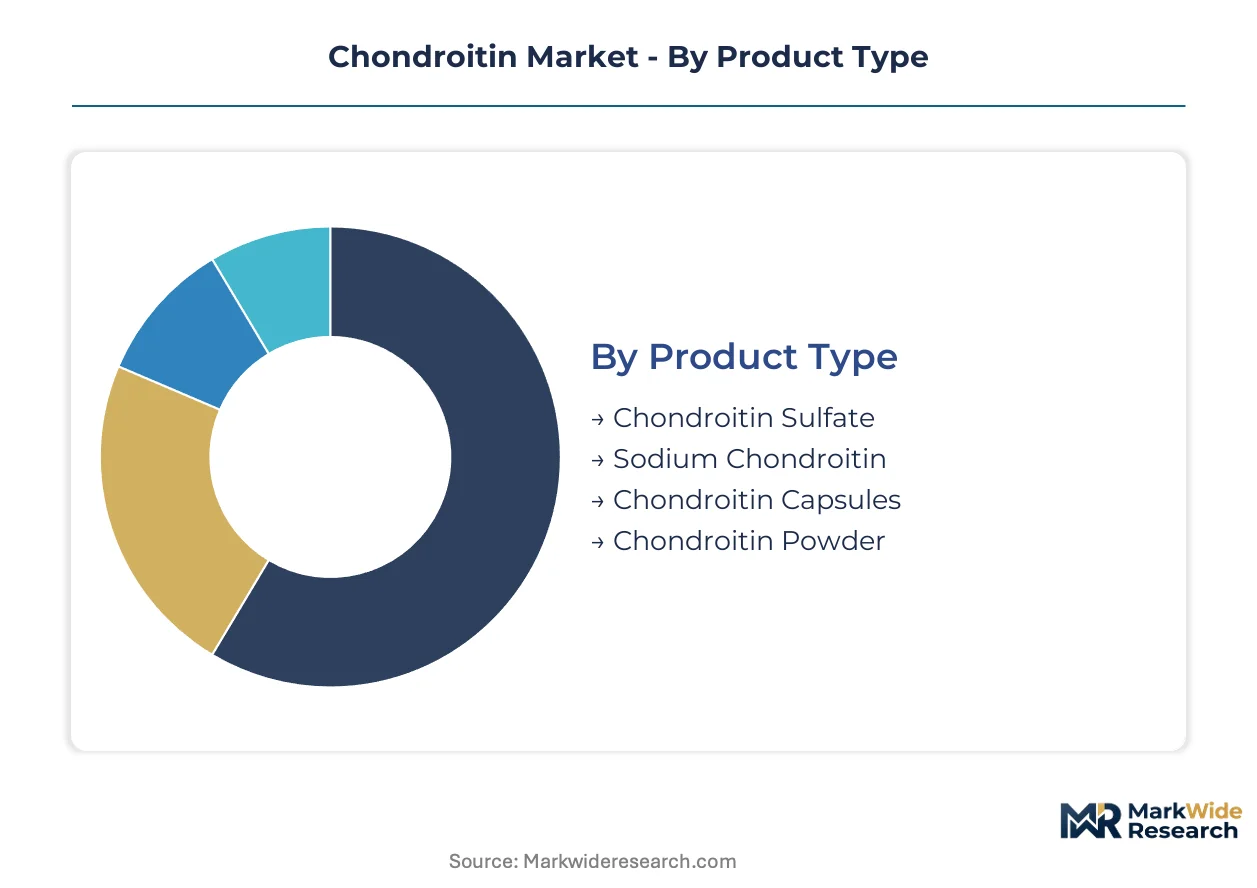
The Chondroitin market demonstrates diverse segmentation, reflecting varied product forms, application areas, and end-user preferences. Understanding these distinct segments is crucial for suppliers to align their production capabilities and regulatory compliance efforts with specific market needs, particularly across the diverging nutraceutical and pharmaceutical pathways.
Product Type:
The intensity of after-sales service and technical support varies significantly across chondroitin product types, from bulk raw materials to finished dosage forms requiring formulation expertise.
- Chondroitin Sulfate:This sulfated glycosaminoglycan, typically extracted from bovine, porcine, or avian cartilage, is the most prevalent raw material form. Demand for Chondroitin Sulfate is concentrated in the nutraceutical industry for joint health formulations, driven by consumer interest in preventative wellness in countries like the United States and Germany.
- Chondroitin Powder:As a versatile bulk ingredient, chondroitin powder serves as a foundational component for various applications, including dietary supplements and veterinary products. Its commercial significance lies in its ease of integration into different dosage forms, with high-volume producers in China supplying global manufacturers.
- Sodium Chondroitin:This is a salt form of chondroitin, often used for increased solubility or specific formulation requirements in certain medical or dietary supplement products.
- Chondroitin Capsules:These represent a finished dosage form, primarily targeting the consumer market for joint health and osteoarthritis management due to their convenience and precise dosing.
Chondroitin Sulfate holds the largest share; momentum sits with Chondroitin Powder.
Application:
Application focus determines the required purity, regulatory pathway, and clinical evidence for chondroitin products, influencing market access and pricing strategies.
- Osteoarthritis:Chondroitin is widely applied in formulations designed to alleviate symptoms and support cartilage health in individuals suffering from osteoarthritis, particularly in older demographics. This application segment requires significant clinical validation, especially for pharmaceutical-grade products in regions like the European Union.
- Nutraceuticals:This broad application encompasses dietary supplements aimed at general joint health, mobility, and preventative care for active individuals. The nutraceutical segment drives substantial volume demand, with products often combined with other ingredients like glucosamine for synergistic effects.
- Joint Care:Products for general joint care focus on maintaining healthy cartilage and supporting overall joint function, catering to a wider consumer base beyond specific medical conditions. This segment often overlaps with the broader nutraceutical market.
- Sports Injuries:Chondroitin formulations are increasingly used to aid in the recovery and rehabilitation from sports-related joint injuries, supporting cartilage repair and reducing inflammation.
The segment commanding the highest volume is Nutraceuticals, while Osteoarthritis exhibits the steepest expansion trajectory.
End User:
Customer type dictates the distribution channels and marketing approaches for chondroitin products, ranging from direct patient access to bulk ingredient supply to manufacturers.
- Pharmacies:Pharmacies serve as a primary retail channel for both over-the-counter chondroitin supplements and prescription-based medical products. They benefit from consumer trust and professional advice in countries like the United States and Germany.
- Online Retail:The online retail segment provides extensive reach and convenience for consumers purchasing chondroitin supplements, often offering a wider selection and competitive pricing. This channel shows significant growth, especially in developed economies.
- Hospitals:Hospitals primarily utilize pharmaceutical-grade chondroitin for specialized medical procedures, such as ophthalmology or as an active pharmaceutical ingredient in specific treatments.
- Clinics:Clinics, including orthopedic and sports medicine centers, recommend or dispense chondroitin products for patient care, often focusing on therapeutic applications.
Pharmacies dominate the distribution landscape, with Online Retail showing considerable dynamism.
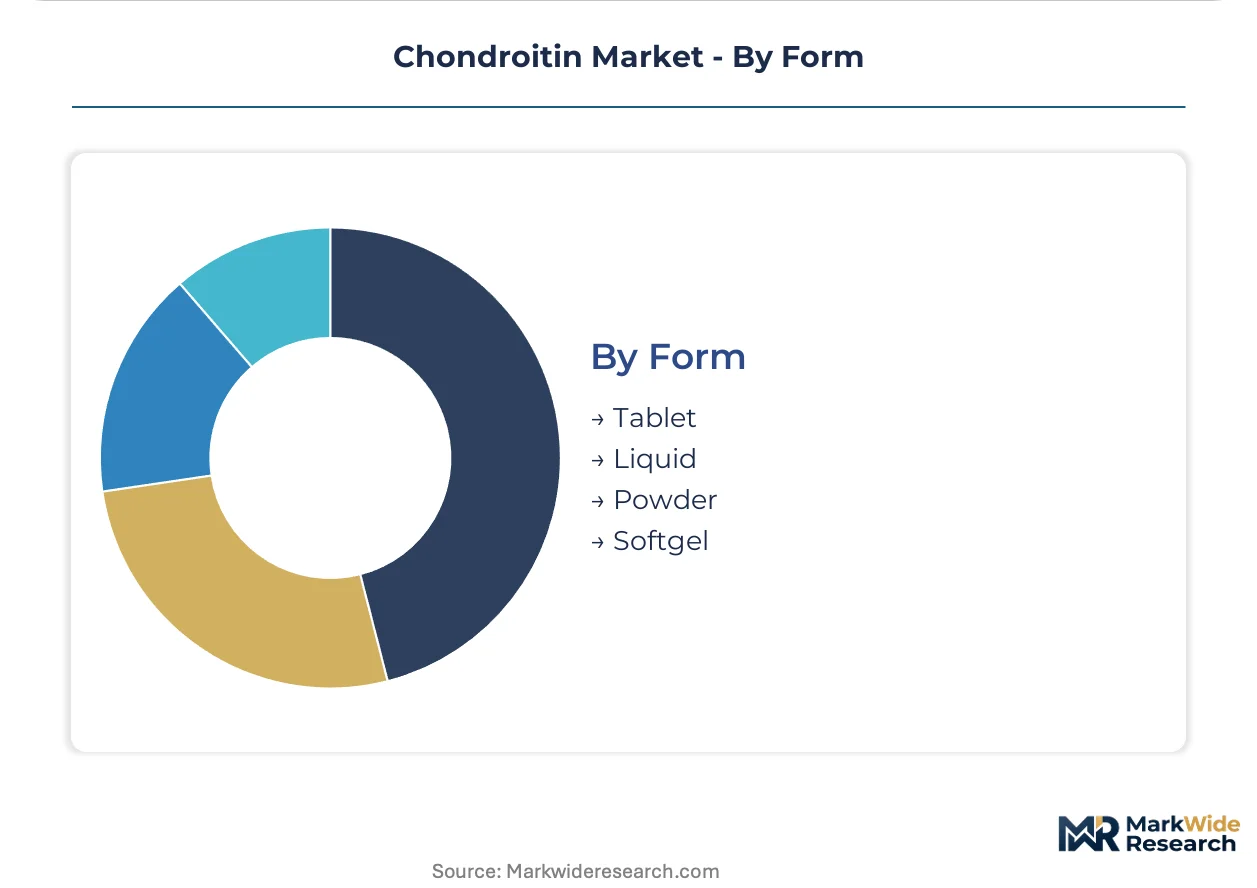
Form:
The physical form of chondroitin influences its manufacturing process, stability, bioavailability, and consumer preference, impacting market adoption.
- Tablet:Tablets are a widely accepted and convenient dosage form for chondroitin supplements, offering precise dosing and extended shelf life. This form is a staple in the consumer health market.
- Powder:Chondroitin in powder form is primarily used as a raw material for manufacturing other dosage forms or as a bulk supplement for direct consumption. Its versatility makes it essential for industrial applications.
- Liquid:Liquid chondroitin formulations offer an alternative for consumers who prefer not to swallow pills or desire faster absorption, often found in specialized dietary supplements.
- Softgel:Softgel capsules provide an easily digestible and often visually appealing alternative to tablets, sometimes preferred for ingredients that benefit from oil-based formulations.
The most prevalent form for consumer uptake is Tablet, while Powder provides a versatile base for manufacturing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States Food and Drug Administration (FDA) significantly influences the global chondroitin market, particularly for dietary supplements. Developed economies, including the United States and Germany, drive substantial demand due to aging populations seeking joint health solutions. China also plays a critical role with its expanding production capabilities for raw materials.
United States
Demand for joint health supplements is high among an aging population seeking to manage osteoarthritis. The FDA establishes strict guidelines for purity and labeling of dietary supplements. Major nutraceutical companies in regions like California and New Jersey integrate chondroitin into multi-ingredient formulas.
Germany
Germany's elderly population sustains strong demand for osteoarthritis management products. The European Medicines Agency (EMA) sets stringent requirements for pharmaceutical-grade chondroitin. Pharmaceutical manufacturers in Bavaria and North Rhine-Westphalia focus on high-purity medicinal applications.
China
Increased production capacity for raw chondroitin sulfate is reshaping global supply dynamics. China's NMPA enforces distinct standards for active pharmaceutical ingredients, influencing export quality. Large-scale fermentation facilities in provinces like Shandong and Jiangsu serve high-volume nutraceutical markets.
Japan
Wellness trends and a focus on preventative health among its aging demographic boost demand for joint care supplements. Japan's PMDA oversees high-purity chondroitin for specialized medical and research applications. Specialized manufacturers in the Kanto region and Kansai focus on advanced chondroitin formulations.
Spain
Spain's market benefits from companies leveraging pharmaceutical-grade manufacturing for premium segments. The EMA's framework for medicinal products mandates extensive clinical evidence for chondroitin's use in osteoarthritis. Bioiberica S.A.U., based near Barcelona, exemplifies advanced research and development in chondroitin production.
Chondroitin Market Key Industry Players
Specialized pharmaceutical-grade manufacturers and high-volume nutraceutical suppliers split the chondroitin market. The industry structure shows a clear bifurcation between producers focusing on stringent regulatory compliance and those prioritizing cost-efficiency for mass markets. Strategic archetypes include vertically integrated pharmaceutical ingredient specialists, large-scale fermentation producers, and bulk raw material suppliers. Several companies engage in strategic partnerships and capacity expansions to secure raw material supply and broaden market reach, while others pursue technology licensing for novel production methods.
On the premium-tier vector, Spain-based Bioiberica S.A.U. exemplifies pharmaceutical-grade manufacturing and extensive clinical research for specialized applications. China-based Synutra occupies a position as a large-scale fermentation producer, serving high-volume nutraceutical markets. Meanwhile, Japan's SEIKAGAKU CORPORATION represents high-purity chondroitin for advanced medical and research applications, demonstrating a focus on specialized segments. These companies anchor distinct segments of the chondroitin supply chain.
| Leading Market Players |
|---|
| Bioiberica S.A.U. |
| TSI Group Ltd. |
| Pacific Rainbow International |
| Synutra |
| SEIKAGAKU CORPORATION |
| Merck |
| Chongqing Aoli Biopharmaceutical Co. Ltd |
| Summit Nutritionals International |
| Gnosis S.p.A. |
| Others |
Cost & Logistics Intelligence
China's expanded production capacity for raw chondroitin sulfate has created an oversupply dynamic, driving down costs for high-volume nutraceutical grades and influencing global sourcing strategies.
Pricing Analysis
Significant geographic price spreads exist for chondroitin, driven by regional regulatory frameworks and supply concentrations. Pricing exhibits a tiered premium-mid-economy differentiation, based on purity levels and regulatory compliance standards. Pricing pressure intensifies for nutraceutical grades due to high-volume Chinese production. Nutraceutical manufacturers exhibit high price sensitivity, while pharmaceutical buyers prioritize purity and compliance.
Supply Chain Analysis
China's NMPA enforces distinct standards for active pharmaceutical ingredients, creating de facto export controls on high-purity chondroitin. Global supply concentrates in China, Spain, and Japan, with a heavy reliance on animal cartilage from bovine, porcine, or avian sources. A structural risk is supply chain vulnerability to epizootic diseases, such as avian influenza. Distribution runs through direct sales to manufacturers and specialized ingredient distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The chondroitin market requires a strong substitution defense, as incumbents must navigate persistent competition from alternative joint health ingredients like glucosamine and emerging plant-based compounds.
For Market Incumbents: Pre-empt supply chain disruptions by diversifying raw material sourcing, including significant investment in fermentation-based chondroitin sulfate production. Secure long-term contracts with certified suppliers to mitigate raw material volatility. Invest in R&D for novel formulations that offer superior efficacy against alternative ingredients. Focus on expanding pharmaceutical-grade manufacturing to meet stringent regulatory requirements.
For New Entrants and Emerging Players: Underpenetration in the veterinary medicine segment in North America presents a significant white-space opportunity for specialized chondroitin formulations. Target the medical device applications, such as ophthalmology, with high-purity, non-animal derived chondroitin. A go-to-market angle emphasizing vegan certification and superior batch-to-batch consistency will attract discerning buyers. Focus on niche applications requiring stringent quality controls.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among pharmaceutical-grade chondroitin producers with established regulatory compliance and clinical validation. The market offers long-term viability due to sustained demand from aging populations and preventative health trends. Acquisition targets should be vertically integrated pharmaceutical ingredient specialists or companies with proprietary fermentation technologies. Monitor regulatory shifts towards non-animal derived sources as a key inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Fermentation Technology Investment | Mitigates raw material volatility and addresses ethical consumer concerns for vegan products. |
| GMP Certification Expansion | Unlocks access to premium pharmaceutical markets in Europe and Japan. |
| Veterinary Product Line Launch | Captures growth in the expanding companion animal health sector. |
| Clinical Trial Sponsorship | Validates efficacy for osteoarthritis, strengthening pharmaceutical claims for chondroitin. |
| Supply Chain Traceability Program | Builds consumer trust and meets nutraceutical brand owner demands for origin. |
Research Approach
Findings reconcile primary fieldwork against secondary review of regulatory filings, industry association reports, and academic literature. Primary interviews included regulatory affairs leads, R&D directors, procurement managers, and nutraceutical brand owners. Data triangulation employed both bottom-up and top-down approaches to ensure robust market sizing and segmentation across various dimensions.
Forecast inputs considered include evolving regulatory landscapes, demographic shifts, and technological advancements in chondroitin production. The analytical framework modeled segmentation dimensions by product type, application, end-user, form, and regional regulatory clusters. Compound annual growth rates were derived from historical trends, identified market drivers, and expert projections across the analysis window.
Practitioners should monitor epizootic disease outbreaks and shifts in regulatory approval pathways for early signals. Forecasts reflect assumptions regarding raw material availability and consumer health trends. Material shifts in animal sourcing or fermentation technology would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutraceuticals
Magtein Market
Nutraceuticals
US Pet Nutraceuticals Market
Nutraceuticals
High Potency Apis Market
Nutraceuticals
Nootropics Market
Nutraceuticals
Europe Collagen Peptide Products Market
Nutraceuticals
Ayurvedic Products Market
Nutraceuticals
Asia-Pacific Pet Nutraceuticals Market
Nutraceuticals
North America Nutraceuticals Market
Nutraceuticals
Herbal Nutraceuticals Market
Nutraceuticals
US and China Glucose Market
Nutraceuticals
Micro-Ecological Regulators Market
Nutraceuticals
Postbiotics Market
Nutraceuticals
Oxiracetam Market
Nutraceuticals
Cognitive Health Ingredients Market
Nutraceuticals
Global Synbiotics Market
Nutraceuticals
Tetrahydropalmatine Market