
 Fish-Oil Based Drugs Market | 2026-2036
Fish-Oil Based Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Fish-Oil Based Drugs Market Foresight
Specialty clinics is unwinding from retail pharmacies as the dominant procurement channel for prescription-grade omega-3 therapies. Amarin Pharmaceuticals Ireland Limited leverages its FDA-approved icosapent ethyl franchise to dominate the hypertriglyceridemia segment. BASF SE anchors the European supply base through backward integration into Antarctic krill and marine sourcing networks. DSM-Firmenich competes on pharmaceutical-grade purification standards for ethyl ester concentrates.
Fish-oil based drugs comprise purified omega-3 fatty acid formulations—primarily eicosapentaenoic acid (EPA) and docosahexaenoic acid (DHA)—delivered as ethyl esters or re-esterified triglycerides with purity thresholds exceeding 90% for prescription indications. These compounds function as lipid-modifying agents that reduce hepatic very-low-density lipoprotein production, serving cardiovascular and metabolic therapeutic protocols in regulated clinical environments. Omega-3 ethyl esters command the largest revenue pool due to established FDA monographs and cardiologist familiarity, while combined EPA and DHA formulations represent the fastest-growing category as polyunsaturated fatty acid research extends into inflammatory and neuroprotective indications. Softgel dosage forms occupy the dominant position in retail and institutional channels, though liquid suspensions are gaining traction in pediatric and geriatric populations where swallowing compliance limits capsule adoption.
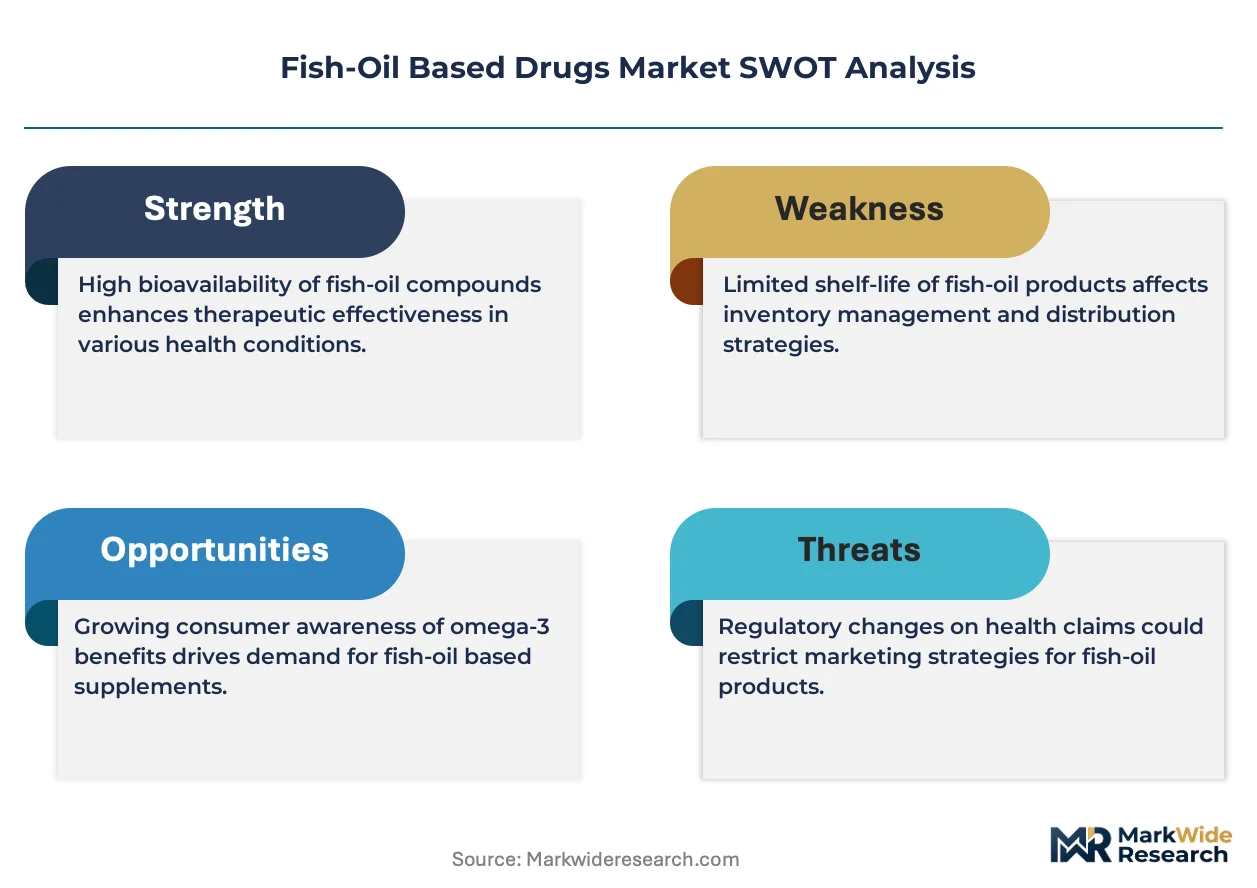
The US FDA maintains strict distinction between dietary supplement omega-3s and prescription drug classifications under New Drug Application pathways, forcing manufacturers to validate cGMP compliance and clinical efficacy endpoints. The European Medicines Agency enforces additional pharmacovigilance requirements for marine-derived therapeutics through centralized marketing authorization procedures. Japan's Ministry of Health, Labour and Welfare recognizes specific omega-3 formulations as functional foods with qualified health claims, creating a dual-track regulatory environment. Stakeholders must monitor evolving EPA-to-DHA ratio requirements in cardiovascular outcome trials and preemptively adapt formulation strategies before guideline committees issue updated therapeutic recommendations.
Market Dynamics
The FDA's prescription omega-3 drug pathway is compressing competitive differentiation around clinical-grade purity standards, forcing manufacturers to validate efficacy endpoints that dietary supplement competitors cannot replicate. This regulatory moat is accelerating hospital procurement consolidation toward verified ethyl ester formulations.
Growth Catalysts
- Cardiovascular protocol expansion:Hospital formularies are embedding EPA-DHA therapies into post-MI standard of care, driving institutional volume commitments that retail channels cannot match.
- EMA pharmacovigilance harmonization:Centralized marketing authorization procedures for marine-derived therapeutics are reducing multi-country registration friction for compliant manufacturers.
- Hypertriglyceridemia diagnosis rates:Metabolic screening protocols in managed care networks are identifying candidate patients earlier in disease progression.
Market Restraints
- Antarctic krill supply concentration:BASF SE's backward integration into polar marine sourcing networks creates bottleneck risk for competing ethyl ester feedstock.
- FDA cGMP compliance costs:New Drug Application validation requirements impose capital barriers that exclude dietary supplement manufacturers from prescription crossover.
- Plant-based omega-3 substitution:Algal DHA fermentation processes are capturing pediatric and vegan-sensitive segments that fish oil cannot serve.
Strategic Opportunities
- Pediatric liquid suspensions:Geriatric swallowing compliance limitations and pediatric capsule aversion are opening formulation white space beyond dominant softgel formats.
- Japan's functional food dual-track:METI and PMDA's qualified health claim pathway allows premium positioning for quasi-pharmaceutical omega-3 products.
- Neuroprotective indication expansion:Polyunsaturated fatty acid research into cognitive decline is creating prescriber familiarity beyond cardiovascular endpoints.
Industry Challenges
- EPA-to-DHA ratio standardization:Evolving cardiovascular outcome trial specifications force preemptive formulation adaptation before guideline committee updates.
- Pharmaceutical-grade purification capex:DSM-Firmenich's purification standards require continuous capital reinvestment in molecular distillation capacity.
- Specialty clinic credentialing timelines:Institutional pharmacy and therapeutics committee approvals delay revenue recognition for new hospital entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fish-Oil Based Drugs Market |
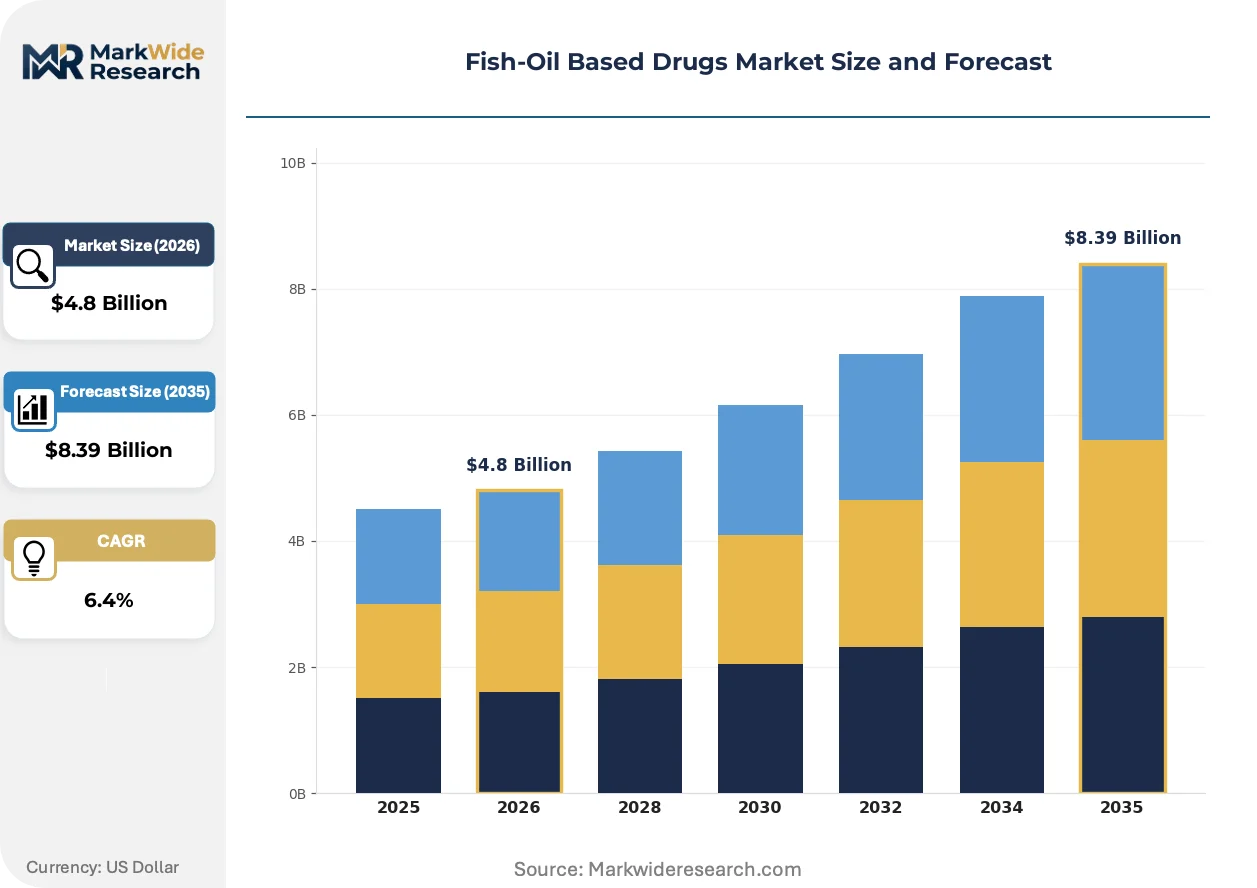
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.39 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Omega-3 Ethyl Esters, Omega-3 Acid Triglycerides, Combined EPA & DHA Formulations, Ethyl Esters Concentrates Application: Cardiovascular Diseases, Hypertriglyceridemia, Inflammatory Disorders, Cognitive Health, Dermatological Conditions End User: Hospitals, Specialty Clinics, Retail Pharmacies, Nutraceutical Manufacturers Dosage Form: Capsules, Softgels, Liquid Suspensions, Injectable Solutions |
| Companies Covered | Amarin Pharmaceuticals Ireland Limited, Stepan Company, Pharma Marine, Omega Protein Corporation, GC Rieber Oil, Croda International PLC, BASF SE, DSM-Firmenich, GSK plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fish-Oil Based Drugs Market Shifts & Advancements
Re-esterified triglyceride formulations are disrupting the ethyl ester dominance that FDA monographs established, while regulatory convergence between pharmaceutical and functional food categories is blurring traditional competitive boundaries.
Re-esterified triglyceride technology is decomposing the bioavailability advantage that ethyl esters held through three decades of cardiologist familiarity. Hospital pharmacy directors are adopting these formulations for statin combination therapies where absorption efficiency determines formulary placement. The structural consequence is compressing price premiums for legacy ethyl ester products that cannot demonstrate comparable pharmacokinetic profiles.
EMA centralized marketing authorization procedures are tightening pharmacovigilance requirements for marine-derived therapeutics across EU member states. Manufacturers must now submit real-world safety data as a condition of marketing authorization renewal, not just initial approval. This is forcing reformulation investments in oxidation stability and contaminant screening that disproportionately burden mid-scale European suppliers.
Specialty clinics are displacing retail pharmacies as the dominant procurement channel for prescription-grade omega-3 therapies. Hospital outpatient departments and cardiology group practices are consolidating volume through 340B pricing programs and group purchasing organizations. This channel rotation is most visible in United States metropolitan markets where integrated delivery networks control specialist referrals.
Fish-Oil Based Drugs Market Segmentation
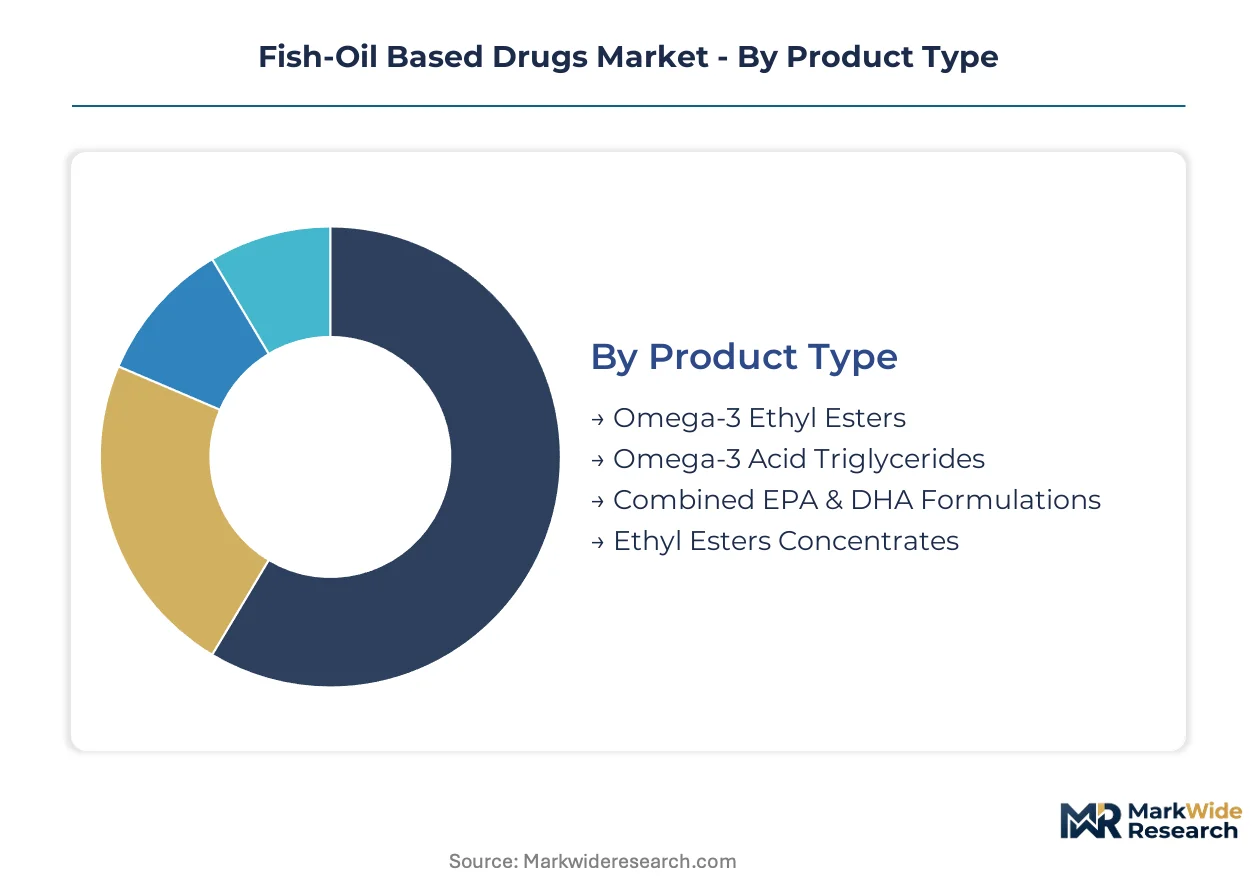
Segmentation in the fish-oil based drugs market reveals how regulatory pathways and clinical adoption patterns concentrate value across distinct formulation and delivery categories. Each segment carries differentiated substitution risks from algal alternatives, plant-based omega-3s, and dietary supplement crossovers.
Product Type:
Substitution pressure from algal fermentation and plant-based omega-3 sources weighs most heavily on standard-grade formulations, while prescription-grade ethyl esters and concentrated EPA-DHA combinations maintain regulatory moats against dietary supplement competitors.
- Omega-3 Ethyl Esters:Purified fatty acids esterified with ethanol to enhance stability and shelf life, meeting FDA monograph specifications for prescription lipid-modifying therapy. Hospital formularies in the United States concentrate procurement around these formulations for post-MI protocols, though re-esterified triglyceride alternatives now challenge their bioavailability claims.
- Combined EPA & DHA Formulations:Dual-component concentrates delivering both eicosapentaenoic and docosahexaenoic acids in variable ratios for cardiovascular and neuroprotective indications. Demand is climbing fastest in specialty clinics across Germany and the Netherlands where polyunsaturated fatty acid research extends into cognitive decline protocols.
- Omega-3 Acid Triglycerides:Natural molecular form omega-3s reconstituted from ethyl esters to improve intestinal absorption kinetics.
- Ethyl Esters Concentrates:Ultra-purified formulations exceeding 90% omega-3 content for severe hypertriglyceridemia cases.
Omega-3 Ethyl Esters anchors the volume base while Combined EPA & DHA Formulations gains share at the steepest rate.
Application:
Cost tier stratification separates acute cardiovascular intervention from preventive metabolic management, with hospital reimbursement rates determining which indications sustain prescription-grade pricing premiums.
- Cardiovascular Diseases:Primary indication encompassing post-myocardial infarction secondary prevention and coronary artery disease risk modification through triglyceride reduction. United States integrated delivery networks embed EPA-DHA therapies into standard-of-care order sets, driving institutional volume commitments that retail channels cannot replicate.
- Hypertriglyceridemia:Severe elevation of circulating triglycerides requiring pharmacological intervention when lifestyle modification proves insufficient. Managed care screening protocols in California and Texas metabolic health networks are identifying candidate patients earlier, expanding the addressable population for prescription-grade therapies.
- Inflammatory Disorders:Emerging application targeting rheumatoid arthritis and psoriasis through omega-3 mediated eicosanoid pathway modulation.
- Cognitive Health:Neuroprotective indication exploring EPA-DHA neuroplasticity effects in age-related cognitive decline.
- Dermatological Conditions:Adjunct therapy for atopic dermatitis and psoriasis leveraging anti-inflammatory fatty acid metabolites.
Cardiovascular Diseases commands the revenue base while Hypertriglyceridemia expands most quickly as diagnostic screening intensifies.
End User:
Customer type migration shows institutional procurement displacing retail dispensing, with 340B pricing programs and group purchasing organizations consolidating volume through hospital outpatient channels.
- Hospitals:Acute care institutions and integrated delivery networks controlling inpatient and emergency department prescribing decisions. The Mayo Clinic and Cleveland Clinic systems anchor institutional adoption through pharmacy and therapeutics committee standardization of omega-3 protocols.
- Specialty Clinics:Cardiology and endocrinology group practices managing chronic lipid disorders in outpatient settings. These facilities are displacing retail pharmacies as the dominant procurement channel in United States metropolitan markets where specialist referrals concentrate volume.
- Retail Pharmacies:Community and chain pharmacy dispensing for maintenance therapy prescriptions.
- Nutraceutical Manufacturers:B2B purchasers of pharmaceutical-grade feedstock for functional food and supplement formulation.
Hospitals anchor the volume base while Specialty Clinics gains share at the steepest rate.
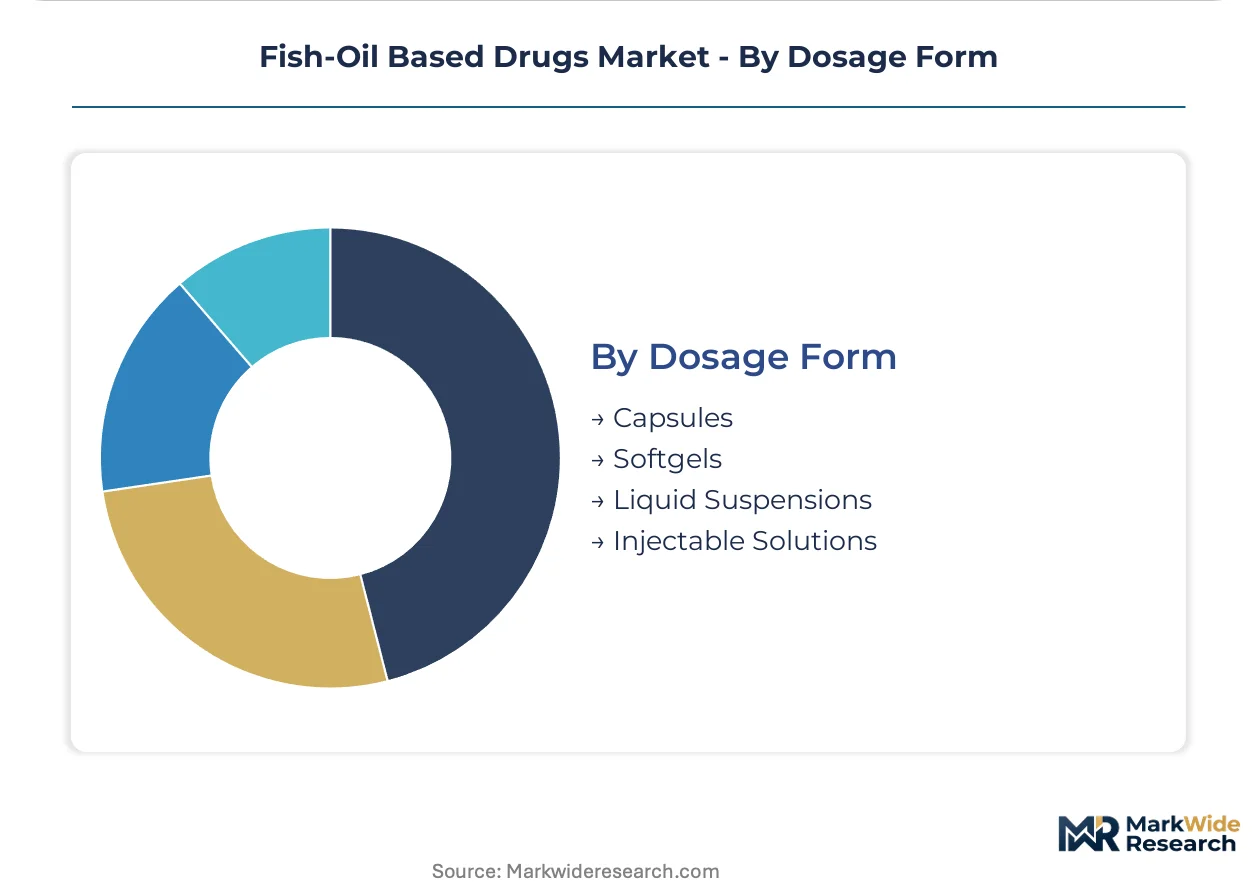
Dosage Form:
Patient compliance limitations across age demographics are fragmenting delivery format preferences, with swallowing difficulties in pediatric and geriatric populations opening formulation white space beyond dominant softgel formats.
- Softgels:Gelatin-encapsulated liquid fill dominating retail and institutional channels due to manufacturing scale and cardiologist familiarity. United States hospital pharmacies standardize on this format for statin combination therapies where patient acceptance is established.
- Liquid Suspensions:Emulsified or oil-based preparations enabling dose titration and administration to patients with capsule swallowing limitations. Pediatric wards in Boston and Philadelphia academic medical centers are adopting these formats for compliance-constrained populations.
- Capsules:Two-piece hard shell alternatives for powder or granule formulations.
- Injectable Solutions:Parenteral delivery for critical care settings requiring rapid lipid modification.
Softgels anchors the volume base while Liquid Suspensions gains share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's pharmaceutical cold chain infrastructure anchors European distribution for temperature-sensitive omega-3 formulations, while direct rail links from Antarctic logistics hubs feed BASF's processing facilities in Germany.
United States
Hospital outpatient departments and integrated delivery networks concentrate procurement through 340B pricing programs. The FDA's prescription omega-3 drug pathway under New Drug Application standards accelerates clinical-grade product differentiation. The Mayo Clinic and Cleveland Clinic systems anchor institutional adoption through pharmacy and therapeutics committee standardization.
Germany
Specialty clinics across metropolitan markets displace retail pharmacies as dominant procurement channels. The EMA's centralized marketing authorization procedures enforce pharmacovigilance requirements for marine-derived therapeutics. The Hamburg-Bremen port cluster processes Antarctic krill feedstock for BASF's backward-integrated supply networks.
Japan
METI and PMDA's qualified health claim pathway enables premium positioning for quasi-pharmaceutical omega-3 products. The Ministry of Health, Labour and Welfare recognizes specific formulations as functional foods, creating a dual-track regulatory environment. Tokyo and Osaka academic medical centers drive prescriber familiarity through cardiovascular outcome research.
United Kingdom
Cardiology group practices consolidate volume through National Health Service formularies embedding EPA-DHA therapies into post-MI protocols. The Medicines and Healthcare products Regulatory Agency aligns with EMA centralized procedures for marine-derived therapeutics. London and Cambridge research clusters extend polyunsaturated fatty acid investigations into neuroprotective indications.
Netherlands
Managed care screening protocols identify hypertriglyceridemia patients earlier in disease progression. The Dutch Medicines Evaluation Board participates in EMA centralized marketing authorization for prescription lipid-modifying therapies. The Rotterdam pharmaceutical logistics hub distributes temperature-sensitive formulations across continental Europe.
Fish-Oil Based Drugs Market Competitive Landscape
Concentration sits with vertically integrated pharmaceutical-grade manufacturers and specialized marine sourcing enterprises. The vendor base stratifies across three tiers: multinational chemical conglomerates with captive Antarctic supply networks, mid-scale European purification specialists, and regional fermentation technology developers. Dominant competitive moves include backward integration into polar marine sourcing and capacity expansion in molecular distillation infrastructure.
Within the pharmaceutical-grade tier, Amarin Pharmaceuticals Ireland Limited exemplifies FDA-validated prescription drug pathways, while BASF SE anchors European supply security through Antarctic krill networks. DSM-Firmenich occupies a position defined by purification standards for ethyl ester concentrates. These three entities represent distinct strategic archetypes: regulatory moat defense, upstream supply control, and technical specification leadership.
| Leading Market Players |
|---|
| Amarin Pharmaceuticals Ireland Limited |
| Stepan Company |
| Pharma Marine |
| Omega Protein Corporation |
| GC Rieber Oil |
| Croda International PLC |
| BASF SE |
| DSM-Firmenich |
| GSK plc |
| Others |
Supply & Pricing Matrix
Algal DHA fermentation's emergence as a pediatric and vegan-compatible substitute is simultaneously fragmenting supply geography away from Antarctic marine networks and compressing price premiums for standard-grade fish-oil formulations that cannot match its sustainability credentials.
Pricing Analysis
Volume-discount tiering structures separate prescription-grade ethyl esters for hospital formularies from dietary supplement alternatives, with FDA cGMP compliance and New Drug Application validation serving as the primary price differentiation drivers. Price compression in the standard-grade segment intensifies as algal fermentation scales capture pediatric and vegan-sensitive demand that fish oil cannot serve. Hospital procurement through 340B pricing programs exhibits the lowest price sensitivity, while retail nutraceutical channels face acute margin pressure from unverified supplement competitors.
Supply Chain Analysis
Norway and Peru anchor industrial-scale fish-oil extraction for pharmaceutical-grade feedstock, while Germany concentrates molecular distillation and purification capacity for ethyl ester concentrates. Raw material dependencies center on anchovy and sardine fisheries in the Humboldt Current, Antarctic krill harvests in the Southern Ocean, and specialized gelatin for softgel encapsulation. Single-source vulnerability concentrates in BASF's captive Antarctic krill networks, which feed re-esterified triglyceride production. Distribution runs through pharmaceutical cold chains from the Port of Rotterdam to hospital pharmacy and therapeutics committees across continental Europe and North American integrated delivery networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fish-oil based drugs represent an early-cycle expansion story where cardiovascular protocol penetration in hospital settings creates durable volume commitments that retail channels cannot replicate.
For Market Incumbents: Compound formulary lock-in through pharmacy and therapeutics committee standardization at leading integrated delivery networks like Mayo Clinic and Cleveland Clinic systems. Expand molecular distillation capacity in Germany to preempt DSM-Firmenich's purification standards from capturing the re-esterified triglyceride segment that now challenges ethyl ester bioavailability claims. Deepen backward integration into Antarctic krill sourcing to defend against BASF's supply concentration advantage. For New Entrants and Emerging Players: Pediatric liquid suspension formulation gaps expose white space where swallowing compliance limitations constrain incumbent softgel dominance. Target academic medical centers in Boston and Philadelphia where pediatric wards actively seek dose-titration alternatives for compliance-constrained populations. Pursue Japan's functional food dual-track pathway through METI and PMDA qualified health claims to bypass FDA New Drug Application barriers. For Investors and Strategic Acquirers: The market sits at a clinical-validation phase that favors pharmaceutical-grade purification specialists with established regulatory moats. Long-term viability hinges on EPA-to-DHA ratio standardization outcomes from cardiovascular outcome trials. Acquisition targets should demonstrate molecular distillation infrastructure and EMA centralized marketing authorization compliance. Watch EPA-to-DHA formulation specification updates from guideline committees as the critical inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Pharmaceutical-Grade Purification Scale-Up | DSM-Firmenich's distillation standards force continuous capital reinvestment to maintain FDA compliance tiers. |
| Antarctic Krill Backward Integration | BASF's polar marine sourcing networks create supply security that competing ethyl ester manufacturers cannot replicate. |
| EMA Centralized Marketing Authorization | Real-world safety data submission requirements for renewal disproportionately burden mid-scale European suppliers. |
| Pediatric Liquid Suspension Development | Boston and Philadelphia academic medical centers drive adoption for compliance-constrained geriatric and pediatric populations. |
| Japan Functional Food Dual-Track Positioning | METI and PMDA's qualified health claim pathway enables premium pricing outside FDA prescription drug classification. |
Research Methodology
Cross-validation between primary interviews with cardiology group practice administrators, hospital pharmacy directors, regulatory affairs specialists at marine sourcing enterprises, and formulary committee members anchors the qualitative findings. Secondary validation draws from FDA New Drug Application filings, EMA centralized marketing authorization procedures, ClinicalTrials.gov cardiovascular outcome study registrations, and hospital procurement database extracts. Bottom-up demand modeling from specialty clinic prescribing patterns triangulates against top-down market sizing from pharmaceutical-grade omega-3 production capacity disclosures.
Sensitivity analysis across EPA-to-DHA ratio specification scenarios, algal fermentation substitution rates, and reimbursement policy shifts informs the analytical framework over the projection horizon. Segmentation dimensions include product type, application indication, end-user channel, and dosage form, with regulatory pathway clustering as an additional pharmaceutical-specific dimension. CAGRs derive from institution-level volume commitment trajectories and diagnostic screening protocol expansion rates in managed care networks.
Underlying assumptions cover cardiovascular guideline committee adoption timelines, with deviation risk concentrated in EPA-to-DHA ratio standardization outcomes and Antarctic krill harvest quota adjustments. Forecasts reflect these conditions subject to revision from regulatory pathway bifurcation or marine ecosystem management interventions. Recalibration cycles align with material shifts in cardiovascular outcome trial readouts and EMA pharmacovigilance requirement updates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutraceuticals
Hydrolyzed Bovine Collagen Market
Nutraceuticals
UK Pet Nutraceuticals Market
Nutraceuticals
North America OTC Health Products Market
Nutraceuticals
Healthy Care Coenzyme Q10 Market
Nutraceuticals
Cartino Collagen Market
Nutraceuticals
Micro-Ecological Regulators Market
Nutraceuticals
Oxiracetam Market
Nutraceuticals
Multifunctional Health Pot Market
Nutraceuticals
US Pet Nutraceuticals Market
Nutraceuticals
Ayurvedic Products Market
Nutraceuticals
Coenzyme Q10 Market
Nutraceuticals
North America Effervescent Tablet Market
Nutraceuticals
Nootropics Market
Nutraceuticals
Global Eye Health Supplement Market
Nutraceuticals
Anti-Inflammatory Peptides Market
Nutraceuticals
Eye Health Ingredients Market