
 Asia-Pacific Effervescent Tablet Market | 2026-2036
Asia-Pacific Effervescent Tablet Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Effervescent Tablet Market Outlook
Multi-source API procurement is pivoting toward captive carbonate and citrate sourcing across major manufacturers. Bayer AG leverages its German-Australian supply corridor to sustain cost-competitive bicarbonate inputs. Haleon anchors its regional formulation capacity through dedicated facilities in India and Thailand. Abbott Laboratories differentiates via pharmacy-exclusive distribution partnerships that control shelf positioning in Australian and Chinese retail networks.
Asia-Pacific effervescent tablets are solid dosage forms containing organic acids and carbonate or bicarbonate salts that generate carbon dioxide upon aqueous contact, producing a rapidly absorbed solution for drug or nutrient delivery. The manufacturing process requires controlled humidity environments below critical moisture thresholds to prevent premature effervescent reaction during compression and packaging. Vitamin C formulations occupy the largest volume share due to established consumer familiarity and daily supplementation habits across East Asian markets. Electrolyte variants represent the fastest-expanding category, propelled by sports nutrition demand and tropical climate hydration needs in Southeast Asia. E-commerce distribution channels capture accelerating margin pools as direct-to-consumer subscription models bypass traditional wholesale markups in India and South Korea.
China's NMPA enforces stability testing protocols and excipient sourcing documentation that filter out substandard imports. India's CDSCO mandates BIS certification for effervescent packaging materials, while Australia's TGA imposes strict label claims verification for complementary medicines containing effervescent delivery formats. Stakeholders must monitor evolving ASEAN harmonization efforts for pharmaceutical excipient standards, as regulatory misalignment between member states continues to fragment cross-border product registration strategies.
Market Dynamics
Asia-Pacific effervescent tablet manufacturers face intensifying pressure from NMPA stability protocols that mandate excipient traceability, compressing margins for importers while rewarding captive carbonate sourcing strategies across domestic Chinese and Thai production bases.
Growth Catalysts
- CDSCO packaging mandates:India's BIS certification requirements for effervescent materials are consolidating supplier bases toward certified domestic converters, reducing import dependency for pharmacy chains in Mumbai and Bangalore.
- Aging demographics in Japan and Australia:Nutraceutical applications targeting bone health and immune support are expanding prescription-adjacent consumption patterns among populations over 65.
- Sports nutrition hydration demand:Electrolyte variants are capturing tropical climate use cases across Southeast Asia, with Vietnam and Indonesia showing concentrated uptake among marathon and football participants.
Market Restraints
- Carbonate input cost volatility:Sodium bicarbonate spot pricing fluctuates with energy-intensive Solvay process economics, squeezing formulation margins for non-integrated manufacturers.
- Humidity-controlled production capex:Compression and packaging facilities require sub-30% relative humidity environments, creating capital barriers for regional entrants lacking climate infrastructure.
- ASEAN regulatory fragmentation:Divergent pharmaceutical excipient standards across member states force redundant registration filings, delaying product launches in Thailand versus Vietnam versus Philippines.
Strategic Opportunities
- India e-commerce subscription models:Direct-to-consumer platforms in Delhi and Hyderabad are bypassing wholesale markups, capturing margin pools previously held by traditional pharmacy distributors.
- China OTC pathway streamlining:NMPA's expedited review tracks for established effervescent formulations are shortening time-to-market for vitamin C and calcium repositioning candidates.
- South Korean functional food convergence:Beauty-from-within positioning is merging effervescent collagen delivery with established K-beauty retail networks in Seoul and Busan.
Industry Challenges
- Moisture barrier formulation expertise:The shortage of pharmaceutical engineers skilled in effervescent stability modeling is constraining R&D throughput for regional innovators.
- Cross-border cold chain integrity:Temperature excursions during India-China API transit are degrading carbonate salt reactivity, forcing redundant quality testing at receiving facilities.
- Legacy ERP integration:Mid-tier manufacturers struggle to connect batch-level humidity monitoring systems with enterprise traceability platforms required by Australian TGA audit protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Effervescent Tablet Market |
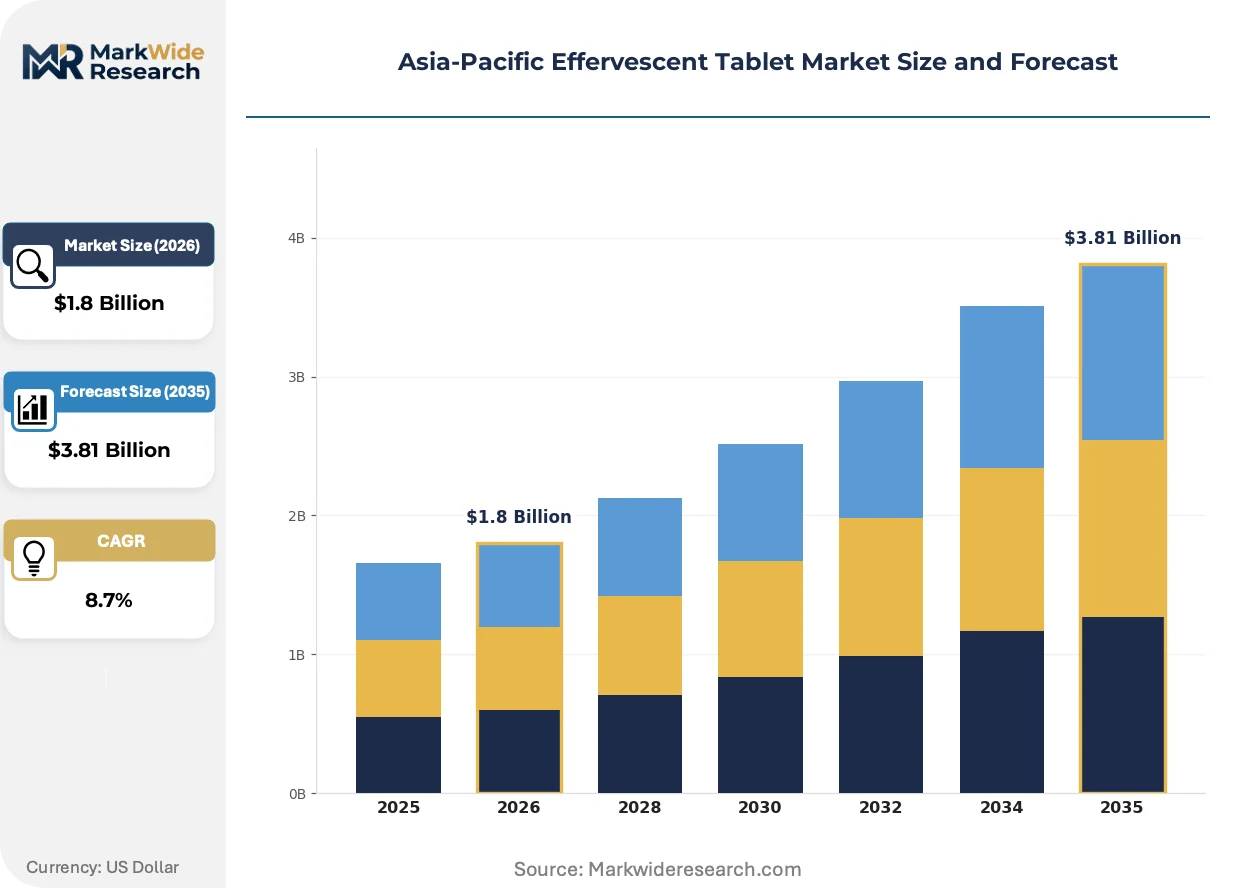
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vitamin C, Electrolyte, Antacid, Aspirin End User: Pharmacies, Hospitals, Supermarkets, Online Retailers Formulation Type: Sugar-Free, Caffeine-Enhanced, Herbal, Custom Blends Distribution Channel: Direct Sales, Wholesale, E-commerce, Retail Outlets |
| Companies Covered | GlaxoSmithKline plc, Bayer AG, Reckitt Benckiser Group plc, Sanofi S.A., Abbott Laboratories, Haleon, Pfizer Inc., Novartis AG, Perrigo Company plc, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Effervescent Tablet Market Strategic Shifts
Asia-Pacific effervescent tablet production is pivoting toward moisture-resistant packaging technologies and direct-to-consumer channel architectures, compressing traditional wholesale hierarchies while elevating formulation stability standards.
Effervescent tablet manufacturers are integrating silica-based desiccant-in-capsule systems that maintain sub-critical moisture levels through tropical distribution cycles. Japanese and Australian nutraceutical brands are adopting these systems fastest, compressing shelf-life risk premiums that previously inflated working capital requirements for Southeast Asian exporters.
China's NMPA is tightening excipient sourcing documentation requirements under revised stability testing protocols. The industrial consequence is a filtering effect that disadvantages small-scale importers lacking batch-level carbonate provenance records. Vitamin C and electrolyte categories face the steepest compliance ramps, with domestic Chinese manufacturers responding through captive mining partnerships in Qinghai and Sichuan.
Subscription-based replenishment models are displacing pharmacy-centric purchasing across Indian and South Korean urban markets. Direct-to-consumer platforms in Bengaluru and Seoul are capturing recurring revenue streams previously fragmented across 40,000+ independent retail counters. This channel rotation is most visible in electrolyte and immunity-positioned SKUs, where convenience positioning outweighs price sensitivity among 25-40 year-old professional demographics.
Asia-Pacific Effervescent Tablet Market Segmentation
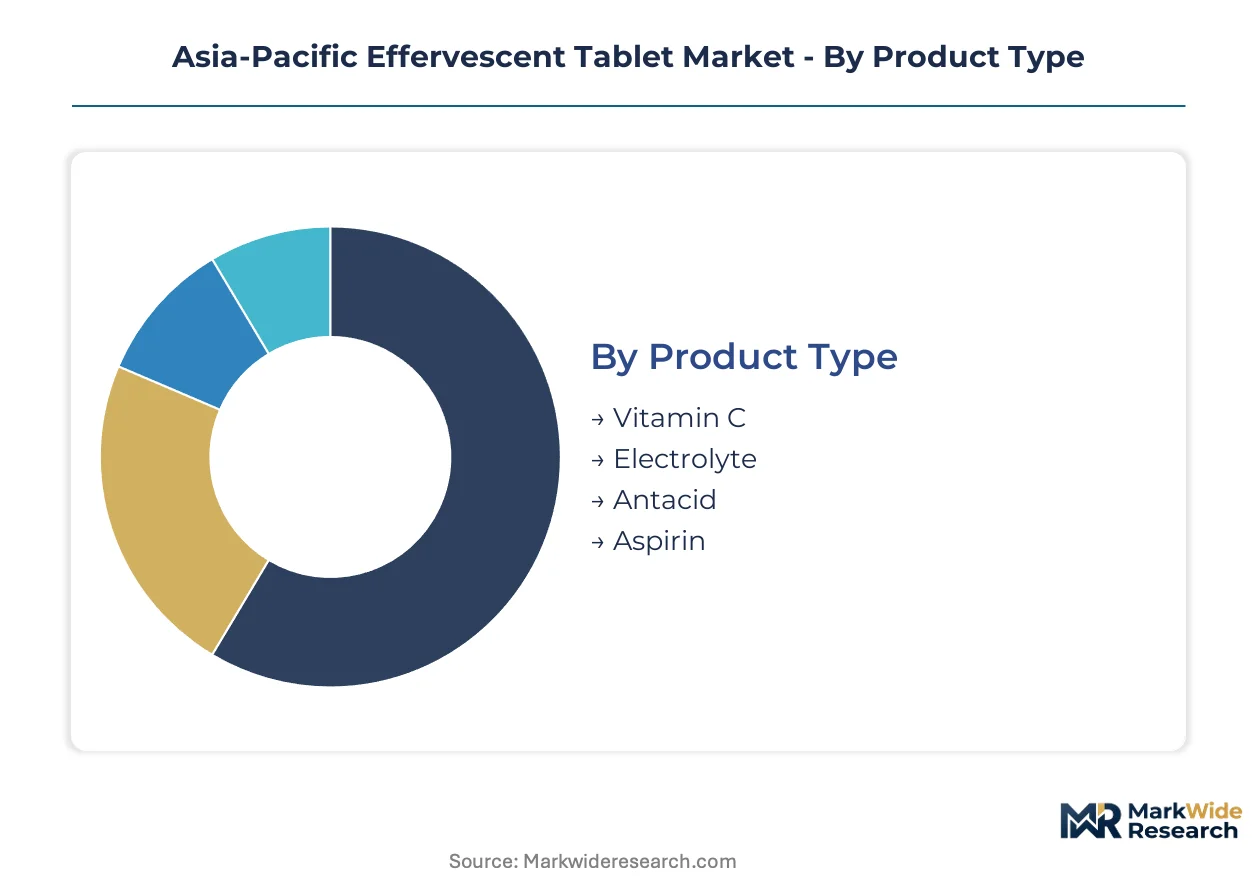
Effervescent tablet segmentation in Asia-Pacific reflects divergent capital requirements across manufacturing configurations. Humidity-controlled production environments and excipient sourcing strategies create tiered investment barriers that reshape competitive positioning by segment.
Product Type:
Vitamin C formulations demand the heaviest upfront investment due to stability testing protocols and carbonate sourcing documentation required by China's NMPA.
- Vitamin C:Ascorbic acid combined with sodium bicarbonate and citric acid forms the foundational effervescent chemistry. Daily supplementation habits across Japan, South Korea, and urban China sustain volume concentration, though NMPA excipient traceability mandates compress margins for non-integrated producers.
- Electrolyte:Sodium, potassium, and magnesium salts targeting hydration recovery generate carbon dioxide upon dissolution for rapid absorption. Marathon and football participants in Vietnam and Indonesia are driving concentrated uptake, with tropical climate use cases expanding faster than temperate-market alternatives.
- Antacid:Calcium carbonate and magnesium hydroxide blends neutralize gastric acid through effervescent action. Pharmacy chains in Mumbai and Bangalore stock these as prescription-adjacent digestive remedies.
- Aspirin:Acetylsalicylic acid effervescent formats accelerate absorption for cardiovascular and pain relief applications. Australia's TGA imposes strict label claims verification for these complementary medicine formats.
Vitamin C absorbs the bulk of installed capacity; electrolyte variants are expanding most quickly.
End User:
Customer type determines working capital intensity, with inventory holding periods and payment terms varying sharply across institutional versus retail channels.
- Pharmacies:India's CDSCO-mandated BIS certification for packaging materials consolidates supplier bases toward certified domestic converters. Mumbai and Bangalore pharmacy chains are reducing import dependency through localized sourcing.
- Hospitals:Clinical procurement of electrolyte and antacid formulations for inpatient hydration and gastroenterology protocols. Australia's public hospital networks specify TGA-registered products exclusively.
- Supermarkets:Mass-market vitamin C placement in East Asian retail formats targets impulse supplementation purchases. Shelf positioning negotiations in Australian chains require pharmacy-exclusive distribution partnerships.
- Online Retailers:Direct-to-consumer subscription models in Delhi and Hyderabad bypass wholesale markups previously captured by traditional distributors.
Pharmacies command the deepest inventory commitments; online retailers are climbing the fastest as channel share rotates toward digital platforms.
Formulation Type:
Ingredient complexity drives margin stratification, with premium positioning tied to certification thresholds and clean-label positioning.
- Sugar-Free:Aspartame or stevia-sweetened alternatives targeting diabetic and weight-conscious demographics. Japan's METI guidelines on functional food labeling support premium positioning for these variants.
- Caffeine-Enhanced:Anhydrous caffeine integration for energy-positioned effervescent delivery. South Korean functional food convergence is merging these formats with K-beauty retail networks in Seoul.
- Herbal:Botanical extracts including ginseng, ginger, and turmeric combined with effervescent bases. India's traditional medicine acceptance creates distribution synergies with Ayurveda-positioned product lines.
- Custom Blends:Bespoke formulations combining multiple actives for specific demographic targeting. Contract manufacturers in Thailand and India are building dedicated capacity for these specialized runs.
Sugar-free formulations hold the largest revenue pool; caffeine-enhanced variants are gaining share fastest among professional demographics aged 25-40.
Distribution Channel:
Channel selection determines margin capture and regulatory exposure, with direct models requiring traceability infrastructure that wholesale intermediaries traditionally obscured.
- Direct Sales:Manufacturer-to-institutional contracts for hospital and corporate wellness programs. Australia's TGA audit protocols demand batch-level humidity monitoring integration with enterprise traceability platforms.
- Wholesale:Traditional pharmacy distributor networks fragment margin pools across 40,000+ independent retail counters in India. Working capital intensity is highest in this channel due to extended payment terms.
- E-commerce:Subscription-based replenishment platforms in Bengaluru and Seoul capture recurring revenue streams. These direct-to-consumer architectures bypass markups that previously inflated end-user pricing.
- Retail Outlets:Brick-and-mortar pharmacy and supermarket placement requiring shelf positioning investments. China's NMPA streamlined approval pathways are shortening time-to-market for OTC effervescent candidates in these channels.
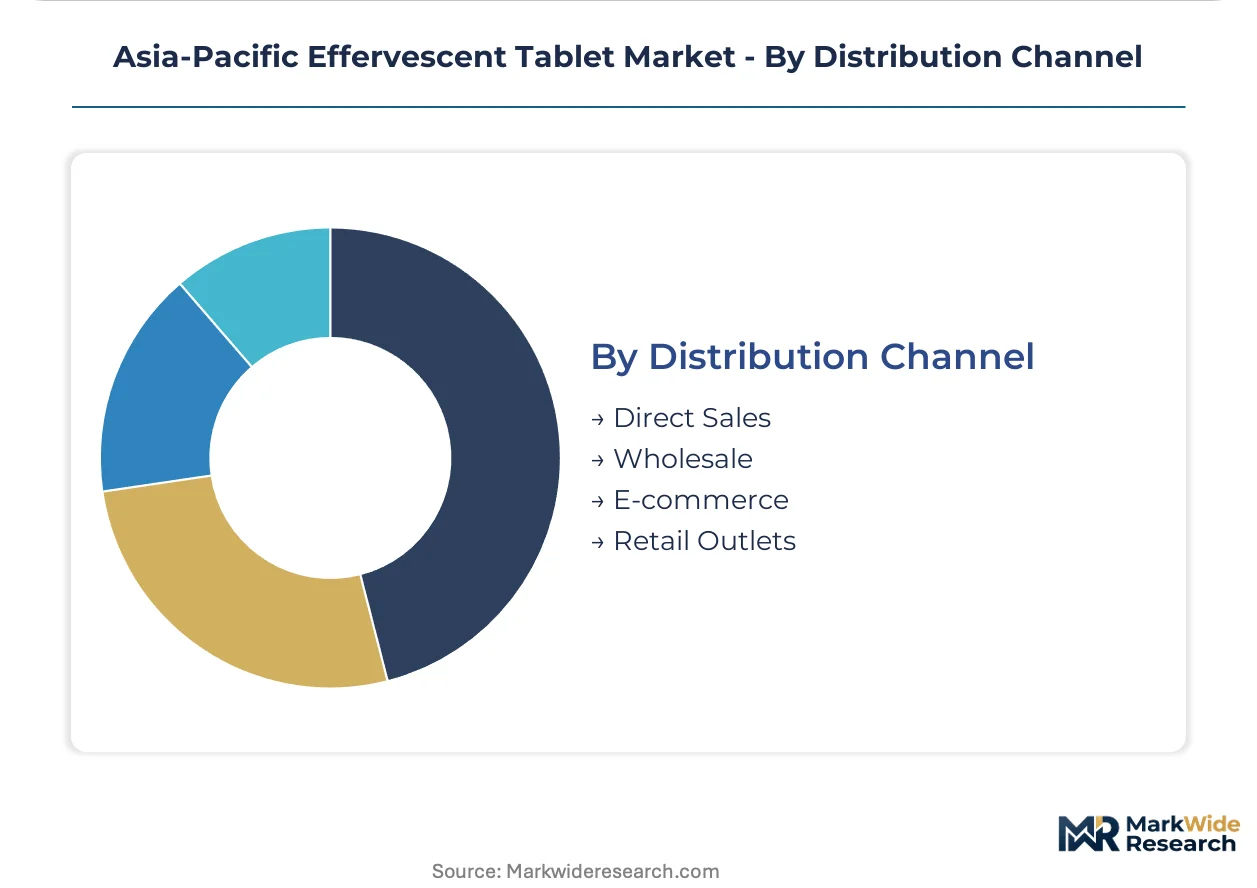
Wholesale channels still absorb the majority of volume throughput; e-commerce is expanding most quickly as subscription models displace pharmacy-centric purchasing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in China's urban pharmacy networks and India's e-commerce corridors, with regulatory harmonization efforts creating divergent compliance burdens across national boundaries.
China
NMPA stability testing protocols and excipient sourcing documentation filter substandard imports while rewarding domestic carbonate producers. Vitamin C and electrolyte categories face steep compliance ramps. Captive mining partnerships in Qinghai and Sichuan secure bicarbonate supply chains for integrated manufacturers.
Japan
Aging demographics over 65 drive nutraceutical consumption for bone health and immune support. METI functional food labeling guidelines enable premium positioning for sugar-free variants. Tokyo-Osaka pharmacy chains stock prescription-adjacent effervescent formats alongside traditional supplements.
India
CDSCO-mandated BIS certification for packaging materials consolidates supplier bases toward certified domestic converters. Mumbai and Bangalore pharmacy chains reduce import dependency through localized sourcing. Direct-to-consumer subscription platforms in Delhi and Hyderabad bypass wholesale markups.
Australia
TGA label claims verification requirements impose strict audit protocols for complementary medicines. Public hospital networks specify TGA-registered products exclusively for inpatient hydration protocols. Melbourne and Sydney retail networks require pharmacy-exclusive distribution partnerships for shelf positioning.
South Korea
Beauty-from-within positioning merges effervescent collagen delivery with established K-beauty retail networks in Seoul and Busan. MFDS regulatory frameworks support functional food convergence. Caffeine-enhanced variants gain share among 25-40 year-old professional demographics.
Asia-Pacific Effervescent Tablet Market Competitive Environment
Capacity expansion dominates the current landscape as manufacturers retrofit humidity-controlled facilities to meet NMPA and TGA stability requirements. The vendor base clusters around three tiers: integrated pharmaceutical conglomerates with captive carbonate sourcing, regional formulation specialists serving single-country markets, and contract manufacturers building dedicated effervescent lines. Strategic partnerships between API producers and packaging converters accelerate, while portfolio diversification into electrolyte and collagen categories reshapes revenue mixes.
Within the integrated pharmaceutical tier, Bayer AG and Haleon occupy positions anchored by regional formulation infrastructure, while Abbott Laboratories exemplifies pharmacy-exclusive distribution strategies. These entities represent archetypes of supply chain control versus channel access, with each approach carrying distinct capital intensity profiles and regulatory exposure levels across NMPA, CDSCO, and TGA jurisdictions.
| Leading Market Players |
|---|
| GlaxoSmithKline plc |
| Bayer AG |
| Reckitt Benckiser Group plc |
| Sanofi S.A. |
| Abbott Laboratories |
| Haleon |
| Pfizer Inc. |
| Novartis AG |
| Perrigo Company plc |
| Others |
Value Chain & Pricing Dynamics
Certification-grade bifurcation between TGA-registered premium formulations and unbranded commodity imports manifests in divergent margin structures and sourcing architectures across the Asia-Pacific effervescent tablet market. NMPA traceability mandates compress pricing power for non-integrated importers while rewarding domestic Chinese and Thai producers with captive carbonate supply, creating a structural wedge between compliance-cost-burdened and vertically anchored competitors.
Pricing Analysis
Volume throughput concentrates in standard-grade vitamin C formats where per-unit margins thin under carbonate input cost volatility, while premium electrolyte and collagen-positioned SKUs in Japan and South Korea sustain wider spreads through METI and MFDS functional food certifications. Price differentiation hinges on excipient provenance documentation and humidity-controlled production capex, with NMPA stability protocols intensifying cost compression for import-dependent manufacturers. Pharmacy chains in Mumbai and Bangalore exhibit acute price sensitivity, whereas direct-to-consumer subscription platforms in Seoul capture convenience premiums from professional demographics aged 25-40.
Supply Chain Analysis
CDSCO-mandated BIS certification for packaging materials gates supplier participation, consolidating sourcing toward certified domestic converters in India and Thailand while filtering out substandard imports. Sodium bicarbonate feedstock draws from captive mining partnerships in Qinghai and Sichuan, with citrate inputs anchored in regional fermentation capacity. Single-source vulnerability concentrates in carbonate salt reactivity degradation during India-China API transit, forcing redundant quality testing. Distribution runs through e-commerce subscription architectures in Bengaluru and Delhi that displace traditional wholesale hierarchies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
NMPA stability testing protocols erect a cost-of-compliance moat that filters marginal competitors while entrenching integrated domestic producers, transforming regulatory burden into sustainable competitive advantage for qualified players.
For Market Incumbents: Anchor market position through backward integration into Qinghai and Sichuan carbonate mining partnerships that neutralize Solvay process pricing volatility, while retrofitting humidity-controlled facilities to TGA audit specifications that lock out regional entrants lacking climate infrastructure. Defend against direct-to-consumer subscription displacement by securing pharmacy-exclusive distribution partnerships in Australian and Chinese retail networks. For New Entrants and Emerging Players: NMPA's expedited OTC review tracks for established effervescent formulations in China open a window for vitamin C and calcium repositioning candidates that bypass lengthy approval timelines. Target white-space opportunities in South Korean beauty-from-within collagen delivery through K-beauty retail network partnerships, and exploit underpenetrated electrolyte demand among marathon participants in Vietnam and Indonesia through tropical climate-specific hydration positioning. For Investors and Strategic Acquirers: Re-rating potential sits with integrated pharmaceutical conglomerates possessing captive carbonate sourcing and NMPA-compliant manufacturing footprints, given accelerating channel rotation toward direct-to-consumer platforms that reward supply chain control. Monitor ASEAN harmonization progress on pharmaceutical excipient standards as the inflection signal—successful alignment would compress cross-border registration costs and unlock portfolio scalability across Thailand, Vietnam, and Philippines.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Carbonate Sourcing | Backward integration into Qinghai mining partnerships neutralizes Solvay process input volatility for NMPA-compliant manufacturers. |
| Humidity-Controlled Facility Retrofit | Sub-30% relative humidity production environments satisfy TGA audit protocols that filter regional entrants lacking capital intensity. |
| Direct-to-Consumer Platform Launch | Subscription models in Bengaluru and Seoul bypass wholesale markups previously captured by 40,000+ independent pharmacy counters. |
| Beauty-from-Within Collagen Positioning | Functional food convergence with K-beauty retail networks in Seoul and Busan opens premium pricing tiers among professional demographics. |
| ASEAN Excipient Standard Harmonization | Cross-border registration alignment would compress redundant filing costs across Thailand, Vietnam, and Philippines regulatory jurisdictions. |
Study Parameters
Independent corroboration across CDSCO regulatory filings, NMPA stability protocol documentation, and TGA complementary medicine registers underwrites the qualitative findings in this analysis. Primary interviews with pharmaceutical manufacturing executives, packaging material procurement leads, pharmacy chain category managers, and e-commerce platform operators combined with secondary validation from BIS certification records, ASEAN harmonization working papers, and METI functional food labeling guidelines. Bottom-up capacity assessments and top-down demand modeling triangulate volume and value estimates.
Comparable-period anchoring to historical NMPA approval timelines and CDSCO packaging mandate implementation phases structured the forecast window across the analysis window. Segmentation dimensions modeled include product type chemistry, end-user channel configuration, formulation complexity tier, and distribution architecture. CAGRs derive from regression analysis against aging demographic trajectories in Japan and Australia, sports nutrition penetration rates in Southeast Asia, and e-commerce subscription adoption curves in India and South Korea.
The model assumes a particular technology adoption path for silica-based desiccant-in-capsule moisture barrier systems; alternative pathways for active packaging would alter the outlook for shelf-life extension and tropical distribution viability. Forecasts reflect assumptions regarding NMPA enforcement consistency, ASEAN regulatory convergence velocity, and carbonate input cost trajectories. A model refresh is warranted upon material change in ASEAN excipient harmonization treaty ratification or NMPA stability protocol revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutraceuticals
High Potency Apis Market
Nutraceuticals
Cissus Quadrangularis Market
Nutraceuticals
Chondroitin Sulfate Market
Nutraceuticals
Coenzyme Q10 Market
Nutraceuticals
Asia-Pacific Pet Nutraceuticals Market
Nutraceuticals
US Pet Nutraceuticals Market
Nutraceuticals
Hydrolyzed Bovine Collagen Market
Nutraceuticals
PMS and Menstrual Health Supplements Market
Nutraceuticals
Global Synbiotics Market
Nutraceuticals
Anti-Inflammatory Peptides Market
Nutraceuticals
Healthy Care Coenzyme Q10 Market
Nutraceuticals
North America OTC Health Products Market
Nutraceuticals
Postbiotics Market
Nutraceuticals
Middle East and Africa Effervescent Tablet Market
Nutraceuticals
UK Pet Nutraceuticals Market
Nutraceuticals
Cognitive Health Ingredients Market