
 Hematopoietic Agents Market | 2026-2036
Hematopoietic Agents Market Size, Share, and Industry Trends Forecast 2026-2036
Hematopoietic Agents Market Foresight
Oncology clinics is redrawing demand patterns as the fastest-expanding buyer archetype for hematopoietic agents, overtaking traditional hospital pharmacy procurement. Amgen Inc dominates the erythropoietin segment with decades of manufacturing scale and clinical data accumulation. Pfizer Inc leverages its global distribution infrastructure to sustain biosimilar penetration across European and North American markets. Novartis AG anchors its position through specialized oncology support portfolios that integrate G-CSF therapies into comprehensive cancer care protocols.
Hematopoietic agents comprise recombinant protein biologics and biosimilars that stimulate blood cell production through erythropoietin receptor agonism, granulocyte colony-stimulating factor signaling, or thrombopoietin pathway activation, typically manufactured via mammalian cell culture expression systems with glycosylation profiles critical for in vivo half-life and immunogenicity profiles. These agents serve primary commercial purposes in reversing chemotherapy-induced cytopenias, reducing transfusion dependency, and accelerating engraftment following hematopoietic stem cell transplantation. Erythropoietin products occupy the most mature margin pool with established reimbursement but face accelerating biosimilar erosion, while granulocyte colony-stimulating factor variants represent the fastest-growing structural segment driven by prophylactic adoption in dose-dense oncology regimens. Subcutaneous injection delivery sustains its dominance due to patient self-administration feasibility and reduced infusion center burden.
FDA, EMA, and WHO prequalification standards collectively shape hematopoietic agent development through biosimilar interchangeability designations, batch consistency requirements, and immunogenicity surveillance mandates that determine market access speed and competitive substitution potential. The FDA's oncology center of excellence and EMA's biosimilar scientific committees enforce comparability exercise rigor that directly impacts development timelines and commercial launch sequencing for follow-on biologics. Stakeholders must monitor evolving interchangeability legislation at the US state level and EMA's refined immunogenicity guidance to anticipate substitution policy shifts that will reshape procurement negotiations and formulary positioning.
Market Dynamics
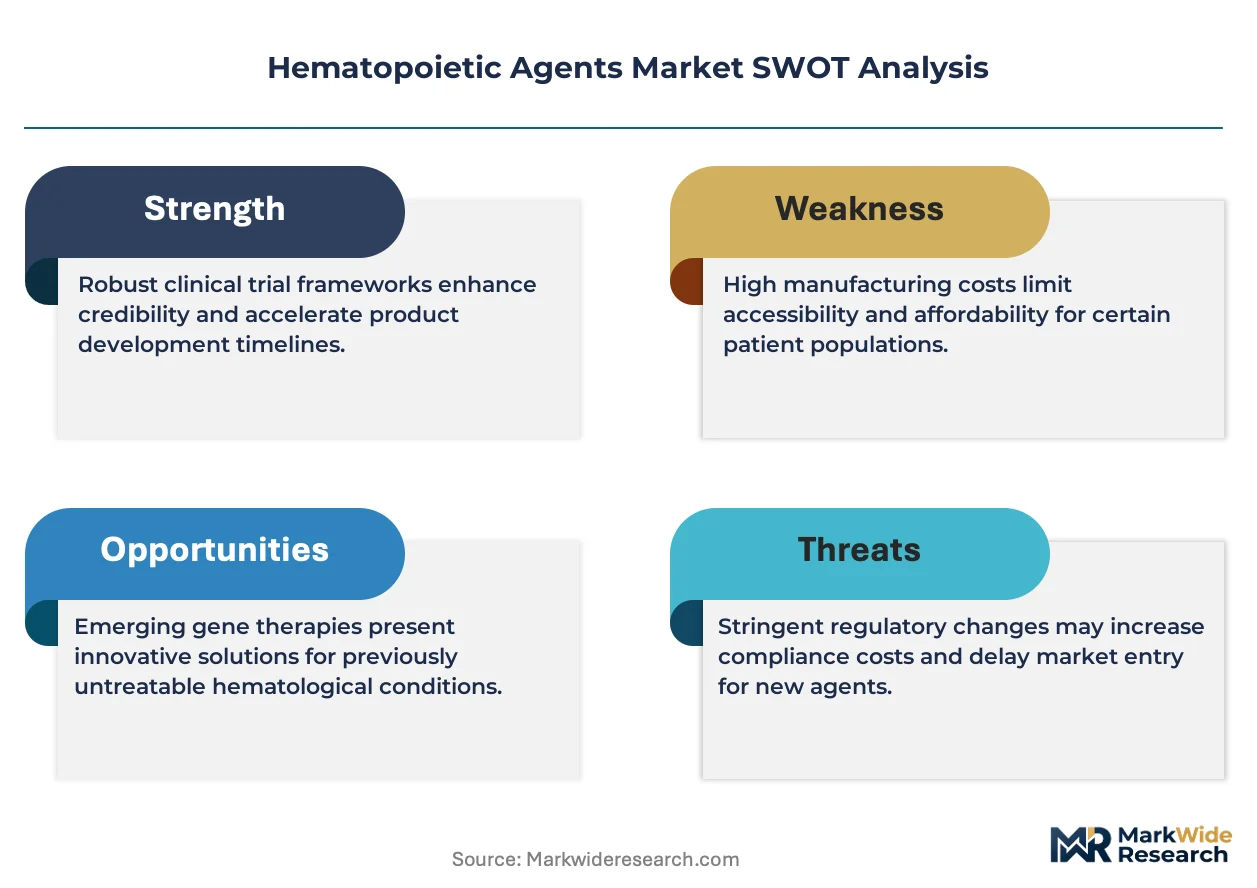
Biosimilar interchangeability designations from the FDA and EMA are compressing originator pricing power while expanding patient access across oncology and transplantation settings.
Growth Catalysts
- Dose-dense chemotherapy protocols:Oncology clinics in the United States and Germany are expanding prophylactic G-CSF administration to support accelerated treatment cycles, driving volume expansion.
- EMA biosimilar scientific committee guidance:Streamlined comparability exercises for erythropoietin biosimilars are accelerating European market entry and therapeutic substitution.
- Stem cell transplantation infrastructure:Japan's expansion of hematopoietic stem cell programs is concentrating demand for engraftment-accelerating agents in tertiary care centers.
Market Restraints
- Mammalian cell culture input costs:Glycosylation-grade media and serum components face price volatility that squeezes manufacturing margins for recombinant protein production.
- Supply concentration in South Korean contract manufacturing:A limited pool of CDMOs with validated mammalian expression systems creates bottlenecks for biosimilar developers seeking capacity.
- Immunogenicity surveillance mandates:FDA requirements for long-term antibody monitoring extend post-market commitments and elevate regulatory maintenance burdens.
Strategic Opportunities
- Home administration subcutaneous devices:Pre-filled pen and auto-injector formats for G-CSF therapies open direct-to-patient channels that bypass infusion center dependency.
- India's oncology infrastructure buildout:Underpenetrated chemotherapy support markets in tier-2 cities present first-mover positioning for biosimilar erythropoietin entrants.
- WHO prequalification pathway:Emerging market procurement programs are creating volume anchors for manufacturers achieving international reference standard status.
Industry Challenges
- Glycoprotein analytical capability scarcity:Batch consistency testing for glycosylation microheterogeneity requires specialized mass spectrometry expertise that outstrips current workforce supply.
- Cold chain integrity at last-mile distribution:Temperature excursions during subcutaneous product delivery to outpatient oncology clinics compromise protein stability and trigger rejection.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hematopoietic Agents Market |
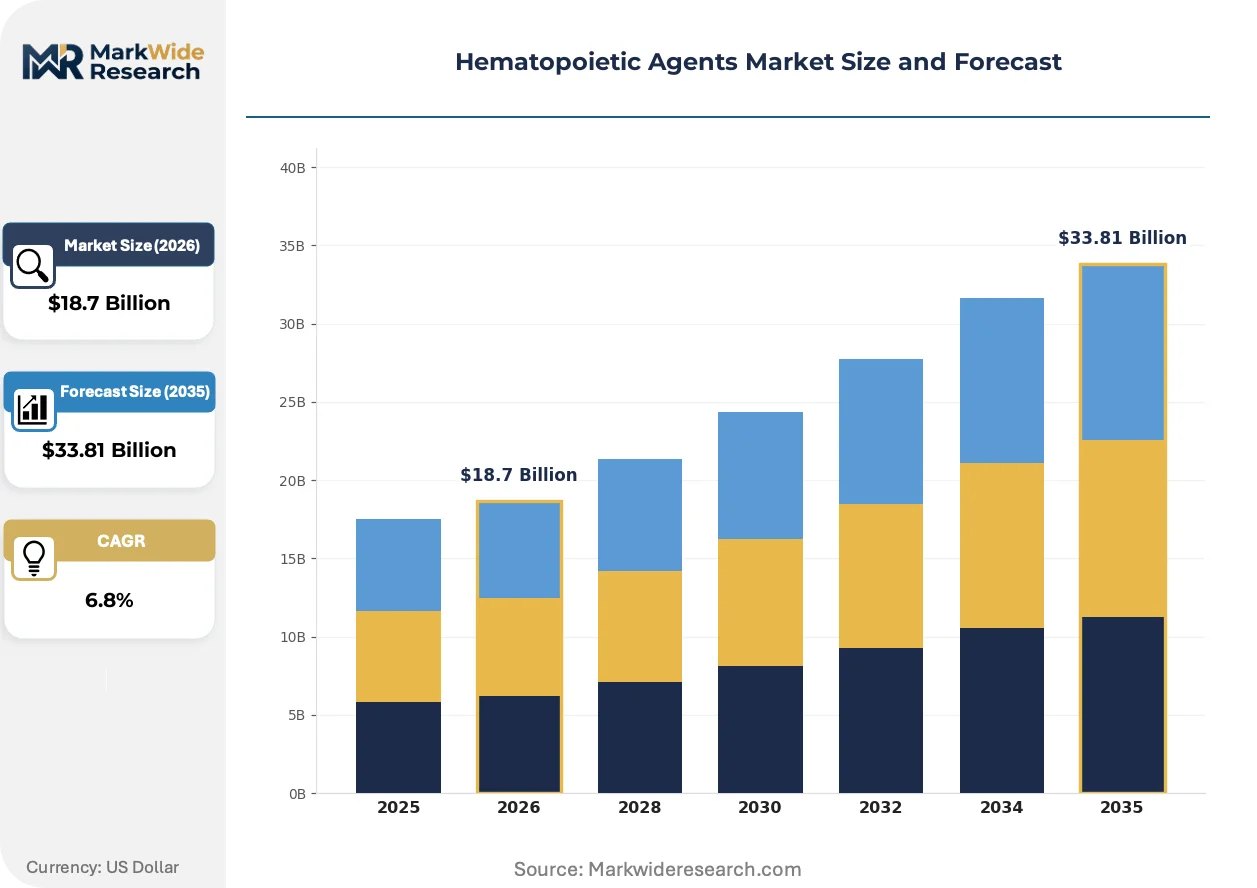
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Erythropoietin, Granulocyte Colony-Stimulating Factor, Thrombopoietin, Stem Cell Factor Application: Anemia Treatment, Oncology Support, Bone Marrow Disorders, Organ Transplantation End User: Hospitals, Clinics, Outpatient Care Centers, Research Laboratories Delivery Mode: Subcutaneous Injection, Intravenous Injection, Oral Administration, Intramuscular Injection |
| Companies Covered | F. Hoffmann-La Roche Ltd, Pfizer Inc, Sanofi, Novartis AG, GSK plc, Teva Pharmaceutical Industries Ltd, Merck & Co., Inc, AbbVie Inc, Amgen Inc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hematopoietic Agents Market Shifts & Advancements
Manufacturing science and delivery modality convergence are compressing treatment settings from hospital infusion centers toward ambulatory and home-based administration.
Long-acting G-CSF pegylation technologies are extending neutrophil recovery duration from single injections. Oncology clinics in the United States are adopting these formulations to eliminate multi-day dosing schedules. This innovation is miniaturizing the clinical footprint required for chemotherapy support, enabling same-day discharge protocols.
EMA's refined immunogenicity guidance for biosimilar monoclonal antibodies is tightening analytical comparability thresholds. Developers must now demonstrate equivalent T-cell epitope mapping between originator and follow-on products. European erythropoietin biosimilar sponsors are responding with enhanced glycan profiling investments to preempt regulatory queries.
Hospital pharmacy buyers are consolidating hematopoietic agent procurement through integrated delivery networks. Group purchasing organizations are displacing individual hospital tenders with multi-year sole-source agreements tied to oncology volume commitments. This concentration is most visible in United States metropolitan markets where IDN penetration exceeds sixty percent of acute care beds.
Hematopoietic Agents Market Segmentation
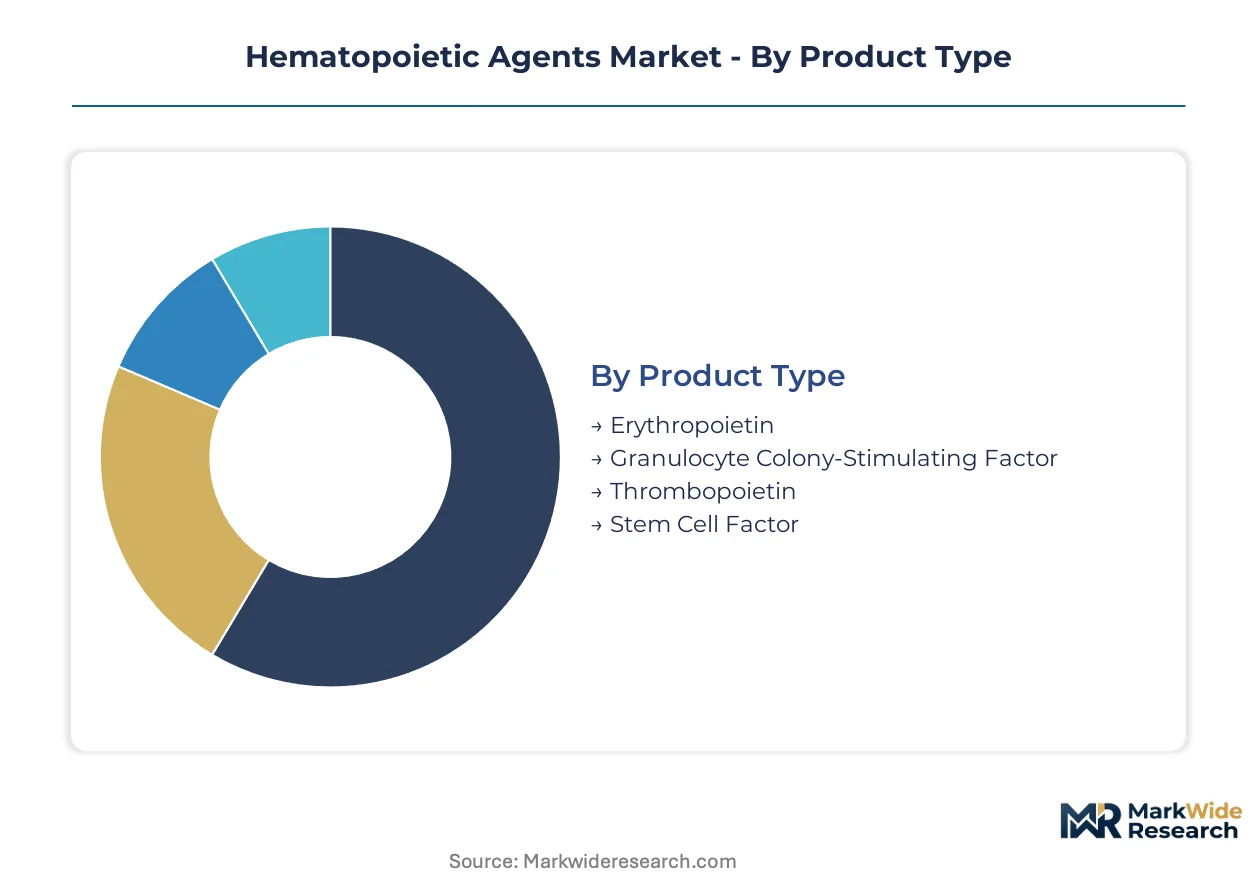
Hematopoietic agents fragment across four structural dimensions that determine reimbursement pathways, procurement channels, and competitive substitution intensity. Each segmentation layer reveals distinct margin profiles and vulnerability to biosimilar erosion.
Product Type:
Erythropoietin faces the most acute biosimilar substitution pressure among all product categories, with multiple approved follow-on biologics compressing originator pricing across every major market.
- Erythropoietin:Recombinant glycoprotein stimulating erythrocyte production through bone marrow erythropoietic progenitor activation. Hospital procurement in Germany and the United States is consolidating around biosimilar tenders that displace originator contracts.
- Granulocyte Colony-Stimulating Factor:Glycosylated cytokine accelerating neutrophil proliferation and maturation via CSF3 receptor signaling. Oncology clinics in Japan are expanding prophylactic administration for dose-dense chemotherapy regimens, driving volume concentration.
- Thrombopoietin:Megakaryocyte lineage stimulant for platelet production recovery. Post-transplant thrombocytopenia management in tertiary care centers sustains demand.
- Stem Cell Factor:C-Kit ligand supporting hematopoietic stem cell survival and expansion. Research laboratory procurement for ex vivo cell culture applications anchors the segment.
Erythropoietin anchors the volume base while Granulocyte Colony-Stimulating Factor gains share at the steepest rate.
Application:
Cost tier stratification separates acute intervention indications from chronic maintenance protocols, with reimbursement intensity varying by treatment setting and disease severity.
- Anemia Treatment:Chronic renal disease and chemotherapy-induced anemia reversal through erythropoietin receptor agonism. Dialysis centers in the United States concentrate procurement through bundled payment mechanisms.
- Oncology Support:Cytopenia prophylaxis and neutropenia recovery acceleration during myelosuppressive chemotherapy. German oncology clinics are expanding G-CSF protocol adoption for accelerated treatment cycles.
- Bone Marrow Disorders:Aplastic anemia and myelodysplastic syndrome management through multilineage stimulation. Tertiary referral centers in Japan concentrate specialized demand.
- Organ Transplantation:Engraftment acceleration and graft-versus-host disease prophylaxis in hematopoietic stem cell transplantation. Major academic medical centers anchor procurement volume.
Oncology Support commands the largest revenue pool while Bone Marrow Disorders expands most quickly through transplant infrastructure buildout.
End User:
Customer type concentration is shifting from inpatient pharmacy procurement toward ambulatory administration settings that enable patient self-management.
- Hospitals:Inpatient infusion center administration for acute cytopenia and transplantation support. Integrated delivery networks in the United States are consolidating hematopoietic agent procurement through sole-source agreements.
- Clinics:Outpatient oncology and nephrology administration with subcutaneous self-injection training. Community oncology practices in Germany are expanding G-CSF prophylaxis protocols.
- Outpatient Care Centers:Ambulatory infusion and home nursing support for chronic anemia management. Dialysis chains are verticalizing erythropoietin administration into captive treatment settings.
- Research Laboratories:Ex vivo stem cell expansion and cell therapy manufacturing applications. Academic medical centers and contract research organizations anchor demand.
Hospitals retain the dominant procurement volume while Clinics capture the steepest expansion trajectory through same-day discharge protocols.
Delivery Mode:
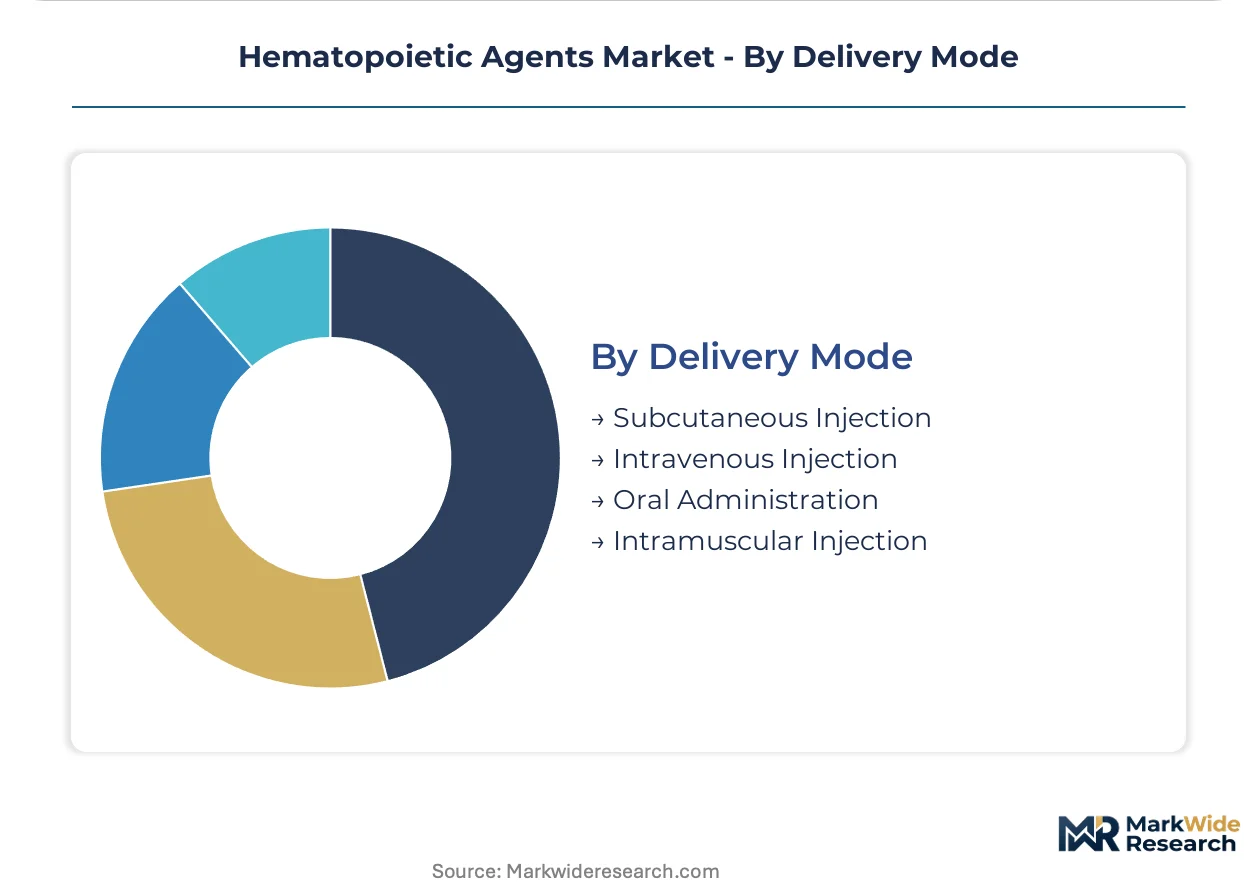
Supply concentration in pre-filled delivery systems is displacing traditional vial-and-syringe formats across all administration settings.
- Subcutaneous Injection:Self-administered cytokine delivery via pre-filled syringes and auto-injectors. Home administration feasibility in the United States is reducing infusion center dependency.
- Intravenous Injection:Hospital-based infusion for acute cytopenia and transplantation settings. Tertiary care centers in Japan maintain IV protocols for high-risk patients.
- Oral Administration:Small-molecule thrombopoietin receptor agonists for chronic platelet disorders. Specialty pharmacy distribution channels concentrate access.
- Intramuscular Injection:Alternative depot delivery for patients with compromised subcutaneous tissue integrity. Limited to specific clinical scenarios.
Subcutaneous Injection dominates administration volume while Oral Administration climbs the fastest through patient convenience differentiation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Contract manufacturing capacity for mammalian cell culture concentrates in South Korean CDMOs, creating geographic chokepoints for biosimilar developers. FDA and EMA regulatory pathways diverge in interchangeability designation rigor, fragmenting launch sequencing across Atlantic markets.
United States
Oncology clinics in Texas and Florida are expanding prophylactic G-CSF protocols for dose-dense chemotherapy regimens. FDA interchangeability designations for erythropoietin biosimilars are accelerating therapeutic substitution in Medicare Part B reimbursement. The Boston-Cambridge corridor anchors specialized hematopoietic stem cell transplantation programs driving engraftment agent demand.
Germany
Community oncology practices in Bavaria and North Rhine-Westphalia are consolidating G-CSF procurement through regional purchasing cooperatives. EMA biosimilar scientific committee guidance on glycan profiling is tightening comparability thresholds for erythropoietin follow-on products. The Rhine-Main biopharma cluster hosts contract manufacturing capacity serving European biosimilar developers.
Japan
Tertiary care centers in Tokyo and Osaka are expanding hematopoietic stem cell transplantation infrastructure for aging-related blood disorders. PMDA accelerated approval pathways for G-CSF biosimilars are compressing regulatory review timelines versus originator reference products. The Kansai region concentrates domestic mammalian cell culture manufacturing for regional supply security.
India
Tier-2 city oncology infrastructure in Maharashtra and Gujarat is creating first-mover positioning opportunities for biosimilar erythropoietin entrants. CDSCO streamlined biosimilar approval frameworks are reducing regulatory lag versus FDA and EMA precedents. The Hyderabad-Visakhapatnam pharmaceutical corridor is scaling recombinant protein manufacturing capacity for export markets.
South Korea
CDMOs in Songdo and Osong are capturing contract manufacturing demand from global biosimilar developers seeking validated mammalian expression systems. MFDS biosimilar guidelines aligned with ICH standards are positioning domestic sponsors for WHO prequalification. The Incheon free economic zone concentrates cold chain logistics infrastructure for biologic distribution.
Hematopoietic Agents Market Competitive Landscape
Concentration sits with diversified biopharmaceutical conglomerates that anchor erythropoietin and G-CSF segments through decades of clinical data accumulation. Three archetypes define competitive positioning: originator biologic developers defending margin pools through lifecycle management, biosimilar specialists exploiting regulatory pathway efficiencies, and integrated oncology portfolio players bundling hematopoietic agents into comprehensive care protocols. M&A activity targets specialized cell therapy manufacturing capabilities, while capacity expansion concentrates in South Korean contract manufacturing partnerships.
Among Swiss-based pharmaceutical conglomerates, F. Hoffmann-La Roche Ltd and Novartis AG exemplify integrated oncology portfolio archetypes that bundle hematopoietic support therapies into comprehensive cancer care protocols. Amgen Inc represents the originator biologic developer archetype, anchoring the erythropoietin segment through accumulated manufacturing scale and clinical evidence repositories. Pfizer Inc sits within the biosimilar penetration tier, leveraging global distribution infrastructure to sustain follow-on biologic uptake across European and North American procurement channels.
| Leading Market Players |
|---|
| F. Hoffmann-La Roche Ltd |
| Pfizer Inc |
| Sanofi |
| Novartis AG |
| GSK plc |
| Teva Pharmaceutical Industries Ltd |
| Merck & Co., Inc |
| AbbVie Inc |
| Amgen Inc |
| Others |
Supply & Pricing Matrix
Multi-year sole-source agreements between integrated delivery networks and erythropoietin manufacturers lock in supply access while compressing price visibility for competing biosimilar sponsors. These contracts tether hospital procurement to originator products through oncology volume commitments, forcing follow-on biologics to compete on rebate structures rather than list price alone.
Pricing Analysis
Volume-discount tiering structures separate originator erythropoietin from biosimilar competitors through bundled payment mechanisms in Medicare Part B and German sickness funds. Price differentiation rests on glycosylation consistency certification and FDA interchangeability designation status, with oncology clinics showing highest sensitivity to out-of-pocket differentials. Cost compression in the erythropoietin segment is intensifying as EMA biosimilar scientific committee guidance accelerates therapeutic substitution timelines.
Supply Chain Analysis
Inventory lead times for glycosylation-grade mammalian cell culture media extend manufacturing planning horizons to twelve-to-eighteen months for recombinant protein producers. Supply concentrates in South Korean CDMOs with validated expression systems, drawing from Chinese-sourced serum components and German-engineered bioreactor equipment. Single-source vulnerability in contract manufacturing capacity creates bottlenecks for biosimilar developers. Distribution runs through cold chain logistics networks anchored in the Incheon free economic zone.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The hematopoietic agents market sits at a platform-economics inflection where EMA-FDA regulatory interoperability is reshaping competitive entry sequencing and procurement bundling across Atlantic markets.
For Market Incumbents: Compound manufacturing scale advantages through backward integration into glycosylation-grade media production, securing input cost stability against serum price volatility. Anchor formulary position by investing in FDA interchangeability designation pursuit for long-acting G-CSF formulations, preempting biosimilar substitution at integrated delivery networks. For New Entrants and Emerging Players: CDSCO streamlined biosimilar approval frameworks offer fastest regulatory path to commercial presence in India's tier-2 city oncology infrastructure. Target Maharashtra and Gujarat hospital procurement departments with erythropoietin biosimilar tenders priced to displace originator contracts. Build market presence through direct engagement with regional purchasing cooperatives rather than national distribution partnerships. For Investors and Strategic Acquirers: Specialized cell therapy manufacturing capabilities with validated mammalian expression systems represent priority acquisition targets, given scarcity of workforce expertise in glycoprotein analytical characterization. Long-term viability over the next decade hinges on substitution policy shifts at US state level and EMA immunogenicity guidance refinement. Watch for interchangeability legislation acceleration as signal for procurement negotiation leverage redistribution.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Interchangeability Designation Pursuit | Accelerates therapeutic substitution in Medicare Part B reimbursement channels. |
| Backward Integration into Media Production | Secures glycosylation-grade input supply against Chinese serum price volatility. |
| CDSCO Fast-Track Biosimilar Filing | Compresses regulatory lag versus FDA and EMA precedent for Indian market entry. |
| Home Administration Device Development | Opens direct-to-patient channels bypassing infusion center dependency in US oncology. |
| WHO Prequalification Pathway Achievement | Unlocks emerging market procurement volume through international reference standard status. |
Research Methodology
A spread of perspectives from formulary directors, hospital procurement managers, regulatory affairs leads, and payer access specialists converged on the working assumptions shaping this analysis. Primary fieldwork combined structured interviews with secondary validation through FDA filings, EMA submissions, ClinicalTrials.gov records, and hospital procurement databases. Bottom-up volume modeling and top-down value triangulation anchored the analytical framework.
Segmentation dimensions modeled span product type, application, end user, and delivery mode across the projection horizon, with regional regulatory clusters and glycosylation complexity tiers as cross-cutting variables. CAGRs derived from trend extrapolation of biosimilar penetration curves and dose-dense chemotherapy protocol adoption rates. Forecast inputs incorporated EMA biosimilar scientific committee guidance evolution and PMDA accelerated approval pathway utilization.
Decision-makers should treat outputs as directional under assumptions of stable regulatory interchangeability frameworks and continued integrated delivery network consolidation; material deviation in biosimilar substitution policy would warrant model refresh. Revision becomes warranted when FDA state-level interchangeability legislation crosses adoption thresholds or South Korean CDMO capacity expansion materially outpaces demand.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Hematology
Neutropenia Treatment Market
Hematology
Acute Myeloid Leukemia Treatment Market
Hematology
Hairy Cell Leukemia Treatment Market
Hematology
Graft vs Host Disease Market
Hematology
Multiple Myeloma Treatment Market
Hematology
Hemoglobin Analyzer Market
Hematology
Bone Marrow Transplant Market
Hematology
Idiopathic Thrombocytopenic Purpura Market
Hematology
Hemoglobinopathy Treatment Drug Market
Hematology
Congenital Amegakaryocytic Thrombocytopenia (CAMT) Market
Hematology
Peripheral T-Cell Lymphoma Treatment Market
Hematology
Blood Screening Market
Hematology
Haematocrit Centrifuge Market
Hematology
Global Hematology Market
Hematology
Follicular Lymphoma Treatment Market
Hematology
Chronic Immune Thrombocytopenia Treatment Market