
 Heel Tampography Printing Machine Market | 2026-2036
Heel Tampography Printing Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Heel Tampography Printing Machine Market Foresight
Italian machinery producers is consolidating around precision-engineered pad printing systems for luxury footwear applications. Comec Italia leverages decades of regional manufacturing heritage to sustain export competitiveness across European tannery districts. Tampoprint AG anchors German engineering credibility in automated cliche engraving and closed-cup systems. Inkcups competes through North American service density and digital integration capabilities.
Heel tampography printing machines transfer ink from an etched metal plate through a silicone pad onto curved or irregular shoe heel surfaces, typically achieving print resolutions of 300-600 dpi with solvent-based or UV-curable formulations. The equipment serves footwear factories requiring durable brand logos, size markings, and decorative patterns on rubber, leather, or synthetic heel components. Automatic systems command the dominant installed base among high-volume footwear manufacturers seeking throughput above 1,500 impressions hourly. UV-curable technology represents the fastest-expanding ink category as brands eliminate volatile organic compound exposure in factory environments. Robotic configurations remain nascent but attract investment from exporters pursuing lights-out production for premium private-label contracts.
CE marking and REACH obligations in Europe restrict solvent-based chemistry deployment, pushing machinery buyers toward compliant UV and water-based system architectures. EPA air quality standards in the United States similarly constrain conventional ink formulations in domestic footwear printing operations. China's GB standards and MIIT equipment safety directives govern import specifications for tampography machinery entering Asian manufacturing zones. Stakeholders must evaluate total cost of ownership across ink conversion, regulatory certification, and automation tier when replacing or expanding heel printing capacity.
Market Dynamics
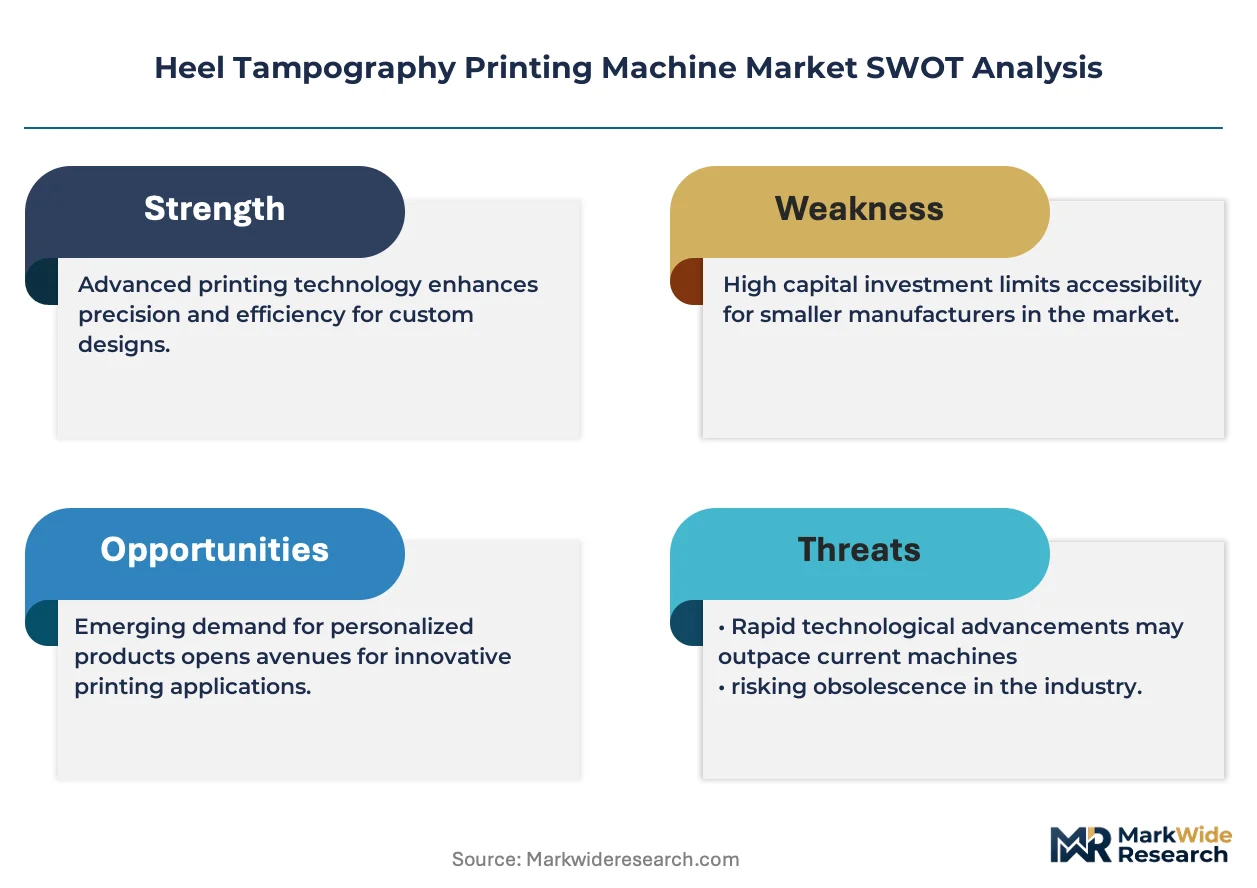
UV-curable ink chemistry is compressing factory certification timelines while REACH and EPA air quality mandates force solvent-based system obsolescence across European and North American footwear manufacturing clusters.
Growth Catalysts
- REACH Phase-Out Deadlines:ECHA restrictions on volatile organic compounds in industrial coatings are compelling footwear factories to replace legacy solvent-based tampography lines with compliant UV-curable architectures.
- Vietnam Production Expansion:Nike, Adidas, and Deckers supplier networks are localizing heel decoration capacity in Ho Chi Minh City industrial zones to reduce logistics exposure from Chinese port congestion.
- Closed-Cup Ink Systems:German-engineered sealed ink cup technology cuts solvent evaporation by 80% and reduces cleaning downtime, accelerating adoption among high-volume contract manufacturers.
Market Restraints
- UV Ink Feedstock Concentration:Photoinitiator supply chains concentrate in Chinese chemical parks near Ningbo, creating input cost volatility when environmental inspections trigger production pauses.
- Silicone Pad Technical Limits:Current pad durometer formulations struggle to maintain image fidelity below 0.3mm on aggressively curved stiletto heels, constraining luxury women's footwear applications.
- CE Certification Friction:Machinery safety directive compliance testing for automated tampography systems requires 8-14 month validation cycles at notified bodies in Italy and Germany.
Strategic Opportunities
- Robotic Lights-Out Production:Vision-guided robotic pad positioning converging with automated cliché engraving enables unmanned third-shift operation for premium private-label exporters.
- India PLI Scheme:Production-linked incentives for footwear and leather goods manufacturing are drawing machinery tenders from Puma and Asics suppliers establishing Tamil Nadu operations.
- Water-Based Ink Revival:Advances in polyurethane dispersion chemistry are reopening water-based pathways for brands seeking VOC elimination without UV capital expenditure.
Industry Challenges
- Pad Printing Technician Scarcity:Skilled operators capable of color matching across solvent, UV, and water-based chemistries command 40% wage premiums in Dongguan and Porto Feliz factory clusters.
- Legacy ERP Integration:Automated tampography cells require custom middleware to connect with 1990s-era production scheduling systems still prevalent in Italian tannery district suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Heel Tampography Printing Machine Market |
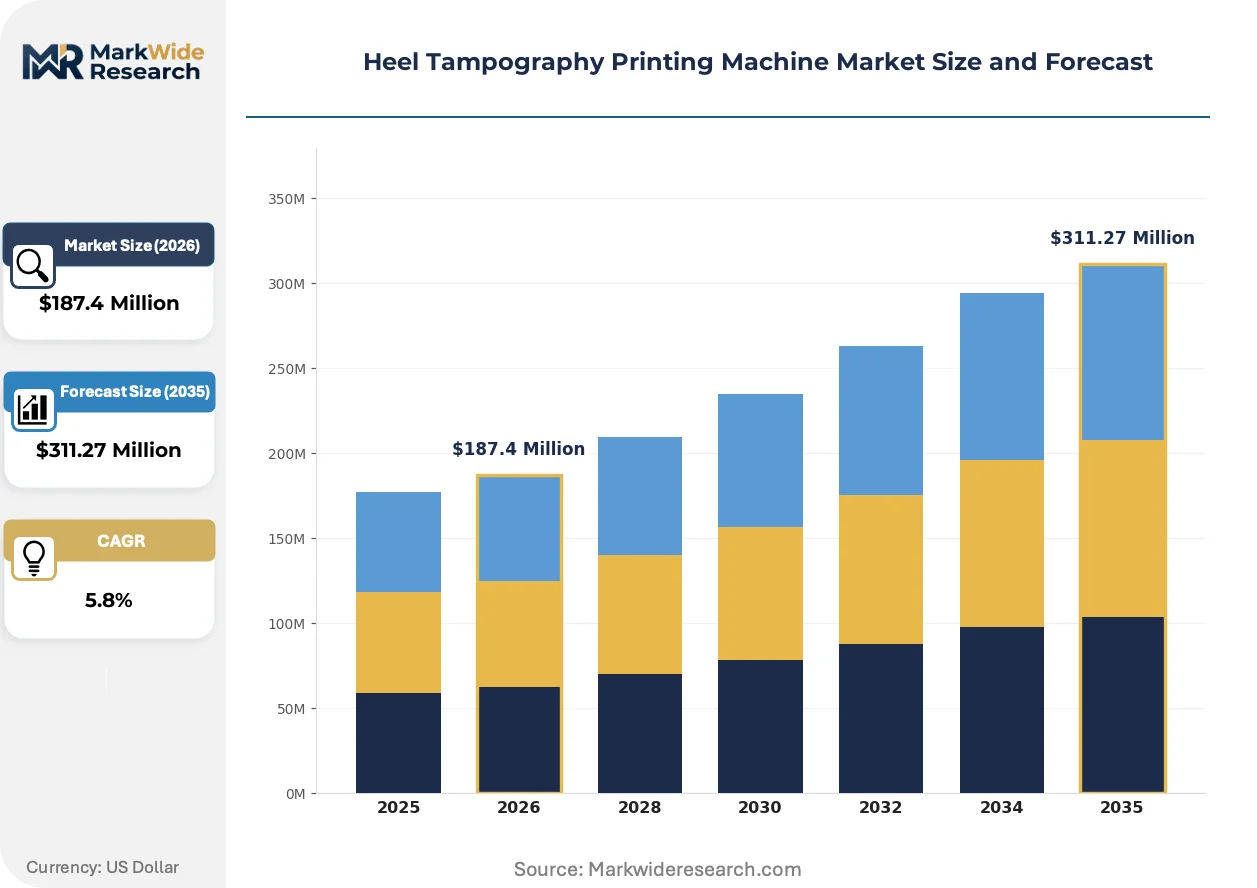
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $311.27 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automatic, Semi-Automatic, Manual, Robotic End User: Footwear Manufacturers, Printing Service Providers, Retailers, Exporters Application: Footwear Branding, Decorative Printing, Customized Designs, Repair Services Technology: Solvent-Based, UV-Curable, Water-Based, Thermal Transfer |
| Companies Covered | Comec Italia, Inkcups, Kent, Mascoprint Developments Ltd., Printex USA, ITW Trans Tech, Tampoprint AG, Miedl & Schnall GmbH, Teca-Print, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Heel Tampography Printing Machine Market Shifts & Advancements
Digital workflow integration and regulatory chemistry mandates are restructuring equipment specifications faster than replacement cycles, compressing technology adoption windows from seven years to four.
Laser cliché engraving is automating plate production for tampography operations, eliminating chemical etching baths and reducing tooling turnaround from 48 hours to 90 minutes. Footwear manufacturers in Portugal and Mexico are retrofitting existing pad printing stations with fiber laser modules at 60% of new system cost. This upgrade path is automating job changeover flexibility and enabling economic lot sizes below 500 units.
EPA National Emission Standards for Hazardous Air Pollutants are tightening permissible solvent emissions from footwear finishing operations, forcing US-based manufacturers to document mass balance for every gram of ink consumed. The regulatory pressure is accelerating UV system replacement timelines in Maine and Massachusetts factory locations. Equipment financiers now structure 36-month lease-to-own products around compliance-driven replacement cycles.
Brand technical audit requirements are reshaping supplier qualification protocols, with Nike's Manufacturing Restricted Substances List and Adidas' Environmental Guidelines now mandating third-party ink chemistry certification before factory approval. Tier-two contract manufacturers in Indonesia and Bangladesh face 18-month compliance investment horizons. Audit-driven standardization is consolidating machinery purchasing decisions toward vendors with pre-certified integrated ink systems.
Heel Tampography Printing Machine Market Segmentation
Equipment procurement in heel tampography diverges sharply by operational scale and regulatory exposure. Factory automation tiers and ink chemistry choices determine replacement timelines, capital intensity, and compliance pathways across footwear manufacturing clusters.
Product Type:
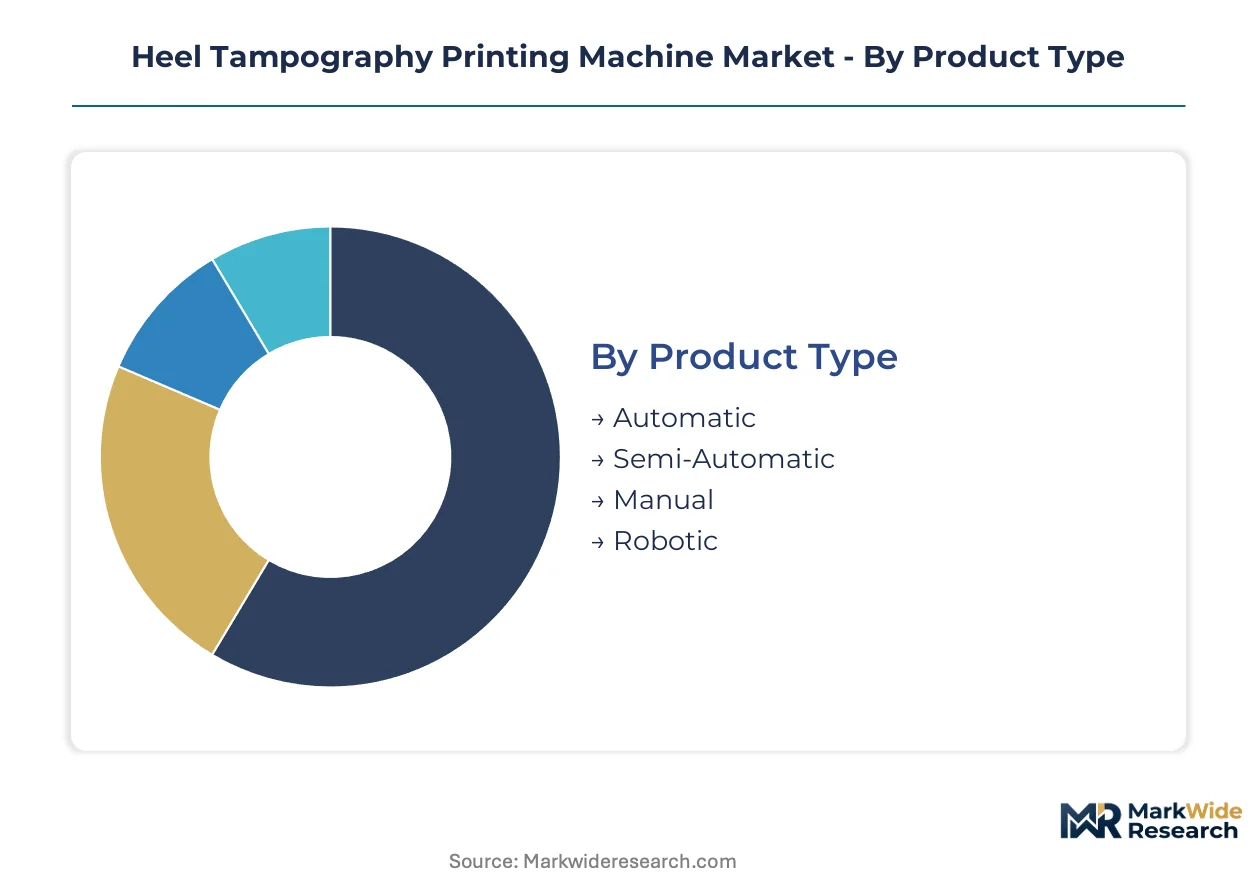
Replacement cycles accelerate where throughput requirements and labor cost trajectories reshape factory economics. Automatic systems dominate high-volume environments; robotic configurations attract greenfield investments seeking lights-out operation.
- Automatic:Closed-cup architectures with sealed ink systems achieve sustained throughput above 1,500 impressions hourly. Vietnamese contract manufacturers in Ho Chi Minh City industrial zones favor these configurations to meet Nike and Adidas supplier audit requirements for consistent brand logo reproduction.
- Robotic:Vision-guided pad positioning converges with automated cliché engraving to enable unmanned third-shift production. Premium private-label exporters in Portugal and Mexico pilot these cells for lot sizes below 500 units without manual changeover.
- Semi-Automatic:Hybrid stations balance operator oversight with programmable indexing for mid-tier footwear factories.
- Manual:Entry-level benchtop units serve repair shops and micro-batch customizers with minimal capital outlay.
Volume placements concentrate in Automatic systems; the steepest expansion trajectory belongs to Robotic configurations.
End User:
Customer procurement authority varies by supply chain tier and brand audit exposure. Direct manufacturers control specification; service providers and exporters adapt to downstream compliance mandates.
- Footwear Manufacturers:Integrated factories in Italy's tannery districts specify precision-engineered pad printing systems for luxury heel applications. REACH Phase-Out deadlines compel these buyers toward UV-curable architectures with documented mass balance for every gram of ink consumed.
- Exporters:Private-label suppliers in Bangladesh and Indonesia face 18-month compliance investment horizons under Nike Manufacturing Restricted Substances List and Adidas Environmental Guidelines. Pre-certified integrated ink systems dominate their machinery tenders.
- Printing Service Providers:Independent decorators serve fragmented regional footwear clusters with flexible job-shop capacity.
- Retailers:Vertical footwear brands with in-house customization counters deploy compact semi-automatic stations.
Procurement volume clusters with Footwear Manufacturers; the compliance-driven replacement cycle is accelerating fastest among Exporters.
Application:
Functional requirements diverge by durability standards, design complexity, and batch frequency. Branding applications prioritize regulatory chemistry; decorative and custom work demands rapid job changeover.
- Footwear Branding:Durable size markings and corporate logos on rubber, leather, or synthetic heel components require solvent-resistant or UV-cured formulations. EPA National Emission Standards for Hazardous Air Pollutants force US-based manufacturers in Maine and Massachusetts toward documented ink consumption tracking.
- Customized Designs:Short-run personalization for limited-edition releases leverages laser cliché engraving retrofits. Portuguese manufacturers achieve 90-minute tooling turnaround versus 48-hour chemical etching cycles.
- Decorative Printing:Patterned heel surfaces for fashion-forward women's footwear strain silicone pad durometer limits below 0.3mm on aggressively curved stiletto geometries.
- Repair Services:Aftermarket restoration of worn heel markings operates at lower resolution thresholds with portable manual equipment.
Factory placements concentrate in Footwear Branding; the technology refresh rate is climbing fastest in Customized Designs.
Technology:
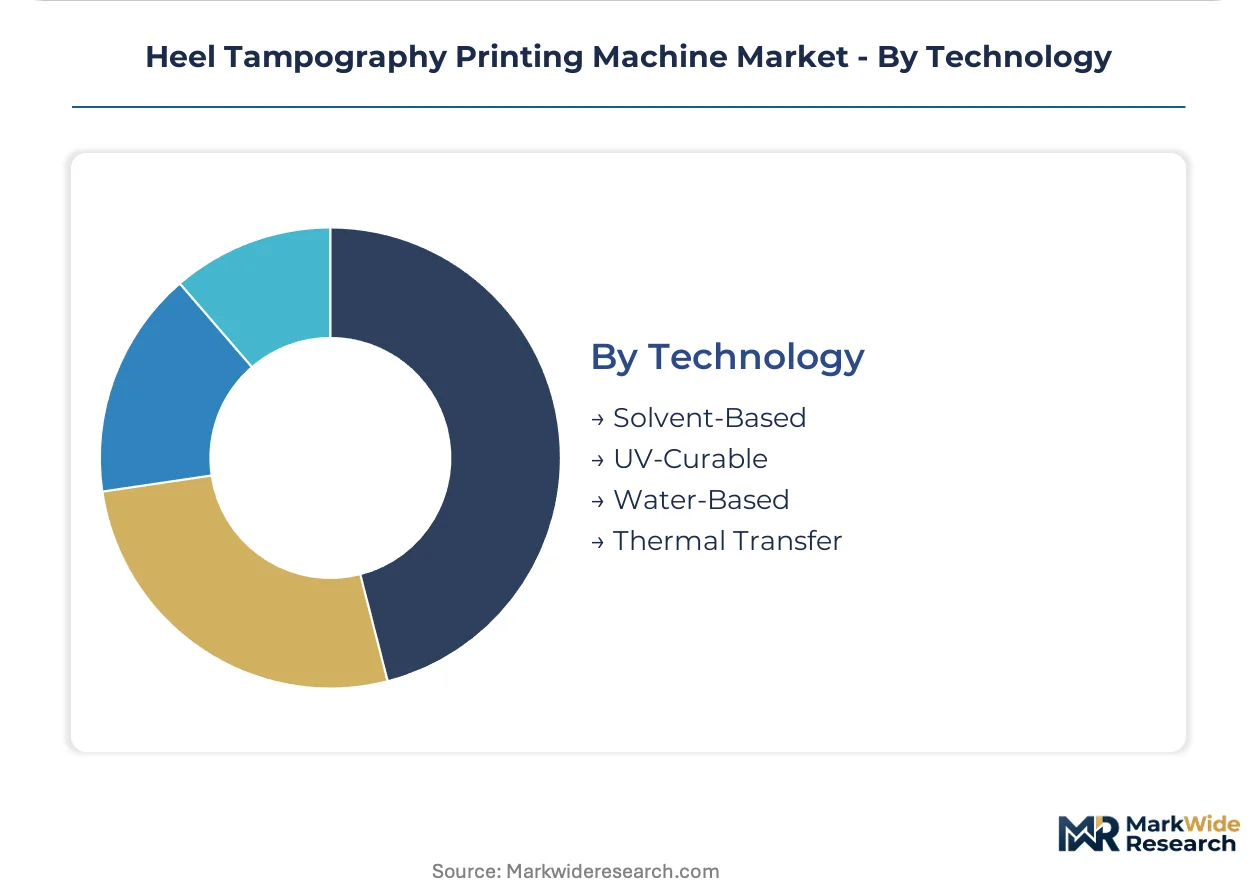
Ink chemistry selection locks in regulatory compliance pathways, ventilation infrastructure, and curing energy requirements. UV and water-based formulations are displacing legacy solvent systems under emissions mandates.
- UV-Curable:Photoinitiator-activated formulations eliminate volatile organic compound exposure and compress factory certification timelines. ECHA restrictions on industrial coatings compel European footwear factories to replace legacy solvent-based lines with these architectures.
- Solvent-Based:Conventional nitrocellulose and polyurethane systems retain cost advantage in unregulated manufacturing zones but face obsolescence under REACH and EPA air quality standards.
- Water-Based:Polyurethane dispersion advances reopen VOC-free pathways for brands avoiding UV capital expenditure.
- Thermal Transfer:Ribbon-based imaging serves niche applications requiring photographic reproduction on synthetic heel materials.
Installed base concentrates in Solvent-Based systems; the sharpest share gains are occurring in UV-Curable formulations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Photoinitiator supply chains near Ningbo anchor Asian ink chemistry production, while machinery specification authority concentrates in Italian tannery districts and German engineering centers. Factory procurement decisions track regulatory enforcement intensity across manufacturing clusters.
China
MIIT equipment safety directives govern import specifications for tampography machinery entering Dongguan and Wenzhou manufacturing zones. Environmental inspections in Ningbo chemical parks trigger photoinitiator production pauses that transmit cost volatility downstream. Footwear factories in Guangdong province face GB standards compliance for VOC emissions from solvent-based finishing operations.
Vietnam
Nike and Adidas supplier networks localize heel decoration capacity in Ho Chi Minh City industrial zones to reduce logistics exposure from Chinese port congestion. Contract manufacturers favor closed-cup automatic systems achieving throughput above 1,500 impressions hourly. The country's footwear export growth is compressing equipment procurement timelines for compliant UV-curable architectures.
Germany
ECHA REACH restrictions on volatile organic compounds compel footwear factories to replace legacy solvent-based lines with compliant UV-curable systems. Tampoprint AG anchors engineering credibility in automated cliché engraving from its base in Schwetzingen. CE marking validation cycles at notified bodies require 8-14 month compliance testing for automated tampography systems.
Italy
Comec Italia leverages decades of regional manufacturing heritage in precision-engineered pad printing systems for luxury footwear applications. REACH Phase-Out deadlines push tannery district buyers toward documented mass balance for every gram of ink consumed. The Veneto and Tuscany industrial corridors concentrate specification authority for high-end heel decoration equipment.
United States
EPA National Emission Standards for Hazardous Air Pollutants tighten permissible solvent emissions from footwear finishing operations in Maine and Massachusetts factory locations. Equipment financiers structure 36-month lease-to-own products around compliance-driven replacement cycles. Inkcups competes through North American service density and digital integration capabilities from its Massachusetts base.
Heel Tampography Printing Machine Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue robotic automation and digital workflow integration. The vendor base stratifies across precision-engineered European specialists, North American service-intensive operators, and Asian volume fabricators. Three archetypes dominate: heritage engineering houses with tannery district relationships, digitally integrated service providers, and automated system integrators. Competitive moves concentrate on geographic expansion into Vietnam and India, plus technology licensing for UV-curable ink system integration.
Within the heritage engineering tier, Comec Italia and Tampoprint AG exemplify regional manufacturing credibility sustained through decades of tannery district presence. Among digitally integrated competitors, Inkcups occupies a position defined by North American service density. Miedl & Schnall GmbH represents the specialized German fabricant archetype, while Mascoprint Developments Ltd. and Teca-Print sit within the mid-tier precision segment serving contract manufacturers with flexible job-shop configurations.
| Leading Market Players |
|---|
| Comec Italia |
| Inkcups |
| Kent |
| Mascoprint Developments Ltd. |
| Printex USA |
| ITW Trans Tech |
| Tampoprint AG |
| Miedl & Schnall GmbH |
| Teca-Print |
| Others |
Supply & Pricing Matrix
Photoinitiator spot prices in Ningbo chemical parks transmit immediate volatility into UV-curable ink system costs, compressing margins for machinery vendors and forcing three-tier pricing stratification across premium German-engineered, mid-tier Italian, and economy Asian equipment tiers.
Pricing Analysis
Extended warranty and preventive maintenance bundling separates premium vendors from unbundled competitors in the automatic system tier. Price differentiation rests on CE certification grade and installed base density in Vietnam's Ho Chi Minh City industrial zones. Cost compression in the semi-automatic tier is intensifying because Chinese fabricants are absorbing photoinitiator volatility to maintain volume share. Contract manufacturers serving Nike and Adidas supplier networks exhibit lowest price sensitivity; micro-batch customizers in repair segments demonstrate highest.
Supply Chain Analysis
Dual-sourcing mandates from European footwear manufacturers require qualified suppliers for both silicone pad formulations and laser engraving modules. Component supply concentrates in Germany, Italy, and China. Raw material dependencies include photoinitiators from Ningbo chemical parks, precision-ground ceramic rings for sealed ink cups, and fiber laser sources. Single-source vulnerability in photoinitiator supply creates exposure when environmental inspections trigger production pauses. Distribution runs through machinery distributors with tannery district relationships and direct OEM sales to high-volume contract manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around regulatory compliance capabilities, with REACH Phase-Out deadlines and EPA emission standards forcing solvent-based system vendors toward distressed exits.
For Market Incumbents: Acquire automated cliché engraving technology to close the job changeover gap with laser-retrofit competitors. Incumbents must anchor defensive positioning through backward integration into UV ink formulation partnerships and capacity expansion in Vietnam's supplier-dense industrial corridors. Threat from digitally integrated North American service providers demands preemptive certification investment in Nike Manufacturing Restricted Substances List pre-approval. For New Entrants and Emerging Players: Begin with robotic lights-out production configurations targeting Portuguese and Mexican premium private-label exporters. The most penetrable white space sits in sub-500 unit lot sizes where vision-guided pad positioning eliminates manual changeover. Go-to-market leverage centers on 36-month lease-to-own financing structures aligned with compliance-driven replacement cycles in US factory locations. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-tier precision specialists with established CE marking pathways in Italian tannery districts. Long-term viability across the five-to-ten year window hinges on water-based ink chemistry R&D pipelines as brands seek VOC elimination without UV capital expenditure. The signal to watch is India's PLI scheme machinery tender volume from Puma and Asics suppliers establishing Tamil Nadu operations.| Strategic Initiative | Industry Significance |
|---|---|
| UV Ink System Integration | ECHA REACH deadlines in Europe are accelerating compliant architecture procurement timelines. |
| Laser Cliché Retrofit Capability | Portuguese manufacturers achieve 90-minute tooling turnaround versus 48-hour chemical etching cycles. |
| Vietnam Manufacturing Footprint | Ho Chi Minh City industrial zones concentrate Nike and Adidas supplier network demand. |
| Water-Based Ink R&D Pipeline | Polyurethane dispersion advances reopen VOC-free pathways for capital-constrained brands. |
| Robotic Lights-Out Production | Vision-guided pad positioning enables unmanned third-shift operation for premium exporters. |
Research Methodology
Document review covered customs and trade data, machinery safety directive filings, and SEC equipment manufacturer disclosures, complemented by interviews with plant engineers at Vietnamese contract manufacturers, aftermarket service heads in Italian tannery districts, procurement leads at German OEMs, and technical R&D directors at ink chemistry suppliers. Secondary validation drew from MIIT equipment import specifications, ECHA restriction substance databases, and EPA National Emission Standards compliance records. Bottom-up installation base counts and top-down footwear production capacity estimates were triangulated to anchor market sizing.
Segment-level projections across automatic, robotic, semi-automatic, and manual system tiers were generated over the projection horizon, with ink chemistry splits modeled separately for UV-curable, solvent-based, water-based, and thermal transfer technologies. CAGRs were derived from replacement cycle compression analysis and regulatory enforcement intensity scoring. Key inputs included photoinitiator supply disruption frequency, CE certification queue lengths at Italian and German notified bodies, and brand audit requirement diffusion rates across Bangladesh and Indonesia supplier networks.
Underlying measurement precision varies by segment; automatic system placements in Vietnam carry tighter precision than robotic configuration pilots in Portugal and Mexico. Forecasts reflect documented assumptions around REACH Phase-Out deadline adherence and EPA enforcement continuity. Deviation in photoinitiator supply chain stability or ECHA restriction timeline acceleration would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Textile Machinery and Equipment
Global Rotary Clothes Dryer Market
Textile Machinery and Equipment
Textile Winding Machine Market
Textile Machinery and Equipment
Europe Fabric Shavers Market
Textile Machinery and Equipment
Global Weaving Machinery Market
Textile Machinery and Equipment
Stringing Machines Market
Textile Machinery and Equipment
Global Spinning Machinery Market
Textile Machinery and Equipment
Hoarding Tarpaulin Market
Textile Machinery and Equipment
Sewing Machine Market
Textile Machinery and Equipment
Automatic Webbing Cutting Machines Market
Textile Machinery and Equipment
Electric Fabric Shaver Market
Textile Machinery and Equipment
Disposable Garment Bags Market
Textile Machinery and Equipment
Textile Tester Market
Textile Machinery and Equipment
Global Knitting Machinery Market
Textile Machinery and Equipment
Direct to Garment Printing Market
Textile Machinery and Equipment
Yankee Dryer Market
Textile Machinery and Equipment
Middle East and Africa Textile Films Market