
 Global Spinning Machinery Market | 2026-2036
Global Spinning Machinery Market Size, Share, and Industry Trends Forecast 2026-2036
Global Spinning Machinery Market Outlook
Direct-to-mill distribution is reconfiguring how spinning machinery reaches end users across Asia. Trützschler Group leverages its integrated blowroom-to-yarn portfolio to control specification conversations with large textile mills. Rieter Holding AG anchors European precision engineering reputation while extending service networks into South Asian manufacturing clusters. Murata Machinery Ltd. competes on automated rotor spinning specialization, positioning its vortex technology as an alternative to conventional ring frames.
Spinning machinery comprises mechanical and electromechanical systems that draw, twist, and wind staple fibers into continuous yarn, operating at spindle speeds exceeding 20,000 rpm in modern compact spinning configurations. Ring spinning systems sustain dominant installed base share due to yarn quality versatility across cotton and synthetic blends, while air jet spinning is displacing rotor systems in polyester-cotton woven apparel applications where lower hairiness commands premium positioning. Automated technology segments capture disproportionate margin pools as labor cost arbitrage diminishes and energy efficiency mandates tighten operational thresholds for semi-automated legacy assets.
REACH substance restrictions and CE machinery directives in Europe shape material specifications for lubricants and electronic components, while China's GB standards and dual carbon goals enforce energy consumption benchmarks on imported equipment. India's BIS certification requirements and PLI scheme eligibility criteria filter market access for machinery suppliers seeking textile mill customers. Stakeholders must monitor how carbon border adjustment mechanisms and evolving national efficiency standards alter total cost of ownership calculations across procurement decisions.
Market Dynamics
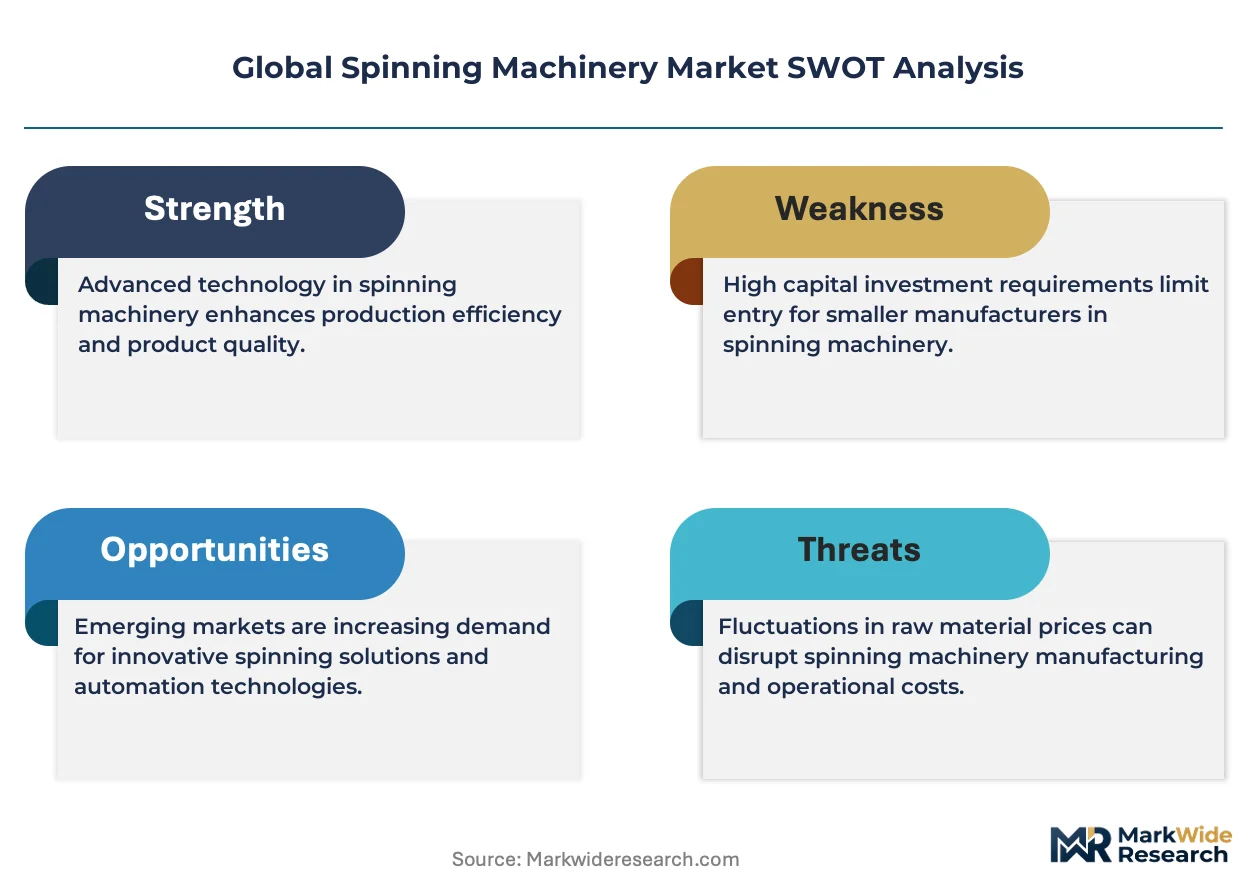
Energy efficiency mandates and carbon accounting requirements are compressing operational lifespans of semi-automated legacy assets, forcing textile mills toward compact spinning configurations and automated material handling systems that reduce per-kilogram energy intensity.
Growth Catalysts
- India PLI scheme eligibility:Domestic textile manufacturers accessing production-linked incentives must install BIS-certified equipment, creating certified machinery procurement pipelines for compliant suppliers.
- Technical textile expansion:Automotive airbag fabric and medical nonwoven applications demand specialized yarn constructions, requiring precision spinning systems with enhanced tenacity control.
- Ring frame automation:Automated doffing and splicing systems reduce labor dependency in high-wage manufacturing clusters, accelerating replacement cycles in Turkey and Vietnam.
Market Restraints
- Specialized steel alloy volatility:Spindle components and ring travelers require tool-grade stainless formulations subject to nickel and chromium price swings, compressing equipment margin stability.
- European REACH substance restrictions:Lubricant formulations and electronic component coatings face ECHA authorization requirements that extend qualification timelines for imported subsystems.
- Rotor spinning quality ceiling:Open-end systems cannot achieve ring-frame yarn strength for fine-count woven shirting, limiting addressable premium apparel segments.
Strategic Opportunities
- Ethiopian textile park buildout:Industrial zone developers seek turnkey spinning installations with captive power integration, creating integrated project opportunities absent established supplier relationships.
- Vietnam fabric-to-garment integration:Forward-integrated mills require matched spinning-weaving systems that compress logistics costs for export-oriented polyester-cotton operations.
- Digital twin deployment:Virtual commissioning of ring frame installations reduces physical prototyping for custom fiber processing configurations, compressing delivery timelines.
Industry Challenges
- Mechatronics technician scarcity:Automated spinning systems require maintenance personnel fluent in both mechanical adjustment and PLC diagnostics, a skill combination concentrated in European and Japanese supplier networks.
- Legacy system integration friction:Brownfield mills operating 1990s-era frames face incompatible control architectures when retrofitting automated material handling, forcing parallel infrastructure investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Spinning Machinery Market |
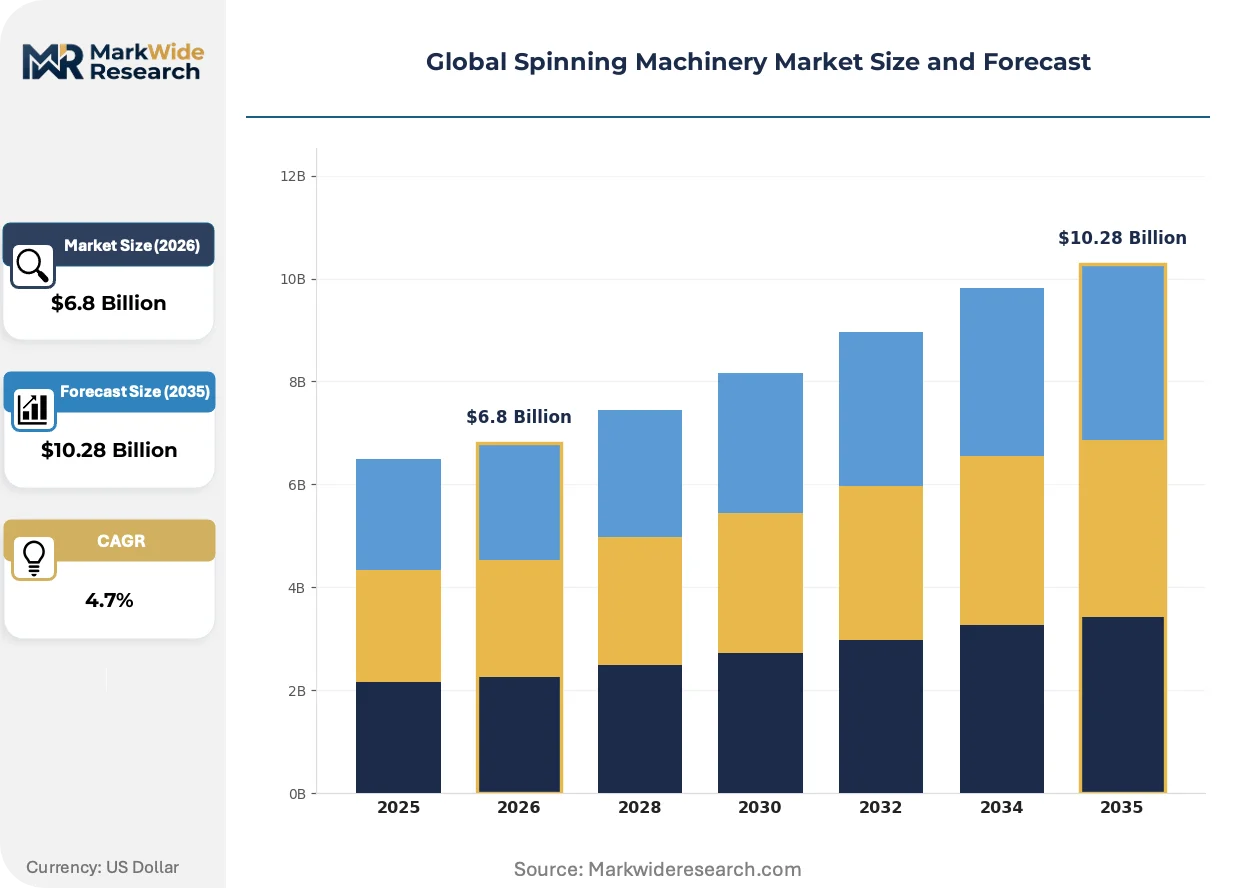
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $10.28 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ring Spinning, Open-End Spinning, Air Jet Spinning, Compact Spinning Technology: Automated, Semi-Automated, Conventional, Computerized End User: Textile Mills, Garment Manufacturers, Specialty Fiber Producers, Non-Woven Producers Deployment: On-Premise, Cloud-Based, Hybrid, Mobile |
| Companies Covered | Trützschler Group, Murata Machinery Ltd., Rieter Holding AG, Marzoli Machines Textile S.r.l., Savio Macchine Tessili S.p.A., Saurer Intelligent Technology AG, Toyota Industries Corporation, A.T.E. Enterprises, Lakshmi Machine Works Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Spinning Machinery Market Strategic Shifts
Digital thread technologies and predictive maintenance architectures are reconfiguring how spinning assets are specified, financed, and operated across Asian manufacturing clusters. Equipment buyers now weight connectivity specifications alongside mechanical throughput metrics.
Cloud-based spindle monitoring platforms aggregate vibration and temperature telemetry from distributed ring frame installations, enabling centralized performance optimization. Large South Indian textile groups deploy these systems across multi-location footprints. Real-time anomaly detection is virtualizing traditional preventive maintenance schedules, compressing unplanned downtime intervals and reshaping service contract structures.
China's GB 18613-2020 motor efficiency standards and dual carbon enforcement protocols now filter import approvals for spinning machinery, with MIIT energy labeling requirements extending to auxiliary blowroom equipment. European suppliers face extended conformity assessment periods for high-speed spindle motors. Mills in Zhejiang and Jiangsu provinces prioritize equipment configurations that minimize carbon intensity calculations for export-bound yarn.
Direct equipment financing from machinery manufacturers displaces traditional textile banking relationships in Bangladesh and Pakistan. Rieter and Trützschler now structure repayment against production volume guarantees rather than balance sheet collateral. This instrument innovation concentrates in markets where conventional project finance faces currency hedging constraints, altering competitive access for smaller European specialists without captive financing arms.
Global Spinning Machinery Market Segmentation
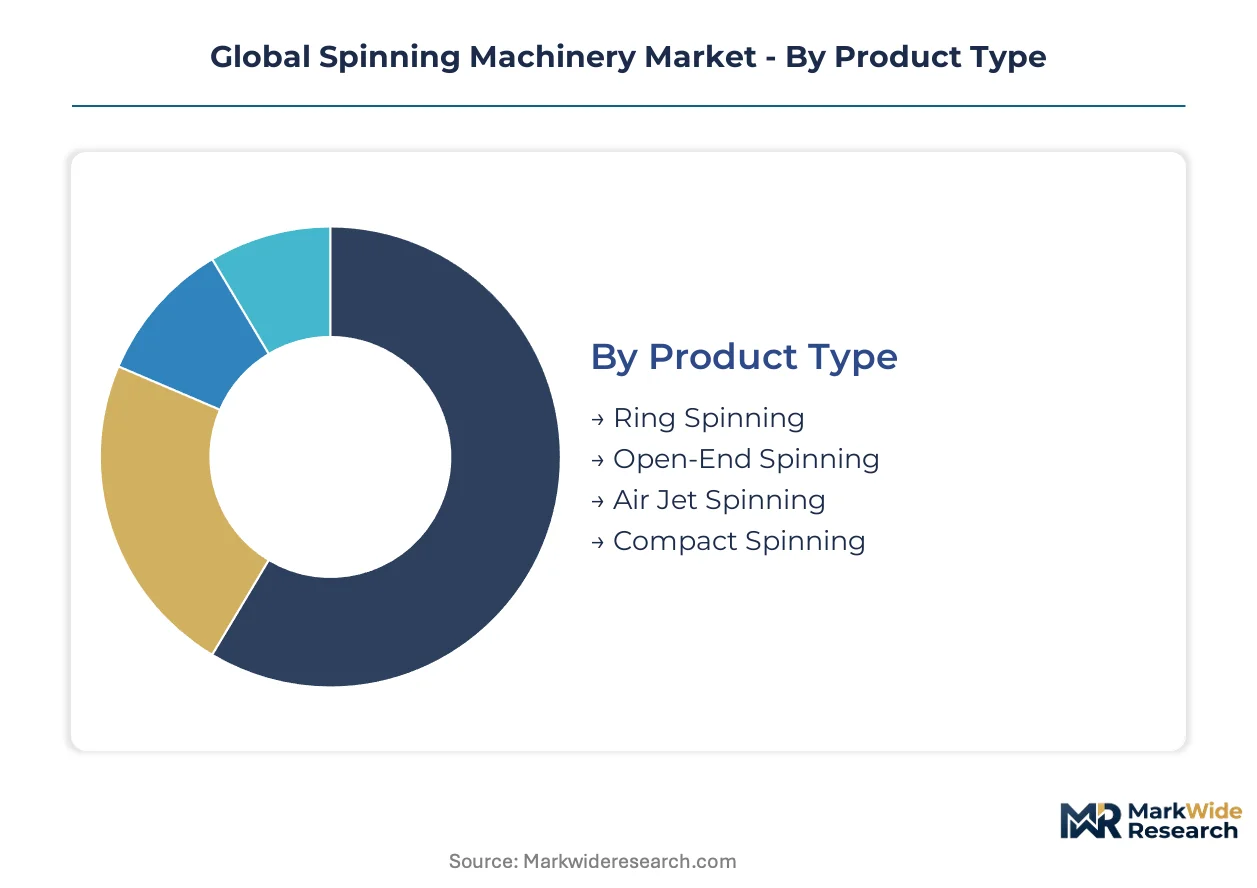
Spinning machinery procurement decisions cascade across multiple technical and operational dimensions, with product architecture and automation level determining capital intensity, maintenance protocols, and workforce composition. Mill operators weight these segments against fiber slates, energy costs, and compliance obligations when specifying equipment portfolios.
Product Type:
Mature ring frame configurations anchor installed capacity across South Asian textile clusters, while emerging compact and air jet technologies capture replacement demand in quality-sensitive applications.
- Ring Spinning:Mechanical drafting systems with traveler-based twisting mechanisms process cotton and synthetic blends across count ranges from Ne 6 to Ne 120. Indian textile mills in Tiruppur and Surat deploy these frames for woven shirting and denim warp yarns where tenacity specifications are non-negotiable.
- Compact Spinning:Condensed fiber delivery through pneumatic compaction zones reduces hairiness and improves yarn strength compared to conventional ring systems. Turkish mills serving European apparel brands specify these configurations for fine-count compact yarns commanding premium positioning in dress shirt fabrics.
- Open-End Spinning:Rotor-based systems eliminate roving stages through direct sliver-to-yarn conversion, dominating coarse-count applications in terry towel and denim weft production.
- Air Jet Spinning:Murata vortex technology wraps staple fibers around a core through air turbulence, displacing rotor systems in polyester-cotton blends for woven apparel.
Ring spinning retains volume leadership; compact spinning holds the steepest expansion curve among frame-based technologies.
Technology:
Cost tier stratification separates premium automated configurations from economy conventional systems, with semi-automated equipment occupying contested middle ground as labor arbitrage diminishes.
- Automated:Integrated doffing robots, automatic splicers, and centralized control architectures reduce direct labor to 0.3 operators per 1,000 spindles. Vietnam's integrated fabric mills specify these systems to offset rising wage pressure in Ho Chi Minh City manufacturing zones.
- Computerized:Digital process control with recipe management and quality data logging enables rapid style changeovers without mechanical adjustment. Bangladeshi spinning mills deploy these platforms to manage frequent fiber mix variations between cotton, viscose, and recycled polyester inputs.
- Semi-Automated:Partial mechanization of material handling with manual intervention for doffing and piecing, concentrated in brownfield upgrades where full automation faces infrastructure constraints.
- Conventional:Mechanical control systems with operator-dependent adjustment, now confined to lowest-cost coarse-count production in Pakistan's informal sector.
Automated systems command the highest capital commitment; computerized platforms are gaining share fastest among mid-scale operators.
End User:
Application-driven specification divergence separates commodity yarn producers from technical textile specialists, with margin profiles determining acceptable equipment payback periods.
- Textile Mills:Integrated spinning-weaving or spinning-knitting operations requiring high-volume, consistent yarn supply for captive fabric production. Indian PLI beneficiaries in Gujarat and Maharashtra prioritize BIS-certified equipment to maintain incentive eligibility.
- Specialty Fiber Producers:Operations processing aramid, carbon, or high-performance polyethylene fibers into technical yarns for automotive and aerospace applications. These installations demand precision tension control and contamination-free environments absent in commodity cotton processing.
- Garment Manufacturers:Captive spinning units within vertically integrated apparel operations, concentrated in Ethiopia's industrial parks and Vietnam's fabric-to-garment corridors.
- Non-Woven Producers:Airlaid and spunlace operations requiring parallel-laid or random fiber webs rather than twisted continuous yarns, specifying different opening and carding configurations.
Textile mills retain volume leadership; specialty fiber producers pursue the steepest expansion trajectory driven by technical textile demand.
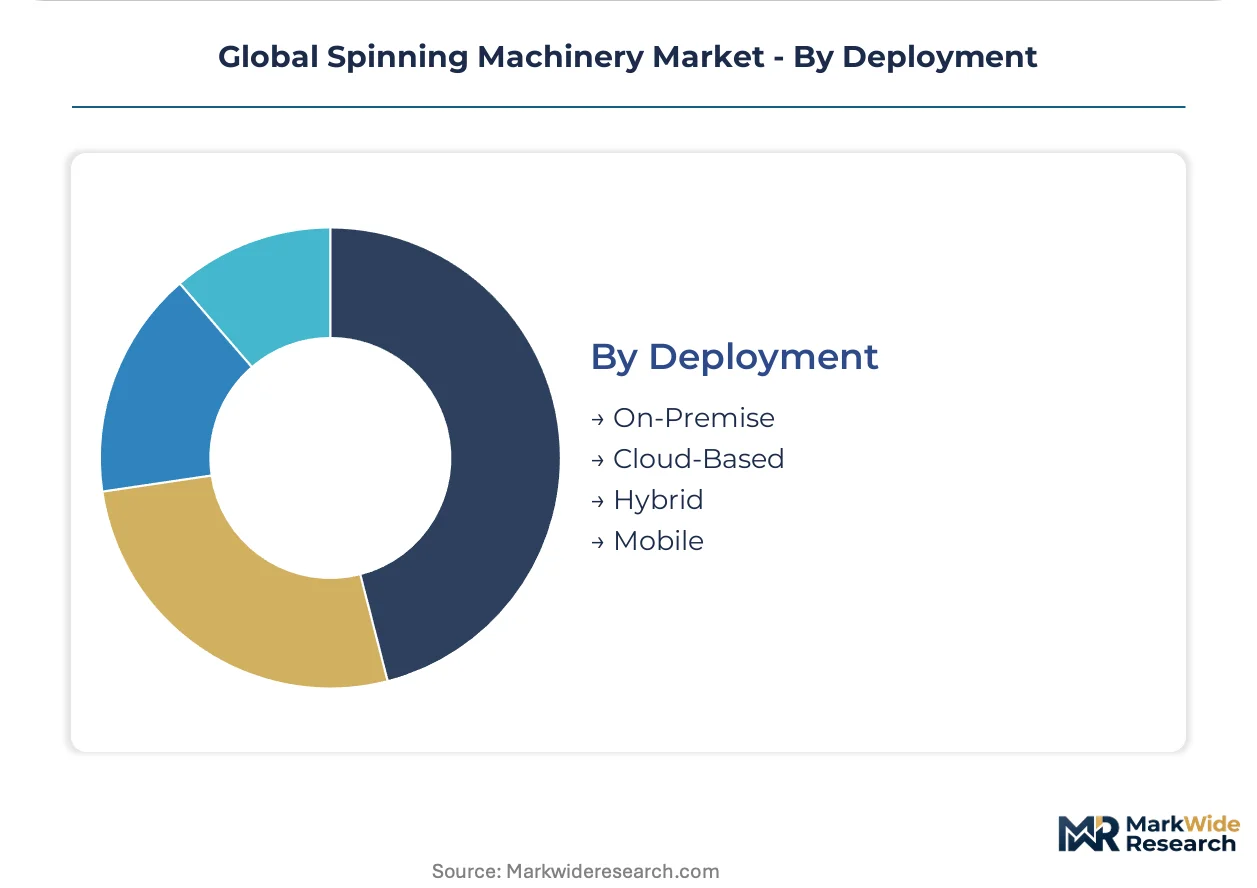
Deployment:
Customer type and facility infrastructure dictate connectivity architecture, with hybrid configurations emerging as legacy assets integrate with cloud-native monitoring platforms.
- On-Premise:Localized control systems with factory-floor SCADA networks, dominant in Chinese mills where data sovereignty concerns and MIIT cybersecurity requirements constrain external cloud connectivity.
- Hybrid:Edge computing with selective cloud telemetry, enabling real-time spindle monitoring while retaining critical control functions locally. Large South Indian textile groups deploy these architectures across multi-location footprints.
- Cloud-Based:Centralized data aggregation and predictive analytics delivered through SaaS platforms, concentrated in European installations where GDPR-compliant data handling is established.
- Mobile:Tablet and smartphone interfaces for maintenance alerts and production dashboards, typically layered over other deployment modes rather than standalone.
On-premise systems retain volume leadership; hybrid deployments are climbing fastest as brownfield mills modernize connectivity without full infrastructure replacement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Government production-linked incentives in India are compressing procurement timelines for BIS-certified equipment, while China's dual carbon enforcement protocols filter import approvals through MIIT energy labeling requirements. European REACH substance restrictions and CE machinery directives reshape material specifications for lubricants and electronic components across continental supply chains.
India
Domestic textile manufacturers accessing PLI scheme benefits must install BIS-certified equipment, creating certified procurement pipelines for compliant machinery suppliers. The CDSCO and DGFT coordinate import clearance protocols for high-speed spindle motors exceeding 20,000 rpm specifications. Tiruppur and Surat industrial clusters deploy compact spinning configurations for woven shirting and denim warp yarns where tenacity specifications are non-negotiable.
China
GB 18613-2020 motor efficiency standards and MIIT energy labeling requirements now filter import approvals for spinning machinery, extending conformity assessment periods for European spindle motor suppliers. The dual carbon goals enforce energy consumption benchmarks on imported equipment through SAMR enforcement channels. Zhejiang and Jiangsu province mills prioritize equipment configurations that minimize carbon intensity calculations for export-bound yarn production.
Germany
Precision engineering reputation anchors European supplier positioning, with ECHA REACH substance restrictions shaping lubricant formulations and electronic component coatings for textile machinery exports. The KBA and federal economic ministries coordinate export credit guarantees for integrated spinning-weaving installations in emerging markets. Baden-Württemberg manufacturing clusters specialize in high-speed traveler and ring components for fine-count yarn applications.
Vietnam
Integrated fabric-to-garment operations require matched spinning-weaving systems that compress logistics costs for export-oriented polyester-cotton production. The Ministry of Industry and Trade coordinates technology import licensing for automated doffing and splicing systems. Ho Chi Minh City manufacturing zones specify automated configurations to offset rising wage pressure in high-volume apparel operations.
Turkey
European apparel brand supply chain requirements drive specification of compact spinning configurations for fine-count yarns commanding premium positioning in dress shirt fabrics. The Turkish Standards Institution enforces CE-aligned machinery safety protocols for imported ring frames. Bursa and Denizli textile clusters deploy automated material handling systems to reduce labor dependency in high-wage manufacturing environments.
Global Spinning Machinery Market Competitive Environment
On the supply side, the industry is consolidating around integrated blowroom-to-yarn portfolios and automated rotor spinning specializations that control specification conversations with large textile mills. Three strategic archetypes dominate: European precision engineering specialists with extended service networks, Japanese automation-focused manufacturers with vortex technology positioning, and Indian domestic champions leveraging PLI scheme eligibility. Competitive moves concentrate on geographic expansion into South Asian manufacturing clusters and portfolio diversification through digital twin deployment for virtual commissioning.
Among European precision engineering specialists, Rieter Holding AG and Saurer Intelligent Technology AG occupy positions anchored by CE machinery directive compliance and extended service architectures. Trützschler Group exemplifies the integrated portfolio archetype through blowroom-to-yarn system control. Murata Machinery Ltd. represents the automation-focused Japanese manufacturer positioning, with vortex technology serving as an alternative to conventional ring frames in polyester-cotton applications.
| Leading Market Players |
|---|
| Trützschler Group |
| Murata Machinery Ltd. |
| Rieter Holding AG |
| Marzoli Machines Textile S.r.l. |
| Savio Macchine Tessili S.p.A. |
| Saurer Intelligent Technology AG |
| Toyota Industries Corporation |
| A.T.E. Enterprises |
| Lakshmi Machine Works Ltd. |
| Others |
Value Chain & Pricing Dynamics
Overcapacity in Chinese spinning machinery component manufacturing is compressing supplier margins while forcing European precision engineering specialists toward premium positioning and extended service bundling. This utilization dynamic concentrates pricing power with buyers in India and Vietnam, where PLI scheme eligibility and fabric-to-garment integration timelines accelerate procurement negotiations.
Pricing Analysis
Volume-discount tiering structures dominate equipment procurement, with three-tier pricing stratification across premium automated configurations, standard computerized platforms, and economy conventional systems. Price differentiation hinges on BIS certification status for Indian PLI compliance and bundled after-sales service architectures. Pricing pressure stems from nickel and chromium volatility in specialized steel alloys for spindle components. Small-scale Bangladeshi and Pakistani mills exhibit highest price sensitivity, while Turkish and Vietnamese integrated operators prioritize total cost of ownership over upfront capital outlay.
Supply Chain Analysis
Contract manufacturing concentration rests with Baden-Württemberg precision component specialists and Japanese mechatronics integrators serving final assembly operations. Geographic supply concentration centers on Germany, Japan, and India for critical subsystems. Raw material dependencies draw from tool-grade stainless steel formulations, high-efficiency spindle motors, and REACH-compliant lubricant chemistries. Single-source vulnerability persists in high-speed traveler and ring component supply. Distribution runs through direct-to-mill channels displacing traditional textile banking intermediaries in South Asian procurement corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution defense imperatives as air jet spinning systems displace rotor configurations in polyester-cotton woven apparel, threatening ring frame dominance in quality-sensitive segments.
For Market Incumbents: Build switching-cost moats through captive financing arms and predictive maintenance platform lock-in. Integrate blowroom-to-yarn system control to specification conversations with large South Asian textile groups. Invest in BIS certification pipelines to capture Indian PLI scheme procurement volumes. Counter Murata vortex positioning with compact spinning tenacity differentiation in fine-count applications. For New Entrants and Emerging Players: Pursue Ethiopian industrial park turnkey installations where established supplier relationships remain absent. Target Vietnam fabric-to-garment integration corridors requiring matched spinning-weaving systems. Exploit mechatronics technician scarcity by positioning digital twin virtual commissioning capabilities. Structure equipment-as-a-service offerings to bypass conventional project finance constraints in currency-hedged markets. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among automated system suppliers with predictive maintenance SaaS platforms and long-term service contracts. Long-term viability favors precision engineering specialists with CE machinery directive compliance and extended Asian service architectures. Monitor carbon border adjustment mechanism implementation as inflection indicator for energy-efficient equipment demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Spindle Component Manufacturing | Mitigates nickel and chromium price volatility exposure for European precision engineering suppliers. |
| Digital Twin Deployment for Virtual Commissioning | Compresses delivery timelines for custom fiber processing configurations in brownfield mill upgrades. |
| Captive Financing Arm Establishment | Structures repayment against production volume guarantees in Bangladesh and Pakistan markets. |
| BIS Certification Pipeline Investment | Secures eligibility for Indian PLI scheme procurement volumes in Gujarat and Maharashtra clusters. |
| Predictive Maintenance Platform Integration | Enables real-time spindle monitoring across multi-location South Indian textile group footprints. |
Study Parameters
Operator-level perspectives from textile mill maintenance directors, OEM procurement teams, aftermarket service heads, and plant engineers anchored the qualitative base. Primary interview data combined with secondary validation from customs and trade records, SEC filings of listed machinery manufacturers, BIS certification databases, and MIIT energy labeling disclosures. Bottom-up equipment shipment tracking and top-down textile capacity expansion analysis provided triangulation across modeling approaches.
Scenario-bracketing framed projections across the analysis window, with segmentation dimensions spanning product architecture, automation level, end-user application, and deployment connectivity. CAGRs derived from regression analysis against fiber processing capacity additions and regulatory compliance timelines. Industry-specific forecast inputs incorporated PLI scheme disbursement schedules and dual carbon enforcement protocol implementation trajectories.
Sensitivities concentrate around carbon border adjustment mechanism adoption, REACH substance restriction expansion, and specialized steel alloy price volatility. Forecasts reflect assumptions regarding BIS certification pipeline development and MIIT import approval timelines. Quarterly review of Indian PLI disbursement data, Chinese GB standard revision notices, and European ECHA authorization updates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Textile Machinery and Equipment
3D Knitting Machines Market
Textile Machinery and Equipment
Compact Spinning Machine Market
Textile Machinery and Equipment
Embroidery Equipment Market
Textile Machinery and Equipment
Global Rotary Clothes Dryer Market
Textile Machinery and Equipment
Tarpaulin Market
Textile Machinery and Equipment
Industrial Laminating Machines Market
Textile Machinery and Equipment
Cloth Measuring Machine Market
Textile Machinery and Equipment
Fabric Cutting Machines Market
Textile Machinery and Equipment
Stringing Machines Market
Textile Machinery and Equipment
Asia Pacific Fabric Shavers Market
Textile Machinery and Equipment
Heel Tampography Printing Machine Market
Textile Machinery and Equipment
Automatic Webbing Cutting Machines Market
Textile Machinery and Equipment
Global Textile Machinery Market
Textile Machinery and Equipment
Automatic Roll Filters Market
Textile Machinery and Equipment
Disposable Garment Bags Market
Textile Machinery and Equipment
Global Knitting Machinery Market