
 Yankee Dryer Market | 2026-2036
Yankee Dryer Market Size, Share, and Industry Trends Forecast 2026-2036
Yankee Dryer Market Analysis
Aftermarket service revenue is narrowing the margin pool once dominated by new equipment sales across the Yankee dryer supply base. Valmet Corporation leverages its installed base of over 1,500 Yankee dryers to sustain recurring service contracts and spare parts throughput. Kadant Inc. competes through its doctor blade and profiling systems that extend the operational life of existing dryer shells. Toscotec S.p.A. specializes in rebuilds and energy-efficient retrofits, anchoring its position in European and Asian tissue mills.
A Yankee dryer is a large-diameter, steam-heated drying cylinder, typically 2.5 to 6.0 meters in diameter and cast from gray iron or high-strength steel, designed to dry tissue and fine paper webs at speeds exceeding 2,000 meters per minute while imparting the crepe structure critical to product bulk and softness. Cast iron shells retain dominance in high-speed tissue lines due to thermal conductivity and machining heritage, though stainless steel and composite alternatives are gaining traction where corrosion resistance and reduced shell weight enable faster rotation and lower bearing loads. Application demand clusters in pulp and paper, where tissue-grade Yankee dryers command premium engineering margins, while food processing and chemical manufacturing represent smaller, specification-driven niches with longer replacement cycles.
EPA emissions standards for industrial boilers and the EU Green Deal carbon border adjustments shape Yankee dryer procurement by mandating heat recovery systems and condensate optimization. The EU F-Gas Regulation and REACH compliance on coating chemistries further constrain supplier material choices and aftermarket chemical portfolios. Stakeholders must monitor how evolving energy efficiency certifications and carbon accounting rules redefine total cost of ownership calculations for new versus rebuilt dryer assets.
Market Dynamics
The Yankee dryer market pivots on the tension between energy efficiency mandates and the capital intensity of shell replacement cycles, with regulatory pressure forcing tissue mills to optimize existing assets rather than deploy greenfield capacity.
Growth Catalysts
- EU Green Deal boiler efficiency mandates:European tissue mills must retrofit heat recovery systems onto existing Yankee dryers, creating sustained demand for condensate optimization engineering and shell rebuild services.
- Stainless steel shell adoption:Corrosion-resistant alloys enable faster rotation speeds and reduced bearing loads, attracting premium tissue producers seeking crepe quality improvements without full line replacement.
- China's pulp and paper cluster expansion:Provincial capacity targets in Shandong and Guangdong provinces drive procurement of high-speed cast iron Yankees for new tissue-grade production lines.
Market Restraints
- Gray iron feedstock volatility:Foundry-grade pig iron prices fluctuate with blast furnace capacity cuts, compressing margins for cast shell manufacturers dependent on long-dated material contracts.
- Specialized grinding equipment concentration:Precision shell resurfacing requires CNC grinding machines controlled by a limited supplier base in Germany and Italy, creating single-source vulnerability for aftermarket rebuilds.
- REACH coating chemistry constraints:ECHA restrictions on chrome-based release coatings force reformulation of Yankee surface treatments, extending qualification timelines for new chemical portfolios.
Strategic Opportunities
- Indonesian tissue mill modernization:Underpenetrated Southeast Asian markets present white space for energy-efficient retrofits as domestic producers seek export-grade softness specifications.
- Condensing steam turbine integration:Cogeneration convergence with Yankee steam systems enables mills to monetize waste heat through on-site power generation, improving total asset economics.
- US Inflation Reduction Act industrial efficiency incentives:Tax credits for heat recovery equipment accelerate payback periods for condensate optimization projects in American tissue facilities.
Industry Challenges
- Shell grinding artisan scarcity:Precision machinists capable of maintaining 0.025 mm shell tolerance across 6-meter diameters are retiring faster than training programs replace them.
- Legacy DCS integration friction:Modern steam profiling systems must interface with 1990s-era distributed control architectures, complicating automation upgrades without full line shutdowns.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Yankee Dryer Market |
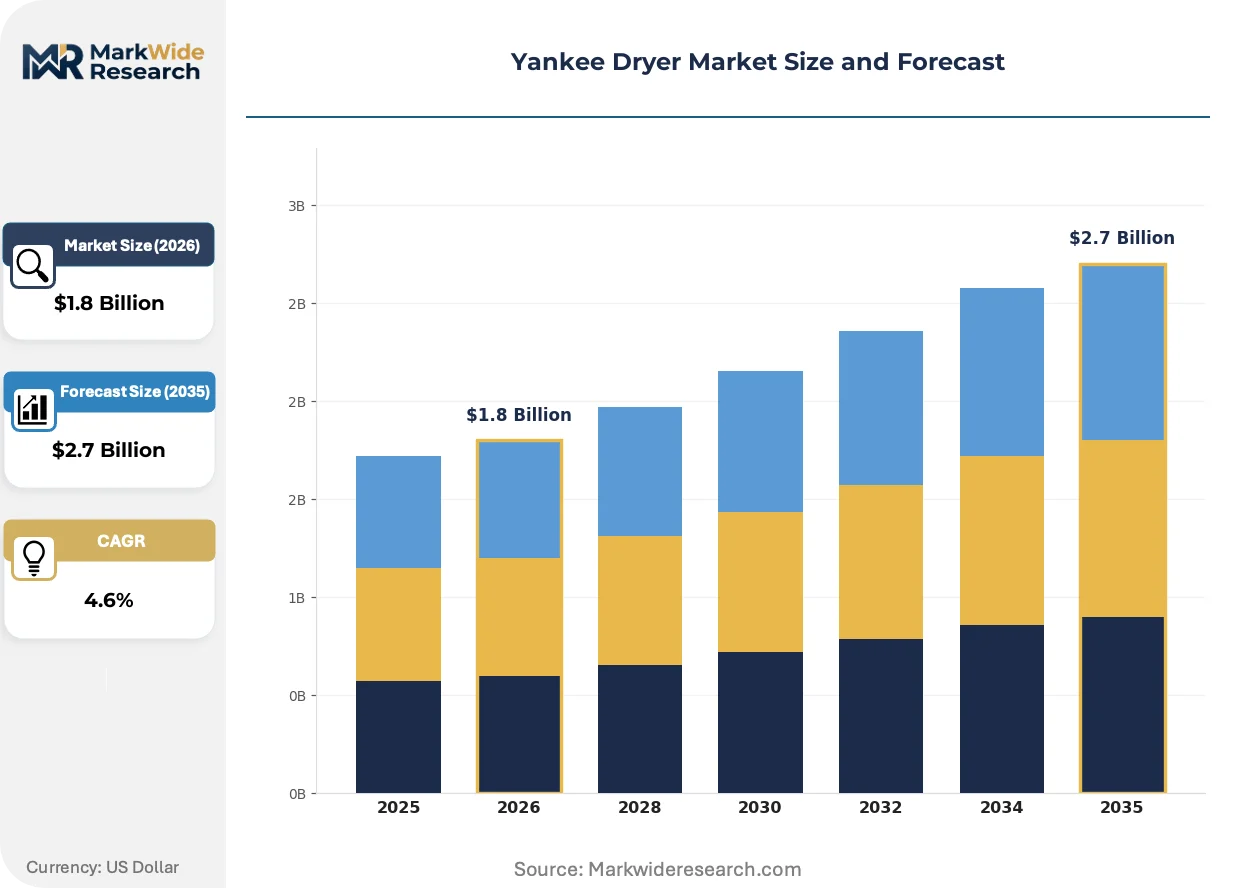
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cast Iron, Stainless Steel, Composite, Others Application: Pulp & Paper, Textile, Food Processing, Chemical Manufacturing Size: Small, Medium, Large, Extra Large End User: Manufacturers, OEMs, Industrial Facilities, Research Institutions |
| Companies Covered | Kadant Inc., Toscotec S.p.A., Valmet Corporation, Giesse Paper Machinery Srl, Shandong Xinhe Paper-Making Engineering Co., Ltd., Andritz AG, PMP Group Inc., Hergen S.p.A., Voith Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Yankee Dryer Market Emerging Trajectories
Advanced materials and digital steam profiling are compressing the performance gap between rebuilt and new Yankee assets, forcing suppliers to redefine value propositions around lifecycle optimization rather than equipment replacement alone.
Composite shell technologies incorporating carbon fiber reinforcement layers are collapsing the weight-performance tradeoff that historically favored cast iron for high-speed tissue applications. European premium tissue producers are piloting these hybrid constructions to achieve 15% rotational speed improvements without proportional bearing load increases. The structural consequence is a bifurcation in supplier capabilities, with traditional foundries losing position to engineered materials specialists capable of thermal-mechanical modeling.
EPA industrial boiler MACT standards and the EU F-Gas Regulation are tightening in parallel, mandating leak detection systems for steam condensate circuits and phasing down fluorinated greenhouse gases used in certain coating applications. Tissue mills in Germany and Wisconsin face overlapping compliance timelines that favor integrated heat recovery retrofits over standalone equipment purchases. The affected segment—mid-capacity tissue producers with 1990s-vintage Yankees—is consolidating procurement around full-system rebuild vendors rather than component suppliers.
Buyer concentration among multinational tissue brands is compressing supplier negotiation leverage through framework agreements that bundle Yankee service with stock preparation and winding equipment. Regional paper machinery distributors in Brazil and Turkey are losing position to direct mill relationships as procurement functions centralize at headquarters level. This pattern is most visible in Procter & Gamble and Essity's recent European capacity expansions, where single-source accountability clauses predominate.
Yankee Dryer Market Segmentation
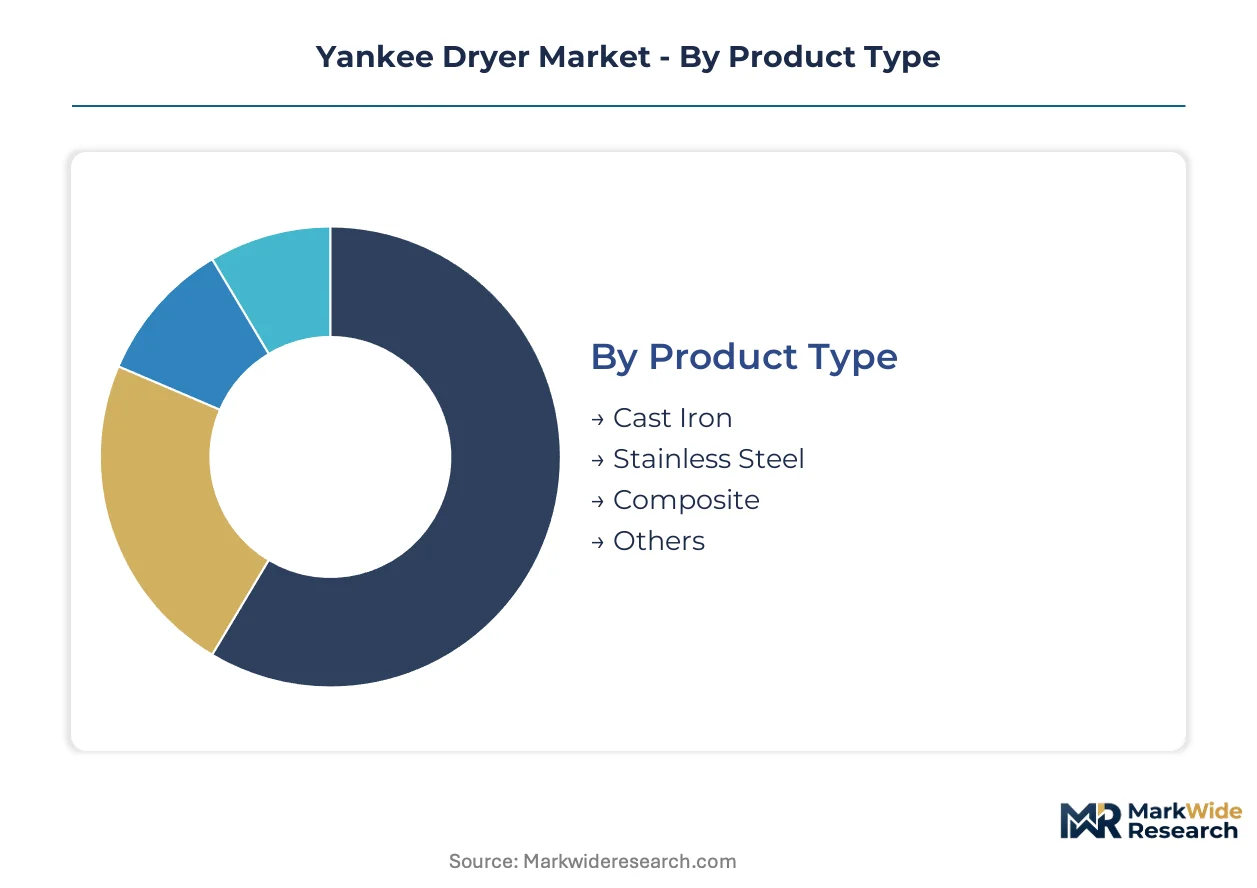
Yankee dryer procurement patterns diverge sharply across material specifications and operational scale, with tissue-grade applications commanding engineering premiums while peripheral segments follow replacement-cycle economics. Understanding these dimensional splits reveals where supplier margins concentrate versus where commoditization pressures dominate.
Product Type:
Material composition determines thermal performance limits, rotational speed ceilings, and corrosion resilience across Yankee dryer installations.
- Cast Iron:Gray iron shells deliver superior thermal conductivity and established machining protocols, retaining dominance in high-speed tissue lines exceeding 2,000 meters per minute across German and Chinese mill clusters. European foundries face margin compression from volatile pig iron feedstock contracts.
- Stainless Steel:Corrosion-resistant alloys enable 15% rotational speed improvements and reduced bearing loads, attracting premium tissue producers in Wisconsin and Guangdong seeking crepe quality upgrades without full line replacement cycles.
- Composite:Carbon fiber-reinforced hybrid constructions collapse historical weight-performance tradeoffs, piloting with European engineered materials specialists.
- Others:Experimental ceramic-coated and aluminum alloy variants serve niche chemical processing applications with lower thermal duty requirements.
Cast iron holds installed capacity. Stainless steel is rotating up the share rankings.
Application:
End-use differentiation separates high-frequency replacement markets from capital-intensive long-cycle segments.
- Pulp & Paper:Tissue-grade Yankee dryers absorb the majority of engineering R&D investment, with creping doctor systems and steam profiling commanding premium pricing from multinational tissue brands in North America and Europe.
- Textile:Lower-speed drying cylinders for nonwoven fabrics follow extended replacement timelines, concentrating demand in Turkish and Brazilian textile machinery corridors.
- Food Processing:Sanitary-grade stainless steel specifications dominate dairy and confectionery drying, with FDA compliance requirements extending qualification periods.
- Chemical Manufacturing:Corrosion-resistant coatings and specialized surface treatments serve pharmaceutical and specialty chemical producers with 15-20 year asset lifecycles.
Pulp and paper maintains volume leadership. Food processing is climbing fastest on regulatory compliance spending.
Size:
Diameter and width specifications align with production line throughput tiers and corresponding capital deployment strategies.
- Small:Compact units below 2.5 meters diameter serve pilot lines and specialty tissue producers in research-intensive configurations.
- Medium:Mid-range 2.5-4.0 meter shells balance throughput and rebuild economics, dominating Southeast Asian modernization programs.
- Large:4.0-5.5 meter diameter Yankees anchor high-volume consumer tissue lines, with Shandong province driving procurement concentration.
- Extra Large:Exceeding 5.5 meters, these units require custom foundation engineering and specialized transport logistics, limiting supplier participation to integrated mill system vendors.
Large diameter holds installed capacity. Extra large is rotating up the share rankings on greenfield tissue investments.
End User:
Customer type shapes procurement complexity, service contract structures, and technical specification authority.
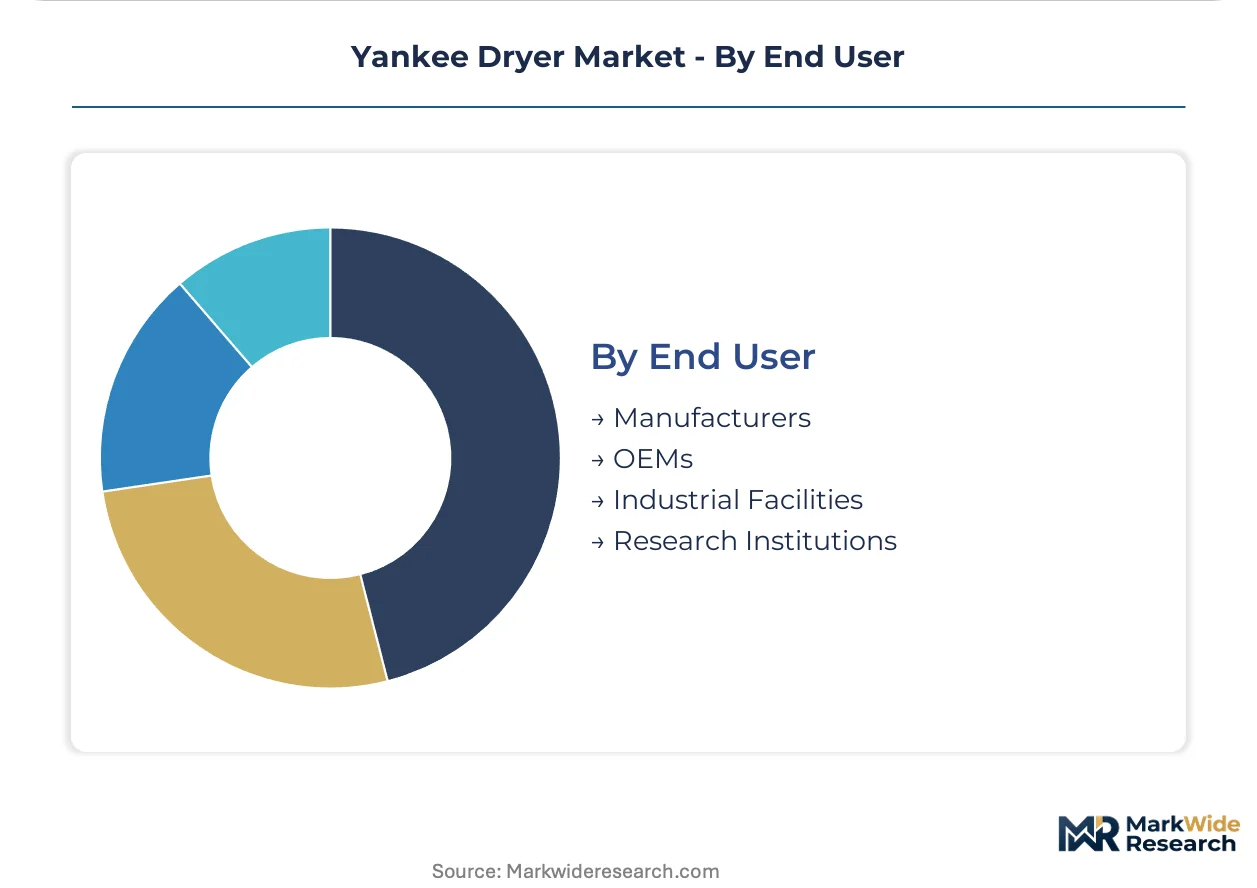
- Manufacturers:Tissue producers with captive engineering staff drive direct OEM relationships, consolidating procurement through headquarters-level framework agreements.
- OEMs:Paper machinery builders bundle Yankee dryers into complete line deliveries, capturing margin through system integration rather than component sales.
- Industrial Facilities:Chemical and food processing operators prioritize total cost of ownership calculations, extending replacement cycles through rebuild services.
- Research Institutions:University and government pilot facilities generate specification influence disproportionate to volume, shaping next-generation material qualifications.
Manufacturers hold installed capacity. OEMs are rotating up the share rankings on bundled line deliveries.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Foundry-grade cast iron supply and precision grinding equipment concentrate in German and Italian industrial clusters, while tissue production demand clusters in Wisconsin, Guangdong, and Shandong provinces. This geographic split between component fabrication and end-use installation shapes procurement logistics and service contract structures.
United States
Wisconsin tissue mills drive demand for stainless steel shell retrofits and condensate optimization systems. EPA industrial boiler MACT standards mandate heat recovery equipment upgrades, compressing payback periods for efficiency investments. Green Bay and Fox River Valley mill clusters anchor North American rebuild service demand.
Germany
EU Green Deal carbon border adjustments force tissue producers toward energy-efficient Yankee retrofits rather than greenfield capacity. ECHA REACH restrictions on chrome-based release coatings extend qualification timelines for surface treatment suppliers. Düsseldorf-Ruhr industrial corridor hosts precision CNC grinding equipment vendors critical to shell resurfacing.
China
Provincial capacity targets in Shandong and Guangdong provinces drive procurement of high-speed cast iron Yankees for new tissue-grade lines. MEE emissions standards for industrial boilers accelerate adoption of condensate optimization engineering. Qingdao and Dongguan machinery clusters concentrate domestic foundry and assembly capacity.
Italy
Premium tissue producers pilot carbon fiber-reinforced composite shells to achieve rotational speed improvements without bearing load penalties. EU F-Gas Regulation phases down fluorinated greenhouse gases in coating applications, forcing reformulation of Yankee surface treatments. Lucca and Bologna precision machining corridors supply specialized grinding equipment for shell rebuilds.
Indonesia
Domestic tissue producers seek export-grade softness specifications through energy-efficient retrofits of existing Yankee assets. National industrial efficiency programs incentivize heat recovery system installations. Surabaya and Jakarta mill clusters present white space for rebuild service vendors.
Yankee Dryer Market Vendor Landscape
Integrated mill system vendors and specialized component fabricators split the market between bundled line deliveries and aftermarket rebuild services. Consolidation pressure concentrates procurement authority at multinational tissue brand headquarters, compressing regional distributor margins. Two strategic archetypes dominate: full-system integrators capturing margin through single-source accountability clauses, and precision machining specialists controlling scarce shell grinding capacity. Competitive moves center on framework agreement consolidation and geographic expansion of service networks.
Among European-integrated specialists, Valmet Corporation and Toscotec S.p.A. occupy positions exemplifying the full-system archetype, while Kadant Inc. represents the component-specialist vector. Shandong Xinhe Paper-Making Engineering Co., Ltd. anchors Chinese domestic fabrication capacity. These three named entities illustrate how geographic origin and organizational structure map to distinct competitive positioning within the supplier base.
| Leading Market Players |
|---|
| Kadant Inc. |
| Toscotec S.p.A. |
| Valmet Corporation |
| Giesse Paper Machinery Srl |
| Shandong Xinhe Paper-Making Engineering Co., Ltd. |
| Andritz AG |
| PMP Group Inc. |
| Hergen S.p.A. |
| Voith Group |
| Others |
Supply Flow & Price Mechanics
Foundry undercapacity in Germany and Italy is compressing gray iron shell availability, forcing Yankee dryer suppliers to prioritize framework contract customers while spot buyers absorb premium pricing for expedited delivery slots.
Pricing Analysis
Aftermarket service contracts generate lifetime value exceeding original equipment margins by substantial multiples. Pricing stratifies across premium, standard, and economy tiers based on shell material grade and certification to EU Green Deal efficiency standards. Cost compression in cast iron feedstock is intensifying because blast furnace capacity cuts in European foundries. Mid-cap tissue producers with aging assets exhibit highest price sensitivity, while multinational brands prioritize single-source accountability over unit cost.
Supply Chain Analysis
Contract foundries in Germany, Italy, and China hold concentrated Yankee shell casting capacity. Production draws from foundry-grade pig iron, precision CNC grinding equipment, and chrome-based release coating chemistries. Single-source vulnerability runs through the limited supplier base of CNC grinding machines in Düsseldorf-Ruhr and Lucca-Bologna corridors. Distribution runs through direct mill relationships and OEM system integrators, with regional distributors losing position to headquarters-level procurement centralization.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Yankee dryer market is accelerating through composite shell disruption and EU F-Gas Regulation compliance timelines that favor full-system rebuild vendors over component suppliers.
For Market Incumbents: Harden installed base lock-in through captive aftermarket service networks and condensate optimization engineering capabilities. Expand precision grinding capacity in German and Italian machining corridors before artisan scarcity worsens. Composite shell specialists threaten cast iron foundry margins; backward integration into carbon fiber thermal-mechanical modeling preserves positioning. For New Entrants and Emerging Players: Build out rebuild service capabilities targeting Indonesian and Southeast Asian tissue mills seeking export-grade softness specifications without greenfield capital deployment. Indonesia presents the most penetrable geography given underpenetrated energy-efficient retrofit demand. Lead with heat recovery system integration and condensate optimization engineering as the go-to-market wedge. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across composite shell manufacturing as carbon fiber reinforcement layers require specialized thermal-mechanical modeling infrastructure. The five-to-ten-year viability window favors engineered materials specialists over traditional foundries. Target acquisition candidates with captive precision grinding capacity and EPA or EU Green Deal certification portfolios. Monitor ECHA coating chemistry restrictions as the signal to watch for qualification timeline compression.| Strategic Initiative | Industry Significance |
|---|---|
| Heat Recovery System Retrofit | EU Green Deal boiler mandates in Germany and Wisconsin compress payback periods for efficiency investments. |
| Composite Shell Pilot Program | Carbon fiber-reinforced hybrids in Italy enable 15% rotational speed gains without bearing load penalties. |
| Precision Grinding Capacity Expansion | CNC equipment scarcity in Düsseldorf-Ruhr and Lucca-Bologna corridors threatens aftermarket rebuild throughput. |
| Condensate Optimization Engineering | Integrated steam profiling systems capture IRA tax credits for US tissue facilities in Wisconsin mill clusters. |
| Direct Mill Relationship Development | Headquarters-level procurement centralization at Procter & Gamble and Essity displaces regional distributors. |
Methodological Framework
The analysis maps cast iron, stainless steel, and composite Yankee dryer segments, each validated through maintenance directors, plant engineers, OEM procurement teams, and aftermarket service heads. Primary interviews with tissue mill engineering staff and paper machinery OEMs combined with secondary validation from EPA industrial boiler MACT filings, EU ECHA REACH registrations, customs trade data, and SEC equipment supplier disclosures. Bottom-up unit deployment tracking and top-down capacity utilization estimates triangulate market sizing.
Assumptions held fixed include EU Green Deal and EPA emissions standard enforcement timelines, foundry-grade pig iron supply elasticity, and artisan training program graduation rates. Segmentation dimensions modeled encompass shell material composition, application grade, diameter specification, and end-user procurement authority across the projection horizon. CAGRs derive from installed base replacement cycle analysis, greenfield capacity announcements in Shandong and Guangdong, and retrofit penetration elasticity to energy efficiency incentives.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Chinese domestic fabricators or accelerated composite shell adoption by European premium tissue producers would shift outcomes. Quarterly review of ECHA coating chemistry restriction timelines, MEE emissions standard implementation in Chinese provinces, and IRA tax credit utilization rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Textile Machinery and Equipment
Automatic Webbing Cutting Machines Market
Textile Machinery and Equipment
Embroidery Equipment Market
Textile Machinery and Equipment
Mesh Tarpaulin Sheets Market
Textile Machinery and Equipment
Textile Mill Electric Drives Market
Textile Machinery and Equipment
Middle East and Africa Textile Films Market
Textile Machinery and Equipment
Disposable Garment Bags Market
Textile Machinery and Equipment
Tarpaulin Sheets Market
Textile Machinery and Equipment
Direct to Garment Printing Market
Textile Machinery and Equipment
Fabric Cutting Machines Market
Textile Machinery and Equipment
Webbing Cutting Machine Market
Textile Machinery and Equipment
Cloth Measuring Machine Market
Textile Machinery and Equipment
Technical Textile Production Equipment Market
Textile Machinery and Equipment
Cotton Processing Equipment Market
Textile Machinery and Equipment
Automatic Fabric Folding Machines Market
Textile Machinery and Equipment
Embroidery Machine Market
Textile Machinery and Equipment
Sewing Machine Component Market