
 Direct to Garment Printing Market | 2026-2036
Direct to Garment Printing Market Size, Share, and Industry Trends Forecast 2026-2036
Direct to Garment Printing Market Analysis
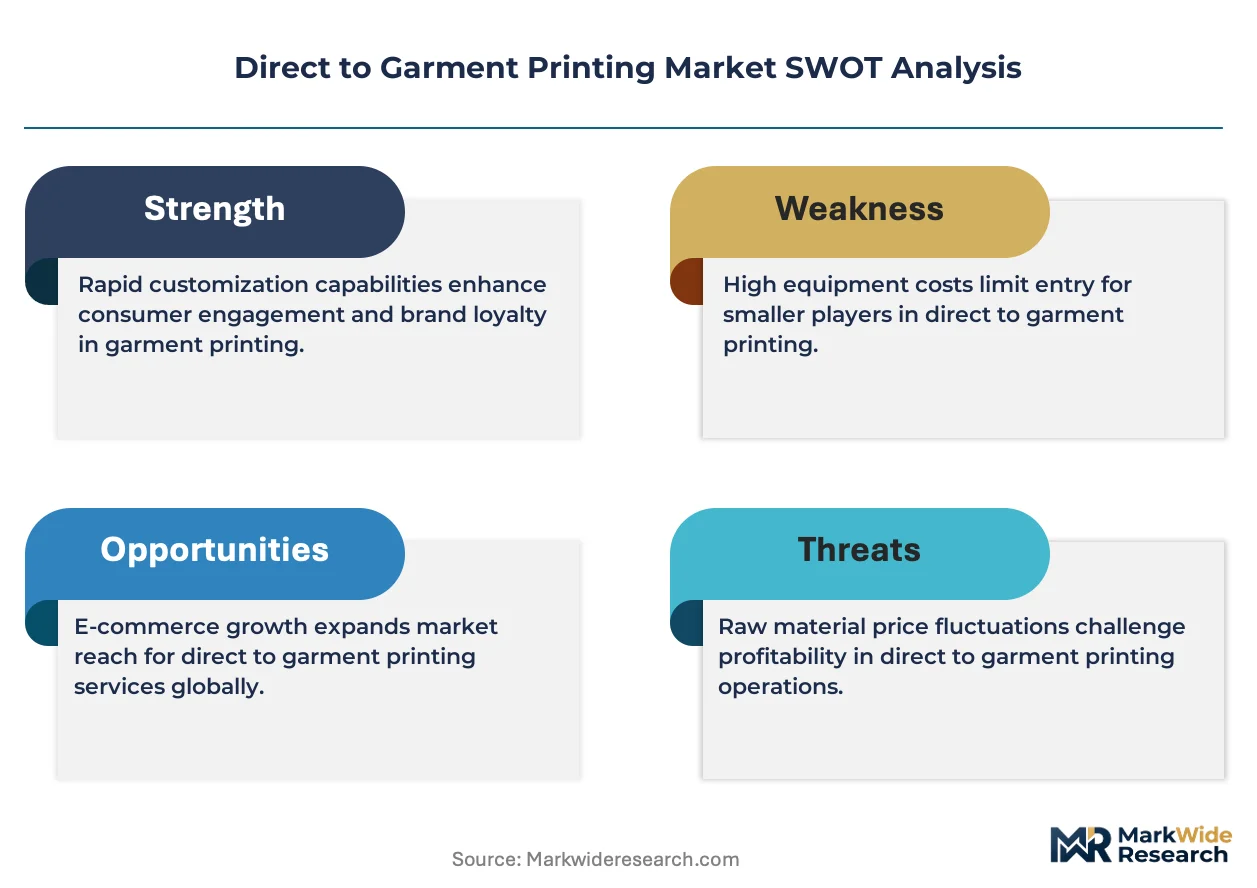
Asset-light leasing models for industrial DTG presses is narrowing the capital barrier for custom print shops entering production-scale operations. Printful leverages its vertically integrated software-to-fulfillment stack to sustain same-day throughput across multiple North American nodes. Custom Ink anchors consumer brand recognition through proprietary design tools that compete on creative workflow rather than unit economics alone.
Direct to garment printing deposits water-based pigment inks directly onto textile fibers using modified inkjet printheads operating at resolutions up to 1200 dpi, eliminating screen setup costs and enabling single-unit production runs. The technology segment splits between pure inkjet systems dominating established custom shops and hybrid direct-to-film configurations capturing entrants seeking transfer versatility. Product type concentration sits with t-shirts as the volume anchor, while hoodies command higher margin pools due to extended print areas and premium positioning.
FDA oversight of textile contact materials intersects with EPA regulations on volatile organic compound emissions from ink curing processes, pressuring equipment vendors to certify low-VOC thermal and UV curing subsystems. OEKO-TEX Standard 100 and REACH chemical restrictions in Europe further constrain formulation choices for suppliers serving cross-border e-commerce channels. Stakeholders must monitor how evolving state-level extended producer responsibility frameworks for textile waste reshape equipment amortization and ink recovery economics.
Market Dynamics
Water-based pigment ink formulations meeting OEKO-TEX Standard 100 requirements are compressing the operational envelope for custom print shops, forcing simultaneous compliance investment and workflow reconfiguration across the value chain.
Growth Catalysts
- Micro-fulfillment network expansion:Regional distribution centers across the United States are embedding DTG presses directly into last-mile nodes, collapsing inventory carrying costs for online apparel retailers.
- REACH chemical restrictions:European cross-border e-commerce channels are demanding certified ink formulations, creating competitive differentiation for suppliers with pre-validated OEKO-TEX Standard 100 portfolios.
- Hybrid direct-to-film configurations:New market entrants are adopting transfer-versatile equipment that reduces technical onboarding barriers for shops pivoting from screen printing.
Market Restraints
- Pigment ink supply concentration:Specialty chemical formulations for textile-grade pigments concentrate among a narrow supplier base in Germany and Japan, exposing print shops to input cost volatility.
- EPA volatile organic compound limits:Thermal and UV curing subsystems face certification bottlenecks, extending equipment procurement timelines for facilities in emission-controlled airsheds.
- Screen printing substitution resilience:Bulk promotional orders above 500 units retain cost advantages with conventional analog methods, capping DTG penetration in institutional procurement channels.
Strategic Opportunities
- India apparel manufacturing clusters:Tiruppur and Surat production hubs show underpenetrated DTG adoption despite established garment export infrastructure, presenting first-mover positioning for equipment lessors.
- State-level extended producer responsibility frameworks:California and New York textile waste mandates are creating service revenue pools for ink recovery and press refurbishment business models.
- AI-driven pre-treatment automation:Convergence of machine vision with robotic garment handling is compressing labor content per unit in high-throughput fulfillment centers.
Industry Challenges
- Color management specialist scarcity:RIP software calibration and ICC profile generation require hybrid technical-creative skill sets that outpace vocational training pipeline output.
- Legacy ERP integration friction:Shop management systems designed for screen printing workflows resist API-level connectivity with modern DTG fleet management platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Direct to Garment Printing Market |
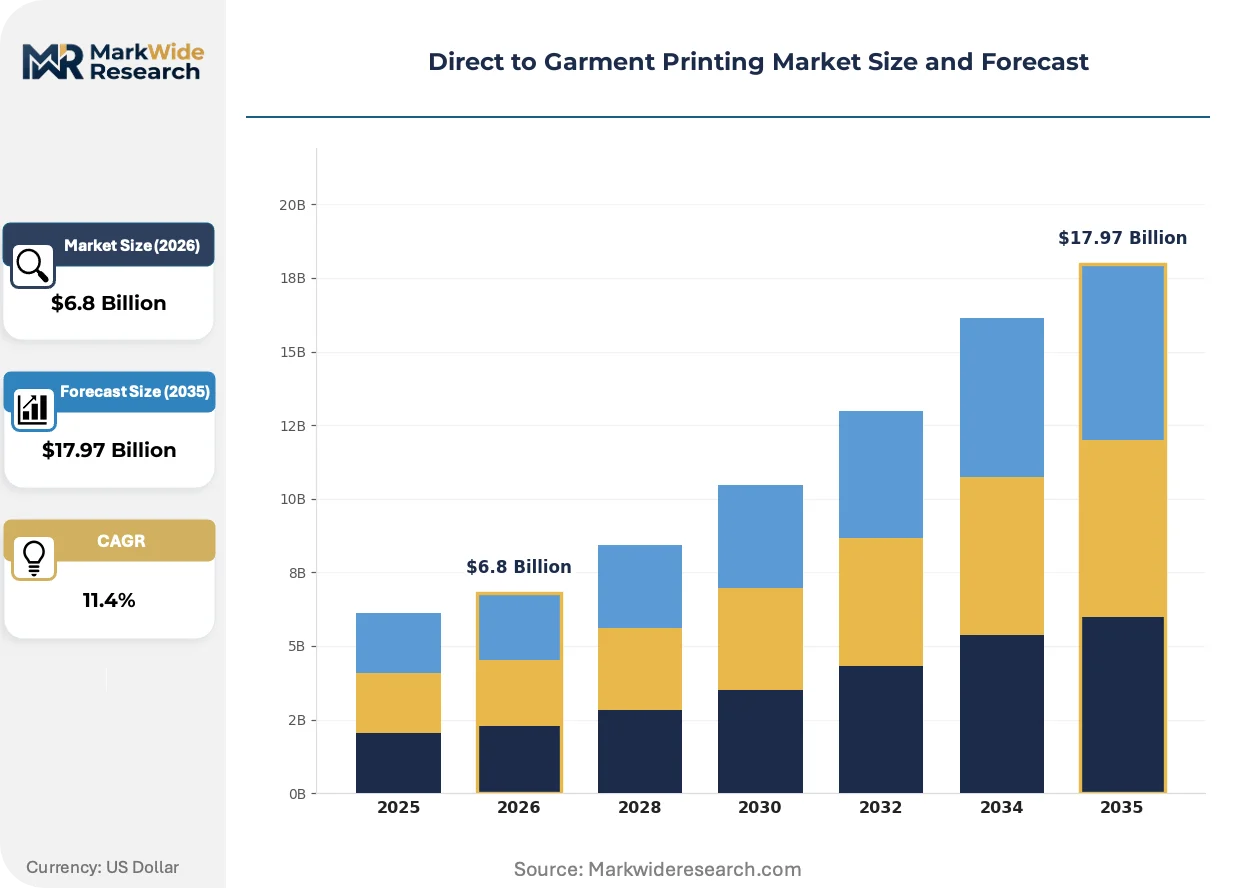
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $17.97 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Inkjet, Digital, Hybrid, Direct-to-Film Product Type: T-Shirts, Hoodies, Bags, Caps End User: Retailers, Online Stores, Custom Print Shops, Promotional Companies Material: Cotton, Polyester, Blends, Canvas |
| Companies Covered | Printify, Rush Order Tees, Printful, Broken Arrow Wear, Northwest Custom Apparel, Gelato, Custom Ink, Apliiq, CustomCat, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Direct to Garment Printing Market Emerging Trajectories
Active ink deposition control and automated pretreatment systems are compressing the labor-content-per-unit equation, while regulatory chemistry constraints are locking in formulation standards that favor early certifiers.
Industrial DTG printhead arrays are migrating from 600 dpi baseline resolution toward 1200 dpi native capability with variable droplet control. High-volume custom shops in the United States are adopting these systems to capture premium positioning in photographic reproduction segments. The technology migration from standard to high-definition deposition is enabling same-day fulfillment commitments that previously required overnight screen setup.
EPA oversight of volatile organic compound emissions from curing subsystems is tightening certification requirements for thermal and UV equipment categories. Equipment vendors must now submit third-party test data demonstrating sub-threshold VOC release rates before commercial deployment. California Air Resources Board implementation timelines are accelerating compliance investment cycles for print shops operating in the Los Angeles and San Diego metropolitan airsheds.
On-demand fulfillment contracts are displacing bulk pre-order commitments as the dominant procurement modality among mid-market online apparel retailers. Micro-fulfillment networks in Texas, Ohio, and Pennsylvania are capturing volume that previously flowed through centralized offshore screen printing. This channel rotation is most visible in influencer-launched fashion labels where design-to-door timelines compress below 72 hours.
Direct to Garment Printing Market Segmentation
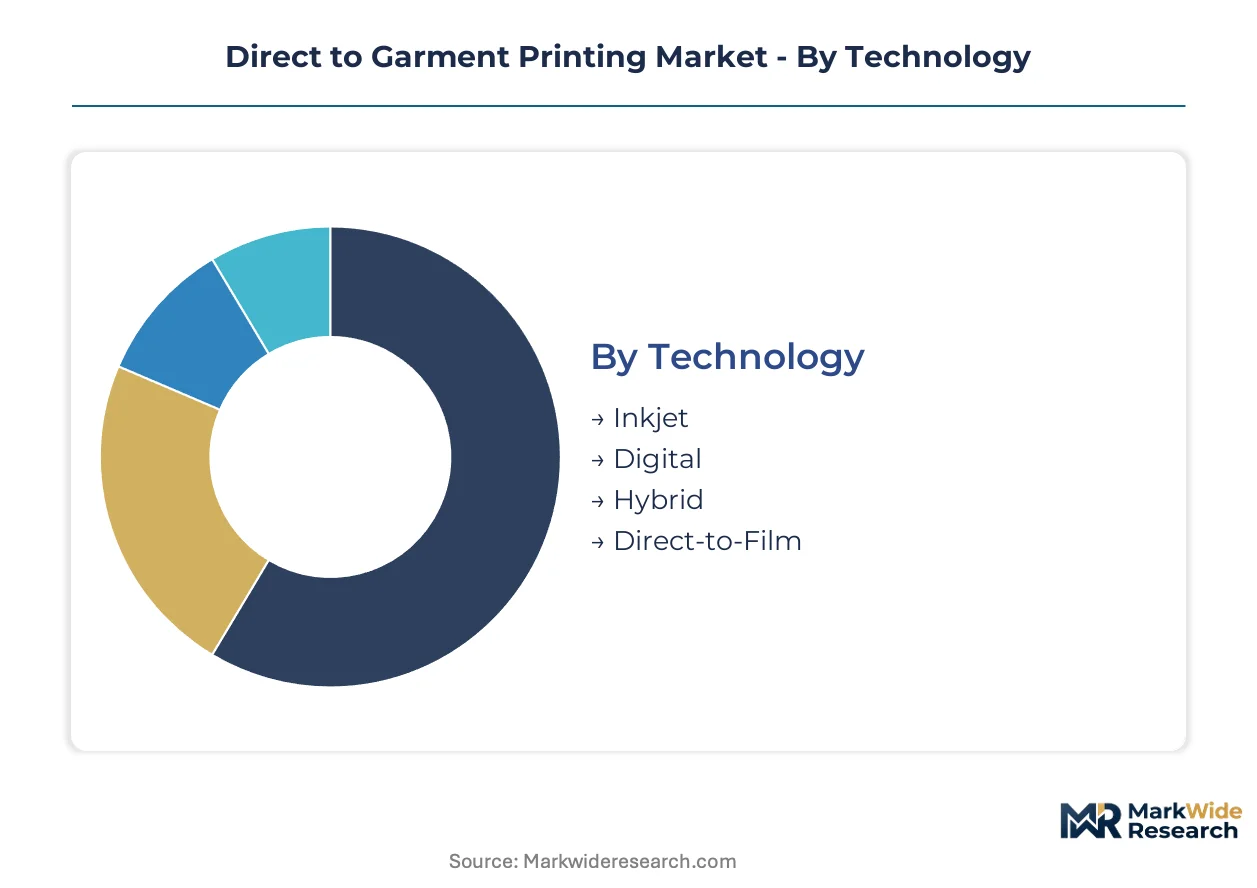
DTG market segmentation reveals how equipment specifications, substrate compatibility, and fulfillment models intersect to determine vendor profitability. Understanding these dimensional splits enables targeted positioning across the value chain from ink chemistry to last-mile delivery.
Technology:
Pure inkjet systems dominate high-throughput fulfillment, while hybrid configurations attract screen-printing converts seeking operational flexibility.
- Inkjet:Modified piezoelectric printheads deposit water-based pigment inks at resolutions up to 1200 dpi, enabling photographic reproduction without screen setup. Demand concentrates in United States micro-fulfillment networks where same-day throughput justifies capital intensity.
- Hybrid:Dual-mode systems combine direct-to-garment with direct-to-film transfer capability, reducing technical onboarding for shops pivoting from analog workflows. Adoption clusters among North American custom print shops serving promotional and event merchandise segments with volatile order sizes.
- Digital:Software-integrated presses with automated pretreatment and curing reduce labor content per unit in high-volume operations.
- Direct-to-Film:Transfer-versatile equipment enables printing onto non-cotton substrates and hard-to-reach garment areas, expanding addressable product scope.
Established volume favors Inkjet; emerging adoption favors Hybrid.
Product Type:
Margin structure varies sharply across garment categories based on printable surface area and positioning tier.
- T-Shirts:Cotton and cotton-blend tees constitute the volume anchor, with standardized print areas and streamlined pretreatment protocols supporting economies of scale. United States online apparel retailers drive procurement concentration for basic crew-neck styles in influencer-launched fashion labels.
- Hoodies:Extended print zones across front panels, sleeves, and kangaroo pockets command premium pricing, with heavier fabric weights requiring adjusted curing profiles. Demand concentrates in North American custom print shops serving collegiate and streetwear segments with higher willingness-to-pay for complex graphics.
- Bags:Canvas totes and drawstring bags present irregular print surfaces requiring specialized platens and pretreatment automation.
- Caps:Curved bill and structured crown geometries limit compatible equipment, constraining supplier base and sustaining price premiums.
Unit economics favor T-Shirts at scale; margin capture favors Hoodies in premium positioning.
End User:
Procurement sophistication separates enterprise fulfillment networks from fragmented custom shop demand.
- Retailers:Brick-and-mortar apparel chains integrate DTG for localized replenishment and limited-edition drops, collapsing inventory risk. Adoption concentrates among mid-market United States fashion retailers rebuilding post-pandemic supply chains around responsiveness rather than cost minimization.
- Online Stores:Pure-play e-commerce operators embed DTG presses into regional distribution nodes, enabling sub-72-hour design-to-door timelines. Demand clusters in Texas, Ohio, and Pennsylvania micro-fulfillment networks capturing volume from centralized offshore screen printing.
- Custom Print Shops:Small-batch producers serve individual consumers and local businesses with design-to-print workflows, prioritizing equipment versatility over raw throughput.
- Promotional Companies:Corporate merchandise suppliers face substitution pressure from screen printing above 500-unit order thresholds, capping DTG penetration in institutional procurement channels.
Volume concentration sits with Online Stores; margin sustainability sits with Retailers controlling brand equity.
Material:
Substrate chemistry determines ink formulation requirements and curing subsystem specifications.
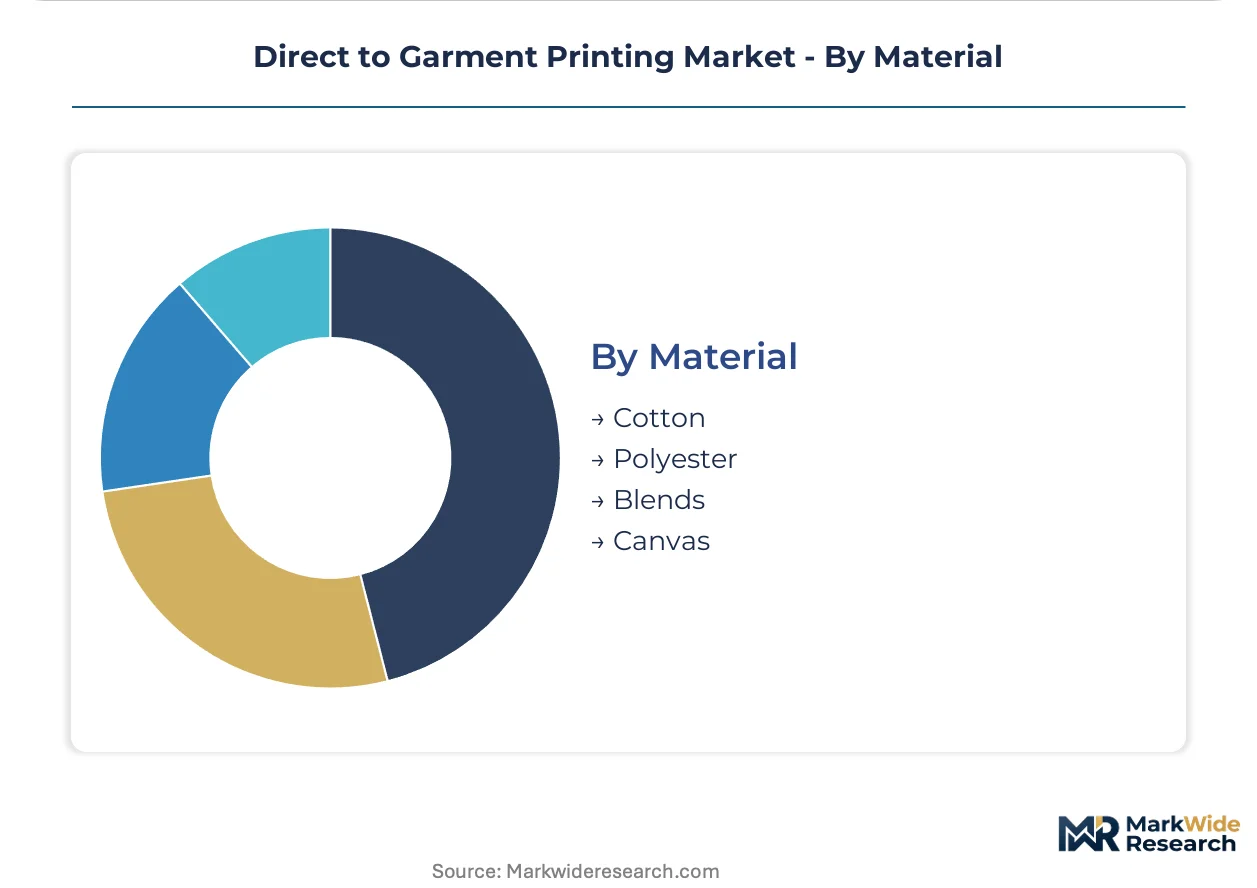
- Cotton:Natural fiber compatibility with water-based pigment inks simplifies pretreatment and maximizes color vibrancy, anchoring standard DTG workflows. United States custom print shops and online retailers drive procurement concentration for ringspun and combed varieties in premium positioning tiers.
- Polyester:Synthetic fiber dye migration and sublimation risks require specialized ink chemistries and lower-temperature curing protocols, constraining equipment compatibility. Demand concentrates in athletic and performance apparel segments where moisture-wicking properties command specification priority.
- Blends:Cotton-polyester mixtures balance hand-feel and durability, presenting intermediate technical requirements that hybrid systems address cost-effectively.
- Canvas:Heavyweight woven cotton demands reinforced platens and extended curing cycles, limiting compatible equipment to industrial-grade configurations.
Technical accessibility favors Cotton; performance requirements favor Polyester in athletic applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Trade flows in direct-to-garment printing equipment and consumables tilt heavily toward import-dependent markets, with manufacturing concentration in Germany and Japan creating supply bottlenecks for print shops in high-demand regions.
United States
Micro-fulfillment networks in Texas, Ohio, and Pennsylvania embed DTG presses directly into regional distribution nodes, collapsing inventory carrying costs for online apparel retailers. EPA volatile organic compound limits on thermal and UV curing subsystems extend equipment procurement timelines in California and New York metropolitan airsheds. Los Angeles and San Diego clusters face accelerated compliance investment cycles under California Air Resources Board implementation timelines.
Germany
Specialty chemical formulations for textile-grade pigments concentrate among narrow supplier bases, exposing European print shops to input cost volatility. REACH chemical restrictions constrain formulation choices for suppliers serving cross-border e-commerce channels. Stuttgart and Munich industrial zones anchor equipment vendor R&D activity for low-VOC thermal curing subsystems.
Japan
Piezoelectric printhead manufacturing concentrates in precision electronics corridors serving global DTG equipment assemblers. METI industrial standards shape equipment certification protocols for export markets. Osaka-Kobe manufacturing clusters supply modified inkjet printheads operating at resolutions up to 1200 dpi.
India
Tiruppur and Surat apparel production hubs show underpenetrated DTG adoption despite established garment export infrastructure. BIS certification requirements for imported textile machinery create procedural friction for equipment lessors entering the market. Maharashtra and Gujarat industrial zones present first-mover positioning opportunities for regional distribution networks.
United Kingdom
Post-Brexit regulatory divergence from REACH frameworks creates formulation compliance complexity for ink suppliers serving EU and UK markets simultaneously. London and Southeast England concentrate demand from influencer-launched fashion labels compressing design-to-door timelines below 72 hours. Midlands manufacturing corridors integrate DTG for localized replenishment in mid-market retail chains.
Direct to Garment Printing Market Vendor Landscape
On the supply side, the industry is consolidating around vertically integrated fulfillment operators and fragmenting across specialized custom print shops. Equipment vendors compete through certification velocity for low-VOC curing subsystems. Three strategic archetypes dominate: software-integrated fulfillment networks, design-tool-centric consumer platforms, and hybrid direct-to-film equipment specialists. Competitive moves concentrate on geographic node expansion and proprietary workflow automation.
Within the fulfillment network tier, Printful and Printify exemplify vertically integrated software-to-fulfillment stacks sustaining same-day throughput across multiple North American nodes. Custom Ink anchors consumer brand recognition through proprietary design tools that compete on creative workflow rather than unit economics alone. Rush Order Tees occupies a position among regional custom print shops leveraging hybrid direct-to-film configurations to reduce technical onboarding barriers for screen printing converts.
| Leading Market Players |
|---|
| Printify |
| Rush Order Tees |
| Printful |
| Broken Arrow Wear |
| Northwest Custom Apparel |
| Gelato |
| Custom Ink |
| Apliiq |
| CustomCat |
| Others |
Supply Flow & Price Mechanics
REACH chemical restrictions on textile-grade pigment formulations determine both three-tier pricing structure across premium, standard, and economy levels and the geographic clustering of supplier R&D investment. Print shops serving cross-border e-commerce channels absorb certification-driven cost premiums that compress margins at the economy tier while rewarding early OEKO-TEX Standard 100 certifiers with pricing power.
Pricing Analysis
Industrial OEM buyers anchor a hybrid pricing structure combining per-unit transactional rates with subscription-based fleet management tiers. Price differentiation rests on certification grade—OEKO-TEX Standard 100 versus uncertified formulations—and volume scale through micro-fulfillment network commitments. Cost compression in the economy tier is intensifying because specialty chemical suppliers in Germany and Japan concentrate pigment ink production. Small-batch custom print shops exhibit highest price sensitivity, while vertically integrated fulfillment networks controlling proprietary software stacks demonstrate lowest sensitivity due to workflow lock-in effects.
Supply Chain Analysis
Export-control scrutiny on precision piezoelectric printhead technology limits flows from Japan to non-allied manufacturing zones. Geographic supply concentration centers on Germany for specialty chemical formulations, Japan for modified inkjet printheads operating at resolutions up to 1200 dpi, and the United States for low-VOC thermal curing subsystem assembly. Raw material dependencies include water-based pigment dispersions, piezoelectric ceramic substrates, and UV-curable oligomer resins. Single-source vulnerability concentrates in Japanese printhead manufacturing corridors. Distribution runs through equipment vendor direct sales for industrial configurations and regional distributor networks for entry-level hybrid systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Direct to Garment Printing Market sits in early-cycle recovery as on-demand fulfillment contracts displace bulk pre-order commitments among mid-market online apparel retailers.
For Market Incumbents: Insulate margin pools by deepening backward integration into water-based pigment ink formulation capabilities, neutralizing supply concentration risk from German and Japanese chemical suppliers. Pursue OEKO-TEX Standard 100 pre-certification for curing subsystems ahead of California Air Resources Board implementation timelines, converting compliance investment into pricing power against uncertified competitors. For New Entrants and Emerging Players: Build out hybrid direct-to-film service capabilities in underpenetrated India apparel manufacturing clusters, specifically Tiruppur and Surat production hubs with established garment export infrastructure but minimal DTG adoption. Target first-mover positioning through equipment leasing models that circumvent BIS certification friction for imported textile machinery, offering regional distribution networks as a bundled value proposition. For Investors and Strategic Acquirers: The market sits at a capacity-expansion phase that favors vertically integrated software-to-fulfillment operators with same-day throughput capabilities across multiple North American nodes. Long-term viability over a 5-10 year window rests on AI-driven pre-treatment automation compressing labor content per unit. Monitor state-level extended producer responsibility framework adoption in California and New York as the signal for ink recovery and press refurbishment service revenue inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Low-VOC Curing Certification | EPA and California Air Resources Board compliance accelerates equipment vendor differentiation in emission-controlled airsheds. |
| Micro-Fulfillment Node Expansion | Regional distribution center embedding in Texas, Ohio, and Pennsylvania collapses inventory carrying costs for online apparel retailers. |
| AI-Driven Pre-Treatment Automation | Machine vision convergence with robotic garment handling compresses labor content per unit in high-throughput fulfillment centers. |
| Backward Integration into Ink Formulation | In-house water-based pigment chemistry development neutralizes supply concentration risk from German and Japanese specialty chemical suppliers. |
| Hybrid Direct-to-Film Configuration Launch | Transfer-versatile equipment reduces technical onboarding barriers for screen printing converts entering DTG workflows. |
Methodological Framework
Operator-level perspectives from custom print shop owners, equipment vendor technical sales directors, online apparel retailer supply chain managers, and specialty chemical formulation chemists anchored the qualitative base. Primary interview insights combined with secondary validation from EPA enforcement actions, California Air Resources Board regulatory filings, OEKO-TEX Standard 100 certification databases, and customs trade data on textile machinery imports. Bottom-up unit economics modeling triangulated against top-down market sizing across technology, product type, end user, and material segmentation dimensions.
Scenario-bracketing around regulatory compliance timelines and on-demand fulfillment adoption curves shaped the analytical framework across the projection horizon. Segmentation modeling captured technology splits between pure inkjet and hybrid configurations, product type concentration across t-shirts and hoodies, end user sophistication tiers from online stores to promotional companies, and material chemistry requirements for cotton versus polyester substrates. CAGRs derived from installed base expansion rates, fleet utilization assumptions, and average revenue per press calculations without year-specific anchoring.
The forecast holds incumbent behavior within observed patterns; aggressive moves by vertically integrated fulfillment networks or state-level extended producer responsibility mandates would shift outcomes. Material shifts in EPA volatile organic compound enforcement intensity or REACH chemical restriction scope expansion would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Textile Machinery and Equipment
Gel Dryer Market
Textile Machinery and Equipment
Mexico Screen Printing Mesh Market
Textile Machinery and Equipment
Global Textile Machinery Market
Textile Machinery and Equipment
Automatic Roll Filters Market
Textile Machinery and Equipment
Global Digital Textile Printing Machine Market
Textile Machinery and Equipment
Textile Printer Market
Textile Machinery and Equipment
Middle East and Africa Textile Films Market
Textile Machinery and Equipment
Linen Supply and Management Services Market
Textile Machinery and Equipment
T-Shirt Printing Machine Market
Textile Machinery and Equipment
Cloth Cutting Machines Market
Textile Machinery and Equipment
Global Industrial Fabric Market
Textile Machinery and Equipment
Dyeing Machine Market
Textile Machinery and Equipment
Netted Fabrics Market
Textile Machinery and Equipment
Cotton Processing Equipment Market
Textile Machinery and Equipment
Hoarding Tarpaulin Market
Textile Machinery and Equipment
Global Weaving Machinery Market