
 Electric Fabric Shaver Market | 2026-2036
Electric Fabric Shaver Market Size, Share, and Industry Trends Forecast 2026-2036
Electric Fabric Shaver Market Insights
Premium-grade motor specifications and stainless steel blade assemblies is bifurcating the competitive landscape into performance tiers. Philips leverages its grooming-appliance manufacturing scale to occupy the rechargeable segment with extended runtime architectures. Conair sustains brand strength across North American retail channels through dedicated fabric-care sub-brands. Steamery differentiates via Scandinavian design positioning and direct-to-consumer channel control in European markets.
An electric fabric shaver is a handheld electromechanical device employing rotary or oscillating blade systems, typically operating at 3,000–10,000 RPM, to remove surface pills, lint, and fuzz from woven and knitted textiles without damaging base fibers. Its primary commercial purpose is garment refurbishment and lifecycle extension for household, hospitality, and apparel resale applications. Rechargeable shavers lead volume shipments due to lithium-ion density improvements and cordless convenience expectations. Professional use applications command margin concentration as salon-grade units require higher duty cycles and replaceable blade systems. USB charging power sources represent the fastest-growing configuration as universal cable compatibility reduces accessory friction.
FCC electromagnetic emissions standards govern motor and charging subsystem compliance for US-bound products, while CE marking and EU RoHS substance restrictions shape material selection and market access protocols for European distribution. China's GB standards and NMPA-adjacent appliance safety frameworks regulate domestic manufacturing and import substitution patterns. Stakeholders must monitor battery transportation certification evolution and emerging right-to-repair disclosure requirements that could mandate replaceable blade and power module architectures.
Market Dynamics
USB-C charging integration and lithium-ion battery miniaturization are compressing product development cycles and forcing incumbent manufacturers to retool assembly lines around universal power architectures.
Growth Catalysts
- Household textile care demand:Consumers in Germany, China, and the United States are extending garment lifecycles through proactive maintenance, creating pull for rechargeable fabric shavers in residential settings.
- EU RoHS substance restrictions:These material selection protocols are accelerating lead-free soldering and recyclable plastic adoption, opening premium positioning for compliant manufacturers in European distribution channels.
- Appliance upgrade cycles:Shortened replacement timelines for small domestic appliances in urban Chinese households are generating volume demand for cordless, lithium-ion powered units with extended runtime specifications.
Market Restraints
- Blade steel price volatility:Stainless steel input costs for precision-machined rotary blade assemblies create margin pressure, particularly for manufacturers without captive metallurgical supply arrangements.
- Single-source battery dependency:Concentration of cylindrical lithium-ion cell production in East Asian manufacturing clusters exposes supply chains to logistics disruptions and tariff exposure.
- Motor RPM ceiling limitations:Thermal dissipation constraints in handheld form factors restrict maximum operating speeds, capping performance differentiation for premium-tier product positioning.
Strategic Opportunities
- Hospitality refurbishment services:Hotel chains and linen rental operators in France and Italy represent underpenetrated B2B demand for professional-grade units with replaceable blade systems and duty-cycle warranties.
- Right-to-repair disclosure mandates:Emerging European regulatory frameworks requiring modular component architecture could favor manufacturers with in-house blade and power module replacement programs.
- Direct-to-consumer channel control:Scandinavian design-positioned brands demonstrate margin capture through owned e-commerce platforms, bypassing retail markup structures in premium household segments.
Industry Challenges
- Battery transportation certification complexity:UN 38.3 lithium-ion testing protocols and IATA dangerous goods classifications create documentation burdens and shipping restrictions for cross-border fulfillment operations.
- Electromagnetic emissions compliance:FCC Part 15 testing for motor and charging subsystems requires specialized laboratory partnerships, extending product launch timelines for new market entrants.
- Blade geometry IP fragmentation:Patent thickets around oscillating versus rotary cutting mechanisms force licensing negotiations or design-around engineering investments for competitive feature parity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electric Fabric Shaver Market |
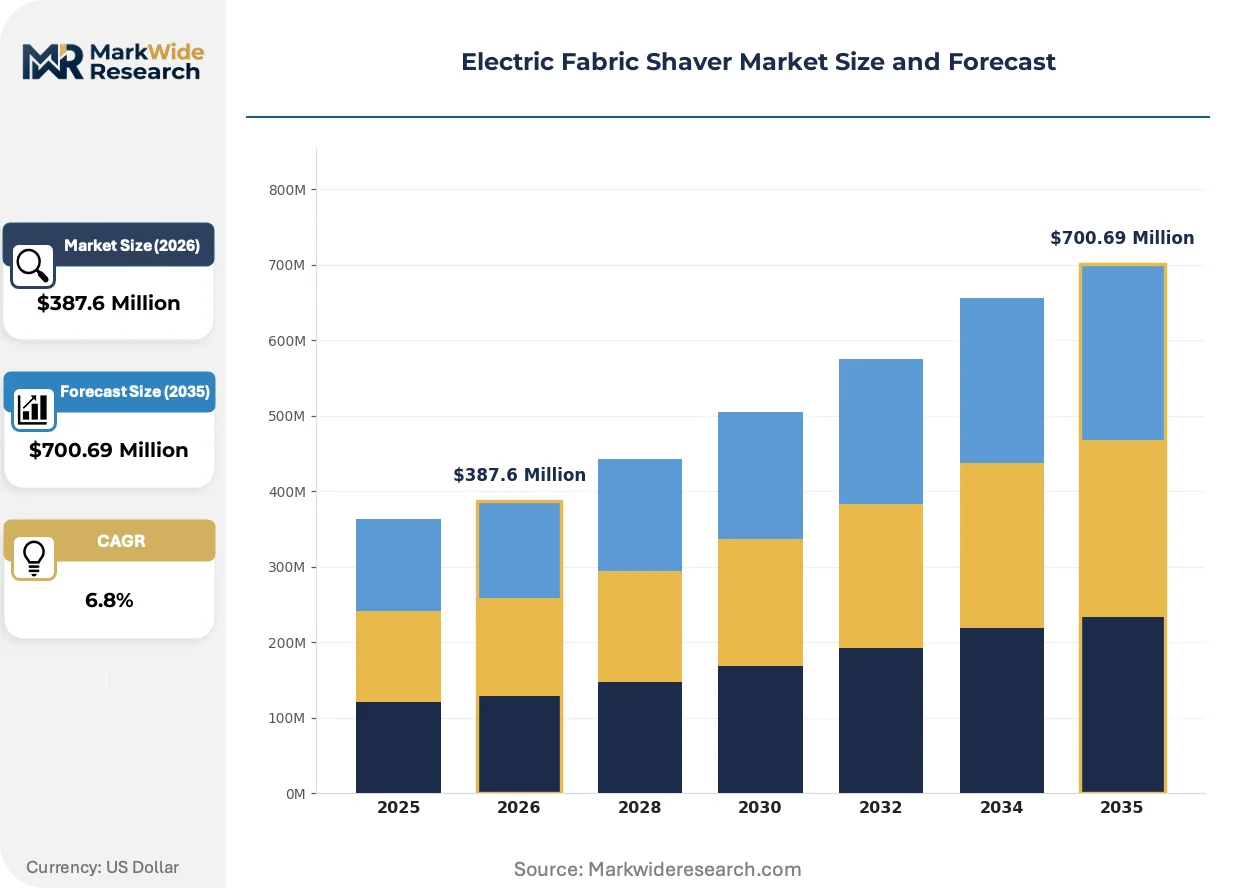
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $700.69 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Shavers, Battery-Operated Shavers, Corded Shavers, Rechargeable Shavers Application: Home Use, Professional Use, Travel Use, Commercial Use Power Source: Electric, Battery, Solar, USB Charging Material: Plastic, Stainless Steel, Aluminum, Composite |
| Companies Covered | Philips, Conair, Steamery, Beautural, Gleener, Sunbeam, Evercare, Norelco, Rowenta, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electric Fabric Shaver Market Trends and Innovations
Product architectures are converging around universal power standards and smart battery management, while sustainability disclosure requirements reshape material sourcing transparency across manufacturing tiers.
Brushless DC motor technology is displacing brushed alternatives in mid-tier and premium electric fabric shavers, delivering higher torque density and extended operational lifespan. Hospitality procurement departments and professional garment care services are specifying these motors for equipment refresh cycles. The shift is compressing warranty cost structures and enabling multi-year service contracts that were previously uneconomical.
EU battery passport requirements under the Ecodesign for Sustainable Products Regulation are mandating supply chain traceability for lithium-ion cells and recycled content thresholds. Manufacturers must now document carbon intensity and material provenance through digital product passports accessible to downstream buyers. Professional-grade equipment destined for European commercial laundries and textile rental operators faces the most immediate compliance deadlines.
Garment resale platforms and secondhand clothing marketplaces are creating concentrated demand for refurbishment tools among individual sellers and small consignment operators. These buyers prioritize compact form factors and USB charging compatibility over industrial durability specifications. The behavioral shift is most pronounced in metropolitan United States markets where online resale participation rates exceed national averages.
Electric Fabric Shaver Market Segmentation
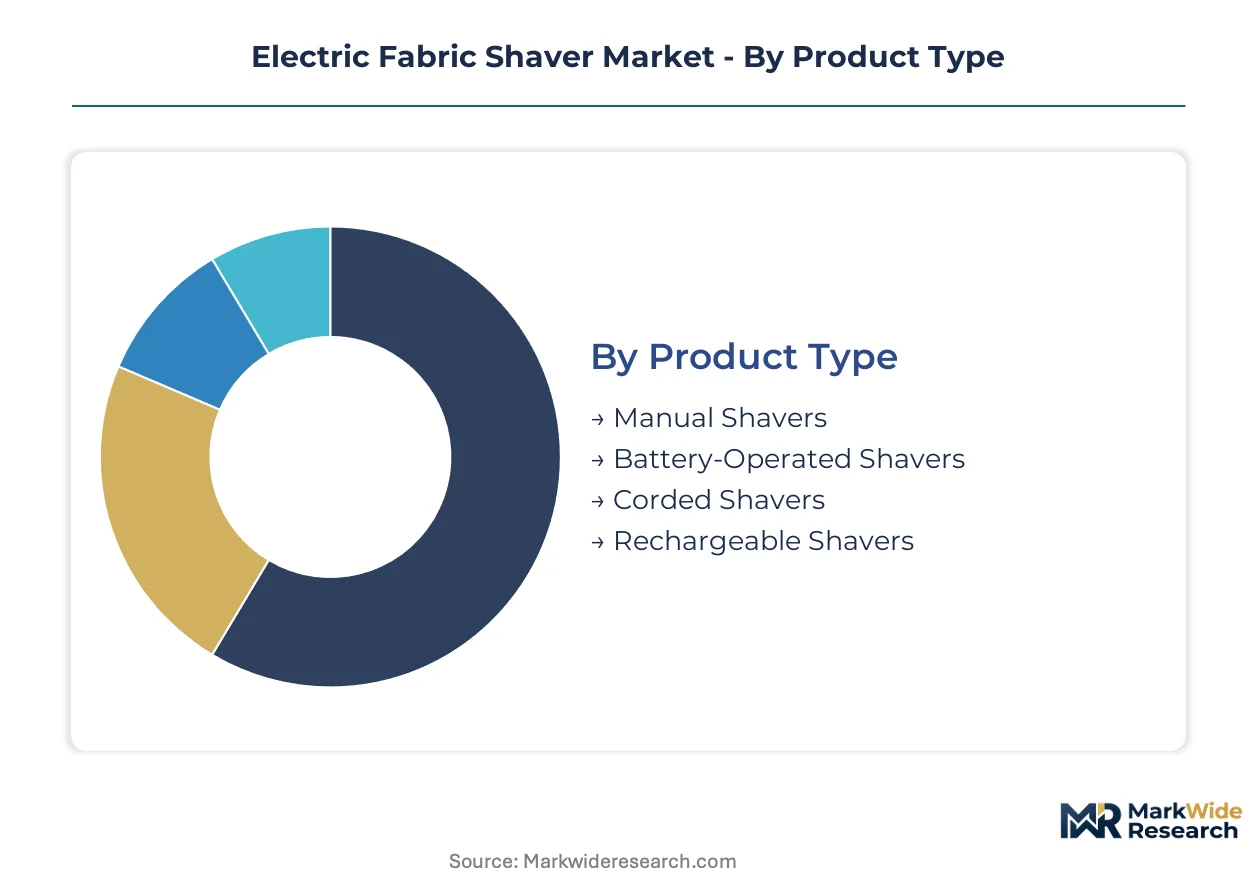
Channel mix varies sharply across electric fabric shaver segments. Rechargeable units flow predominantly through direct-to-consumer platforms, while corded alternatives anchor big-box retail. Professional-grade equipment moves through specialized B2B distributors serving hospitality and textile rental operators.
Product Type:
Channel concentration differs by power architecture. Battery-operated and rechargeable variants dominate e-commerce fulfillment, while corded and manual units sustain retail shelf presence.
- Rechargeable Shavers:Lithium-ion cell integration enables cordless operation with 45–90 minute runtime specifications. Demand concentrates in urban Chinese and German households where appliance upgrade cycles accelerate replacement of legacy corded units.
- Battery-Operated Shavers:Disposable alkaline or rechargeable AA/AAA configurations serve price-sensitive entry segments. North American discount retailers and travel convenience channels generate volume throughput for this architecture.
- Manual Shavers:Spring-loaded rotary mechanisms without electrical components target sustainability-conscious consumers seeking repairable, battery-free alternatives.
- Corded Shavers:AC-powered motors deliver sustained torque for heavy-duty applications in commercial laundry operations and professional garment care services.
Rechargeable shavers dominate installed base. Battery-operated configurations are where expansion concentrates.
Application:
Margin structure separates consumer from commercial deployment. Professional and commercial applications command 3–4x unit economics through replaceable blade systems and extended warranty terms.
- Professional Use:Salon-grade units with 10,000+ RPM brushless motors and modular blade cartridges serve garment care specialists and resale platform operators. France and Italy hospitality procurement departments specify these for linen refurbishment programs.
- Commercial Use:Hotel chains and textile rental operators in European markets demand duty-cycle warranties and bulk blade replacement contracts. EU battery passport compliance adds documentation overhead for this segment.
- Home Use:Residential consumers prioritize USB charging compatibility and compact storage footprint over industrial durability specifications.
- Travel Use:Pocket-sized form factors with universal voltage adapters target frequent travelers through airport retail and online marketplace fulfillment.
Professional use commands margin concentration. Home use drives volume scale.
Power Source:
Supply chain configuration shapes cost tier positioning. USB charging architectures leverage East Asian lithium-ion cell concentration, while solar variants face panel miniaturization constraints.
- USB Charging:USB-C integration enables universal cable compatibility, reducing accessory friction for cross-border e-commerce. This configuration is climbing the fastest in metropolitan United States markets where resale platform participation drives refurbishment tool demand.
- Battery:Cylindrical lithium-ion cell dependency exposes manufacturers to UN 38.3 transportation certification complexity and IATA dangerous goods restrictions.
- Electric:AC mains operation eliminates battery supply chain risk but constrains portability for consumer applications.
- Solar:Photovoltaic panel integration remains niche due to form factor limitations and inconsistent indoor light availability.
USB charging leads new product development. Battery configurations sustain legacy installed base.
Material:
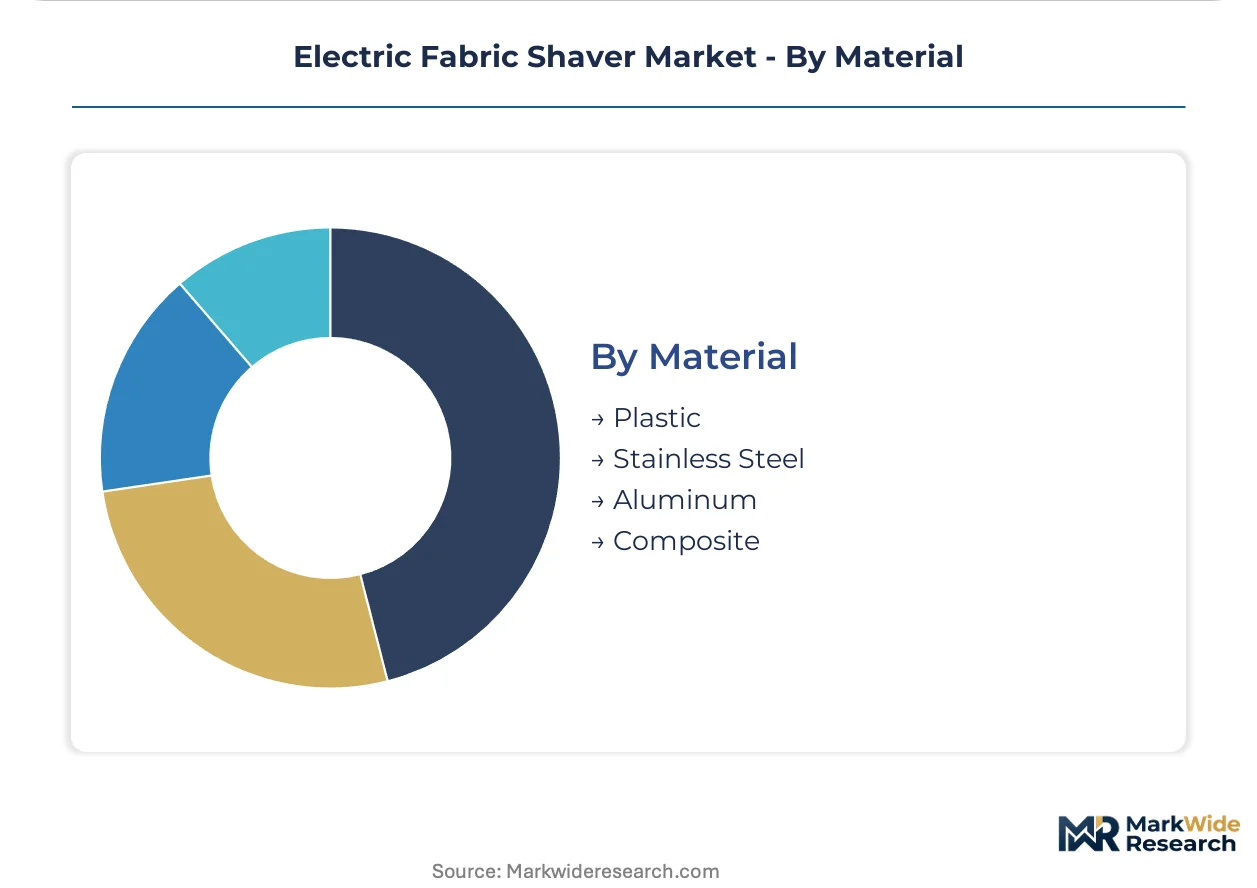
Regulatory pressure on substance restrictions favors certain material selections. EU RoHS compliance accelerates lead-free soldering and recyclable plastic adoption.
- Stainless Steel:Precision-machined rotary blade assemblies and motor housings deliver corrosion resistance and extended service life. Input cost volatility from nickel and chromium markets creates margin pressure for manufacturers without captive metallurgical arrangements.
- Aluminum:Die-cast chassis components reduce weight for portable configurations while meeting thermal dissipation requirements in high-RPM motor applications.
- Plastic:ABS and polycarbonate enclosures dominate economy tier production, with post-consumer recycled content ratios rising under Ecodesign for Sustainable Products Regulation thresholds.
- Composite:Glass-reinforced polymer blends balance structural rigidity with weight reduction in premium handheld designs.
Stainless steel anchors premium positioning. Plastic sustains mass-market volume.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's manufacturing dominance in lithium-ion cells and precision-machined components positions it as a net exporter of electric fabric shaver assemblies, while Germany and the United States import finished units to serve premium household and hospitality refurbishment demand.
China
Shenzhen and Dongguan manufacturing clusters supply cylindrical lithium-ion cells and brushless DC motor subassemblies to global OEMs. GB standards and NMPA-adjacent appliance safety frameworks regulate domestic production quality. Appliance upgrade cycles in urban households around Shanghai and Beijing accelerate cordless unit adoption.
Germany
EU RoHS compliance and CE marking requirements shape material selection for products entering European distribution. REACH substance restrictions accelerate lead-free soldering adoption among importers. Bavaria-based hospitality procurement departments specify professional-grade units with modular blade systems for linen refurbishment programs.
United States
FCC Part 15 electromagnetic emissions standards govern motor and charging subsystem compliance for domestic-bound products. Metropolitan resale platform participation in New York and Los Angeles drives USB charging configuration demand. Retail channel concentration through big-box and direct-to-consumer platforms fragments price positioning.
France
Hotel chains and textile rental operators in Paris and Lyon generate B2B demand for duty-cycle warranty equipment. Ecodesign for Sustainable Products Regulation battery passport requirements mandate supply chain traceability documentation. Auvergne-Rhône-Alpes industrial laundries specify professional-grade refurbishment tools.
Italy
Hospitality procurement in Milan and Rome concentrates demand for salon-grade units with replaceable blade cartridges. EU right-to-repair disclosure mandates favor manufacturers offering modular component architecture. Northern Italian textile rental operators drive commercial segment specification requirements.
Electric Fabric Shaver Market Competitive Landscape
Listed leaders compete with private specialists across channel control and design positioning. The vendor base spans grooming-appliance conglomerates, dedicated fabric-care sub-brands, and Scandinavian design-positioned direct-to-consumer operators. Three archetypes dominate: scale-driven manufacturers leveraging captive supply chains, design-forward specialists capturing premium margins through owned e-commerce, and hospitality-focused B2B providers with service contract capabilities. Competitive moves center on USB-C charging retooling and direct-to-consumer channel bypass of retail markup structures.
Among Netherlands-origin grooming conglomerates, Philips occupies the rechargeable segment archetype. Conair exemplifies North American retail channel strength through dedicated fabric-care sub-brand positioning. Steamery represents Scandinavian design-forward specialists with direct-to-consumer control in European markets.
| Leading Market Players |
|---|
| Philips |
| Conair |
| Steamery |
| Beautural |
| Gleener |
| Sunbeam |
| Evercare |
| Norelco |
| Rowenta |
| Others |
Pricing and Supply Chain Analysis
Sixty-day inventory cycles for cylindrical lithium-ion cells compress margin flexibility for shaver OEMs while concentrating pricing power with East Asian cell manufacturers who dictate terms through allocation priority. This lead-time environment forces brands to pre-position working capital or surrender margin to secure supply, embedding cost volatility directly into product tier positioning.
Pricing Analysis
Industrial OEM buyers anchor three-tier pricing structure across premium, standard, and economy levels. Price differentiation separates brushless DC motor configurations with extended warranties from brushed alternatives, with certification tier (CE marking versus non-compliant) adding secondary separation. Pricing pressure stems from nickel and chromium input volatility in precision-machined blade assemblies, compressing margins for manufacturers lacking captive metallurgical arrangements. Price-sensitive discount retailers and travel convenience channels absorb cost increases poorly, while hospitality procurement departments exhibit lowest sensitivity due to duty-cycle warranty bundling.
Supply Chain Analysis
Sixty-day inventory cycles for lithium-ion cells expose manufacturers to IATA dangerous goods shipping restrictions and UN 38.3 certification documentation burdens that extend fulfillment timelines. Supply concentrates in China, South Korea, and Japan for cylindrical cells and brushless DC motor subassemblies, with precision-machined stainless steel blade components drawing from German and Italian metalworking clusters. Single-source vulnerability sits with East Asian cell manufacturing concentration, amplified by tariff exposure on cross-border component flows. Distribution runs through direct-to-consumer platforms for rechargeable units, while corded alternatives sustain big-box retail anchoring.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward hospitality procurement departments and garment resale platform operators as these segments consolidate volume through multi-year service contracts and bulk refurbishment tool specifications.
For Market Incumbents: Consolidate backward integration into brushless DC motor production or captive blade steel sourcing to defend against margin compression from nickel price volatility. Lock in multi-year lithium-ion cell offtake agreements with Shenzhen and Dongguan manufacturers before allocation priority shifts to automotive and energy storage buyers. CE marking and EU battery passport compliance investments create switching costs that protect European hospitality accounts from design-forward entrants. For New Entrants and Emerging Players: FCC Part 15 certification fast-track through specialized electromagnetic testing laboratories in Shenzhen opens US market access without incumbent retail channel dependence. Target underpenetrated B2B hospitality refurbishment services in France and Italy, where hotel chains specify professional-grade units with replaceable blade systems and lack established supplier relationships. Direct-to-consumer e-commerce launch with USB-C charging compatibility bypasses retail markup structures and captures margin from metropolitan resale platform operators. For Investors and Strategic Acquirers: Carve-out targets emerge from grooming-appliance conglomerates seeking to divest non-core fabric-care sub-brands amid portfolio rationalization. Five-to-ten year viability hinges on right-to-repair regulatory momentum in European markets favoring modular component architecture. Watch EU Ecodesign for Sustainable Products Regulation enforcement intensity as inflection indicator for battery passport compliance cost structures that reshape competitive economics.| Strategic Initiative | Industry Significance |
|---|---|
| USB-C Charging Architecture Retooling | Universal cable compatibility reduces accessory friction for cross-border direct-to-consumer fulfillment. |
| Backward Integration into Brushless DC Motors | In-house motor production compresses warranty cost structures and enables multi-year service contracts. |
| EU Battery Passport Compliance Program | Digital product passport documentation secures access to hospitality procurement in France and Italy. |
| Direct-to-Consumer Channel Launch | Owned e-commerce platforms bypass retail markup and capture premium margin from design-conscious buyers. |
| Professional-Grade Modular Blade System Development | Replaceable cartridge architecture aligns with emerging right-to-repair disclosure mandates in European markets. |
Research Methodology
Initial hypotheses were tested against primary input from appliance product managers, hospitality procurement directors, garment resale platform operators, and lithium-ion cell supply planners, then refined through secondary validation. Primary fieldwork encompassed structured interviews with brand managers at grooming-appliance conglomerates, category buyers at North American big-box retailers, and aftermarket service heads at European textile rental operators. Secondary sources included FCC Part 15 electromagnetic emissions filings, EU Ecodesign for Sustainable Products Regulation draft texts, customs records for electric appliance trade flows, and SEC 10-K disclosures from listed personal-care appliance manufacturers. Bottom-up shipment estimates by power architecture and application were triangulated against top-down market sizing derived from household appliance penetration benchmarks.
Variance decomposition across the analysis window isolates volume drivers from price-mix effects. The analytical framework models segmentation dimensions including power source configuration, application tier, motor technology type, and regional regulatory cluster. CAGRs were derived from logistic adoption curves fitted to cordless replacement patterns in urban Chinese and German households, cross-referenced with lithium-ion cell cost-down trajectories and USB charging standard penetration rates. Brushless DC motor share assumptions and EU battery passport compliance cost pass-through estimates fed directly into margin projections.
The analysis sits within stated boundaries; outcomes outside sustained lithium-ion cell cost reduction, stable nickel and chromium input pricing, or unchanged electromagnetic emissions testing protocols would require recalibration. Forecasts reflect documented assumptions regarding appliance upgrade cycle timing and hospitality capital expenditure patterns. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Textile Machinery and Equipment
Europe Fabric Shavers Market
Textile Machinery and Equipment
Fiber Spinning Equipment Market
Textile Machinery and Equipment
Plasma Surface Treatment Machine for Leather Market
Textile Machinery and Equipment
Warping Machines Market
Textile Machinery and Equipment
Middle East and Africa Textile Films Market
Textile Machinery and Equipment
Automatic Roll Filters Market
Textile Machinery and Equipment
Cotton Processing Equipment Market
Textile Machinery and Equipment
Stringing Machines Market
Textile Machinery and Equipment
Automatic Webbing Cutting Machines Market
Textile Machinery and Equipment
Mexico Screen Printing Mesh Market
Textile Machinery and Equipment
Fabric Reversing Machines Market
Textile Machinery and Equipment
Direct to Garment Printing Market
Textile Machinery and Equipment
Spools Market
Textile Machinery and Equipment
Cloth Measuring Machine Market
Textile Machinery and Equipment
Fabric Cutting Machines Market
Textile Machinery and Equipment
Compact Spinning Machine Market