
 Stringing Machines Market | 2026-2036
Stringing Machines Market Size, Share, and Industry Trends Forecast 2026-2036
Stringing Machines Market Analytics
The capability gap between automated and manual production lines is collapsing as mid-tier manufacturers gain access to servo-controlled tensioning systems. Babolat leverages its European engineering heritage to sustain premium positioning in precision electronic machines. Gamma Sports anchors its competitive stance through vertical control over domestic US distribution channels. Yonex Co., Ltd. dominates Asian markets with manufacturing scale that supports both professional athlete and sports club segments.
Stringing machines are electromechanical devices that apply calibrated tension to synthetic or natural gut strings during racket preparation, with electronic models achieving pull accuracies within plus or minus one pound across tension ranges of eleven to ninety pounds. These machines serve the essential function of optimizing string bed performance for tennis, badminton, squash, and racketball players at competitive and recreational levels. Electric machines lead product type segmentation due to their balance of speed and precision in high-volume retail environments, while computerized machines represent the fastest-growing category as professional athletes and coaches demand programmable tension profiles. The application dimension tilts heavily toward tennis given its larger global participant base, though badminton stringing is gaining structural importance in Asian markets where the sport commands dominant viewership.
The US Consumer Product Safety Commission and the EU's CE marking framework both govern electrical safety standards for powered stringing equipment sold in their respective jurisdictions, with the EU F-Gas Regulation additionally shaping refrigerant-based component sourcing for climate-controlled manufacturing facilities. China's SAMR enforces GB standards for electromagnetic compatibility that affect imported electronic machine designs. Stakeholders must monitor how divergent efficiency regulations across the US, Europe, and China reshape component sourcing and final assembly location decisions.
Market Dynamics
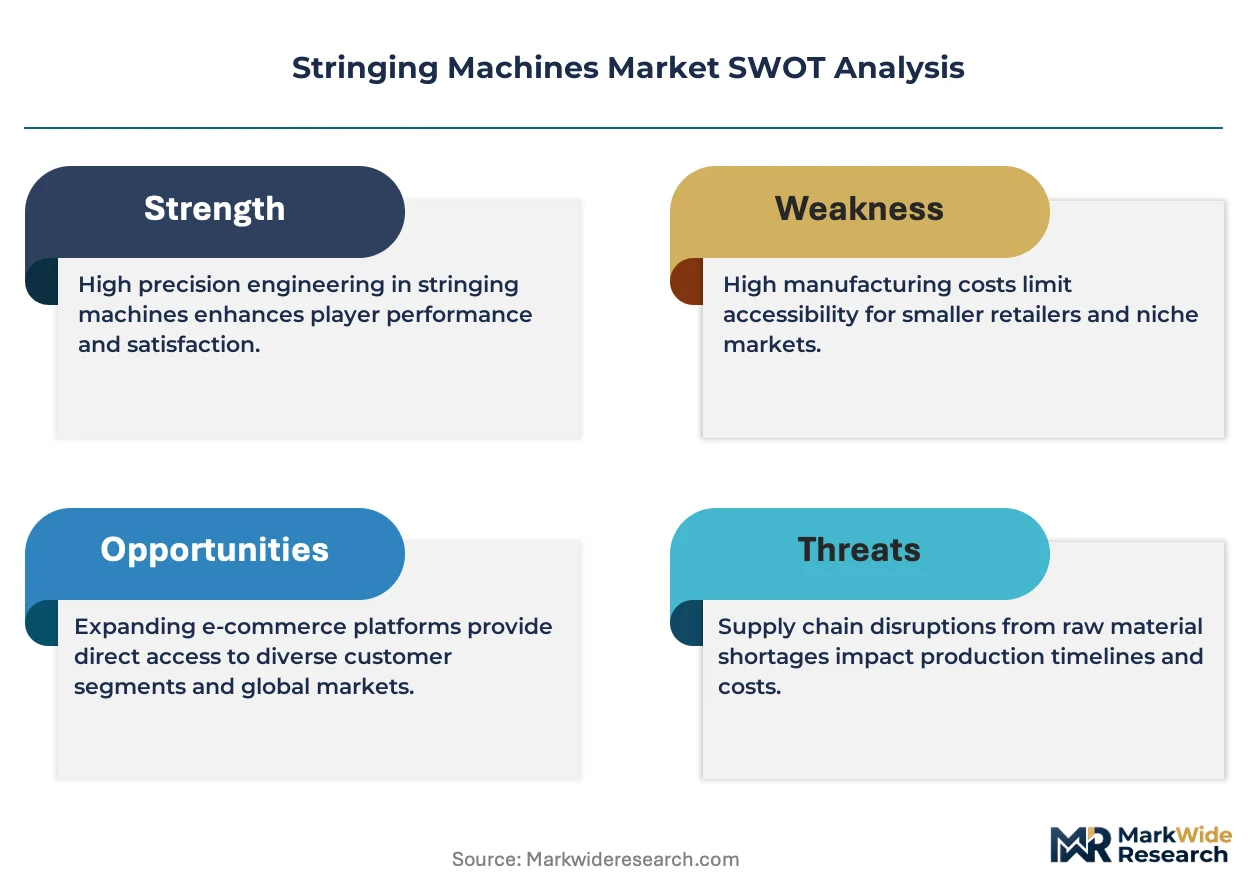
Servo-controlled tensioning systems are collapsing the performance gap between automated and manual stringing equipment, forcing mid-tier manufacturers to upgrade electromechanical architectures or exit the precision segment entirely.
Growth Catalysts
- EU Green Deal efficiency mandates:Energy-consumption directives are accelerating R&D investment into lower-wattage motor designs and regenerative braking systems for electric stringing machines.
- Badminton participation clusters:China and Indonesia are expanding domestic racket sports infrastructure, creating concentrated demand for high-throughput stringing services in urban training centers.
- Programmable tension profiling:Microprocessor-controlled machines now enable customized string bed configurations that adapt to individual athlete biomechanics and playing surfaces.
Market Restraints
- Copper and rare-earth magnet costs:Electric machine production faces input price volatility in servo motor components sourced from concentrated Asian smelting operations.
- CE marking compliance friction:Small-batch European manufacturers encounter extended certification timelines for electromagnetic compatibility testing under evolving EU F-Gas and electrical safety frameworks.
- Manual machine substitution persistence:Recreational players and budget-conscious tennis clubs continue purchasing mechanical crank machines for sub-fifty-pound tension applications.
Strategic Opportunities
- India's underpenetrated badminton infrastructure:The country's national sports federation is subsidizing racket sports academies in tier-two cities, opening service-provider demand for entry-level electronic machines.
- Direct-to-academy distribution:Manufacturers are bypassing traditional retail channels to sell calibrated maintenance packages directly to professional training facilities.
- ISO 9001 quality certification tailwinds:Sports clubs in Germany and Japan are mandating certified equipment for official tournament preparation, filtering non-compliant suppliers from procurement shortlists.
Industry Challenges
- Certified stringing technician scarcity:Professional racket sports associations in France and the United Kingdom report insufficient accredited personnel to operate precision electronic machines at major tournament venues.
- Legacy analog calibration drift:Service centers struggle to maintain tension accuracy in first-generation electronic machines without manufacturer-specific diagnostic software licenses.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Stringing Machines Market |
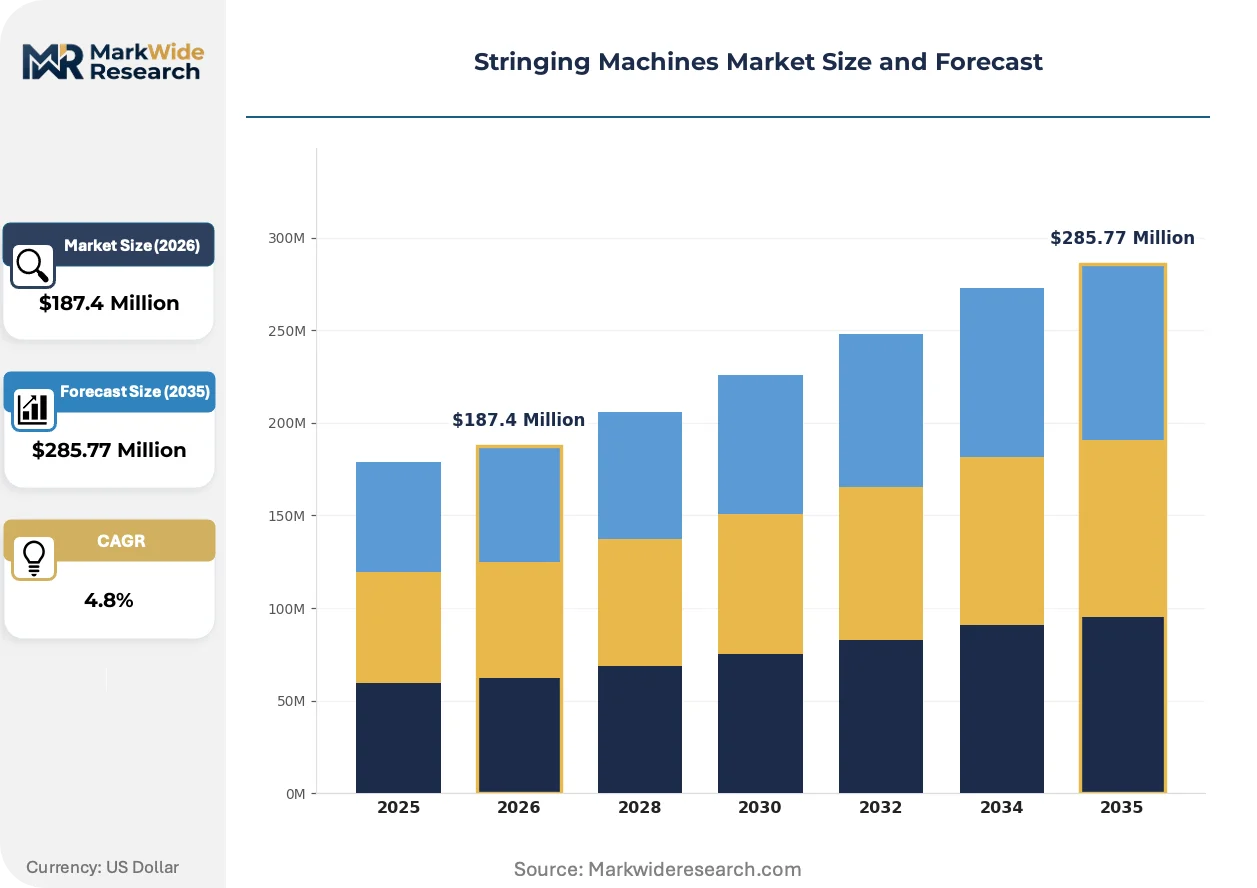
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $285.77 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Machines, Electric Machines, Hybrid Machines, Computerized Machines Application: Tennis, Badminton, Squash, Racketball End User: Professional Athletes, Coaches, Sports Clubs, Retailers Solution: On-Demand Service, In-Store Service, Mobile Service, Subscription Service |
| Companies Covered | Alpha Racquet Sports, Yonex Co., Ltd., Wilson, Prince, HEAD, Babolat, Eagnas, Klipper USA, Gamma Sports, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Stringing Machines Market Evolving Landscape
Digital tension logging and cloud-based string bed analytics are redefining how professional athletes and coaches optimize equipment performance across training cycles.
Servo-driven tension heads with closed-loop feedback is bifurcating the mid-market segment. These systems deliver sub-pound accuracy at price points previously reserved for manual machines. Regional tennis academies in Spain and Italy are adopting them for player-specific string customization. The technology is compressing margins for premium-tier manufacturers while enabling independent stringers to compete on precision metrics.
The EU F-Gas Regulation is reshaping climate-controlled manufacturing requirements for electronic machine assembly facilities. Component suppliers must now document refrigerant-free cooling systems in precision calibration chambers. German and Czech production sites are retrofitting clean-room infrastructure to maintain CE marking eligibility, while Chinese export-oriented factories face parallel GB standard compliance costs for electromagnetic compatibility certification.
After-sales service unbundling is disrupting traditional equipment distribution in North American markets. Buyers now purchase base machines through e-commerce channels while sourcing calibration contracts directly from manufacturer-authorized technicians. This pattern concentrates in California and Florida, where high-density tennis club networks support independent service provider ecosystems outside conventional dealer territories.
Stringing Machines Market Segmentation
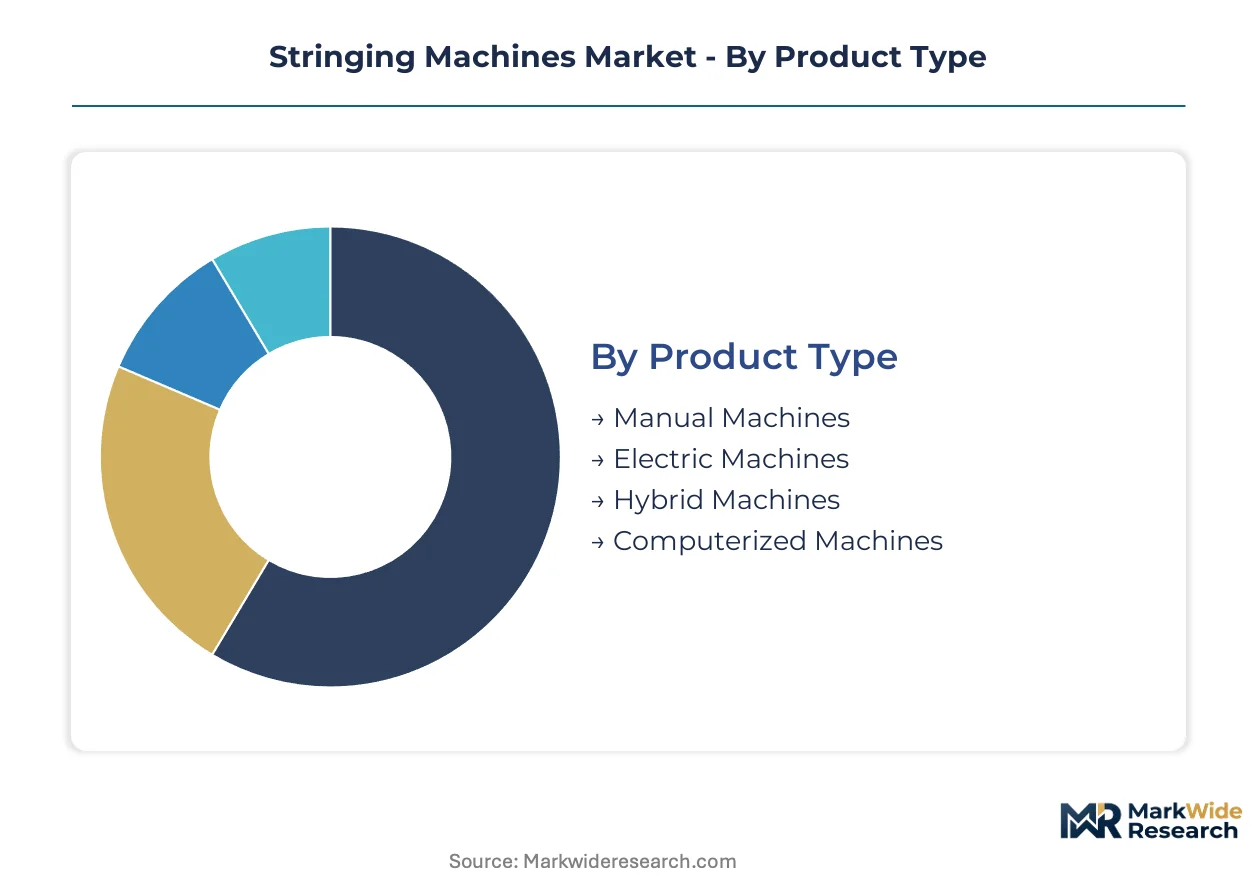
Segmentation in stringing machines reveals how precision requirements and service delivery models diverge across athlete tiers and geographic markets. Each dimension exposes distinct procurement patterns that shape manufacturer R&D priorities and distribution channel investments.
Product Type:
Electric and computerized machines dominate export flows from Germany and Japan, while manual equipment remains concentrated in domestic Chinese and Indian production serving local price-sensitive buyers.
- Manual Machines:Mechanical crank systems apply tension through spring-loaded or weighted mechanisms without electrical components. Demand clusters in India's tier-two badminton academies and Latin American recreational tennis clubs where capital constraints outweigh precision requirements.
- Electric Machines:Motor-driven tension heads achieve consistent pull speeds across extended operating sessions. Professional stringing services in Spain and Italy favor these units for their throughput balance, though EU Green Deal efficiency mandates are forcing motor redesigns to reduce wattage consumption.
- Hybrid Machines:Combine manual frame clamping with electric tensioning heads. Japanese tennis retailers deploy these for mid-tier customer segments seeking electronic accuracy without full automation costs.
- Computerized Machines:Microprocessor-controlled units with programmable tension profiles and digital logging. Momentum concentrates in Chinese professional training centers and German tournament venues where athlete-specific string bed analytics justify premium procurement.
Electric machines hold the largest share; momentum sits with computerized systems.
Application:
Cost tiers separate professional tournament preparation from recreational club use, with premium electronic machines reserved for competitive stringing and mechanical units saturating entry-level segments.
- Tennis:The largest participant base globally drives volume demand across all machine tiers. US tennis clubs in California and Florida operate high-throughput electronic stringing stations, while European tournament venues mandate certified computerized equipment for official preparation.
- Badminton:Stringing requires higher tension ranges and finer gauge compatibility than tennis. Indonesian and Chinese urban training centers are scaling dedicated badminton stringing services, creating concentrated demand for precision machines with specialized badminton mounting systems.
- Squash:Smaller global participant base limits dedicated machine procurement. Most squash stringing occurs on shared tennis-badminton equipment in multi-sport clubs across Egypt and the United Kingdom.
- Racketball:Predominantly North American demand with limited specialized equipment. Retailers in Texas and Arizona typically adapt tennis stringing machines for racketball specifications rather than investing in purpose-built units.
Tennis commands the largest installed base; badminton is climbing the fastest as Asian infrastructure investment accelerates.
End User:
Customer type determines whether procurement flows through retail channels, direct manufacturer relationships, or service-provider intermediaries.
- Professional Athletes:Require individualized string bed configurations with documented tension histories. These users source directly from manufacturer-authorized technicians in Germany and Japan, bypassing retail distribution entirely.
- Coaches:Operate multiple rackets across athlete rosters, prioritizing speed and consistency over customization depth. Spanish and Italian tennis academies favor mid-tier electric machines with rapid turnaround capabilities.
- Sports Clubs:Procurement decisions increasingly mandate ISO 9001 certification for tournament eligibility. German and Japanese clubs filter suppliers through formal quality frameworks, concentrating volume among certified manufacturers.
- Retailers:Face margin compression from after-sales service unbundling. North American sporting goods chains now compete with independent technicians who purchase base machines through e-commerce and source calibration separately.
Sports clubs represent the largest procurement volume; professional athletes are gaining share fastest as direct-to-athlete distribution models mature.
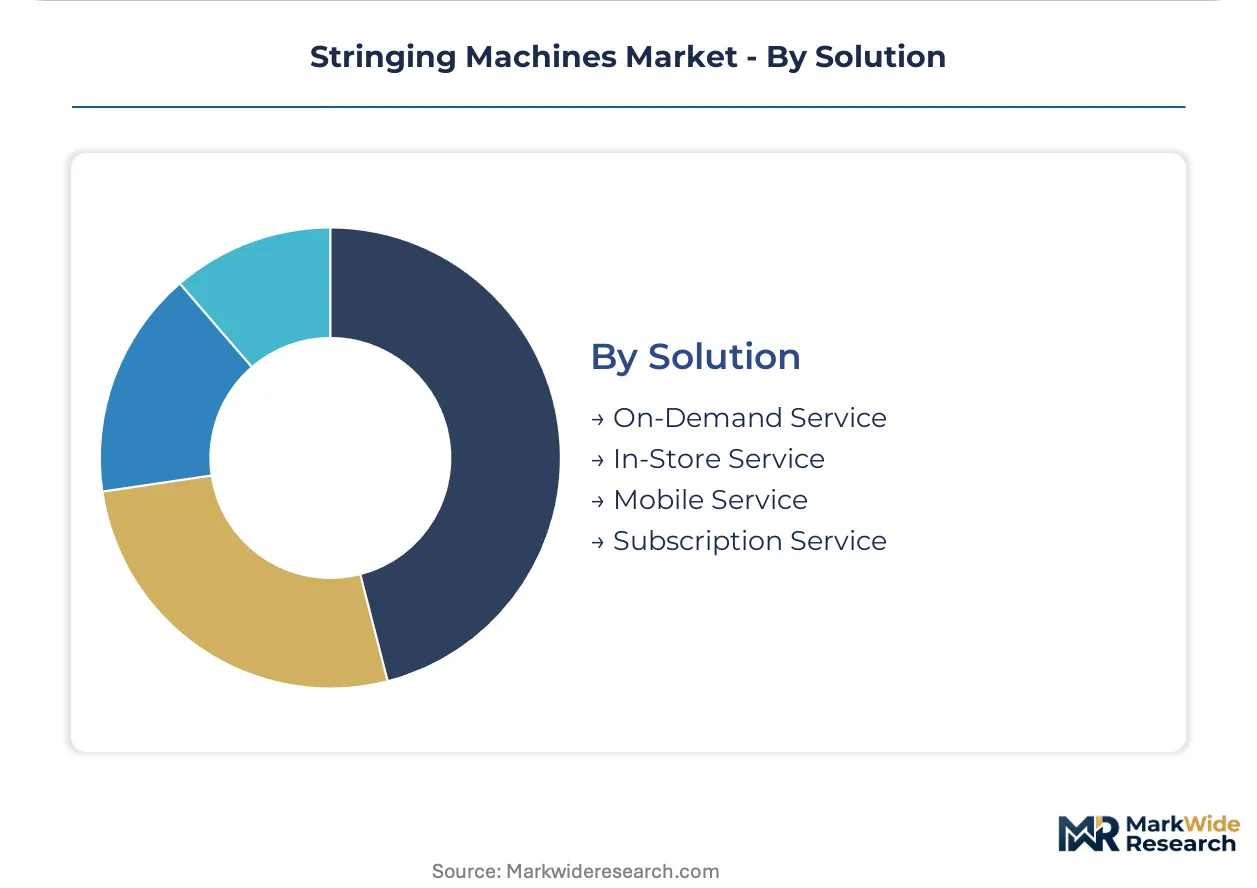
Solution:
Supply concentration in manufacturer-authorized technician networks is reshaping how calibration and maintenance services attach to equipment sales.
- On-Demand Service:Pay-per-stringing transactions at retail locations. These services concentrate in high-traffic urban centers where walk-in volume justifies dedicated machine staffing.
- In-Store Service:Integrated retail operations where stringing supports racket and accessory sales. US specialty tennis retailers in Florida and California use stringing as a traffic driver for higher-margin product categories.
- Mobile Service:Technician-operated equipment transported to tournaments and training camps. European tournament circuits rely on mobile providers for on-site stringing where venue infrastructure lacks fixed installations.
- Subscription Service:Fixed monthly fees covering unlimited stringing with priority turnaround. Emerging in Chinese professional training centers and Japanese tennis academies where predictable budgeting outweighs per-transaction pricing.
In-store service holds the largest share; subscription models are expanding most quickly as academy economics favor operational predictability.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China consumes stringing machines through high-volume training center deployment, while Germany and Japan prioritize precision-certified equipment for tournament venues. The United States splits demand between retail service stations and mobile technician fleets.
China
Urban badminton academies in Beijing and Shanghai are scaling dedicated stringing services for professional athlete preparation. SAMR enforces GB standards for electromagnetic compatibility on imported electronic machines. Manufacturing clusters in Guangdong Province supply both domestic racket sports infrastructure and export markets across Southeast Asia.
Germany
Sports clubs mandate ISO 9001 certification for tournament-eligible equipment procurement. The EU F-Gas Regulation shapes climate-controlled assembly requirements for precision calibration chambers. Bavarian production sites retrofit clean-room infrastructure to maintain CE marking eligibility for electronic machine exports.
United States
California and Florida tennis club networks support independent mobile technician ecosystems outside conventional dealer territories. The US Consumer Product Safety Commission governs electrical safety standards for powered equipment. E-commerce channels now capture base machine sales while calibration contracts flow directly to manufacturer-authorized technicians.
Japan
Professional athletes source individualized string bed configurations directly from authorized technicians, bypassing retail distribution entirely. METI oversees industrial standards for precision electromechanical equipment. Kanto region tennis academies adopt subscription service models with fixed monthly fees for unlimited stringing.
Indonesia
Domestic racket sports infrastructure expansion creates concentrated demand for high-throughput stringing services in Jakarta and Surabaya training centers. The national sports federation subsidizes academy development in tier-two cities. Local service providers favor entry-level electronic machines with rapid turnaround capabilities for badminton-specific mounting requirements.
Stringing Machines Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in the stringing machines market. European engineering heritage supports premium positioning in precision electronic equipment, while Asian manufacturing scale dominates volume production for professional and recreational segments. Three archetypes define competitive positioning: vertically integrated sports equipment conglomerates, precision electromechanical specialists, and regional fabrication houses serving price-sensitive domestic markets. Capacity expansion and direct-to-academy distribution models represent the dominant competitive moves reshaping channel economics.
Among Japanese sports equipment conglomerates, Yonex Co., Ltd. exemplifies the scale-driven archetype with manufacturing breadth spanning professional athlete and institutional segments. Babolat represents the European precision engineering tradition, leveraging electromechanical heritage to anchor premium-tier positioning. Gamma Sports occupies a position within the North American specialist tier, with vertical control over domestic distribution channels distinguishing its competitive stance against e-commerce entrants.
| Leading Market Players |
|---|
| Alpha Racquet Sports |
| Yonex Co., Ltd. |
| Wilson |
| Prince |
| HEAD |
| Babolat |
| Eagnas |
| Klipper USA |
| Gamma Sports |
| Others |
Value Network & Pricing Analysis
Long-term calibration service contracts lock in both supply access and price visibility for high-volume stringing operations, insulating German and Japanese tournament venues from spot-market volatility in servo motor components while binding Chinese training centers to fixed maintenance schedules under SAMR electromagnetic compatibility enforcement.
Pricing Analysis
After-sales service revenue tiers, particularly multi-year calibration contracts, now drive lifetime value more than equipment margins. Three-tier pricing structure across premium, standard, and economy levels separates ISO 9001-certified computerized machines from mid-tier electric units and manual crank systems. Pricing pressure stems from servo-driven tension heads achieving sub-pound accuracy at previously mid-market price points, compressing premium-tier margins. Budget-conscious recreational clubs in India and Latin America exhibit highest price sensitivity, while professional athletes in Japan and Germany prioritize precision over cost.
Supply Chain Analysis
Port congestion on Asia-Europe trade lanes elevates inbound logistics costs for German assemblers sourcing precision servo motors from Guangdong manufacturing clusters. Supply concentrates in China, Japan, and Germany for electronic machine production, with copper windings and rare-earth magnets drawing from concentrated Asian smelting operations. Single-source vulnerability in neodymium magnet supply creates structural risk for motor production. Distribution runs through manufacturer-authorized technician networks that bypass traditional retail channels in North America and Europe.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Stringing machines represent an early-cycle expansion story as programmable tension profiling penetrates professional training infrastructure, with China's subsidized badminton academy buildout accelerating adoption curves beyond historical recreational-club replacement rates.
For Market Incumbents: Fortify certified technician networks against independent service provider encroachment in California and Florida, where e-commerce base machine sales threaten dealer margins. Deepen backward integration into servo motor production to offset rare-earth magnet cost volatility from concentrated Asian suppliers. Prioritize ISO 9001 certification maintenance as German and Japanese sports clubs harden procurement filters. For New Entrants and Emerging Players: Lead with subscription service models targeting Chinese and Indonesian urban training centers, where predictable operational budgeting outweighs per-transaction pricing. India's tier-two badminton academies offer the most penetrable geography given national federation subsidies and limited incumbent presence. Deploy direct-to-academy distribution bypassing retail channel gatekeepers entirely. For Investors and Strategic Acquirers: Capital is best deployed toward precision electromechanical specialists with captive calibration service networks and CE marking compliance infrastructure already in place. Long-term viability over a five-to-ten year window favors manufacturers with demonstrated GB standard navigation for Chinese market access. Watch mobile technician fleet density in high-volume tennis corridors as the inflection signal for channel disruption maturity.| Strategic Initiative | Industry Significance |
|---|---|
| Direct-to-Academy Distribution Launch | Bypasses retail margin compression in California and Florida club networks. |
| Servo Motor Backward Integration | Captures rare-earth magnet supply chain exposure affecting Japanese and German assemblers. |
| ISO 9001 Certification Pathway | Unlocks procurement shortlists at German and Japanese tournament-eligible sports clubs. |
| Subscription Service Model Rollout | Aligns pricing with academy operational budgeting preferences in Beijing and Shanghai. |
| Mobile Technician Fleet Expansion | Captures on-site tournament stringing demand outside fixed venue infrastructure. |
Research Methodology
Operator-level perspectives from stringing service technicians, sports club procurement managers, racket sports federation equipment officers, and precision electromechanical engineers anchored the qualitative base. Primary interviews combined with secondary validation from SAMR GB standard filings, EU F-Gas Regulation compliance databases, and US Consumer Product Safety Commission electrical safety directives. Bottom-up demand modeling across training center deployment rates and top-down equipment replacement cycles were triangulated to establish market sizing.
Sensitivity analysis tested forecast robustness across copper price volatility scenarios and badminton infrastructure subsidy policy shifts. Segmentation dimensions modeled include product type tier, application sport, end-user archetype, and solution delivery mode across the projection horizon. CAGRs derived from equipment replacement cycle analysis and penetration rate trajectories in subsidized academy markets. Servo motor cost curves and CE marking compliance timelines served as industry-specific forecast inputs.
The analysis sits within stated boundaries; outcomes outside sustained Chinese badminton participation growth or EU Green Deal efficiency mandate enforcement would require recalibration. Forecasts reflect documented assumptions regarding technician certification pipeline expansion and rare-earth magnet supply concentration. Practitioners should keep alternative scenarios live as SAMR electromagnetic compatibility enforcement patterns and F-Gas Regulation clean-room retrofit timelines evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Textile Machinery and Equipment
Automatic Roll Filters Market
Textile Machinery and Equipment
Automatic Fabric Folding Machines Market
Textile Machinery and Equipment
Cloth Cutting Machines Market
Textile Machinery and Equipment
Industrial Sewing Machines Market
Textile Machinery and Equipment
Technical Textile Production Equipment Market
Textile Machinery and Equipment
Portable Fabric Canopies Market
Textile Machinery and Equipment
Textile Printer Market
Textile Machinery and Equipment
US Textile Processing Machinery Market
Textile Machinery and Equipment
3D Knitting Machines Market
Textile Machinery and Equipment
Global Digital Textile Printing Machine Market
Textile Machinery and Equipment
Europe Fabric Shavers Market
Textile Machinery and Equipment
Automatic Webbing Cutting Machines Market
Textile Machinery and Equipment
Drop Cloth Market
Textile Machinery and Equipment
Fabric Cutting Machines Market
Textile Machinery and Equipment
Gel Dryer Market
Textile Machinery and Equipment
Global Circular Knitting Machine Market