
 Textile Winding Machine Market | 2026-2036
Textile Winding Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Textile Winding Machine Market Insights
The gap between premium and commodity textile winding equipment is broadening as servo motor driven systems with electronic tension control command widening price premiums over mechanical control alternatives. Murata Machinery leverages its precision engineering heritage to anchor the high-throughput automatic segment in East Asian markets. Rieter Holding AG sustains competitive intensity through backward integration into yarn monitoring systems that pair with its winding platforms.
A textile winding machine is a yarn handling apparatus that transfers fibers from spinning bobbins onto cones, cheeses, or reels at controlled tension, typically operating at surface speeds between 800 and 2,000 meters per minute to prepare yarn for downstream fabric formation. Automatic winding machines with electronic control systems now dominate installed capacity in large textile mills, while precision winding machines for technical textile producers represent the fastest-expanding margin pool due to exacting denier tolerances in carbon fiber and aramid processing. Semi-automatic configurations retain relevance among mid-scale apparel manufacturers where capital constraints limit full automation.
CE marking requirements under the EU Machinery Directive and REACH chemical compliance for lubricants and coatings shape equipment specifications for European exports, while India's BIS certification mandates electrical safety standards for imported winding systems. The EU F-Gas Regulation constrains refrigerant choices in climate-controlled mill environments where humidity-sensitive winding operates. Stakeholders must weigh energy efficiency certifications against total cost of ownership when specifying machines for multi-decade mill investments.
Market Dynamics
Apparel manufacturers in Tamil Nadu and technical textile producers in Germany are driving divergent equipment specifications simultaneously, splitting demand between high-throughput automatic systems and precision winding platforms for carbon fiber processing.
Growth Catalysts
- Servo motor systems with electronic tension control:Apparel manufacturers adopt these to meet tighter fabric specifications for premium garment exports. The technology enables consistent yarn quality at surface speeds exceeding 1,500 meters per minute.
- EU Green Deal energy mandates:Mills across member states face binding efficiency targets that favor equipment retrofits. The directive accelerates replacement cycles for mechanical control winding machines.
- India's PLI scheme for textiles:State-level incentives in Tamil Nadu subsidize machinery upgrades for integrated spinning-winding operations. The policy concentrates demand in the Coimbatore-Tiruppur belt.
Market Restraints
- Copper and rare earth magnet cost volatility:Servo motor windings depend on neodymium and dysprosium supplies concentrated in Chinese processing facilities. Price swings compress margins for European and Japanese equipment builders.
- REACH chemical compliance for coatings:Lubricant formulations for high-speed spindles face restricted substance lists. Reformulation extends product development timelines by 12-18 months for EU-bound equipment.
- Mechanical control legacy installed base:Mid-scale apparel manufacturers in Bangladesh and Vietnam delay replacement due to capital constraints. This segment represents a stranded demand pool with limited near-term conversion.
Strategic Opportunities
- Technical textile precision winding:Carbon fiber and aramid processing for aerospace composites requires exacting denier tolerances below 0.5%. Equipment builders can command premium positioning in this underpenetrated margin pool.
- EU F-Gas Regulation climate control:Humidity-sensitive winding operations in climate-controlled mills must adopt compliant refrigerant systems. This creates bundled equipment-plus-HVAC specification opportunities.
- Semi-automatic configuration for mid-scale buyers:Capital-constrained manufacturers in Vietnam and Indonesia need stepping-stone automation. Modular upgrade paths from semi-automatic to full automatic capture this transition segment.
Industry Challenges
- Electromechanical technician scarcity:Servo-driven systems require calibration skills spanning mechanical engineering and programmable logic controllers. Mills in India's secondary textile clusters struggle to retain qualified personnel.
- BIS certification timeline for imports:Electrical safety testing for winding machines entering India extends lead times by 4-6 months. Certification bottlenecks disrupt just-in-time capacity expansion schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Textile Winding Machine Market |
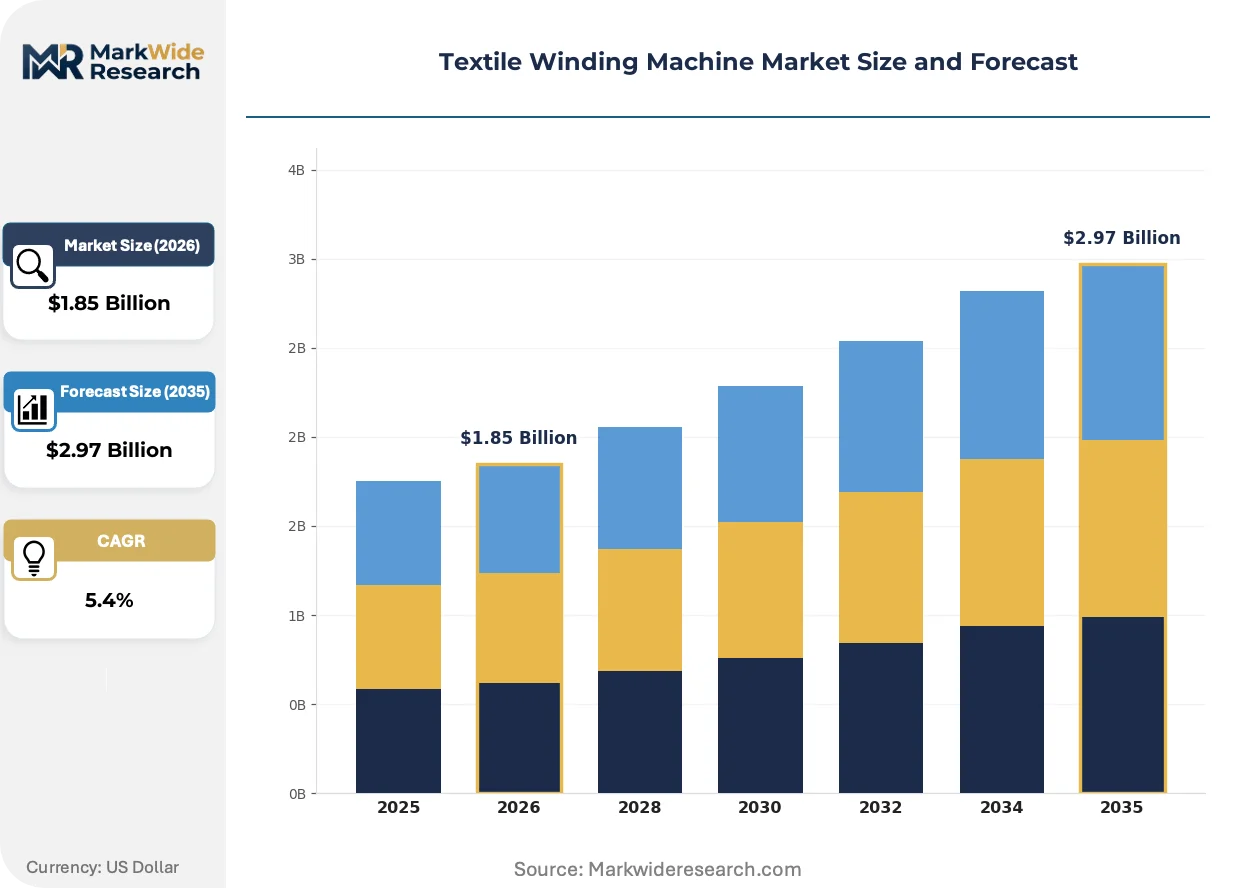
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $2.97 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automatic Winding Machines, Semi-Automatic Winding Machines, Manual Winding Machines, Precision Winding Machines Technology: Electronic Control, Mechanical Control, Pneumatic Control, Servo Motor Driven Application: Knitting, Weaving, Embroidery, Sewing, Braiding End User: Textile Mills, Apparel Manufacturers, Industrial Fabricators, Technical Textile Producers |
| Companies Covered | Murata Machinery, Rieter Holding AG, Saurer Group, SSM Schärer Schweiter Mettler AG, Savio Macchine Tessili, Lakshmi Machine Works, Vandewiele NV, TMT Machinery, Jingwei Textile Machinery, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Textile Winding Machine Market Trends and Innovations
Digital thread monitoring and predictive maintenance capabilities are redefining equipment specifications, with buyers now evaluating total cost of ownership across multi-decade mill investments rather than upfront capital expenditure alone.
Direct-drive torque motors with integrated encoders are absorbing the traditional gearbox-spindle assembly in next-generation winding heads. Technical textile producers in Germany and Japan are specifying these configurations for carbon fiber processing where vibration control determines yield rates. The elimination of mechanical transmission components compresses maintenance intervals and enables real-time tension adjustment at surface speeds approaching 2,000 meters per minute.
REACH chemical compliance for lubricants and coatings is forcing reformulation of spindle oils and anti-static surface treatments. Equipment builders serving EU markets must document substance safety data across extended supply chains. The regulatory burden falls most heavily on mid-tier manufacturers lacking in-house toxicology expertise, creating specification advantages for vertically integrated producers with captive chemical engineering capabilities.
Buyer evaluation criteria have migrated from equipment-first to ecosystem-first, with yarn monitoring system compatibility now determining winding platform selection. Large textile mills in India's integrated spinning-weaving operations demand seamless data integration between winding machines and downstream looms. This specification shift favors equipment builders with backward integration into sensor and software platforms, compressing standalone hardware vendors into commodity positioning.
Textile Winding Machine Market Segmentation
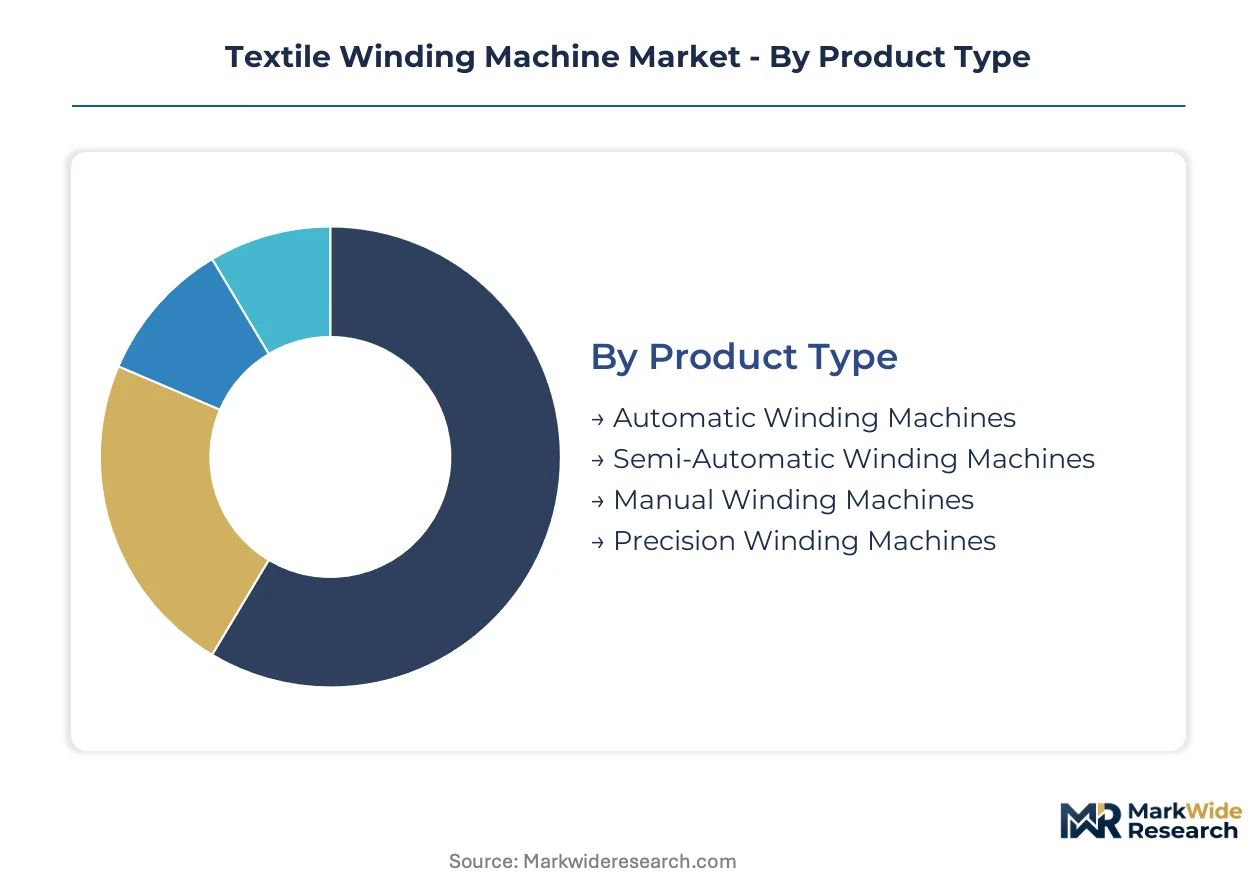
Equipment specification diverges sharply across textile winding machine segments as regulatory certification requirements and end-use precision demands reshape buyer priorities. Segmentation reveals how servo motor adoption, REACH compliance burdens, and technical textile processing requirements concentrate margin pools in distinct configuration tiers.
Product Type:
CE marking under the EU Machinery Directive and BIS electrical safety certification in India impose divergent testing timelines across automatic, semi-automatic, and precision winding platforms.
- Automatic Winding Machines:These systems integrate electronic tension control and programmable logic controllers to operate at surface speeds exceeding 1,500 meters per minute. Demand concentrates in Tamil Nadu's integrated spinning-winding operations where India's PLI scheme subsidizes machinery upgrades for export-oriented apparel manufacturers.
- Precision Winding Machines:Engineered for denier tolerances below 0.5% in carbon fiber and aramid processing, these platforms employ direct-drive torque motors with integrated encoders. Technical textile producers in Germany and Japan specify these configurations for aerospace composite applications where vibration control determines yield rates.
- Semi-Automatic Winding Machines:Modular configurations serve capital-constrained manufacturers in Vietnam and Indonesia as stepping-stone automation with upgrade paths to full automatic systems.
- Manual Winding Machines:Legacy mechanical configurations retain niche relevance in artisanal textile operations and small-batch technical fiber sampling.
Leading the category by volume: Automatic Winding Machines. Growing fastest: Precision Winding Machines.
Technology:
Cost tier stratification separates premium servo motor platforms from mechanical control alternatives, with electronic control systems commanding widening price premiums due to energy efficiency certifications.
- Servo Motor Driven:Neodymium and dysprosium-dependent windings enable real-time tension adjustment at speeds approaching 2,000 meters per minute. Apparel manufacturers adopt these to meet tighter fabric specifications for premium garment exports, though copper and rare earth magnet cost volatility compress margins for European and Japanese equipment builders.
- Electronic Control:Microprocessor-based systems with yarn monitoring integration dominate large textile mill procurement in India's integrated spinning-weaving operations where seamless data flow to downstream looms determines platform selection.
- Mechanical Control:Legacy installed base in Bangladesh and Vietnam faces delayed replacement due to capital constraints, creating stranded demand with limited near-term conversion potential.
- Pneumatic Control:Compressed air actuation retains cost advantage in humidity-controlled environments where EU F-Gas Regulation compliance constrains refrigerant choices for climate-sensitive winding operations.
Margin concentrates heaviest in servo motor configurations. Electronic control platforms are expanding most quickly as mills retrofit for EU Green Deal efficiency mandates.
Application:
Application-driven specification splits between high-throughput knitting and weaving operations versus precision-dependent embroidery and technical braiding processes.
- Knitting:Circular and flatbed knitting preparation demands consistent yarn tension for stitch uniformity in hosiery and sweater manufacturing.
- Weaving:Warp winding for shuttle and shuttleless looms requires precise length measurement and tension control to minimize loom stoppages in integrated Tamil Nadu mills.
- Embroidery:Fine-count yarn handling for computerized embroidery machines necessitates anti-static surface treatments and specialized spindle oils facing REACH chemical compliance reformulation.
- Sewing:Thread winding for industrial and domestic sewing applications spans commodity to premium tiers based on tensile strength requirements.
- Braiding:Technical textile braiding for aerospace and medical applications commands exacting specifications for carbon fiber and aramid processing.
Weaving applications anchor volume demand. Technical braiding for aerospace composites shows steepest expansion trajectory.
End User:
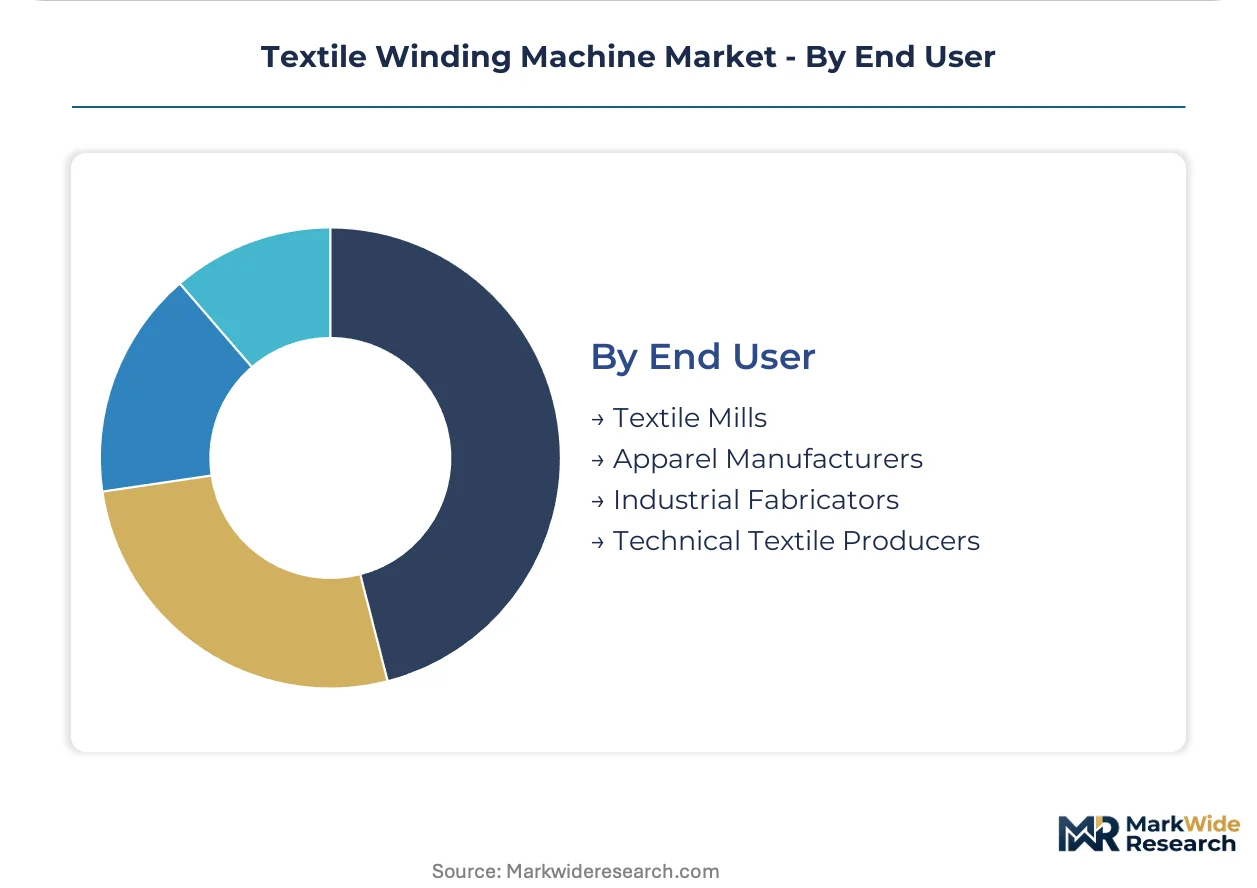
Customer type determines specification complexity, with technical textile producers demanding precision winding platforms while apparel manufacturers prioritize throughput economics.
- Textile Mills:Integrated spinning-winding-weaving operations in India's Coimbatore-Tiruppur belt specify automatic systems with backward integration into yarn monitoring platforms.
- Apparel Manufacturers:Export-oriented garment producers in Tamil Nadu adopt servo motor driven systems to meet tighter fabric specifications for premium markets.
- Technical Textile Producers:Carbon fiber and aramid processors in Germany and Japan specify precision winding machines with direct-drive torque motors for aerospace composite applications.
- Industrial Fabricators:Conveyor belt, rope, and cordage manufacturers balance capital constraints against durability requirements in semi-automatic configurations.
Textile mills dominate procurement volume. Technical textile producers represent the fastest-growing customer segment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Coimbatore anchors machinery demand through Tamil Nadu's integrated spinning-winding corridor, where state-level incentives concentrate investment in servo-driven equipment upgrades for export-oriented apparel production.
India
Tamil Nadu's PLI scheme subsidizes automatic winding systems for integrated spinning-winding-weaving operations. BIS certification mandates extend electrical safety testing timelines for imported equipment. The Coimbatore-Tiruppur belt concentrates procurement volume as apparel manufacturers retrofit for tighter fabric specifications in premium garment exports.
Germany
Technical textile producers specify precision winding platforms for carbon fiber and aramid processing in aerospace composite applications. EU Green Deal binding efficiency targets accelerate replacement cycles for mechanical control systems. Stuttgart and Munich industrial clusters drive demand for direct-drive torque motor configurations with integrated encoders.
China
Neodymium and dysprosium processing concentration shapes servo motor supply chains for domestic equipment builders. MIIT energy efficiency standards push mills toward electronic control retrofits. Yangtze River Delta textile machinery manufacturers balance rare earth magnet cost volatility against export pricing pressure.
Japan
Carbon fiber processors in Nagoya and Osaka metropolitan areas command exacting denier tolerances below 0.5% for aerospace applications. METI industrial standards govern programmable logic controller integration in next-generation winding heads. Chubu region technical textile specialists adopt vibration-controlled configurations at surface speeds approaching 2,000 meters per minute.
Vietnam
Capital-constrained apparel manufacturers delay full automation due to mechanical control legacy installed base retention. General functional descriptors apply for national equipment safety standards rather than specific regulator naming. Ho Chi Minh City and Hanoi industrial zones represent stranded demand pools with modular semi-automatic upgrade potential.
Textile Winding Machine Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across tiered equipment specifications, with integrated machinery builders facing specialized component suppliers for yarn monitoring system compatibility. The vendor base separates into three strategic archetypes: precision engineering heritage firms anchoring high-throughput automatic segments, backward-integrated platform providers bundling sensor and software ecosystems, and regional fabricators serving price-sensitive semi-automatic demand. Dominant competitive moves include geographic expansion into Tamil Nadu's incentive corridor and technology licensing for REACH-compliant lubricant formulations.
Among Swiss-anchored specialists, SSM Schärer Schweiter Mettler AG and Rieter Holding AG exemplify backward-integrated platform strategies pairing winding hardware with yarn monitoring ecosystems. Murata Machinery occupies a position representing precision engineering heritage in East Asian high-throughput specifications. These three names anchor distinct competitive vectors without exhaustively mapping the vendor landscape.
| Leading Market Players |
|---|
| Murata Machinery |
| Rieter Holding AG |
| Saurer Group |
| SSM Schärer Schweiter Mettler AG |
| Savio Macchine Tessili |
| Lakshmi Machine Works |
| Vandewiele NV |
| TMT Machinery |
| Jingwei Textile Machinery |
| Others |
Pricing and Supply Chain Analysis
EU Green Deal energy mandates gate qualified supply for premium-tier textile winding equipment, restricting market access to builders capable of documenting efficiency certifications while compressing margins for non-compliant mechanical control alternatives. REACH chemical compliance for lubricants and coatings further stratifies pricing power, with reformulation capabilities determining which equipment suppliers can serve European apparel manufacturers and technical textile producers.
Pricing Analysis
Throughput-linked value anchors pricing for automatic winding systems, with electronic tension control configurations commanding substantial premiums over mechanical alternatives based on surface speed capabilities exceeding 1,500 meters per minute. Price differentiation rests on energy efficiency certification grade and REACH-compliant lubricant formulation status. Cost compression in servo motor tiers intensifies because neodymium and dysprosium supply volatility compresses margins for European and Japanese builders. Capital-constrained apparel manufacturers in Vietnam and Indonesia exhibit highest price sensitivity, while technical textile producers in Germany and Japan prioritize yield-optimized precision platforms.
Supply Chain Analysis
Regional distribution centers in Stuttgart, Coimbatore, and Nagoya anchor hub-and-spoke patterns for precision winding equipment, with spare parts and technical service radiating from machinery manufacturing clusters. Geographic supply concentration centers on China for rare earth magnet processing, Germany for direct-drive torque motor engineering, and India for integrated spinning-winding system assembly. Raw material dependencies draw from copper winding supplies, neodymium-dysprosium magnet feeds, and REACH-compliant specialty lubricants. Single-source vulnerability in Chinese rare earth processing facilities poses structural supply chain risk. Distribution runs through OEM-direct channels for large integrated mills and machinery distributors for mid-scale apparel manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Textile winding equipment manufacturing is consolidating as REACH compliance burdens and rare earth cost volatility force weaker players lacking captive chemical engineering capabilities from European market participation.
For Market Incumbents: Hedge servo motor supply exposure through long-term offtake agreements with Chinese rare earth processors or alternative magnet sourcing from Australian and Vietnamese deposits. Accelerate backward integration into yarn monitoring sensor platforms to defend against standalone hardware commoditization in India's integrated mill procurement. Prioritize certification investment for EU F-Gas Regulation compliance in climate control bundling opportunities. For New Entrants and Emerging Players: Direct-drive torque motor technology with integrated encoder systems offers entry into precision winding for carbon fiber processing, where exacting denier tolerance requirements below 0.5% limit incumbent lock-in. Target Vietnam's stranded demand pool of capital-constrained apparel manufacturers with modular semi-automatic configurations featuring clear upgrade paths to full automation. Pursue go-to-market partnerships with regional machinery distributors possessing established relationships in Ho Chi Minh City industrial zones. For Investors and Strategic Acquirers: BIS certification timeline extensions beyond six months for imported equipment entering India is the leading indicator that domestic manufacturing capacity will command acquisition premiums. Five-to-ten year viability favors vertically integrated builders combining winding hardware with captive sensor and software platforms. Monitor PLI scheme incentive disbursement velocity in Tamil Nadu as the inflection signal for demand acceleration in integrated spinning-winding corridors.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Yarn Monitoring | Captures ecosystem-first procurement criteria from India's integrated spinning-weaving mills. |
| REACH-Compliant Lubricant Formulation | Enables European market access for high-speed spindle systems serving German technical textile producers. |
| Rare Earth Magnet Supply Diversification | Reduces margin compression risk from Chinese neodymium-dysprosium processing concentration. |
| Modular Semi-Automatic Platform Development | Addresses capital-constrained demand in Vietnam and Indonesia with upgradeable stepping-stone automation. |
| EU F-Gas Regulation Climate Control Bundling | Creates specification advantages in humidity-sensitive winding operations across German and Italian mills. |
Research Methodology
Multi-period observation of servo motor adoption rates, BIS certification timeline extensions, and PLI scheme disbursement patterns anchored the trend analysis, supplemented by interviews with plant engineers at integrated Tamil Nadu textile mills, procurement directors at German technical textile producers, aftermarket service heads at European equipment builders, and regulatory affairs specialists navigating REACH compliance. Secondary validation drew from EU Machinery Directive filings, BIS electrical safety certification records, MIIT energy efficiency disclosures, and customs data on rare earth magnet trade flows. Bottom-up equipment shipment tracking and top-down mill capacity expansion analysis were triangulated against segmentation model outputs.
Input-output matrix framing connected raw material cost indices for copper and rare earth elements against end-use demand from apparel manufacturers and technical textile producers across the projection horizon. Segmentation dimensions modeled include product type tier, control technology architecture, end-use application precision requirements, and regional regulatory cluster. CAGRs were derived from equipment replacement cycle analysis and capacity expansion pipeline tracking. Industry-specific forecast inputs incorporated EU Green Deal binding efficiency target compliance deadlines and India's PLI scheme machinery upgrade subsidy trajectories.
Forecast precision tightens around the base case; tail outcomes carry wider variance under rare earth export restriction scenarios or REACH substance list expansion. Outputs reflect documented assumptions on replacement cycle timing and incentive program continuity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Textile Machinery and Equipment
Global Textile Machinery Market
Textile Machinery and Equipment
Global Industrial Fabric Market
Textile Machinery and Equipment
Yankee Dryer Market
Textile Machinery and Equipment
Disposable Garment Bags Market
Textile Machinery and Equipment
Braiding Equipment Market
Textile Machinery and Equipment
Sewing Machine Market
Textile Machinery and Equipment
Global Digital Printing and Dyeing Machine Market
Textile Machinery and Equipment
Tarpaulin Market
Textile Machinery and Equipment
Mexico Screen Printing Mesh Market
Textile Machinery and Equipment
Webbing Cutting Machine Market
Textile Machinery and Equipment
Gel Dryer Market
Textile Machinery and Equipment
Textile Tester Market
Textile Machinery and Equipment
Dyeing Machine Market
Textile Machinery and Equipment
Global Custom T-Shirt Printing Market
Textile Machinery and Equipment
Cloth Cutting Machines Market
Textile Machinery and Equipment
Textile Mill Electric Drives Market