
 US Wall Beds Market | 2026-2036
US Wall Beds Market Size, Share, and Industry Trends Forecast 2026-2036
US Wall Beds Market Insights
Modular bundling of wall bed frames with integrated storage and desk systems is restructuring how residential buyers evaluate space efficiency. Murphy Wall Beds Hardware Inc. leverages its hardware engineering heritage to dominate the premium mechanism segment. Wilding Wallbeds anchors its position through direct-to-consumer channel control across the Southwest. SICO Incorporated specializes in commercial-grade folding systems for hospitality contracts, competing on durability specifications rather than residential aesthetics.
A wall bed is a vertically storable sleeping platform hinged at one end for rotation into a cabinet or wall cavity, typically engineered with counterbalanced lift mechanisms rated for cycles between five thousand and fifteen thousand uses, designed to reclaim floor area in space-constrained interiors. Murphy beds lead the product type landscape due to established installer networks and consumer familiarity, while Murphy sofas represent the fastest-expanding segment as hybrid living-work arrangements persist. Metal and composite materials are capturing margin pools from traditional wood as weight reduction becomes a specification priority for multifamily construction.
The Consumer Product Safety Commission governs entrapment and structural failure standards for convertible furniture, while California's Bureau of Electronic and Appliance Repair enforces flammability and labeling rules that shape material selection across manufacturing footprints. OSHA workplace safety guidelines influence assembly-line automation investments at domestic fabrication facilities. Stakeholders must monitor evolving municipal density bonuses and accessory dwelling unit codes that directly determine install-base expansion in high-growth metros.
Market Dynamics
California's Title 24 energy standards and evolving municipal density codes are compressing material specifications and installation geometries, forcing manufacturers to engineer lighter platforms that satisfy both structural load requirements and square-footage maximization imperatives for multifamily developers.
Growth Catalysts
- Accessory Dwelling Unit Liberalization:Texas metro corridors and California municipalities are relaxing ADU size restrictions, directly expanding install-base potential for space-efficient sleeping systems in secondary units.
- OSHA Workplace Automation Incentives:Domestic fabrication facilities are accelerating robotic assembly-line investments to reduce manual handling injuries while improving mechanism precision for high-cycle lift systems.
- Hybrid Living-Work Normalization:Remote work persistence in dense urban cores is sustaining demand for convertible home office configurations that reclaim floor area during working hours.
Market Restraints
- Engineered Material Cost Volatility:Aluminum and composite resin input prices fluctuate with energy-intensive production cycles, compressing margin pools for mid-tier manufacturers dependent on metal-to-wood substitution strategies.
- Installer Network Concentration:Skilled assembly labor concentrates in coastal metropolitan markets, creating fulfillment bottlenecks for direct-to-consumer brands penetrating interior Southwest and Mountain West corridors.
- Consumer Product Safety Commission Entrapment Standards:Stricter testing protocols for counterbalance failure modes extend product development timelines and elevate certification costs for mechanism innovators.
Strategic Opportunities
- Texas Density Acceleration Corridors:Houston, Dallas-Fort Worth, and Austin multifamily permitting velocity outpaces national averages, creating concentrated demand for developer-specified Murphy bed systems in micro-unit configurations.
- Integrated Storage-Desk Convergence:Modular bundling of sleeping platforms with built-in shelving and workstations captures premium pricing from remote workers seeking single-vendor space efficiency solutions.
- California Bureau of Electronic and Appliance Repair Flammability Waivers:Emerging pathways for engineered composite materials to achieve reduced testing burdens accelerate wood-alternative adoption in manufacturing footprints.
Industry Challenges
- Pneumatic and Spring Mechanism Calibration Expertise:Shortage of technicians trained in high-cycle lift system tuning creates warranty service backlogs and degrades brand reputation for direct-to-consumer entrants.
- Municipal Code Fragmentation:Inconsistent accessory dwelling unit and density bonus regulations across Texas, California, and Florida metros force SKU proliferation and complicate national distribution strategies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Wall Beds Market |
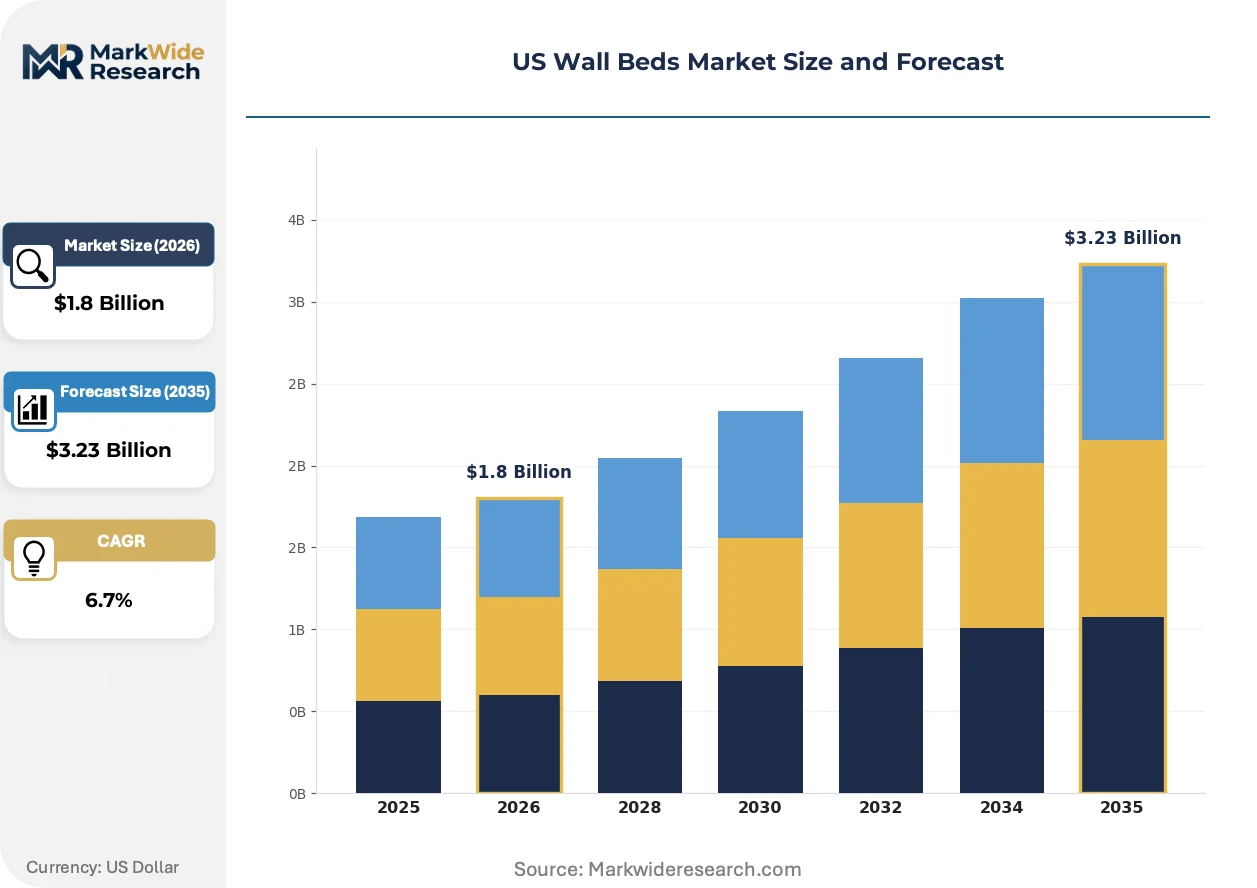
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Murphy Beds, Folding Beds, Murphy Sofas, Convertible Sofa Beds Material: Wood, Metal, Fabric, Composite End User: Residential, Hospitality, Student Housing, RVs Distribution Channel: Online Retail, Specialty Stores, Home Improvement Stores, Direct Sales |
| Companies Covered | Murphy Wall Beds Hardware Inc., Wilding Wallbeds, SICO Incorporated, Wall Beds Manufacturing Inc., FlyingBeds International, The Bedder Way Company, Bestar Inc., The London Wallbed Company, Expand Furniture, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Wall Beds Market Trends and Innovations
Mechanism engineering and material science are converging to redefine durability expectations and installation economics, while regulatory pressure on flammability and energy performance accelerates substitution away from traditional solid-wood platforms.
Composite honeycore panels bonded with aluminum framing are unifying structural rigidity with weight reduction targets set by multifamily developers. Texas and California general contractors specify these assemblies for high-rise micro-units where crane-lift constraints limit traditional material transport. The technology is unifying previously separate supply chains for cabinetry, bedding, and structural components into single-source procurement relationships.
California's Title 24 energy standards now extend to embodied carbon calculations in residential fixtures, compelling manufacturers to document lifecycle emissions for engineered materials. This regulatory expansion favors domestic composite fabricators with transparent supply chains over imported solid-wood competitors. Multifamily developers in Los Angeles and San Francisco metros now embed these specifications in RFP requirements, filtering vendor pools before bid submission.
Builder-direct procurement models are displacing retail showroom dependence for volume multifamily contracts. National homebuilders in Texas corridor markets negotiate frame-and-mechanism packages at the development planning stage, bypassing traditional furniture distribution entirely. This channel compression concentrates pricing power with hardware-integrated manufacturers while marginalizing pure-play retail brands in the institutional segment.
US Wall Beds Market Segmentation
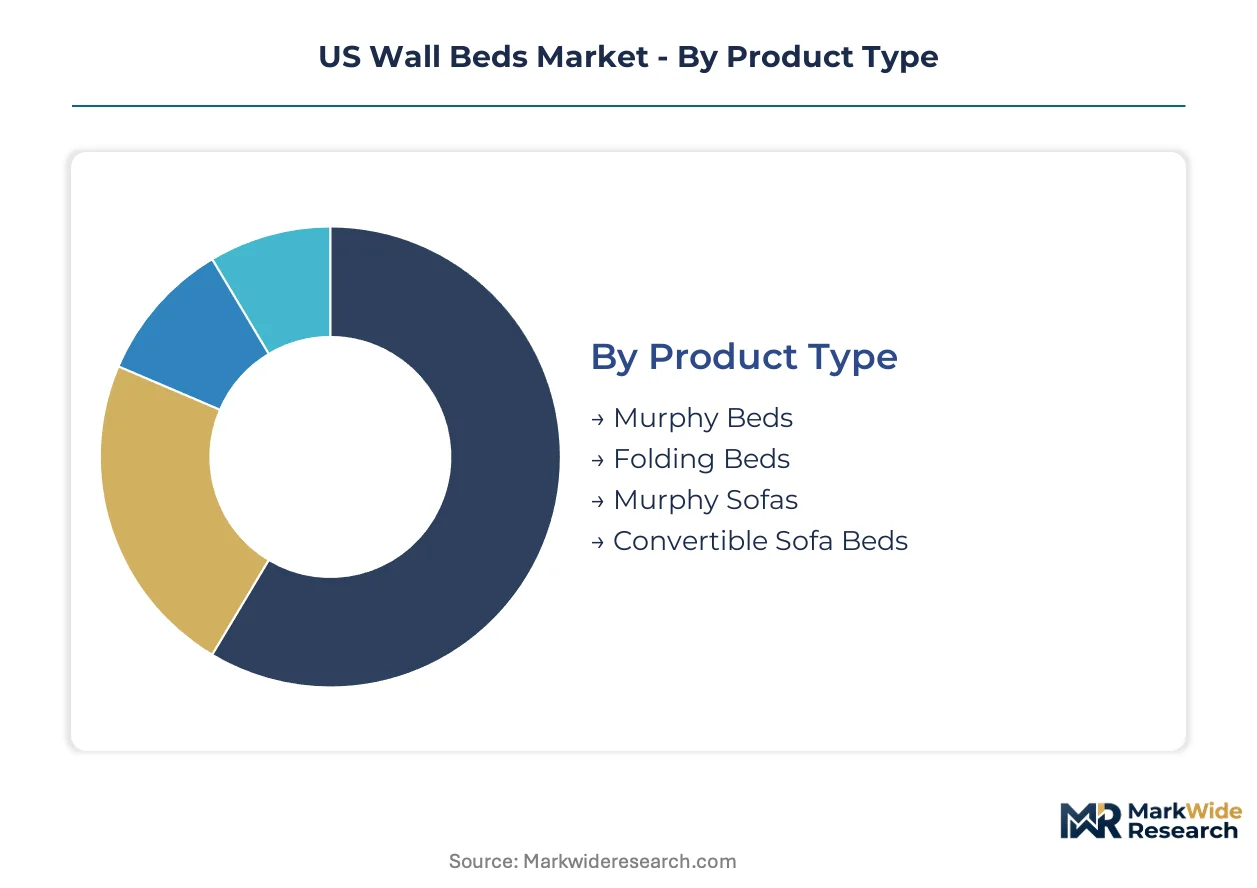
Segmentation in the US wall beds market reflects divergent procurement logics across residential buyers, institutional specifiers, and commercial contractors. Material choices and distribution channels stratify sharply between premium custom installations and volume multifamily deployments.
Product Type:
Residential buyers prioritize floor-area recovery and daily-cycle durability when selecting convertible sleeping platforms.
- Murphy Beds:Vertically rotating platforms with counterbalanced lift mechanisms rated for ten thousand-plus cycles dominate developer specifications. Demand concentrates in Texas corridor micro-units where square-footage maximization directly determines rentable yields.
- Murphy Sofas:Hybrid seating-sleeping systems integrate dual-density foam cores with steel frame foundations. California remote workers in San Francisco and Los Angeles metros drive specification for home-office configurations that reclaim floor area during working hours.
- Folding Beds:Collapsible metal frames with fabric decking serve hospitality overflow and temporary residential needs.
- Convertible Sofa Beds:Traditional pull-out mechanisms occupy budget-conscious residential segments and secondary vacation properties.
Volume sits with Murphy beds; growth tilts toward Murphy sofas.
Material:
Weight reduction imperatives from California Title 24 standards and crane-lift constraints in high-rise construction are restructuring material procurement hierarchies.
- Composite:Honeycore aluminum-bonded panels unify structural rigidity with forty-percent weight reduction versus solid wood. Texas and California general contractors specify these for high-rise micro-units where embodied carbon documentation now filters vendor pools.
- Metal:Powder-coated steel and aluminum framing systems deliver cycle durability for hospitality and student housing contracts. OSHA workplace automation incentives at domestic fabrication facilities improve mechanism precision for high-volume lift systems.
- Wood:Traditional hardwood platforms retain premium residential preference for aesthetic warmth and repairability.
- Fabric:Upholstered surfaces and textile decking serve secondary comfort and visual integration functions.
Composite materials are gaining share fastest; wood retains the largest installed base.
End User:
Procurement authority and specification timing vary dramatically across buyer categories, from individual homeowners to national multifamily developers.
- Residential:Individual homeowners and renters purchase through retail channels for space-constrained urban apartments and accessory dwelling units. California ADU liberalization and Texas density acceleration corridors expand install-base potential for secondary units.
- Hospitality:Hotel operators and extended-stay chains specify commercial-grade folding systems for flexible room configurations. SICO Incorporated and similar vendors compete on durability specifications and cycle ratings rather than residential aesthetics.
- Student Housing:University housing authorities and private student accommodation developers procure volume contracts for convertible sleeping platforms in shared units.
- RVs:Recreational vehicle manufacturers integrate lightweight wall bed mechanisms for space-efficient cabin layouts.
Residential channels command the deepest volume; hospitality contracts offer the most predictable procurement pipelines.
Distribution Channel:
Channel structure is bifurcating between builder-direct institutional procurement and fragmented retail pathways for individual buyers.
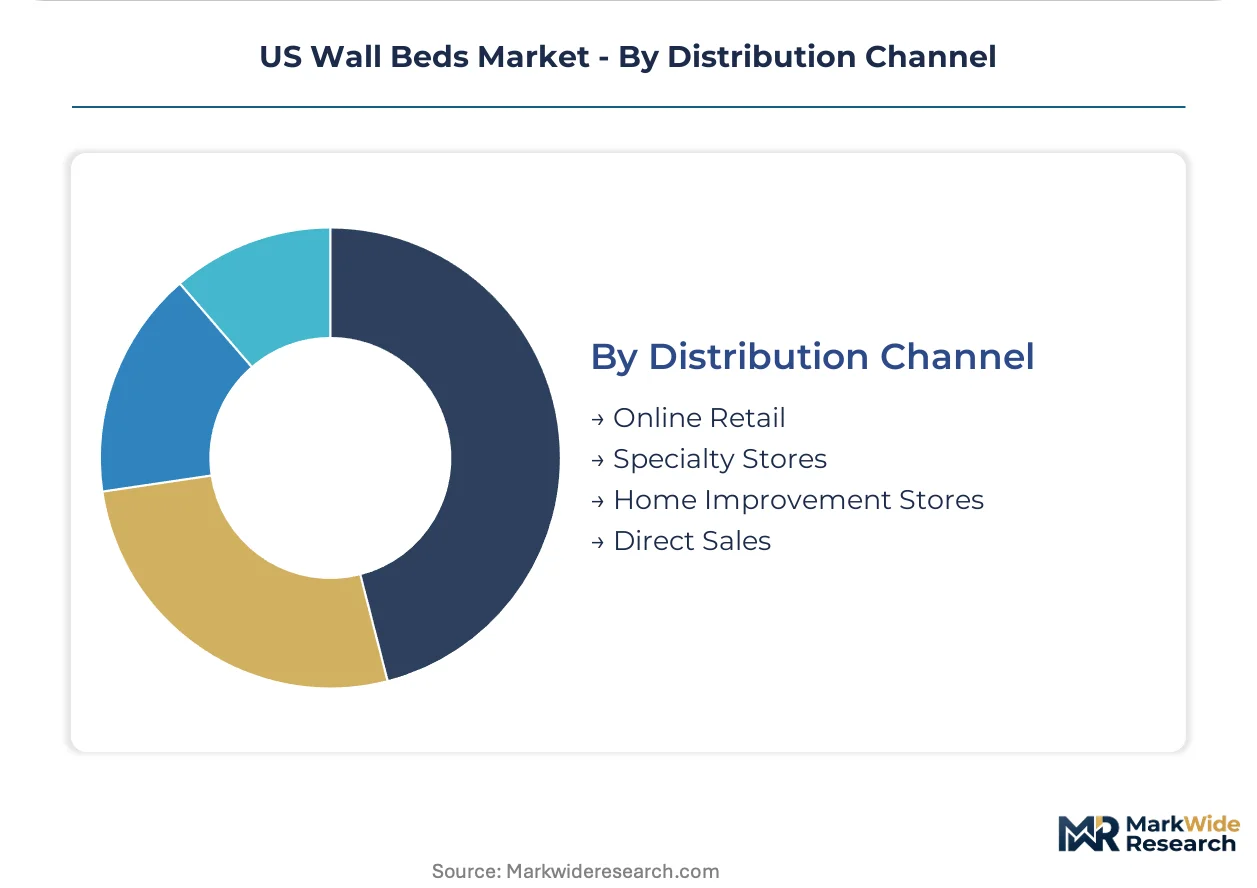
- Direct Sales:National homebuilders in Texas corridor markets negotiate frame-and-mechanism packages at development planning stage, bypassing traditional furniture distribution entirely. This channel compression concentrates pricing power with hardware-integrated manufacturers.
- Online Retail:Direct-to-consumer brands penetrate Southwest and Mountain West corridors, though skilled installer network concentration in coastal metros creates fulfillment bottlenecks for remote markets.
- Specialty Stores:Dedicated wall bed showrooms and custom cabinetry dealers serve premium residential renovations and architect-specified projects.
- Home Improvement Stores:Big-box retailers stock entry-level folding bed systems for DIY installation and temporary residential needs.
Direct sales capture the steepest expansion trajectory; specialty stores retain margin concentration in custom residential segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Domestic manufacturing concentrates in the Southwest and California corridors, while consumption tilts toward Texas density acceleration zones and California ADU expansion markets where multifamily developers specify space-efficient sleeping systems.
California
Title 24 energy standards and embodied carbon documentation requirements filter vendor pools for multifamily developers in Los Angeles and San Francisco metros. The Bureau of Electronic and Appliance Repair enforces flammability rules that accelerate composite material adoption. San Diego and Sacramento ADU liberalization expands install-base potential for secondary units.
Texas
Houston, Dallas-Fort Worth, and Austin multifamily permitting velocity outpaces national averages, concentrating demand for developer-specified Murphy bed systems. Municipal density bonuses in Texas metros lack the carbon documentation burden seen in coastal markets. San Antonio and Austin general contractors negotiate frame-and-mechanism packages at development planning stage.
Florida
Orlando and Miami hospitality markets sustain commercial-grade folding system procurement for flexible room configurations. Florida's absence of statewide ADU standardization creates municipal code fragmentation that complicates distribution strategies. Tampa and Jacksonville student housing developments procure volume contracts for convertible sleeping platforms.
New York Metro
Manhattan and Brooklyn micro-unit construction drives specification for weight-reduced wall bed systems where crane-lift constraints limit traditional material transport. New York State building codes emphasize fire safety testing that elevates certification costs for mechanism innovators. Long Island and Westchester accessory dwelling unit conversions expand residential retrofit demand.
Pacific Northwest
Seattle and Portland urban growth boundaries accelerate housing density in space-constrained cores where floor-area recovery commands premium pricing. Oregon and Washington energy performance standards align with California's trajectory toward lighter engineered materials. Boise and Spokane emerging multifamily markets attract direct-to-consumer brands penetrating interior Mountain West corridors.
US Wall Beds Market Competitive Landscape
The competitive structure tilts toward hardware-integrated manufacturers with direct builder relationships. Three tiers stratify the vendor base: premium mechanism specialists, direct-to-consumer brands with installer network control, and commercial-grade hospitality suppliers. Consolidation pressure concentrates pricing power with domestic fabricators possessing OSHA-compliant automation investments. Strategic moves center on backward integration into composite panel production and exclusive procurement partnerships with national homebuilders.
Within the hardware-specialist tier, Murphy Wall Beds Hardware Inc. and Wilding Wallbeds occupy positions reflecting divergent channel strategies—one leveraging engineering heritage for premium mechanism supply, the other anchoring Southwest market penetration through direct-to-consumer control. SICO Incorporated represents the commercial-grade archetype, competing on durability specifications for hospitality contracts rather than residential aesthetics. These three exemplify how mechanism expertise, geographic concentration, and end-use specialization segment competitive positioning.
| Leading Market Players |
|---|
| Murphy Wall Beds Hardware Inc. |
| Wilding Wallbeds |
| SICO Incorporated |
| Wall Beds Manufacturing Inc. |
| FlyingBeds International |
| The Bedder Way Company |
| Bestar Inc. |
| The London Wallbed Company |
| Expand Furniture |
| Others |
Pricing and Supply Chain Analysis
Composite honeycore panel bonding with aluminum framing is compressing both per-unit production economics and supplier concentration, as domestic fabricators with OSHA-compliant automation investments capture mechanism-integrated procurement relationships from fragmented wood-cabinet networks.
Pricing Analysis
Margin tightening in the mid-tier segment reflects aluminum and composite resin input volatility tied to energy-intensive production cycles. Three-tier pricing structure across premium mechanism systems, standard frame-and-panel configurations, and economy folding platforms stratifies by cycle rating and installation complexity. Pricing pressure intensifies in standard tiers as Texas corridor homebuilders negotiate volume frame-and-mechanism packages at development planning stage. Residential retail buyers exhibit highest price sensitivity; national multifamily developers prioritize total installed cost and lifecycle durability over per-unit purchase price.
Supply Chain Analysis
Builder-direct channels handle hyperscale multifamily demand from Texas and California developers, while online retail and specialty showrooms serve fragmented residential procurement. Domestic fabrication concentrates in Southwest and California corridors where Title 24 compliance and OSHA automation incentives anchor production. Raw material flows draw from engineered composite resin suppliers, aluminum extrusion mills, and pneumatic lift mechanism foundries. Single-source vulnerability in high-cycle spring and gas-strut components creates warranty service bottlenecks. Distribution runs through direct sales for institutional volume, online retail for geographic expansion, and specialty dealers for premium custom installations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Mechanism engineering and material science convergence is displacing traditional solid-wood platforms, creating repositioning windows for hardware-integrated manufacturers and composite fabricators.
For Market Incumbents: Anticipate margin compression from metal-to-wood substitution strategies by deepening captive supply of composite honeycore panels and securing exclusive procurement partnerships with national homebuilders in Texas density corridors. California Title 24 embodied carbon documentation requirements filter vendor pools—invest in transparent supply chain certification to defend specification status. For New Entrants and Emerging Players: The pricing gap between premium mechanism specialists and economy folding platforms creates white-space opportunity in mid-tier Murphy sofa configurations for California remote workers. Target Pacific Northwest urban growth boundary markets where floor-area recovery commands premium pricing but installer network concentration remains underdeveloped. Pursue direct-to-consumer channel control with contracted assembly technician networks. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by national homebuilders seeking backward integration into space-efficient fixture supply. Long-term viability hinges on composite material cost stabilization and municipal ADU liberalization persistence. Monitor Texas multifamily permitting velocity as inflection indicator for developer-specified demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Composite Panel Production | Captures margin from honeycore aluminum-bonded assemblies specified by California Title 24 compliance. |
| Exclusive Procurement Partnership with National Homebuilders | Concentrates pricing power in Texas corridor micro-unit developments bypassing traditional furniture distribution. |
| OSHA-Compliant Robotic Assembly Investment | Reduces manual handling injuries while improving mechanism precision for high-cycle lift systems. |
| Direct-to-Consumer Channel Expansion | Penetrates Mountain West corridors where skilled installer network concentration creates incumbent fulfillment bottlenecks. |
| California Bureau Flammability Certification Pathway | Accelerates wood-alternative adoption through reduced testing burdens for engineered composite materials. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, combined with primary interviews across multifamily development executives, general contractors, wall bed mechanism engineers, specialty retail dealers, and municipal planning officials. Secondary sources included Consumer Product Safety Commission entrapment standards documentation, California Bureau of Electronic and Appliance Repair flammability rulings, OSHA workplace safety guidelines, and multifamily permitting databases. Bottom-up unit demand modeling and top-down construction spending allocation were triangulated for validation.
Reconciliation of shipment data from composite fabricators, mechanism suppliers, and distribution channels informed volume estimates across the projection horizon. Segmentation dimensions encompassed product type, material platform, end-user category, and distribution channel, with additional modeling of cycle-rating tiers and geographic density corridors. CAGRs were derived from regression analysis against housing permit velocity and ADU policy liberalization indices. Industry-specific inputs included crane-lift weight constraints and embodied carbon documentation requirements.
Inputs from municipal planning departments and trade association members were available through the study window; gaps in real-time installer network capacity data introduce uncertainty bands around direct-to-consumer penetration forecasts. Periodic stress-testing of base assumptions against Texas permitting volatility and composite resin pricing cycles is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bedroom Furniture
Luxury and Premium Mattress Market
Bedroom Furniture
Malaysia Mattress Market
Bedroom Furniture
Malaysia Pillow Market
Bedroom Furniture
Wall Bed Market
Bedroom Furniture
Closets, Nightstands, and Dressers Market
Bedroom Furniture
United Kingdom Mattress Market
Bedroom Furniture
Asia-Pacific Mattress Market
Bedroom Furniture
Saudi Arabia Mattress Market
Bedroom Furniture
Smart Bed Market
Bedroom Furniture
North America Wall Bed Market
Bedroom Furniture
North America Mattress Market
Bedroom Furniture
Latin America Mattress Market
Bedroom Furniture
Latex Pillow Market
Bedroom Furniture
Germany Mattress Market
Bedroom Furniture
Bedding Market
Bedroom Furniture
China Mattress Market