
 Fixed RFID Readers Market | 2026-2036
Fixed RFID Readers Market Size, Share, and Industry Trends Forecast 2026-2036
Fixed RFID Readers Market Analysis
Third-party logistics providers are reorganizing capital allocation toward fixed reader infrastructure as e-commerce fulfillment velocity requirements tighten. Zebra Technologies dominates enterprise-grade fixed reader deployments through its deep channel control across North American distribution centers. Impinj differentiates via RAIN RFID endpoint IC-to-reader system architecture, sustaining technology leadership in high-density read environments. FEIG ELECTRONIC anchors European industrial automation demand with specialized UHF readers engineered for metallic interference conditions.
Fixed RFID readers are stationary interrogation devices operating at defined frequency bands—typically 860–960 MHz in UHF regions—designed to capture tag data without manual intervention across conveyor belts, dock doors, and storage zones. These units integrate power amplifiers, digital signal processors, and antenna multiplexers to achieve read rates exceeding 1,000 tags per second in dense pallet configurations. Passive technology occupies the volume core of the hardware installed base, though semi-passive configurations are gaining traction in cold-chain asset tracking where onboard sensor logging extends functional utility. Supply chain applications concentrate margin pools at the systems-integration layer, while inventory management represents the largest addressable application segment by unit volume across retail and manufacturing end users.
FCC Part 15 regulations in the United States govern unlicensed UHF operation and directly shape reader transmit power limits, forcing hardware vendors to region-lock firmware configurations. ETSI EN 302 208 harmonizes European spectrum allocation, with CE marking requirements filtering non-compliant equipment from EU market access. Stakeholders must monitor evolving RFID privacy mandates from national data protection authorities, as tag-level traceability intersects with GDPR-style personal data governance in consumer-facing deployments.
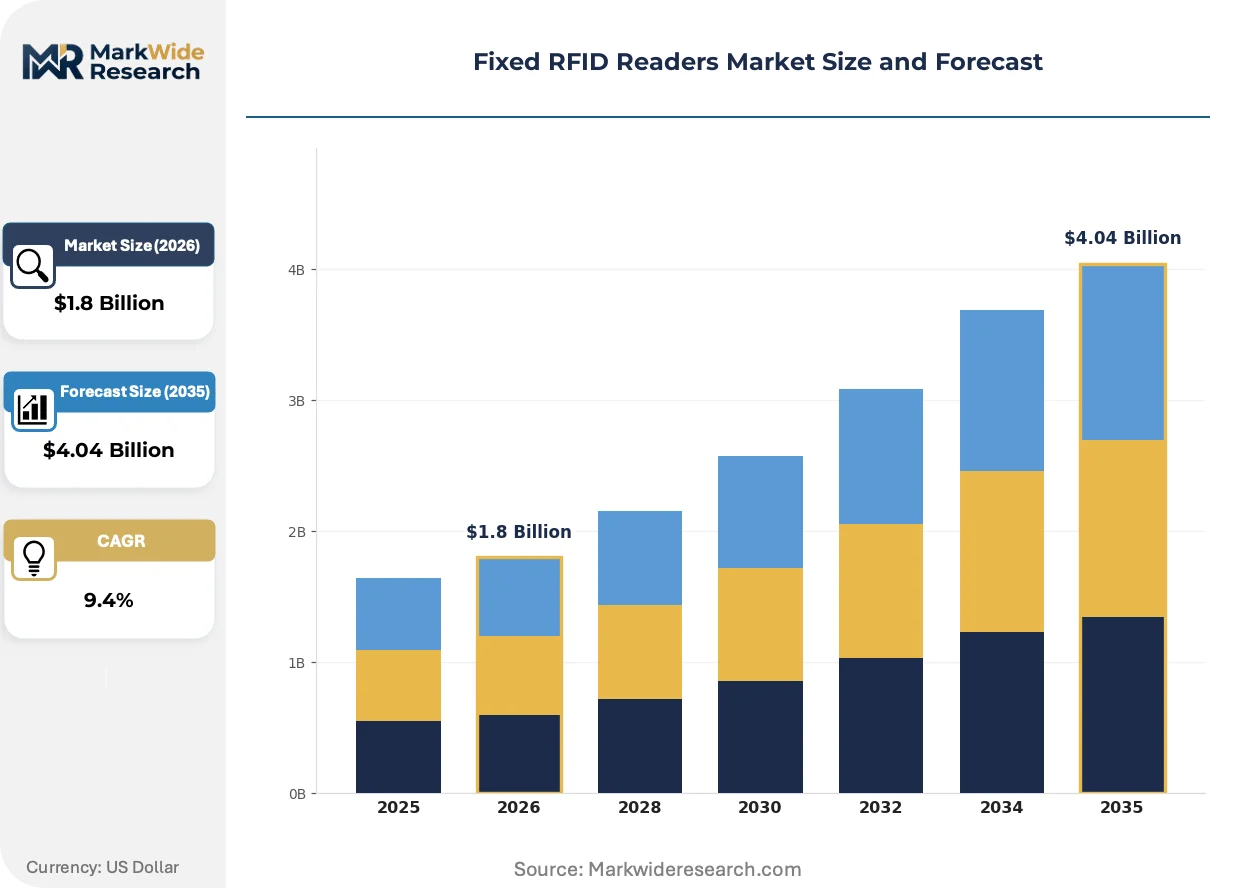
Market Dynamics
EPC Gen 2 V2 air-interface protocol standardization is compressing hardware replacement cycles across installed bases, forcing vendors to recertify product lines while buyers accelerate depreciation schedules on legacy interrogators.
Growth Catalysts
- Automotive supplier mandates:Tier-one logistics contracts in Germany's industrial corridor now require RFID-enabled track-and-trace compliance, pulling fixed reader infrastructure into supplier facilities.
- Warehouse automation velocity:E-commerce fulfillment centers demand real-time visibility mandates that only dense fixed-reader arrays can satisfy at conveyor throughput speeds.
- ETSI EN 302 208 harmonization:Unified European spectrum allocation enables single-SKU hardware deployment across EU member states, reducing vendor certification burden and buyer procurement complexity.
Market Restraints
- Semiconductor supply concentration:Digital signal processors and power amplifiers for UHF readers depend on concentrated Asian foundry capacity, exposing lead time volatility.
- Metallic interference physics:Dense industrial environments with steel racking and automated guided vehicles create multipath reflection that degrades read reliability in core manufacturing applications.
- FCC Part 15 power limits:United States transmit power caps constrain read range in large distribution centers, forcing denser antenna deployment and higher infrastructure cost.
Strategic Opportunities
- Cold-chain sensor convergence:Semi-passive RFID with onboard temperature logging is penetrating pharmaceutical distribution, extending reader utility beyond identity capture to condition monitoring.
- India's PLI scheme for electronics:Domestic manufacturing incentives are attracting reader assembly capacity to serve South Asian logistics and retail modernization programs.
- Dock-door automation retrofit:Existing facilities without built-in RFID infrastructure represent addressable white space for modular portal installations requiring minimal civil work.
Industry Challenges
- RAIN RFID protocol engineering talent:Shortage of firmware developers skilled in dense-tag collision arbitration algorithms limits vendor product roadmap velocity.
- GDPR-tag traceability intersection:Consumer-facing deployments must reconcile item-level RFID tracking with personal data governance, complicating privacy impact assessments.
- Legacy WMS integration:Enterprise warehouse management systems with rigid data schemas require expensive middleware development to ingest streaming tag-event data.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fixed RFID Readers Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.04 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Handheld, Fixed, Integrated, Portable Technology: Active, Passive, Semi-Passive, NFC Application: Inventory Management, Access Control, Asset Tracking, Supply Chain End User: Retail, Healthcare, Manufacturing, Transportation |
| Companies Covered | FEIG ELECTRONIC, Datalogic, Zebra Technologies, OMRON, Siemens, Impinj, CAEN RFID, SICK, Honeywell, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fixed RFID Readers Market Emerging Trajectories
Fixed reader architecture is bifurcating between high-performance enterprise deployments and cost-optimized edge nodes, with software-defined radio platforms enabling firmware-upgradeable frequency agility.
Beam-steering phased-array antennas are supplanting static panel configurations in high-density portal applications. Automotive inbound logistics operations at BMW's Spartanburg and Leipzig assembly plants have adopted electronically steerable arrays to track mixed-sku pallet flows without mechanical antenna positioning. The technology is compressing infrastructure footprint per read point while improving tag-capture consistency on irregularly loaded conveyors.
CE marking requirements under the EU's Radio Equipment Directive are tightening electromagnetic compatibility testing protocols for industrial UHF readers. Manufacturers must now demonstrate immunity to automated guided vehicle communication bands and welding equipment interference. German automotive suppliers are prioritizing pre-certified reader platforms to avoid customs delays at intra-EU fulfillment nodes.
Third-party logistics providers are unbundling reader hardware procurement from systems integration services, creating direct vendor relationships that bypass traditional automation channel partners. DHL Supply Chain and GXO Logistics have established technical evaluation teams capable of specifying antenna configurations and middleware requirements independently. This behavior is most visible in North American e-commerce fulfillment contracts where reader density directly determines labor cost per unit shipped.
Fixed RFID Readers Market Segmentation
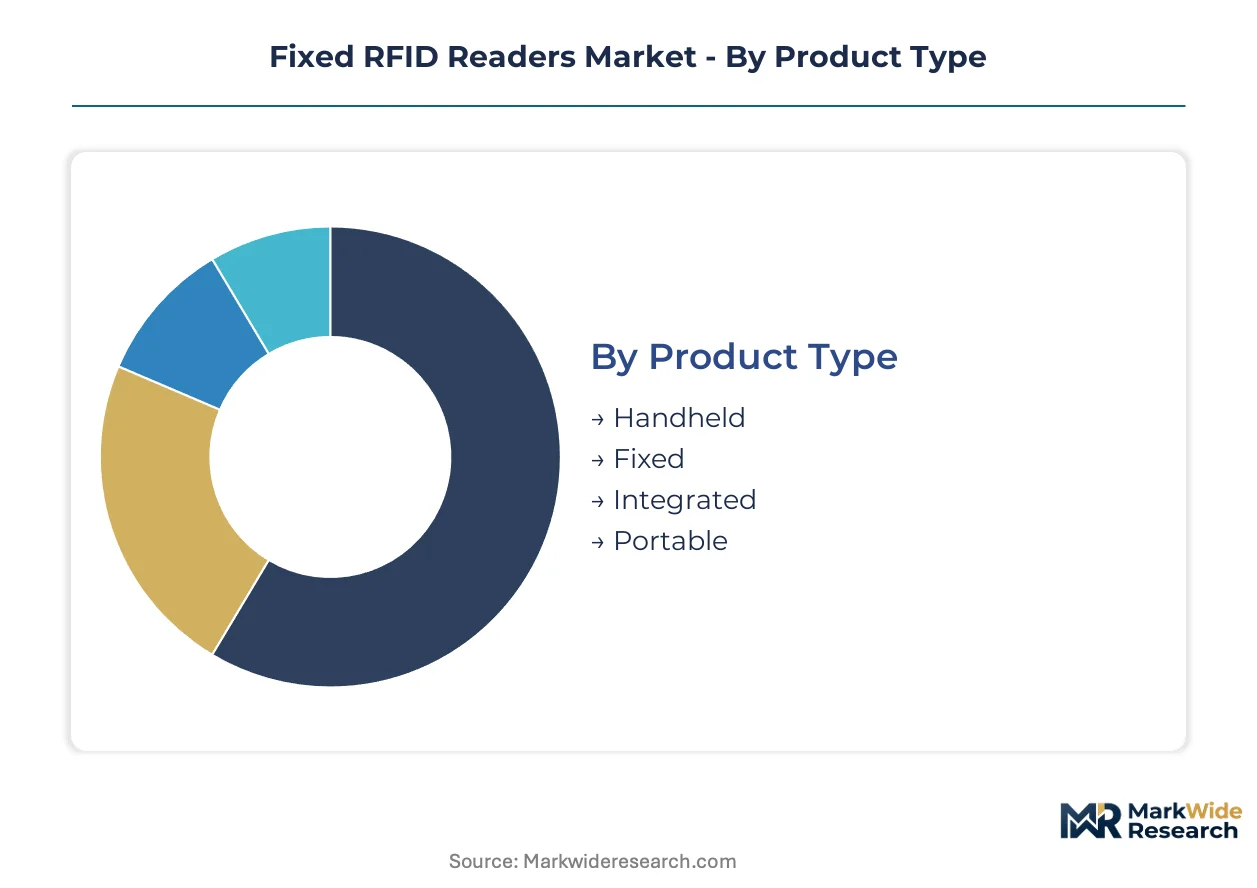
Fixed RFID reader segmentation reveals distinct procurement patterns across hardware configurations and deployment contexts. Buyers prioritize interrogator specifications based on read density requirements, environmental interference conditions, and integration complexity with existing automation infrastructure.
Product Type:
FCC Part 15 transmit power caps and ETSI EN 302 208 spectrum harmonization create divergent hardware certification requirements that shape regional product availability. Fixed installations dominate capital allocation in high-throughput environments where continuous interrogation eliminates manual scanning labor.
- Fixed:Stationary interrogation devices operating at 860–960 MHz achieve read rates exceeding 1,000 tags per second across conveyor belts and dock doors. German automotive suppliers in Baden-Württemberg and Bavaria mandate fixed reader infrastructure for tier-one logistics compliance, compressing hardware replacement cycles under EPC Gen 2 V2 protocols.
- Handheld:Battery-operated mobile units with integrated antennas serve exception handling and cycle-counting workflows where fixed infrastructure gaps exist. Retail distribution centers in the United States deploy handheld readers for inventory reconciliation in mezzanine storage zones beyond fixed reader coverage.
- Integrated:Embedded interrogation modules built into OEM equipment such as smart shelves and automated guided vehicles. Compact form factors suit space-constrained installations in pharmaceutical clean rooms and cold-chain storage facilities.
- Portable:Ruggedized transportable units with external antenna connectivity for temporary deployments at pop-up fulfillment nodes and construction-site asset tracking. India's logistics modernization programs under PLI scheme incentives are attracting portable reader assembly capacity for South Asian deployment.
Fixed handles the majority of throughput; portable is gaining share fastest among product configurations.
Technology:
Cost tier differentiation separates high-performance active systems from volume-deployed passive infrastructure, with semi-passive configurations capturing margin in condition-monitoring applications.
- Passive:Tag operation powered entirely by harvested reader RF energy dominates unit volume across retail and manufacturing installed bases. EPC Gen 2 V2 standardization enables dense-tag collision arbitration in e-commerce fulfillment centers where pallet-level identification drives conveyor routing decisions.
- Semi-Passive:Battery-assisted backscatter with onboard sensor logging extends functional utility to cold-chain pharmaceutical distribution where temperature excursion monitoring is mandatory. FDA track-and-trace requirements for drug serialization are accelerating semi-passive deployment in U.S. wholesale distribution.
- Active:Self-powered transmitters with proprietary protocols deliver extended read range for yard management and inter-facility vehicle tracking. Higher unit costs limit deployment to high-value asset categories in transportation and heavy equipment leasing.
- NFC:Near-field communication at 13.56 MHz serves proximity authentication and payment-adjacent applications with limited relevance to supply chain interrogation at scale. Healthcare access control and patient wristband identification represent primary demand concentration.
Passive technology commands the volume core; semi-passive is climbing the fastest on functional expansion into sensor convergence.
Application:
Application segmentation tracks directly to buyer procurement authority structures, with supply chain and inventory management representing distinct budget centers and vendor relationships.
- Inventory Management:Real-time stock visibility across storage zones, picking operations, and cycle-count workflows. Retailers in the United States deploy fixed reader arrays at receiving docks and back-of-store staging areas to eliminate manual barcode scanning.
- Supply Chain:End-to-end track-and-trace from manufacturing source through distribution to point of sale. BMW's Spartanburg and Leipzig assembly plants utilize beam-steering phased-array configurations for mixed-SKU pallet tracking without mechanical antenna positioning.
- Asset Tracking:Location monitoring for returnable transport items, tooling, and mobile equipment. Metallic interference physics in steel-racking environments drives demand for specialized UHF readers engineered by European industrial automation specialists.
- Access Control:Personnel and vehicle entry authorization integrated with building management systems. Healthcare facilities combine NFC and UHF technologies for staff credential verification and pharmaceutical secure storage access.
Inventory management captures the largest addressable segment by unit volume; supply chain is expanding most quickly on automotive supplier mandate pull-through.
End User:
End user segmentation reflects divergent technical specifications, with manufacturing demanding interference-resistant industrial designs and retail prioritizing dense-read performance at lowest infrastructure cost per read point.
- Manufacturing:Production line WIP tracking, quality control station routing, and finished goods serialization. Automated guided vehicle communication bands and welding equipment create electromagnetic compatibility challenges addressed through CE marking protocols under EU Radio Equipment Directive.
- Retail:Receiving accuracy, backroom inventory visibility, and loss prevention at store exits. DHL Supply Chain and GXO Logistics have established direct vendor relationships bypassing traditional automation channel partners for reader hardware procurement.
- Healthcare:Pharmaceutical distribution track-and-trace, medical device sterilization cycle logging, and patient identification. GDPR-style personal data governance intersects with tag-level traceability in consumer-facing deployments, complicating privacy impact assessments.
- Transportation:Fleet yard management, intermodal container tracking, and cross-dock shipment verification. Yard environments with metallic trailer surfaces and variable weather exposure demand ruggedized reader enclosures with extended operating temperature ranges.
Manufacturing leads on technical specification intensity; retail is the steepest expansion trajectory on e-commerce fulfillment velocity requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's automotive supplier corridor exports RFID-enabled track-and-trace compliance infrastructure to tier-one logistics networks across the European Union. This trade-flow dynamic compresses hardware replacement cycles as EPC Gen 2 V2 protocols standardize across cross-border fulfillment nodes.
United States
E-commerce fulfillment velocity mandates from Amazon, Walmart, and Target drive dense fixed-reader array deployment at conveyor throughput speeds. FCC Part 15 regulations govern unlicensed UHF operation and force region-locked firmware configurations that constrain read range in large distribution centers. The Inland Empire logistics cluster east of Los Angeles concentrates reader infrastructure investment to serve trans-Pacific container flows through the Ports of Long Beach and Los Angeles.
Germany
Tier-one automotive supplier contracts in Baden-Württemberg and Bavaria now mandate RFID-enabled track-and-trace compliance as a non-negotiable condition. ETSI EN 302 208 harmonizes European spectrum allocation and enables single-SKU hardware deployment across EU member states. The Stuttgart industrial corridor anchors demand concentration, with Bosch and Continental supplier networks pulling fixed reader infrastructure into upstream facilities.
China
Domestic logistics modernization programs under MIIT smart supply chain directives accelerate fixed reader deployment at cross-dock facilities and bonded warehouse zones. GB standards for UHF RFID equipment create certification requirements that filter non-compliant hardware from government procurement channels. The Yangtze River Delta manufacturing belt—spanning Shanghai, Suzhou, and Ningbo—concentrates reader demand from export-oriented electronics and automotive component suppliers.
India
PLI scheme incentives for electronics manufacturing attract reader assembly capacity to serve South Asian retail and logistics modernization programs. BIS certification requirements for radio equipment create compliance barriers that favor domestic production over imported hardware. The Delhi-Mumbai Industrial Corridor freight nodes and Bangalore e-commerce fulfillment clusters represent primary demand concentration for dock-door automation retrofits.
Japan
METI Industry 4.0 promotion programs subsidize RFID infrastructure deployment at automotive and electronics manufacturing facilities pursuing digital supply chain transformation. JIS standards for UHF RFID interoperability reduce integration complexity with existing factory automation systems. The Chubu region around Nagoya—Toyota's production heartland—concentrates fixed reader demand for just-in-sequence parts tracking at assembly plants.
Fixed RFID Readers Market Vendor Landscape
Player mix skews toward diversified industrial automation conglomerates with established channel control across North American and European distribution networks. Market structure exhibits tiered concentration, with three to four vendors capturing majority share in enterprise-grade deployments while regional specialists serve interference-heavy industrial applications. Strategic archetypes separate into channel-dominant platform vendors, RAIN RFID system architects, and European industrial specialists. Competitive moves concentrate on firmware-upgradeable hardware platforms and direct bypass of traditional systems integration partners.
Among North American technology vendors, Zebra Technologies, Impinj, and Honeywell occupy distinct positioning vectors. Zebra exemplifies channel-dominant platform deployment through deep distribution center relationships. Impinj anchors the RAIN RFID endpoint-to-reader system architecture tier with high-density read environment specialization. Honeywell sits within the diversified industrial conglomerate archetype, leveraging cross-portfolio automation integration capabilities. European industrial automation demand is served by FEIG ELECTRONIC and SICK, with FEIG representing specialized UHF reader engineering for metallic interference conditions and SICK exemplifying sensor-to-reader convergence in factory automation contexts. Siemens and OMRON represent diversified automation conglomerates with integrated RFID offerings embedded within broader Industry 4.0 portfolios.
| Leading Market Players |
|---|
| FEIG ELECTRONIC |
| Datalogic |
| Zebra Technologies |
| OMRON |
| Siemens |
| Impinj |
| CAEN RFID |
| SICK |
| Honeywell |
| Others |
Supply Flow & Price Mechanics
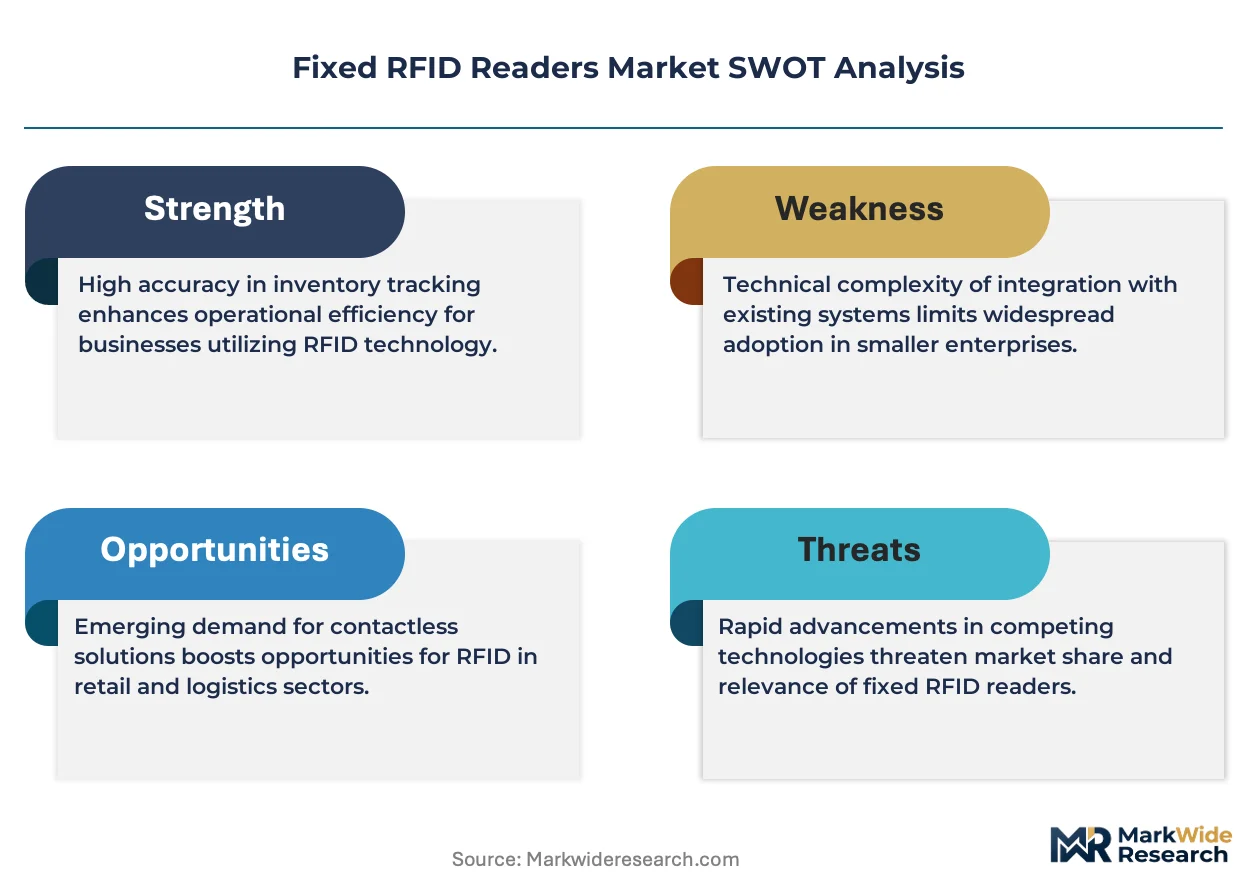
Fourteen-week lead times for digital signal processors and power amplifiers concentrate pricing power among Asian foundry-dependent vendors, compressing margins for European automation specialists while rewarding vertically integrated reader manufacturers with captive semiconductor sourcing.
Pricing Analysis
EPC Gen 2 V2-compliant reader hardware commands 15-25% premiums over legacy Gen 2 V1 installations, while next-generation software-defined radio platforms with firmware-upgradeable frequency agility stratify pricing across premium, standard, and economy tiers. Price differentiation centers on CE marking certification grade and read density performance in metallic interference conditions. Cost compression in economy-tier portable readers intensifies because India's PLI scheme incentives attract assembly capacity that undercuts German industrial automation pricing. Third-party logistics providers exhibit highest price sensitivity due to direct vendor relationship strategies that bypass traditional channel markups, whereas automotive tier-one suppliers prioritize certification reliability over unit cost.
Supply Chain Analysis
Strategic stockpiling of RF power amplifiers and antenna multiplexers dominates inventory strategy among German automotive suppliers facing ETSI EN 302 208 recertification deadlines, while North American e-commerce fulfillment operators prefer just-in-time reader procurement aligned with warehouse automation construction timelines. Manufacturing concentration centers on China for PCB assembly and antenna fabrication, Taiwan for digital signal processor foundry capacity, and Germany for specialized industrial-grade enclosure production. Raw material dependencies include gallium nitride substrates for power amplifiers, FR-4 and ceramic PCB laminates, and aluminum die-cast housings. Single-source vulnerability in 40nm RFIC foundry capacity exposes lead time volatility. Distribution runs through industrial automation channel partners in Europe and direct vendor relationships among North American third-party logistics providers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fixed RFID reader demand tracks the capital expenditure cycle of warehouse automation and automotive supplier compliance mandates, positioning this market for cyclical recovery as EPC Gen 2 V2 protocol standardization forces hardware replacement across installed bases.
For Market Incumbents: Consolidate channel control through exclusive distribution agreements with European industrial automation integrators, defending against direct vendor relationship strategies employed by DHL Supply Chain and GXO Logistics. Invest in CE marking pre-certification under EU Radio Equipment Directive tightening to capture German automotive supplier procurement locked to compliant platforms. Vertical integration into RF power amplifier sourcing reduces exposure to Taiwan foundry concentration risk. For New Entrants and Emerging Players: Firmware customization services for legacy WMS integration represent a service-layer gap where incumbent platform vendors under-serve mid-market distribution centers with rigid data schemas. Target dock-door automation retrofit opportunities in India's Delhi-Mumbai Industrial Corridor freight nodes, where PLI scheme incentives reduce import compliance barriers. Pursue antenna configuration-as-a-service go-to-market angles that bypass capital-intensive reader manufacturing. For Investors and Strategic Acquirers: Long-term, this sits as a protocol-convergence play because EPC Gen 2 V2 standardization compresses replacement cycles and concentrates procurement authority among enterprise buyers with multi-site standardization mandates. Acquisition target archetype: European industrial specialists with pre-certified metallic-interference-resistant reader platforms and established relationships with Bosch and Continental supplier networks. Monitor ETSI EN 302 208 harmonization implementation delays as inflection indicator for hardware certification backlog risk.| Strategic Initiative | Industry Significance |
|---|---|
| Firmware-Upgradeable Hardware Platform Development | Enables single-SKU deployment across FCC Part 15 and ETSI EN 302 208 regulatory zones without hardware swaps. |
| Direct Channel Bypass Partnership | Third-party logistics providers like DHL Supply Chain establish technical evaluation teams capable of independent antenna specification. |
| CE Marking Pre-Certification Investment | German automotive suppliers prioritize pre-certified reader platforms to avoid customs delays at intra-EU fulfillment nodes. |
| Semiconductor Supply Diversification | Reduces lead time volatility exposure from concentrated Asian foundry capacity for digital signal processors. |
| Cold-Chain Sensor Convergence Integration | Extends reader utility beyond identity capture to FDA-mandated temperature excursion monitoring in pharmaceutical distribution. |
Methodological Framework
A standing panel of warehouse automation directors, automotive supplier procurement managers, RFID systems integrators, and semiconductor component specialists provided ongoing calibration across primary interview cycles, validated against customs trade data for UHF reader equipment, SEC 10-K filings from industrial automation conglomerates, ETSI regulatory implementation notices, and MIIT smart supply chain directive documentation. Bottom-up reader shipment estimates by frequency band and form factor were triangulated against top-down capital expenditure tracking from third-party logistics providers and automotive OEM supplier networks.
Consistency checks against external benchmarks validated volume and value outputs across the analysis window, with segmentation dimensions modeling product type, technology tier, application workflow, end-user industry vertical, and regional regulatory cluster. CAGRs were derived from installed base replacement dynamics and net new deployment tracking. Forecast inputs incorporated EPC Gen 2 V2 protocol adoption curves and PLI scheme incentive disbursement timelines for Indian electronics manufacturing.
Underlying assumptions cover ETSI EN 302 208 harmonization completion, FCC Part 15 stability, and semiconductor foundry capacity normalization, with deviation risk concentrated in GDPR-tag traceability regulatory enforcement and legacy WMS integration middleware development bottlenecks. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors
Vibration Monitoring Market
Sensors
North America Eye Tracking Solutions Market
Sensors
Smart Mat Market
Sensors
Real Time Location System Market
Sensors
Europe Lidar Market
Sensors
Global Heat Stress Monitor (HSM) Market
Sensors
Ultrasonic Technologies Market
Sensors
Heat Stress Meter Market
Sensors
Global Radio Frequency Identification (RFID) Smart Cabinet Market
Sensors
Eye Tracking Market
Sensors
Gesture Recognition in Retail Market
Sensors
Handheld RFID Readers Market
Sensors
Voice Sounders Market
Sensors
Global Load Monitoring System (LMS) Market
Sensors
Surface Haptic Technology Market
Sensors
Global Smart Leak Detection Solutions Market