
 Global Fall Protection Market | 2026-2036
Global Fall Protection Market Size, Share, and Industry Trends Forecast 2026-2036
Global Fall Protection Market Foresight
Aftermarket service revenue for inspection, recertification, and equipment refurbishment is rewriting margin economics across the competitive landscape. 3M Company leverages its channel density to capture recurring calibration and replacement demand from industrial accounts. Honeywell International Inc. anchors its position through integrated connected-safety platforms that bundle hardware with software monitoring. MSA Safety Inc. competes on R&D intensity, sustaining technology leadership in gas detection and fall protection convergence.
Fall protection encompasses engineered systems—body harnesses with minimum 5,000-pound tensile-rated D-rings, energy-absorbing lanyards limiting arrest forces to 1,800 pounds, and self-retracting lifelines with integrated braking mechanisms—designed to eliminate or arrest falls from elevated work surfaces in occupational settings. Harnesses and self-retracting devices command the deepest margin pools due to certification complexity and replacement-cycle rigor, while anchor points represent a mature, price-commoditized category where installation services differentiate suppliers. Deployment through fixed systems dominates capital-intensive sectors like oil and gas, whereas portable and temporary installations accelerate in construction and renewable energy where site mobility governs procurement.
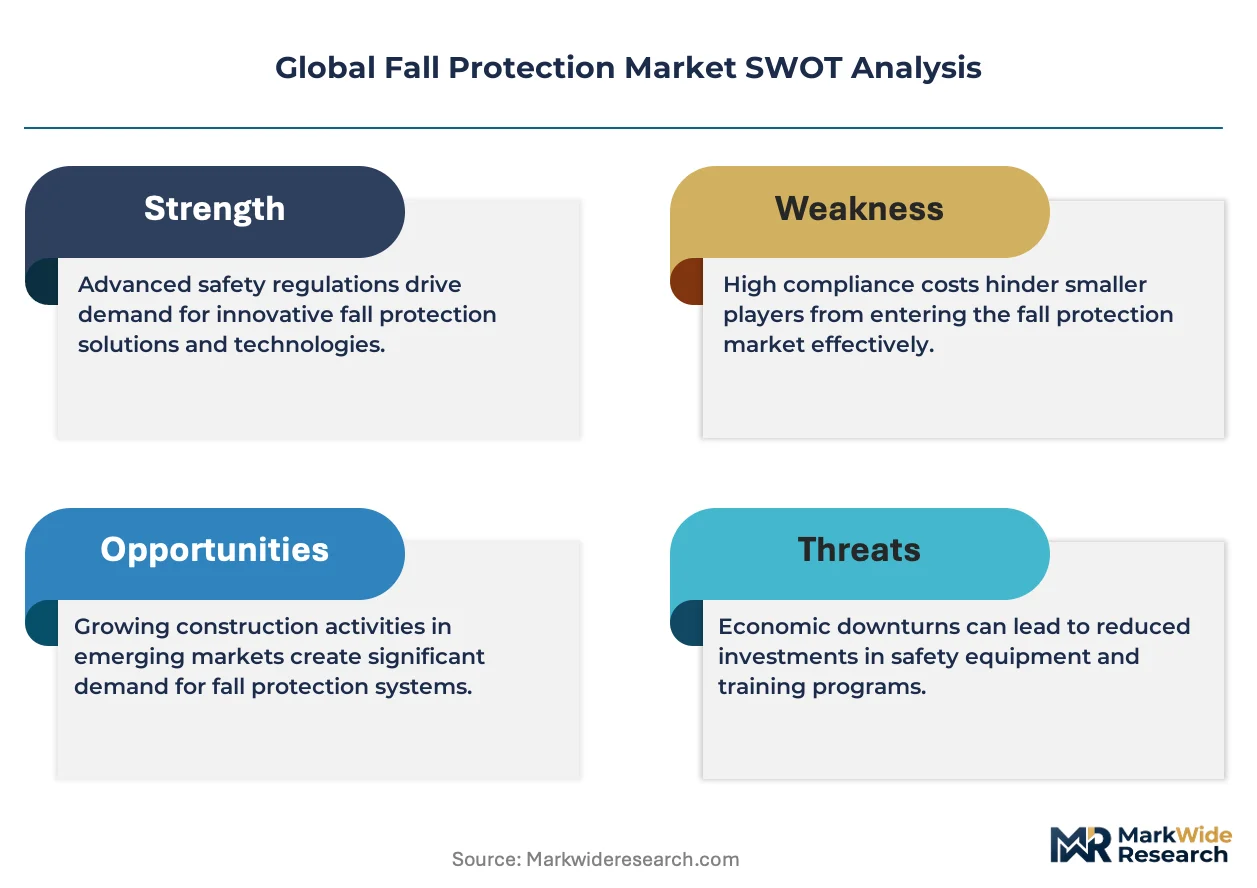
OSHA 1926 Subpart M and ANSI Z359 family standards govern product design and employer compliance in the United States, while the EU Machinery Directive and EN 795/EN 353-1 certification frameworks shape market access across Europe. China's GB 24542 and GB 24543 national standards, enforced by SAMR, are tightening import requirements and elevating domestic testing infrastructure. Stakeholders must monitor regulatory divergence between ANSI and EN test protocols, as dual-certification burdens will determine which suppliers retain cross-border competitiveness.
Market Dynamics
OSHA's 2023 enforcement surge on construction fall hazards is compressing replacement cycles for legacy anchor systems while accelerating procurement of connected-safety platforms that integrate hardware with real-time monitoring software.
Growth Catalysts
- OSHA 1926 Subpart M:Tighter inspection protocols across US construction sites are forcing contractors to retire non-compliant harnesses and energy-absorbing lanyards ahead of scheduled replacement dates.
- Wind turbine installation:Technician ascent work at 80-meter hub heights is driving specialized self-retracting lifeline procurement in Texas, Iowa, and offshore zones.
- Polymer webbing advances:Ultra-high-molecular-weight polyethylene fibers are reducing harness weight by 40% while maintaining 5,000-pound tensile ratings, accelerating adoption among roofing contractors.
Market Restraints
- Steel and aluminum input costs:Volatility in D-ring and carabiner raw materials is compressing margins for anchor point manufacturers locked into annual contract pricing.
- Chinese testing infrastructure concentration:SAMR-accredited laboratories for GB 24542 certification remain concentrated in Shanghai and Beijing, creating bottlenecks for foreign suppliers seeking market entry.
- ANSI-EN test protocol divergence:Dual-certification requirements for arrest force measurement (1,800 pounds US versus 6 kN Europe) inflate R&D overhead for cross-border product lines.
Strategic Opportunities
- India's PLI scheme for safety equipment:Domestic manufacturing incentives are opening import-substitution pathways for harness assembly operations in Gujarat and Tamil Nadu.
- Solar photovoltaic installation:Rooftop panel mounting at 15-30 degree pitches is creating demand for temporary horizontal lifeline systems in residential and commercial segments.
- Connected-safety convergence:Integration of fall protection hardware with gas detection and lone-worker monitoring is enabling bundled platform sales to oil and gas operators.
Industry Challenges
- Competent person training gaps:OSHA mandates for qualified inspectors exceed available certified trainers in secondary US construction markets, delaying site clearance timelines.
- Legacy anchor retrofit complexity:Installation of modern self-retracting lifelines onto pre-2010 structural steel requires engineering assessment protocols that extend project durations by 2-4 weeks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Fall Protection Market |
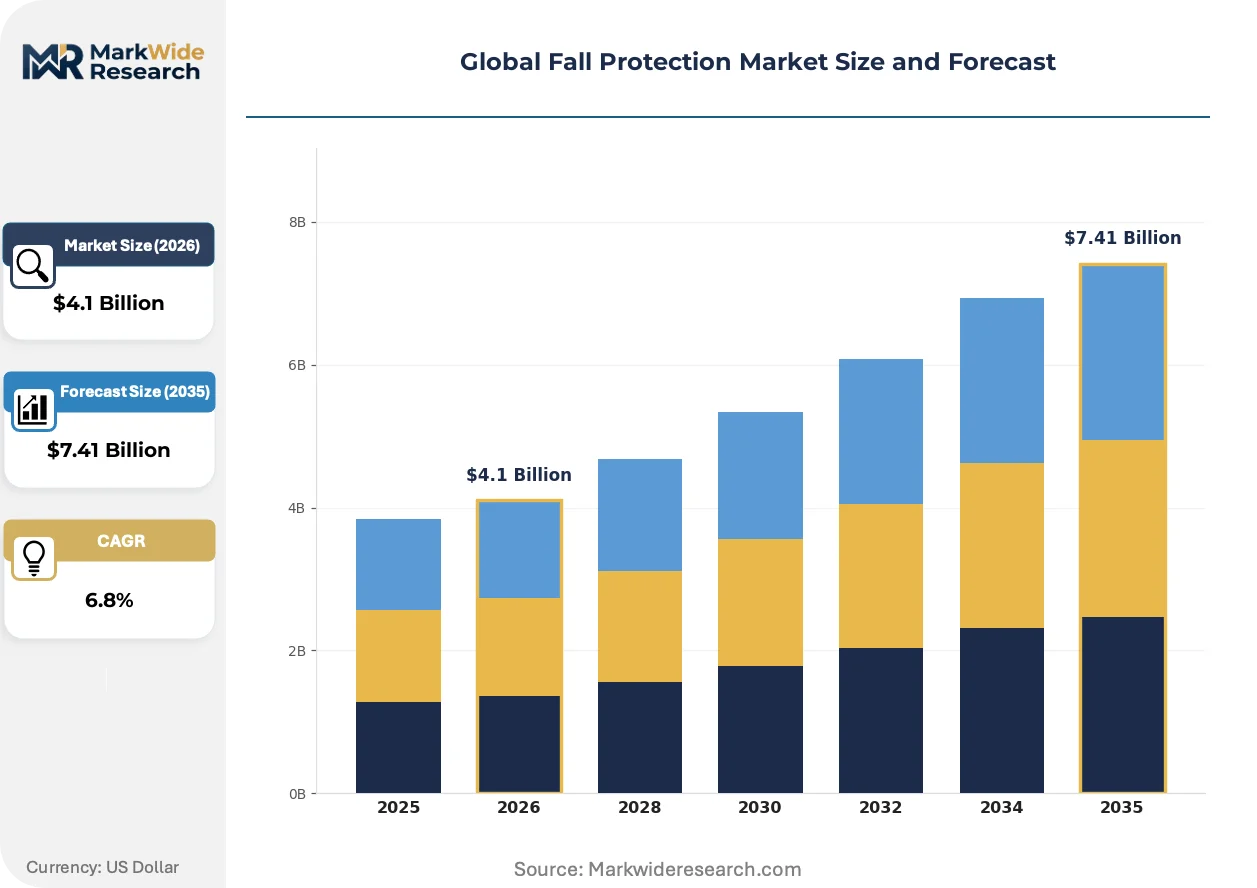
| Market Size in 2026 | $4.1 Billion |
| Market Size in 2035 | $7.41 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Harnesses, Lanyards, Lifelines, Anchor Points, Self-Retracting Devices Application: Construction Sites, Manufacturing Facilities, Warehousing, Oil & Gas Rigs, Telecommunications, Renewable Energy End User Industry: Commercial Contractors, Industrial Operators, Facility Maintenance, Utility Companies, Municipal Services Deployment Method: Fixed Systems, Portable Systems, Temporary Installations, Integrated Solutions |
| Companies Covered | 3M Company, Honeywell International Inc., MSA Safety Inc., Petzl Group, SKYLOTEC GmbH, WernerCo, FallTech, Guardian Fall Protection, Kee Safety Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Fall Protection Market Shifts & Advancements
Sensor-embedded personal protective equipment is transforming fall protection from passive arrest systems into predictive safety networks that alert supervisors before incidents occur.
Biometric strain sensors woven into harness shoulder straps is digitizing worker fatigue monitoring. Oil and gas operators in the Permian Basin are piloting these systems for derrick workers on 12-hour rotations. The technology is compressing incident response times from minutes to seconds by triggering automatic descent device activation.
EU Machinery Directive amendments tightening CE marking requirements for temporary anchor devices are forcing European manufacturers to redesign quick-install roof brackets. German construction firms are absorbing 15-20% equipment cost increases to maintain worksite compliance. The regulatory pressure is accelerating consolidation among small Italian and Spanish anchor point fabricators lacking in-house testing capabilities.
Equipment-as-a-service models are displacing capital purchase patterns among mid-sized US roofing contractors. Third-party logistics providers now bundle harness inspection, recertification, and replacement logistics into monthly per-worker fees. This shift is most visible in Florida and California where high worker turnover makes asset tracking uneconomical for individual employers.
Global Fall Protection Market Segmentation
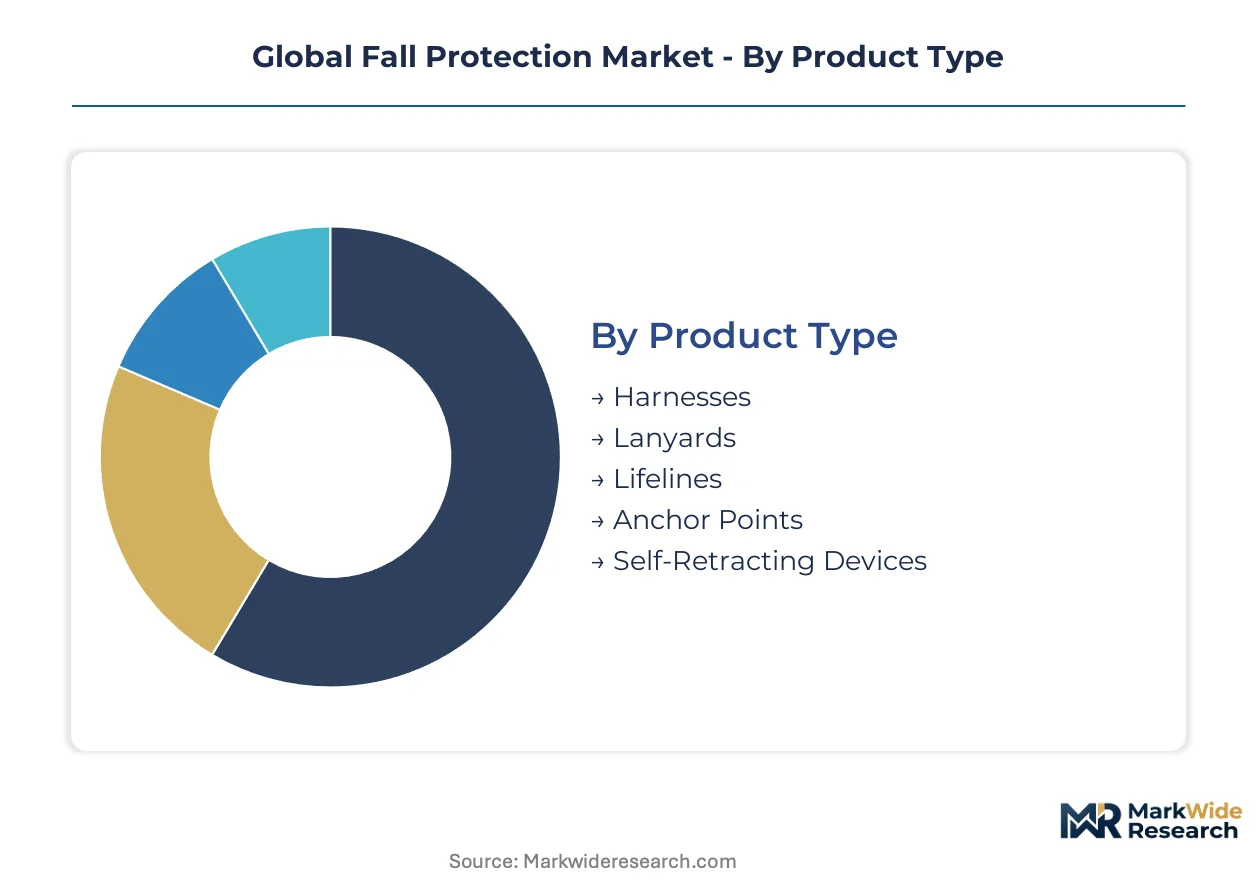
Fall protection procurement patterns diverge sharply across product architectures, workplace environments, and deployment methodologies. Understanding these fault lines reveals where certification complexity creates margin premiums versus where commoditization pressures dominate supplier economics.
Product Type:
Workplace elevation profiles dictate hardware selection across five functional categories spanning arrest, restraint, and positioning systems.
- Harnesses:Full-body configurations with 5,000-pound tensile-rated D-rings and dorsal attachment points dominate commercial construction. Roofing contractors in Florida and California absorb premium pricing for polymer webbing that cuts weight 40% without sacrificing load ratings.
- Self-Retracting Devices:Integrated braking mechanisms with automatic lock-on-fall functionality command the deepest margin pools due to recertification complexity and replacement-cycle rigor. Wind turbine technicians at 80-meter hub heights in Texas and Iowa drive specialized procurement of sealed units resistant to temperature cycling.
- Lanyards:Energy-absorbing designs limiting arrest forces to 1,800 pounds per OSHA 1926 Subpart M.
- Lifelines:Horizontal and vertical configurations for temporary horizontal lifeline systems on solar rooftops.
- Anchor Points:Mature category where installation services differentiate suppliers from commodity fabricators.
Established volume favors harnesses; emerging adoption favors self-retracting devices.
Application:
Height exposure severity and regulatory inspection frequency segment demand across six occupational settings.
- Construction Sites:OSHA's enforcement surge on fall hazards compresses replacement cycles for legacy anchor systems while accelerating connected-safety platform procurement. Commercial contractors face mandatory harness retirement ahead of scheduled dates.
- Renewable Energy:Technician ascent work at extreme elevations drives specialized self-retracting lifeline demand. Offshore wind zones in Europe and onshore clusters in the US Midwest require corrosion-resistant hardware with integrated gas detection convergence.
- Oil & Gas Rigs:Fixed systems dominate capital-intensive deployment with bundled platform sales.
- Manufacturing Facilities:Permanent installations with scheduled inspection protocols.
- Warehousing:Portable systems for mezzanine and elevated platform access.
- Telecommunications:Tower climbing equipment with lone-worker monitoring integration.
Construction absorbs the highest unit volumes; renewable energy shows the steepest expansion trajectory.
End User Industry:
Asset ownership structure and worker turnover rates determine procurement economics across five customer archetypes.
- Commercial Contractors:Equipment-as-a-service models displace capital purchases among mid-sized roofing operations. Third-party logistics providers bundle inspection, recertification, and replacement into monthly per-worker fees where high turnover makes asset tracking uneconomical.
- Industrial Operators:Oil and gas majors in the Permian Basin pilot biometric strain sensors woven into harness shoulder straps for derrick workers on extended rotations.
- Utility Companies:Integrated connected-safety platforms with real-time monitoring software.
- Facility Maintenance:Scheduled replacement programs tied to ANSI Z359 inspection intervals.
- Municipal Services:Budget-constrained procurement with extended equipment lifecycles.
Commercial contractors are shifting fastest to service-based procurement; industrial operators retain capital purchase dominance.
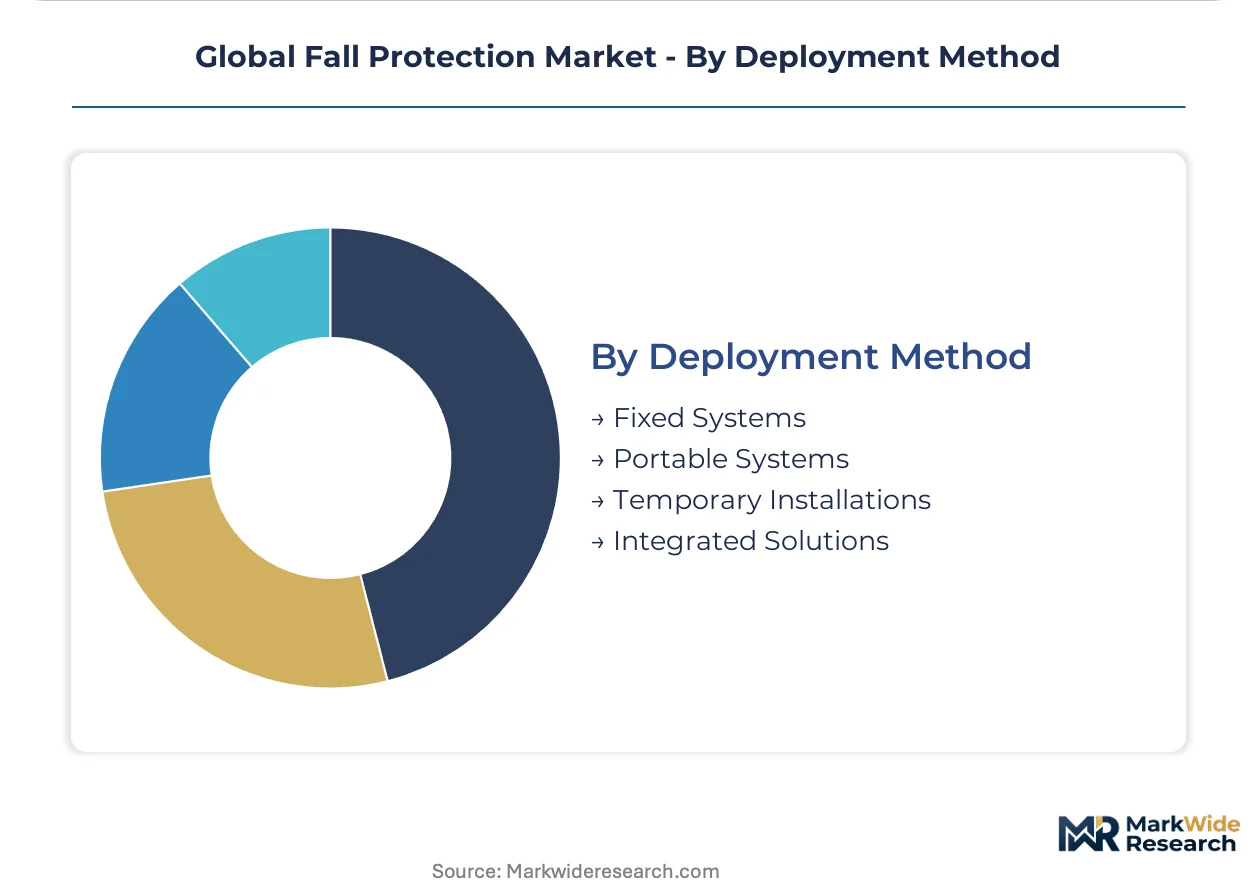
Deployment Method:
Site permanence and mobility requirements shape system architecture selection.
- Fixed Systems:Capital-intensive installations dominate oil and gas infrastructure with engineering assessment protocols for structural steel integration. Legacy anchor retrofit complexity extends project durations 2-4 weeks.
- Temporary Installations:Accelerate in construction and renewable energy where site mobility governs procurement. EU Machinery Directive amendments force 15-20% equipment cost increases for quick-install roof brackets.
- Portable Systems:Mobile configurations for multi-site contractors.
- Integrated Solutions:Hardware-software bundles with predictive safety networks.
Fixed systems retain the largest installed base; temporary installations are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies. The United States prioritizes connected-safety platform integration, while European procurement emphasizes CE-marked temporary systems, and Chinese demand concentrates on domestic-certified infrastructure hardware.
United States
Construction contractors across Texas and Florida are accelerating harness replacement cycles ahead of OSHA 1926 Subpart M inspection mandates. The Department of Labor's 2023 enforcement surge on fall hazards has compressed retirement timelines for legacy anchor systems. Houston's Permian Basin oil operators pilot biometric strain sensors for derrick workers on extended rotations.
Germany
EU Machinery Directive amendments are forcing 15-20% equipment cost increases for quick-install roof brackets across Bavarian and North Rhine-Westphalian construction sites. German fabricators absorb these premiums to maintain worksite compliance. Industrial clusters around Stuttgart and Munich are consolidating testing capabilities for EN 795/EN 353-1 certification.
China
Infrastructure renewal in the Yangtze River Delta and Pearl River Delta is elevating procurement of GB 24542-certified harness assemblies. SAMR enforcement is tightening import requirements and concentrating accredited laboratory capacity in Shanghai and Beijing. Domestic manufacturers in Jiangsu and Guangdong provinces are expanding testing infrastructure to capture substitution demand.
India
The PLI scheme for safety equipment is opening import-substitution pathways for harness assembly operations in Gujarat and Tamil Nadu. Central Electricity Authority mandates for renewable energy worker protection are driving specialized procurement for wind technician ascent equipment. Industrial corridors around Ahmedabad and Chennai are attracting component fabrication investments.
Brazil
ANVISA alignment with international fall protection standards is elevating certification requirements for construction hardware in São Paulo and Rio de Janeiro state projects. Federal infrastructure programs are accelerating anchor system deployment across hydroelectric and transmission line maintenance operations. Southeast industrial clusters are absorbing compliance costs to retain federal contract eligibility.
Global Fall Protection Market Competitive Landscape
Capability concentration sits with integrated safety platform developers; scale advantage sits with diversified industrial conglomerates. The market structures around three tiers: multinational technology leaders bundling hardware with software monitoring, regional specialists dominating certification-intensive product categories, and price-competitive fabricators serving commoditized anchor point segments. Dominant competitive moves include strategic partnerships for connected-safety convergence and geographic expansion into PLI-incentivized manufacturing jurisdictions.
Within the integrated platform tier, 3M Company and Honeywell International Inc. exemplify archetypes combining channel density with recurring service revenue capture. MSA Safety Inc. occupies a position emphasizing R&D intensity and technology convergence. Among European specialists, Petzl Group and SKYLOTEC GmbH represent certification-focused engineering heritage. These named entities anchor competitive dynamics without exhausting the vendor landscape.
| Leading Market Players |
|---|
| 3M Company |
| Honeywell International Inc. |
| MSA Safety Inc. |
| Petzl Group |
| SKYLOTEC GmbH |
| WernerCo |
| FallTech |
| Guardian Fall Protection |
| Kee Safety Inc. |
| Others |
Supply & Pricing Matrix
Jiangsu province's polymer webbing manufacturing clusters command decisive leverage over global harness pricing through captive access to ultra-high-molecular-weight polyethylene fiber production. Their capacity discipline transmits directly into margin structures for downstream full-body harness and self-retracting device assembly.
Pricing Analysis
Long-term offtake agreements dominate procurement between industrial operators and tier-one manufacturers, locking in volume commitments against price stability guarantees. Price differentiation centers on certification grade—dual ANSI Z359 and EN 795 compliance commands 15-25% premiums over single-standard products—and after-sales service bundling including inspection and recertification logistics. Cost compression in anchor point manufacturing is intensifying as steel and aluminum input volatility squeezes fabricators locked into annual contract pricing. Commercial roofing contractors exhibit the highest price sensitivity due to thin project margins and high worker turnover, while oil and gas operators show least sensitivity given bundled platform procurement and safety-critical application requirements.
Supply Chain Analysis
Ultra-high-molecular-weight polyethylene fiber feedstock draws from concentrated production in China, the United States, and the Netherlands, with polymer-grade specifications varying by tensile rating requirements. Component dependencies extend to aircraft-grade aluminum for D-rings and carabiners, synthetic elastomers for energy-absorbing lanyard cores, and precision-machined steel for self-retracting lifeline braking mechanisms. Single-source vulnerability in SAMR-accredited testing infrastructure—concentrated in Shanghai and Beijing—creates certification bottlenecks for foreign suppliers seeking GB 24542 market entry. Distribution runs through specialized industrial safety distributors with field service capabilities, rather than generalist construction supply houses.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Fall Protection Market sits in early-cycle expansion as connected-safety platform adoption penetrates beyond early-adopter oil and gas operators into mainstream construction and renewable energy deployment. OSHA enforcement tightening and EU Machinery Directive amendments are accelerating hardware replacement cycles and software bundling simultaneously.
For Market Incumbents: Harden certification moats by deepening in-house testing capabilities for dual ANSI-EN compliance as regulatory divergence intensifies R&D overhead burdens on cross-border competitors. Anchor channel control through equipment-as-a-service model expansion, converting capital purchase relationships into recurring revenue streams that resist price commoditization in anchor point segments.
For New Entrants and Emerging Players: Establish a beachhead in India's PLI-incentivized manufacturing corridor, where domestic assembly cost structures undercut import landed costs for regional Southeast Asian and Middle Eastern markets. Target solar photovoltaic installation contractors with temporary horizontal lifeline systems purpose-built for 15-30 degree rooftop pitches, a specification gap left by legacy construction-focused suppliers.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors integrated platform developers with software-hardware convergence capabilities over pure-play hardware fabricators facing margin compression. Long-term viability hinges on recurring service revenue attachment rates rather than transactional equipment sales volume. Watch biometric sensor integration adoption curves in Permian Basin oil operations as the inflection signal for connected-safety platform mainstreaming.
| Strategic Initiative | Industry Significance |
|---|---|
| Connected-Safety Platform Integration | Hardware-software bundling with OSHA-compliant real-time monitoring captures recurring service revenue from industrial accounts. |
| Dual-Certification R&D Investment | ANSI Z359 and EN 795 convergence capabilities determine cross-border competitiveness as test protocol divergence widens. |
| Equipment-as-a-Service Model Expansion | Monthly per-worker fees displace capital purchases among high-turnover roofing contractors in Florida and California. |
| PLI-Aligned Manufacturing Footprint | Domestic assembly in Gujarat and Tamil Nadu reduces import substitution costs for Indian renewable energy infrastructure procurement. |
| Biometric Sensor Technology Development | Strain-sensor integration into harness shoulder straps enables predictive fatigue monitoring for extended-rotation derrick workers. |
Research Methodology
A standing panel of safety equipment procurement managers at commercial contractors, industrial HSE directors, certification laboratory technical leads, and aftermarket service operations heads provided ongoing calibration against market developments. Primary fieldwork combined structured interviews with these stakeholders and secondary validation through OSHA enforcement action databases, EU Machinery Directive amendment filings, SAMR GB standard publication records, and customs trade data for polymer webbing and aluminum component flows. Bottom-up equipment shipment analysis and top-down industrial safety spend estimates were triangulated to anchor volume and value outputs.
Scenario-bracketing around OSHA enforcement intensity, raw material price volatility bands, and connected-safety platform adoption curves shaped projections across the analysis window. Segmentation dimensions modeled include product architecture, workplace environment severity, deployment methodology permanence, and end-user industry asset ownership structure. CAGRs were derived from installed base replacement cycle analysis and penetration rate assumptions for emerging application segments including wind turbine technician ascent equipment and solar rooftop temporary lifeline systems.
Stress conditions across steel and aluminum input cost volatility, SAMR laboratory accreditation bottlenecks, and ANSI-EN regulatory divergence timelines were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding enforcement continuity and technology adoption elasticity. Cross-checking against industrial safety distributor inventory turnover benchmarks and construction sector employment data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Personal Safety
Rearward Facing Type Child Safety Seats Market
Personal Safety
Fall Detection System Market
Personal Safety
Global Self Defense Products Market
Personal Safety
Smart Personal Safety and Security Device Market
Personal Safety
Personal Safety Apps for Women Market
Personal Safety
Pepper Sprays Market
Personal Safety
Asia-Pacific People Screening Market
Personal Safety
Child Leash Market
Personal Safety
Bulletproof Vest Market
Personal Safety
Road Safety Market
Personal Safety
Personal Safety Alarms Market
Personal Safety
Pedestrian Protection Airbag Market
Personal Safety
Night Vision Goggles Market
Personal Safety
Life Jacket Market
Personal Safety
China Travel Safety Kits Market
Personal Safety
Child Safety Seat Market