
 Global Healthcare Integration Market | 2026-2036
Global Healthcare Integration Market Size, Share, and Industry Trends Forecast 2026-2036
Global Healthcare Integration Market Foresight
The EU AI Act is restructuring procurement criteria for clinical decision support systems across European health networks. Oracle Cerner leverages its cloud infrastructure footprint to sustain large-scale hospital deployments in North America. Epic Systems Corporation anchors its competitive position through deep integration with ambulatory care workflows. Siemens Healthineers competes by specializing in imaging-to-EHR connectivity across diagnostic laboratories.
Healthcare integration encompasses the technical architectures, middleware platforms, and standardized protocols that enable disparate clinical, operational, and financial systems to exchange structured data in real time, typically employing HL7 FHIR, DICOM, and IHE profiles to ensure semantic interoperability. Its primary commercial purpose is eliminating information silos that fragment patient records, delay care coordination, and inflate administrative costs across multi-site health delivery organizations. Integration Platforms currently occupy the largest product-type position by deployment volume, while Cloud-Based deployment is expanding fastest as health systems shed capital-intensive on-premises data centers. API Management solutions are capturing concentrated margin pools as payers and third-party application developers demand programmable access to clinical repositories.
The FDA enforces information blocking provisions under the 21st Century Cures Act, penalizing vendors that restrict health data exchange and thereby accelerating demand for certified interoperable platforms. EMA's Medical Device Regulation and Japan's METI digital health standards are converging on FHIR-based data exchange requirements, compressing market access for non-compliant systems. Stakeholders must monitor whether emerging national AI governance frameworks will mandate algorithmic audit trails as a precondition for integrated clinical workflow certification.
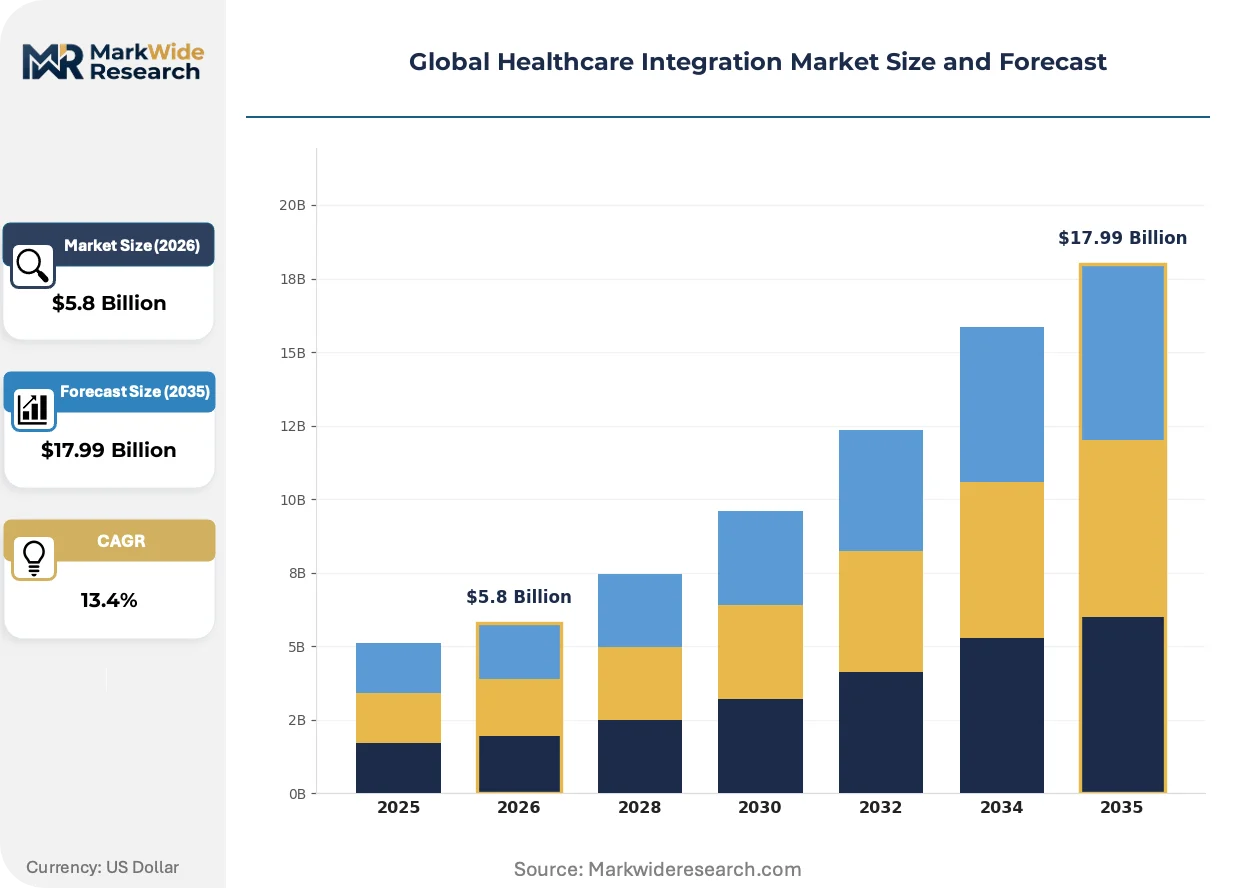
Market Dynamics
The FDA's 21st Century Cures Act information blocking enforcement is compelling health IT vendors to dismantle proprietary data silos, fundamentally restructuring how hospital systems procure interoperability infrastructure.
Growth Catalysts
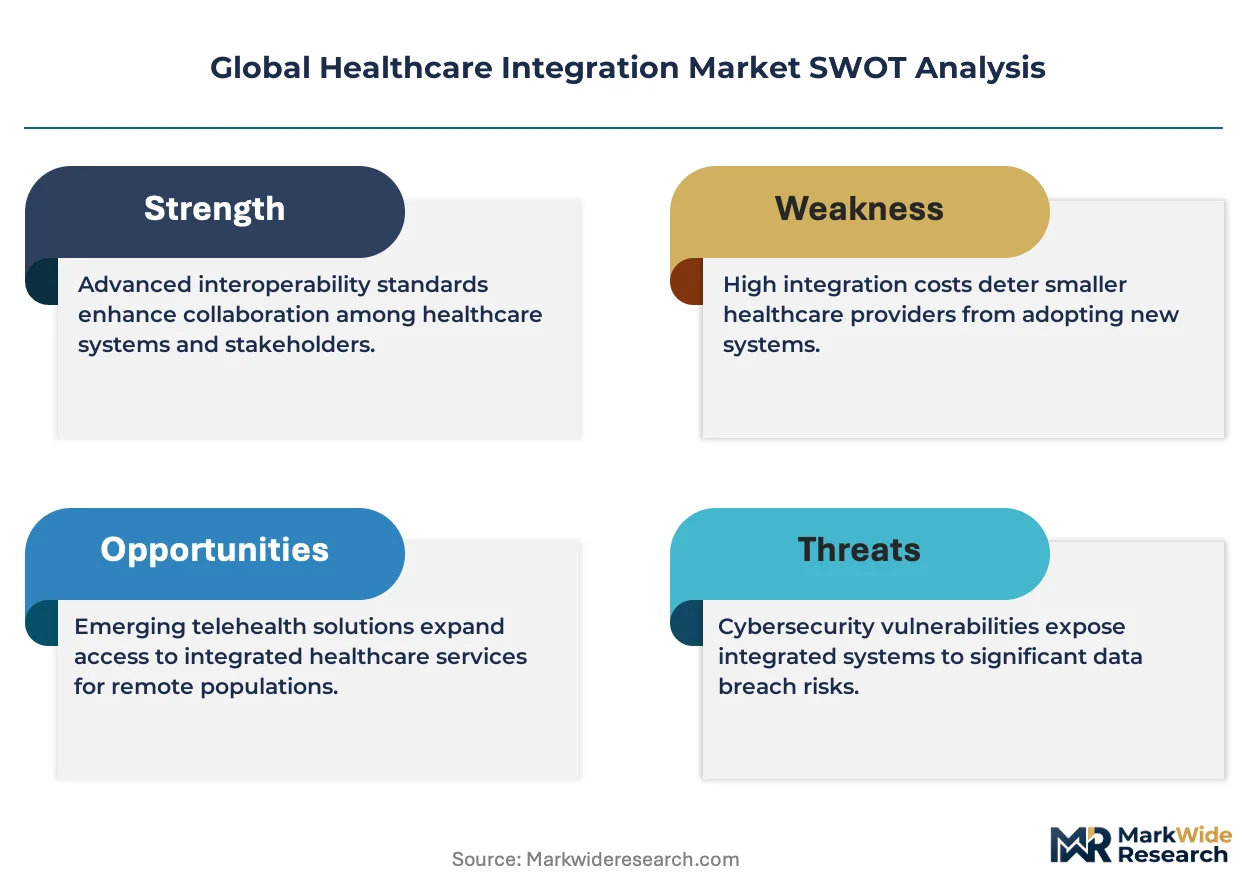
- FHIR-based data exchange mandates:Japan's METI digital health standards and the EU AI Act are converging on HL7 FHIR protocols, forcing vendor compliance upgrades across diagnostic networks.
- Cloud migration acceleration:Health systems in the United States, Germany, and Australia are shedding on-premises data centers for API-enabled platforms that reduce capital intensity.
- Reimbursement-linked certification:Federal incentive programs tie hospital payments to certified electronic health record integration, creating procurement urgency.
Market Restraints
- Legacy system technical debt:Decades-old hospital information systems lack native API architectures, requiring expensive middleware layers for FHIR connectivity.
- Input cost volatility:Cloud compute and cybersecurity talent costs have risen sharply, compressing margins for integration platform vendors.
- Regulatory fragmentation:Divergent national data localization requirements between China's NMPA, India's CDSCO, and Brazil's ANVISA complicate multi-territory platform deployment.
Strategic Opportunities
- Algorithmic audit trail mandates:Emerging AI governance frameworks in the European Union and United States are creating demand for integrated clinical workflow certification that embeds explainability logging.
- Imaging-to-EHR connectivity:Diagnostic laboratories in South Korea and Switzerland are investing in DICOM-to-FHIR bridges that unify radiology workflows with ambulatory records.
- Third-party developer ecosystems:Payers in the United Kingdom and Canada are opening clinical repositories via API management layers, enabling new application marketplaces.
Industry Challenges
- Interoperability engineer scarcity:Health systems struggle to recruit specialists fluent in HL7 FHIR, IHE profiles, and cloud-native architectures.
- Multi-vendor integration complexity:Hospitals running Epic, Cerner, and Siemens Healthineers simultaneously face semantic mapping failures that delay care coordination.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Healthcare Integration Market |
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $17.99 Billion |
| CAGR (2026 – 2036) | 13.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Integration Platforms, Middleware Solutions, Interface Engines, API Management, Data Repositories, Messaging Systems Application: Electronic Health Records, Laboratory Information Systems, Radiology Information Systems, Patient Portals, Telemedicine, Revenue Cycle Management End User: Hospitals, Diagnostic Laboratories, Ambulatory Care Centers, Insurance Providers, Research Institutes, Pharmacy Chains Deployment: Cloud-Based, On-Premises, Hybrid, Managed Services, Virtual Appliances, Microservices Architecture |
| Companies Covered | Oracle Cerner, Epic Systems Corporation, InterSystems Corporation, GE Healthcare, IBM, Siemens Healthineers, Allscripts Healthcare Solutions, Philips Healthcare, Infor, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Healthcare Integration Market Shifts & Advancements
Real-time data streaming architectures are displacing batch-oriented integration, enabling clinical decision support at the point of care rather than in retrospective reporting cycles.
Fast Healthcare Interoperability Resources (FHIR) R4 and R5 specifications are unifying previously incompatible EHR vocabularies into standardized resource models. Large academic medical centers in the United States and university hospitals in Germany are deploying FHIR-native platforms for medication reconciliation and care transition management. This unification is compressing implementation timelines for multi-site health networks from years to months.
The EU AI Act's risk-based classification system for clinical decision support is restructuring procurement criteria across European health networks. High-risk diagnostic algorithms now require conformity assessments that integrate with existing EMA Medical Device Regulation pathways. Diagnostic imaging vendors in France, Italy, and the Netherlands are redesigning product roadmaps to embed algorithmic audit capabilities that satisfy both frameworks.
Subscription-based platform pricing is displacing perpetual license models for integration middleware. Hospital procurement teams in Australia and the United Kingdom are negotiating outcome-tied contracts that link vendor payments to measured reductions in care coordination delays. This shift is most visible in accountable care organizations and integrated delivery networks where CFOs demand operational metrics rather than technical feature checklists.
Global Healthcare Integration Market Segmentation
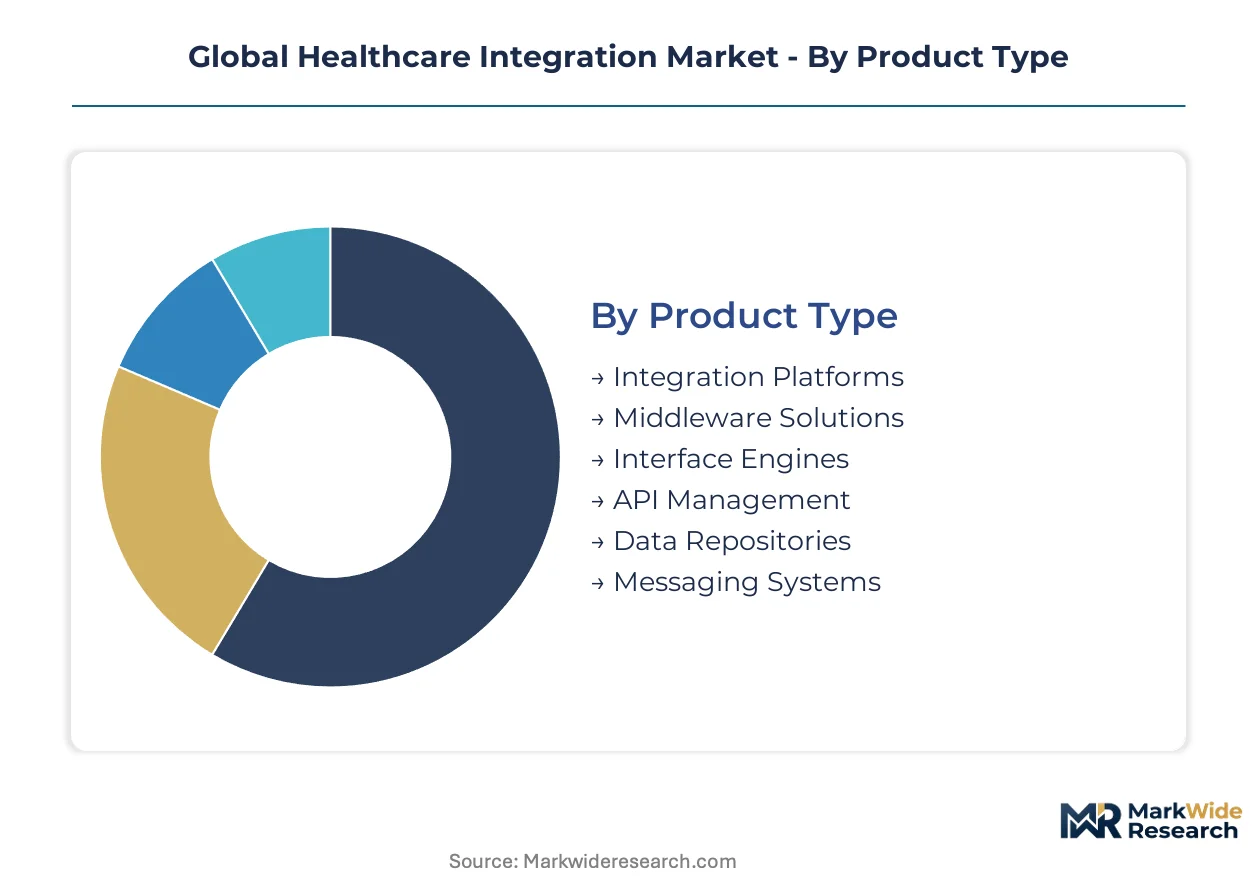
Healthcare integration vendors structure product portfolios around distinct certification burdens and deployment complexities. Each segment carries specific regulatory obligations that shape procurement timelines and margin structures across hospital systems and diagnostic networks.
Product Type:
FDA 21st Century Cures Act information blocking rules impose certification requirements unevenly across product categories, with API-facing platforms facing the heaviest compliance scrutiny.
- Integration Platforms:Comprehensive middleware architectures orchestrating data flows between disparate clinical systems. Demand concentrates in United States integrated delivery networks where federal reimbursement penalties for non-interoperability drive urgent replacement cycles. These platforms require ONC certification for participation in Medicare incentive programs.
- API Management:Programmable gateway layers enabling third-party application access to clinical repositories. United Kingdom and Canadian payers are opening repositories via these layers, creating concentrated margin pools as developer ecosystems expand. GDPR and HIPAA compliance audits add implementation overhead.
- Middleware Solutions:Translation engines bridging legacy HL7 v2 messaging with modern FHIR protocols.
- Interface Engines:Point-to-point connectivity tools for specific departmental system linkages.
- Data Repositories:Centralized storage architectures for longitudinal patient records.
- Messaging Systems:Secure transport layers for real-time clinical alerts and notifications.
Leading the category by volume: Integration Platforms. Growing fastest: API Management.
Application:
Procurement urgency varies sharply by clinical workflow, with revenue-cycle-linked applications commanding larger budgets than administrative modules.
- Electronic Health Records:Core clinical documentation systems requiring bidirectional data exchange with ancillary departments. United States hospital systems prioritize EHR-anchored integration due to federal meaningful use penalties, while German university hospitals deploy FHIR-native platforms for medication reconciliation workflows.
- Revenue Cycle Management:Financial workflow integration spanning claims submission, eligibility verification, and denial management. Australian accountable care organizations negotiate outcome-tied contracts linking vendor payments to measured reductions in administrative delays.
- Laboratory Information Systems:Diagnostic test ordering, result reporting, and specimen tracking integration.
- Radiology Information Systems:Imaging workflow coordination with PACS and EHR environments.
- Patient Portals:Consumer-facing access layers for appointment scheduling and record review.
- Telemedicine:Virtual care platform connectivity with existing clinical repositories.
Top procurement spend: Electronic Health Records. Steepest expansion trajectory: Revenue Cycle Management.
End User:
Technical sophistication and integration budget scale inversely across the care continuum, with tertiary hospitals absorbing complexity that outpatient facilities outsource.
- Hospitals:Multi-site health systems running simultaneous Epic, Cerner, and Siemens Healthineers deployments face acute semantic mapping failures. These organizations recruit scarce interoperability engineers fluent in HL7 FHIR and IHE profiles at premium compensation.
- Diagnostic Laboratories:South Korean and Swiss facilities invest in DICOM-to-FHIR bridges unifying radiology workflows with ambulatory records. EMA Medical Device Regulation conformity assessments compress market access timelines for non-compliant imaging integration.
- Ambulatory Care Centers:Smaller-scale practices prioritizing cloud-based deployment to avoid capital-intensive infrastructure.
- Insurance Providers:Payers requiring programmatic access to clinical data for risk stratification.
- Research Institutes:Academic medical centers demanding FHIR-native platforms for care transition management.
- Pharmacy Chains:Retail pharmacy networks integrating prescription data with hospital discharge summaries.
Dominant volume share: Hospitals. Gaining share fastest: Diagnostic Laboratories.
Deployment:
Capital intensity preferences and cybersecurity risk tolerance segment the deployment landscape across health system CFO priorities.
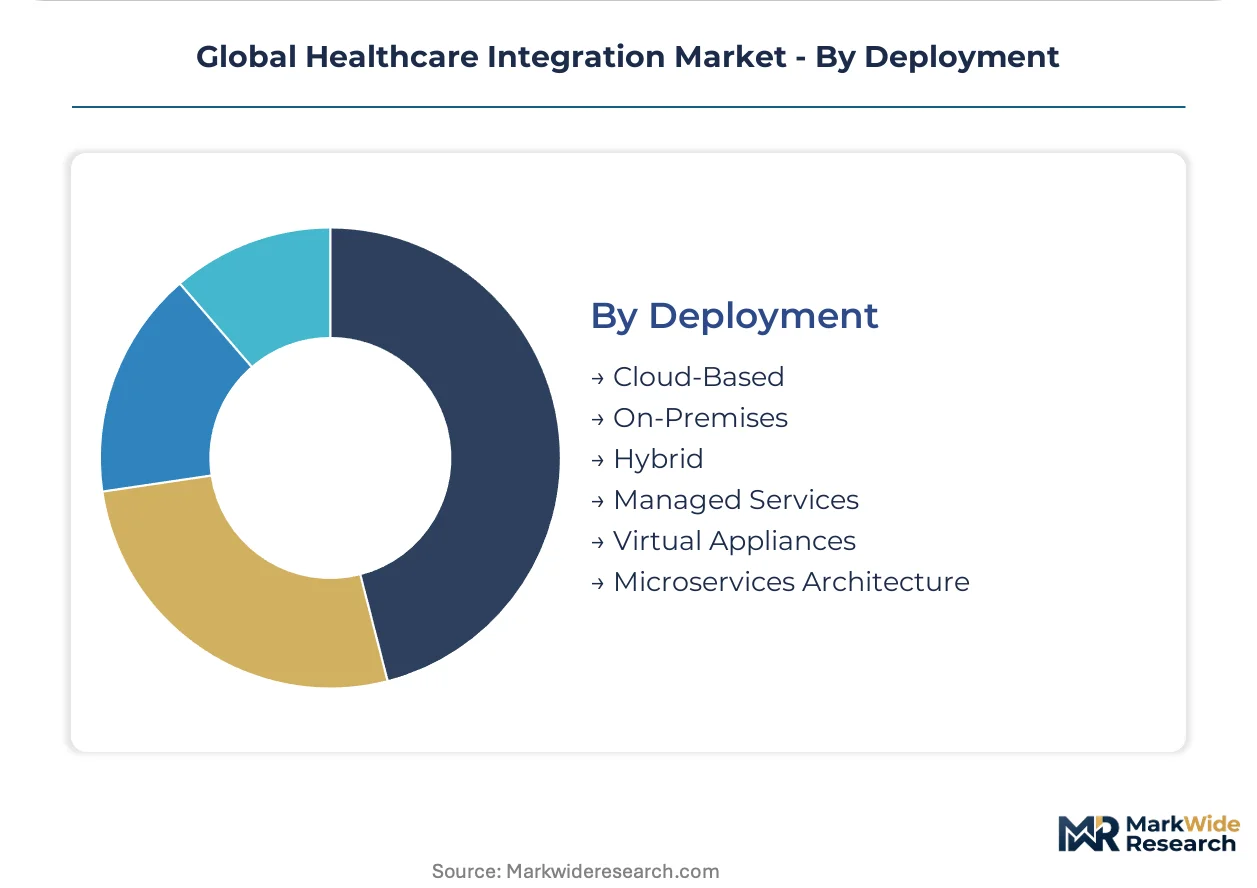
- Cloud-Based:API-enabled platforms eliminating on-premises data center overhead. Health systems in Germany, Australia, and the United States are shedding capital-intensive infrastructure for subscription models, though cloud compute cost volatility compresses vendor margins.
- Microservices Architecture:Containerized integration components enabling incremental modernization of legacy estates. Japan's METI digital health standards and EU AI Act convergence on FHIR protocols accelerate demand for modular, upgradeable deployment patterns.
- On-Premises:Self-managed infrastructure retained by organizations with strict data localization requirements.
- Hybrid:Mixed cloud and local deployment balancing flexibility with control.
- Managed Services:Outsourced operational responsibility for integration platform maintenance.
- Virtual Appliances:Pre-configured software images for rapid departmental deployment.
Current deployment majority: Cloud-Based. Climbing the fastest: Microservices Architecture.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Boston metropolitan area anchors North American healthcare integration deployment, hosting Epic Systems Corporation headquarters and dense clusters of academic medical centers piloting FHIR-native architectures.
United States
Federal meaningful use penalties and Medicare reimbursement linkage drive hospital procurement urgency. FDA 21st Century Cures Act information blocking enforcement compels vendor compliance upgrades. The Boston-Cambridge corridor concentrates Epic Systems Corporation operations alongside Massachusetts General Hospital and Brigham and Women's Hospital deployments.
Germany
University hospitals in Baden-Württemberg and Bavaria prioritize FHIR-native platforms for medication reconciliation workflows. EMA Medical Device Regulation and EU AI Act convergence compress market access timelines for non-compliant systems. The Rhine-Neckar metropolitan region hosts Siemens Healthineers integration engineering centers serving diagnostic laboratory networks.
Japan
METI digital health standards mandate FHIR protocol adoption across diagnostic networks. PMDA guidance aligns with international interoperability frameworks, accelerating cloud migration among Tokyo metropolitan hospitals. The Osaka-Kobe corridor concentrates imaging-to-EHR connectivity investments for aging population care coordination.
Switzerland
Diagnostic laboratories in Zurich and Geneva invest in DICOM-to-FHIR bridges unifying radiology workflows with ambulatory records. Swissmedic requirements overlap with EU MDR pathways, streamlining conformity assessments for integrated clinical systems. The Basel metropolitan area anchors pharmaceutical-research institute data integration demand.
Australia
Accountable care organizations in New South Wales and Victoria negotiate outcome-tied contracts linking vendor payments to care coordination metrics. TGA digital health frameworks emphasize API-enabled platform certification. The Melbourne-Sydney corridor concentrates cloud-based deployment adoption as health systems shed on-premises infrastructure.
Global Healthcare Integration Market Competitive Landscape
The competitive structure tilts toward diversified health IT conglomerates with cloud infrastructure depth. Hospital procurement teams favor vendors offering end-to-end integration stacks over point solutions. Three archetypes dominate: EHR-native platform builders, imaging-system specialists with diagnostic connectivity expertise, and cloud infrastructure providers retrofitting interoperability layers. M&A activity concentrates on API management capabilities and FHIR-native middleware acquisitions.
Among North American health IT conglomerates, Oracle Cerner and Epic Systems Corporation exemplify the EHR-native archetype, anchoring competitive positioning through deep workflow integration. Siemens Healthineers occupies the imaging-to-EHR specialist tier, while InterSystems Corporation represents the middleware-native approach with database architecture heritage. These three patterns illustrate how vendor origin shapes interoperability strategy.
| Leading Market Players |
|---|
| Oracle Cerner |
| Epic Systems Corporation |
| InterSystems Corporation |
| GE Healthcare |
| IBM |
| Siemens Healthineers |
| Allscripts Healthcare Solutions |
| Philips Healthcare |
| Infor |
| Others |
Supply & Pricing Matrix
FHIR-native platform architectures are simultaneously compressing implementation timelines and redistributing value capture toward API management layers, reshaping how vendors structure subscription economics and where procurement budgets concentrate across hospital systems.
Pricing Analysis
Outcome-tied contracts anchor pricing models across Australian accountable care organizations and United States integrated delivery networks, linking vendor payments to measured reductions in care coordination delays. Three-tier pricing structure across premium, standard, and economy levels separates ONC-certified platforms from uncertified middleware and basic interface engines. Cost compression in cloud compute tiers is intensifying because hyperscaler pricing volatility has compressed vendor margins. Ambulatory care centers exhibit highest price sensitivity due to capital constraints, while tertiary hospital systems absorb premium pricing for workflow-integrated stacks.
Supply Chain Analysis
Refurbishment flows for legacy HL7 v2 interface engines create secondary market circulation as hospitals modernize toward FHIR-native architectures, extending equipment lifecycles in cost-constrained settings. Component manufacturing concentrates in the United States, Germany, and India for middleware platforms and API gateway hardware. Supply chains draw from specialized semiconductor foundries, cybersecurity talent pools, and cloud infrastructure providers. Single-source vulnerability in FHIR certification expertise creates bottlenecks for rapid deployment scaling. Distribution runs through direct enterprise sales teams and systems integrator partnerships serving multi-site health networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Healthcare integration sits in a protocol-transition phase as HL7 FHIR R4 and R5 specifications displace decades-old HL7 v2 messaging, forcing vendor roadmap recalibration and procurement cycle acceleration.
For Market Incumbents: To counter cloud-native entrants with API-first architectures, Oracle Cerner and Epic Systems Corporation must deepen backward integration into FHIR-native middleware development while expanding certification engineering capacity in the Boston-Cambridge corridor to maintain ONC compliance leadership. For New Entrants and Emerging Players: Mid-sized diagnostic laboratories in South Korea and Switzerland present the most penetrable buyer archetype, as these facilities seek DICOM-to-FHIR bridges outside incumbent EHR vendor ecosystems. A developer marketplace strategy targeting payer API programs in the United Kingdom and Canada offers lowest customer acquisition friction. For Investors and Strategic Acquirers: Re-rating potential sits with FHIR-native middleware specialists given EU AI Act algorithmic audit mandates and FDA information blocking enforcement creating compliance-driven procurement urgency. Long-term viability favors platforms with embedded explainability logging capabilities. Monitor ONC certification backlog delays as an inflection indicator for vendor market share shifts.| Strategic Initiative | Industry Significance |
|---|---|
| FHIR-Native Platform Development | Eliminates expensive middleware layers for legacy system connectivity, accelerating hospital procurement cycles. |
| API Management Layer Acquisition | Captures concentrated margin pools as United Kingdom and Canadian payers open clinical repositories to third-party developers. |
| ONC Certification Investment | Secures participation in Medicare incentive programs tying federal reimbursement to interoperability compliance. |
| Algorithmic Audit Trail Embedding | Satisfies EU AI Act high-risk diagnostic algorithm requirements and EMA Medical Device Regulation conformity assessments. |
| Cloud Infrastructure Partnership | Reduces capital intensity for health systems in Germany, Australia, and the United States shedding on-premises data centers. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with hospital CIOs, health system procurement committees, biomedical informaticists, and interoperability engineers. Hospital procurement databases, CMS Medicare reimbursement records, FDA 510(k) submissions, and GPO contract repositories provided demand-side validation. Bottom-up deployment volume estimates triangulated against top-down healthcare IT spending forecasts across the analysis window.
Reconciliation of hospital EHR installation records, cloud infrastructure capex disclosures, and regulatory compliance timelines shaped the projection framework. Segmentation modeling incorporated product type, deployment architecture, application workflow, and end-user sophistication tiers. CAGRs derived from fitted growth curves calibrated to federal incentive program phase-in schedules and international FHIR mandate adoption curves. Supply-side inputs included vendor revenue disclosures and systems integrator backlog indicators.
Revisions become necessary when FDA information blocking enforcement intensity shifts, EU AI Act implementation timelines accelerate, or cloud compute pricing volatility exceeds historical bands. Practitioners should monitor ONC certification queue lengths and FHIR implementation engineer wage inflation for early signals of supply constraint impacts on deployment timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Health Informatics
Global Healthcare Business Intelligence (BI) Market
Health Informatics
Global E-Health Market
Health Informatics
Healthcare Operational Analytics Market
Health Informatics
Vocal Biomarkers Market
Health Informatics
USA Electronic Health Records (EHR) Market
Health Informatics
Global Consumer Genomics Market
Health Informatics
Healthcare Electronic Data Interchange (EDI) Market
Health Informatics
Ambulatory Electronic Health Record Market
Health Informatics
Healthcare BI Market
Health Informatics
Global Non Clinical Information System Market
Health Informatics
Healthcare Laboratory Informatics Market
Health Informatics
Asia Pacific Healthcare Analytics Market
Health Informatics
Healthcare Application Programming Interfaces Market
Health Informatics
High Acuity Information Systems Market
Health Informatics
Global Natural Language Processing (NLP) in Healthcare and Life Sciences Market
Health Informatics
Healthcare Prescriptive Analytics Market