
 Sea Moss Supplements Market | 2026-2036
Sea Moss Supplements Market Size, Share, and Industry Trends Forecast 2026-2036
Sea Moss Supplements Market Insights
Private-label formulation revenue is fragmenting as branded ingredient sourcing becomes a distinct margin pool. Maju Superfoods leverages wildcrafted Atlantic supply chains to sustain premium positioning. TrueSeaMoss anchors direct-to-consumer subscription models. Starwest Botanicals competes through bulk botanical distribution networks that extend into co-manufacturing partnerships.
Sea moss supplements derive from dried and processed Chondrus crispus or Gracilaria species, standardized for carrageenan content and iodine levels typically between 500 to 2,500 micrograms per serving, serving thyroid support and immune function applications. Gummies now command the fastest expansion within product type segmentation as palatability drives repeat purchase behavior. Online retail channels capture disproportionate growth velocity relative to brick-and-mortar health stores. Organic sea moss sourcing carries premium pricing power that standard wildcrafted grades cannot match.
The U.S. FDA's Current Good Manufacturing Practice regulations and the FTC's substantiation requirements for health claims create compliance thresholds that filter smaller entrants. EFSA's novel food assessments in Europe impose additional safety documentation burdens on Atlantic-sourced imports. Stakeholders must monitor evolving iodine intake guidance from WHO and national health agencies, as cumulative exposure limits threaten formulation flexibility across multiple supplement categories.
Market Dynamics
Wildcrafted Atlantic supply concentration and FDA labeling rule changes are forcing reformulation investments across the supplement value chain. Iodine intake guidance variability between WHO and national health agencies creates formulation complexity that favors larger manufacturers with regulatory affairs capacity.
Growth Catalysts
- FTC substantiation requirements:Health claim documentation standards from the US regulator are filtering smaller entrants and consolidating shelf space for compliant manufacturers with clinical dossiers.
- Immunity-focused functional foods:Food manufacturers now embed sea moss into positioned wellness products, expanding addressable consumption occasions beyond traditional supplement formats.
- Direct-to-consumer subscription mechanics:Recurring revenue models from online-first brands are compressing customer acquisition costs and improving lifetime value metrics relative to retail distribution.
Market Restraints
- Atlantic wildcrafting dependency:Harvest concentration along Ireland, Jamaica, and St. Lucia coastlines exposes supply to climate-driven biomass variability and seasonal access restrictions.
- Carrageenan content standardization:Polysaccharide potency inconsistency between Gracilaria and Chondrus crispus batches forces expensive reprocessing or grade-down acceptance.
- EFSA novel food assessments:European safety documentation burdens for Atlantic-sourced imports extend market entry timelines by 18-36 months for new suppliers.
Strategic Opportunities
- Organic certification premium capture:USDA Organic and EU Organic sourcing commands pricing power that standard wildcrafted grades cannot match, justifying farmed cultivation investments.
- Gummy format palatability advantage:Taste-masked delivery systems are driving repeat purchase behavior among younger demographic cohorts previously resistant to capsule or powder formats.
- Co-manufacturing partnership expansion:Bulk botanical distributors with established extraction infrastructure can capture margin from branded finished goods producers seeking capacity without capital deployment.
Industry Challenges
- Phycological identification expertise scarcity:Qualified taxonomists capable of distinguishing adulterated or mislabeled seaweed species are concentrated in academic institutions rather than commercial quality control departments.
- Co-packer queue compression:CGMP-certified contract manufacturers with allergen-segregated sea moss handling capacity face booking backlogs that delay new product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sea Moss Supplements Market |
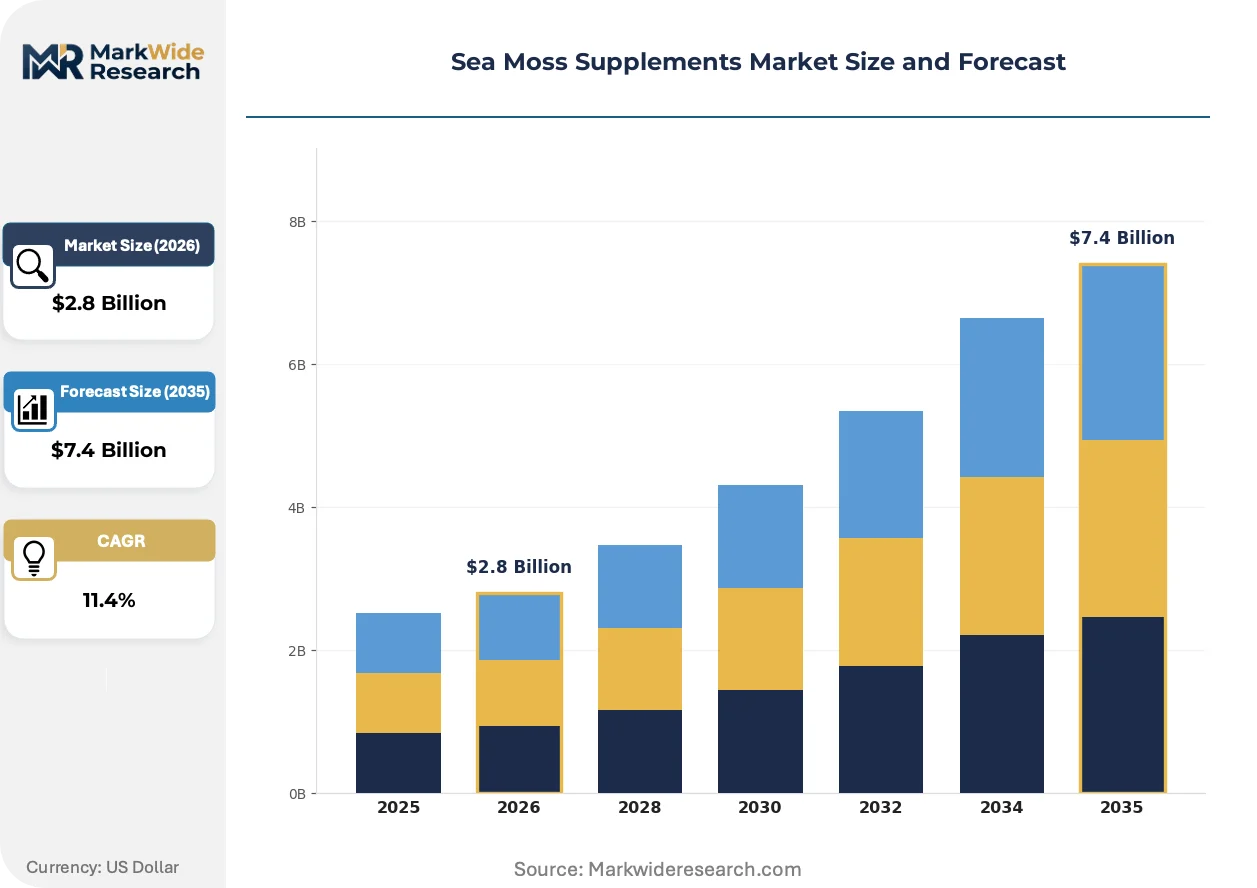
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $7.4 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pills, Powders, Gummies, Capsules Source: Atlantic Sea Moss, Pacific Sea Moss, Organic Sea Moss, Wildcrafted Sea Moss Distribution Channel: Online Retail, Health Stores, Supermarkets, Specialty Shops Packaging Type: Bottles, Pouches, Jars, Sachets |
| Companies Covered | Maju Superfoods, TrueSeaMoss, Starwest Botanicals, VitaRaw, Bloom Nutrition, Power By Naturals, Veganlifemoss, GlassWing Organics, Vital Proteins, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sea Moss Supplements Market Trends and Innovations
Cold-press extraction and microencapsulation technologies are reshaping bioactive retention and shelf stability expectations. Regulatory divergence between iodine exposure limits is forcing regional formulation customization.
Ultrasound-assisted extraction protocols are rendering obsolete traditional heat-degraded processing methods that compromised fucoidan and carrageenan molecular integrity. Premium supplement brands in North American wellness retail are adopting these systems at pilot scale. The technology is rendering obsolete legacy sun-drying infrastructure that dominated Jamaican and Irish processing clusters for decades.
EFSA's evolving novel food safety assessments are extending documentation requirements for Atlantic-sourced Chondrus crispus imports into European markets. Manufacturers must now submit comprehensive toxicological dossiers including cumulative iodine exposure modeling. Small and mid-sized exporters without dedicated regulatory affairs functions are withdrawing from EU market development rather than absorbing compliance costs.
Subscription-based replenishment models are compressing traditional retail replenishment cycles and disintermediating brick-and-mortar health store distribution. Direct-to-consumer brands now capture disproportionate growth velocity relative to established supplement retail channels. This behavioral shift is most visible in US metropolitan wellness consumer segments where convenience and personalization outweigh immediate product access.
Sea Moss Supplements Market Segmentation
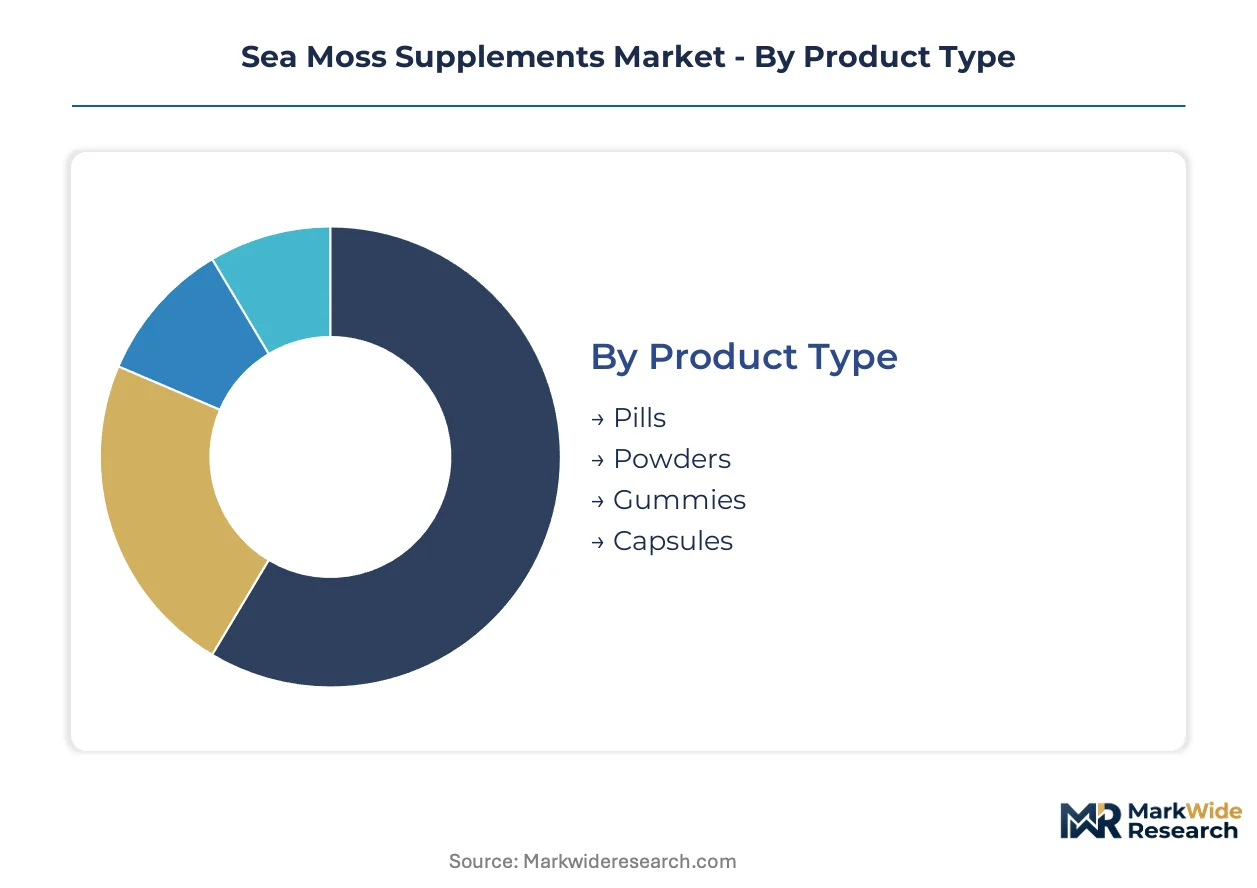
Sea moss supplement manufacturers face divergent technical requirements across delivery formats and sourcing grades. Each segmentation dimension carries distinct margin profiles, regulatory exposure, and supply chain configuration demands that shape competitive positioning.
Product Type:
Delivery format determines bioactive retention, dosing precision, and consumer compliance rates across demographic cohorts.
- Gummies:Palatability-engineered matrices mask iodine bitterness and marine aftertaste, driving repeat purchase frequency among consumers aged 25-40 previously resistant to traditional supplement formats. Demand concentrates in US direct-to-consumer subscription channels where convenience outweighs per-serving cost premiums.
- Powders:Unflavored and flavored variants offer dose flexibility for functional food integration and smoothie customization, serving the athletic performance and wellness lifestyle segments. Procurement is shifting toward bulk canister formats in North American wellness retail as consumers prioritize cost-per-serving efficiency over single-use convenience.
- Capsules:Standardized carrageenan content and iodine dosing meet clinical trial protocols and practitioner recommendation requirements.
- Pills:Compressed tablet formats compete on shelf stability and transportation density for international distribution.
Capsules command the established base. The steepest expansion runs through gummies.
Source:
Provenance certification tiers separate premium positioning from commodity substitution risk.
- Organic Sea Moss:USDA Organic and EU Organic cultivation protocols command pricing power that standard wildcrafted grades cannot match, justifying controlled-environment farmed production investments in St. Lucia and Irish coastal zones. EFSA novel food assessments impose documentation burdens that filter smaller Atlantic harvesters from European market entry.
- Wildcrafted Sea Moss:Atlantic Chondrus crispus harvested from Ireland, Jamaica, and St. Lucia coastlines carries terroir marketing value and traditional use credibility. Climate-driven biomass variability and seasonal access restrictions expose supply security to disruption.
- Atlantic Sea Moss:Irish Moss (Chondrus crispus) dominates North American premium positioning with established carrageenan standardization protocols.
- Pacific Sea Moss:Gracilaria species from Southeast Asian cultivation operations offer volume scalability at lower iodine concentration profiles.
Wildcrafted Atlantic supply anchors premium tier credibility. Organic certification gains share fastest as farmed cultivation scales.
Distribution Channel:
Channel selection determines customer acquisition economics and brand control intensity.
- Online Retail:Direct-to-consumer subscription mechanics compress customer acquisition costs and improve lifetime value metrics relative to retail distribution, with US metropolitan wellness segments showing strongest behavioral shift toward convenience and personalization.
- Health Stores:Practitioner recommendation networks and in-store education staff drive high-consideration purchases for thyroid support applications.
- Supermarkets:Mass-market placement requires price compression and simplified messaging that sacrifices iodine potency claims.
- Specialty Shops:Caribbean and Irish heritage retail channels sustain ethnic community demand for traditional preparation formats.
Health stores retain the established practitioner-recommended base. Online retail climbs the fastest as subscription models disintermediate brick-and-mortar.
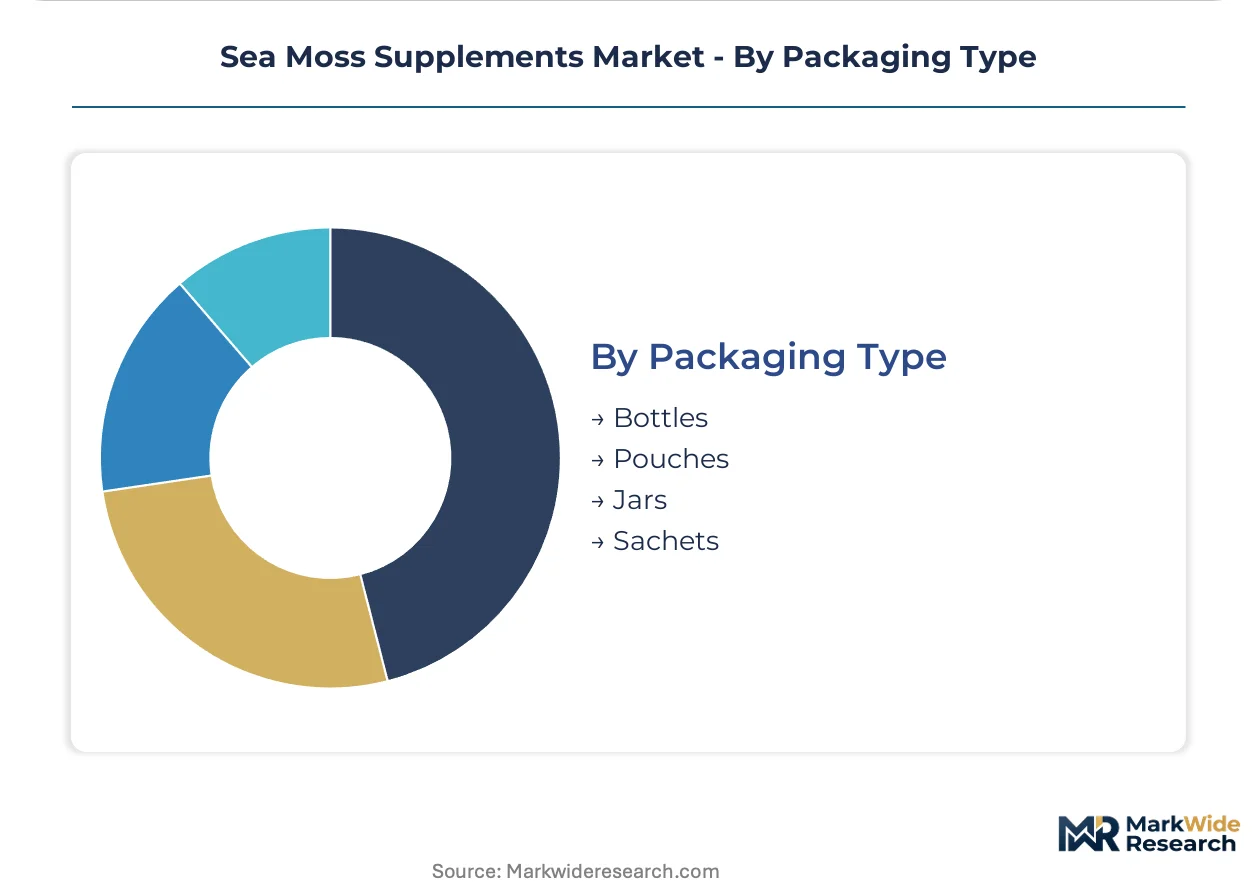
Packaging Type:
Primary packaging selection reflects moisture sensitivity, shelf-life requirements, and sustainability positioning tradeoffs.
- Bottles:Amber glass and opaque PET formats protect carrageenan and fucoidan integrity from UV degradation, dominating premium capsule and pill presentations.
- Pouches:Flexible stand-up formats reduce shipping cube and material cost for powder bulk offerings.
- Jars:Wide-mouth glass containers serve gummy formats requiring scoop or hand access without compression damage.
- Sachets:Single-serve foil laminates enable sampling programs and travel-format premium positioning.
Bottles sustain the established premium positioning base. Pouches gain share fastest as direct-to-consumer brands optimize logistics economics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply between North American direct-to-consumer subscription markets and European practitioner-recommended channels, with Asian markets still favoring traditional dried formats over processed supplements.
United States
Direct-to-consumer subscription models capture the fastest growth velocity among metropolitan wellness consumers aged 25-40. The FDA's evolving dietary supplement labeling requirements under 21 CFR Part 101 reshape product positioning and health claim substantiation. Brooklyn and Los Angeles anchor the brand incubator ecosystem, with cold-press extraction pilot facilities displacing legacy sun-drying infrastructure.
Germany
Practitioner recommendation networks drive high-consideration thyroid support purchases through apothecary and health store channels. EFSA novel food assessments impose 18-36 month documentation timelines on Atlantic-sourced Chondrus crispus imports. Hamburg and Berlin concentrate the regulatory affairs capacity that filters smaller exporters from European market entry.
United Kingdom
Heritage Irish Moss consumption sustains ethnic Caribbean and Irish community demand alongside emerging wellness adoption. The Food Standards Agency enforces cumulative iodine exposure modeling that complicates multi-supplement formulations. London and Manchester host the co-manufacturing partnerships linking bulk botanical distributors to branded finished goods producers.
Canada
Health Canada Natural and Non-prescription Health Products Directorate (NNHPD) licensing requirements create compliance thresholds favoring established manufacturers with clinical dossiers. Toronto and Vancouver wellness retail channels show accelerating subscription model penetration that disintermediates traditional health store distribution.
Jamaica
Wildcrafted Atlantic supply concentration along St. Lucia and Jamaican coastlines exposes premium tier credibility to climate-driven biomass variability. Seasonal access restrictions and traditional harvest rights create supply security challenges for North American brands sourcing terroir-marketed ingredients. Kingston processing clusters face technology displacement from ultrasound-assisted extraction adoption.
Sea Moss Supplements Market Competitive Landscape
Capability concentration sits with premium-tier wildcrafting specialists; scale advantage sits with bulk botanical distributors and direct-to-consumer platforms. The vendor base stratifies across three archetypes: Atlantic supply chain controllers, subscription mechanics innovators, and co-manufacturing infrastructure operators. Dominant competitive moves include backward integration into controlled-environment farmed cultivation and strategic partnerships with CGMP-certified contract manufacturers.
Within the wildcrafted premium tier, Maju Superfoods exemplifies Atlantic supply chain anchoring, while TrueSeaMoss occupies the direct-to-consumer subscription mechanics position. Starwest Botanicals represents the bulk botanical distribution archetype with co-manufacturing partnership extension.
| Leading Market Players |
|---|
| Maju Superfoods |
| TrueSeaMoss |
| Starwest Botanicals |
| VitaRaw |
| Bloom Nutrition |
| Power By Naturals |
| Veganlifemoss |
| GlassWing Organics |
| Vital Proteins |
| Others |
Pricing and Supply Chain Analysis
Undercapacity in CGMP-certified contract manufacturing with allergen-segregated sea moss handling is squeezing new product launch timelines and concentrating pricing power with established suppliers who secured queue priority. This utilization imbalance feeds directly into procurement behavior, as brands absorb premium slotting fees or accept extended lead times rather than forfeit shelf positioning.
Pricing Analysis
Long-term offtake agreements with Atlantic wildcrafting cooperatives in Ireland and Jamaica anchor supply security for premium-tier brands, while spot purchasing dominates Pacific Gracilaria sourcing. Three-tier pricing structure across organic certified, wildcrafted Atlantic, and farmed Pacific grades separates USDA Organic positioning from standard wildcrafted credibility. Cost compression in the Pacific farmed tier is intensifying because cultivation scale in Indonesia and Vietnam outpaces iodine standardization infrastructure. Direct-to-consumer subscription buyers show lowest price sensitivity; supermarket mass-market placement demands greatest cost efficiency.
Supply Chain Analysis
Extended payment terms from bulk botanical distributors to Caribbean harvesting cooperatives are straining working capital at the extraction tier and accelerating consolidation toward vertically integrated processors. Raw material sourcing draws from Ireland, Jamaica, and St. Lucia for Atlantic Chondrus crispus; Indonesia and Vietnam for Pacific Gracilaria cultivation. Single-source vulnerability concentrates in seasonal wildcrafting windows along Irish coastlines disrupted by climate-driven biomass variability. Distribution runs through direct-to-consumer subscription platforms, health store practitioner networks, and co-manufacturing partnerships with branded finished goods producers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward direct-to-consumer subscription platforms that compress traditional retail replenishment cycles, as platform consolidation among wellness-focused e-commerce operators reduces supplier negotiation leverage.
For Market Incumbents: Build regulatory affairs capacity as a moat against EFSA novel food documentation burdens and FDA CGMP compliance thresholds that filter smaller competitors. Secure backward integration into controlled-environment organic cultivation in St. Lucia and Irish coastal zones to reduce climate-driven supply disruption exposure. Expand co-manufacturing partnership networks to capture margin from capacity-constrained brands seeking queue priority. For New Entrants and Emerging Players: Mid-market gummy format positioning in US metropolitan wellness segments represents the most penetrable entry point, as taste-masked delivery systems drive repeat purchase frequency among consumers aged 25-40 previously resistant to capsule formats. Pacific Gracilaria sourcing with lower iodine concentration profiles offers formulation flexibility absent from Atlantic supply chains. Launch through subscription-first mechanics with personalized dosing protocols to compress customer acquisition costs against established retail distribution. For Investors and Strategic Acquirers: Long-term, this sits as a certification-premium play because organic and wildcrafted Atlantic supply scarcity will sustain pricing power as farmed cultivation scales. Target acquisition profiles center on CGMP-certified contract manufacturers with allergen-segregated handling capacity and established Atlantic supply chain relationships. Monitor EFSA novel food approval timelines for Atlantic-sourced Chondrus crispus as inflection indicator for European market entry feasibility.| Strategic Initiative | Industry Significance |
|---|---|
| Organic Certification Investment | USDA Organic and EU Organic protocols command pricing premiums that justify controlled-environment farmed cultivation capital deployment. |
| Cold-Press Extraction Adoption | Ultrasound-assisted protocols displace legacy sun-drying infrastructure in Jamaican and Irish processing clusters. |
| Direct-to-Consumer Subscription Launch | Recurring revenue mechanics compress customer acquisition costs and improve lifetime value metrics relative to retail distribution. |
| Co-Manufacturing Partnership Expansion | Bulk botanical distributors with extraction infrastructure capture margin from capacity-constrained branded finished goods producers. |
| Regulatory Affairs Capacity Buildout | Dedicated EFSA and FDA compliance functions filter smaller entrants and consolidate shelf space for compliant manufacturers. |
Research Methodology
Desk research of customs import records, FDA warning letter databases, and EFSA novel food submission registries preceded structured interviews with supplement brand founders, CGMP contract manufacturing operations managers, Atlantic wildcrafting cooperative leaders, and health store category buyers. Primary fieldwork validated iodine standardization protocols, carrageenan content testing methodologies, and subscription mechanics economics against secondary trade flow data and regulatory filing documentation. Bottom-up segmentation modeling triangulated against top-down market sizing from channel revenue disclosures.
Assumptions held fixed include current FDA dietary supplement labeling requirements under 21 CFR Part 101 and EFSA novel food assessment timelines; variables tested include iodine intake guidance divergence between WHO and national health agencies, climate-driven biomass variability in Atlantic harvesting zones, and subscription model penetration rates across metropolitan wellness segments. Volume and value outputs across the analysis window reflect segmentation by product type, sourcing grade, and distribution channel, with CAGRs derived from cohort-based adoption curve modeling and price elasticity estimates for gummy versus capsule formats.
Practitioners should monitor EFSA novel food approval velocity for Atlantic-sourced imports and FDA enforcement patterns on iodine health claim substantiation for early signals of regulatory constraint tightening. Forecasts reflect documented assumptions on subscription model retention rates and wildcrafted supply security. Macroeconomic recession impacts on discretionary wellness spending, regulatory deviation on cumulative iodine exposure limits, or technological disruption in ultrasound-assisted extraction scale-up would prompt forecast revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
Middle East and Africa Collagen Supplements Market
Nutritional Supplements
Asia-Pacific Arachidonic Acid Market
Nutritional Supplements
Australia Collagen Peptides Market
Nutritional Supplements
Ready-To-Use Therapeutic Food Market
Nutritional Supplements
Multi Nutritional Supplement Market
Nutritional Supplements
Digestive Health Supplements Market
Nutritional Supplements
Psyllium-Based Supplement Market
Nutritional Supplements
Choline Bitartrate Market
Nutritional Supplements
Whey Basic Protein Isolates Market
Nutritional Supplements
GLP-1 Hydration Product Market
Nutritional Supplements
Marine Collagen Market
Nutritional Supplements
Nutrition Powder Market
Nutritional Supplements
Apo-8 Carotenal Market
Nutritional Supplements
Global Adaptogens Market
Nutritional Supplements
South America Dietary Supplement Market
Nutritional Supplements
Vitamin B12 Market