
 Concentrate Protein Market | 2026-2036
Concentrate Protein Market Size, Share, and Industry Trends Forecast 2026-2036
Concentrate Protein Market Analysis
Ingredient formulation services is fragmenting across specialized dairy processors and plant-extraction houses. Cargill Inc. leverages its oilseed processing footprint to anchor soy concentrate supply in North America. Fonterra Co-operative Group Limited dominates whey protein concentrate output through New Zealand's integrated dairy cooperative structure. Glanbia plc specializes in sports nutrition ingredient systems, extending its reach from commodity powders to finished premix solutions.
Concentrate protein denotes protein ingredients with partial purification, typically retaining 35–80% protein content alongside residual fats, carbohydrates, and minerals through ultrafiltration or acid precipitation processes. These ingredients serve as cost-effective functional building blocks for food fortification and texture modification. Whey concentrate maintains the largest volume position in dairy-origin systems, while pea concentrate accelerates within plant-based formulations as beverage manufacturers seek neutral-flavor protein with lower allergenicity profiles. Powder form commands the dominant share in bulk ingredient logistics, though liquid concentrates gain traction in ready-to-drink manufacturing lines for operational efficiency.
FDA nutrition labeling requirements and EFSA health claims regulations determine permissible protein content declarations and structure-function statements in the United States and European Union. China's National Health Commission establishes novel food ingredient approval pathways for emerging protein sources including insect and microbial concentrates. Stakeholders must monitor evolving amino acid scoring methodologies and carbon accounting standards that will reshape procurement criteria and supplier qualification protocols.
Market Dynamics
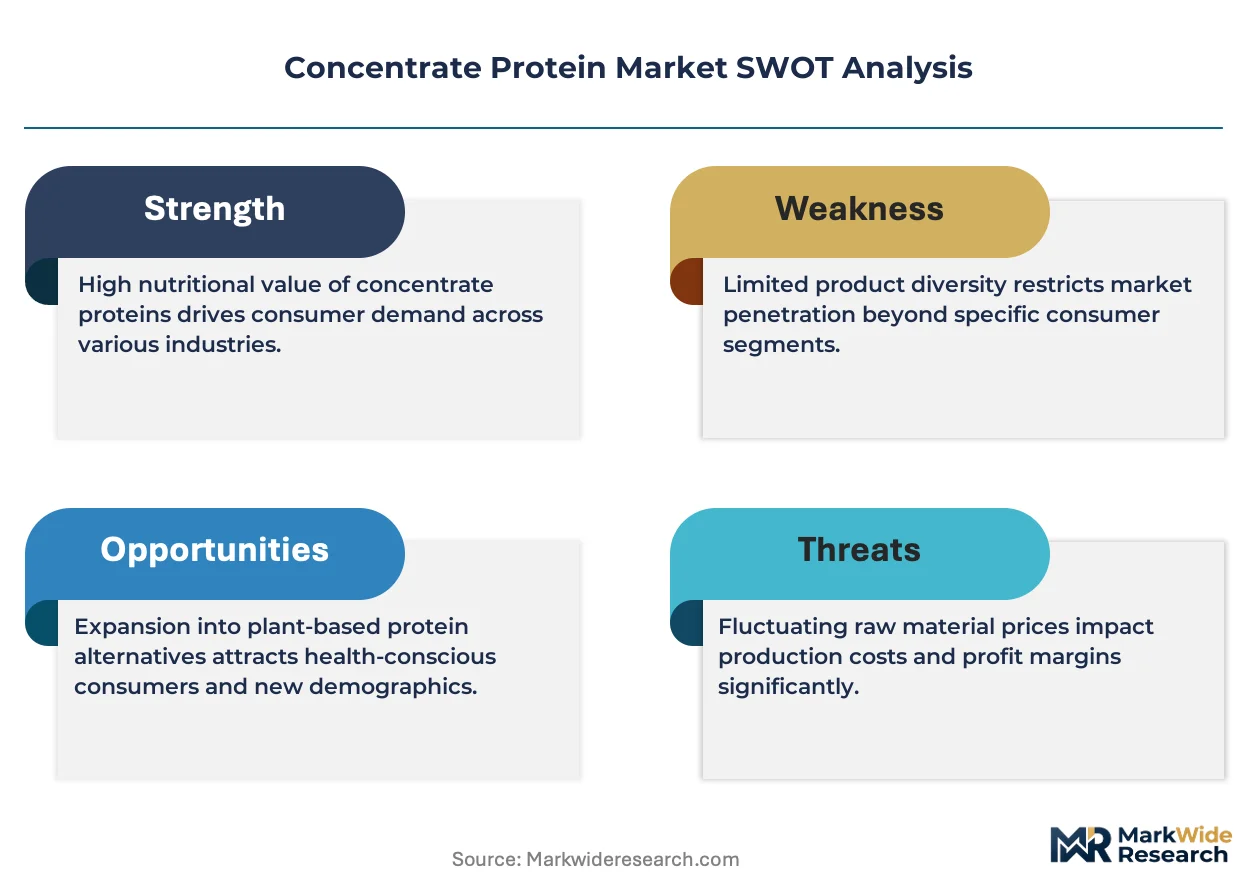
Sports nutrition brands now consolidate procurement volumes around functional ingredient systems, compressing supplier margins while elevating technical service requirements across whey and plant concentrate categories.
Growth Catalysts
- EFSA health claims framework:Permissible structure-function statements for muscle maintenance and satiety drive reformulation toward protein concentrates with validated amino acid profiles in European sports and senior nutrition applications.
- Pea protein extraction advances:Membrane filtration improvements reduce off-flavor compounds in plant concentrates, enabling beverage manufacturers to substitute dairy-origin ingredients in ready-to-drink formulations.
- China's novel food pathways:National Health Commission approval mechanisms for microbial and insect proteins accelerate domestic sourcing alternatives to imported whey concentrates.
Market Restraints
- Whey powder input volatility:New Zealand and EU dairy commodity pricing cycles transmit directly to concentrate protein cost structures, compressing blender margins during trough periods.
- Allergen labeling stringency:FDA Food Allergen Labeling and Consumer Protection Act requirements force dedicated production lines for dairy-origin concentrates, raising capital intensity for multi-ingredient processors.
- Precision fermentation proteins:Microbial biomass alternatives with complete amino acid profiles threaten mid-tier concentrate positioning in premium sports nutrition segments.
Strategic Opportunities
- India FSSAI fortification mandates:School meal and mid-day nutrition programs create institutional procurement channels for cost-effective soy and milk protein concentrates.
- Cell-cultured hybrid formulations:Blending traditional concentrates with novel proteins enables clean-label positioning while managing unit economics in premium meat alternatives.
- Direct-to-manufacturer platforms:Digital ingredient marketplaces reduce distributor layers, allowing regional dairies and extraction houses to capture margin previously allocated to traders.
Industry Challenges
- Downstream integration demands:Finished goods brands now require premix development, flavor masking, and application testing services that stretch processor technical capabilities beyond commodity production.
- Carbon accounting verification:Scope 3 emissions documentation for dairy and oilseed supply chains demands farm-level data partnerships that most concentrate suppliers have not constructed.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Concentrate Protein Market |
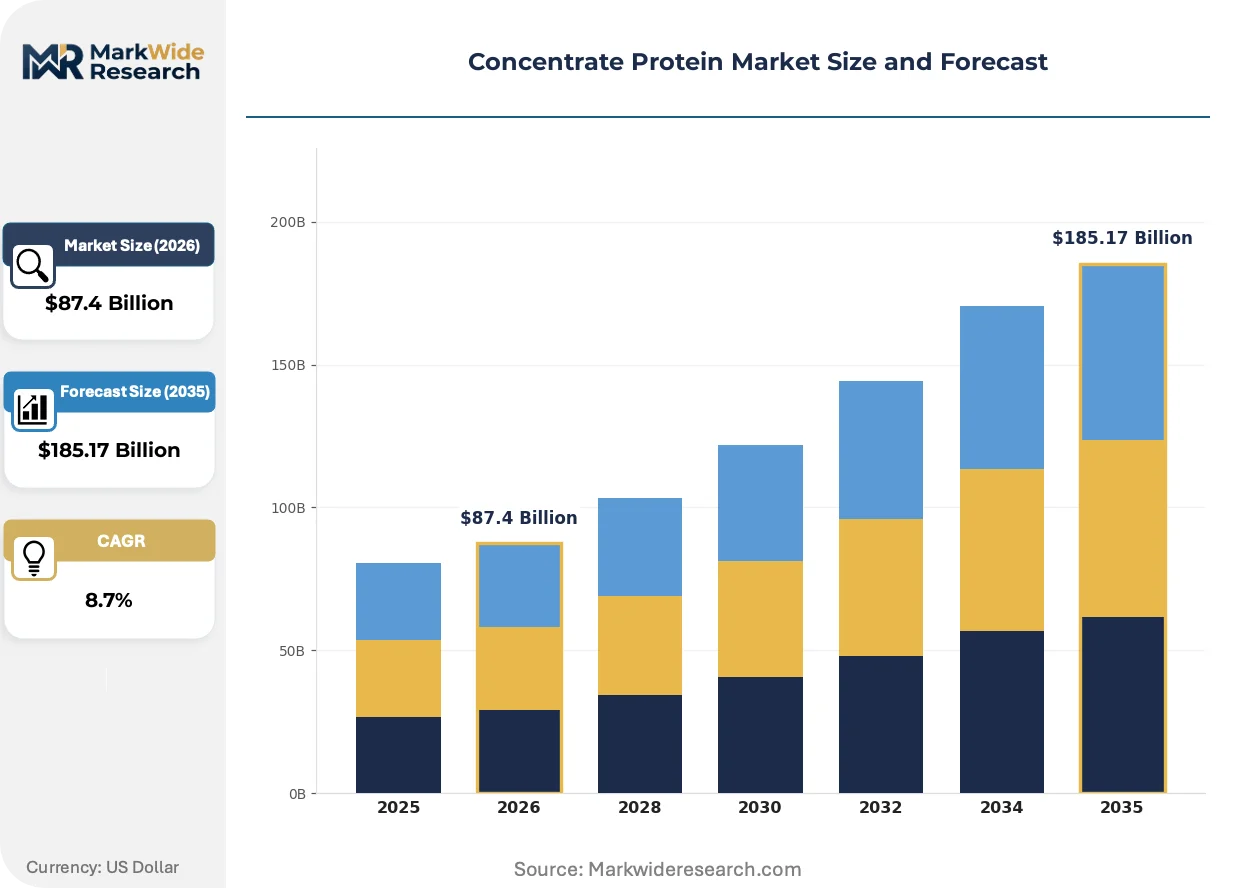
| Market Size in 2026 | $87.4 Billion |
| Market Size in 2035 | $185.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Whey, Soy, Pea, Casein End User: Sports Nutrition, Functional Foods, Beverages, Bakery Form: Powder, Liquid, Granulated, Concentrated Origin: Dairy, Plant-based, Animal, Others |
| Companies Covered | Archer Daniels Midland Company, Cargill Inc., Glanbia plc, Fonterra Co-operative Group Limited, Arla Foods Ingredients Group P/S, Kerry Group, Ingredion Incorporated, Wilmar International Ltd., Morinaga Milk Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Concentrate Protein Market Emerging Trajectories
Digital formulation platforms and precision processing technologies are compressing development cycles while regulatory authorities on three continents simultaneously tighten compositional and labeling standards for protein ingredients.
Membrane filtration is virtualizing traditional separation infrastructure. Advanced ceramic and polymeric membranes enable continuous processing with smaller physical footprints than batch centrifugation systems. Mid-sized dairy processors in Germany and the Netherlands adopt these units to serve regional sports nutrition brands with customized protein fractions. This technology is virtualizing capital requirements for entry into concentrate production, lowering barriers for specialized regional players.
China's GB standards for protein content determination and novel food safety assessments are tightening import requirements for concentrate ingredients. SAMR enforcement of these standards forces foreign suppliers to establish domestic testing partnerships or joint venture manufacturing. Whey concentrate exporters to China now face extended registration timelines and batch-level certification obligations that reshape inventory planning and working capital structures.
Brand procurement teams now consolidate supplier relationships around full-service ingredient partners capable of co-development and regulatory dossier preparation. Traditional commodity traders lose share to technical service-oriented processors in United States and German markets. This concentration of buying power toward integrated suppliers is most visible in ready-to-drink beverage manufacturing, where formulation complexity and speed-to-market requirements favor partners with in-house application laboratories.
Concentrate Protein Market Segmentation
Concentrate protein procurement patterns diverge sharply across application requirements, with sports nutrition demanding validated amino acid profiles while functional foods prioritize cost-efficient fortification. Formulation complexity and regulatory compliance costs create distinct competitive arenas within each segment boundary.
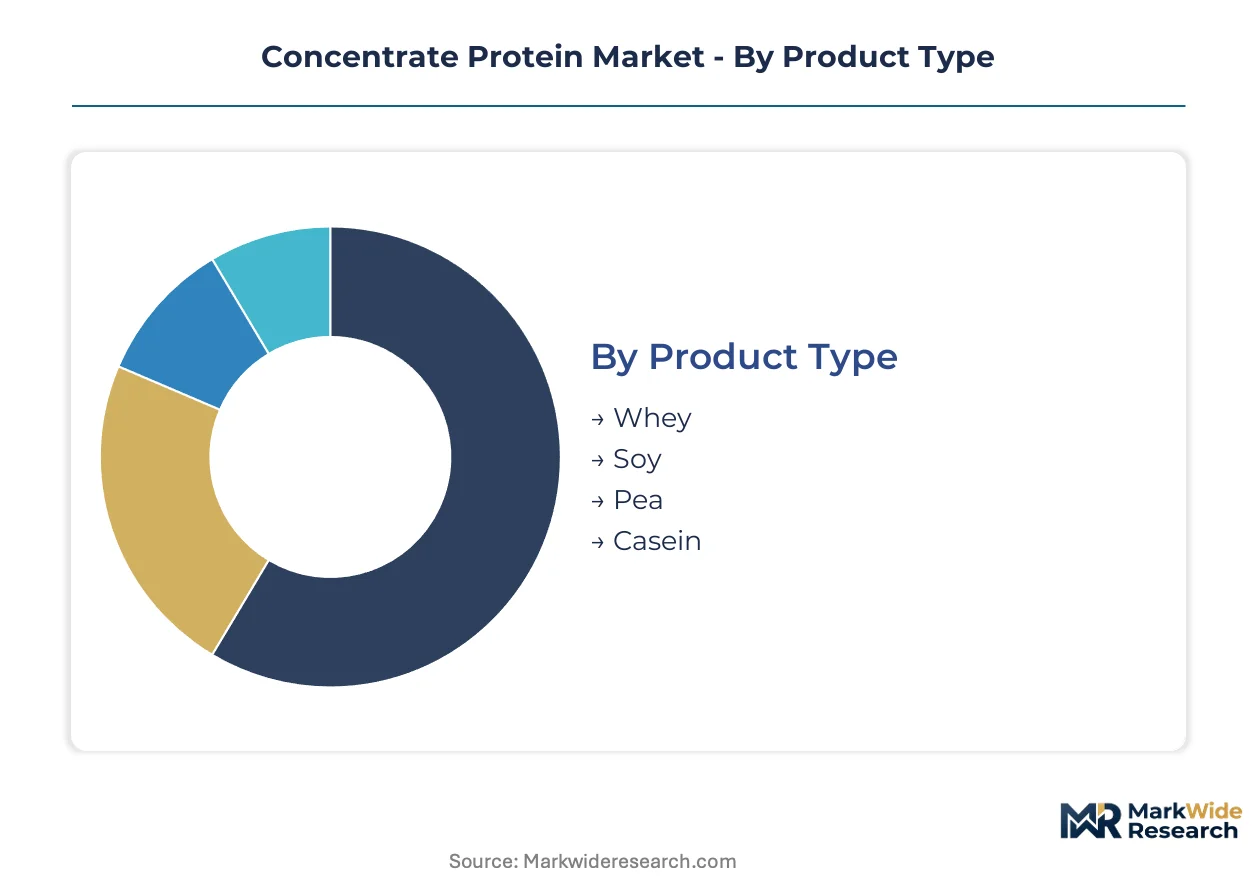
Product Type:
Use-case spectrum spans rapid-absorption athletic recovery through sustained-release senior nutrition, with each protein source occupying distinct functional niches.
- Whey:Retains 35–80% protein content alongside lactose and milk fats through ultrafiltration, delivering rapid amino acid availability. Demand concentrates in United States sports nutrition applications where FDA label claims for muscle protein synthesis drive specification requirements.
- Pea:Yellow split pea extraction yields concentrates with improved solubility and reduced off-flavor profiles through membrane filtration advances. Beverage manufacturers in Germany substitute pea for dairy concentrates to meet EFSA allergen labeling preferences and clean-label positioning.
- Soy:Oilseed processing byproduct with established supply infrastructure and cost advantages in bulk fortification.
- Casein:Slow-digesting micellar structure supports overnight recovery and medical nutrition applications.
The dominant share belongs to Whey, while Pea is closing the gap fastest.
End User:
Customer procurement maturity varies from commodity spot-buying in bakery to technical partnership models in sports nutrition.
- Sports Nutrition:Brands consolidate volumes around full-service ingredient partners demanding premix development, flavor masking, and regulatory dossier preparation. Technical service requirements compress supplier margins while elevating entry barriers in United States and German markets.
- Functional Foods:Cereal and snack manufacturers prioritize cost-efficient fortification with established dairy concentrates. India's FSSAI school meal mandates create institutional procurement channels for soy and milk protein concentrates.
- Beverages:Ready-to-drink manufacturing lines favor liquid concentrate formats for operational efficiency.
- Bakery:Texture modification and shelf-life extension drive specification requirements.
Sports Nutrition commands procurement volume leadership, though Functional Foods is expanding most quickly through fortification mandates.
Form:
Supply chain configuration determines format selection, with bulk logistics favoring powder and manufacturing efficiency driving liquid adoption.
- Powder:Dominates bulk ingredient logistics with extended shelf stability and reduced transportation costs. Regional dairies and extraction houses capture margin through direct-to-manufacturer digital platforms.
- Liquid:Concentrated protein solutions integrate directly into ready-to-drink manufacturing lines, eliminating reconstitution steps. China's SAMR batch-level certification obligations reshape inventory planning for imported liquid concentrates.
- Granulated:Improved flow properties support automated dosing in high-speed food processing.
- Concentrated:Reduced water content formats optimize shipping economics for remote manufacturing locations.
Powder retains volume dominance, though Liquid is gaining share fastest in beverage manufacturing.
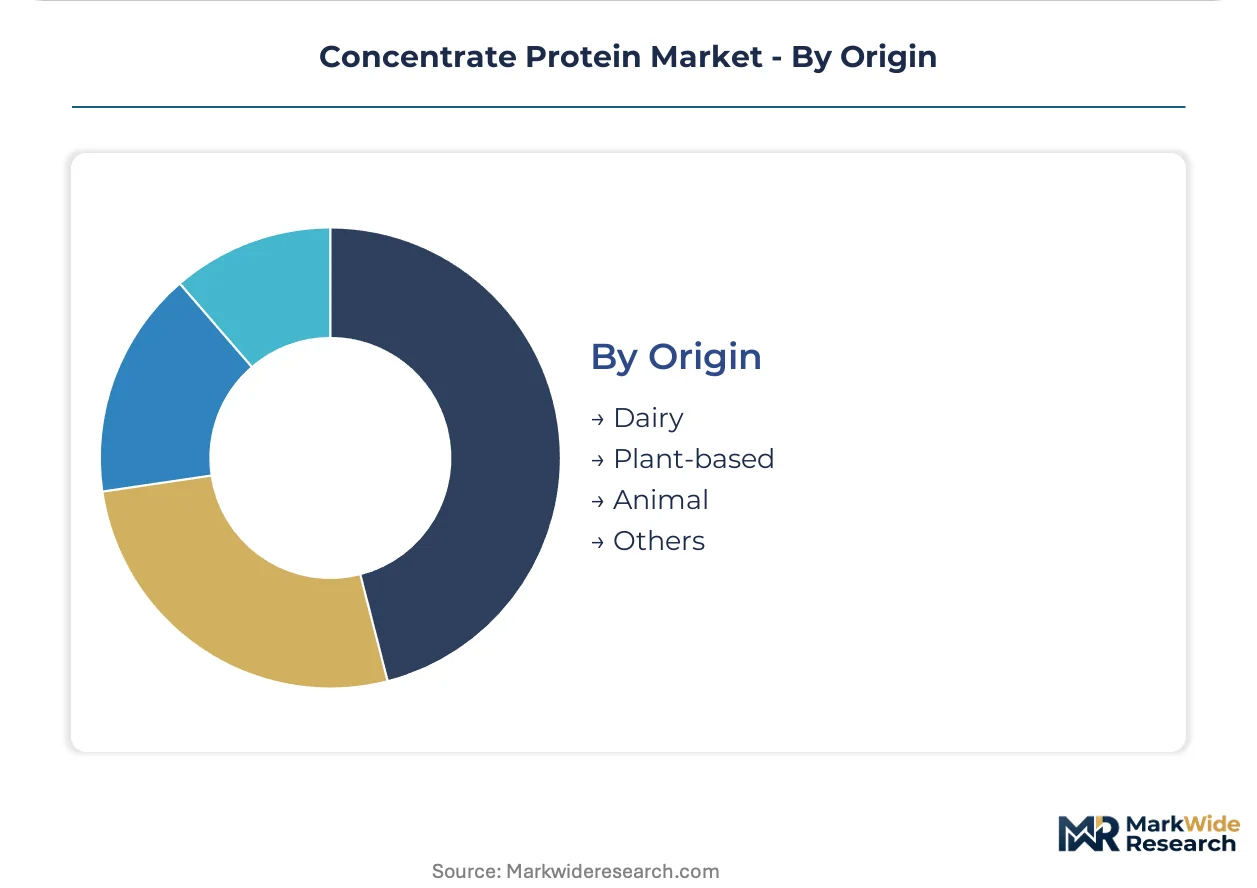
Origin:
Carbon accounting verification and Scope 3 documentation requirements are reshaping supplier qualification protocols across source categories.
- Dairy:Whey and casein concentrates from New Zealand and EU supply chains face commodity pricing volatility that transmits directly to cost structures. Farm-level data partnerships remain underdeveloped for most concentrate suppliers.
- Plant-based:Pea and soy extraction houses leverage oilseed processing infrastructure with lower capital intensity than dairy systems. Cargill anchors North American soy concentrate supply through existing crushing footprint.
- Animal:Egg and collagen concentrates serve specialized medical and beauty nutrition segments.
- Others:Insect and microbial proteins advance through China's National Health Commission novel food approval pathways.
Dairy maintains established volume leadership, while Plant-based is climbing the fastest amid carbon accounting pressures and allergen labeling preferences.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Germany and China demonstrate the highest price elasticity for concentrate protein, while United States sports nutrition brands absorb premium pricing for validated amino acid profiles. Regulatory compliance costs in China and the European Union compress margins for imported concentrates. Supply chain localization pressures are reshaping procurement geography across all major demand centers.
United States
FDA nutrition labeling requirements for muscle protein synthesis claims drive specification standards for whey concentrate in sports nutrition applications. The Food Allergen Labeling and Consumer Protection Act mandates dedicated production lines for dairy-origin ingredients, raising capital intensity for multi-ingredient processors. Greater Chicago and Wisconsin dairy corridors host specialized ultrafiltration operations serving ready-to-drink beverage manufacturers with customized protein fractions.
Germany
EFSA health claims framework for muscle maintenance and satiety accelerates reformulation toward concentrates with validated amino acid profiles in senior nutrition applications. EFSA allergen labeling preferences push beverage manufacturers toward pea concentrate substitution for dairy-origin ingredients. North Rhine-Westphalia membrane filtration specialists serve regional sports nutrition brands with continuous processing systems that compress development cycles.
China
National Health Commission novel food approval pathways for microbial and insect proteins accelerate domestic sourcing alternatives to imported whey concentrates. SAMR enforcement of GB standards for protein content determination forces foreign suppliers to establish domestic testing partnerships or joint venture manufacturing. Yangtze River Delta processing clusters face extended registration timelines and batch-level certification obligations that reshape inventory planning structures.
India
FSSAI fortification mandates for school meal and mid-day nutrition programs create institutional procurement channels for cost-effective soy and milk protein concentrates. The country's national food safety regulator establishes compositional standards that favor regional dairy cooperatives over imported concentrates. Maharashtra and Gujarat oilseed processing infrastructure anchors domestic soy concentrate supply for bulk fortification applications.
New Zealand
Fonterra's integrated dairy cooperative structure dominates whey protein concentrate output through farm-to-ingredient vertical control. Dairy commodity pricing cycles transmit directly to global concentrate cost structures, compressing blender margins during trough periods. Canterbury and Waikato processing regions maintain volume leadership in dairy-origin concentrate exports despite carbon accounting verification pressures on Scope 3 emissions documentation.
Concentrate Protein Market Vendor Landscape
Integrated dairy cooperatives and diversified agribusiness conglomerates split the market between captive supply security and portfolio breadth. Supplier consolidation is concentrating procurement volumes around technical service partners capable of premix development and regulatory dossier preparation. Three archetypes dominate: New Zealand dairy cooperatives with farm-level integration, North American oilseed processors leveraging crushing infrastructure, and European specialists in sports nutrition ingredient systems. Competitive dynamics center on backward integration into membrane filtration capacity and geographic expansion through joint venture manufacturing in China.
Within the integrated cooperative tier, Fonterra Co-operative Group Limited and Arla Foods Ingredients Group P/S exemplify farm-to-ingredient control structures that anchor supply security for global sports nutrition brands. Among diversified agribusiness operators, Cargill Inc. and Archer Daniels Midland Company occupy positions that leverage oilseed processing footprints to serve cost-sensitive fortification markets. Glanbia plc represents the technical service archetype, extending reach from commodity powders toward finished premix solutions that address formulation complexity demands in ready-to-drink manufacturing.
| Leading Market Players |
|---|
| Archer Daniels Midland Company |
| Cargill Inc. |
| Glanbia plc |
| Fonterra Co-operative Group Limited |
| Arla Foods Ingredients Group P/S |
| Kerry Group |
| Ingredion Incorporated |
| Wilmar International Ltd. |
| Morinaga Milk Group |
| Others |
Supply Flow & Price Mechanics
Canterbury and Waikato processing regions anchor global whey concentrate capacity through Fonterra's integrated cooperative structure, transmitting New Zealand dairy commodity cycles directly into downstream pricing power for sports nutrition brands. This geographic concentration creates asymmetric leverage where regional weather events and farm-gate milk pricing immediately reshape blender margins across United States and German markets.
Pricing Analysis
After-sales technical service contracts now drive lifetime value capture as brands demand premix development, flavor masking, and regulatory dossier preparation bundled into long-term supply agreements. Three-tier pricing structure across premium validated-amino-acid concentrates, standard commodity whey, and economy soy isolates reflects certification grade and customization level differentiation. Cost compression in mid-tier whey concentrates is intensifying because precision fermentation proteins threaten positioning with complete amino acid profiles. Functional food manufacturers exhibit highest price sensitivity through spot-buying commodity volumes, while sports nutrition brands absorb premium pricing for EFSA-validated muscle maintenance claims.
Supply Chain Analysis
Upstream skim milk and yellow split pea feedstock availability centers on New Zealand, United States, and Canada dairy corridors plus North American and European oilseed crushing infrastructure. Membrane filtration equipment, ceramic separation modules, and acid precipitation chemicals constitute critical input dependencies. Single-source vulnerability concentrates in Fonterra's farm-to-ingredient vertical control over global whey concentrate exports. Distribution runs through direct-to-manufacturer digital platforms that disintermediate traditional commodity traders, allowing regional dairies and extraction houses to capture margin previously allocated to distributor layers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Precision fermentation proteins with complete amino acid profiles represent the substitution threat incumbents must navigate, requiring defensive repositioning toward technical service differentiation and regulatory dossier capabilities that novel proteins cannot yet replicate.
For Market Incumbents: Insulate market position by deepening backward integration into membrane filtration capacity in Germany and Netherlands regional clusters, securing captive supply security against commodity pricing volatility. Anchor technical service partnerships with sports nutrition brands through in-house application laboratories that deliver premix development and flavor masking capabilities precision fermentation competitors lack. Prioritize EFSA health claims validation investment to maintain premium positioning against microbial biomass alternatives.
For New Entrants and Emerging Players: India's FSSAI-mandated school meal fortification programs represent the most penetrable entry point, creating institutional procurement channels for cost-effective soy and milk protein concentrates underserved by technical service-oriented incumbents. China's Yangtze River Delta processing clusters offer white-space opportunity through joint venture manufacturing partnerships that satisfy SAMR batch-level certification obligations for imported concentrates. Target direct-to-manufacturer digital platform go-to-market angles that bypass entrenched distributor relationships in United States and German markets.
For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because supplier concentration around full-service ingredient partners capable of co-development and carbon accounting verification will compress margins for commodity-only processors. Acquisition target archetype: European membrane filtration specialists with continuous processing technology and existing sports nutrition brand relationships. Watch precision fermentation protein cost curves as the inflection signal—when microbial biomass reaches price parity with mid-tier whey concentrates, traditional processor valuations will face structural repricing pressure.
| Strategic Initiative | Industry Significance |
|---|---|
| Membrane Filtration Capacity Expansion | Advanced ceramic and polymeric systems enable continuous processing with smaller footprints than batch centrifugation. |
| EFSA Health Claims Validation Investment | Permissible structure-function statements for muscle maintenance differentiate premium concentrates in European markets. |
| Joint Venture Manufacturing in China | Domestic production partnerships satisfy SAMR registration timelines and batch-level certification obligations. |
| Carbon Accounting Verification Partnerships | Farm-level data partnerships address Scope 3 emissions documentation demanded by finished goods brands. |
| Direct-to-Manufacturer Digital Platform Launch | Eliminating distributor layers allows regional processors to capture margin previously allocated to traders. |
Methodological Framework
A standing panel of sports nutrition procurement directors, dairy processing plant managers, membrane filtration equipment specialists, and regulatory affairs leads provided ongoing calibration across the analysis window. Primary interviews with ingredient formulation scientists and beverage manufacturing R&D heads combined with secondary validation through FDA nutrition labeling guidance documents, EFSA health claims registers, China's GB standards databases, and Fonterra cooperative financial disclosures. Bottom-up volume modeling across whey, pea, soy, and casein concentrate categories triangulated against top-down macroeconomic indicators and protein consumption trend analysis.
Scenario-bracketing around commodity dairy pricing cycles, precision fermentation protein cost reduction trajectories, and regulatory approval timeline variations shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include protein source origin, end-use application, powder versus liquid format, and geographic regulatory cluster. CAGRs derived from historical volume trajectories adjusted for substitution elasticity parameters and sports nutrition brand consolidation patterns. Industry-specific forecast inputs incorporated membrane filtration technology adoption rates and FSSAI fortification mandate implementation schedules.
Stress conditions across New Zealand drought frequency, Chinese import registration delays, and precision fermentation protein price parity achievement were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding EFSA health claims framework stability and SAMR enforcement consistency. Cross-checking against dairy commodity futures market pricing and sports nutrition brand earnings disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
Bee Pollen Supplements Market
Nutritional Supplements
South America Meal Replacement Products Market
Nutritional Supplements
Nutritional Lipids Market
Nutritional Supplements
Global Hangover Rehydration Supplements Market
Nutritional Supplements
North America Saffron Supplements Market
Nutritional Supplements
Vegan Protein Supplements Market
Nutritional Supplements
Asia Pacific Nutritional Supplements Market
Nutritional Supplements
Elderberry Extract Market
Nutritional Supplements
United States Vitamin D Supplements Market
Nutritional Supplements
Omega-3 Fish Oils Market
Nutritional Supplements
Coral Calcium Supplements Market
Nutritional Supplements
Europe Nutrition and Supplements Market
Nutritional Supplements
Marine Collagen Market
Nutritional Supplements
Global Nutraceutical Market
Nutritional Supplements
Pulse Protein Market
Nutritional Supplements
Fucoidan Market