
 Health Check-Up Market | 2026-2036
Health Check-Up Market Size, Share, and Industry Trends Forecast 2026-2036
Health Check-Up Market Analytics
Artificial intelligence is consolidating into routine pathology workflows, replacing manual slide review with algorithm-assisted diagnostics. Quest Diagnostics leverages its national laboratory network to sustain specimen volume advantages across preventive and diagnostic service lines. Labcorp anchors its position through in-house production of specialized assay platforms, reducing third-party reagent dependency. Sonic Healthcare competes on geographic dominance, operating one of the largest international networks of accredited medical laboratories.
Health check-up services encompass scheduled clinical assessments combining physical examination, biomarker analysis, imaging protocols, and risk-stratified screening to detect pre-symptomatic disease or monitor chronic conditions. These services typically process blood chemistry panels with turnaround targets under 24 hours, serving both individual patients and institutional payers seeking early intervention cost avoidance. Preventive care and diagnostic tests command the deepest margin pools, while telehealth delivery is expanding fastest as asynchronous consultation platforms integrate with home specimen collection kits. Corporate end users represent a concentrated demand segment, with employers contracting annual workforce screening bundles that bundle biometric testing with wellness program incentives.
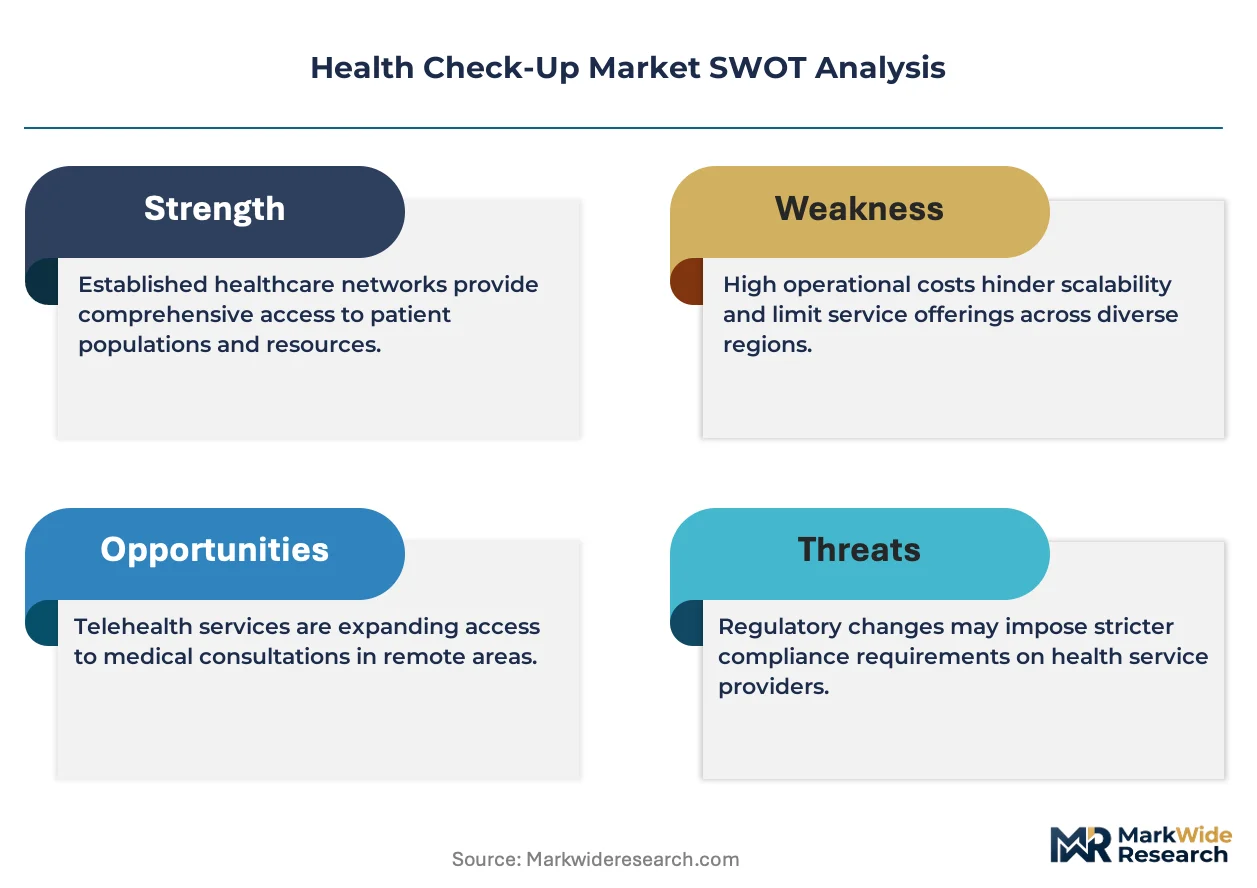
The FDA and Clinical Laboratory Improvement Amendments set analytical performance standards that shape market access for independent laboratories, while HIPAA mandates govern patient data portability across competing service networks. The Centers for Medicare & Medicaid Services reimbursement schedules directly influence which screening panels laboratories prioritize in their service menus. Stakeholders must monitor how evolving FDA guidance on laboratory-developed tests will restructure compliance costs and competitive positioning for regional diagnostic chains.
Market Dynamics
Employer-sponsored preventive screening mandates are compressing service delivery timelines while expanding panel complexity, forcing laboratories to reconfigure specimen processing workflows around 24-hour turnaround guarantees rather than traditional batch scheduling.
Growth Catalysts
- Corporate wellness mandates:Large employers in the United States now contract annual workforce biometric bundles that tie premium discounts to completion rates, institutionalizing recurring revenue streams for diagnostic networks.
- CLIA quality elevation:The FDA's updated Clinical Laboratory Improvement Amendments are disqualifying marginal operators, concentrating accredited volume among laboratories with capitalized quality infrastructure.
- Home specimen collection convergence:Asynchronous telehealth platforms are integrating with dried blood spot and saliva logistics, extending screening access beyond traditional phlebotomy sites.
Market Restraints
- Reagent supply concentration:Specialized assay chemistries depend on concentrated Asian manufacturing of enzyme substrates and monoclonal antibodies, exposing margins to input volatility and customs friction.
- CMS reimbursement compression:The Centers for Medicare & Medicaid Services annual fee schedule updates directly compress panel economics, forcing laboratories to absorb cost inflation or exit low-margin screening categories.
- Laboratory-developed test uncertainty:Evolving FDA guidance on in-house assay validation is extending compliance timelines and legal exposure for regional diagnostic chains without dedicated regulatory affairs functions.
Strategic Opportunities
- Chronic disease monitoring expansion:Diabetes and cardiovascular risk-stratified panels for pre-symptomatic populations remain underpenetrated in employer contracts, creating white space beyond annual wellness baselines.
- AI-assisted pathology workflows:Algorithmic slide review is converging with digital imaging infrastructure, enabling laboratories to process higher specimen volumes without proportional histotechnologist hiring.
- State-level Medicaid expansion:Several US states are extending preventive screening benefits to expanded eligibility populations, opening access channels distinct from commercial employer contracting.
Industry Challenges
- Histotechnologist talent scarcity:Specialized tissue processing and staining expertise faces generational replacement gaps, constraining pathology service expansion regardless of imaging automation.
- Laboratory information system integration:Legacy electronic health record architectures create interoperability friction when connecting new telehealth platforms to established specimen tracking databases.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Health Check-Up Market |
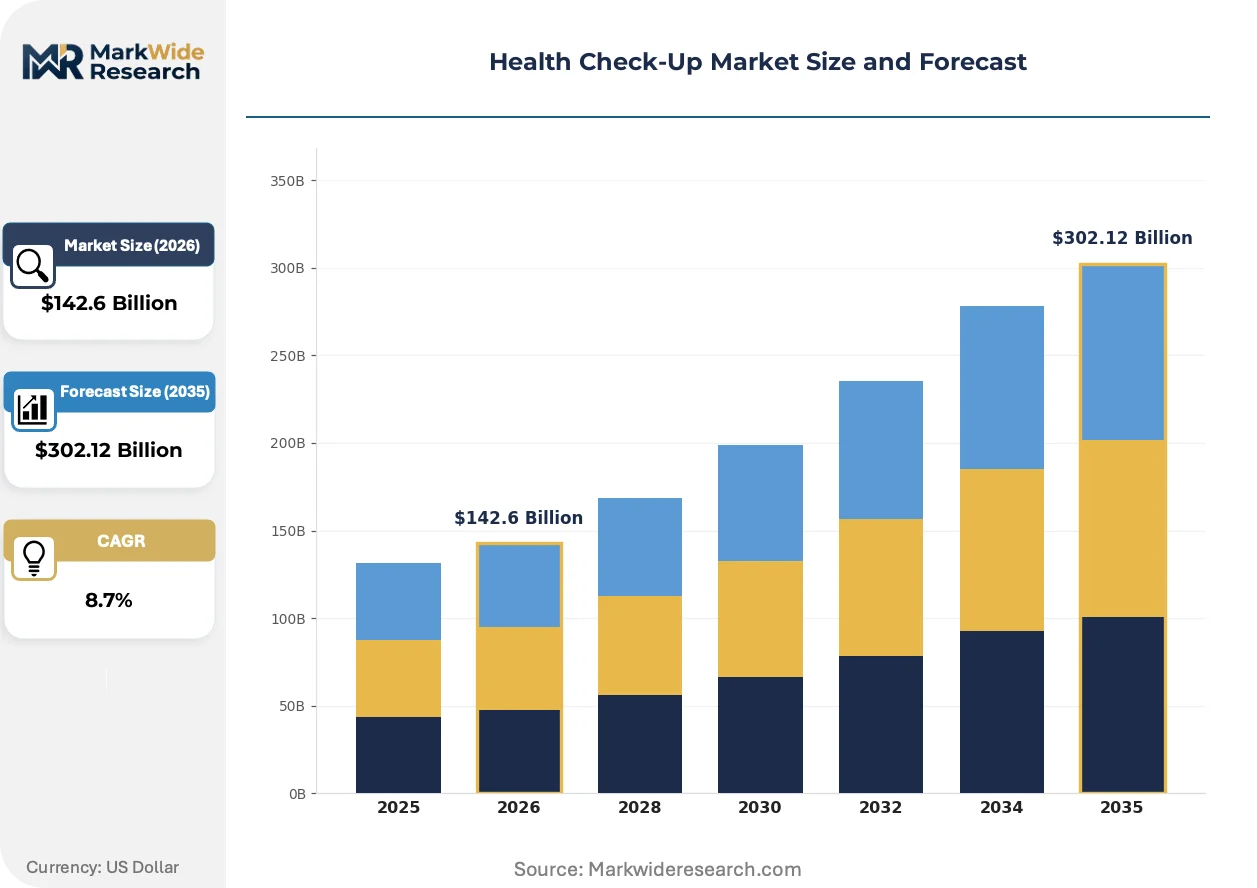
| Market Size in 2026 | $142.6 Billion |
| Market Size in 2035 | $302.12 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Preventive Care, Diagnostic Tests, Screening Services, Wellness Programs Delivery Mode: In-Clinic, Home Visits, Telehealth, Mobile Units End User: Individuals, Corporates, Insurance Providers, Healthcare Institutions Age Group: Children, Adults, Seniors, Adolescents |
| Companies Covered | Quest Diagnostics, Labcorp, Sonic Healthcare, SYNLAB, Eurofins Scientific, ARUP Laboratories, Apollo Hospitals Enterprise Ltd., SRL Diagnostics, LalPathLabs, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Health Check-Up Market Evolving Landscape
Diagnostic service delivery is fragmenting across synchronous, asynchronous, and fully automated channels, with specimen logistics and algorithmic interpretation replacing centralized laboratory real estate as the primary competitive moat.
Artificial intelligence is integrating into routine pathology workflows, replacing manual slide review with algorithm-assisted pattern recognition for hematology and histopathology screening. Large employer health plans are adopting AI-augmented diagnostics fastest, contracting with national laboratory networks that have deployed validated algorithms across distributed pathologist teams. This compression of interpretation timelines is enabling same-day result delivery for cancer screening panels that previously required 48-72 hour turnaround.
Europe's Medical Device Regulation is tightening analytical performance documentation requirements for in-vitro diagnostic software, forcing laboratories to maintain extensive clinical validation datasets for algorithm-assisted screening tools. The regulation's industrial consequence is a compliance cost barrier that favors scaled operators with dedicated regulatory affairs infrastructure over regional diagnostic chains. Germany and France are experiencing the most pronounced consolidation effects, with accredited laboratory networks acquiring smaller competitors to amortize MDR compliance investments.
Consumer-directed health plan enrollment is accelerating screening frequency among high-deductible populations who bear first-dollar costs, but compressing price tolerance and shifting preference toward transparent menu pricing. Direct-to-consumer laboratory portals are displacing physician-mediated ordering for wellness panels in this segment, particularly in states with broad direct access testing laws. This channel disintermediation is most visible in California and Texas, where asynchronous physician review platforms have scaled to serve home specimen collection demand.
Health Check-Up Market Segmentation
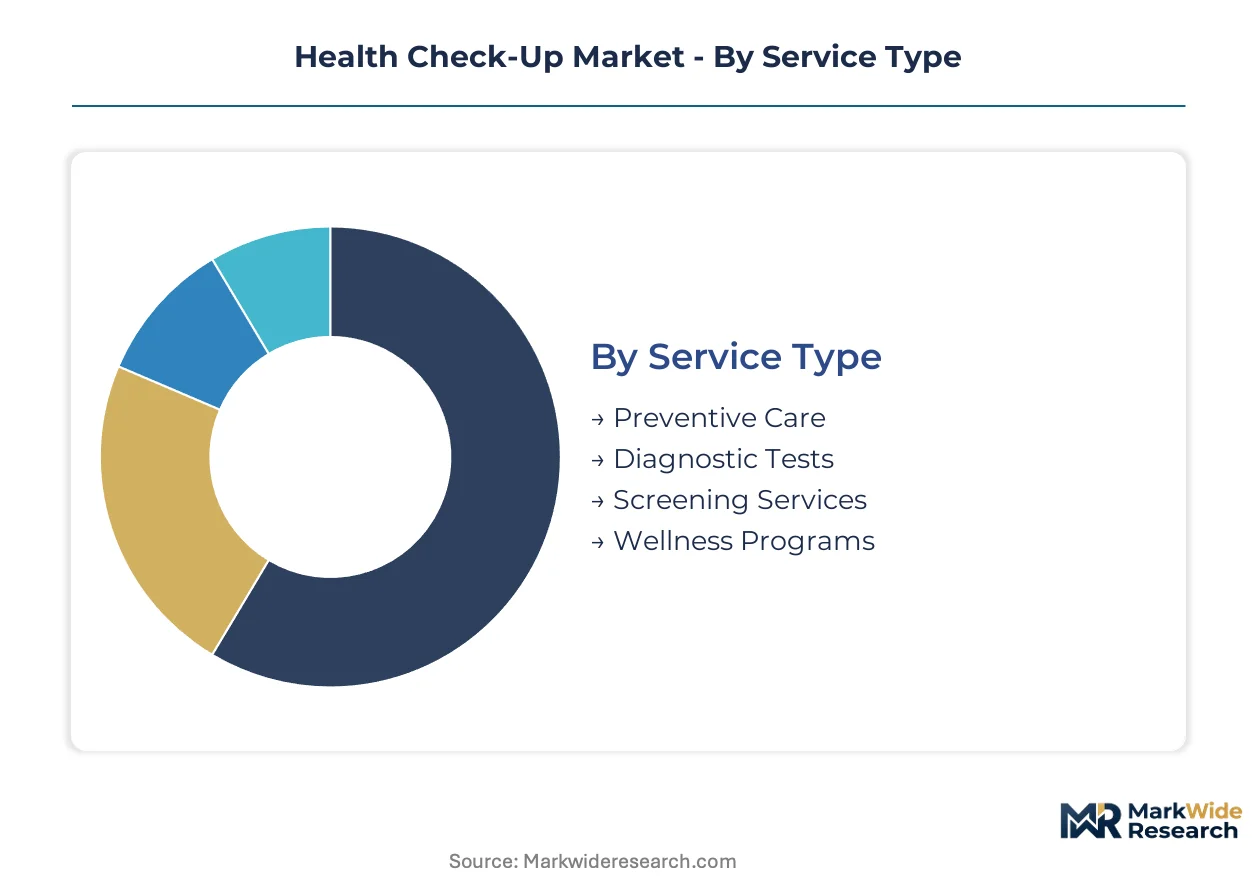
Service configuration in health check-ups determines capital deployment patterns, with imaging infrastructure and specimen processing capacity driving fixed-cost structures. Segmentation reveals where laboratories concentrate accredited capacity versus where asynchronous platforms are displacing physical site dependency.
Service Type:
Preventive care and diagnostic tests demand the heaviest upfront instrumentation investment, while wellness programs require lighter fixed assets but heavier digital platform spend.
- Preventive Care:Scheduled assessments combining physical examination, biomarker panels, and risk-stratified screening to intercept pre-symptomatic disease. Corporate employers in the United States contract annual biometric bundles that institutionalize recurring revenue for diagnostic networks with CLIA-accredited infrastructure.
- Diagnostic Tests:Blood chemistry panels, urinalysis, and specialized assay processing with turnaround targets under 24 hours. Demand concentrates among healthcare institutions seeking early intervention cost avoidance, though CMS reimbursement compression forces laboratories to absorb cost inflation or exit low-margin categories.
- Screening Services:Targeted protocols for cancer, cardiovascular, and metabolic condition detection requiring imaging and pathology coordination.
- Wellness Programs:Behavior-modification and lifestyle coaching layered atop biometric testing, delivered through employer-sponsored platforms.
Most installed capacity flows through diagnostic tests. Expansion is steepest in preventive care.
Delivery Mode:
Channel selection determines last-mile logistics spend and patient capture efficiency, with telehealth platforms achieving the lowest marginal cost per encounter.
- Telehealth:Asynchronous consultation platforms integrating with home specimen collection kits and dried blood spot logistics. Direct-to-consumer portals in California and Texas displace physician-mediated ordering where broad direct access testing laws apply.
- In-Clinic:Traditional phlebotomy and examination sites requiring real estate, equipment, and staffing density. Volume concentrates in accredited laboratory networks that have deployed AI-assisted pathology workflows across distributed pathologist teams.
- Home Visits:Mobile phlebotomy and nursing services extending reach beyond fixed-site accessibility constraints.
- Mobile Units:Deployable screening vehicles serving rural populations and corporate campus events with limited infrastructure investment.
Telehealth commands the shallowest capital intensity per patient served. Physical channels retain volume concentration in employer-mandated screening contracts.
End User:
Payer type shapes panel complexity, pricing transparency requirements, and contractual structure, with corporates offering the most predictable recurring demand.
- Corporates:Large employers contracting workforce screening bundles that tie premium discounts to biometric completion rates. United States mandates sustain the highest screening frequency globally, with annual contracts institutionalizing recurring revenue streams.
- Individuals:Consumer-directed health plan enrollees bearing first-dollar costs and shifting preference toward transparent menu pricing. High-deductible populations accelerate screening frequency but compress price tolerance.
- Insurance Providers:Payer contracts determining covered panel scope and reimbursement rates through annual fee schedule negotiations.
- Healthcare Institutions:Hospital and health system laboratories processing referral volumes with integrated electronic health record architectures.
Corporate contracts anchor the most stable demand. Individual-directed purchasing is climbing the fastest as direct-to-consumer platforms scale.
Age Group:
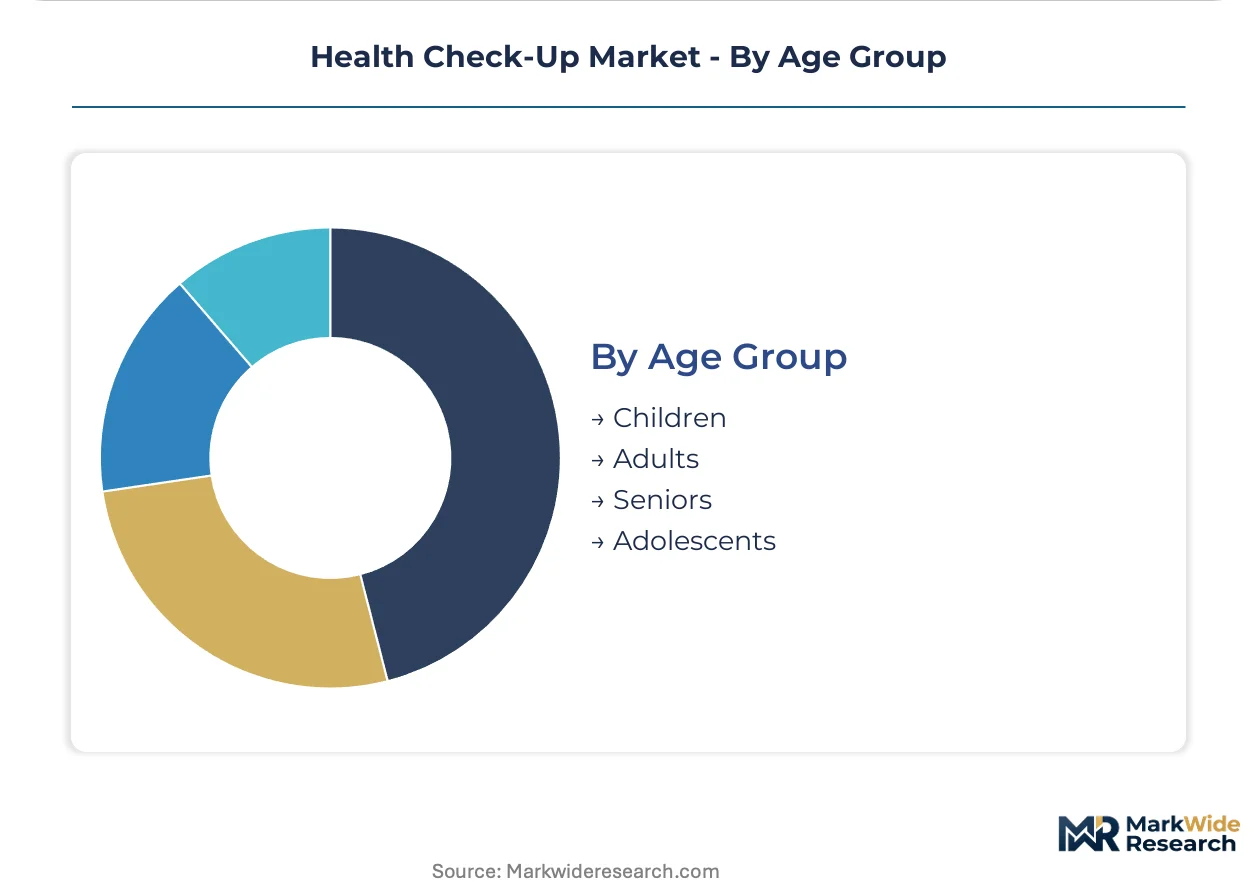
Demographic targeting determines panel design, with seniors requiring the most comprehensive biomarker arrays and adolescents the narrowest screening scope.
- Seniors:Comprehensive panels monitoring chronic disease progression and polypharmacy interactions. Medicare reimbursement schedules directly influence which screening categories laboratories prioritize for this population.
- Adults:Workforce-age populations driving employer-sponsored screening volume with risk-stratified cardiovascular and metabolic panels.
- Children:Developmental and immunization-focused assessments with lower per-encounter revenue but higher visit frequency.
- Adolescents:Transitional screening protocols bridging pediatric and adult care models.
Seniors generate the deepest per-panel margins. Adult workforce screening offers the steepest expansion trajectory through corporate wellness mandate growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Dallas-Fort Worth metroplex anchors North American diagnostic laboratory concentration, with employer-sponsored screening contracts driving specimen volume density across CLIA-accredited networks.
United States
Employer mandates and aging demographics sustain the highest screening frequency globally, with annual biometric bundles institutionalizing recurring revenue streams. The FDA's updated Clinical Laboratory Improvement Amendments elevate quality benchmarks and disqualify marginal operators. The Dallas-Fort Worth corridor concentrates national laboratory network capacity, processing employer-contracted panels under 24-hour turnaround guarantees.
Germany
Europe's Medical Device Regulation tightens analytical performance documentation requirements for algorithm-assisted screening tools. The MDR compliance cost barrier favors scaled operators with dedicated regulatory affairs infrastructure over regional diagnostic chains. The Rhine-Ruhr metropolitan region experiences pronounced laboratory network consolidation as accredited operators acquire smaller competitors to amortize validation investments.
China
Expanding middle-class health awareness and corporate wellness program adoption accelerate preventive screening demand in tier-one cities. The National Medical Products Administration governs in-vitro diagnostic software registration and clinical validation standards. The Yangtze River Delta cluster, centered on Shanghai, concentrates domestic laboratory network expansion and telehealth platform integration with home specimen collection logistics.
India
Urban workforce expansion and insurance penetration drive diagnostic test volume growth across metropolitan centers. The Central Drugs Standard Control Organization regulates clinical laboratory quality standards and medical device import licensing. The Mumbai-Pune corridor anchors western India's accredited laboratory density, with corporate hospital chains expanding preventive screening footprints into secondary cities.
Japan
Aging demographic concentration and universal health coverage sustain comprehensive senior panel demand with deep per-encounter margins. The Ministry of Health, Labour and Welfare sets reimbursement schedules that influence laboratory service menu prioritization. The Kanto region surrounding Tokyo concentrates the nation's highest diagnostic testing volume, with metropolitan hospital networks deploying AI-assisted pathology workflows across distributed pathologist teams.
Health Check-Up Market Competitive Landscape
Strategic partnerships dominate the current landscape, with national laboratory networks integrating telehealth platforms and home specimen logistics to extend reach beyond traditional phlebotomy sites. The vendor base organizes into three tiers: multinational networks with CLIA-accredited infrastructure, regional hospital-affiliated laboratories, and direct-to-consumer portal operators. Two strategic archetypes predominate: scale-driven specimen volume aggregators and technology-forward algorithm-assisted diagnostics specialists. M&A activity and geographic expansion constitute the principal competitive moves, as quality infrastructure investments create compliance cost barriers that favor consolidation.
Among North American network operators, Quest Diagnostics and Labcorp occupy positions exemplifying the scale-driven archetype, anchoring employer-contracted volume through national laboratory footprints. Sonic Healthcare represents the geographic dominance model, with one of the largest international networks of accredited medical laboratories spanning multiple continents. These three entities illustrate how capitalized quality infrastructure and distributed processing capacity create sustainable competitive positioning against regional diagnostic chains facing MDR and CLIA compliance cost pressures.
| Leading Market Players |
|---|
| Quest Diagnostics |
| Labcorp |
| Sonic Healthcare |
| SYNLAB |
| Eurofins Scientific |
| ARUP Laboratories |
| Apollo Hospitals Enterprise Ltd. |
| SRL Diagnostics |
| LalPathLabs |
| Others |
Value Network & Pricing Analysis
Enzyme substrate costs from Asian manufacturing clusters cascade through diagnostic panel pricing tiers, with CLIA-accredited laboratories passing input volatility downstream to employer-sponsored wellness bundles while absorbing margin compression in Medicare-reimbursed categories.
Pricing Analysis
Input-cost pass-through from concentrated reagent manufacturing determines panel economics across service tiers. Three-tier pricing structure across premium, standard, and economy levels separates AI-augmented pathology with same-day turnaround from batch-processed standard panels and basic wellness screenings. Pricing pressure stems from CMS reimbursement schedule compression forcing laboratories to exit low-margin categories or absorb cost inflation. Corporate employers exhibit lowest price sensitivity due to premium discount tie-ins, while high-deductible individual purchasers drive transparent menu pricing demand.
Supply Chain Analysis
Dual-sourcing requirements for monoclonal antibodies and specialized assay chemistries mandate multi-supplier qualification across China, South Korea, and Japan manufacturing bases. Raw material dependencies center on enzyme substrates, diagnostic reagents, and digital imaging components. Single-source vulnerability concentrates in Asian substrate production exposed to customs friction and input volatility. Distribution runs through national laboratory networks with CLIA-accredited infrastructure, regional hospital-affiliated laboratories, and direct-to-consumer portal operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic arbitrage opportunities emerge between United States employer-mandated screening density and European MDR compliance cost barriers, with regulatory differential favoring scaled operators with dedicated quality infrastructure over regional chains.
For Market Incumbents: Anchor market position through backward integration into specialized assay platform production, reducing third-party reagent dependency that exposes margins to Asian supply volatility. Pursue AI-assisted pathology workflow deployment across distributed pathologist teams to compress interpretation timelines below 24-hour employer guarantees. Defend against telehealth platform disintermediation by integrating home specimen collection logistics with asynchronous consultation infrastructure. For New Entrants and Emerging Players: Direct-to-consumer laboratory portals offer the lowest capital intensity route into California and Texas markets where broad direct access testing laws displace physician-mediated ordering. Target chronic disease monitoring panels for pre-symptomatic diabetes and cardiovascular risk stratification, segments remaining underpenetrated in employer contracts beyond annual wellness baselines. Leverage state-level Medicaid expansion channels distinct from saturated commercial employer contracting. For Investors and Strategic Acquirers: Consolidation pressure builds where MDR and CLIA compliance investments create amortization barriers favoring scaled operators over regional diagnostic chains. Long-term viability frames around AI-augmented diagnostic networks with validated algorithm portfolios and distributed processing capacity. Acquisition target archetype: mid-cap accredited laboratories with CLIA infrastructure and underutilized geographic coverage. Signal to watch: FDA guidance finalization on laboratory-developed test validation timelines.| Strategic Initiative | Industry Significance |
|---|---|
| AI-Assisted Pathology Deployment | Algorithmic slide review enables higher specimen volumes without proportional histotechnologist hiring across Quest Diagnostics and Labcorp networks. |
| Home Specimen Collection Integration | Asynchronous telehealth platforms with dried blood spot logistics extend screening access beyond traditional phlebotomy sites in California and Texas. |
| CLIA Quality Infrastructure Investment | Capitalized accreditation creates compliance cost barriers that disqualify marginal operators and concentrate volume among national laboratory networks. |
| Chronic Disease Panel Expansion | Diabetes and cardiovascular risk-stratified protocols for pre-symptomatic populations capture white space beyond annual employer wellness baselines. |
| Strategic Partnership with Telehealth Platforms | Integration with asynchronous consultation infrastructure defends against direct-to-consumer portal disintermediation in high-deductible individual segments. |
Research Methodology
Direct dialogue with laboratory operations directors, CLIA compliance officers, employer benefits managers, and pathology informatics specialists grounded qualitative findings, cross-referenced against FDA 510(k) filings, CMS Medicare fee schedule data, hospital procurement databases, and GPO contract repositories. Bottom-up and top-down triangulation validated segment-level assumptions.
Analytical lens combined bottom-up service line modeling with top-down payer reimbursement flow analysis across the projection horizon. Segmentation dimensions included service type, delivery mode, end user, and age group, with geographic regulatory cluster as an additional healthcare-specific dimension. CAGRs derived from volume trajectory analysis correlated with reimbursement schedule evolution and employer mandate penetration curves.
The model assumes a particular technology adoption path; alternative pathways for AI-assisted diagnostics would alter the outlook if algorithm validation timelines extend beyond current projections. Deviation in FDA laboratory-developed test guidance finalization would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Personal Health
Piercing Aftercare Spray Market
Personal Health
Health Coaching Market
Personal Health
Europe Hair Loss Treatment Products Market
Personal Health
Maternity and Personal Care Market
Personal Health
Smoking Cessation and Nicotine De Addiction Market
Personal Health
US Vaginal Moisturizers and Lubricants Market
Personal Health
Workplace Wellness Market
Personal Health
Global on Site Preventive Care Market
Personal Health
Biohacking Market
Personal Health
Asia Health Check-Ups Market
Personal Health
Asia Pacific Hair Loss Treatment Products Market
Personal Health
Menopause Wellness Market
Personal Health
Jet Lag Therapy Market
Personal Health
Asia-Pacific Mobile Health Market
Personal Health
Corporate Wellness Market
Personal Health
Sleeping Aids Market