
 Interdental Brush Market | 2026-2036
Interdental Brush Market Size, Share, and Industry Trends Forecast 2026-2036
Interdental Brush Market Intelligence
Orthodontic patient demand is rebalancing the interdental brush end-use mix as aligner and bracket treatments expand among younger adults. TePe Oral Health Care dominates the professional channel through dental clinic recommendations across Scandinavia. Procter & Gamble leverages mass retail distribution to sustain volume leadership in North American pharmacies. Colgate-Palmolive Company anchors its position through co-placement with toothpaste in supermarket oral care aisles.
An interdental brush is a slender dental hygiene device with a narrow cylindrical or conical brush head mounted on a coated wire or plastic core, designed to clean proximal tooth surfaces and periodontal pockets that standard bristles cannot reach. Manual brushes occupy the largest volume share due to low unit cost and universal availability, while electric variants capture margin pools through rechargeable base units and replacement head subscriptions. Nylon filaments lead material selection for stiffness control and antimicrobial coating compatibility, though biodegradable plastic handles are gaining traction among sustainability-focused buyers.
FDA 510(k) clearance governs device classification for interdental brushes sold in the United States, while CE marking under the EU Medical Device Regulation shapes European market access and post-market surveillance obligations. ISO 16409 sets dimensional and performance benchmarks that manufacturers must meet for international distribution. Stakeholders should monitor regulatory divergence between FDA's medical device framework and emerging EU sustainability mandates affecting plastic component sourcing.
Market Dynamics
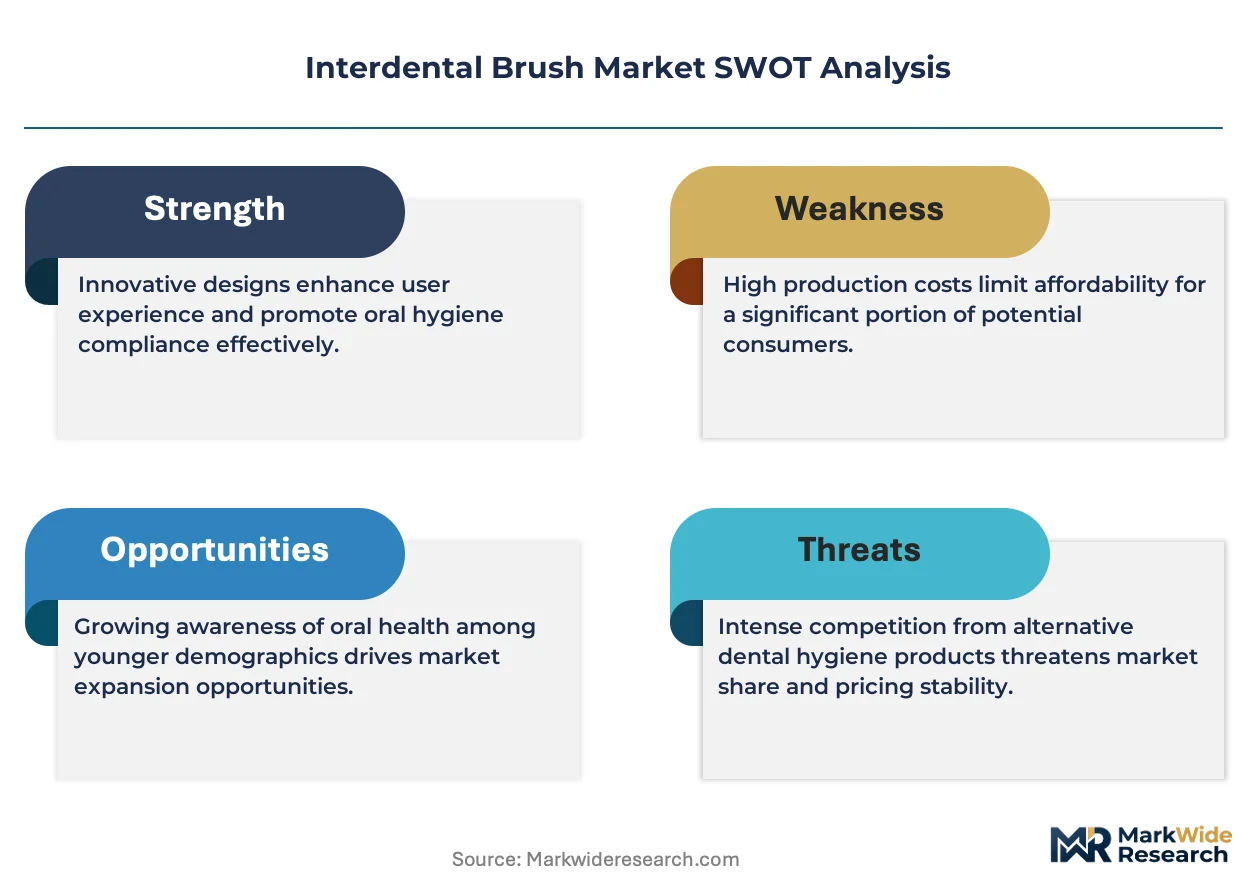
Orthodontic alignment procedures are expanding the addressable patient base for interdental brushes, rebalancing demand from general oral hygiene toward specialized periodontal maintenance and bracket-care applications.
Growth Catalysts
- EU Medical Device Regulation:CE marking under MDR elevates quality benchmarks, filtering low-grade imports and rewarding compliant manufacturers with premium channel access across Germany, France, and Italy.
- Biodegradable handle materials:PLA and bamboo fiber composites are capturing sustainability-focused buyers in Scandinavian retail, creating material differentiation where nylon filaments once dominated.
- Orthodontic patient volumes:Clear aligner and bracket treatments among adults aged 25-40 are generating recurring replacement demand for narrow-gauge brush heads.
Market Restraints
- Petroleum-based polymer volatility:Polypropylene and ABS handle costs fluctuate with crude oil indices, compressing margins on economy-tier SKUs.
- Single-supplier wire coating concentration:Medical-grade nylon coating for core wires concentrates among three German specialty chemical suppliers, creating input bottleneck risk.
- Floss stick substitution:Pre-threaded floss picks capture convenience-oriented users in North American mass retail, eroding trial adoption for traditional interdental brushes.
Strategic Opportunities
- Indian dental professional channel:Penetration of dental clinic recommendation programs remains below 15% in tier-2 and tier-3 cities, offering first-mover positioning before branded competition consolidates.
- Subscription replacement head models:Direct-to-consumer auto-ship programs for electric interdental brush refills are displacing pharmacy replenishment in UK urban markets.
- ISO 16409 certification harmonization:Emerging Asian manufacturers leveraging ISO benchmarks gain accelerated regulatory clearance in Middle Eastern import regimes.
Industry Challenges
- FDA 510(k) documentation timelines:New device submissions face 12-18 month review cycles for novel filament configurations, delaying product launches.
- Antimicrobial coating validation:Silver-ion and chlorhexidine-impregnated filaments require extensive biocompatibility testing, stretching R&D budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Interdental Brush Market |
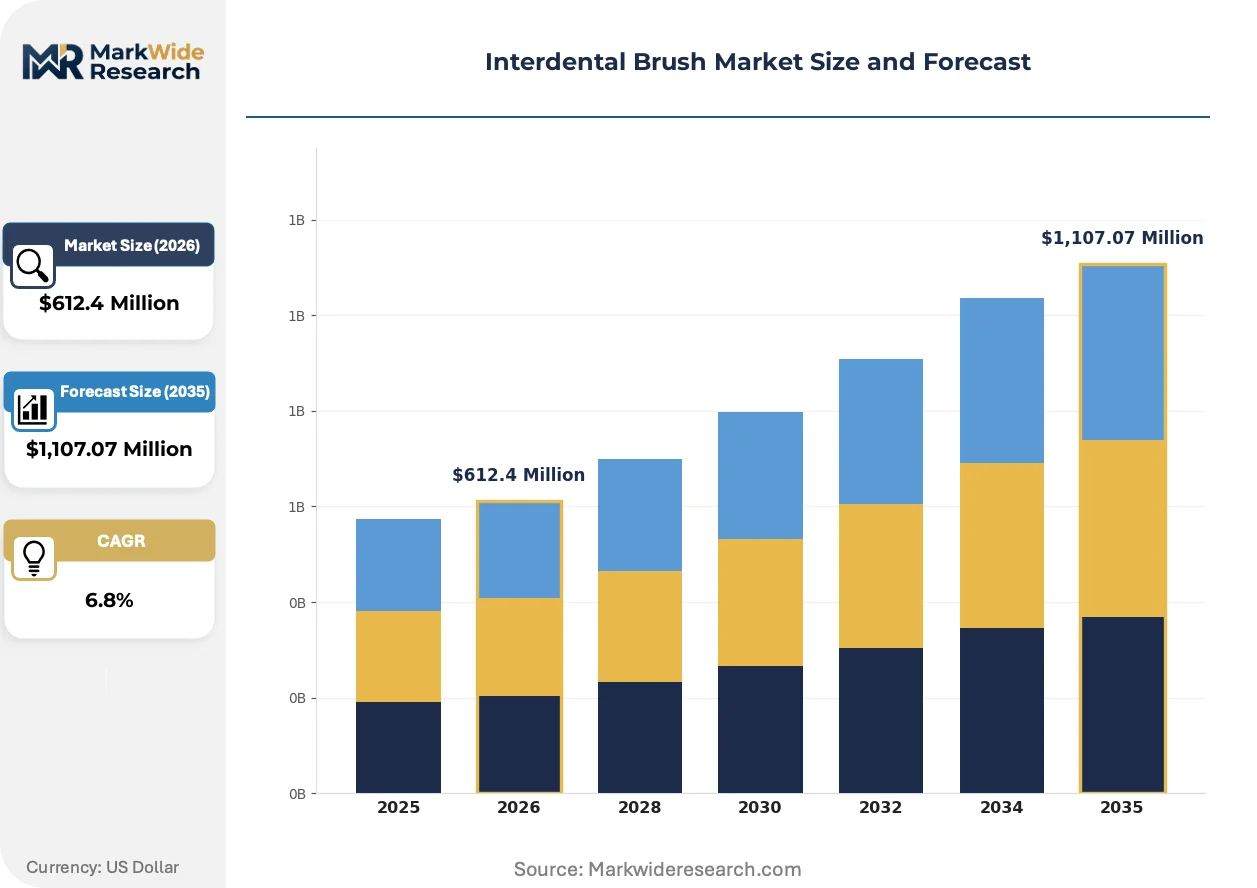
| Market Size in 2026 | $612.4 Million |
| Market Size in 2035 | $1,107.07 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Brushes, Electric Brushes, Disposable Brushes, Specialty Brushes End User: Adults, Seniors, Children, Orthodontic Patients Size: Small, Medium, Large, Extra Large Material: Plastic, Nylon, Rubber, Others |
| Companies Covered | TePe Oral Health Care, Procter & Gamble, Colgate-Palmolive Company, Sunstar Suisse S.A., CURADEN AG, TRISA AG, Lion Corporation, Oral-B, Prestige Consumer Healthcare Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Interdental Brush Market Strategic Shifts & Innovations
Product architecture is bifurcating between disposable manual formats and rechargeable electric systems, while regulatory sustainability mandates are forcing material sourcing recalibration across manufacturing footprints.
Rechargeable interdental cleaning systems with oscillating brush heads are electrifying the premium segment, capturing orthodontic patients who require daily proximal cleaning. German and Japanese dental clinics are prescribing these devices at three times the rate of manual alternatives. The technology is compressing replacement head margins while expanding recurring revenue pools for base unit manufacturers.
EU Green Deal plastic sourcing requirements are mandating recycled content minimums for medical device packaging, forcing handle and blister-pack suppliers to requalify resin streams. Manufacturers serving German and Benelux markets face 2027 compliance deadlines for post-consumer recycled integration. The policy is accelerating supplier consolidation as smaller molders lack certification capital for traceability systems.
Dental clinic recommendation programs are displacing retail self-selection as the primary trial mechanism for interdental brush adoption. Scandinavian and German hygienists now distribute starter kits during periodontal maintenance visits, shifting volume through professional channels rather than supermarket aisles. This pattern is most visible in urban German markets where dental professional density exceeds 85 practitioners per 100,000 residents.
Interdental Brush Market Segmentation
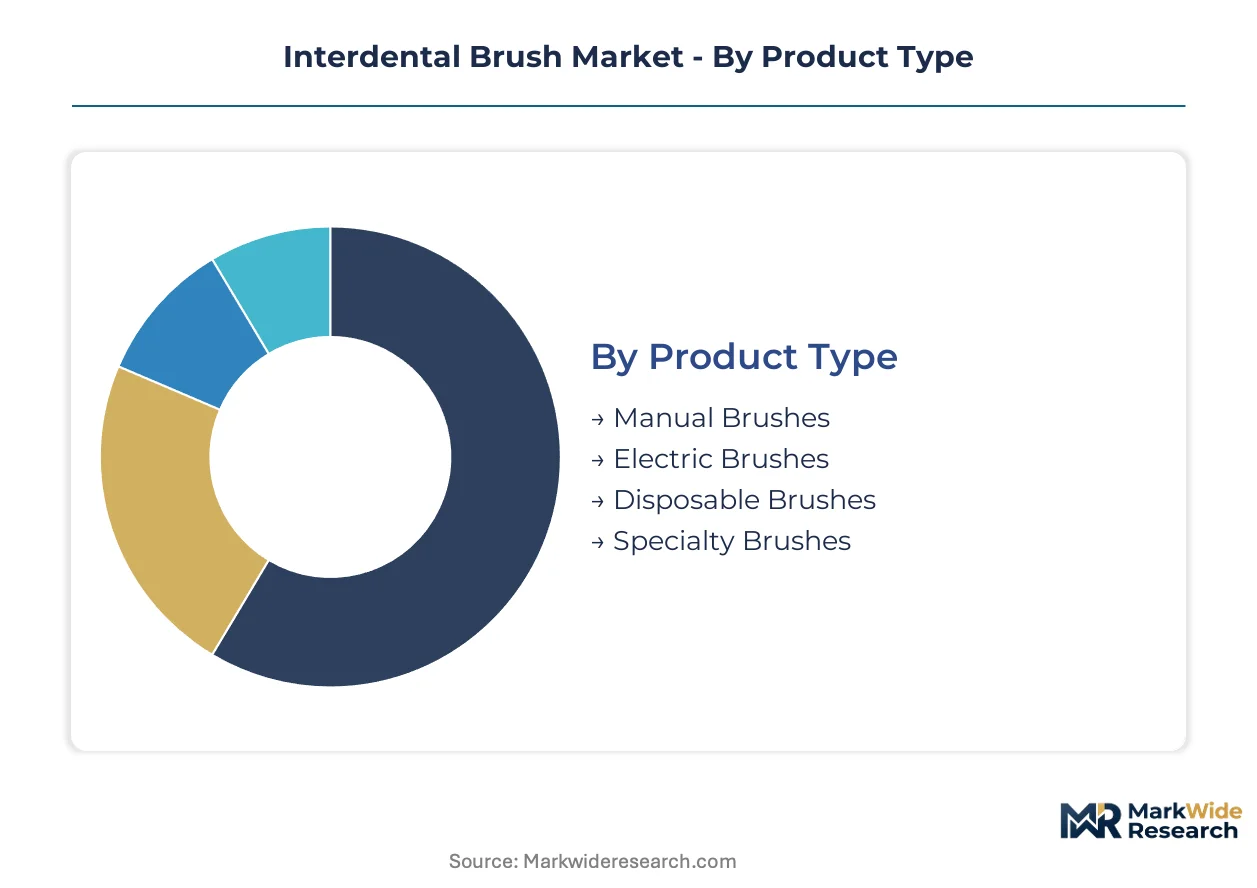
Interdental brush manufacturers configure product portfolios around replacement frequency and upgrade triggers. Electric base units generate multi-year revenue streams through captive refill sales, while manual formats compete on immediate accessibility and trial conversion.
Product Type:
Upgrade cycles differentiate revenue stability across formats, with subscription-enabled electric systems capturing lifetime value and disposable variants optimizing for clinical trial distribution.
- Manual Brushes:Coated wire cores with cylindrical or conical nylon heads dominate pharmacy and supermarket placement. German dental clinics distribute starter kits during periodontal maintenance visits, converting patients before retail self-selection occurs. Manual Brushes sit at the top of the volume ranking, with Electric Brushes climbing the fastest.
- Electric Brushes:Rechargeable base units with oscillating or sonic brush heads command premium positioning through subscription replacement programs. UK urban markets show auto-ship refills displacing pharmacy replenishment among orthodontic patients requiring daily proximal cleaning.
- Disposable Brushes:Single-use plastic handles with pre-mounted heads serve travel and clinical trial applications. Scandinavian airlines and hotel chains bundle these into amenity kits.
- Specialty Brushes:Angled heads and extra-narrow gauges address implant maintenance and lingual bracket access. Japanese dental clinics prescribe these for post-surgical periodontal pockets.
Margin pools concentrate in electric base units and subscription refills, while manual formats absorb commodity polymer cost volatility.
End User:
Application intensity varies by oral anatomy and clinical intervention history, with orthodontic maintenance demanding the highest replacement frequency.
- Adults:Ages 25-55 drive preventive periodontal care adoption, particularly in German and Scandinavian markets where dental professional recommendation rates rank highest globally. Adults represent the largest addressable base.
- Seniors:Receding gingival tissue and wider interproximal spaces create specialized sizing requirements. Japanese geriatric dental programs distribute larger-gauge brushes through municipal health centers.
- Children:Pediatric formulations emphasize softer filaments and color-coded sizing for parental supervision. French school-based oral health initiatives incorporate starter kits into hygiene curriculum.
- Orthodontic Patients:Clear aligner and bracket treatments generate recurring replacement demand for narrow-gauge heads. German clinics prescribe cleaning systems at three times the rate of manual alternatives.
Orthodontic Patients command the steepest expansion trajectory as adult alignment procedures proliferate, while Adults retain volume leadership.
Size:
Dimensional matching to interdental space geometry determines clinical efficacy and repurchase loyalty.
- Small:0.4-0.6mm diameter filaments access tight anterior spaces and pediatric dentition. Italian dental hygienists emphasize gauge-appropriate selection to prevent gingival trauma.
- Medium:0.7-0.9mm cores serve general adult maintenance with moderate papilla height. Medium sizing anchors standard pharmacy assortments across Benelux retail.
- Large:1.0-1.2mm diameters address posterior molars and post-orthodontic spacing. Swiss periodontal practices stock Large gauges for implant maintenance protocols.
- Extra Large:1.3mm+ specifications serve geriatric patients and post-surgical tissue recession cases. Austrian rehabilitation clinics distribute these through prosthodontic referral networks.
Medium sizing dominates unit volume, with Small gauges gaining share fastest among aligner patient populations.
Material:
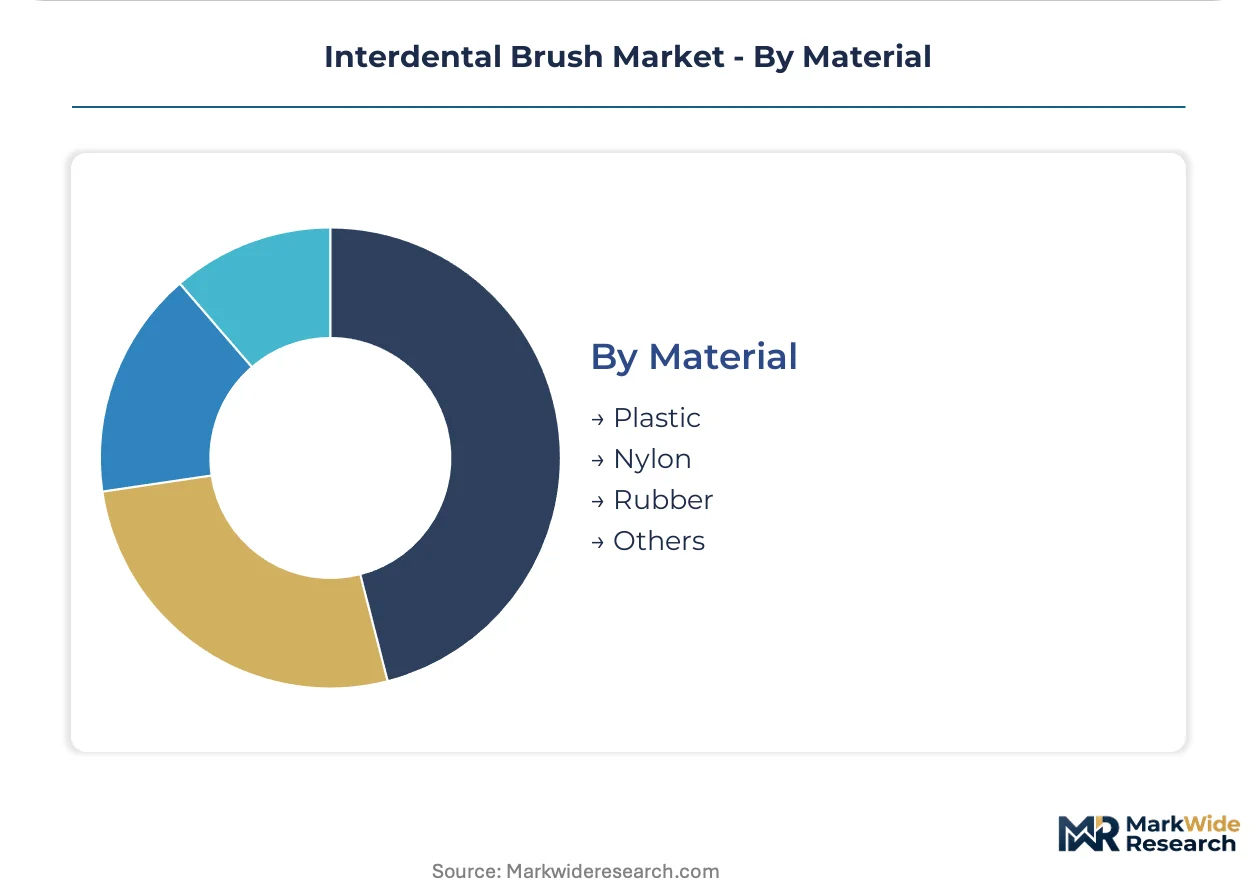
Handle and filament material selection balances mechanical performance, regulatory compliance, and emerging sustainability mandates.
- Plastic:Polypropylene and ABS handles provide cost-efficient molding and color differentiation. EU Green Deal recycled content minimums are forcing resin stream requalification for 2027 compliance.
- Nylon:Polyamide filaments enable stiffness grading and antimicrobial coating compatibility. German specialty chemical suppliers concentrate medical-grade nylon coating for core wires.
- Rubber:Thermoplastic elastomer grips enhance manual dexterity for senior and pediatric users. Japanese manufacturers lead ergonomic overmolding integration.
- Others:PLA and bamboo fiber composites capture sustainability-focused Scandinavian retail demand. Biodegradable alternatives remain limited by moisture resistance and molding precision.
Nylon leads filament selection by volume, with Others expanding most quickly under EU packaging and sourcing regulations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping interdental brush manufacturing footprints as EU MDR compliance costs diverge from Asian production economics. Manufacturers are relocating molding operations to jurisdictions with lower quality-system overhead while maintaining European distribution hubs for premium channel access.
Germany
Dental professional recommendation rates rank highest globally, with hygienists prescribing interdental cleaning systems during periodontal maintenance visits. CE marking under EU MDR elevates quality benchmarks, filtering low-grade imports from neighboring markets. The Stuttgart-Mannheim corridor concentrates medical-grade nylon coating suppliers for core wire production.
United States
Adult orthodontic alignment procedures among ages 25-40 generate recurring replacement demand for narrow-gauge brush heads. FDA 510(k) clearance governs device classification, with review cycles extending 12-18 months for novel filament configurations. Greater Boston anchors dental technology R&D clusters developing antimicrobial coating validation protocols.
Japan
Geriatric dental programs distribute larger-gauge brushes through municipal health centers serving aging populations with receding gingival tissue. PMDA medical device regulations align with ISO 16409 dimensional benchmarks for international distribution compatibility. The Kansai region around Osaka hosts precision molding specialists supplying ergonomic thermoplastic elastomer grips.
United Kingdom
Subscription auto-ship programs for electric interdental brush refills displace pharmacy replenishment among urban orthodontic patients. MHRA post-Brexit regulatory divergence from EU MDR creates parallel conformity assessment requirements for cross-border trade. London's direct-to-consumer dental technology startups are piloting AI-guided sizing recommendations for personalized brush selection.
India
Dental clinic recommendation programs penetrate below 15% in tier-2 and tier-3 cities, offering first-mover positioning before branded competition consolidates. CDSCO medical device rules are harmonizing with ISO standards to accelerate import clearance timelines. Maharashtra's Thane-Belapur industrial belt is attracting contract manufacturers serving Middle Eastern export markets.
Interdental Brush Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, with professional-channel incumbents commanding premium positioning against mass-retail private labels. The market structure concentrates around three tiers: dental-clinic-recommended specialists, pharmacy-distributed consumer brands, and OEM suppliers serving retail private-label programs. Strategic archetypes include Scandinavian professional-channel specialists, North American mass-market consumer goods conglomerates, and Asian contract manufacturers scaling ISO-certified production. Dominant competitive moves encompass M&A to secure dental professional recommendation networks and capacity expansion into biodegradable handle materials for EU sustainability compliance.
Within the professional-channel tier, TePe Oral Health Care and CURADEN AG exemplify Scandinavian-German positioning anchored in dental clinic distribution. Procter & Gamble represents the mass-market conglomerate archetype leveraging pharmacy and supermarket shelf space. Among Asian fabricators, Lion Corporation occupies a position reflecting Japanese precision manufacturing heritage. These three anchors illustrate the geographic and channel-based segmentation that defines competitive positioning.
| Leading Market Players |
|---|
| TePe Oral Health Care |
| Procter & Gamble |
| Colgate-Palmolive Company |
| Sunstar Suisse S.A. |
| CURADEN AG |
| TRISA AG |
| Lion Corporation |
| Oral-B |
| Prestige Consumer Healthcare Inc. |
| Others |
Cost & Logistics Intelligence
Family-owned mid-cap specialists concentrated in southern Germany and western Switzerland anchor wire-coating and precision-molding operations, translating captive technical expertise into pricing discipline that resists commodity erosion. Their ownership structure insulates long-term supplier relationships from quarterly margin pressure, reinforcing stability in medical-grade nylon coating costs that flow through to finished brush pricing.
Pricing Analysis
Distributor margin layers absorb 35-45 points between factory gate and dental clinic shelf, compressing manufacturer returns on manual formats while electric base units retain direct-to-practitioner pricing power. Three-tier pricing structure across premium, standard, and economy levels separates ISO 16409-certified professional systems from pharmacy self-selection tiers and private-label economy SKUs. Pricing pressure stems from petroleum-based polymer volatility in polypropylene handles, eroding margins on entry-level disposable brushes. Orthodontic patients in German and UK urban markets show lowest price sensitivity due to prescription-driven adoption, while North American mass retail consumers exhibit highest elasticity toward floss-stick substitutes.
Supply Chain Analysis
CE marking and FDA 510(k) qualification gates filter supplier bases, concentrating medical-grade wire coating among three German specialty chemical producers and precision molding in Stuttgart-Mannheim and Osaka-Kansai corridors. Raw material dependencies center on polypropylene and ABS resins for handles, polyamide filaments for brush heads, and medical-grade nylon coatings for core wire protection. Single-source vulnerability in German wire-coating supply creates bottleneck exposure for manufacturers lacking dual-qualified alternatives. Distribution runs through dental clinic recommendation networks in Scandinavia and Germany, pharmacy chains in North America, and direct-to-consumer auto-ship platforms in UK urban markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds value through regulatory ratcheting, with EU MDR CE marking deadlines and FDA 510(k) documentation requirements continuously elevating compliance barriers that filter low-grade competition and sustain premium pricing for qualified incumbents.
For Market Incumbents: Deploy certification investment as the primary defensive lever, pursuing dual FDA-CE marking for next-generation antimicrobial filament configurations to outpace documentation timelines that delay rival launches. Consolidate backward integration into medical-grade wire coating through exclusive supply agreements with Stuttgart-area chemical specialists, neutralizing single-source vulnerability that threatens production continuity. Floss-stick substitution in North American mass retail represents the most acute substitution threat requiring channel-control responses through dental professional recommendation program expansion. For New Entrants and Emerging Players: The 40-50 point price-point gap between premium electric systems and economy manual brushes offers white-space positioning for mid-tier rechargeable formats targeting Indian tier-2 and tier-3 dental clinics. Penetration below 15% in Indian professional channels outside major metros presents the most penetrable geography before branded competition consolidates. Subscription replacement head models auto-shipped direct-to-consumer provide the most viable go-to-market angle, bypassing pharmacy shelf-space barriers that incumbent conglomerates dominate. For Investors and Strategic Acquirers: Valuations sit cheapest among Asian contract manufacturers with ISO 16409 certification but limited brand equity, offering platform rollup potential as EU MDR compliance costs force smaller molders toward exit. Long-term viability across the 5-10 year window hinges on sustainability credentialing for biodegradable handle materials and captive refill revenue streams from electric base unit installed bases. The signal to watch is German dental professional recommendation rate trends, which historically predict category volume shifts 18-24 months before retail data confirmation.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR compliance unlocks premium channel access across German and Scandinavian dental clinics. |
| Backward Integration | Captive wire-coating capacity neutralizes single-source dependency on three German chemical suppliers. |
| Subscription Replacement Model | Auto-ship refill programs displace pharmacy replenishment among UK orthodontic patient populations. |
| Sustainability Repositioning | PLA and bamboo fiber handles capture EU Green Deal compliance premiums in Benelux retail. |
| Hospital System Partnership | Japanese municipal health center distribution secures geriatric segment volume through public procurement. |
Research Approach
Direct dialogue with dental hygienists, periodontal specialists, dental clinic procurement managers, and oral care product brand managers grounded qualitative insights in clinical practice realities. Secondary validation drew from FDA 510(k) device clearance databases, EU MDR notified body certification records, ISO 16409 technical standard documentation, and customs trade data tracking interdental brush import flows. Bottom-up patient population modeling and top-down retail audit triangulation converged on volume estimates across manual, electric, and disposable format segments.
Bottom-up demand modeling tracked orthodontic patient procedure volumes, replacement frequency by brush type, and channel-specific pricing tiers across the projection horizon. Segmentation dimensions encompassed product architecture, end-user clinical indication, dimensional sizing, and material composition including emerging biodegradable alternatives. CAGRs derived from fitted adoption curves incorporating regulatory milestone effects and dental professional recommendation rate trajectories. Forecast inputs included antimicrobial coating validation timelines and EU recycled content mandate implementation schedules.
Caveats apply where FDA documentation review cycle extensions, petroleum-based resin price spikes, or floss-stick substitution acceleration could materially shift the outlook for manual brush volume trajectories. A model refresh is warranted upon material change in German dental professional recommendation rate trends or EU MDR enforcement intensity against non-compliant imports.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Personal Health
Feminine Hygiene Market
Personal Health
Sleeping Aids Market
Personal Health
PTBCHA Market
Personal Health
Tick Repellent Market
Personal Health
Skin Tag Remover Market
Personal Health
Maternity Personal Care Products Market
Personal Health
Infrared Sauna Blankets Market
Personal Health
Asia-Pacific Mobile Health Market
Personal Health
North America Workplace Wellness Market
Personal Health
Hair Restoration Market
Personal Health
Sextech and Sexual Wellness Market
Personal Health
Asia Health Check-Ups Market
Personal Health
Sexual Wellness Market
Personal Health
Tongue Scraper Market
Personal Health
Menstrual Cup Market
Personal Health
Biohacking Market