
 Global Health and Wellness Market | 2026-2036
Global Health and Wellness Market Size, Share, and Industry Trends Forecast 2026-2036
Global Health and Wellness Market Intelligence
Direct-to-consumer wellness channels is narrowing as subscription platforms and telehealth portals consolidate patient access. Nestlé S.A. leverages its pharmaceutical-nutrition hybrid pipeline to anchor chronic-disease prevention portfolios. Herbalife Nutrition Ltd. competes through independent distributor networks that sustain personalized coaching models across Latin America and Southeast Asia. Unilever PLC differentiates via clean-label positioning that controls shelf space in European and North American retail.
Global health and wellness encompasses preventive care services, functional nutrition products, physical fitness systems, and digital behavior-modification platforms engineered to reduce chronic disease incidence and extend quality-adjusted life years. Manufacturing integrates bioactive compound extraction, wearable sensor calibration, and AI-driven personalization algorithms that tailor interventions to metabolic profiles and activity patterns. Dietary supplements occupies the deepest margin pools due to repeat-purchase loyalty and minimal regulatory friction in cross-border e-commerce. Wearable devices leads technology adoption as continuous glucose monitors and sleep trackers migrate from diabetic populations to general wellness consumers. Fitness centers remains the most mature end-user channel, while corporate wellness programs represent the fastest-growing demand source as employers absorb insurance cost inflation.
FDA nutrition labeling rules and EU EFSA health-claim authorizations shape permissible marketing language and substantiation burdens for functional food entrants. China's NMPA and SAMR enforce dual carbon goals that constrain packaging materials and manufacturing emissions for imported wellness goods. Japan's PMDA and METI coordinate quasi-drug classifications that create distinct compliance pathways for beauty-nutrition hybrids. Stakeholders must monitor divergent substantiation standards across FDA, EFSA, and NMPA jurisdictions when scaling claims from single-market approvals to multi-regional portfolios.
Market Dynamics
Employer-funded wellness programs are compressing traditional insurance models as corporations absorb rising healthcare costs through preventive intervention budgets, redirecting procurement from reactive medical claims to proactive employee health infrastructure.
Growth Catalysts
- Corporate wellness mandates:Large employers in the United States and Germany are expanding on-site clinics and biometric screening programs to reduce premium inflation. This employer segment now represents the fastest-growing demand source across the analysis window.
- EFSA health-claim authorizations:Streamlined substantiation pathways for functional foods in Europe accelerate product launches. Manufacturers leverage these approvals to enter multiple EU member states with unified labeling.
- Continuous glucose monitor migration:Wearable metabolic tracking devices originally developed for diabetic populations are crossing into general wellness consumer segments. This technology convergence expands addressable markets beyond clinical indications.
Market Restraints
- Bioactive compound supply concentration:Specialist extraction facilities cluster in China and India, creating input vulnerability for Western formulators. Geopolitical friction or logistics disruption propagates through finished goods pricing.
- FDA nutrition labeling compliance costs:Reformulated substantiation requirements for structure-function claims impose documentation burdens that disadvantage smaller functional food entrants lacking regulatory affairs infrastructure.
- Plant-protein input volatility:Pea and rice protein isolate prices fluctuate with agricultural yields and processing capacity constraints. Alternative protein economics remain sensitive to commodity crop cycles.
Strategic Opportunities
- Preventive care infrastructure in Brazil:Underpenetrated employer wellness penetration relative to GDP per capita suggests whitespace for corporate program vendors. ANVISA regulatory harmonization with FDA standards reduces market entry friction.
- AI-driven personalization algorithms:Machine learning models trained on microbiome and metabolomic data enable subscription nutrition services. Technology convergence between diagnostic testing and recommendation engines creates new service categories.
- EU Green Deal packaging mandates:Sustainable material requirements favor suppliers with biodegradable or recyclable packaging capabilities. Early compliance positions capture shelf space in European retail consolidation.
Industry Challenges
- Metabolic data science talent scarcity:Interpretation of continuous biomarker streams requires specialized computational biology and nutrition science cross-training. Recruitment competition from pharmaceutical and technology sectors constrains expansion timelines.
- Multi-jurisdiction claim substantiation:Divergent FDA, EFSA, and NMPA evidentiary standards force redundant clinical study designs. Portfolio scaling demands parallel rather than sequential regulatory strategies.
- Wearable sensor calibration complexity:Accuracy validation across diverse skin types, activity intensities, and environmental conditions requires extensive field testing. Product liability exposure accompanies consumer-grade medical-adjacent positioning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Health and Wellness Market |
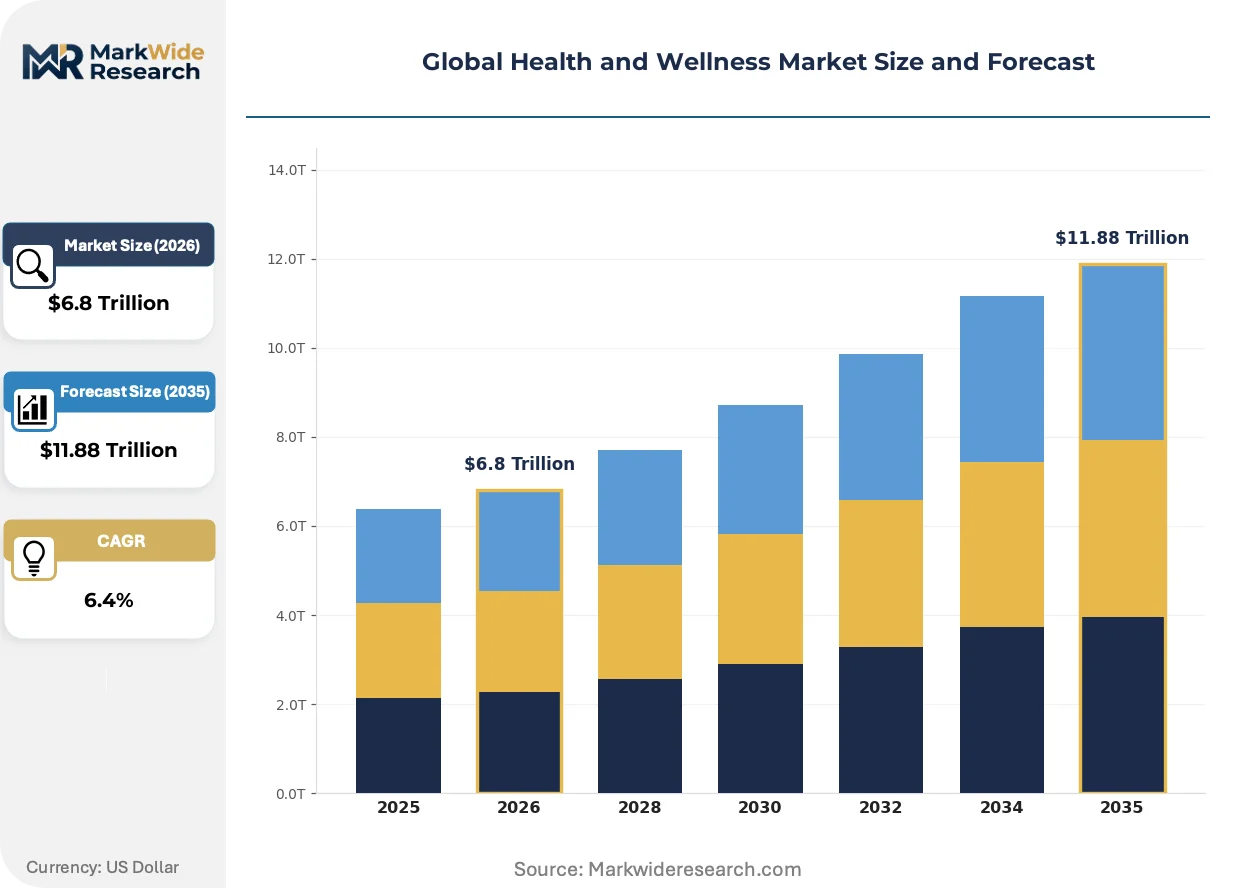
| Market Size in 2026 | $6.8 Trillion |
| Market Size in 2035 | $11.88 Trillion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fitness Equipment, Dietary Supplements, Organic Food, Health Apps Technology: Wearable Devices, Mobile Health, Telemedicine, Virtual Coaching End User: Individuals, Corporations, Healthcare Providers, Fitness Centers Delivery Mode: Online Sales, Retail Stores, Direct Sales, Subscription Services |
| Companies Covered | Herbalife Nutrition Ltd., Danone S.A., Nestlé S.A., PepsiCo, L'Oréal S.A., Unilever PLC, Bayer AG, The Procter & Gamble Company, Amway Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Health and Wellness Market Strategic Shifts & Innovations
Telehealth portals and subscription platforms are collapsing the traditional patient-clinic relationship, replacing episodic care with continuous digital engagement that captures behavioral data for personalized intervention design.
Continuous glucose monitoring technology is collapsing the boundary between diabetic management and general metabolic optimization. Athletes and biohackers in the United States and Australia now adopt prescription-grade sensors for non-clinical performance tracking. This adoption pattern compresses the addressable market definition and forces manufacturers to reposition clinical devices for consumer wellness retail channels.
EU EFSA health-claim substantiation requirements are tightening evidentiary standards for functional food marketing language. Manufacturers must now generate human intervention studies rather than rely on mechanistic or observational data. Botanical and probiotic categories face particular compression as legacy claims undergo retrospective review and delisting.
Employer procurement patterns are rotating from insurance premium containment toward direct wellness infrastructure ownership. Large corporations in Germany and Japan are building captive on-site fitness and nutrition programs. This channel shift displaces traditional gym memberships and redirects subscription platform revenues toward B2B contracting models with multi-year service agreements.
Global Health and Wellness Market Segmentation
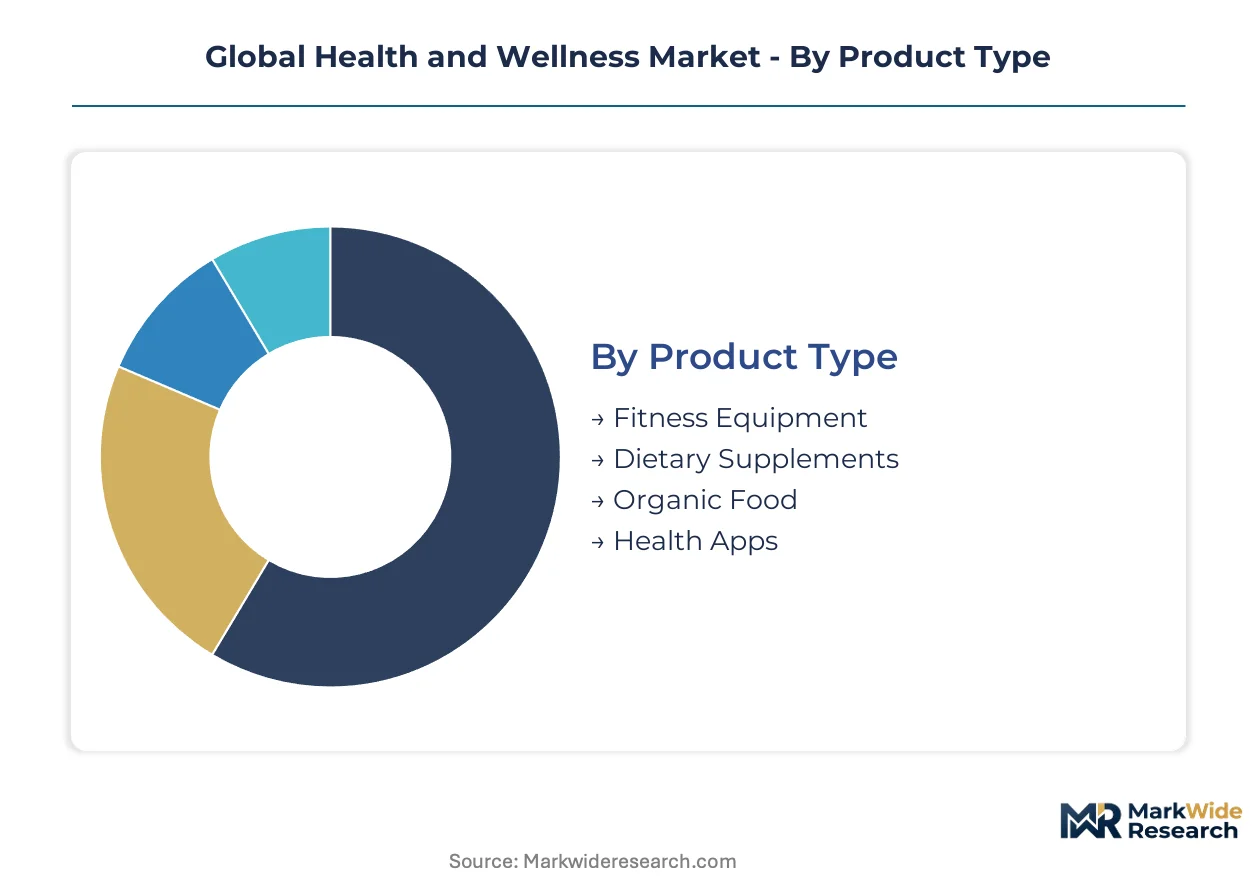
Segmentation in health and wellness reveals how preventive care infrastructure fragments across hardware, software, and service modalities. Each dimension carries distinct margin profiles and regulatory exposure that shape vendor specialization strategies.
Product Type:
Mature consumable categories dominate revenue concentration while connected hardware accelerates technology convergence.
- Fitness Equipment:Connected strength training and cardiovascular systems integrate biometric feedback loops for real-time form correction. Demand concentrates in Germany and Australia as boutique studio chains expand franchise networks. Equipment-as-a-service financing models reduce upfront capital barriers for smaller gym operators.
- Dietary Supplements:Bioactive compound formulations span probiotics, adaptogens, and targeted micronutrient stacks with batch-level traceability requirements. China and the United States absorb the majority of cross-border e-commerce volume despite divergent FDA and NMPA substantiation standards.
- Organic Food:Certified production systems with EU organic or USDA equivalency command retail shelf space premiums.
- Health Apps:Behavior-modification software with FDA Software as a Medical Device clearance penetrates employer wellness procurement.
Dietary Supplements handles the majority of throughput; Health Apps is the fastest mover on share.
Technology:
Hardware sensor platforms anchor recurring revenue while software layers extract value from longitudinal data streams.
- Wearable Devices:Continuous glucose monitors and multi-spectrum sleep trackers calibrate optical sensors against clinical reference standards. Athletes in Australia and biohackers in the United States drive non-diabetic adoption beyond original clinical indications.
- Mobile Health:Smartphone-native diagnostic tools leverage camera and accelerometer arrays for remote patient monitoring. India and Brazil show the steepest expansion trajectory as cellular infrastructure penetrates rural catchment areas.
- Telemedicine:Synchronous video consultation platforms integrate with EHR systems for prescription continuity.
- Virtual Coaching:AI-augmented personal training algorithms adapt workout programming based on recovery biomarkers.
Wearable Devices commands the installed base; Mobile Health is climbing the fastest on user acquisition metrics.
End User:
Procurement authority determines pricing power and contract duration across consumer and institutional channels.
- Corporations:Employer-funded wellness programs absorb biometric screening, on-site fitness infrastructure, and subscription platform licenses as insurance cost containment measures. Large employers in Germany and Japan structure multi-year service agreements with outcome-based components.
- Individuals:Direct-to-consumer purchasers prioritize convenience and personalization over clinical validation. Urban clusters in China and the United States concentrate discretionary spending on premium subscription tiers.
- Healthcare Providers:Hospital systems and physician networks prescribe reimbursed preventive interventions.
- Fitness Centers:Traditional gym operators compete with boutique studios for membership retention.
Individuals generate the highest transaction frequency; Corporations is gaining share fastest on contract value expansion.
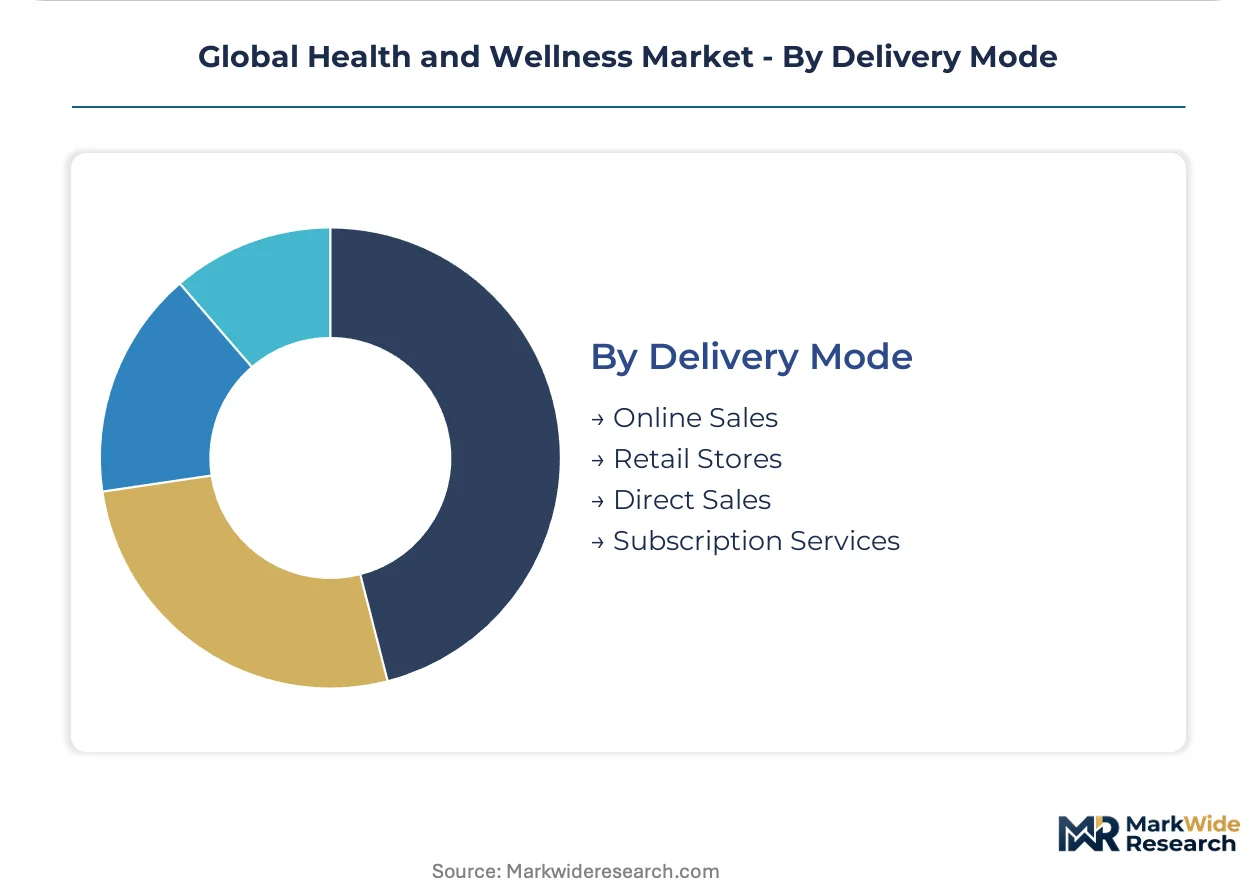
Delivery Mode:
Channel economics diverge sharply between inventory-heavy retail and asset-light digital distribution.
- Subscription Services:Recurring revenue models for personalized nutrition and fitness programming capture lifetime value through data-driven retention algorithms. Platforms serving the United States and United Kingdom experiment with microbiome testing integration to deepen engagement.
- Online Sales:Cross-border e-commerce channels exploit regulatory arbitrage for supplement categories with uneven jurisdiction-specific approvals. Customs complexity in China and Brazil creates fulfillment differentiation for localized warehouse networks.
- Retail Stores:Mass merchandisers and specialty health chains control impulse purchase visibility.
- Direct Sales:Independent distributor networks sustain personalized coaching relationships in Latin America.
Online Sales processes the highest order volume; Subscription Services is expanding most quickly on revenue predictability.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA nutrition labeling reforms and EU EFSA health-claim pathways are redirecting manufacturing investment toward jurisdictions with harmonized regulatory frameworks. Employer-funded wellness programs in Germany and Japan absorb biometric infrastructure at scale. China's NMPA dual carbon mandates constrain packaging materials for imported goods.
United States
Employer wellness mandates drive biometric screening and on-site clinic procurement as corporations absorb insurance cost inflation. FDA structure-function claim reforms impose documentation burdens that disadvantage smaller functional food entrants. Austin and Denver metro areas concentrate boutique fitness studio chains expanding franchise networks.
Germany
Large employers structure multi-year wellness service agreements with outcome-based components to reduce premium inflation. EU EFSA health-claim authorizations accelerate functional food launches across member states with unified labeling. Bavaria and North Rhine-Westphalia host corporate program vendors scaling preventive care infrastructure.
China
Expanding middle-class investment in preventive care and fitness infrastructure concentrates demand in tier-one cities. NMPA and SAMR enforce dual carbon goals that constrain packaging materials and manufacturing emissions for imported wellness goods. Shanghai and Beijing clusters drive cross-border e-commerce volume for dietary supplements.
Japan
Corporate captive wellness programs displace traditional gym memberships through direct infrastructure ownership. PMDA and METI coordinate quasi-drug classifications creating distinct compliance pathways for beauty-nutrition hybrids. Tokyo and Osaka anchor technology convergence between diagnostic testing and recommendation engines.
Brazil
Underpenetrated employer wellness penetration relative to GDP per capita suggests whitespace for corporate program vendors. ANVISA regulatory harmonization with FDA standards reduces market entry friction for functional food entrants. São Paulo and Rio de Janeiro concentrate direct sales distributor networks sustaining personalized coaching models.
Global Health and Wellness Market Key Industry Players
On the supply side, the industry is consolidating around pharmaceutical-nutrition hybrid pipelines and independent distributor networks with personalized coaching capabilities. Strategic archetypes span multinational conglomerates with clean-label positioning, nutrition-specialist firms with bioactive compound extraction expertise, and direct-sales operators with captive coaching relationships. Dominant competitive moves include portfolio diversification into chronic-disease prevention and geographic expansion through localized regulatory compliance infrastructure.
Within the multinational conglomerate tier, Nestlé S.A. and Unilever PLC exemplify archetypes leveraging pharmaceutical-nutrition hybrid pipelines and clean-label positioning respectively. Herbalife Nutrition Ltd. occupies a position within the direct-sales archetype, sustaining personalized coaching models through independent distributor networks. These three entities represent distinct strategic vectors: hybrid R&D integration, retail shelf-space control, and relationship-based distribution.
| Leading Market Players |
|---|
| Herbalife Nutrition Ltd. |
| Danone S.A. |
| Nestlé S.A. |
| PepsiCo |
| L'Oréal S.A. |
| Unilever PLC |
| Bayer AG |
| The Procter & Gamble Company |
| Amway Corporation |
| Others |
Cost & Logistics Intelligence
Single-source dependency on Chinese bioactive compound extraction facilities determines both pricing tier spreads and supply chain shape, as geopolitical friction propagates through finished goods pricing and forces Western formulators to diversify input sourcing or absorb margin compression.
Pricing Analysis
Certification level creates the primary spread, with FDA-grade substantiation commanding premium positioning against EFSA-equivalent or unverified tiers. Three-tier pricing structure across premium, standard, and economy levels reflects documentation depth, with corporate wellness procurement showing lowest price sensitivity due to outcome-based contracting, while direct-to-consumer supplement buyers drive cost compression through subscription platform comparison shopping.
Supply Chain Analysis
Upstream feedstock concentration in China and India for botanical extracts and protein isolates anchors global formulation capacity. Specialist extraction facilities draw from agricultural commodity cycles in Southeast Asia and South America, with tariff exposure on cross-border supplement shipments creating inventory positioning risk. Distribution runs through direct-to-consumer e-commerce platforms and corporate wellness procurement offices rather than traditional retail wholesale.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory entrenchment around health-claim substantiation creates durable defensive moats, as multi-jurisdiction approval portfolios require sunk cost investments that emerging competitors struggle to replicate.
For Market Incumbents: Build regulatory data moats through parallel FDA, EFSA, and NMPA clinical study investments that block fast-follower entrants. Anchor backward integration into bioactive compound extraction to neutralize input volatility from Chinese supply concentration. Secure multi-year corporate wellness contracts with biometric outcome guarantees to lock out substitute platform vendors. For New Entrants and Emerging Players: Build out AI-driven personalization algorithms targeting underpenetrated employer segments in Brazil and Southeast Asia where ANVISA harmonization reduces compliance friction. Capture share through microbiome testing integration that incumbent supplement brands lack technical capability to match rapidly. For Investors and Strategic Acquirers: EU Green Deal packaging mandates reshape the acquisition landscape toward suppliers with biodegradable certification and localized European manufacturing footprints. Long-term viability hinges on regulatory compliance infrastructure rather than brand equity alone. Watch FDA structure-function claim enforcement intensity as the signal for margin compression timing in functional food categories.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Jurisdiction Regulatory Approval | Parallel FDA, EFSA, and NMPA submissions accelerate geographic scaling beyond single-market constraints. |
| AI-Driven Personalization Platform | Machine learning on microbiome data creates subscription stickiness that commodity supplements cannot match. |
| Corporate Wellness Contracting | Multi-year employer agreements with biometric outcomes displace traditional gym membership revenue pools. |
| Sustainable Packaging Transition | EU Green Deal compliance secures shelf access as European retail consolidates around carbon-neutral suppliers. |
| Continuous Glucose Monitor Consumerization | Prescription-grade sensor repositioning for wellness segments expands addressable market beyond diabetic populations. |
Research Approach
Findings reconcile primary fieldwork against secondary review of FDA filings, EFSA health-claim registers, NMPA approval databases, and corporate wellness procurement records. Interviews with regulatory affairs directors, employer benefits managers, supplement formulators, and diagnostic platform engineers were cross-checked against customs trade data and hospital procurement disclosures. Bottom-up SKU-level modeling was triangulated against top-down category spend estimates.
Forecast inputs span product type, technology modality, end-user procurement authority, and delivery channel across the analysis window. Segmentation dimensions include hardware versus consumable revenue mix, subscription versus transactional purchase patterns, and jurisdiction-specific regulatory cluster. CAGRs were derived from trend extrapolation moderated by saturation thresholds in mature fitness center channels.
Stress conditions across commodity input volatility, tariff regime shifts, and health-claim enforcement intensity were modeled; outcomes outside those bands fall beyond the analytical envelope. Cross-checking against employer wellness budget disclosures and supplement import customs data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Personal Health
Menopause Wellness Market
Personal Health
Disposable Underwear Market
Personal Health
Patient Health Management Market
Personal Health
Sleep Mask Market
Personal Health
Sextech and Sexual Wellness Market
Personal Health
Health Coaching Market
Personal Health
Obesity Treatment Market
Personal Health
Foot Insole Market
Personal Health
Tongue Scraper Market
Personal Health
Global OTC Hair Loss Treatment Market
Personal Health
Asia Health Check-Ups Market
Personal Health
PTBCHA Market
Personal Health
Tick Repellent Market
Personal Health
OTC Health Products Market
Personal Health
Blackhead Removing Vacuum Market
Personal Health
US Vaginal Moisturizers and Lubricants Market