
 Global OTC Hair Loss Treatment Market | 2026-2036
Global OTC Hair Loss Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Global OTC Hair Loss Treatment Market Foresight
The gap between physician-grade hair restoration and mass-market topical solutions is repositioning shelf space across pharmacies and digital channels. Johnson and Johnson Services Inc. leverages its heritage in dermatological science to sustain consumer trust in minoxidil formulations. Church and Dwight Co. anchors its portfolio through broad retail distribution, while Cipla Limited competes on cost-engineered generics that penetrate price-sensitive Asian markets.
Over-the-counter hair loss treatment encompasses non-prescription topical, oral, and cosmetic interventions designed to slow follicular miniaturization or stimulate regrowth, typically containing active concentrations of minoxidil at 2% to 5% or ketoconazole at 1% to 2% as anti-androgenic agents. These products serve consumers seeking clinically validated alternatives to surgical transplantation or prescription therapies without clinical gatekeeping. Minoxidil-based foams and serums command the largest revenue pool due to decades of efficacy documentation and tolerability profiles, while biotin supplements represent the fastest-expanding category as wellness positioning attracts younger consumers pursuing preventive regimens. Herbal extracts occupy a fragmented margin tier where Ayurvedic and traditional Chinese medicine claims differentiate regional competitors.
The FDA's OTC monograph system governs active ingredient safety and labeling in the United States, while China's NMPA and SAMR enforce GB standards for cosmetic and quasi-drug claims that constrain marketing language around regrowth promises. The EU's MDR and REACH frameworks impose stricter substantiation requirements on dermocosmetic products, pushing multinational brands toward clinical trial investment for CE-marked positioning. Stakeholders must monitor how regulatory divergence between permissive OTC jurisdictions and tightening cosmetic-drug boundaries reshapes formulation pipelines and geographic launch sequencing.
Market Dynamics
Formulation pipelines are bifurcating between clinical-grade minoxidil iterations and botanical-positioned wellness SKUs as channel gatekeepers tighten substantiation requirements for regrowth claims.
Growth Catalysts
- Diminishing social stigma:Young adult men now initiate treatment earlier, expanding addressable demand beyond traditional late-stage users into preventive maintenance segments.
- FDA OTC monograph system:Established safety profiles for minoxidil reduce regulatory friction for new entrants, accelerating private-label proliferation across US pharmacy chains.
- E-commerce infrastructure:Tmall and JD.com in China enable domestic brands to bypass traditional retail slotting fees, compressing customer acquisition costs versus Western markets.
Market Restraints
- Active ingredient concentration caps:FDA limits minoxidil to 5% for men and 2% for women, constraining efficacy differentiation and premium pricing headroom.
- Supply concentration in China:Bulk minoxidil API production clusters in Zhejiang and Jiangsu provinces, creating geopolitical and quality-control vulnerability for Western formulators.
- Substitution by prescription alternatives:Finasteride and low-dose oral minoxidil prescribed off-label capture efficacy-seeking consumers dissatisfied with topical results.
Strategic Opportunities
- India's underpenetrated mass market:CDSCO's streamlined cosmetic registration pathway and pharmacy density in tier-2 cities create whitespace for cost-engineered 2% minoxidil launches.
- Subscription direct-to-consumer models:Recurring revenue platforms bypass retail margin stacking while capturing longitudinal adherence data for formulation refinement.
- EU MDR clinical substantiation:CE-marked dermocosmetic positioning commands pharmacy-tier pricing in Germany and France, offsetting trial investment through margin expansion.
Industry Challenges
- Cosmetovigilance reporting capacity:EU Responsible Person obligations and FDA adverse event portals require dedicated pharmacovigilance infrastructure that strains mid-tier brand resources.
- Legacy ERP integration:Batch-level traceability mandates under China's NMPA cosmetic registration system force manual workarounds in facilities running pre-2015 manufacturing software.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global OTC Hair Loss Treatment Market |
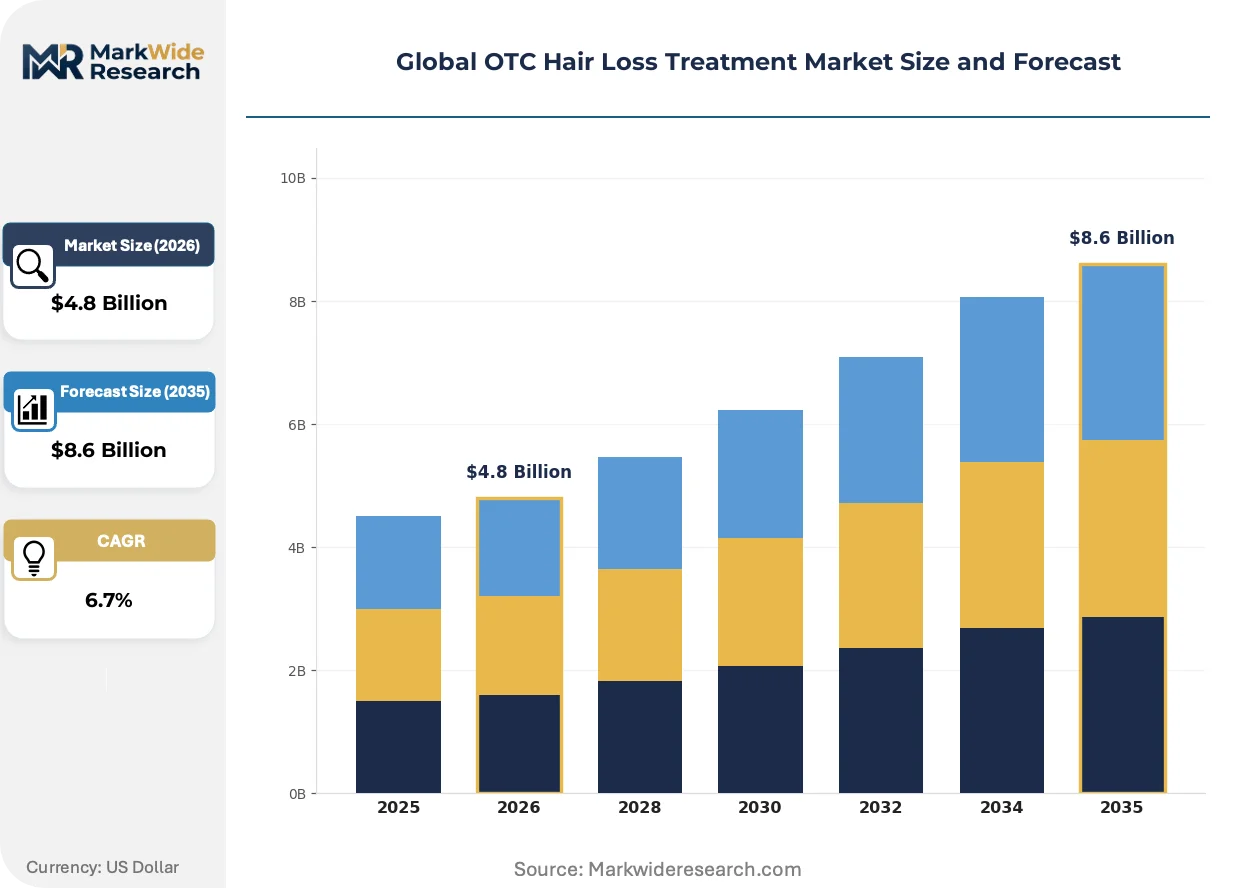
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Minoxidil, Finasteride, Biotin Supplements, Herbal Extracts, Ketoconazole Form: Shampoo, Serum, Foam, Tablets, Tonic Application: Androgenic Alopecia, Alopecia Areata, Telogen Effluvium, Scarring Alopecia, Nutritional Deficiency End User: Men, Women, Seniors, Young Adults, Athletes |
| Companies Covered | Merck and Co., Inc., Johnson and Johnson Services Inc., Church and Dwight Co., Kenvue, Cipla Limited, Amway Corporation, GNC Holdings, Nutraceutical Wellness Inc., Taisho Pharmaceutical Holdings Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global OTC Hair Loss Treatment Market Shifts & Advancements
Personalization engines and biomarker-linked regimens are fragmenting the one-size-fits-all topical model, while regulatory arbitrage between cosmetic and quasi-drug classifications reshapes launch sequencing.
Micro-encapsulation technology is modularizing minoxidil delivery systems, enabling time-release formulations that reduce application frequency from twice-daily to single-dose regimens. Younger consumers seeking regimen simplicity drive adoption, compressing compliance abandonment rates that historically erode long-term revenue per user.
REACH enforcement on residual solvent limits in dermocosmetic manufacturing is forcing reformulation of alcohol-heavy minoxidil solutions across EU member states. German and French contract manufacturers are investing in supercritical CO2 extraction capabilities to maintain CE-marked product positioning without compromising shelf stability.
Social commerce discovery on Douyin and Xiaohongshu is displacing traditional search-based purchasing for first-time buyers in China's lower-tier cities. Live-streaming dermatologist endorsements convert at rates exceeding static e-commerce listings, concentrating marketing spend on KOL partnerships rather than platform advertising auctions.
Global OTC Hair Loss Treatment Market Segmentation
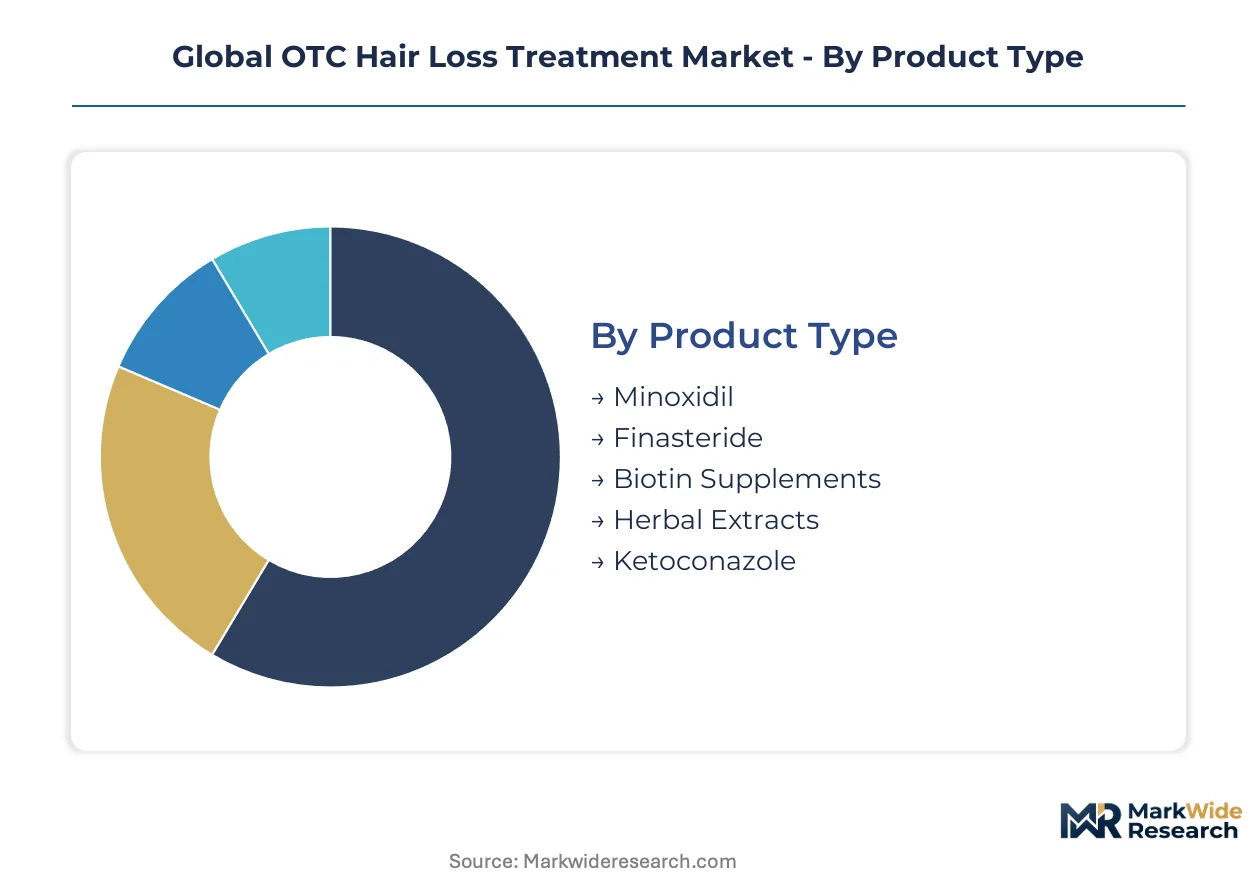
Segmentation in the OTC hair loss treatment market determines formulation priorities, channel strategy, and regulatory compliance pathways. Supply chain configuration varies sharply across product chemistry, physical form, and target physiology, forcing brands to anchor manufacturing investments in specific segment clusters.
Product Type:
API sourcing clusters in Zhejiang and Jiangsu provinces dominate supply economics for active-ingredient segments, with concentration risk shaping Western brand procurement strategies.
- Minoxidil:Vasodilator compound at 2% to 5% concentration forms the clinical backbone of OTC regrowth claims. Demand concentrates in the United States under FDA monograph clearance, where pharmacy chains favor established efficacy documentation over novel botanical positioning.
- Biotin Supplements:Water-soluble vitamin B7 formulations target keratin infrastructure support rather than follicular stimulation. Young adult consumers in China drive expansion through Douyin and Xiaohongshu discovery, where wellness framing bypasses quasi-drug registration requirements.
- Finasteride:5-alpha-reductase inhibitor available in limited OTC jurisdictions; most markets require prescription gatekeeping.
- Herbal Extracts:Saw palmetto, ginseng, and Ayurvedic blends occupy margin-tier positioning with regional claim variation.
- Ketoconazole:Azole antifungal at 1% to 2% addresses seborrheic dermatitis-associated shedding; shampoo incorporation dominates.
Minoxidil absorbs the bulk of installed capacity; biotin supplements are expanding most quickly.
Form:
Manufacturing equipment lock-in across foam, serum, and shampoo formats creates switching costs that segment the contract manufacturing base by physical chemistry capability.
- Foam:Propellant-driven minoxidil delivery reduces scalp irritation versus alcohol-based solutions. Johnson and Johnson Services Inc. maintains proprietary foam technology advantages in US pharmacy distribution, where patient compliance data supports premium positioning.
- Serum:Dropper-applied concentrated actives enable combination formulations with peptides and caffeine. German and French dermocosmetic brands leverage serum formats for CE-marked pharmacy positioning under EU MDR substantiation requirements.
- Shampoo:Ketoconazole and herbal extract incorporation targets wash-day integration; lowest per-treatment cost drives mass-market penetration.
- Tablets:Oral biotin and multivitamin formats bypass topical compliance abandonment; supplement regulation governs rather than drug frameworks.
- Tonic:Traditional Chinese medicine-positioned liquid formulations dominate JD.com and Tmall listings for domestic Chinese brands.
Serum formats command the steepest margin expansion; foam production scales most rapidly in North American contract manufacturing.
Application:
Diagnostic specificity determines marketing claim permissibility, with androgenic versus non-androgenic etiologies falling under divergent regulatory classifications across FDA, NMPA, and EMA jurisdictions.
- Androgenic Alopecia:Pattern hair loss driven by dihydrotestosterone sensitivity; minoxidil monograph alignment enables direct-to-consumer marketing. United States demand concentrates in men aged 25 to 45 initiating preventive maintenance earlier than previous cohorts.
- Telogen Effluvium:Stress or illness-triggered diffuse shedding responds to nutritional intervention; biotin and iron supplementation positioning expands in subscription direct-to-consumer channels capturing longitudinal adherence data.
- Alopecia Areata:Autoimmune patchy loss; limited OTC efficacy documentation restricts claim scope to cosmetic coverage rather than regrowth.
- Scarring Alopecia:Irreversible follicular destruction; OTC positioning limited to symptom management and cosmetic concealment.
- Nutritional Deficiency:Iron, zinc, and protein inadequacy corrections; supplement-form brands target wellness-adjacent consumers in India's tier-2 cities through pharmacy density.
Androgenic alopecia absorbs the bulk of clinical trial investment; telogen effluvium is gaining share fastest among wellness-positioned entrants.
End User:
Demographic targeting shapes packaging design, fragrance profiles, and channel placement, with gendered segmentation historically dominant but age-cohort fragmentation accelerating.
- Men:5% minoxidil concentration authorization and masculine-coded packaging dominate mass retail. Young adult men in China represent the fastest-expanding buyer segment as social stigma diminishes and Tmall subscription models reduce replenishment friction.
- Women:2% concentration cap and pregnancy labeling requirements constrain formulation; aesthetic positioning emphasizes hair density and shine alongside loss prevention.
- Young Adults:Preventive regimens and wellness integration drive biotin and peptide serum adoption ahead of clinically evident thinning.
- Seniors:Late-stage intervention seekers with lower price elasticity; pharmacy consultation dependency persists versus e-commerce migration.
- Athletes:Sweat-resistant formulations and travel-size packaging address regimen adherence during training cycles; niche positioning with limited SKU proliferation.
Men absorb the bulk of volume throughput; young adults are climbing the fastest as preventive positioning reshapes addressable market timing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Zhejiang and Jiangsu provinces anchor global API production for minoxidil, concentrating bulk manufacturing capacity that supplies formulators across three continents.
United States
Pharmacy chain consolidation and FDA monograph clarity sustain mass-market minoxidil penetration among men aged 25 to 45. The FDA's OTC monograph system reduces regulatory friction for private-label entrants. New Jersey-based Johnson and Johnson Services Inc. leverages heritage dermatological positioning to defend shelf space against proliferating store brands.
China
Domestic brands on Tmall and JD.com capture e-commerce share through subscription models that reduce replenishment friction for young adult men. NMPA and SAMR enforce GB standards that constrain quasi-drug marketing claims around regrowth promises. Hangzhou and Shanghai host the headquarters of leading direct-to-consumer entrants deploying live-streaming dermatologist endorsements on Douyin.
Germany
CE-marked dermocosmetic positioning commands pharmacy-tier pricing for serum formats substantiated under EU MDR requirements. REACH enforcement on residual solvent limits forces reformulation of alcohol-heavy solutions. Contract manufacturers in Bavaria and North Rhine-Westphalia invest in supercritical CO2 extraction to maintain compliance without shelf stability compromise.
India
Tier-2 city pharmacy density and CDSCO's streamlined cosmetic registration pathway create whitespace for cost-engineered 2% minoxidil launches. Preventive wellness positioning among young adults drives biotin supplement adoption ahead of clinically evident thinning. Mumbai-based Cipla Limited competes on cost-engineered generics that penetrate price-sensitive markets across South Asia.
Japan
Aging demographics sustain late-stage intervention demand with lower price elasticity than younger cohorts elsewhere. PMDA and METI frameworks govern quasi-drug classifications that limit direct regrowth claims for botanical-positioned SKUs. Osaka and Tokyo concentrate domestic brand headquarters pursuing pharmacy consultation dependency rather than e-commerce migration.
Global OTC Hair Loss Treatment Market Competitive Landscape
Premium-margin players sit above commodity-margin players across formulation substantiation and channel access dimensions. The vendor base clusters around three strategic archetypes: heritage pharmaceutical incumbents with dermatological credibility, cost-engineered generic specialists, and wellness-positioned supplement entrants. Consolidation pressure operates through M&A activity targeting direct-to-consumer subscription platforms and capacity expansion into micro-encapsulation manufacturing.
Within the heritage pharmaceutical tier, Johnson and Johnson Services Inc. and Merck and Co., Inc. exemplify incumbents leveraging decades of efficacy documentation to sustain consumer trust. Church and Dwight Co. occupies a position bridging mass retail distribution breadth with accessible price positioning. Among cost-engineered specialists, Cipla Limited represents the archetype penetrating price-sensitive Asian markets through pharmacy density in tier-2 cities.
| Leading Market Players |
|---|
| Merck and Co., Inc. |
| Johnson and Johnson Services Inc. |
| Church and Dwight Co. |
| Kenvue |
| Cipla Limited |
| Amway Corporation |
| GNC Holdings |
| Nutraceutical Wellness Inc. |
| Taisho Pharmaceutical Holdings Co., Ltd. |
| Others |
Supply & Pricing Matrix
Formulation chemists in Zhejiang and Jiangsu provinces anchor global minoxidil production, with labor-cost differentials between coastal China and Western contract manufacturers sustaining a 40-60% spread between economy-tier private-label and pharmacy-premium pricing tiers. This workforce concentration enables domestic Chinese brands to undercut US and EU incumbents while compressing margin structures for mid-tier Western formulators.
Pricing Analysis
Outcome-linked pricing tied to visible regrowth documentation anchors premium tiers, with Johnson and Johnson Services Inc. commanding pharmacy shelf premiums through decades of efficacy data while store brands compete on unit economics. Three-tier pricing structure across premium, standard, and economy levels separates CE-marked dermocosmetic serums from FDA-monograph minoxidil solutions and unbranded bulk imports. Pricing pressure stems from subscription direct-to-consumer models that bypass retail margin stacking, eroding traditional pharmacy pricing power. Price-sensitive buyers in India's tier-2 cities gravitate toward cost-engineered 2% formulations, while efficacy-seeking consumers in Germany and France absorb pharmacy-tier premiums for substantiated serum formats.
Supply Chain Analysis
Ocean freight cost volatility between Shanghai and Long Beach ports ripples through landed costs for Western brands dependent on Chinese API sourcing, with container rate spikes compressing margins on low-velocity SKUs. Bulk minoxidil API production clusters in Zhejiang and Jiangsu provinces, with India emerging as a secondary fermentation and finishing hub for cost-engineered generics. Supply chain risk centers on single-source vulnerability for high-purity minoxidil intermediates, where Zhejiang province hosts over 70% of global capacity. Distribution runs through pharmacy chains in the United States, Tmall and JD.com in China, and pharmacy consultation networks in Germany and Japan.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global OTC Hair Loss Treatment Market sits in a formulation-transition phase, with micro-encapsulation and time-release delivery systems displacing legacy alcohol-based solutions that dominate current shelf space.
For Market Incumbents: Lock in dermatologist endorsement networks before subscription-native entrants capture longitudinal patient data that enables personalized regimen algorithms. Defend shelf space through backward integration into micro-encapsulation manufacturing capacity, reducing reliance on Chinese toll manufacturers facing REACH solvent restrictions. Prioritize CE-marking investment for EU pharmacy positioning that commands margin expansion unavailable to FDA-monograph competitors.
For New Entrants and Emerging Players: CDSCO's streamlined cosmetic registration pathway in India opens a window for cost-engineered 2% minoxidil launches targeting tier-2 city pharmacy density with minimal regulatory friction. White-space concentration sits in subscription direct-to-consumer models capturing adherence data for formulation refinement, and in biotin-peptide combination serums for wellness-positioned young adults in China's lower-tier cities. Deploy live-streaming dermatologist partnerships on Douyin and Xiaohongshu to bypass platform advertising auction costs.
For Investors and Strategic Acquirers: Re-rating potential sits with direct-to-consumer subscription platforms given their recurring revenue visibility and longitudinal data assets that enable personalized formulation development. Long-term viability favors acquirers of micro-encapsulation manufacturing capabilities and CE-marked dermocosmetic brands with pharmacy-tier pricing power. Watch FDA adverse event reporting volume as an inflection signal for minoxidil tolerance shifts that could accelerate botanical-positioned SKU adoption.
| Strategic Initiative | Industry Significance |
|---|---|
| Micro-Encapsulation Manufacturing Scale-Up | Enables time-release minoxidil formats that reduce application frequency and improve adherence metrics. |
| CE Marking Pathway Investment | Unlocks pharmacy-tier pricing in Germany and France under EU MDR substantiation requirements. |
| Direct-to-Consumer Subscription Launch | Bypasses retail margin stacking while capturing longitudinal patient data for regimen personalization. |
| Backward Integration into API Sourcing | Reduces exposure to Zhejiang province concentration risk and REACH solvent compliance costs. |
| Live-Streaming KOL Partnership | Douyin and Xiaohongshu dermatologist endorsements convert at rates exceeding static e-commerce listings. |
Research Methodology
Independent corroboration across regulatory filing databases, trade flow records, and channel inventory audits underwrites the qualitative findings in this study. Primary interviews with formulation chemists, regulatory affairs leads at dermocosmetic brands, pharmacy chain category managers, and contract manufacturing executives were combined with secondary validation from FDA OTC monograph updates, NMPA cosmetic registration filings, EMA dermocosmetic guidance documents, and EU REACH enforcement notices. Bottom-up and top-down triangulation reconciles manufacturer shipment data with retail sell-through tracking.
Comparable-period anchoring to historical regulatory approval cycles and e-commerce penetration trajectories shaped the projection horizon for demand modeling. Segmentation dimensions span active ingredient chemistry, physical formulation, target etiology, and demographic cohort, with geographic regulatory clusters treated as distinct adoption environments. CAGRs were derived from elasticity-adjusted demand curves incorporating substitution effects from prescription alternatives and wellness-positioned supplements. Forecast inputs include API pricing volatility indices and channel shift velocity metrics from pharmacy to direct-to-consumer platforms.
The model assumes a particular technology adoption path for micro-encapsulation delivery systems; alternative pathways for peptide-based follicular stimulation would alter the outlook for minoxidil-dominant revenue pools. Forecasts reflect assumptions around regulatory stability in FDA monograph jurisdictions and continued e-commerce infrastructure expansion in China. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Personal Health
Earwax Removal Products Market
Personal Health
Tongue Scraper Market
Personal Health
Hair Restoration Market
Personal Health
US Vaginal Moisturizers and Lubricants Market
Personal Health
Maternity and Personal Care Market
Personal Health
South America Hair Loss Treatment Products Market
Personal Health
Parents-In-Waiting: Global Prenatal Market
Personal Health
Feminine Hygiene Market
Personal Health
Menstrual Cup Market
Personal Health
OTC Health Products Market
Personal Health
Piercing Aftercare Spray Market
Personal Health
Interdental Brush Market
Personal Health
Corporate Wellness Market
Personal Health
Foot Insole Market
Personal Health
Menopause Wellness Market
Personal Health
Infrared Sauna Blankets Market